
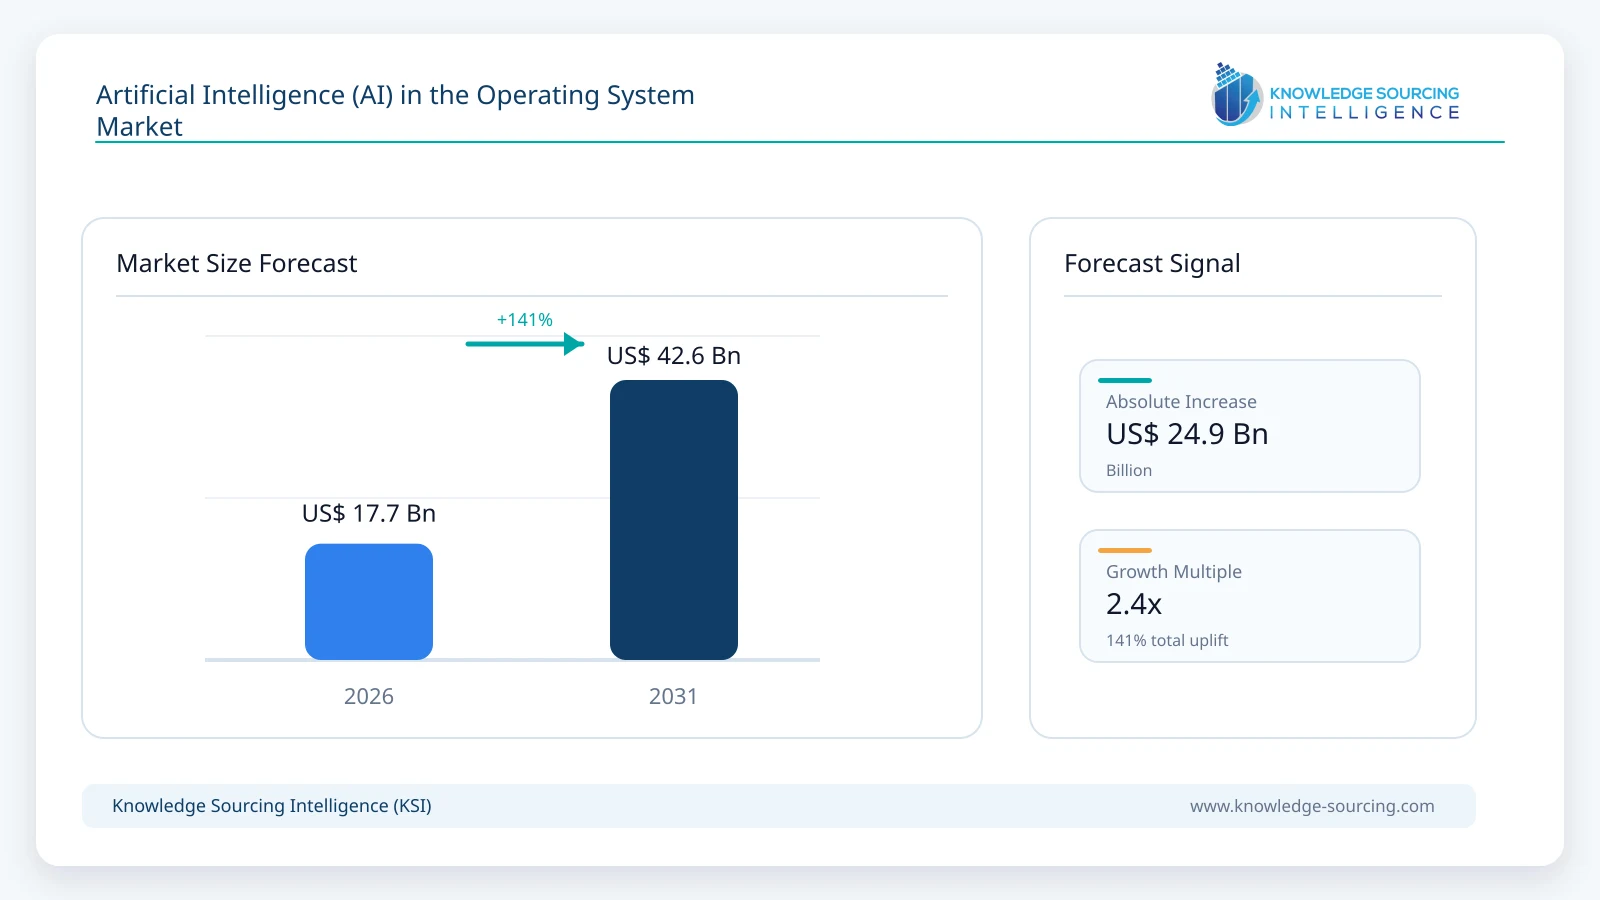
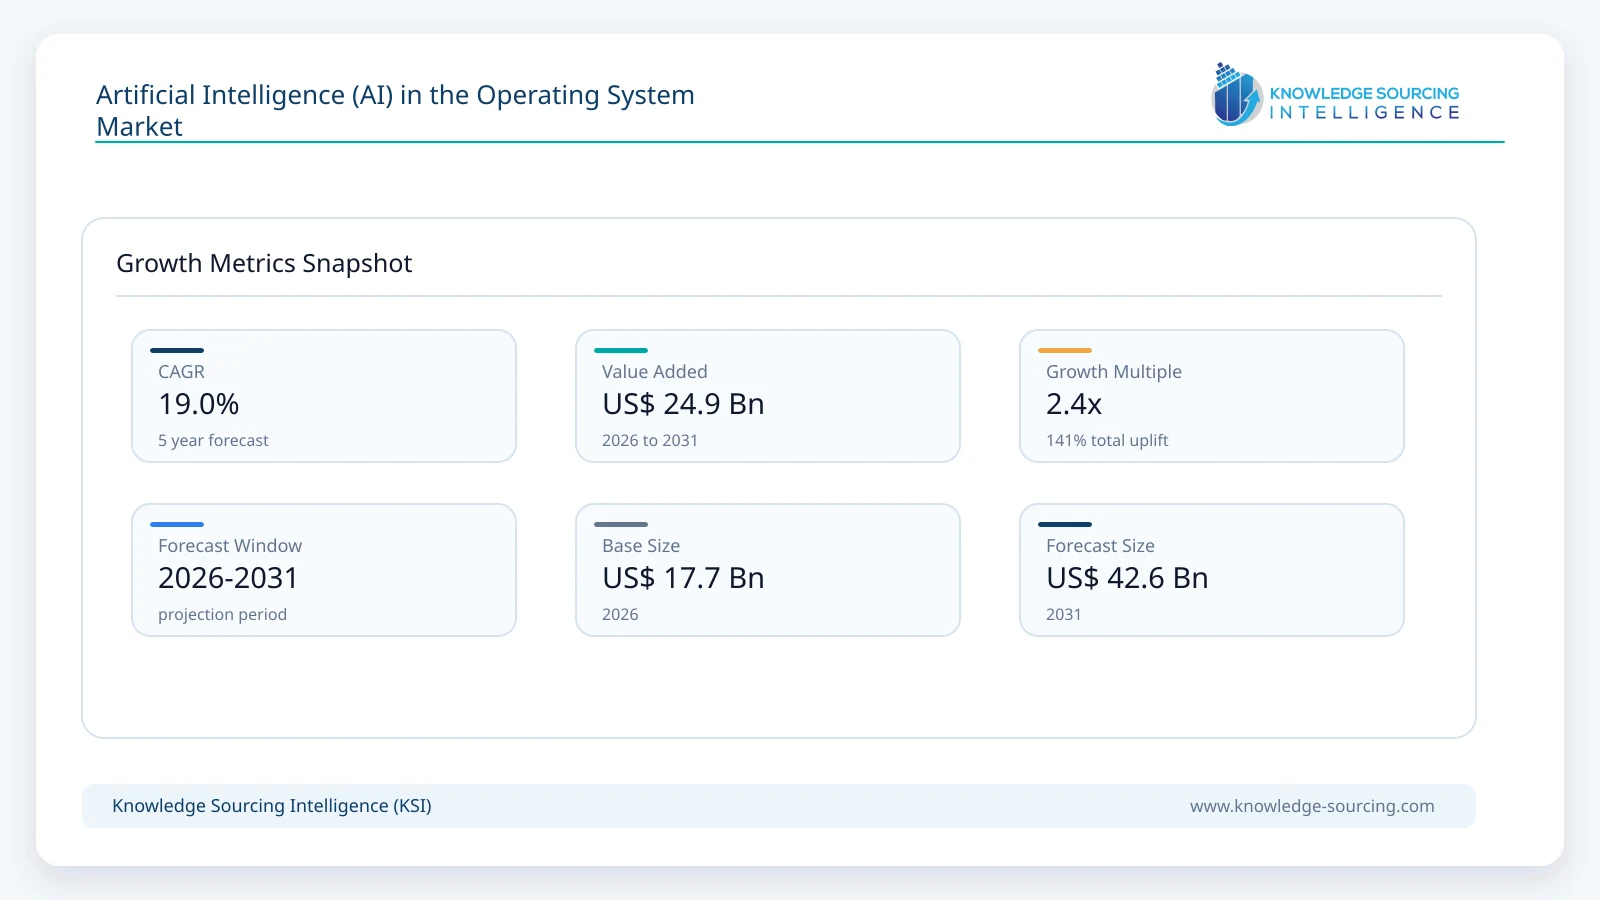
The Artificial Intelligence (AI) in Operating Systems market is forecast to grow at a CAGR of 19.0%, reaching USD 42.6 billion in 2031 from USD 17.7 billion in 2026.
Highlights:
- 1Largest End-UserThe enterprise and professional productivity sector currently represents the largest end-user base, as organizations integrate AI-enabled OS environments to automate multi-step administrative workflows and enhance cybersecurity through real-time behavioral threat detection.
- 2Regulatory ImpactImplementation of the European Union’s AI Act and the U.S. Executive Order on Safe, Secure, and Trustworthy AI has forced OS developers to prioritize transparency and "Explainable AI" (XAI), directly impacting the design of system-level decision-making logs.
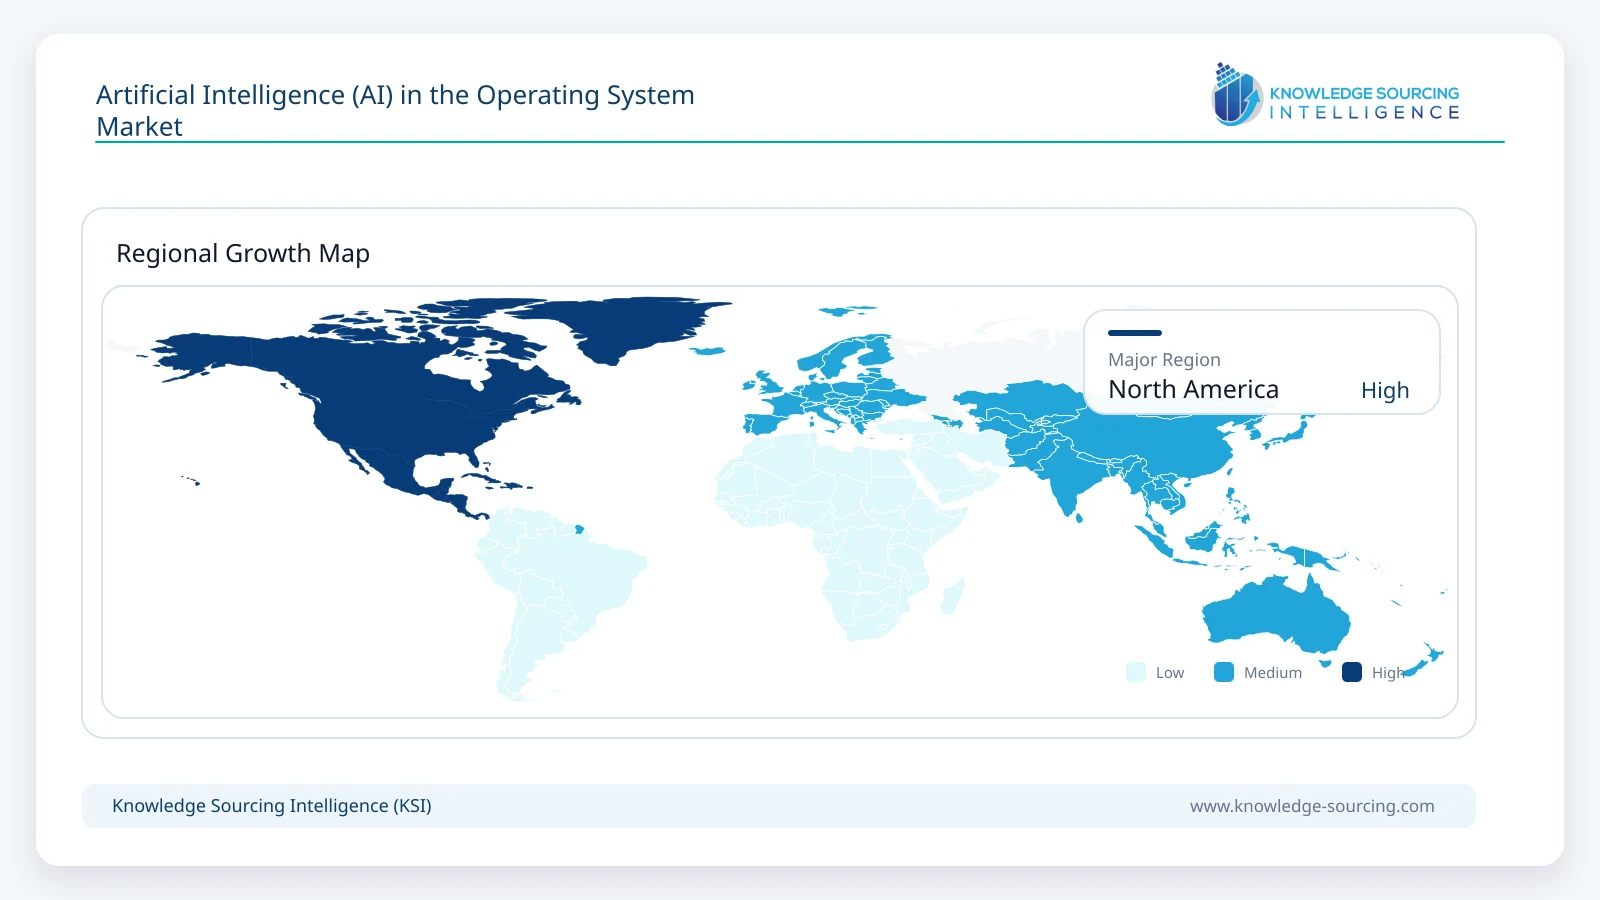
- 3Regional LeaderNorth America maintains a leading position due to the concentration of major OS vendors and the rapid deployment of AI-integrated PC hardware across the region’s expansive corporate and research sectors.
- 4Technology TransitionThere is a significant structural shift from cloud-based AI processing to NPU-accelerated on-device inference, which decreases latency and increases the demand for OS architectures that can manage local model weights efficiently.
- 5Pricing SensitivityThe market is witnessing a transition in monetization strategies from one-time licensing to subscription-based "AI-as-a-Service" models at the OS level, creating high pricing sensitivity among price-conscious consumer segments in emerging markets.
The structural demand for Artificial Intelligence in the operating systems market is fundamentally driven by the requirement for heightened computational efficiency and the democratization of complex cognitive tasks at the hardware-software interface. As silicon manufacturers increasingly integrate Neural Processing Units (NPUs) into standard architectures, the operating system serves as the critical bridge enabling software applications to leverage this hardware. This industry dependency is shifting toward a model where the OS provides native APIs for Large Language Models (LLMs) and Small Language Models (SLMs), moving away from fragmented third-party middleware. This evolution is not merely a feature addition but a complete re-engineering of the system scheduler and memory management to accommodate the unique power and data throughput profiles of AI workloads.
Sustainability transitions and regulatory influences are further refining the strategic importance of AI-integrated operating systems. In the enterprise sector, the demand is catalyzed by the need for autonomous "agentic" workflows that can manage data silos without human intervention. The transition toward the "Intelligent Edge" signifies a move where industrial and automotive sectors require operating systems that can perform real-time localized inference, ensuring safety and operational continuity even in the absence of stable cloud connectivity. Consequently, the OS is evolving into a cognitive layer that balances localized performance with global cloud intelligence.
Market Dynamics
Market Drivers
Silicon-Software Synergy: The proliferation of NPUs and AI-dedicated chipsets (such as Apple’s M-series and Intel’s Core Ultra) requires operating systems to implement native hardware acceleration. This drives demand for AI-integrated OS updates as users seek to unlock the performance potential of their modern hardware for tasks like live translation and local image generation.
Privacy and Security Requirements: Increasing enterprise concern over data leakage in public cloud AI environments is driving demand for "Private AI" delivered via the OS. By hosting AI models locally, the operating system ensures that sensitive user data remains on-device, satisfying strict corporate data sovereignty protocols.
Edge Computing Infrastructure Expansion: The growth of 5G and the Industrial Internet of Things (IIoT) requires real-time operating systems (RTOS) that can handle autonomous decision-making at the edge. This drives demand for AI-capable OS platforms in sectors like aerospace and automotive, where milliseconds of latency in cloud-based AI are unacceptable.
Demand for Agentic Productivity: A shift in user expectations from "search" to "action" is fueling the development of Large Action Models (LAMs) integrated into the OS. This drives demand as these systems can autonomously execute complex tasks across multiple applications, significantly reducing the cognitive load on the user.
Market Restraints and Opportunities
Hardware Fragmentation Constraints: The high degree of variability in AI-acceleration hardware across different devices creates a "performance gap" where AI OS features may not be consistent. This poses a restraint as developers must optimize models for a wide array of GPU/NPU specifications, potentially slowing the rollout of unified AI features.
Regulatory Compliance Costs: Strict international regulations regarding algorithmic bias and data privacy increase the R&D costs for OS providers. Companies must invest heavily in auditing and red-teaming their integrated AI models to ensure compliance with emerging legal frameworks like the EU AI Act.
Specialty Opportunity in Hybrid AI: There is a significant opportunity in developing hybrid AI operating systems that dynamically shift workloads between local NPUs and cloud-based clusters. This optimization allows for high-performance AI features on devices with limited local thermal or power budgets.
Emerging Market Potential for Lightweight AI: As mobile-first economies seek more intuitive interfaces, there is a massive opportunity for "Lite" AI-integrated operating systems that can run on entry-level hardware, potentially displacing traditional interfaces with voice-and-gesture-centric interactions.
Supply Chain Analysis
The supply chain for AI in operating systems is characterized by a deep vertical integration between semiconductor designers and system software architects. Unlike traditional OS development, which followed hardware standards, AI-integrated OS development is often co-engineered with specific silicon architectures. This production concentration is centered around a few key geographic hubs, primarily in the United States and East Asia, where the design of AI-accelerated SoCs (System-on-Chips) occurs. The supply chain is highly sensitive to the availability of high-bandwidth memory (HBM) and specialized fabrication capacity, as the software’s performance is directly tethered to these hardware components.
Regional risk exposure is a critical factor, as trade restrictions on high-end AI chips can bifurcate the market, leading to the development of localized, divergent OS ecosystems in different jurisdictions. Integrated manufacturing strategies have emerged where OS vendors are increasingly designing their own silicon or forming exclusive partnerships to ensure that the OS kernel is optimized for specific hardware instructions. This creates a supply chain dependency where software updates are strictly timed with hardware refresh cycles, ensuring that the latest AI frameworks can be supported without compromising system stability or power efficiency.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
Europe | EU AI Act | Mandatory transparency for generative AI; prohibits "high-risk" biometric systems in the OS; requires strict data governance for GPAI models. |
United States | Executive Order 14110 | Requires developers of dual-use foundation models to report safety test results; focuses on cybersecurity and national security impacts of AI software. |
Global / International | UN Resolution A/78/L.49 | Establishes a global consensus on "safe, secure, and trustworthy" AI, encouraging international cooperation on ethical standards and human rights. |
Key Developments
June 2026: Microsoft announced Project Solara at Build 2026, an agent-first operating platform built on the Microsoft Device Ecosystem Platform (MDEP), enabling AI-native devices where intelligent agents become the primary system interface.
June 2026: Apple introduced the next generation of Apple Intelligence, embedding new Apple Foundation Models directly into its operating systems, bringing systemwide AI capabilities, enhanced privacy architecture, intelligent app experiences, and developer integration.
March 2026: Microsoft introduced the Microsoft 365 E7 Frontier Suite and Agent 365, enabling secure deployment and governance of AI agents tightly integrated with Microsoft's operating environment for enterprise productivity and system management.
Market Segmentation
By Devices: Laptops and PCs
The demand for AI-integrated operating systems in the Laptop and PC segment is driven by the professional requirement for "AI PCs" capable of handling generative tasks locally. As organizations seek to reduce cloud API costs and enhance data security, the OS must provide robust local inference capabilities. This segment is characterized by a high demand for advanced system schedulers that can intelligently distribute workloads between the CPU, GPU, and NPU. The strategic transition toward the "Copilot+" and "Apple Intelligence" standards has made AI integration a non-negotiable requirement for high-end workstations, directly driving the refresh cycle of enterprise hardware.
By Application: Voice Assistance
Voice assistance as an application within the OS has transitioned from a simple command-response tool to a sophisticated natural language interface. This shift is driving demand for "Agentic" OS environments where voice acts as the primary input for complex, multi-step tasks across disparate applications. Modern AI-driven voice assistants are no longer isolated apps but are deeply integrated into the OS’s accessibility and productivity frameworks, enabling hands-free navigation and content manipulation. This evolution is particularly critical for mobile and handheld devices, where screen real estate is limited, and voice-driven orchestration provides a significant operational advantage.
By Application: Personalization Tools
Personalization tools within the AI OS market provide an operational advantage by creating a dynamic, user-specific environment that adapts to behavioral patterns. By analyzing user habits locally, the OS can pre-load frequently used applications, manage battery life based on predicted usage, and offer contextual suggestions. This level of system-wide adaptation increases user efficiency and device "stickiness," as the OS becomes increasingly tailored to the individual’s workflow. The integration of "Small Language Models" for local personalization ensures that this data remains private, addressing a major consumer concern regarding behavioral tracking.
Regional Analysis
North America
North America represents the most mature market for AI in operating systems, driven by a dense ecosystem of software giants, silicon designers, and enterprise early adopters. The requirement is heavily influenced by the high concentration of IT and financial services firms that require AI-driven security and productivity tools. Furthermore, the presence of major developers like Microsoft, Apple, and Google ensures that the region is the primary testbed for new OS features. The regulatory environment, while increasingly focused on safety, remains supportive of innovation through substantial R&D investments.
Asia Pacific
The Asia Pacific region is the fastest-growing market, characterized by rapid digitalization and a massive mobile-first consumer base. Demand in countries like China and India is driven by the expansion of AI-integrated smartphones and the growth of local OS alternatives designed for specific domestic ecosystems. The industrial base in Japan and South Korea further fuels demand for AI in real-time operating systems (RTOS) for robotics and automotive applications. Competitive dynamics are intense, with local players focusing on "Lite" AI OS versions to capture the entry-level device segment.
Europe
Europe’s market is defined by a rigorous regulatory focus, with the EU AI Act serving as the primary driver for how AI is implemented within operating systems. Demand is centered on "Trustworthy AI" and data-sovereign solutions, leading to a high uptake of open-source and privacy-centric OS environments. European enterprises are particularly interested in AI-driven compliance and security features that align with GDPR and other regional mandates. The industrial sector, especially in Germany and France, is a major driver for AI in edge computing and manufacturing-focused OS platforms.
List of Companies
Microsoft
Apple
Blackswan Technologies
Android Inc. (Google)
Humane
Rabbit Inc.
Red Hat, Inc.
Ubuntu (Canonical Ltd.)
IBM
Wind River Systems, Inc.
Microsoft
Microsoft holds a dominant market position in the desktop and enterprise OS space, leveraging its early integration of GPT-based models into the Windows ecosystem. Its strategy centers on the "Copilot" brand, positioning the operating system as an "AI Orchestrator" that bridges the gap between local hardware and cloud intelligence. Microsoft’s competitive advantage lies in its vast enterprise footprint through Microsoft 365, allowing it to deploy AI OS features to millions of users seamlessly. The company’s geographic strength is global, with a particularly strong hold on the corporate markets of North America and Europe.
Apple
Apple’s strategy for AI in operating systems is built on the pillar of "On-Device Privacy" and deep vertical integration. By designing its own silicon (Apple Silicon) and OS (iOS/macOS) in tandem, Apple achieves a level of hardware-software optimization that competitors struggle to match. Its competitive advantage is its "Apple Intelligence" framework, which prioritizes local processing and uses "Private Cloud Compute" for more complex tasks, maintaining a high level of user trust. Apple’s geographic strength is concentrated in the premium consumer segments of North America, China, and Europe, where users prioritize privacy and seamless ecosystem integration.
Blackswan Technologies
Blackswan Technologies occupies a specialized niche with its "ELEMENT" platform, described as the world’s first enterprise AI operating system. Its strategy focuses on cognitive computing and the transformation of raw data into actionable knowledge for data-intensive organizations. Unlike consumer-grade OS platforms, ELEMENT is designed to sit atop existing data infrastructures, providing an AI-driven management layer for financial institutions and large-scale enterprises. Its competitive advantage is its ability to perform contextual analytics and situational understanding, which is highly valued in risk management and compliance-heavy sectors.
Analyst View
The integration of generative AI into the operating system kernel is transforming system software into proactive agents. While North American vendors lead in innovation, navigating global regulatory frameworks remains a significant challenge. The future outlook hinges on localized "On-Device" inference.
Artificial Intelligence (AI) in the Operating System Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 17.7 billion |
| Total Market Size in 2031 | USD 42.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Devices, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
BY DEVICES
- Handheld devices
- Laptops and PCs
- Smart Appliances
- Others
BY APPLICATION
- Voice Assistance
- Personalization tools
- Software
- Applications
- Others
BY GEOGRAPHY
- North America
- United States
- Canada
- Others
- South America
- Brazil
- Argentina
- Europe
- Germany
- France
- United Kingdom
- Spain
- Middle East and Africa
- Saudi Arabia
- UAE
- Israel
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Taiwan
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. The Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. AI IN OPERATING SYSTEMS MARKET BY DEVICES
5.1. Introduction
5.2. Handheld Devices
5.3. Laptops and PCs
5.4. Smart Appliances
5.5. Others
6. AI IN OPERATING SYSTEMS MARKET BY APPLICATION
6.1. Introduction
6.2. Voice Assistance
6.3. Personalization Tools
6.4. Software
6.5. Applications
6.6. Others
7. AI IN OPERATING SYSTEMS MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Devices
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.2. Canada
7.2.3.3. Others
7.3. South America
7.3.1. By Devices
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Devices
7.4.2. By Application
7.4.3. By Country
7.4.3.1. Germany
7.4.3.2. France
7.4.3.3. United Kingdom
7.4.3.4. Spain
7.4.3.5. Others
7.5. Middle East and Africa
7.5.1. By Devices
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. UAE
7.5.3.3. Israel
7.5.3.4. Others
7.6. Asia Pacific
7.6.1. By Devices
7.6.2. By Application
7.6.3. By Country
7.6.3.1. China
7.6.3.2. Japan
7.6.3.3. India
7.6.3.4. South Korea
7.6.3.5. Indonesia
7.6.3.6. Taiwan
7.6.3.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Microsoft
9.2. Apple
9.3. Blackswan Technologies
9.4. Android Inc. (Google)
9.5. Humane
9.6. Rabbit Inc.
9.7. Red Hat, Inc.
9.8. Ubuntu (Canonical Ltd.)
9.9. IBM
9.10. Wind River Systems, Inc.
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size for AI in Operating Systems?
Market forecast to reach $42.6 billion by 2031, growing at 19.0% CAGR.
Which sector is the largest end-user of AI in operating systems?
Enterprise and professional productivity represents the largest end-user base.
Which region currently leads the AI in OS market?
North America maintains a leading position due to major OS vendors.
What technology shift is driving AI in OS market demand?
Shift to NPU-accelerated on-device inference from cloud-based AI processing.
How do regulations impact AI in Operating System design?
Regulations prioritize transparency and "Explainable AI" (XAI) in OS development.
What new monetization strategies are emerging at the OS level?
Transitioning to subscription-based "AI-as-a-Service" models.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Artificial Intelligence (AI) in the Operating System Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ai-in-the-operating-systems-market