
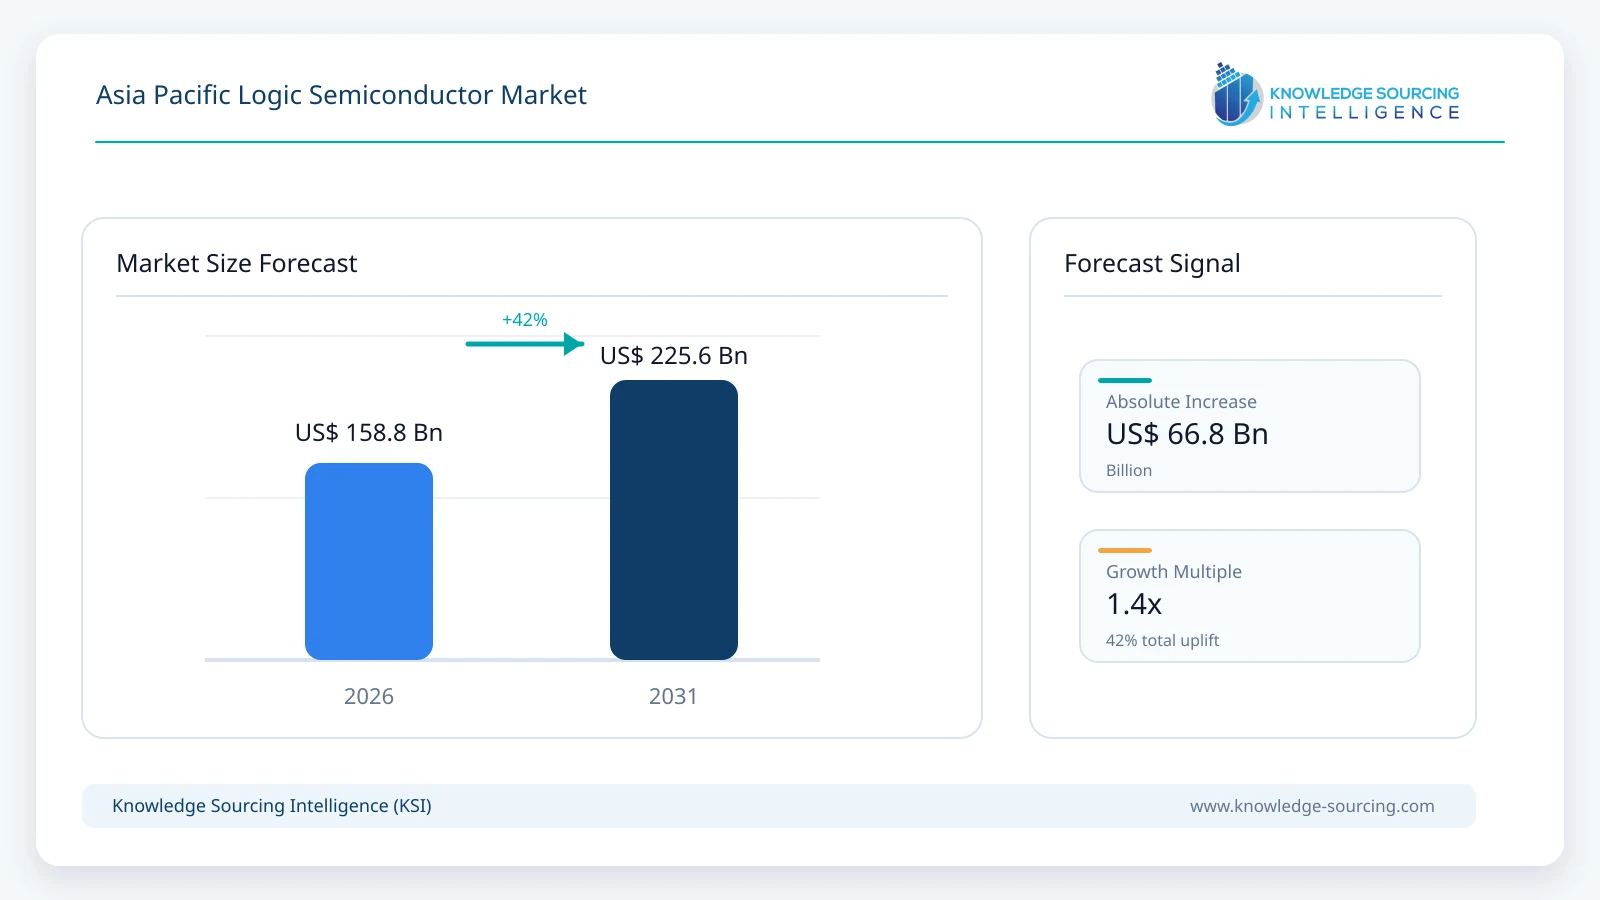
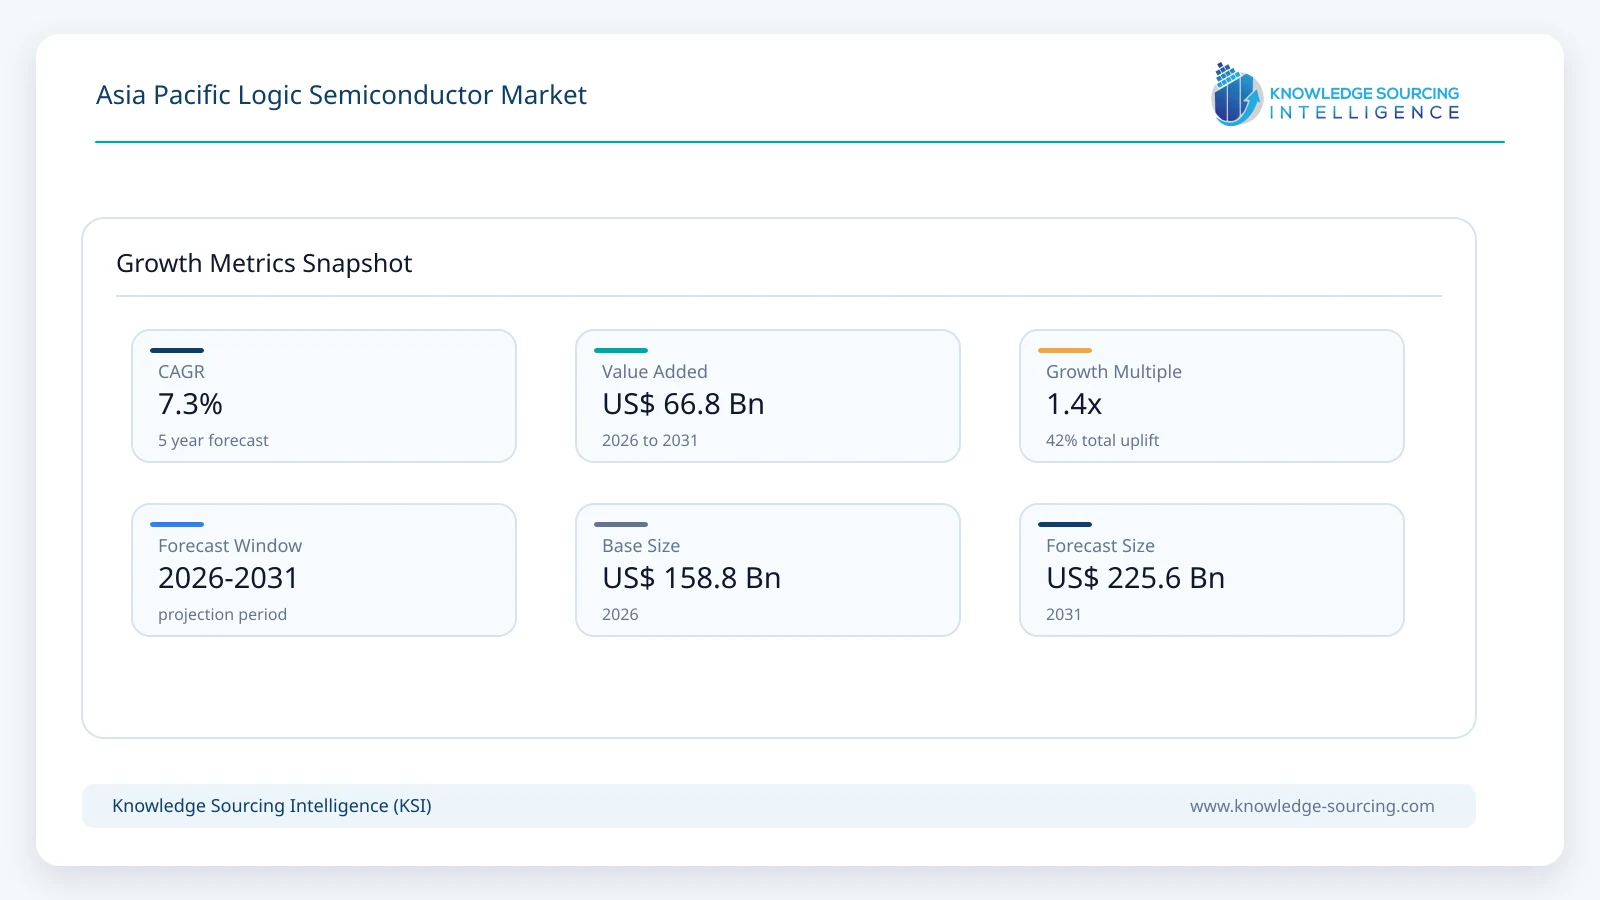
The Asia Pacific Logic Semiconductor Market is expected to expand at a CAGR of 7.27%, reaching USD 225.6 billion in 2031 from USD 158.8 billion in 2026.
Highlights:
- 1Application-specific integrated circuits account for approximately 45.5% of 2026 logic-device value.
- 2Consumer electronics retains the largest end-use share, while data-center logic raises growth intensity.
- 3China contributes about 44.1% of the regional market through electronics-system production and procurement.
- 4Advanced-node processors command higher value, but mature logic remains essential to industrial platforms.
- 5India records the strongest projected country growth as local electronics production broadens.
- 6Foundry capacity, packaging access and qualification increasingly influence logic-chip sourcing decisions.
Logic semiconductors execute digital computation, coordination, and control in electronic systems. The region’s product supply covers application-specific integrated circuits, programmable logic, general-purpose digital devices, display drivers and dedicated special-purpose components. These chips are specified in smartphones, communication infrastructure, computing systems, vehicle electronics and manufacturing equipment. Their commercial value is associated with the semiconductor device supplied to the equipment manufacturer, rather than the selling price of the complete handset, automobile or industrial machine.
Advanced logic fabrication increasingly supports application-specific computing workloads, while mature process nodes continue to serve display interfaces, industrial controllers and embedded products with longer design cycles. TSMC reported that technologies at 7 nanometers and below represented 77% of its wafer revenue in the second quarter of 2026, a measure of how sharply advanced fabrication has shifted toward high-value workloads. That foundry mix does not describe the whole logic device market: cost, availability, product longevity and qualification often favor less advanced nodes for automotive, industrial and commodity control devices.
Market Overview
Taiwanese fabless designers and semiconductor foundries occupy different positions in Asia-Pacific logic supply. MediaTek designs mobile and computing SoCs; Alchip develops custom high-performance ASIC solutions; TSMC fabricates products for external customers. The distinction matters commercially because foundry invoices and the downstream selling price of a finished logic device describe successive stages of the same supply chain. Regional market competition therefore depends on who controls chip architecture, IP, software support and customer qualifications, as well as who can secure wafer capacity and advanced packaging.
In July 2026, TSMC reported that 2nm processes had begun contributing to wafer revenue while 3nm and 5nm technologies accounted for the majority of its advanced fabrication mix. Samsung’s second-quarter announcement described additional 2nm foundry customer engagements and plans to ramp newer mobile products. At the chip-product level, Qualcomm and MediaTek introduced 2nm mobile platforms in September 2026, reflecting demand for stronger on-device inference, imaging and compute efficiency. Announced platform capabilities do not establish immediate high-volume sales across every Asian handset maker; premium device launches, package supply and production yields determine how quickly the new nodes affect revenue.
The mature-node portion of the market has a different operating cycle. UMC reported that 22/28nm accounted for 37% of second-quarter 2026 revenue, supported by demand from communication and consumer customers. Automotive control, industrial electronics and display support also require technologies that balance unit cost, validated reliability and long product availability. China’s official statistics recorded 484.28 billion integrated circuits manufactured in 2025, but this figure covers all IC categories and is not directly equivalent to logic-chip consumption or revenue. Logic demand across the region is consequently best understood as several overlapping production and purchasing systems, not a single advanced-node growth story.
Market Trends
Custom AI Logic Is Changing the Value Mix
Advanced computing projects increasingly require processors and accelerators optimized for a particular model architecture, network topology or power envelope. Taiwan-based Alchip reported that its 3nm accelerator product began shipping to a North American customer in May 2026, while a substantial portion of its second-quarter revenue came from 7nm and finer technologies. These examples establish a commercialization pathway for custom ASICs through Asian design and fabrication ecosystems, even when the chips ultimately serve customers outside the region.
High-complexity ASIC programs involve considerable nonrecurring engineering, IP qualification and packaging coordination. Customers may accept these costs to achieve greater performance per watt or improve control over accelerator supply, but the economics favor organizations with sufficient volumes. Standard logic and lower-complexity programmable devices will remain preferable when flexibility, shorter development cycles or limited procurement scale outweigh the benefits of a bespoke chip.
Mobile Platforms Are Integrating More On-Device Intelligence
Qualcomm’s September 2026 Snapdragon 8 Elite Gen 6 announcement and MediaTek’s Dimensity 9600 Pro launch illustrate how flagship mobile processors combine CPU, graphics, neural processing and imaging capabilities within tightly integrated digital architectures. Logic-chip suppliers are moving more functions onto the primary device to control power consumption and improve responsiveness in applications such as local generative AI, computational photography and gaming. The result is a richer product specification rather than merely a higher number of chips per handset.
Manufacturers face a narrow window in which advanced silicon can command premium pricing before performance features reach lower-cost models. New phone-platform adoption is tied to the release schedules of Chinese, Korean and other regional brands; weaker replacement demand can limit annual shipments even as the semiconductor content of premium devices improves. These volume-and-mix effects are central to interpreting consumer logic revenue.
Advanced and Mature Nodes Are Developing in Parallel
Samsung’s foundry roadmap emphasizes 2nm mobile and high-performance-computing engagements, while UMC continues to report meaningful customer demand at 22/28nm. The divergence reflects the economics of different applications. Large AI accelerators and premium smartphone SoCs benefit from more transistor density; industrial control, ordinary interface logic and many embedded products require reliable supply and long availability at manageable prices.
The industrial customer’s cost calculation includes more than wafer processing. Mask-set expenditure, firmware compatibility, testing, packaging, qualification and supply continuity determine whether a design migrates to a smaller node. Suppliers that maintain proven mature-node product families while allocating advanced capacity to higher-value designs are better placed to withstand swings in consumer demand and AI infrastructure spending.
Automotive Electronics Are Moving Toward Centralized Compute
Vehicle electronics increasingly combine functions previously distributed among separate controllers. Renesas began sampling its 3nm R-Car X5H automotive SoC in late 2025 for combinations of driver assistance, cockpit and gateway workloads, while its February 2026 research described a low-power, high-density logic building block suited to automotive systems. The commercial significance lies in integration and qualification rather than an assumption that every vehicle will immediately use the newest node.
Centralized architectures can lift the value of sophisticated processors even if the number of individual controllers falls. Automotive programs have extended qualification cycles and require robust functional safety, thermal performance and long-term software support. Demand therefore extends from high-performance application processors to stable supporting logic and interfaces, giving manufacturers more than one route to automotive revenue.
Supply Agreements Are Extending into Packaging and Design Services
The July 2026 collaboration announcement between Samsung Electronics and Broadcom concerned foundry technology, memory and advanced packaging for AI infrastructure. Advanced packaging is becoming a critical production constraint because heterogeneous compute systems depend on high-density interconnect, substrate availability and integration with memory. Chip designers increasingly select manufacturing partners partly on the ability to qualify complete packages, rather than wafer process capability alone.
The value chain is consequently more interdependent. Foundries, outsourced assembly providers, IP suppliers and designers often participate in a single program, but their revenues cannot be read as separate demand for finished logic chips. Manufacturing concentration also raises exposure to project delays or cross-border restrictions, particularly for designs dependent on leading-edge nodes and specialized packaging.
Segment Analysis
By Type: Application Specific Integrated Circuit
Application-specific integrated circuits are expected to reach USD 109.42 billion in regional value by 2031 as customers specify digital functionality for AI infrastructure, high-end mobile platforms, communications and dedicated computing products. ASIC suppliers combine architecture, reusable IP and access to advanced foundries, often committing significant engineering resources before volume supply begins. Alchip’s documented 3nm accelerator deliveries and Broadcom’s involvement in customized infrastructure silicon illustrate two different commercial approaches within the segment.
The economics favor application-specific design when high shipment values or repeatable deployments recover engineering and mask costs. They are less favorable for short product runs that need continuing logic reconfiguration. The region’s mature custom-chip base also extends well beyond leading-edge AI, with dedicated processing and interface products in electronics and industrial equipment. Greater ASIC penetration therefore reflects the mix of high-value digital functions, not the replacement of every programmable or standard logic device.
By Industry Vertical: Consumer Electronics
Consumer electronics remains the largest end-use category because Asia Pacific is home to major smartphone, computer, television and connected-device assembly operations. Its 2026 share is estimated at 33.0%, reflecting broad demand for mobile SoCs, application processors, display-control logic and embedded digital functions. China’s smartphone and electronics production scale provides an especially large procurement base, while suppliers in Taiwan and South Korea compete for performance and power-efficiency improvements that influence device design wins.
The industry’s revenue mix is gradually changing as cloud-computing and specialized accelerator systems grow faster. Consumer devices nonetheless retain recurring product cycles and large annual production volumes. Higher-end smartphone logic can increase value per device, but manufacturers also face cost pressure in mainstream products, tighter inventory management and uneven consumer replacement demand. These conditions moderate aggregate growth despite major advances at the premium end of the portfolio.
Market Drivers
Expansion of High-Performance AI Computing
AI infrastructure has raised demand for custom digital processors and accelerated computing architectures that depend heavily on Asian fabrication and packaging capacity. TSMC reported that high-performance computing represented 66% of its second-quarter 2026 platform revenue, while Alchip disclosed customer shipments of 3nm accelerator silicon. These figures concern different points in the value chain but indicate sustained demand for advanced logic design and manufacturing. The expansion supports high-value ASIC content, increasing the commercial importance of advanced packaging, reliable capacity reservations and efficient design implementation.
Integration of More Processing into Mobile Devices
Smartphone chipset specifications now combine substantial CPU, GPU, AI, imaging and communication processing in integrated designs. Qualcomm and MediaTek introduced 2nm mobile platforms in September 2026, supplying concrete examples of product-level innovation. Demand depends on how rapidly OEMs adopt the newer platforms and how the devices perform in terms of power, heat and user-facing features. Competitive differentiation is increasingly based on the total system capability of the chip rather than the number of digital gates alone, supporting higher average value in premium tiers.
Digitization of Industrial and Factory Equipment
Factory automation and connected equipment require deterministic logic for monitoring, control, motor coordination and machine interfaces. China’s official 2025 production statistics record 773,000 industrial robots, while its electronics manufacturing output expanded further during the year. Those indicators do not directly measure logic semiconductor purchases, but they point to a substantial installed manufacturing ecosystem that needs embedded control electronics. Suppliers offering long-lifecycle products and compatible software tools can access repeat production programs across robotics, programmable equipment and factory networks.
Higher Electronic Content in Vehicles
Vehicle electronic architectures are moving toward consolidated computers, advanced driver assistance and more capable cockpit systems. Renesas’ R-Car Gen 5 family demonstrates that one processor can coordinate multiple domains, introducing demand for high-performance digital logic with automotive-grade safety and longevity. The transition coexists with conventional microcontrollers and support devices for powertrain, comfort and body functions. Longer qualification cycles constrain the speed of adoption, but a successful platform nomination can sustain chip demand across several vehicle models and production years.
Broader Asian Electronics Production Networks
China remains a large end-market and integration center for semiconductor-intensive products, while India and Southeast Asia are expanding electronic-device assembly and related component procurement. India’s February 2026 semiconductor programme update confirmed investment approvals across fabrication, packaging and supporting infrastructure. Approvals are not equivalent to immediate commercial wafer output, but the associated assembly and design ecosystem can increase local sourcing and qualification activity. Regional diversification also gives chip producers additional manufacturing customers outside the most established Northeast Asian clusters.
Market Restraints
High Design and Qualification Costs for Advanced Logic
Leading-edge ASIC development requires expensive mask sets, complex validation and specialized engineering, while physical design and packaging must work reliably under demanding power and thermal limits. Alchip’s commercialization progress at 2nm and 3nm demonstrates both customer interest and the technical resources needed to bring such products forward. A smaller electronics manufacturer may find standard or programmable logic more economical than a proprietary device. The resulting customer concentration can make advanced logic demand sensitive to the timing of a few major programs and the availability of specialized design talent.
Wafer Capacity and Advanced Packaging Concentration
High-performance logic production relies on a limited group of leading-edge foundries and assembly ecosystems. TSMC’s rapid 2nm production ramp and Samsung’s advanced-node investment increase capacity but do not eliminate bottlenecks in substrates, high-density interconnect or testing. New manufacturing sites also require lengthy qualification before they can produce critical designs consistently. A disruption to a particular process, packaging line or materials supply can delay several chip programs at once, making capacity planning and multi-sourcing difficult even when underlying end-market demand remains strong.
Export Controls and Technology Access Restrictions
Controls affecting advanced computing devices, chip-design technology and semiconductor manufacturing equipment can reshape the products available to different markets. Suppliers operating across Taiwan, China, Japan, South Korea and multinational customer networks must assess restrictions at the level of process technology, end use and customer. Compliance costs can lengthen design and procurement decisions, while a change in permitted technology can require product redesign. The effect is uneven: mature industrial or display logic may have different exposure from leading-edge AI accelerators.
Cyclicality in Consumer Electronics
Mobile phones, consumer computing and entertainment devices are major users of logic products, but demand is affected by consumer replacement cycles and manufacturer inventories. China’s official figures show that its 2025 smartphone production declined slightly even as total IC output increased. That divergence illustrates why overall wafer or integrated-circuit growth cannot be translated automatically into higher demand for every logic application. Chip providers with heavy exposure to a small number of handset models can see shipment patterns and pricing change rapidly between product generations.
Mature-Node Pricing and Platform Substitution
General-purpose and interface logic products face longstanding pressure from customer cost targets and integration into larger systems-on-chip. As more functions move into an application processor, some separate supporting devices may be removed from the bill of materials. At the same time, industrial customers often retain mature products because qualification and software compatibility discourage redesign. This combination creates uneven revenue conditions: unit shipments may remain resilient while selling prices weaken in standard devices, and customers may prefer integrated digital solutions over replacement of individual chips.
Regional Outlook
China: Largest Country Market
China is estimated to contribute 44.1% of Asia-Pacific logic semiconductor demand in 2026, supported by large-scale electronics manufacturing, smartphone production, automotive electronics and networking-equipment procurement. The country’s National Bureau of Statistics recorded 484.28 billion integrated circuits produced in 2025 and a 10.9% annual increase, although that figure covers memory, analog and other devices as well as logic. China’s broad equipment base allows both advanced application processors and mature interface logic to reach substantial customers through local and multinational supply chains.
Demand is expected to broaden across connected equipment, vehicles and higher-performance computing, while domestic semiconductor capabilities continue to develop. Chinese chip designers have opportunities in special-purpose devices and mature logic, but leading-edge fabrication access and export restrictions influence the highest-end products. The interaction of strong downstream demand with a competitive supplier base makes pricing and technical differentiation more important than simple production-volume growth.
India: Fastest-Growing Country Market
India’s logic semiconductor market is projected to expand at approximately 16.2% annually through 2031 as local electronics assembly, automotive digitization and device-design activity increase. The Ministry of Electronics and Information Technology reported in February 2026 that ten projects had been approved under the national semiconductor ecosystem programme, including fabrication and packaging facilities. Their eventual output will depend on construction, qualification, customer nominations and utilization rather than approval alone.
The stronger near-term purchasing case comes from systems assembled domestically: phones, industrial equipment, vehicle electronics and connected products require a wider set of digital control devices as production scales. India’s current logic revenue base is much smaller than China’s and Taiwan’s, making rapid growth possible without a comparable share of regional value by 2031. Local design support, consistent availability of qualified components and competitive pricing will influence how much of the demand is met through regional distribution versus domestic semiconductor production.
Competitive Landscape
MediaTek, Qualcomm and Samsung Electronics compete in highly integrated application processors and mobile platforms, where performance, software ecosystems, power management and brand-level design wins influence demand. Taiwan-based Alchip and Socionext address custom computing and ASIC programs, while Broadcom targets complex connectivity and AI infrastructure functions. These companies do not all sell to the same customer group: the development costs, contractual arrangements and sales cycles of a cloud accelerator differ markedly from those of a consumer handset chipset.
Renesas, NXP and STMicroelectronics participate through automotive, embedded and industrial processing, where product support and long qualification cycles often carry greater weight than the smallest fabrication geometry. Realtek, Novatek, Rockchip and UNISOC address important segments of connectivity, display and application-specific consumer logic. Foundries such as TSMC and Samsung provide the fabrication capacity that supports many of these devices, but the competitive significance of a foundry contract must be distinguished from the finished semiconductor sold by the chip vendor. Regional leadership is therefore distributed among product owners, design specialists and fabrication partners rather than belonging to a single manufacturing model.
Recent Developments
22 September 2026: Qualcomm introduced its Snapdragon 8 Elite Extreme Gen 6 and Snapdragon 8 Elite Gen 6 mobile SoCs, detailing 2nm logic platforms for forthcoming premium smartphones.
15 September 2026: MediaTek introduced the 2nm Dimensity 9600 Pro mobile SoC, expanding its high-end logic portfolio with integrated on-device AI processing.
26 August 2026: Alchip reported second-quarter results and confirmed that a 3nm accelerator product had begun shipping to a North American customer in May, demonstrating a commercial custom-ASIC program.
29 July 2026: UMC reported second-quarter results with 22/28nm technology generating 37% of revenue and utilization reaching 85%, showing continuing activity in established foundry process nodes.
25 July 2026: Samsung Electronics and Broadcom signed a memorandum of understanding covering next-generation AI infrastructure, foundry technologies, memory and advanced packaging; the agreement was not a production contract.
16 July 2026: TSMC reported second-quarter financial results showing 2nm wafer revenue contribution and a 77% share for process technologies at 7nm and below, alongside strong high-performance-computing demand.
Market Outlook
Asia-Pacific logic semiconductors are expected to gain value through a changing composition of digital devices rather than uniform expansion across all product families. Custom AI and infrastructure ASICs command greater engineering attention and higher chip values, while mobile SoCs continue to improve computing performance within strict thermal limits. Industrial and automotive customers maintain demand for more established processes, helping stabilize parts of the market whose production economics differ from premium computing. The suppliers best positioned to benefit will combine suitable chip architectures with manufacturing capacity, application software and reliable qualification support.
China will remain the largest equipment-manufacturing and procurement market, while India has scope for faster gains as its domestic assembly base expands. Taiwan, South Korea and Japan will continue contributing design, fabrication and high-reliability device capabilities. Constraints around capital intensity, foundry access, advanced packaging and technology controls are unlikely to disappear; customer procurement and product-design strategy will increasingly reflect those risks. The result should be a market in which the fastest-growing functions capture a larger share of revenue without displacing lower-cost logic across everyday electronic systems.
Asia Pacific Logic Semiconductor Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 158.8 billion |
| Total Market Size in 2031 | USD 225.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.27% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Industry Vertical -, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Special Purpose Logic
Display Drivers
General Purpose Logic
Application-Specific Integrated Circuit
Programmable Logic Device
By Industry Vertical
Communication
Consumer Electronics
Automotive
Manufacturing
Other Applications
By Geography
China
South Korea
Japan
Taiwan
India
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Currency and Forecast Timeline
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of High-Performance AI Computing
3.1.2. Integration of More Processing into Mobile Devices
3.1.3. Digitization of Industrial and Factory Equipment
3.1.4. Higher Electronic Content in Vehicles
3.1.5. Broader Asian Electronics Production Networks
3.2. Market Restraints
3.2.1. High Design and Qualification Costs for Advanced Logic
3.2.2. Wafer Capacity and Advanced Packaging Concentration
3.2.3. Export Controls and Technology Access Restrictions
3.2.4. Cyclicality in Consumer Electronics
3.2.5. Mature-Node Pricing and Platform Substitution
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Advanced-Nodes and Mature-Nodes
4.2. ASIC Design and Chiplet Integration
4.3. Logic Device Packaging and Qualification
5. ASIA PACIFIC LOGIC SEMICONDUCTOR MARKET BY TYPE
5.1. Special Purpose Logic
5.2. Display Drivers
5.3. General Purpose Logic
5.4. Application Specific Integrated Circuit
5.5. Programmable Logic Device
6. ASIA PACIFIC LOGIC SEMICONDUCTOR MARKET BY INDUSTRY VERTICAL
6.1. Communication
6.2. Consumer Electronics
6.3. Automotive
6.4. Manufacturing
6.5. Other Applications
7. ASIA PACIFIC LOGIC SEMICONDUCTOR MARKET BY GEOGRAPHY
7.1. China
7.2. South Korea
7.3. Japan
7.4. Taiwan
7.5. India
7.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. MediaTek Inc.
9.2. Samsung Electronics Co., Ltd.
9.3. Qualcomm Incorporated
9.4. Broadcom Inc.
9.5. Renesas Electronics Corporation
9.6. NXP Semiconductors N.V.
9.7. STMicroelectronics N.V.
9.8. Realtek Semiconductor Corp.
9.9. Novatek Microelectronics Corp.
9.10. Alchip Technologies, Limited
9.11. Socionext Inc.
9.12. Rockchip Electronics Co., Ltd.
9.13. UNISOC (Shanghai) Technologies Co., Ltd.
9.14. Taiwan Semiconductor Manufacturing Company Limited
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market growth for Asia Pacific Logic Semiconductors?
The Asia Pacific Logic Semiconductor Market is projected to reach USD 225.6 billion by 2031, at a 7.27% CAGR.
Which logic device segment holds the largest value share in Asia Pacific?
Application-specific integrated circuits account for 45.5% of 2026 logic-device value.
Which country contributes most to the Asia Pacific Logic Semiconductor Market?
China contributes about 44.1% of the regional market share.
Which Asia Pacific country shows the strongest logic semiconductor market growth?
India records the strongest projected country growth as local electronics production broadens.
Which end-use industry has the largest share in the Asia Pacific market?
Consumer electronics retains the largest end-use share; data-center logic raises growth.
What factors increasingly influence logic-chip sourcing decisions?
Foundry capacity, packaging access, and qualification increasingly influence logic-chip sourcing decisions.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia Pacific Logic Semiconductor Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/asia-pacific-logic-semiconductor-market