
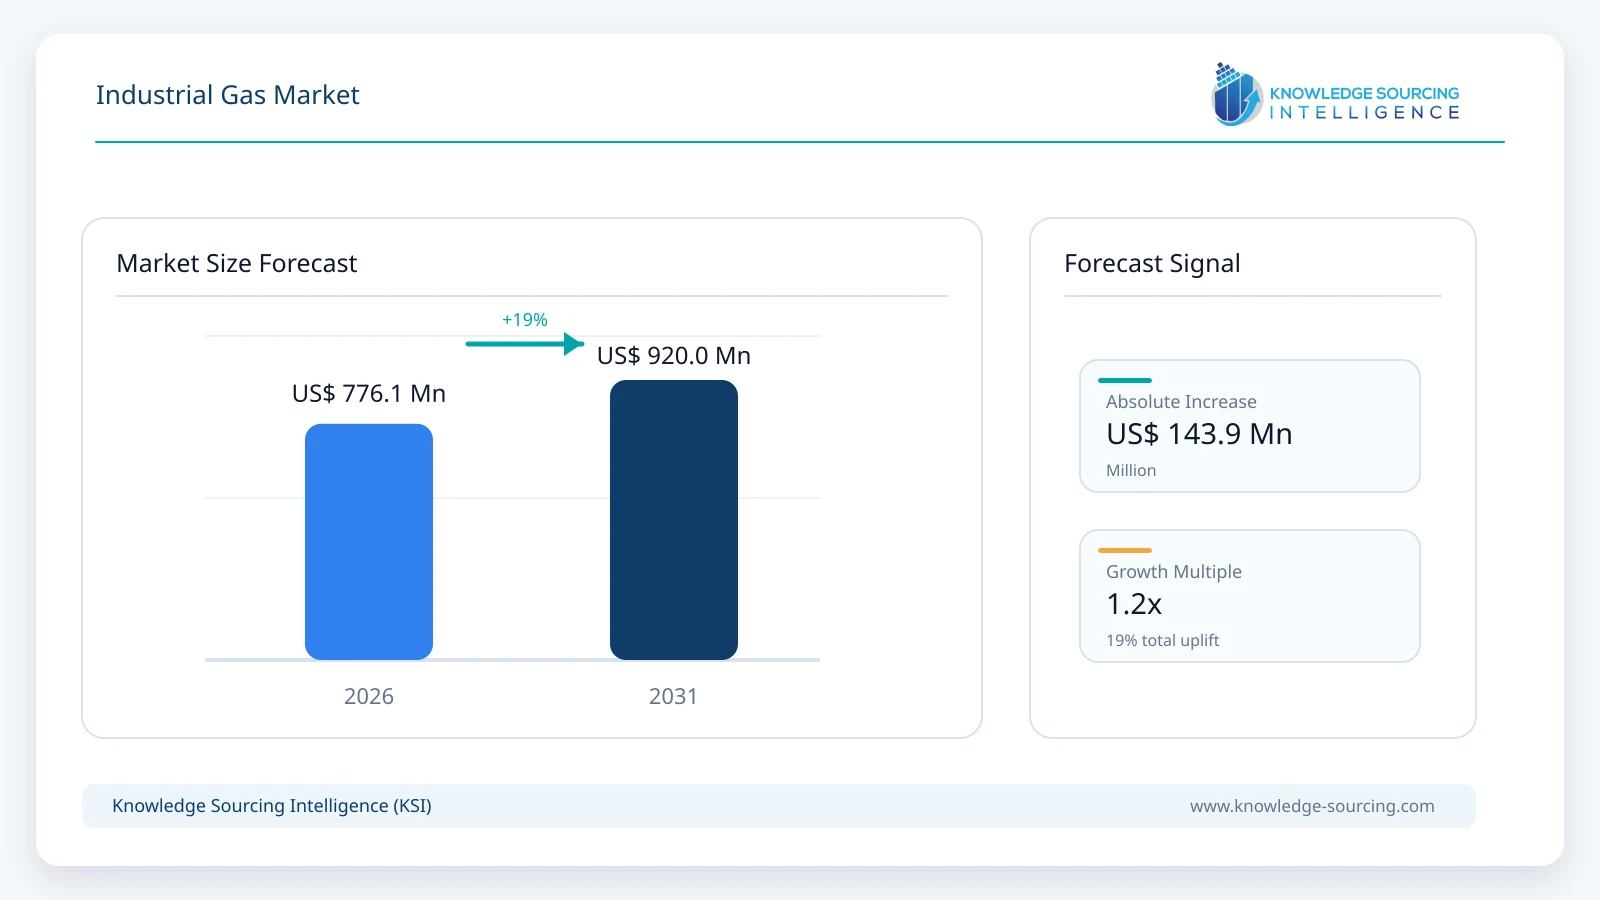
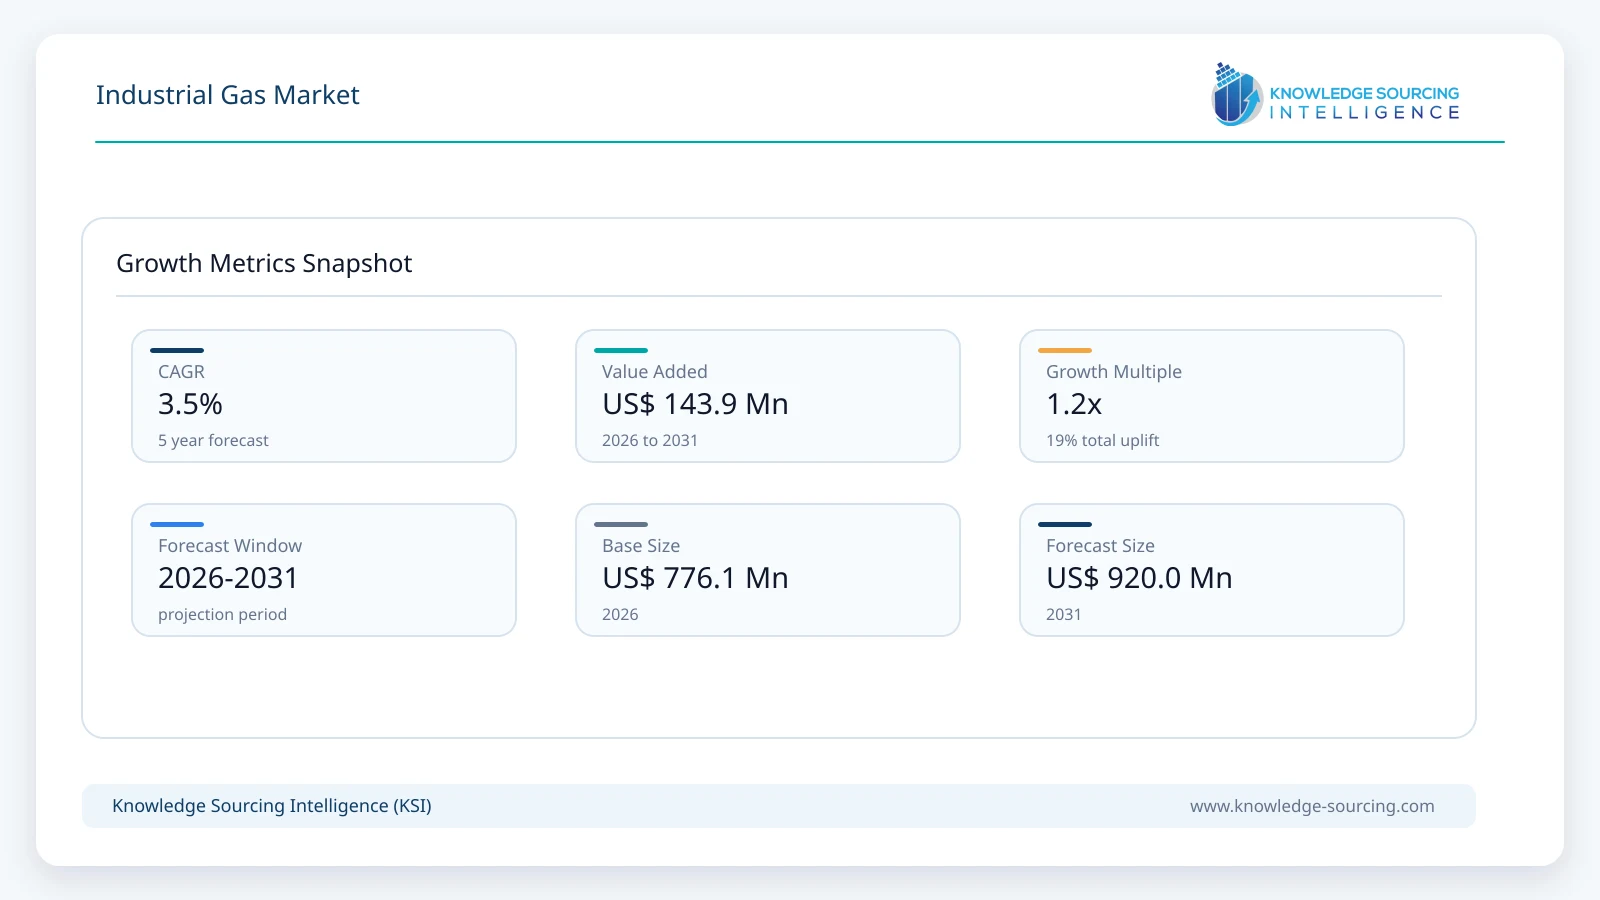
The industrial gas market for flat panel display market is evaluated at USD 776.1 million in 2026 and is projected to grow at a CAGR of 3.5% to reach a market size of USD 920.0 million by 2031.
Highlights:
- 1High-purity electronic gases remain indispensable for deposition, etching, chamber cleaning, and process stability across display fabrication.
- 2Display manufacturers increasingly prioritize uninterrupted gas supply, purity assurance, and integrated gas management services.
- 3OLED, MicroLED, and Mini-LED manufacturing require tighter contamination control and higher-value specialty gas consumption.
- 4Asia Pacific continues to concentrate manufacturing capacity, encouraging localized investments in specialty gas production.
- 5Environmental regulations governing fluorinated gases are accelerating adoption of abatement systems and lower-emission process technologies.
Key Highlights
Market Overview
Demand is closely linked to investments in LCD, OLED, Mini-LED, and emerging MicroLED production lines. Although LCD continues to account for a considerable share of installed manufacturing capacity, capital expenditure increasingly targets premium display technologies that require tighter process control and greater consumption of electronic specialty gases such as silane, nitrogen trifluoride (NF3), nitrous oxide, hydrogen fluoride, and sulfur hexafluoride. Bulk gases including nitrogen, hydrogen, helium, argon, and oxygen remain essential for inert processing environments, carrier applications, cooling, and equipment operation. Air Liquide notes that modern display fabrication facilities require roughly twenty electronics specialty materials together with continuous supplies of ultra-high-purity carrier gases and comprehensive gas management systems.
Purchasing decisions increasingly extend beyond gas molecules themselves. Buyers seek suppliers capable of designing distribution infrastructure, providing on-site generation, maintaining analytical monitoring systems, and ensuring uninterrupted delivery across multi-year production cycles. This requirement favors companies operating integrated production, purification, logistics, and service networks near display manufacturing clusters.
Commercial opportunities over the 2026 to 2031 period will depend primarily on investments in next-generation display fabrication, localization of electronic gas production, compliance with tightening environmental requirements for fluorinated gases, and suppliers' ability to maintain exceptionally high purity while reducing operating costs and emissions.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Display fabrication gas portfolio | Around 20 electronics specialty materials used per display fab | Demonstrates the technical complexity of gas supply requirements. |
Electronic specialty gases covered by industry | 71 gas products (2026) | Reflects expanding process specialization across electronics manufacturing. |
Manufacturing focus | Asia remains the primary display manufacturing hub | Suppliers continue expanding production close to customer fabs. |
Core bulk gases | Nitrogen, hydrogen, oxygen, helium and argon | Reliable bulk gas infrastructure remains fundamental to fab operations. |
Core specialty gases | Silane, NF3, and nitrous oxide | These gases remain essential across deposition and chamber-cleaning processes. |
Market Drivers
Expansion of advanced display fabrication capacity. OLED, Mini-LED, and MicroLED manufacturing requires increasingly sophisticated thin-film deposition, plasma processing, and chamber cleaning operations that consume higher-value electronic specialty gases. Display fabrication resembles semiconductor manufacturing in its dependence on contamination-free production environments and continuous high-purity gas delivery. Equipment suppliers and gas producers are therefore expanding purification capability, bulk delivery infrastructure, and analytical services around major display manufacturing locations. This investment supports long-term supply agreements while increasing demand for specialty gas management throughout new fabrication facilities.
Increasing process purity requirements are raising demand for integrated gas management. Yield improvement remains one of the strongest purchasing priorities for display manufacturers because contamination during deposition or etching directly affects panel quality and manufacturing economics. Rather than purchasing gases as standalone commodities, manufacturers increasingly procure complete solutions including purification equipment, distribution systems, continuous monitoring, analytical services, and inventory management. Air Liquide and Linde have expanded integrated gas supply models that combine specialty gases, bulk gases, pipeline infrastructure, and process monitoring, reflecting customer preference for suppliers capable of supporting entire fabrication ecosystems instead of individual products.
Localization of electronics manufacturing is encouraging regional gas production investments. Concentration of display manufacturing across China, South Korea, Taiwan, and Japan has encouraged industrial gas suppliers to establish production assets closer to fabrication plants to reduce logistics risk and improve supply continuity. High-purity gases require specialized handling, making local production and distribution commercially attractive. Linde and Air Liquide continue investing in dedicated electronics gas production and on-site nitrogen facilities across Asia, while suppliers strengthen regional logistics networks to support expanding fabrication capacity and reduce delivery lead times.
Environmental requirements are accelerating process optimization and specialty gas innovation. Display manufacturers face increasing pressure to reduce emissions associated with fluorinated process gases such as NF3, SF6, and CF4. Regulatory expectations and corporate sustainability commitments are encouraging investments in improved chamber-cleaning processes, abatement technologies, and lower-emission manufacturing practices without compromising production yield. Display manufacturers are also expanding installation of gas abatement systems and adopting process modifications that reduce greenhouse gas emissions. These requirements increase demand for technically advanced gas products together with engineering and environmental support services from industrial gas suppliers.
Market Restraints and Challenges
Stringent purity specifications increase production costs and limit supplier participation. Electronic specialty gases supplied to flat panel display manufacturers require impurity concentrations measured at extremely low levels because contaminants can reduce production yield and damage fabrication equipment. Maintaining these specifications requires multiple purification stages, advanced analytical instruments, dedicated packaging systems, and contamination-controlled logistics. Air Products, Linde, and Air Liquide continue investing in purification technology and quality assurance to meet customer requirements, while smaller suppliers often face high qualification costs before securing commercial supply contracts. These barriers are structural and contribute to supplier concentration in premium gas categories.
Fluorinated process gases face increasing environmental scrutiny. Nitrogen trifluoride (NF3), sulfur hexafluoride (SF6), and tetrafluoromethane (CF4) remain essential for plasma etching and chamber-cleaning applications, yet they possess high global warming potential. Environmental agencies in several jurisdictions continue tightening emissions reporting and encouraging the installation of gas abatement systems. Display manufacturers therefore incur additional investment in emissions control equipment, while gas suppliers increasingly develop lower-emission process solutions and provide engineering support. The challenge affects operating costs rather than eliminating demand because these gases remain technically difficult to replace in several manufacturing processes.
Supply-chain resilience remains a procurement priority following recent industry disruptions. Display fabrication operates continuously, making production interruptions costly. Specialty gases often depend on dedicated production assets, certified transport systems, and qualified cylinder handling procedures. Geopolitical tensions, transportation disruptions, energy price volatility, and dependence on limited manufacturing locations have encouraged display manufacturers to diversify suppliers and maintain higher inventory levels for critical gases. Major industrial gas companies are responding by expanding regional production capacity, establishing redundant supply networks, and investing in local distribution infrastructure, although duplication increases capital requirements and operating costs.
Qualification cycles delay supplier entry into display manufacturing. Display manufacturers typically validate specialty gas suppliers through extensive process qualification before approving production use. Every change in gas specification, purification process, packaging configuration, or manufacturing site requires additional verification to avoid affecting production yield. These qualification procedures lengthen commercialization timelines for new suppliers and restrict rapid substitution, particularly for specialty gases used in deposition and plasma processing. Established suppliers therefore benefit from long customer relationships, while new entrants must demonstrate consistent quality, supply reliability, and analytical capability before participating in large-volume contracts.
Major Segment Analysis
Electronic Specialty Gases
Electronic specialty gases represent the most commercially important product category because they directly influence deposition quality, plasma etching performance, chamber cleaning efficiency, and manufacturing yield. Silane, nitrogen trifluoride, nitrous oxide, ammonia, hydrogen fluoride, hydrogen chloride, sulfur hexafluoride, and tetrafluoromethane perform highly specialized process functions that cannot easily be substituted without modifying fabrication equipment or production recipes. Consequently, purchasing decisions emphasize purity certification, process consistency, technical support, and long-term supply security rather than purchase price alone.
Demand increasingly reflects the industry's migration toward OLED, Mini-LED, and MicroLED production, where tighter process tolerances require higher-purity specialty gases and advanced analytical monitoring. Suppliers compete through purification capability, proprietary production processes, localized manufacturing, and engineering services that integrate gas delivery with process optimization. Qualification periods remain considerably longer than those for bulk gases because manufacturers validate gas quality under actual production conditions before approving commercial supply. These characteristics support comparatively higher value creation within the specialty gas segment and reinforce long-term customer relationships based on manufacturing performance rather than commodity pricing.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Specialty gas production, process innovation, equipment development | Limited large-scale display panel manufacturing |
Europe | Environmental compliance, specialty materials expertise | Smaller display fabrication footprint |
Asia Pacific | Concentration of global display manufacturing and capacity expansion | Supply-chain resilience and environmental compliance |
Middle East and Africa | Industrial gas infrastructure development supporting electronics investment | Limited domestic display manufacturing ecosystem |
North America
North America remains an important center for electronic specialty gas development, purification technology, and equipment innovation despite relatively limited flat panel display manufacturing capacity. Industrial gas suppliers including Air Products, Linde, and Air Liquide maintain substantial research, engineering, and production capabilities supporting global electronics customers. Demand is primarily linked to specialty gas manufacturing, research activities, semiconductor ecosystems, and exports rather than large-scale panel fabrication. Customers increasingly prioritize supply resilience and diversified sourcing following recent global logistics disruptions.
Europe
European demand is supported by specialty materials production, industrial gas technology, environmental compliance expertise, and advanced manufacturing research. Regulatory attention toward fluorinated greenhouse gases encourages investments in emissions reduction technologies, gas recovery systems, and process optimization. Industrial gas suppliers continue strengthening high-purity production capabilities while serving multinational display manufacturers operating globally. Commercial activity is concentrated more in technology development and specialty materials than in large-scale display panel production.
Asia Pacific
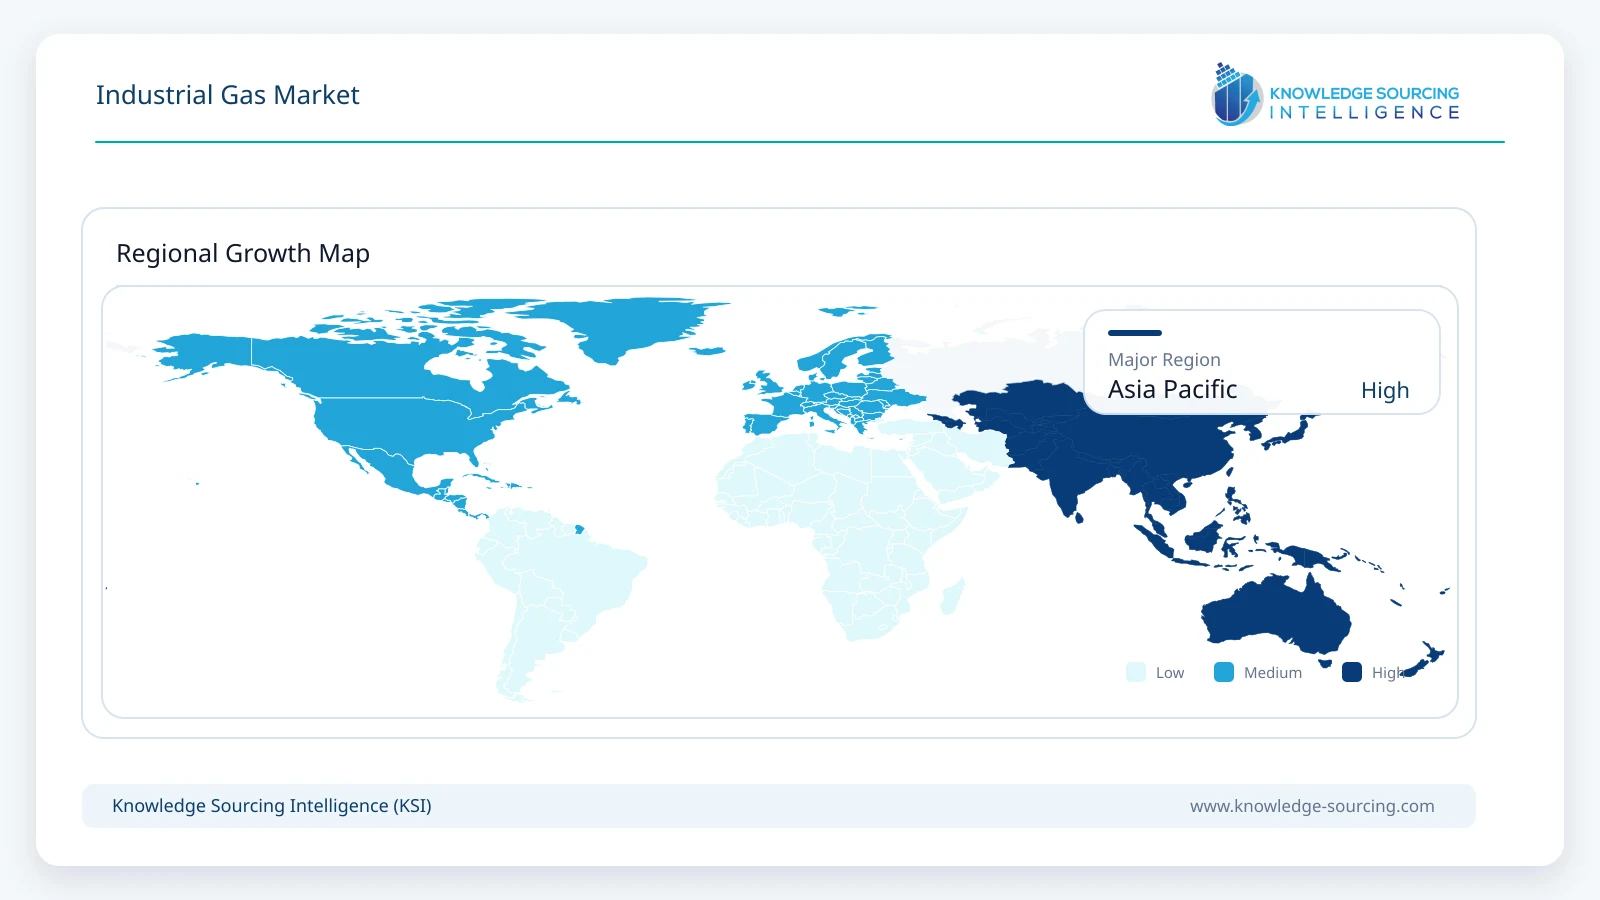
Asia Pacific remains the center of commercial activity because China, Japan, South Korea, and Taiwan host most global flat panel display manufacturing capacity. The region combines extensive fabrication infrastructure with established electronics supply chains, specialty chemical production, equipment manufacturers, and industrial gas facilities. Display producers continue investing in OLED, Mini-LED, and MicroLED manufacturing, encouraging suppliers to expand local purification plants, bulk gas production, and distribution networks. Competition is also strongest in this region because buyers evaluate suppliers on production reliability, technical service, environmental performance, and uninterrupted delivery to high-volume fabrication facilities.
Middle East and Africa
The Middle East and Africa currently represent an emerging commercial opportunity rather than a major display manufacturing base. Regional investment focuses primarily on industrial gas production, infrastructure development, and broader electronics manufacturing initiatives. Although local flat panel display fabrication remains limited, improvements in industrial infrastructure and diversification strategies could gradually support higher demand for electronic gases through component manufacturing, assembly operations, and future electronics investments. International suppliers generally participate through regional distribution partnerships rather than dedicated display-focused production facilities.
Competitive Landscape
The industrial gas market for flat panel displays is characterized by high technical barriers rather than a large number of interchangeable suppliers. Product qualification requirements, ultra-high-purity manufacturing, dedicated distribution infrastructure, and long customer approval cycles favor companies with established electronics businesses and extensive production networks. Competition therefore extends beyond gas supply to encompass purification technology, analytical capabilities, engineering services, and long-term supply reliability.
Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, and Messer Group GmbH compete through integrated gas production, on-site supply systems, and global manufacturing footprints. SK Specialty and Kanto Denka Kogyo strengthen competition in electronic specialty gases, particularly fluorinated process gases used in deposition and chamber cleaning, while Merck KGaA and Entegris expand their positions through electronic materials, contamination control, and process integration solutions. Matheson Tri-Gas supports customers with specialty gas production and localized distribution. Across the industry, suppliers continue investing in regional manufacturing capacity, digital monitoring systems, emissions reduction technologies, and supply-chain resilience to meet increasingly stringent customer requirements and environmental obligations.
Recent Developments
September 2026: LG Display launched its 24.5-inch 720Hz Gaming OLED panel, initiating mass production with a 0.02-millisecond response time for esports monitors.
August 2026: LG Display unveiled FLiPP, its proprietary fine-metal-mask-free OLED patterning technology, targeting brighter panels, longer lifespans, and reduced power consumption through manufacturing innovation.
August 2026: BOE showcased more than 50 display innovations at DIC EXPO 2026, including transparent OLED, crease-free OLED, RGBX, and chip-on-glass Micro LED technologies.
April 2026: Air Products announced expansion of industrial gas supply for Samsung Electronics’ advanced semiconductor fab in South Korea. The project includes onsite production facilities and specialty gas systems supporting high-purity nitrogen, oxygen, argon, and hydrogen requirements.
January 2026: Air Liquide completed acquisition of DIG Airgas, strengthening its South Korean industrial gas presence. The deal expanded capabilities serving electronics manufacturing sectors, including semiconductor and display-related high-technology production ecosystems.
October 2025: Air Liquide announced acquisition agreement for NovaAir in India, expanding industrial gas operations serving electronics, photovoltaic, and advanced manufacturing customers. The move enhanced regional supply capabilities for specialty gases and onsite services.
Regulatory and Policy Environment
Environmental regulation continues to influence both gas selection and manufacturing practices across the flat panel display industry. Fluorinated gases such as nitrogen trifluoride, sulfur hexafluoride, and tetrafluoromethane remain technically important for plasma processing and chamber cleaning, yet they are increasingly subject to emissions reporting requirements and greenhouse gas reduction policies in major manufacturing regions. As a result, display manufacturers are expanding investment in gas abatement systems, process optimization, and emissions monitoring while working with suppliers to reduce process-related emissions without compromising production yield.
Quality management requirements also remain stringent throughout the value chain. Electronic specialty gases must comply with demanding purity specifications supported by continuous analytical verification, contamination control, and validated production systems. Industry standards promoted by organizations such as SEMI support consistent material quality, safety, and interoperability across electronics manufacturing, helping suppliers meet increasingly sophisticated customer requirements while reducing operational risk.
Outlook and Strategic Implications
Demand between 2026 and 2031 is expected to be shaped by continued investment in higher-performance display technologies, greater localization of electronics manufacturing, and stricter environmental expectations governing specialty gas use. Premium display technologies will require tighter contamination control, more sophisticated gas delivery systems, and higher-value specialty gases than conventional display manufacturing. These trends are likely to strengthen the commercial importance of suppliers capable of combining production capacity with engineering services, analytical expertise, and integrated infrastructure.
Strategic priorities across the value chain are expected to include:
Manufacturers: Expand localized production capacity, strengthen purification capability, and improve supply resilience near major display manufacturing clusters.
Display producers: Prioritize long-term supply agreements, emissions reduction, process stability, and uninterrupted gas availability to maximize production yield.
Technology providers: Develop lower-emission process gases, advanced monitoring systems, and digital gas management platforms that improve manufacturing efficiency.
Investors: Focus on companies with diversified electronics portfolios, established customer qualification records, and sustained capital investment in specialty gas production.
As display fabrication becomes more technologically demanding, competitive advantage will increasingly depend on consistent product quality, reliable regional supply networks, environmental compliance, and the ability to support customers throughout the entire manufacturing process rather than supplying gases as standalone industrial commodities.
Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 776.1 million |
| Total Market Size in 2031 | USD 920.0 million |
| Forecast Unit | Million |
| Growth Rate | 3.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Display Technology, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Electronic Specialty Gases
Silane
Nitrogen Trifluoride
Nitrous Oxide
Ammonia (NH3)
Hydrogen Chloride (HCl)
Hydrogen Fluoride (HF)
Tetrafluoromethane (CF4)
Sulfur Hexafluoride (SF6)
Bulk Gases
Nitrogen
Helium
Hydrogen
Oxygen
Argon
Carbon Dioxide
Others
By Display Technology
LCD
MicroLED
OLED
Mini-LED
Others
By Geography
Americas
USA
Canada
Others
Europe, Middle East and Africa
Germany
France
UK
Others
Asia Pacific
China
Japan
South Korea
Taiwan
Others
Geographical Segmentation
- North America
- South America
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of End-Users
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. INDUSTRIAL GAS MARKET FOR FLAT PANEL DISPLAY MARKET ANALYSIS, BY TYPE
5.1. Introduction
5.2. Electronic Specialty Gases
5.2.1. Silane
5.2.2. Nitrogen Trifluoride
5.2.3. Nitrous Oxide
5.2.4. Ammonia (NH3)
5.2.5. Hydrogen Chloride (HCl)
5.2.6. Hydrogen Fluoride (HF)
5.2.7. Tetrafluoromethane (CF4)
5.2.8. Sulfur Hexafluoride (SF6)
5.3. Bulk Gases
5.3.1. Nitrogen
5.3.2. Helium
5.3.3. Hydrogen
5.3.4. Oxygen
5.3.5. Argon
5.3.6. Carbon Dioxide
5.3.7. Others
6. INDUSTRIAL GAS MARKET FOR FLAT PANEL DISPLAY MARKET ANALYSIS, BY DISPLAY TECHNOLOGY
6.1. Introduction
6.2. LCD
6.3. MicroLED
6.4. OLED
6.5. Mini-LED
6.6. Others
7. INDUSTRIAL GAS MARKET FOR FLAT PANEL DISPLAY MARKET ANALYSIS, BY GEOGRAPHY
7.1. Introduction
7.2. Americas
7.2.1. USA
7.2.2. Canada
7.2.3. Others
7.3. Europe Middle East and Africa
7.3.1. Germany
7.3.2. France
7.3.3. UK
7.3.4. Others
7.4. Asia Pacific
7.4.1. China
7.4.2. Japan
7.4.3. South Korea
7.4.4. Taiwan
7.4.5. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Emerging Players and Market Lucrativeness
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. Linde plc
9.2. Air Liquide S.A.
9.3. Air Products and Chemicals, Inc.
9.4. SK Specialty
9.5. Merck KGaA
9.6. Entegris
9.7. The Messer Group GmbH
9.8. Taiyo Nippon Sanso Corporation
9.9. Matheson Tri-Gas, Inc.
9.10. Kanto Denka Kogyo





Frequently asked questions
What is the projected market size for industrial gases in flat panel displays?
The Industrial Gas Market is projected to reach USD 920.0 million by 2031 at a 3.5% CAGR.
What are the primary growth drivers for this market?
Premium display technologies and tighter contamination control drive market growth.
Which region dominates flat panel display manufacturing gas demand?
Asia Pacific concentrates manufacturing capacity, encouraging localized investments.
What types of gases are essential for flat panel display fabrication?
High-purity electronic specialty gases and bulk gases are indispensable.
What are the key commercial opportunities through 2031?
Next-gen display investments, localization, and environmental compliance are key opportunities.
How are display manufacturers' gas supply needs evolving?
Purity assurance, integrated gas management, and uninterrupted supply are prioritized.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Industrial Gas Market for Flat Panel Display Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/industrial-gas-market-for-flat-panel-display