
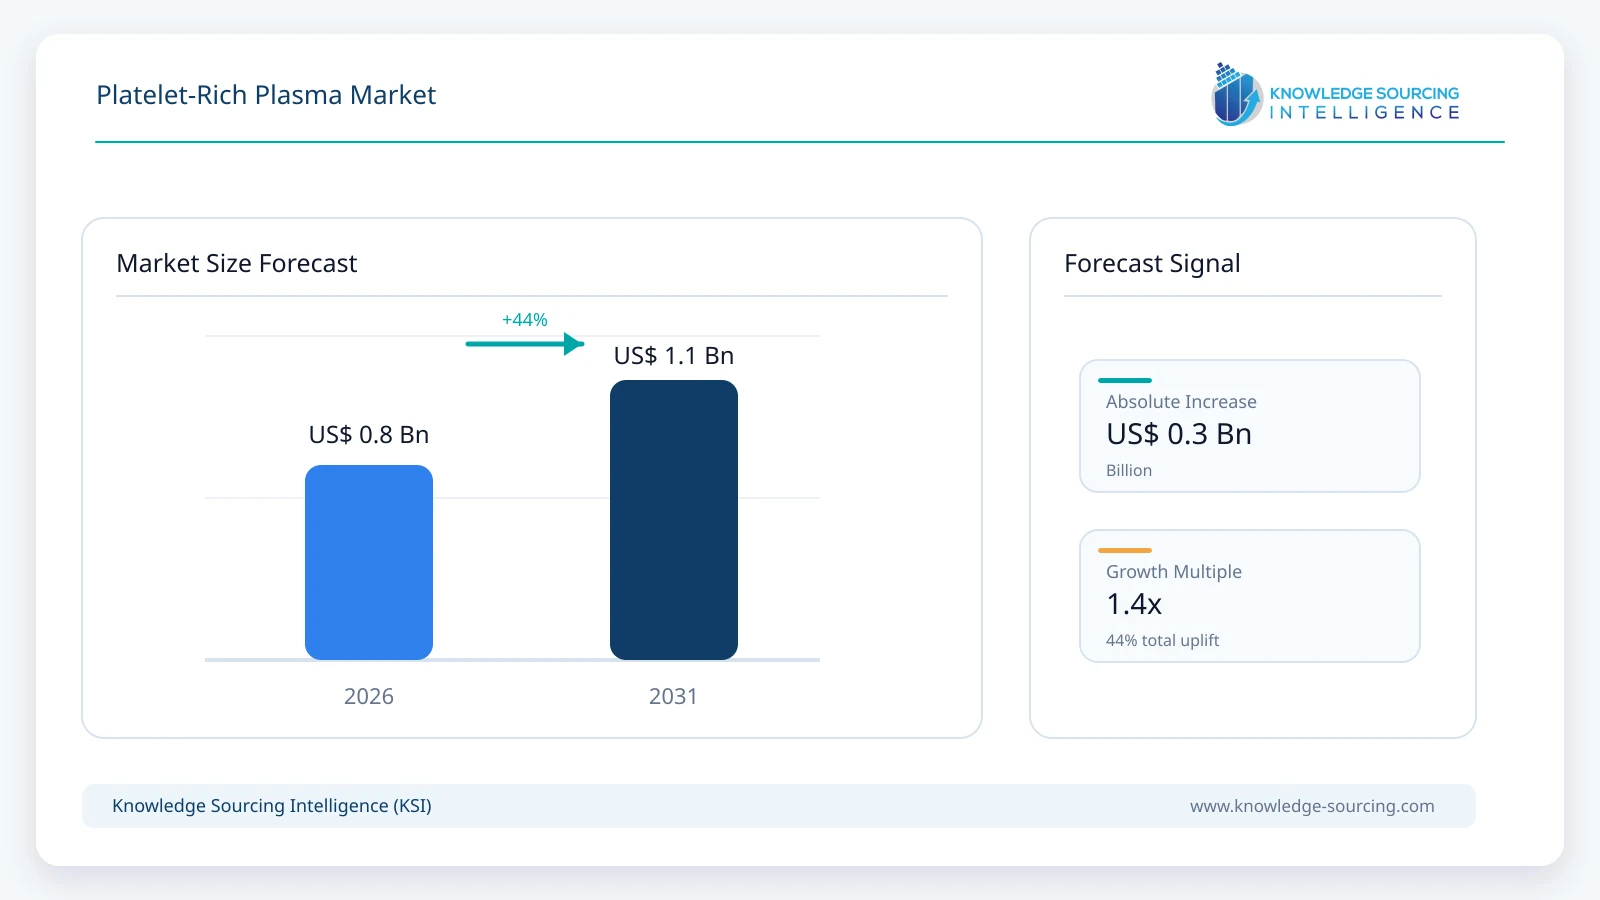
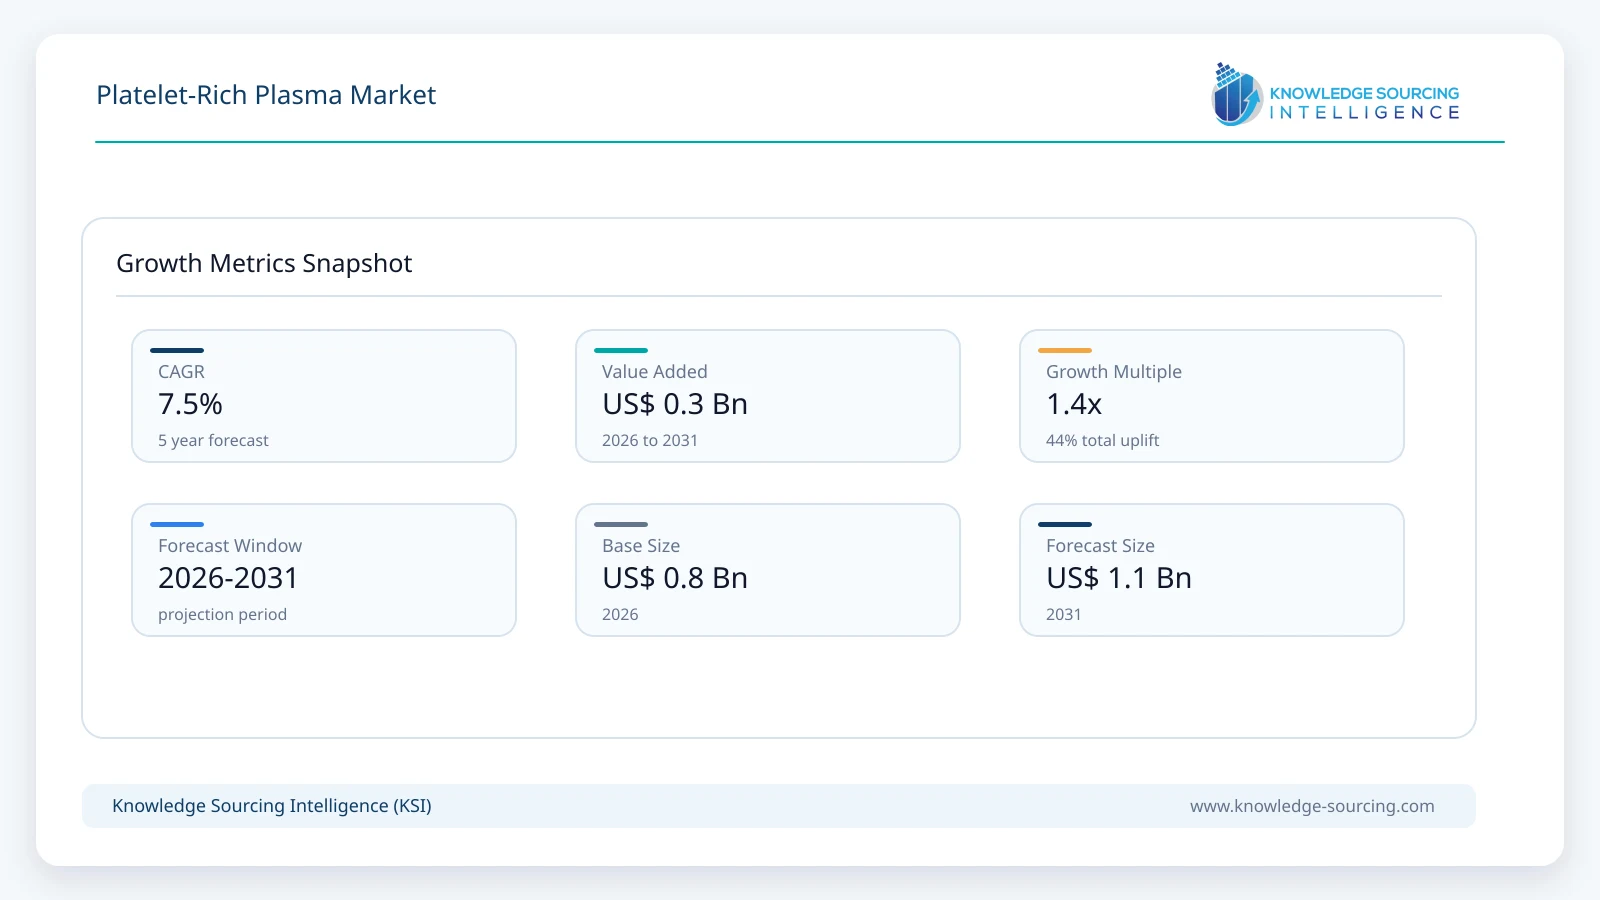
The global platelet-rich plasma (PRP) preparation market is forecast to grow from USD 0.78 billion in 2026 to USD 1.12 billion in 2031, representing a CAGR of 7.5% during the forecast period.
Highlights:
- 1Disposable PRP kits and tubes are estimated to account for approximately 72.0% of global PRP preparation market revenue in 2026.
- 2Leukocyte-poor / pure PRP systems are estimated to represent approximately 55.0% of 2026 market revenue.
- 3Orthopedics and sports medicine are estimated to account for approximately 46.0% of PRP preparation revenue in 2026.
- 4Specialty clinics and physician offices are estimated to represent approximately 49.0% of global end-user spending in 2026.
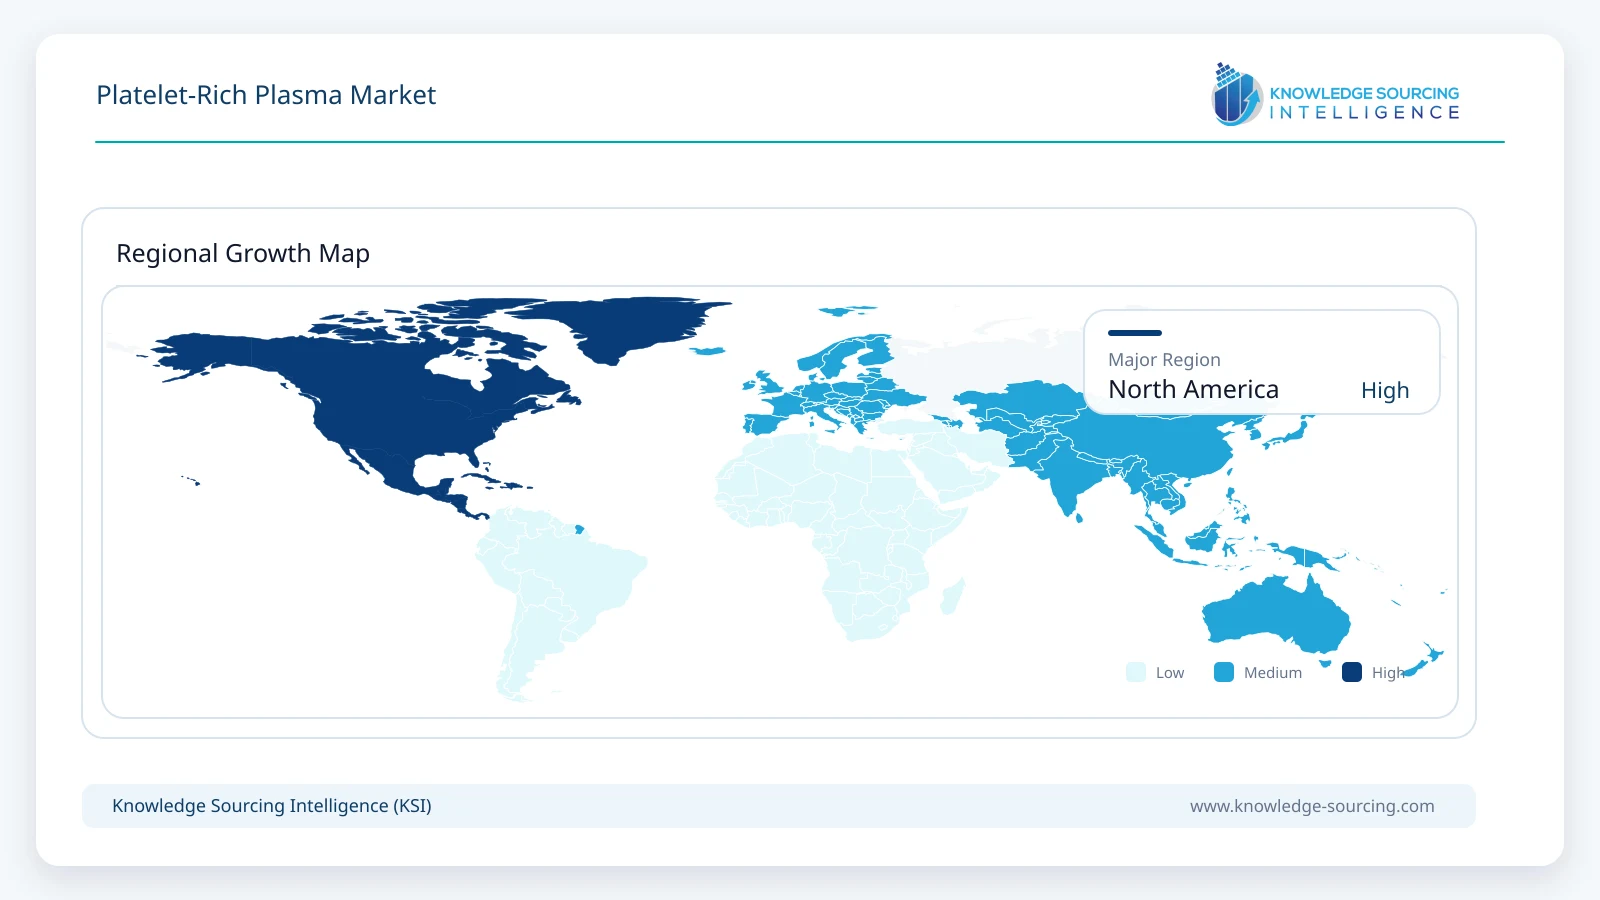
- 5North America is estimated to account for approximately 45.0% of global PRP preparation market revenue in 2026.
- 6FDA activity remained active during 2026, with clearances for the Precise Cell Concentration System, PlateletQuick PRP, SMART M-CELL PRP and RegenBMC supporting continued product development in point-of-care preparation.
Market Overview
Platelet-rich plasma preparation systems are used to process a patient’s own blood at the point of care and produce a platelet-concentrated preparation for subsequent clinical use. The market covered in this study includes dedicated disposable PRP kits and tubes, closed separation systems, PRP-specific centrifuges and related preparation equipment. It excludes physician procedure fees, general laboratory centrifuges, platelet transfusion products, plasma-collection systems and the broader value of regenerative-medicine services. This boundary captures the commercial market for dedicated PRP preparation hardware and recurring consumables rather than the much larger value of the medical procedures in which PRP may be used.
The market is characterized by a recurring consumable model. A preparation platform may remain installed for several years, while each patient procedure typically requires a new sterile tube, syringe, separation chamber or disposable kit. This creates a revenue structure in which procedure volume drives repeat purchasing and gives suppliers an incentive to build installed systems around proprietary or validated consumable workflows. Products marketed by Arthrex, Zimmer Biomet, RegenLab, BTI Biotechnology Institute, Miracell, EmCyte and other specialists illustrate the diversity of closed and semi-closed preparation approaches currently available.
Commercial demand is concentrated in outpatient specialties where point-of-care preparation can be integrated into the clinical workflow. Orthopedic and sports-medicine practices remain central users, while dermatology, aesthetic medicine, hair restoration, dental surgery and selected regenerative-medicine practices add additional demand. Product differentiation increasingly focuses on platelet concentration, red-blood-cell reduction, leukocyte content, processing time, blood volume, sterility and repeatability rather than on centrifugation alone.
Regulatory activity confirms that PRP preparation remains an active device category. During 2026, the U.S. FDA listed clearances for the Precise Cell Concentration System, PlateletQuick PRP, SMART M-CELL PRP and RegenBMC. These clearances relate to specific preparation-system indications and should not be interpreted as approval of PRP as a treatment for every clinical condition in which it is used. Nevertheless, continued device submissions and clearances demonstrate ongoing investment in workflow design, cell-concentration control and point-of-care processing.
Platelet-Rich Plasma Market Trends
Recurring Consumables Remain the Core Commercial Model
PRP preparation differs from many capital-equipment markets because a relatively durable centrifuge or processing platform supports repeated purchases of sterile single-use components. Suppliers therefore compete not only on equipment placement but also on the reliability, convenience and clinical workflow of each disposable preparation cycle. Systems that reduce manual handling, standardize preparation steps and limit contamination risk can support stronger recurring consumable demand. This model also makes procedure growth commercially important: rising use in established outpatient specialties can increase revenue even when the installed equipment base expands only gradually.
Cell-Composition Control Becomes a Product Differentiator
Clinicians increasingly evaluate PRP systems according to the composition of the final preparation rather than simply whether platelet concentration is achieved. Manufacturers differentiate products through platelet yield, red-blood-cell reduction, neutrophil and leukocyte content, processing volume, recovery efficiency and the consistency of the resulting preparation. This has encouraged the development of systems positioned around specific output profiles and more reproducible processing. Clearer documentation of cell composition can also help specialty practices standardize protocols across clinicians and locations, strengthening demand for branded systems with defined preparation characteristics.
Outpatient Workflows Favor Faster and More Closed Systems
Most PRP preparation occurs close to the patient and often within clinics where staff time, room turnover and workflow simplicity directly affect economics. Systems that minimize transfer steps, use preconfigured disposables and shorten processing time are therefore well suited to high-throughput orthopedic, sports-medicine, aesthetic and dental practices. Closed or highly controlled processing also supports sterility and repeatability. As the market matures, suppliers are increasingly competing on the total preparation workflow, including setup, processing, output handling and staff training, rather than on centrifuge specifications in isolation.
Market Segmentation by Product
Disposable PRP Kits and Tubes
Disposable PRP kits and tubes are estimated at approximately USD 562.0 million in 2026. Their position as the largest product category reflects the recurring nature of point-of-care PRP preparation, where a new sterile processing set is generally required for each patient procedure. Revenue therefore scales with treatment volume rather than only with purchases of centrifuges or other durable equipment. Branded systems compete on ease of preparation, closed-system handling, platelet recovery, red-blood-cell reduction, anticoagulant configuration and compatibility with established clinical workflows. The recurring consumable model also creates a direct relationship between supplier revenue and utilization at orthopedic, sports-medicine, aesthetic, dental and regenerative-medicine practices. As providers seek more reproducible preparations and simpler staff workflows, validated single-use kits are expected to remain the principal commercial value pool within PRP preparation through the forecast period.
Market Segmentation by PRP Composition
Leukocyte-Poor / Pure PRP
Leukocyte-poor / pure PRP systems are estimated at approximately USD 429.0 million in 2026. The segment is supported by demand for preparations designed to concentrate platelets while reducing red-blood-cell and neutrophil content, an output profile commonly used across musculoskeletal, soft-tissue and aesthetic workflows. Commercial differentiation is increasingly based on the consistency of the final preparation, including platelet yield, residual red-cell content, processing volume and reproducibility across operators. Systems positioned around controlled cell composition can also help clinics standardize protocols, train staff and document preparation characteristics more consistently. Continued attention to preparation quality and protocol reproducibility is expected to support demand for systems that provide a defined leukocyte-poor or pure PRP output rather than relying on less standardized preparation methods.
Market Segmentation by Application
Orthopedics and Sports Medicine
Orthopedics and sports medicine are estimated at approximately USD 359.0 million in 2026. This application remains the largest commercial use of dedicated PRP preparation systems because orthopedic surgeons, sports-medicine physicians and musculoskeletal clinics have established point-of-care workflows for preparing autologous platelet concentrates. The application benefits from recurring outpatient procedure volumes, a large base of specialist practices and close alignment with existing orthobiologic product portfolios from major orthopedic-device suppliers. Dedicated PRP systems can be incorporated into treatment rooms or procedure centers without the infrastructure required for centralized laboratory processing, making them well suited to same-visit preparation. The continued expansion of sports medicine, musculoskeletal care and orthobiologic services is expected to keep orthopedic applications at the center of commercial PRP-system demand through 2031.
Market Segmentation by End User
Specialty Clinics and Physician Offices
Specialty clinics and physician offices are estimated at approximately USD 382.0 million in 2026. These facilities represent the largest end-user group because PRP preparation is commonly performed immediately before treatment within outpatient practices rather than in centralized hospital laboratories. Orthopedic, sports-medicine, dermatology, aesthetic, hair-restoration, pain-management and regenerative-medicine practices can operate dedicated centrifuges and purchase single-use consumables directly, creating a recurring procurement relationship with system suppliers. The economics favor compact equipment, short processing cycles, straightforward staff training and reliable access to consumables. Clinics also tend to value systems that can be incorporated into existing treatment rooms with limited infrastructure changes. As outpatient specialty care expands and more practices add procedure-based services, specialty clinics and physician offices are expected to remain the most commercially important customer group for PRP preparation systems.
Market Segmentation by Geography
North America
North America is estimated at approximately USD 351.0 million in 2026. The region has a large base of orthopedic, sports-medicine, aesthetic and regenerative-medicine practices, extensive outpatient procedure infrastructure and broad availability of branded PRP preparation systems. The United States also has an active regulatory pathway for dedicated blood-processing devices, with multiple PRP-related clearances recorded during 2026. Private-pay activity in several PRP applications supports commercial adoption even where reimbursement is limited or inconsistent, while established orthopedic-device distribution networks improve access to systems and recurring consumables. The presence of suppliers and commercial partners with strong U.S. coverage further supports market depth. North America is therefore expected to remain the largest regional revenue pool through the forecast period, although growth will continue to depend on clinical adoption, regulatory positioning and procedure economics.
Market Drivers
Expansion of Orthobiologic and Musculoskeletal Care
PRP preparation is closely linked with outpatient musculoskeletal and orthobiologic workflows. Growth in sports medicine, orthopedic procedures and non-surgical musculoskeletal care increases the number of settings in which point-of-care blood processing can be used. Major orthopedic-device suppliers also integrate PRP systems into broader biologics portfolios, improving commercial reach and clinician familiarity. As specialty practices expand procedure-based services, demand for systems that can prepare autologous platelet concentrates quickly and consistently is expected to rise.
Recurring Demand for Single-Use Preparation Components
Each PRP procedure typically requires a new sterile preparation set, making consumable demand directly responsive to clinical utilization. This recurring model supports market growth even when durable equipment replacement is modest. Suppliers with established installed systems can generate repeat revenue through procedure-linked kits, while clinics benefit from standardized components and simplified inventory management. The economic importance of disposables also encourages product development around ease of use, sterility, processing consistency and compatibility with existing centrifuge platforms.
Growth of Aesthetic and Office-Based Procedures
Aesthetic medicine, dermatology and hair-restoration practices have increased the number of outpatient settings using PRP preparation. These practices favor compact systems that can be incorporated into existing treatment rooms and operated by trained clinical staff. While reimbursement may be limited, private-pay economics can support adoption where patients are willing to pay directly for procedures. This creates a commercially attractive channel for suppliers that can provide simple workflows, reliable disposables and training support.
Product Standardization and Regulatory Activity
Continued regulatory submissions and clearances encourage suppliers to document system performance, processing steps and intended use more clearly. Standardized workflows can improve consistency across operators and locations, which is particularly important for multi-site specialty practices. Regulatory activity during 2026 also indicates that manufacturers continue to invest in new or updated preparation systems rather than treating PRP as a static legacy category.
Market Restraints
Variable Clinical Evidence Across Indications
Clinical evidence for PRP is not uniform across every specialty or indication, and device clearance should not be interpreted as proof of therapeutic efficacy for all uses. Differences in preparation protocols, platelet concentration and leukocyte content can also complicate comparison between studies. This variability may slow adoption among providers that require stronger standardized evidence before adding PRP procedures to routine care.
Inconsistent Reimbursement
Many PRP procedures are not routinely reimbursed and may depend on direct patient payment. This can limit procedure volumes when consumers are price sensitive and makes demand more dependent on local practice economics. Clinics therefore evaluate preparation systems not only on technical performance but also on consumable cost, expected procedure throughput and the ability to recover equipment investment through service revenue.
Price Competition from Basic Preparation Methods
Low-cost tubes, general-purpose centrifugation protocols and less integrated preparation approaches can compete with branded closed systems in price-sensitive settings. Premium suppliers must therefore justify higher prices through reproducibility, workflow simplicity, regulatory documentation, sterile handling and more clearly characterized output. Intense price competition can constrain average selling prices where clinicians perceive limited differentiation.
Protocol Variability and Training Requirements
PRP output can be influenced by blood volume, centrifugation settings, handling steps and patient-specific factors. Clinics need clear protocols and staff training to achieve consistent preparation. Systems that require complex manual steps may face slower adoption, while inconsistent operation can weaken confidence in the reproducibility of treatment workflows. Supplier training and technical support therefore remain important elements of commercial adoption.
Competitive Landscape
The PRP preparation market is fragmented across orthopedic-device companies, dedicated blood-processing specialists, regenerative-medicine suppliers and regional manufacturers. Arthrex and Zimmer Biomet participate through established orthopedic and sports-medicine channels, while RegenLab and BTI Biotechnology Institute are dedicated specialists with broad PRP-focused portfolios. EmCyte, Fidia, Royal Biologics, APEX Biologix, Estar Medical, Ycellbio and Celling Biosciences add further competition across clinic-based preparation systems and consumables.
Competitive differentiation centers on preparation consistency, platelet recovery, red-blood-cell and leukocyte control, blood-volume requirements, processing time, closed-system design, sterility, regulatory documentation and the economics of recurring consumables. Because clinics frequently standardize around a preferred preparation workflow, suppliers that combine easy operation with dependable consumable availability can build durable customer relationships. Distribution coverage and clinician training are also important because many buyers are smaller specialty practices rather than centralized hospital procurement organizations.
Recent FDA clearances from Isto Biologics, Forever Labs, Miracell and RegenLab demonstrate that smaller and specialist suppliers continue to introduce or update point-of-care PRP systems. This keeps the market commercially active and prevents the competitive landscape from being dominated solely by large orthopedic-device companies.
Recent Developments
February 3, 2026: The U.S. FDA cleared the Precise Cell Concentration System from Arteriocyte Medical Systems / Isto Biologics under 510(k) BK251168.
March 11, 2026: The U.S. FDA cleared PlateletQuick PRP from Forever Labs under 510(k) BK251299 for point-of-care preparation of autologous PRP for use with bone graft.
April 2, 2026: The U.S. FDA granted 510(k) clearance to Miracell's SMART M-CELL PRP Concentration System under K250516.
May 29, 2026: The U.S. FDA cleared RegenLab USA's RegenBMC (RegenKit-THT-BMC) under 510(k) BK251274 for point-of-care preparation of autologous PRP from peripheral blood or a mixture of peripheral blood and bone marrow for mixing with bone graft.
Market Outlook
The PRP preparation market is expected to expand steadily through 2031 as point-of-care biologic preparation becomes more established across orthopedics, sports medicine and other outpatient specialties. Recurring disposable kits will remain the economic center of the market because revenue scales with procedure activity while installed preparation equipment is replaced less frequently.
Future product development is expected to emphasize reproducible cell composition, faster processing, fewer manual transfer steps and stronger documentation of output characteristics. These features can help clinics standardize protocols and support wider use across multi-site specialty practices. Suppliers with reliable consumable availability, regulatory support and clinician training are likely to be better positioned than vendors competing primarily on centrifuge price.
Market growth will remain moderated by uneven clinical evidence, reimbursement constraints and competition from lower-cost preparation methods. Even so, continued regulatory activity and broad outpatient use support a durable commercial market for dedicated PRP preparation systems and single-use consumables.
Platelets Rich Plasma Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.78 billion |
| Total Market Size in 2031 | USD 1.12 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 7.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, PRP Composition, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Product
Disposable PRP Kits and Tubes
Dedicated Preparation Equipment
By PRP Composition
Leukocyte-Poor / Pure PRP
Leukocyte-Rich PRP
Adjustable / Multi-Protocol Systems
By Application
Orthopedics and Sports Medicine
Aesthetics, Dermatology and Hair Restoration
Dental and Oral Surgery
Others
By End User
Specialty Clinics and Physician Offices
Hospitals and Ambulatory Surgical Centers
Dental Practices
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment and Regional Summary
3.4. Market Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Orthobiologic and Musculoskeletal Care
4.1.2. Recurring Demand for Single-Use Preparation Components
4.1.3. Growth of Aesthetic and Office-Based Procedures
4.1.4. Product Standardization and Regulatory Activity
4.2. Market Restraints
4.2.1. Variable Clinical Evidence Across Indications
4.2.2. Inconsistent Reimbursement
4.2.3. Price Competition from Basic Preparation Methods
4.2.4. Protocol Variability and Training Requirements
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. GLOBAL PLATELET-RICH PLASMA MARKET BY PRODUCT
5.1. Introduction
5.2. Disposable PRP Kits and Tubes
5.3. Dedicated Preparation Equipment
6. GLOBAL PLATELET-RICH PLASMA MARKET BY PRP COMPOSITION
6.1. Introduction
6.2. Leukocyte-Poor / Pure PRP
6.3. Leukocyte-Rich PRP
6.4. Adjustable / Multi-Protocol Systems
7. GLOBAL PLATELET-RICH PLASMA MARKET BY APPLICATION
7.1. Introduction
7.2. Orthopedics and Sports Medicine
7.3. Aesthetics, Dermatology and Hair Restoration
7.4. Dental and Oral Surgery
7.5. Others
8. GLOBAL PLATELET-RICH PLASMA MARKET BY END USER
8.1. Introduction
8.2. Specialty Clinics and Physician Offices
8.3. Hospitals and Ambulatory Surgical Centers
8.4. Dental Practices
8.5. Others
9. GLOBAL PLATELET-RICH PLASMA MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Australia
9.6.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Product and Workflow Positioning
10.3. Regulatory and Commercial Developments
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Arthrex, Inc.
11.2. Zimmer Biomet Holdings, Inc.
11.3. RegenLab SA
11.4. BTI Biotechnology Institute
11.5. Miracell Co., Ltd.
11.6. Isto Biologics / Arteriocyte Medical Systems
11.7. Forever Labs, Inc. / PlateletQuick
11.8. EmCyte Corporation
11.9. Crown Aesthetics / ProGen PRP Eclipse
11.10. Fidia Farmaceutici S.p.A.
11.11. Royal Biologics
11.12. APEX Biologix
11.13. Estar Medical
11.14. Ycellbio Medical Co., Ltd.
11.15. Celling Biosciences, Inc.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Abbreviations
Navigate
Trusted by the world's leading organizations











