
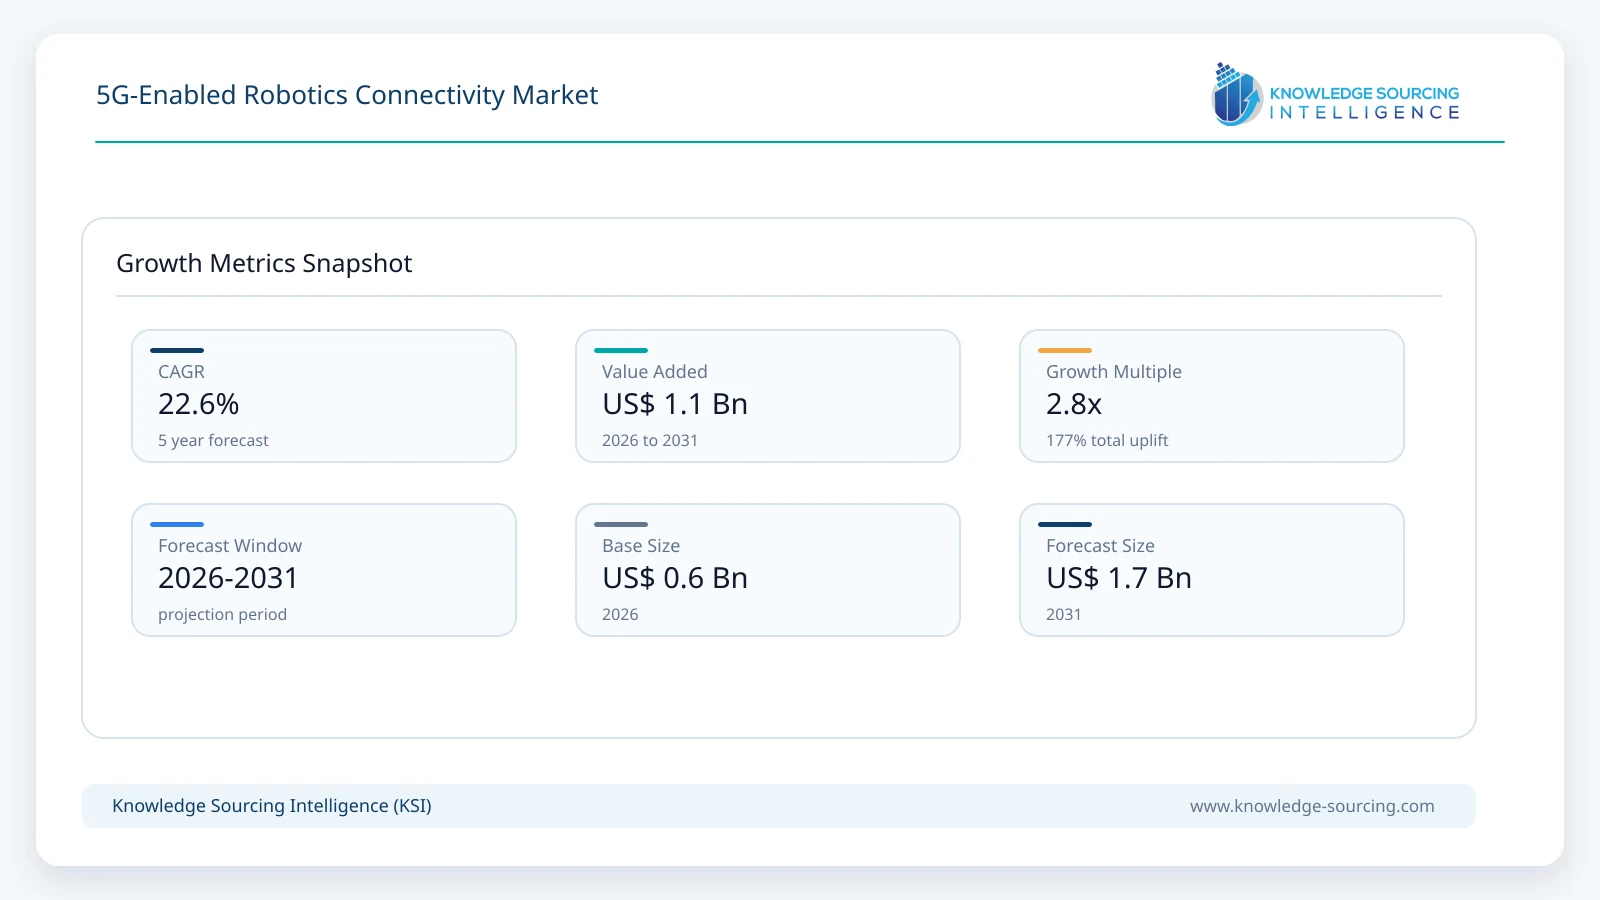
The global 5G-Enabled Robotics Connectivity Market is projected to grow from USD 0.62 billion in 2026 to USD 1.72 billion in 2031, at a CAGR of 22.64% across the forecast period.
Highlights:
- 1Industrial robot installations exceeded 600,000 units worldwide in 2025, according to the International Federation of Robotics, widening the base of facilities that could adopt private wireless robotics.
- 2Industrial 5G radio equipment, ruggedized routers and on-site communication hardware remain the leading component spending group, particularly for new installations.
- 3Autonomous mobile robots account for approximately 56% of estimated 2026 connectivity spending because reliable roaming is particularly relevant to moving fleets.
- 4Network infrastructure leads the technology mix, while edge processing and robotics-specific AI orchestration are gaining commercial attention.
- 5Smart manufacturing remains the largest application, with fleet dispatch, factory material movement and connected inspection creating distinct purchasing needs.
- 6Asia Pacific represents the largest regional opportunity, while Middle East and Africa has the fastest projected expansion from a much smaller industrial private-network base.
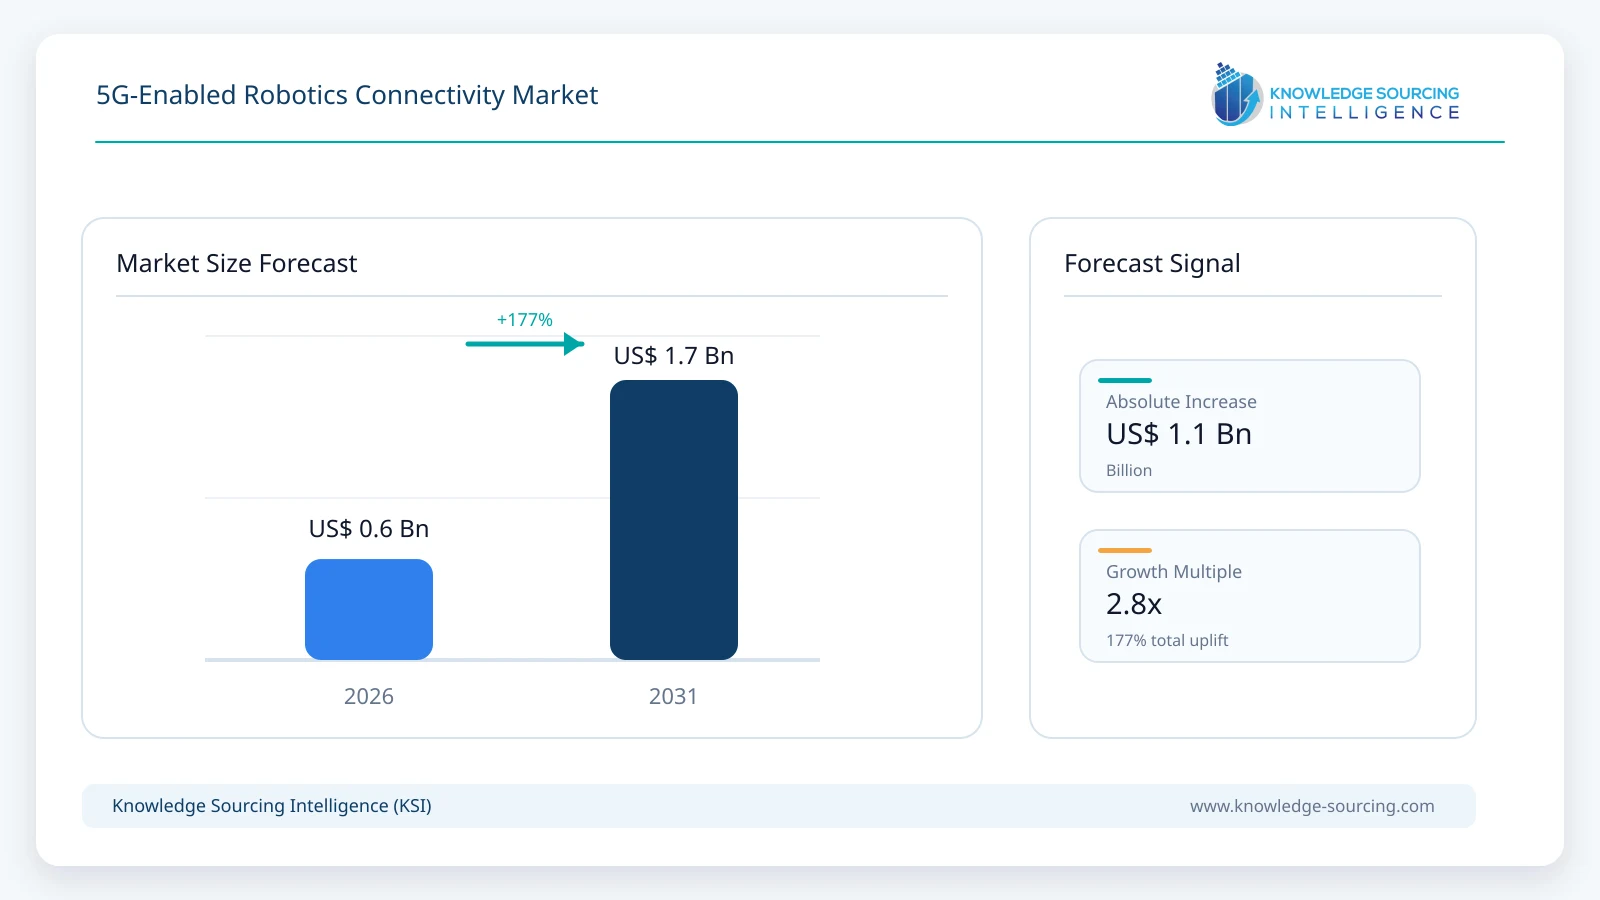
Industrial mobile robots rely on local positioning sensors and onboard safety systems, but communication affects how efficiently a fleet shares tasks, status, maps and exception alerts. Private 5G can support predictable radio coverage and mobility in large or equipment-dense facilities while allowing network administrators to apply enterprise identity, device policy and traffic controls. The value of connectivity therefore arises mainly through higher robot utilization, fewer interrupted tasks and better access to fleet-level data, not through the radio link replacing autonomous safety decisions.
Ericsson's Lewisville smart factory provides an operating example. Its AMRs share lidar-derived information over a private network, and the company reports a 10–15% improvement in material-handling mission completion relative to the earlier Wi-Fi arrangement. Siemens similarly describes its Karlsruhe production facility using an on-premises 5G network with industrial routers installed on AMRs. The two sites demonstrate credible industrial use, but they should not be interpreted as a universal robot-fleet performance uplift.
The supplier value chain includes 5G baseband and radio providers, industrial-network integrators, embedded-module manufacturers, robotics platforms and industrial automation specialists. Nokia, Ericsson and Siemens sell relevant network capabilities; Qualcomm provides robotics computing and 5G connectivity architectures; ABB and Telefónica have collaborated on mobile robot connectivity, while Samsung and NAVER Cloud have deployed private-5G-supported service robots. Suppliers increasingly compete on integration with existing operational technology, spectrum support, installation effort and post-deployment service rather than peak radio throughput alone.
Market Trends
Private 5G Moves from Pilots to Working Robot Fleets
Industrial private networks are increasingly evaluated around specific productive workloads instead of coverage demonstrations. Siemens equips mobile robots in its Karlsruhe factory with SCALANCE 5G routers and operates the radio and core infrastructure locally. Ericsson's United States smart factory also connects its AMRs through private 5G, permitting robots to exchange operating information without repeatedly changing between disconnected wireless zones.
The economic case improves where robots travel across large production footprints and share corridors with machines, forklifts and staff. Dedicated radio infrastructure can stabilize mobility while leaving company IT teams control of credentials and traffic policy. Procurement nevertheless depends on whether the new system delivers measurable improvements over an adequately engineered Wi-Fi network.
Robot Coordination Is Moving Toward Local Edge Processing
Robotic fleet systems are beginning to separate time-critical onboard control from workloads that can be processed on local servers. Nokia Bell Labs has demonstrated autonomous mobile robot navigation offloaded to edge computing across a standalone 5G network. Ericsson and SoftBank reported a February 2026 proof of concept involving dynamic robotic AI-task offloading through an AI-RAN mobile edge platform.
Centralizing mapping, routing and heavy AI inference can reduce the need for identical compute resources in every robot, but links must remain dependable and safety behavior must tolerate outages. The emerging spending opportunity includes edge networking, software orchestration and secure workload placement. A research demonstration does not imply that remotely executed safety control is commercially widespread.
5G-Capable Robotics Hardware Becomes More Integrated
Robot builders are incorporating cellular connectivity into computing and communications design choices rather than treating it only as an external gateway. Qualcomm's Robotics RB6 architecture combines robotics-oriented edge AI and video-processing capabilities with support for 5G radio connectivity. Siemens has also expanded its private network offering into more countries while enhancing industrial 5G routers with device-level edge functions.
Integrated designs can simplify cabling and mechanical packaging while reducing the time needed to qualify network equipment for a mobile machine. However, semiconductor and modem capability is not sufficient evidence of deployed cellular fleets. OEMs still have to qualify antennas, power consumption, radio bands, software maintenance and operator roaming arrangements for their intended applications.
Industrial Network Coverage Is Expanding Across Regions
Siemens announced in April 2026 that its private 5G infrastructure was available across 15 countries in Europe and the Americas, with new radio units designed for additional bands, including United States CBRS. Regional expansion matters for equipment makers seeking repeatable deployments at multiple production sites rather than one-off pilots managed by different integrators.
The addressable robot population is expanding more quickly than many isolated trials suggest. In September 2026, the International Federation of Robotics reported that factories installed more than 600,000 industrial robots during 2025 and that global operational stock reached five million units. Those figures describe industrial robotics activity, not the number of 5G-connected robots. Network suppliers still need integrator partnerships, spectrum access and repeatable site economics to convert a large installed base into attributable cellular contracts.
5G-Enabled Robotics Connectivity Market Segment Analysis
By Component
Hardware
Hardware accounts for the largest estimated component share in 2026 because installing a robotics-capable private network requires radios, local core appliances or servers, industrial antennas and 5G communication devices. Robot operators may buy a dedicated local infrastructure stack or commission part of a broader enterprise private network. Siemens' documented 5G-equipped AMRs show why ruggedized routers and radio coverage remain directly relevant to mobile robot operations.
The segment is estimated to represent approximately 59% of 2026 revenue. As installations mature, recurring management software and support grow, but industrial-grade hardware retains pricing power where electromagnetic interference, factory uptime and certified equipment matter. Procurement teams increasingly evaluate the entire site bill of materials rather than the modem price alone.
By Robotics Type
Autonomous Mobile Robots
Autonomous mobile robots generate the largest connectivity opportunity because they traverse factories and distribution centers while interacting with dispatch, inventory and safety-management systems. Stable handovers and broad indoor coverage can matter when fleets work near shelving, production equipment or loading zones. Ericsson and Siemens each document private-5G-supported AMRs performing practical material-handling missions in operating factories.
The segment accounts for an estimated 56% of global spending in 2026. Revenue expands through cellular-enabled new fleets, retrofit routers, enterprise-network allocation and managed fleet connections. Connectivity investment is less automatic for fixed industrial arms, which may perform high-rate real-time control over wired networks even while external diagnostic data is exchanged wirelessly.
By Technology
Network Infrastructure
Network infrastructure remains the leading technology segment because enterprises must secure dedicated radio coverage, a suitable core and appropriate traffic management before large fleets can run on cellular links. Siemens' private industrial 5G portfolio and Ericsson's private-network deployments illustrate the range of site equipment and network-operation capabilities. Larger campuses may need several radio zones and specialized handover planning.
The segment represents approximately 57% of market value in 2026. Its relative weight gradually declines as more sites install robotic edge software and local AI processing. Existing enterprise networks can serve several applications at once, so buyers increasingly negotiate robotics-attributable capacity and service levels rather than relying solely on enterprise-wide network budgets.
By Application
Smart Manufacturing
Smart manufacturing represents the largest application because mobile material handling, assembly-line replenishment and inspection are established industrial processes with measurable uptime requirements. The International Federation of Robotics reported more than 600,000 industrial robot installations in 2025, alongside five million units operating in factories worldwide. Although most do not necessarily use cellular access, the expanding robotic installed base supports a broader choice of production environments in which private 5G can be evaluated.
Factories with many moving assets may see benefits from unified device management, stronger coverage policies and links to local fleet software. The segment accounts for approximately 44% of 2026 estimated spending. Healthcare and remote inspection can grow quickly from smaller bases, although surgical robotics deployments generally retain carefully engineered local control and cannot be assumed to rely on public mobile networks.
Market Drivers
More Mobile Robots in Material Handling
Distribution centers and factories are increasing use of autonomous machines to transport materials between work cells, receiving points and storage areas. Mobility creates communication conditions that differ from those of stationary industrial arms. Robot traffic can pass through metal structures, loading spaces and changing inventory layouts, making wireless coverage and handover performance important operating concerns.
Ericsson reports that its private-5G-connected AMRs complete factory material-handling missions 10–15% faster than under the previous Wi-Fi arrangement. That site-specific result illustrates a potential productivity mechanism, not a guaranteed outcome. Buyers are most likely to fund cellular upgrades where the measured reduction in interrupted trips offsets radios, routers and network support costs.
Enterprise Private 5G Procurement Expands
Large manufacturers increasingly purchase or operate private wireless systems that can connect vehicles, machines and inspection devices under a common identity and management framework. Siemens expanded its industrial private 5G availability to 15 countries in April 2026, improving the commercial addressability of repeatable multi-site projects. Ericsson and enterprise integrators are also expanding private-wireless delivery capabilities.
Robotics connectivity benefits when shared site infrastructure lowers the effective cost per connected machine. Shared enterprise infrastructure can also distribute communications expense across robots and other machines. Network planners have to align spectrum, local IT responsibilities and industrial equipment approvals before the first fleet is commissioned.
Shared Fleet Data Improves Robot Utilization
Mobile robots become more valuable when dispatch systems can exchange route information, alerts and workload status across an entire facility. Ericsson's connected AMRs exchange lidar-related information to help one robot warn others about blocked routes. Access to consistent operational data also helps teams identify idle equipment, recurring exceptions and maintenance problems.
The commercial mechanism is better fleet throughput rather than higher sensor bandwidth alone. As connected deployments expand, spending shifts toward managed connection software, telemetry security and integrated edge applications. Robot autonomy still requires onboard fail-safe behavior, so enterprise planners must distinguish information-sharing workloads from control functions that cannot tolerate network interruption.
5G Robotics Platforms Reduce Integration Barriers
Robot designers can now choose specialized embedded processors, 5G-capable communication modules and industrial routers intended for their operating environments. Qualcomm's RB6 platform integrates robotics-oriented AI processing with cellular connectivity options, while Siemens supports industrial 5G routers that can be mounted on mobile equipment. These products offer a more standardized starting point than custom communications hardware.
Standard hardware reduces engineering effort for device authentication, driver integration and radio testing, although it does not eliminate site engineering. Equipment makers that can support multiple national spectrum bands and factory network architectures are better positioned to serve multinational industrial buyers over successive robot generations.
Remote Inspection and Site Safety Workloads Broaden Use
Energy assets, industrial plants and large facilities are testing mobile robots for inspection activities that are difficult, repetitive or hazardous for personnel. Ericsson's 2026 Canadian living-lab event demonstrated a connected inspection robot sharing video and surveillance information over a private 5G network. Industrial inspection adds recurring data traffic and supervisory software to the basic connectivity purchase.
The economics depend on how often the robot runs and whether operators can substitute scheduled site visits or improve fault detection. Facilities may adopt 5G for high-quality video and managed security, but low-volume trials do not necessarily become large recurring connectivity contracts. Wider commercialization will depend on proof of operating savings and reliable local network coverage.
Market Restraints
Coverage Engineering and Radio Interference
Factories contain metal equipment, high-bay shelving, moving vehicles and electromagnetic noise that can weaken or obstruct radio signals. Fifth-generation cellular systems still require careful surveying, antenna placement and capacity planning when robots travel through these environments. Handover performance and consistent uplink quality are often more important to fleet operations than headline download speed.
Organizations may need redundant coverage, spectrum planning or additional radio units before permitting critical workflows onto a new network. The resulting site-engineering expense can weaken the investment case for small fleets that already operate adequately on managed Wi-Fi.
High Upfront Cost at Smaller Sites
A dedicated private network entails base stations, core functions, industrial communication devices, integration, cybersecurity controls and ongoing support. Much of this spending must occur before the first robot starts a paid production task. A large factory can spread fixed network costs over many machines; smaller plants have fewer opportunities to allocate those expenses.
Shared carrier-operated networks or managed private-network subscriptions can reduce the initial burden, but availability and service commitments vary by location. Some buyers will continue using existing wireless infrastructure until robot volume, downtime costs or new safety requirements justify switching.
Safety-Critical Control Must Remain Resilient
Robot brakes, collision avoidance and other safety functions cannot depend on an uninterrupted commercial radio path. Communication interruptions, overloaded edge servers and software faults can occur even when a 5G design meets intended performance specifications. Engineers therefore have to preserve appropriate local control and safe-stop behavior for hazardous motions.
Nokia's edge-offloaded navigation demonstration and Ericsson–SoftBank's Physical AI proof of concept show technical possibilities, not universal certification for remote safety control. Validation, failover design and acceptance testing can extend sales cycles in medical, industrial and public-service environments.
Device and Factory System Interoperability
Robot fleets contain equipment from multiple manufacturers with different middleware, fleet-management tools and industrial protocols. A private cellular network must also interoperate with existing Ethernet systems, IT security tools and production applications. Integrating a router is relatively straightforward compared with delivering consistent quality of service across the entire control-to-application chain.
Siemens explicitly emphasizes industrial protocol compatibility in its private 5G offering, reflecting this practical challenge. Without interoperable configuration and observability, an enterprise may postpone broader rollouts or select one integrator for its entire connectivity stack, reducing supplier flexibility.
Alternative Wireless Technologies Remain Competitive
Well-designed industrial Wi-Fi, wired Ethernet and specialized radio systems remain suitable for many robotics workloads. Fixed robots seldom need the mobility advantages of cellular, while moderate-size mobile fleets may already have acceptable coverage and throughput using established networks. Fifth-generation connectivity therefore competes on measurable service performance, reliability and ease of fleet management rather than on universal technical superiority.
Upgrades will remain selective when existing equipment already meets site targets and cybersecurity expectations. Cellular vendors must quantify avoided downtime, operational simplicity or lower lifecycle integration cost to justify a new radio architecture; otherwise buyers may continue refining their existing infrastructure.
Regional Outlook
Asia Pacific
Asia Pacific holds the leading regional position, supported by its concentration of industrial robot installations and manufacturing supply chains. The International Federation of Robotics reported that China installed approximately 354,000 industrial robots in 2025, accounting for around 59% of worldwide installations. Japan and South Korea maintain sophisticated automation ecosystems, while India and Southeast Asian manufacturers are expanding from smaller robotic installation bases. Private 5G serves selected mobile fleets where plant size, network control and data access justify cellular investment.
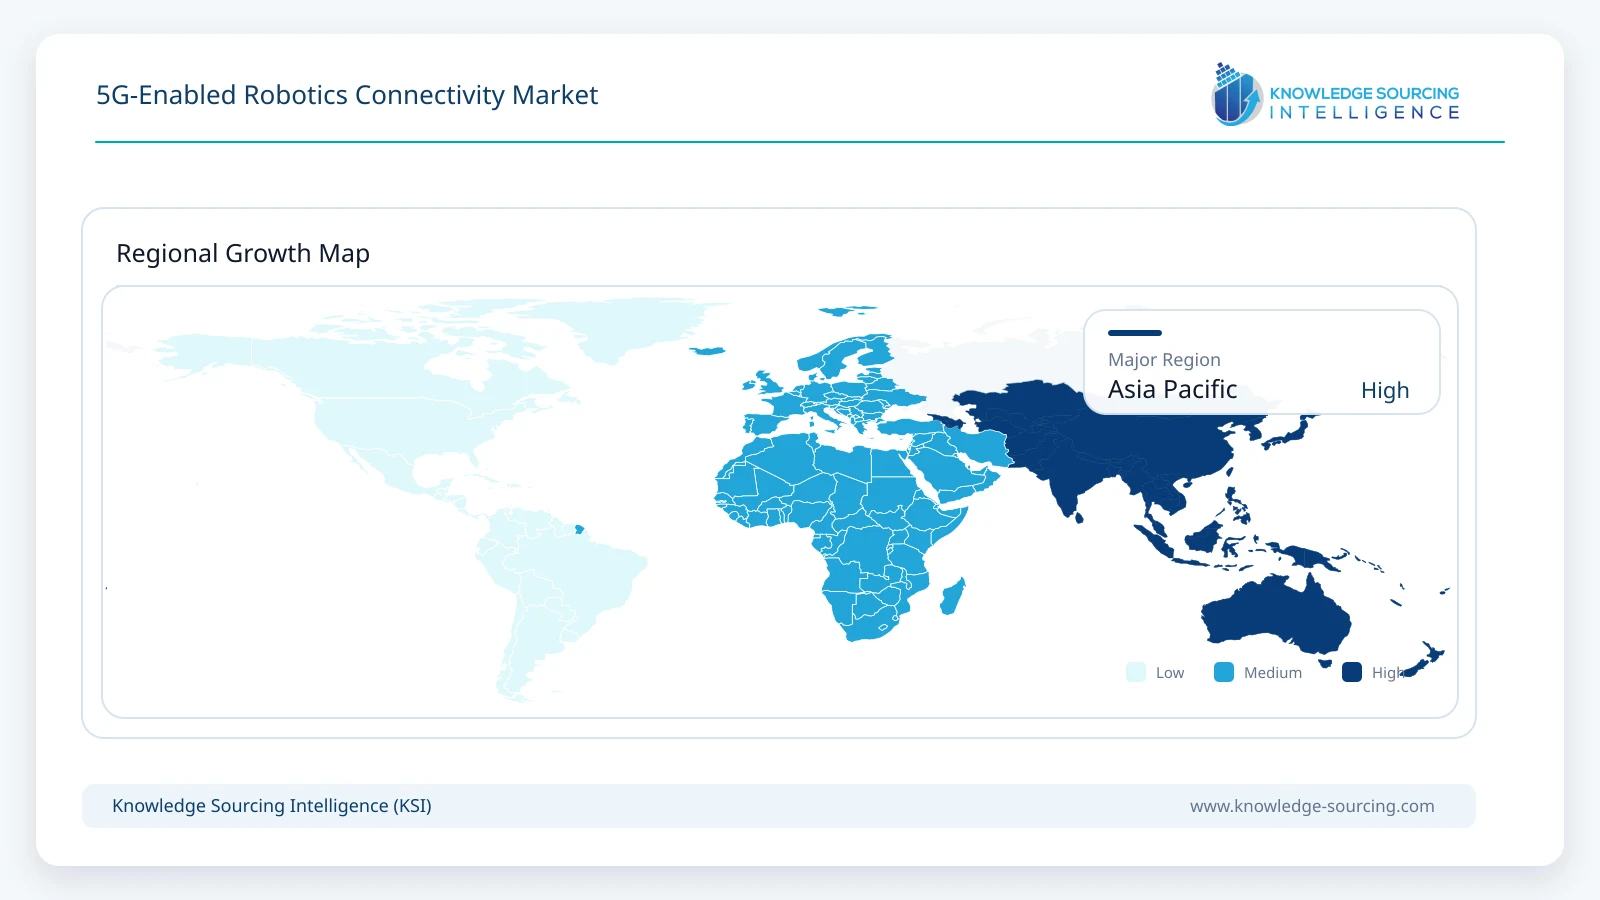
Regional deployment is shaped by more than robot shipments. China offers substantial manufacturing scale and domestic network suppliers; Japan brings demanding industrial automation applications; and South Korea has documented service-robot installations connected through private cellular systems. As manufacturers link mobile robots to factory analytics, more projects will combine radio access with local compute and secure fleet supervision. Buyers still require evidence that cellular mobility outperforms existing wireless arrangements in their specific production environments.
Middle East and Africa
Middle East and Africa is the fastest-growing region in the forecast from a comparatively small initial market. Saudi Arabia and the United Arab Emirates are advancing enterprise 5G capabilities and testing connected inspection and autonomous systems for industrial sites, logistics and critical infrastructure. At LEAP 2025 in Riyadh, Ericsson demonstrated its private-5G-connected Rocky robotic dog for monitoring and inspection; the demonstration illustrated technical feasibility rather than an installed fleet. The UAE operator e& has also disclosed collaborative development with Capra Robotics involving autonomous systems and 5G and AI capabilities.
The regional opportunity rests on new industrial campuses, managed private wireless offerings and robotic inspection in facilities where safe human access can be expensive. Saudi Arabia’s manufacturing and infrastructure programs create demand for networking systems that can be commissioned as part of new sites, while UAE enterprise mobile-edge services offer another route to local robot data processing. Adoption will remain selective because private spectrum, local systems integration, industrial procurement and after-sales support must mature together. The strong growth rate reflects expanding deployments from a low starting point, not evidence that this region already rivals Asia Pacific in absolute value.
Competitive Landscape
The competitive environment spans network infrastructure manufacturers, robotics equipment makers, chipset providers and industrial integrators. Ericsson and Nokia address private radio and core connectivity, while Siemens combines industrial networking with automation system knowledge. Qualcomm supplies enabling robotic compute and communication platforms, and Samsung has demonstrated deployed private-5G-connected NAVER service robots, while Huawei offers industrial enterprise networking. Product comparisons depend on the specific function sold, because a cellular chipset is not an equivalent substitute for a managed site network.
ABB participates through robotics platforms and a documented collaboration with Telefónica on remote AMR management over 5G. Telecommunications and enterprise network operators such as Telefónica and SoftBank contribute deployment management, spectrum access and network services. Private-wireless specialists can compete by reducing site installation complexity, but they must demonstrate compatibility with the customer's robot fleet and cyber policies.
Recent Developments
July 2026: Ericsson described operational AMRs at its Lewisville smart factory using private 5G and exchanging lidar-related information; the company reported material-handling missions completed 10–15% faster than with the earlier Wi-Fi arrangement.
April 2026: Siemens expanded its industrial private-5G portfolio to 15 countries in Europe and the Americas, introducing radio options for additional spectrum bands and routers with edge-runtime support.
April 2026: Ericsson and CENGN demonstrated a connected quadruped inspection robot at a Canadian advanced-manufacturing living lab; the event was a demonstration, not evidence of mass deployment.
March 2026: Qualcomm and NEURA Robotics announced a strategic collaboration on robotic computing, connectivity and physical-AI reference architectures; commercial unit shipments were not disclosed.
February 2026: SoftBank and Ericsson reported a proof of concept for robotic AI-task offloading between devices and mobile-edge resources over coordinated 5G infrastructure.
February 2025: Ericsson demonstrated its private-5G-enabled robotic dog Rocky at LEAP in Saudi Arabia, showing inspection and remote-monitoring scenarios rather than an announced commercial fleet.
Market Outlook
5G robotics connectivity is likely to concentrate on mobile fleets whose operations benefit from consistent site coverage, secure management and connection to nearby computing. Large manufacturers may purchase private radio and core infrastructure alongside enterprise network services, while smaller customers can favor carrier-managed environments or continued use of industrial Wi-Fi. The central measure of value will be avoided interrupted missions, better fleet utilization and simpler management of moving machines, rather than headline radio speed.
Asia Pacific should contribute the largest absolute increase in connectivity spending as industrial robotic fleets expand and network modules are qualified for more plant designs. Middle East and Africa can grow more rapidly in percentage terms from a small base, particularly where new industrial installations specify connectivity during construction. Over time, a larger share of spending may come from managed robotic connections, protected edge workloads and multi-site orchestration, although on-board autonomy and safe local operating behavior will remain essential.
5G-Enabled Robotics Connectivity Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.62 billion |
| Total Market Size in 2031 | USD 1.72 billion |
| Forecast Unit | Billion |
| Growth Rate | 22.64% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Robotics Type, Technology, Application, Geography |
| Companies |
|
Market Segmentation
By Component
Hardware
Software and Services
By Robotics Type
Autonomous Mobile Robots (AMRs)
Collaborative Robots
Others
By Technology
Network Infrastructure
Edge Computing
AI-Driven Robotics
Others
By Application
Healthcare and Telemedicine
Smart Manufacturing
Autonomous Vehicles and Drones
Agriculture Automation
Supply Chain and Logistics
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Asia Pacific
China
India
Japan
South Korea
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. More Mobile Robots in Material Handling
3.1.2. Enterprise Private 5G Procurement Expands
3.1.3. Shared Fleet Data Improves Robot Utilization
3.1.4. 5G Robotics Platforms Reduce Integration Barriers
3.1.5. Remote Inspection and Site Safety Workloads Broaden Use
3.2. Market Restraints
3.2.1. Coverage Engineering and Radio Interference
3.2.2. High Upfront Cost at Smaller Sites
3.2.3. Safety-Critical Control Must Remain Resilient
3.2.4. Device and Factory System Interoperability
3.2.5. Alternative Wireless Technologies Remain Competitive
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. 5G Private Radio and Core Architecture
4.2. Industrial 5G Routers and Robotics Modules
4.3. Edge Computing and Fleet Orchestration
4.4. Network Mobility, Positioning and QoS
4.5. Industrial Cybersecurity and Fail-Safe Integration
5. 5G-ENABLED ROBOTICS CONNECTIVITY MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software & Services
6. 5G-ENABLED ROBOTICS CONNECTIVITY MARKET BY ROBOTICS TYPE
6.1. Introduction
6.2. Autonomous Mobile Robots (AMRs)
6.3. Collaborative Robots
6.4. Others
7. 5G-ENABLED ROBOTICS CONNECTIVITY MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Network Infrastructure
7.3. Edge Computing
7.4. AI-Driven Robotics
7.5. Others
8. 5G-ENABLED ROBOTICS CONNECTIVITY MARKET BY APPLICATION
8.1. Introduction
8.2. Healthcare and Telemedicine
8.3. Smart Manufacturing
8.4. Autonomous Vehicles and Drones
8.5. Agriculture Automation
8.6. Supply Chain and Logistics
9. 5G-ENABLED ROBOTICS CONNECTIVITY MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. United Arab Emirates
9.4.3. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Thailand
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Ericsson AB
11.2. Nokia Corporation
11.3. Siemens AG
11.4. Qualcomm Incorporated
11.5. ABB Ltd.
11.6. Telefónica, S.A.
11.7. SoftBank Corp.
11.8. Huawei Technologies Co., Ltd.
11.9. Samsung Electronics Co., Ltd.
11.10. NAVER Cloud Corporation
11.11. Celona, Inc.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











