Africa Smart Irrigation Market - Strategic Insights and Forecasts (2026-2031)
Africa Smart Irrigation Market Size, Share, Forecasts and Trends Analysis By Component (Hardware, Software and Services), By System Type (Weather-Based Controller Systems, Soil Moisture Sensor-Based Systems, Hybrid and Other Systems), By Irrigation Type (Drip Irrigation, Sprinkler Irrigation, Pivot Irrigation, Others), By Application (Agriculture (Open-Field Farming, Orchards and Vineyards, Greenhouses and Protected Crops), Landscape and Turf, Other Applications), and Region
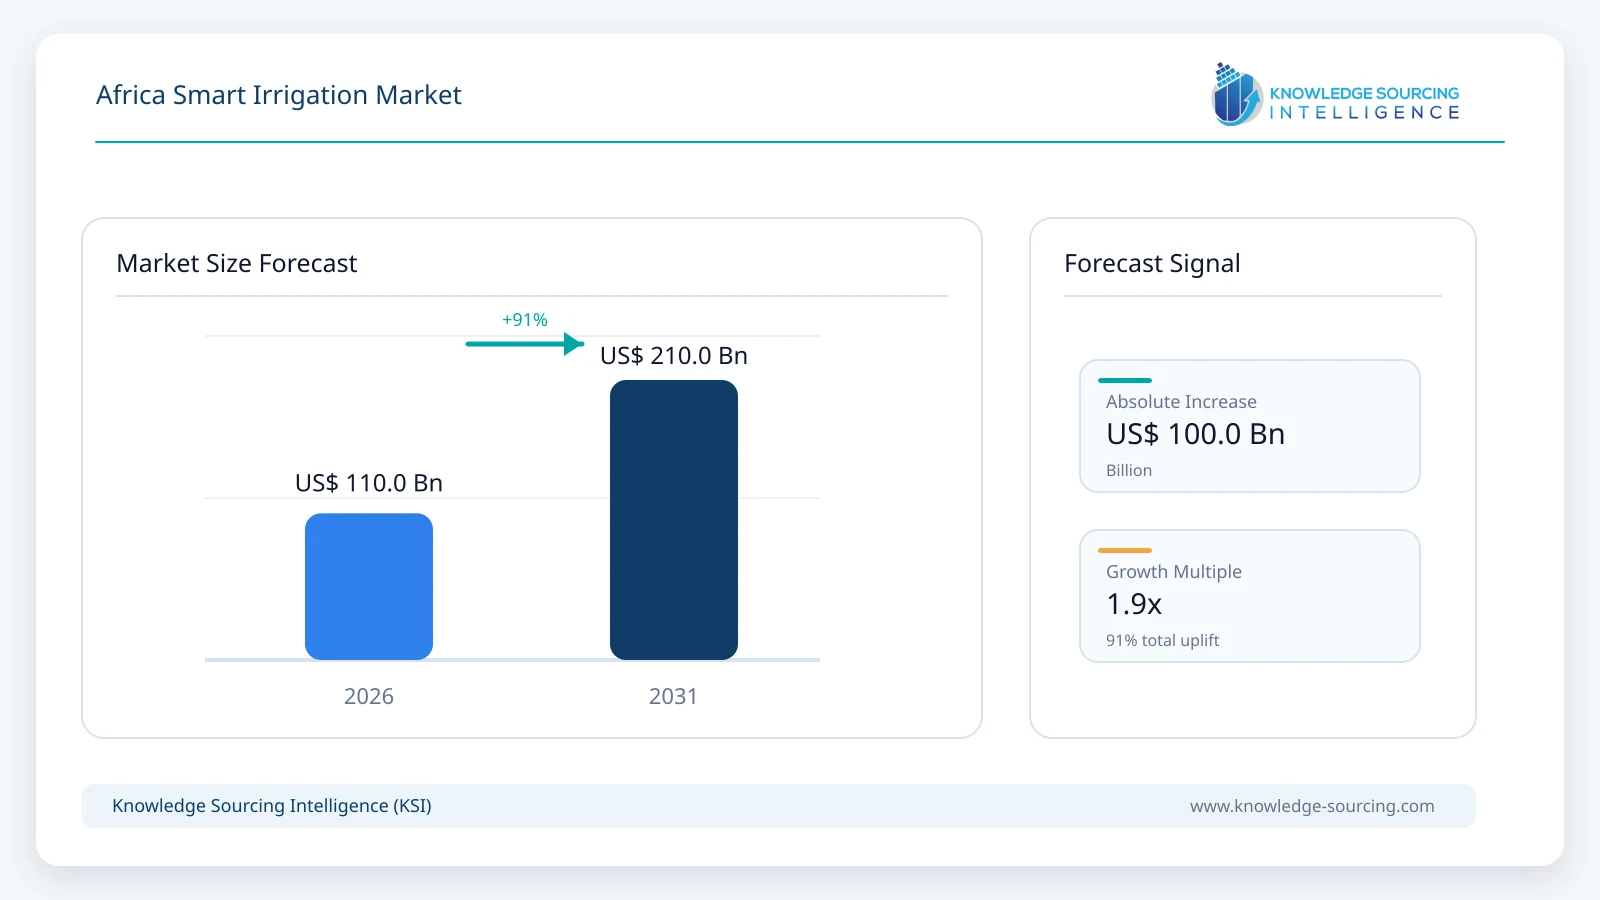
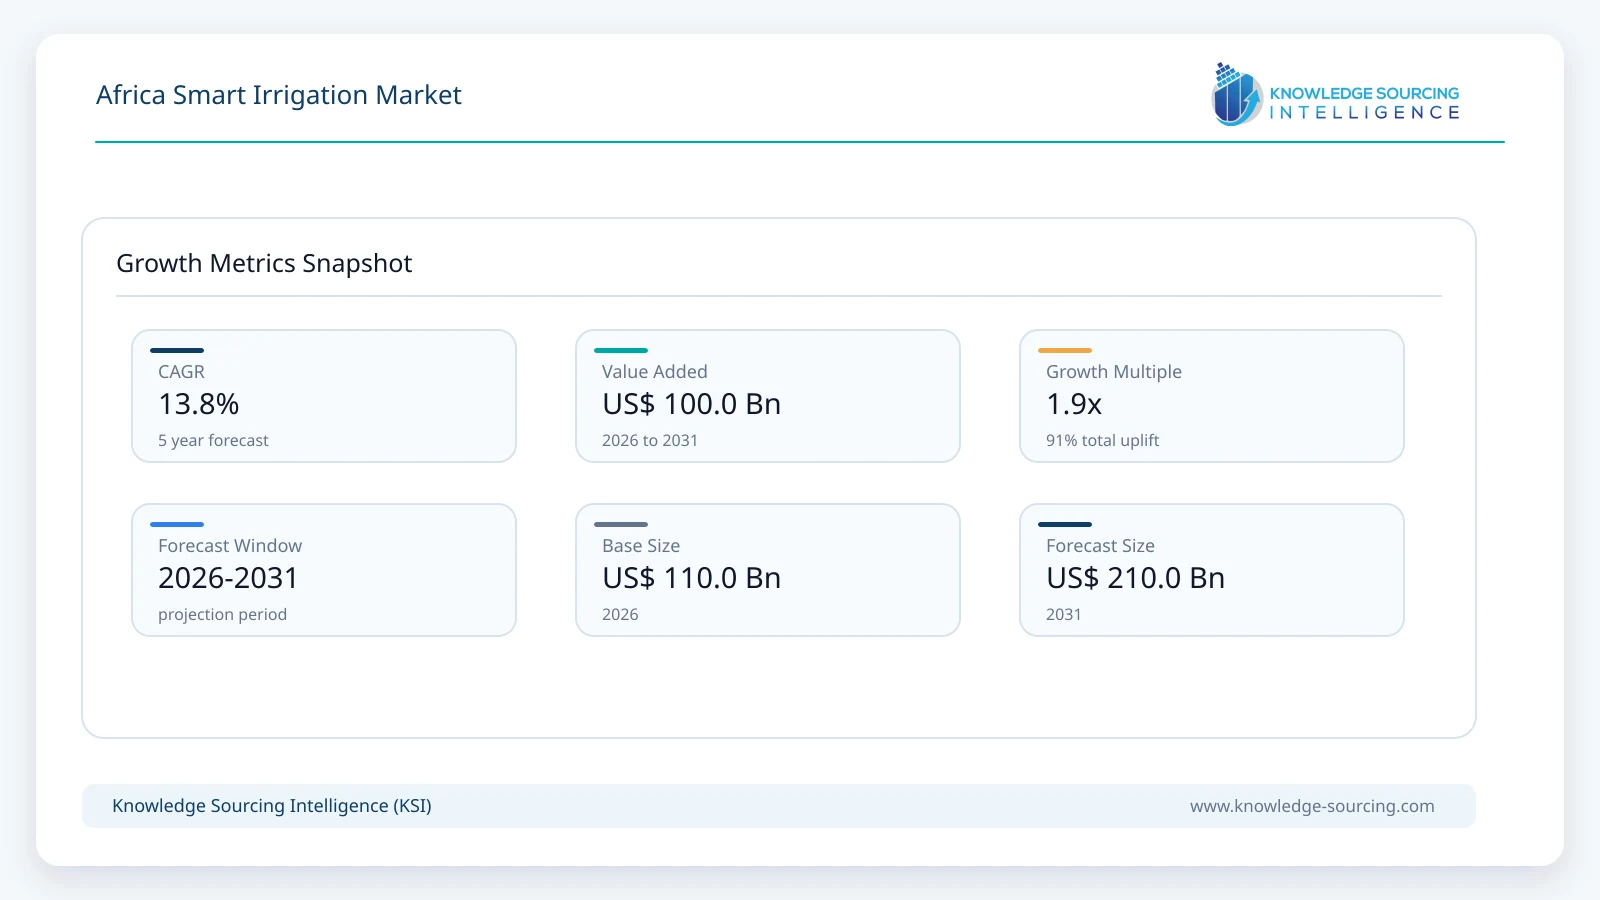
The Africa smart irrigation market is forecast to grow at a CAGR of 13.8%, reaching USD 210.0 million in 2031 from USD 110.0 million in 2026.
Highlights:
1
Hardware accounts for approximately 63% of 2026 revenue, reflecting greenfield infrastructure requirements.
2
Sensor-based systems grow at about 16.5% annually through 2031 as field telemetry expands.
3
Agricultural applications generate roughly USD 92.4 million in 2026, dominating smart-irrigation deployment.
4
South Africa contributes approximately 24% of 2026 revenue through commercial-farm automation demand.
5
PAYG solar irrigation is widening smallholder access beyond conventional equipment-finance channels.
6
Water metering and resilience programs increasingly connect irrigation hardware with digital monitoring.
Market Overview
Smart irrigation differs from conventional irrigation because the water-delivery system is linked to a decision or control layer. A field may use drip, sprinkler or pivot hardware, but it becomes smart when controllers, soil-moisture probes, weather data, flow measurement, remote telemetry or software are used to modify irrigation schedules and monitor actual performance. Netafim's GrowSphere platform, for example, connects controllers, sensors, cloud software and mobile access, while Lindsay's FieldNET and Valmont's AgSense 365 support remote monitoring and control of mechanized irrigation. CropX approaches the market from the agronomy side by combining soil measurements, evapotranspiration and irrigation recommendations. This diversity means the market includes both dedicated smart-irrigation hardware and the digital layer attached to existing irrigation assets.
Africa has a distinctive adoption pathway because irrigation infrastructure itself remains underdeveloped across many countries. SunCulture states that less than 4% of farmland in Sub-Saharan Africa is irrigated, while FAO notes globally that irrigated land produces a disproportionate share of crop value and that water stress is increasing. Consequently, many African buyers are not simply replacing older controllers; they are installing their first reliable irrigation system. This gives integrated solar pump, controller, sensor and financing packages greater relevance than in mature markets where the main purchase may be a software upgrade or replacement controller. At the same time, larger farms in South Africa, Egypt, Morocco, Kenya and other commercial horticulture markets are adopting the same remote control, flow monitoring and precision scheduling technologies used in developed agricultural regions.
Market Trends
Solar irrigation is becoming a platform for connected farm services
Solar pumping is moving beyond its original role as a substitute for diesel. In East Africa, SunCulture combines solar water pumps with financing, installation, after-sales support and IoT monitoring, creating a distribution model in which the pump becomes the entry point for additional digital services. The company is also using carbon-credit economics to reduce customer prices and has linked irrigation ownership with climate-risk products. In December 2025, SunCulture announced the sale of 10,000 Verified Carbon Units to EDF Trading as part of a wider effort to develop a carbon-financing ecosystem for solar irrigation. In April 2026, it completed the first payout cycle under a climate insurance program in Kenya. These models matter because smart irrigation in Africa is often constrained less by the value proposition than by farmer cash flow, access to credit and after-sales capability.
Controllers and software are shifting from remote switching toward closed-loop irrigation
The technology layer is also becoming more capable. Earlier remote-irrigation systems primarily allowed a farmer to turn pumps or pivots on and off from a phone. Newer platforms combine equipment status, soil moisture, weather, crop models, flow data and irrigation recommendations. Valmont announced in January 2025 that it would consolidate Valley 365, AgSense, PrecisionKing and PivoTrac into the AgSense 365 application, while Netafim launched GrowSphere FLEX in August 2026 as a connected irrigation and fertigation controller for smallholder and mid-sized farms. CropX similarly uses field-level soil and evapotranspiration data to guide irrigation timing. For African commercial farms, these capabilities improve labor productivity and water accountability; for smaller farms, simplified controllers and mobile interfaces can reduce the expertise needed to operate more precise irrigation systems.
Market Drivers
Low irrigation penetration and climate variability create a large modernization requirement
Africa's irrigation gap remains the fundamental demand driver. Rain-fed production exposes farmers to increasingly variable rainfall, while drought and water stress make fixed-calendar irrigation less reliable where irrigation already exists. FAO reports that irrigation is central to maintaining agricultural productivity under rising water pressure and that irrigated yields are materially higher than rain-fed yields on average. In Nigeria, the World Bank reported in October 2025 that the TRIMING project had expanded irrigation across 43,400 hectares, demonstrating the scale of infrastructure modernization still underway. Zimbabwe, Rwanda and other countries are also using climate-smart irrigation within resilience programs. The smart-irrigation opportunity therefore grows in two directions: new irrigated acreage creates first-time demand for controllers, meters and monitoring, while existing irrigated farms need better scheduling to produce more crop output per unit of water.
Public investment, water regulation and commercial-farm economics reinforce adoption
Government and development-finance programs increasingly treat irrigation as food-security infrastructure rather than isolated farm equipment. Kenya's 2025 National Irrigation Sector Investment Plan is a USD 2.7 billion, ten-year initiative designed to expand irrigation by 1 million acres, with a financing model that combines public funds, private capital, climate finance and irrigation-as-a-service. In South Africa, the National Water Act framework requires irrigation abstraction to be measured, recorded and reported in defined circumstances, supporting demand for compliant flow measurement and monitoring systems. Commercial horticulture and export-oriented farms add a separate economic driver because irrigation failures directly affect crop quality, export contracts and input efficiency. This makes remote alarms, pump control, fertigation automation and soil-based scheduling easier to justify than on low-value rain-fed crops.
Market Restraint
Upfront cost, service coverage and connectivity limit conversion from basic irrigation to smart systems
The primary constraint is the total installed cost relative to farm income. A smart-irrigation deployment may require a pump, power source, filtration, hydraulic equipment, sensors, controllers, communications and software before the farmer receives any agronomic benefit. This is a much larger barrier for smallholders than the price of an individual sensor. Financing programs reduce the burden, but they transfer risk to suppliers and lenders and require reliable payment infrastructure. Maintenance is another issue: sensors need calibration or replacement, valves and pumps need field service, and connected systems require either cellular, radio or other communications that may be inconsistent in remote areas. These limitations favor suppliers that combine local technicians, spare parts, training and financing with hardware rather than selling technology as a stand-alone digital product.
Segment Analysis
By Component - Hardware
Hardware remains the largest component because much of the market is still building the physical layer required for connected irrigation. Controllers, soil-moisture sensors, weather stations, flow meters, telemetry gateways and smart pump-control devices must often be installed alongside new drip, sprinkler or pivot systems. Hardware revenue is projected to approach USD 124.0 million by 2031, even as its share gradually declines. Software and services grow faster because every connected device adds monitoring, alerts, analytics, reporting and remote-support opportunities. Subscription pricing is still less established than in North America or Europe, but the economics become more attractive as commercial farms centralize multiple irrigation blocks and equipment fleets onto a single platform.
By System Type - Soil Moisture Sensor-Based Systems
Soil-moisture sensor-based systems are the fastest-growing system category and are projected to exceed USD 90 million in annual market value by 2031. Their advantage is that irrigation decisions are tied directly to conditions in the crop root zone rather than only to a weather forecast or fixed schedule. This is particularly useful where soils vary substantially across a farm or where water must be rationed. Weather-based controllers remain important for landscape irrigation and for agricultural scheduling using evapotranspiration, while hybrid systems combine weather, soil, crop and hydraulic data. The direction of travel is toward multi-input systems, but soil sensors provide a practical first step because farmers can see the effect of irrigation and rainfall directly in the field profile.
By Irrigation Type - Drip Irrigation
Drip irrigation is projected to generate approximately USD 105 million of smart-irrigation revenue by 2031. Its position reflects the strong fit between controlled water delivery and high-value horticulture, greenhouse production, orchards and smallholder plots. Smart drip systems can integrate pump automation, filtration monitoring, fertigation, pressure control, flow measurement and field sensors, allowing the digital layer to influence both water quantity and nutrient application. Pivot irrigation remains important for larger commercial farms and is well suited to remote monitoring and variable-rate control through platforms such as AgSense 365 and FieldNET. Sprinkler systems serve a broader set of crops and landscape applications but typically carry less digital content per hectare than complex pivot or fertigation systems.
By Application - Agriculture
Agriculture remains the core application and is projected to reach approximately USD 177 million by 2031. Commercial horticulture, row crops, orchards, vineyards, sugar, greenhouse production and irrigated grains account for most spending because the value of water, fertilizer and crop loss supports investment in automation. Smallholder adoption is increasing where solar pumps, drip kits and controllers are bundled with credit or pay-as-you-grow finance. Non-agricultural applications include golf courses, sports grounds, commercial landscapes, public spaces and larger residential properties. These applications are more established in South Africa and selected North African urban markets, where water restrictions and operating costs can justify central control and soil- or weather-based scheduling.
By Geography - South Africa
South Africa remains the largest single national market and is projected to approach USD 49 million by 2031. The country combines large commercial farms, orchards, vineyards and landscaping demand with local irrigation engineering capabilities and a regulatory framework that emphasizes measurement of agricultural water use. Companies such as Agrico, Irritech Agencies International and TurfManzi provide local design, installation and service, while international brands participate through distributors and project partners. Egypt and Morocco form another substantial demand pool around water-constrained agriculture and modernized irrigation. Kenya is smaller in current revenue but is among the faster-growing markets because of solar irrigation, public investment and financing innovation, while Nigeria presents significant long-term potential as irrigation rehabilitation expands.
Competitive Environment
Competition spans global irrigation manufacturers, digital-agriculture companies and African integrators. Netafim, Rivulis, Valmont and Lindsay compete through large installed bases and connected irrigation platforms, while Rain Bird, Hunter and Toro have strong positions in controllers and landscape irrigation. Reinke participates in mechanized irrigation, and CropX adds a sensor and agronomy software layer that can work with multiple irrigation systems. SunCulture is distinctive because it is built around the economics of African smallholders, combining solar pumping, IoT, financing and local support instead of selling only irrigation components.
Local execution remains a decisive advantage. Irritech Agencies International operates across South Africa, Zambia and Tanzania and has extensive experience with drip, micro and Valley centre-pivot systems. TurfManzi has expanded from South Africa into broader Sub-Saharan commercial and water-management projects, while Agrico provides regional irrigation engineering and mechanization capabilities. Customers often require system design, borehole or water-source assessment, power integration, filtration, commissioning and ongoing field service, which means a technically strong controller manufacturer may still depend on a local integrator to convert technology into a functioning farm system. Financing, spare-parts availability and technician reach are therefore as important as sensor specifications in many African markets.
Recent Developments
August 2026: Orbia Netafim launched GrowSphere FLEX, extending connected irrigation and fertigation control toward smallholder and mid-sized farms.
April 2026: SunCulture completed the first payout cycle under its Kenya climate-insurance program, linking irrigation ownership with farm-risk protection.
December 2025: SunCulture announced the sale of 10,000 Verified Carbon Units to EDF Trading to support a carbon-financing ecosystem for solar irrigation.
November 2025: The African Water Facility adopted a new five-year strategy focused on mobilizing investment and strengthening water security across Africa.
March 2025: Kenya launched its USD 2.7 billion National Irrigation Sector Investment Plan, targeting 1 million additional irrigated acres over ten years.
January 2025: Valmont announced the consolidation of four Valley irrigation-management platforms into the AgSense 365 application.
Africa Smart Irrigation Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 110.0 million
Total Market Size in 2031
USD 210.0 million
Forecast Unit
Billion
Growth Rate
13.8%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Component, System Type, Irrigation Type, Application
Companies
SunCulture
Orbia Netafim
Rivulis Irrigation
Valmont Industries Inc. (Valley Irrigation)
Lindsay Corporation (Zimmatic / FieldNET)
Jain Irrigation Systems Ltd.
Rain Bird Corporation
The Toro Company
Market Segmentation
By Component
Hardware
Software and Services
By System Type
Weather-Based Controller Systems
Soil Moisture Sensor-Based Systems
Hybrid and Other Systems
By Irrigation Type
Drip Irrigation
Sprinkler Irrigation
Pivot Irrigation
Others
By Application
Agriculture
Open-Field Farming
Orchards and Vineyards
Greenhouses and Protected Crops
Landscape and Turf
Other Applications
By Country
South Africa
Egypt
Morocco
Kenya
Nigeria
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Low Irrigation Penetration and Climate Variability Create a Large Modernization Requirement
3.1.2. Public Investment, Water Regulation and Commercial-Farm Economics Reinforce Adoption
3.2. Market Restraint
3.2.1. Upfront Cost, Service Coverage and Connectivity Limit Conversion From Basic Irrigation to Smart Systems
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. IoT-Enabled Solar Irrigation
4.2. Soil Moisture and ET-Based Scheduling
4.3. Remote Pump, Pivot and Valve Control
4.4. AI-Enabled Irrigation Recommendations and Farm Analytics
5. AFRICA SMART IRRIGATION MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software and Services
6. AFRICA SMART IRRIGATION MARKET BY SYSTEM TYPE
6.1. Introduction
6.2. Weather-Based Controller Systems
6.3. Soil Moisture Sensor-Based Systems
6.4. Hybrid and Other Systems
7. AFRICA SMART IRRIGATION MARKET BY IRRIGATION TYPE
7.1. Introduction
7.2. Drip Irrigation
7.3. Sprinkler Irrigation
7.4. Pivot Irrigation
7.5. Others
8. AFRICA SMART IRRIGATION MARKET BY APPLICATION
8.1. Introduction
8.2. Agriculture
8.2.1. Open-Field Farming
8.2.2. Orchards and Vineyards
8.2.3. Greenhouses and Protected Crops
8.3. Landscape and Turf
8.4. Other Applications
9. AFRICA SMART IRRIGATION MARKET BY COUNTRY
9.1. Introduction
9.2. South Africa
9.3. Egypt
9.4. Morocco
9.5. Kenya
9.6. Nigeria
9.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. SunCulture
11.2. Orbia Netafim
11.3. Rivulis Irrigation
11.4. Valmont Industries, Inc. (Valley Irrigation)