AI in Aviation Market - Strategic Insights and Forecasts (2026-2031)
AI in Aviation Market Size, Growth, Share, Forecasts and Trends Analysis By Component Type (Hardware, Software, Services), Technology (Machine Learning, Deep Learning, Computer Vision, Natural Language Processing, Generative AI, Other Technologies), Application (Predictive Maintenance, Flight Operations, Air Traffic Management, Airport Operations, Revenue Management, Baggage Management, Customer Experience, Other Applications), and Geography
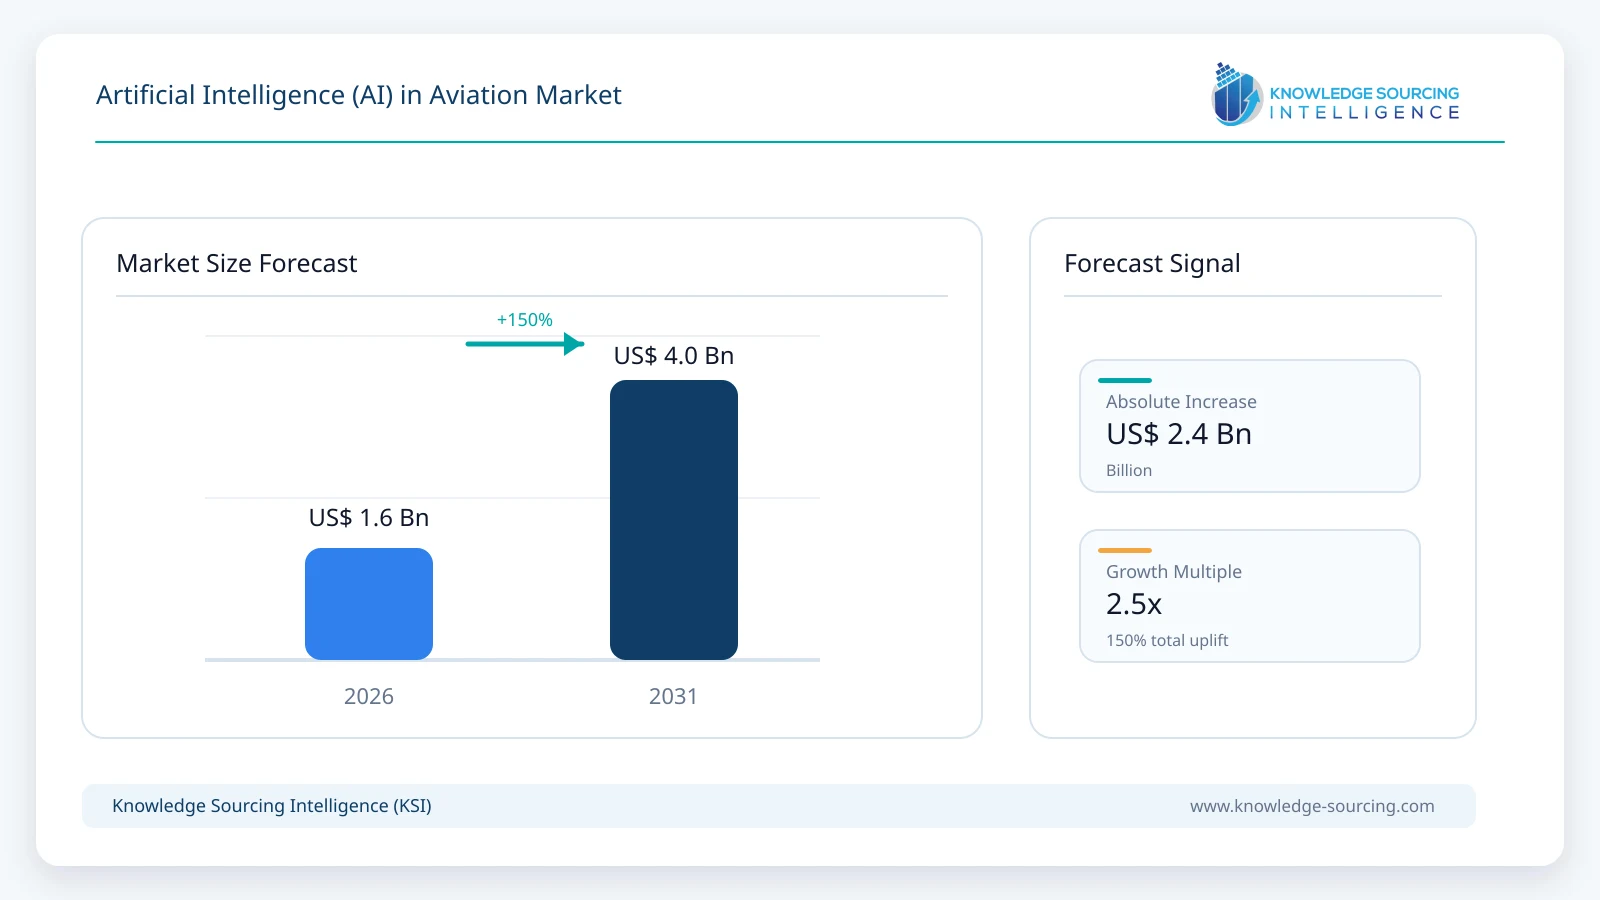
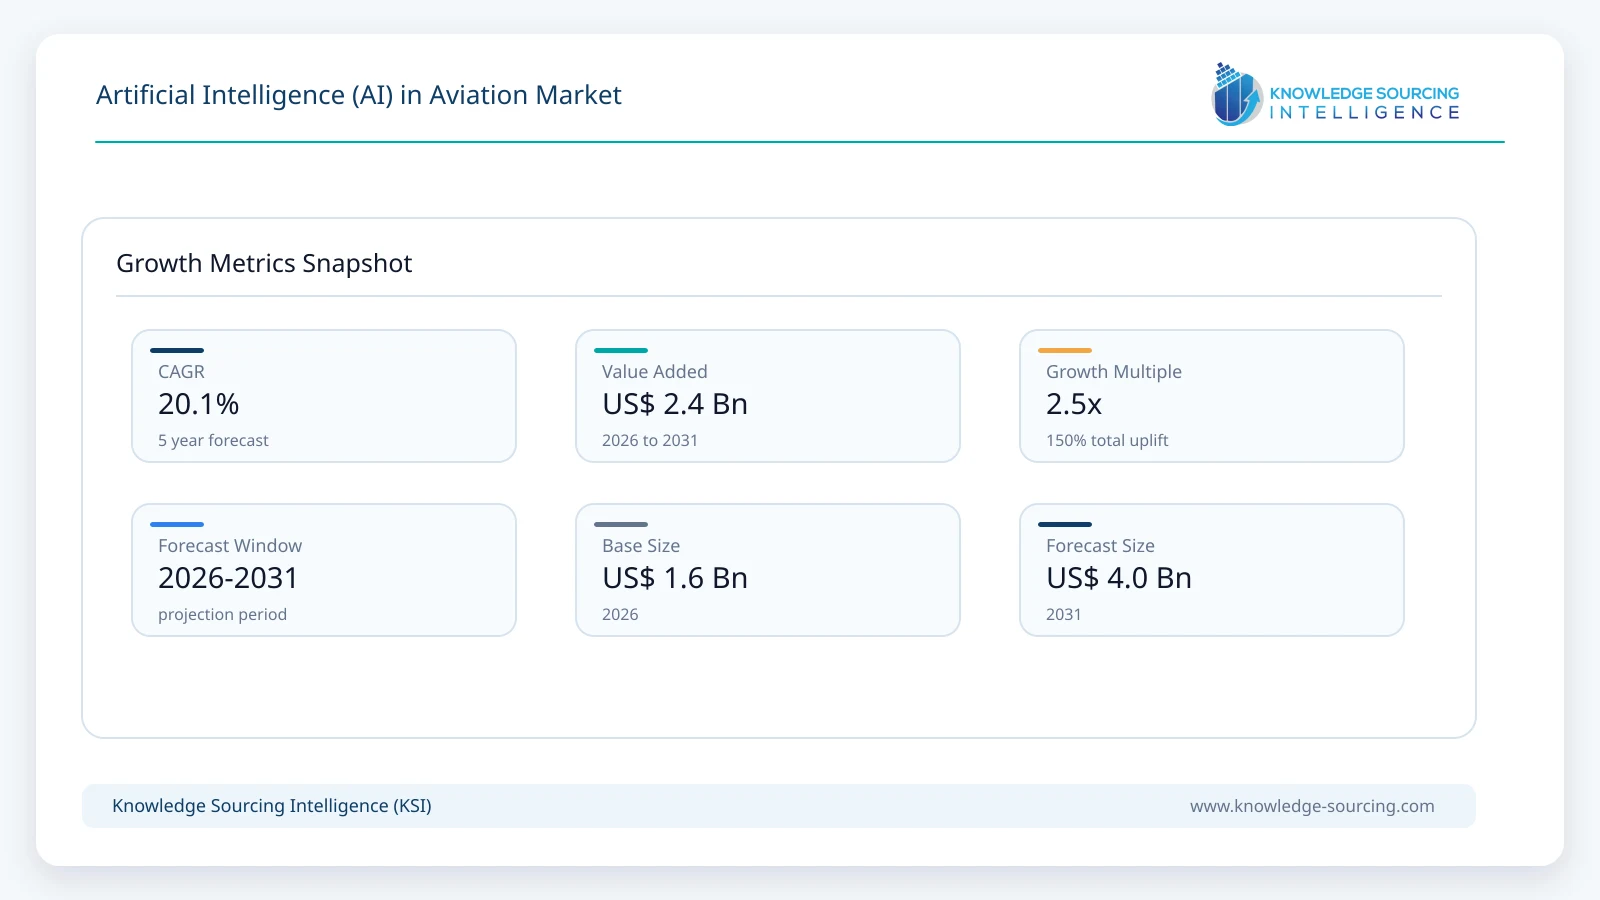
The global AI in Aviation Market is projected to grow from an estimated USD 1.60 billion in 2026 to USD 4.00 billion by 2031, at a CAGR of approximately 20.1% across the forecast period.
Highlights:
1
Software accounts for an indicative 56% of the 2026 product market, led by fleet analytics and enterprise aviation applications.
2
Predictive maintenance represents a sizeable early application, while airport operations gain importance as real-time data coordination improves.
3
Generative AI could approach 21% of the 2031 technology allocation, principally through document, engineering and service workflows.
4
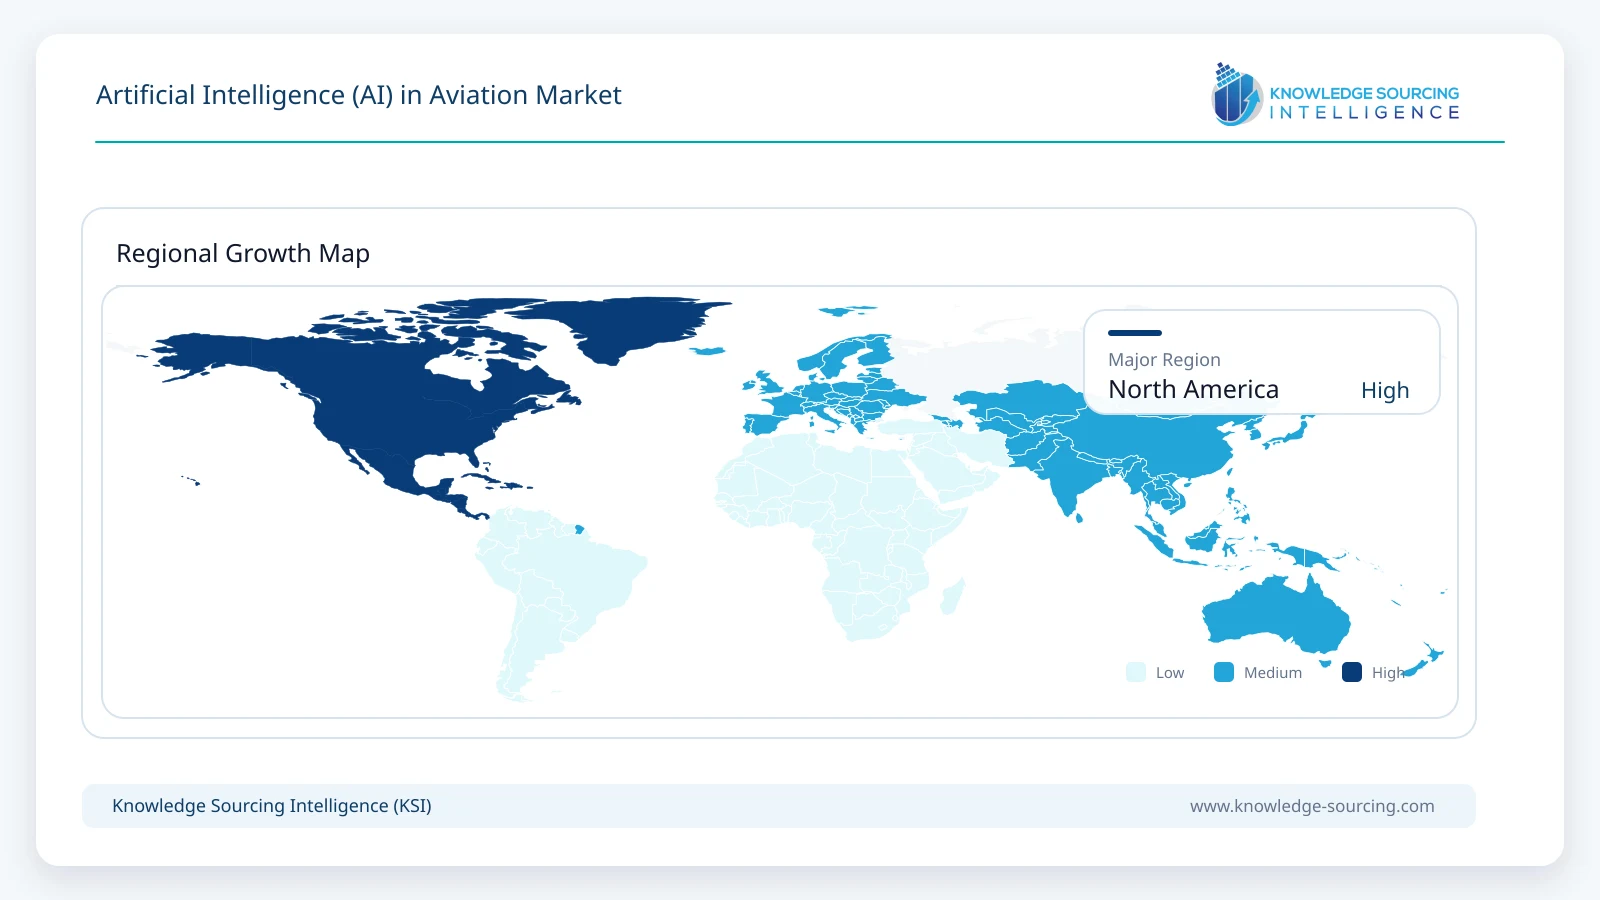
North America retains the largest modeled share, while Asia Pacific has the highest calculated regional growth rate.
5
Regulated functions require traceable validation and human oversight, keeping the commercialization pace below that of administrative automation.
6
OEM-led aviation data platforms and specialist airline-system vendors compete on integration, data rights and recurring operational outcomes.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Key Highlights:
Aircraft-condition analytics, intelligent flight planning, airport-operations forecasting and passenger-service software constitute the core of the AI in Aviation Market. The revenue boundary includes attributable software subscriptions, specialist integration and support, and AI-specific sensing or processing hardware. Aircraft sales, ordinary airport infrastructure, conventional airline IT systems and unallocated public-cloud spending fall outside this scope.
An airline buying a fleet-health application may license the software per aircraft and separately commission an interface to its maintenance information system. An airport deploying passenger-flow prediction needs camera or event data, agreed timestamps, operational ownership and a means of instructing terminal teams. An air navigation service provider faces stricter safety assurance for a decision-support system than a carrier does for a marketing assistant. These distinctions shape achievable pricing and implementation cycles.
SITA’s 2025 airline IT survey reports that 63% of respondents use AI in operations control and that 49% identify data integration and consistency as a major barrier. The figures measure adoption and obstacles, not purchases of aviation AI products. They nonetheless explain why carriers increasingly attach analytics to aircraft assignment, crew recovery and disruption management rather than purchase an isolated prediction engine.
JetBlue’s April 2026 agreement to deploy Skywise Fleet Performance+ across its A320-family and expanding A220 operations shows the maintenance case. Aircraft condition monitoring can reduce unnecessary troubleshooting, but savings depend on lead time, spare-part availability and engineering approval. A fault prediction arriving after a departure window has closed seldom protects the schedule, regardless of the underlying model’s accuracy.
Market Trends
Fleet intelligence shifts from aircraft data to usable engineering decisions
Boeing’s 20 October 2026 Dataliner announcement emphasizes connected information across a fleet rather than separate maintenance dashboards for individual aircraft. Airbus’ reorganized Skywise business pursues a related goal through aircraft and flight-operations data. A reliability engineer needs to understand whether an alert warrants a component removal, a deferred action or a fleet inspection; presenting a large number of anomaly scores is not sufficient.
Mixed-fleet compatibility and the treatment of third-party maintenance records will determine how widely such platforms can be sold. Suppliers with access to OEM engineering context possess an advantage, but airline-controlled data and independent maintenance systems create openings for integrators. Contract performance is increasingly tied to the quality of fault classification and the ability to close a maintenance workflow.
Airport intelligence is moving toward shared turnaround control
Gate occupancy, stand availability, baggage transfers and inbound aircraft delays frequently interact across organizational boundaries. AI models that estimate a gate conflict or missed connection can help only when airport operators, airlines and handlers share the underlying status information early enough to act. SITA’s airport survey reports AI use in passenger-flow management, alongside continued investment in interoperable data infrastructure.
Suppliers are therefore building operational decision layers around existing airport systems rather than replacing every sensor or terminal database. Passenger-flow analytics can support staffing, but physical bottlenecks, service-level agreements and data-sharing rights still decide whether forecast accuracy produces a measurable turnaround benefit.
Generative AI is being directed at specialist operational knowledge
Airbus and Mistral AI announced a May 2026 partnership covering technical documentation, engineering and sensitive aerospace workloads. The arrangement includes options for trusted clouds and on-premises deployments. These are practical requirements for airlines and aerospace companies that cannot release maintenance manuals, engineering drawings or restricted records into unrestricted public services.
Retrieval quality and controlled tool access will matter more than a fluent response. A maintenance document assistant needs version-specific approved instructions and must not invent an aircraft procedure. Customer-service assistants face different risks: fare rules, disruption entitlements and refund authority must remain connected to authoritative reservation systems.
AI-assisted distribution makes search performance an infrastructure issue
Amadeus and NVIDIA signed an October 2026 memorandum to explore accelerated flight search and travel-specific models. Initial technical benchmarking is not evidence of a production rollout, but it reveals the scale challenge created when automated assistants request many combinations of fares, connections and travel conditions rather than a simple list of flights.
Search speed alone will not settle the economics. Sellers must maintain bookable availability, realistic total prices and control of computing cost per query. Airlines and distribution providers will favor systems that connect model-generated requests with reservation and revenue-management rules without producing invalid or unfulfillable offers.
AI in Aviation Market Segment Analysis
By Component
Software
Software represents an estimated USD 2.36 billion of AI aviation spending by 2031 in the modeled product boundary, reflecting a growing base of fleet analytics, operations planning and customer applications. Airline software is commonly purchased alongside maintenance, reservations or dispatch systems already in service. This reduces the need for dedicated aircraft hardware and makes recurring subscriptions more practical than a separate bespoke platform at every airport.
The value of Boeing Dataliner or Skywise Fleet Performance+ depends on integration into authorized technical records, not on a generalized language model. Services remain material during implementation, while hardware is relevant for computer-vision inspection and certain edge processing tasks. Counting an entire baggage installation or avionics unit as AI revenue would overstate the component market.
By Technology
Generative AI
Generative AI is finding purchased use cases in technical-document navigation, engineering support and passenger communications. Airbus’ arrangement with Mistral illustrates why secure deployment matters for proprietary aerospace material. Operations personnel still need verified sources and explicit escalation when an assistant cannot establish an answer. Machine learning remains fundamental to flight optimization and maintenance predictions, while deep learning and computer vision address different data types.
The modeled Generative AI category expands at approximately 30.3% annually through 2031, faster than conventional natural-language interfaces under the chosen allocation. The estimate classifies the principal commercial function of each purchase; it does not imply that generative models are technically separate from machine learning or deep learning. Pricing will be influenced by model usage, domain-specific adaptation and the value of secure integration.
By Application
Predictive Maintenance
Predictive maintenance accounts for approximately USD 448 million in the 2026 application scenario. Aircraft operators face direct costs from unscheduled groundings, repeated fault isolation and poorly timed component replacements. Monitoring programs that combine health measurements with engineering history can prioritize a suitable intervention before the next maintenance window, provided a responsible engineer can evaluate the output.
The applications are commercially credible because a prevented operational disruption has a recognizable economic value. Rolls-Royce and Bombardier expanded health monitoring for Global 5500 and 6500 aircraft in June 2026, linking more detailed engine information with support decisions. Predictive maintenance retains a large share in the 2031 mix, while airport operations and customer interfaces grow from smaller commercial bases.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Drivers
Aircraft availability is becoming a measurable purchasing criterion
JetBlue’s Fleet Performance+ agreement indicates a customer preference for systems that make aircraft health information actionable. A carrier can measure repeat defects, aircraft-on-ground hours, unnecessary removals and time to resolution more readily than it can measure the appeal of a generic AI application. Contracts are attractive when analytics help maintenance teams intervene before schedule reliability deteriorates.
The procurement case strengthens across complex mixed fleets, where engineers must join fault messages, maintenance histories and component-service experience. Vendors that offer credible predictive results together with parts-planning or troubleshooting interfaces can capture more value than sellers of standalone anomaly alerts. Validation expense rises when different aircraft types require distinct models.
Airport congestion is raising the value of coordinated forecasts
Airport operators schedule stands, gates, security resources and baggage transfer operations against constantly changing flight arrivals. SITA’s airport survey identifies AI use in passenger-flow management and continued investment in systems able to share operational information across organizational silos. Forecasting can reduce congestion only if a ground handler or airport controller receives a usable instruction.
As passenger volumes and aircraft-turnover requirements increase, integrated applications become more defensible than disconnected dashboards. Suppliers that can connect timestamps, event definitions and responsibilities across partners are positioned to secure multi-year airport modernization projects. Smaller airports will still weigh deployment complexity against limited IT budgets.
Fuel and disruption economics support operational optimization
IATA’s June 2026 outlook describes higher energy costs, route changes and airspace disruption rather than uninterrupted passenger expansion. Flight-planning tools that incorporate weather, available airspace and crew constraints can have greater economic importance in such conditions. A modest fuel or recovery improvement may affect hundreds of departures across a large carrier.
Airlines will favor decision-support systems that show dispatchers why a recommendation differs from the operating plan. Flight planning is highly constrained, and model output must respect aircraft performance, safety margins and approved operational procedures. Supplier value lies in fitting these recommendations into established flight-operations systems.
Aviation data partnerships are turning analytics into ongoing services
Airbus combined Skywise and NAVBLUE in April 2026 to align flight, technical and ground-operations offerings. Boeing’s Dataliner followed with a connected fleet-data proposition. Both developments indicate that aircraft data and domain expertise are becoming a foundation for sustained customer relationships rather than isolated software projects.
Aircraft operators benefit when updates, data ingestion and model recalibration are provided under an accountable support arrangement. Service revenue can expand through training, integration and performance monitoring, although contracts must distinguish newly billed AI functionality from already included technical support. This is particularly important where OEM programs bundle digital tools into broader maintenance agreements.
Natural-language interfaces are widening the addressable workflow base
Maintenance document search, passenger disruption messaging and airline-shopping interfaces are attracting model-based product development. Airbus and Mistral are addressing sensitive engineering workflows; Amadeus and NVIDIA are evaluating new approaches to flight search. These use cases draw buyers beyond the technical departments that first adopted predictive aircraft analytics.
Commercial adoption requires output controls that reflect each workflow. A chatbot answering a baggage question faces a different liability exposure from an assistant retrieving aircraft maintenance steps. Secure data handling, validated references and integration with existing systems will therefore influence which initial pilots receive recurring budget.
Market Restraints
Safety assurance slows deployment in critical functions
EASA’s June 2026 AI concept-paper consultation illustrates the additional evidence demanded when algorithms influence regulated aviation activities. Model accuracy on historical datasets does not establish reliability during unusual weather, failures or rare air-traffic conditions. Operators need traceable design assumptions and clear procedures for human intervention.
Certification and change-control work can extend procurement timelines and raise lifecycle costs. Suppliers may be able to update an administrative assistant rapidly, but an AI function affecting aircraft operation cannot be changed without the appropriate assurance process. The difference constrains revenue conversion in higher-risk applications.
Fragmented aircraft and airport records create expensive integration work
Aircraft technical logs, engine measurements, airport event feeds and airline planning systems do not share a universal data architecture. SITA reports data consistency as a major obstacle among airline IT respondents. Even a strong prediction model may be unusable when aircraft identification, gate events or component histories are incomplete or inconsistent.
Integration costs can favor larger aviation technology vendors with established customer connections. Smaller suppliers must invest in customer-specific interfaces and data cleansing before a pilot can demonstrate value. Buyers consequently examine the total cost of maintaining those interfaces, not simply the price of a software licence.
Cybersecurity and data rights limit the pool of shareable information
Fleet engineering data, passenger records and airport operations information carry distinct confidentiality and security obligations. Sharing data across airlines, OEMs and ground handlers can improve prediction but also raises questions about ownership, authorized use and onward transfer. An AI service that requires unrestricted access may be disqualified before its technical performance is tested.
Secure hosting, identity controls, logging and model-output restrictions increase the cost of deployment. Airbus’ emphasis on trusted and on-premises AI options reflects this buying requirement. Providers need precise contract rules for data retention and model training if they wish to expand internationally.
Algorithmic outputs do not automatically translate into accepted actions
Maintenance engineers cannot remove an aircraft component merely because an anomaly score is elevated; technical instructions, availability and safety procedures still govern intervention. Likewise, a flight-search model must return an actually bookable fare, not an attractive but impossible itinerary. Predictive performance is only one part of operating value.
False alarms, inconsistent recommendations and limited explanation can erode frontline trust. Businesses therefore spend on supervised trials, exception handling and training, sometimes for longer than the original development effort. Vendors unable to demonstrate how their outputs change an approved decision risk losing contracts at renewal.
Specialist talent and long qualification cycles constrain scale
Aviation AI implementations need aircraft engineers, operations planners, data architects, cybersecurity specialists and qualified operational users. A general-purpose software implementation team often lacks the airworthiness, flight-dispatch or airport-safety context required to evaluate edge cases. Specialist skills remain expensive and difficult to replicate across countries.
Long validation schedules and bespoke system interfaces make revenue conversion uneven, particularly for independent vendors without an installed aviation customer base. Established suppliers benefit from customer relationships, but their product launches also require substantial engineering and support investment before broad deployment.
Regional Outlook
North America-Largest 2026 revenue base
North America represents an indicative 39% of 2026 global market revenue, or USD 624 million, in the reconciled scenario. The separately published KSI United States forecast of USD 430.2 million in 2026 forms the US anchor within that regional amount. Major airline fleets, airport systems, OEM engineering and cloud infrastructure support demand for predictive maintenance, disruption management and passenger-facing applications.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
The regional market reaches approximately USD 1.40 billion in 2031, implying growth of 17.5% annually from the modeled 2026 base. US adoption benefits from existing procurement structures and engineering support, while Canadian airports and airlines offer additional opportunities for software and integration. Mature enterprise systems also make data ownership and interoperability central to contract decisions.
Asia Pacific-Fastest-growing modeled region
Asia Pacific’s mix of expanding airline fleets, heavily used hub airports and varied digital maturity creates opportunities for scalable aviation analytics. The regional model increases from USD 432 million in 2026 to USD 1.32 billion by 2031, equivalent to a CAGR of approximately 25.0%. Growth is concentrated in aviation operations, airport resource management and aircraft-health applications rather than indiscriminate spending on autonomous flight.
China, India, Japan and Southeast Asian aviation hubs face distinct requirements for language support, operational interfaces and data residency. Airport-development programs support new installations, while airlines with mixed fleets need integration across multiple OEM platforms. Local implementation partnerships are likely to matter as much as model performance for providers entering this region.
Competitive Landscape
Airbus Skywise and Boeing Global Services have privileged access to aircraft engineering and lifecycle relationships, but independent platforms remain necessary when operators need to integrate mixed fleets and outside maintenance providers. Rolls-Royce, GE Aerospace and Lufthansa Technik focus on technical health and predictive maintenance, whereas Amadeus and Sabre compete around airline commercial systems, distribution and revenue optimization. SITA concentrates on airport, passenger and operational connectivity.
Thales and Collins Aerospace bring air traffic and avionics expertise, while Honeywell operates across aerospace analytics and connected systems. FLYR offers specialized airline revenue optimization. Cloud infrastructure and foundation-model firms can enable these offerings, but their company-wide revenue is not equivalent to aviation AI product sales. Competition is strongest where a vendor has a repeatable application, clear data rights and documented savings within a controlled operating workflow.
Recent Developments
October 2026: Amadeus and NVIDIA-Signed a memorandum to investigate accelerated flight search and travel-specific models after initial benchmarking; no production deployment or revenue contribution was disclosed.
October 2026: Boeing-Introduced Dataliner, an AI-enabled aircraft data intelligence platform for fleet-level maintenance and operational decision support.
June 2026: Rolls-Royce and Bombardier-Announced enhanced aircraft and engine health monitoring for Global 5500 and 6500 business jets using connected engine and aircraft data.
June 2026: EASA-Published Proposed Issue 03 of its AI Concept Paper for consultation, broadening the discussion to reinforcement learning, symbolic AI and advanced automation; not a final certification approval.
May 2026: Airbus and Mistral AI-Announced a partnership covering engineering, technical documentation and secure aerospace AI deployments, including on-premises options.
April 2026: Airbus Skywise and JetBlue-Announced a Skywise Fleet Performance+ agreement for JetBlue’s A320-family and A220 fleets to support aircraft condition monitoring and maintenance planning.
Market Outlook
Airline and aircraft-manufacturer spending is likely to concentrate on systems that can document a measurable improvement in dispatch reliability, maintenance planning or aircraft utilization. Fleet-health platforms may earn recurring revenue through per-aircraft subscriptions; airport applications often require longer integration projects across airlines, handlers and terminal systems. Vendors that standardize interfaces without obscuring local responsibility should be able to scale more effectively.
Generative AI will create more opportunities in maintenance document search, disruption communications and customer servicing, but certification-grade autonomous functions require a different assurance process. Europe’s evolving aviation AI guidance and comparable FAA work are likely to reinforce demand for traceability, testing and controlled releases. Commercial rollouts will therefore remain concentrated on human-supervised decisions while higher-risk functions advance through validation.