
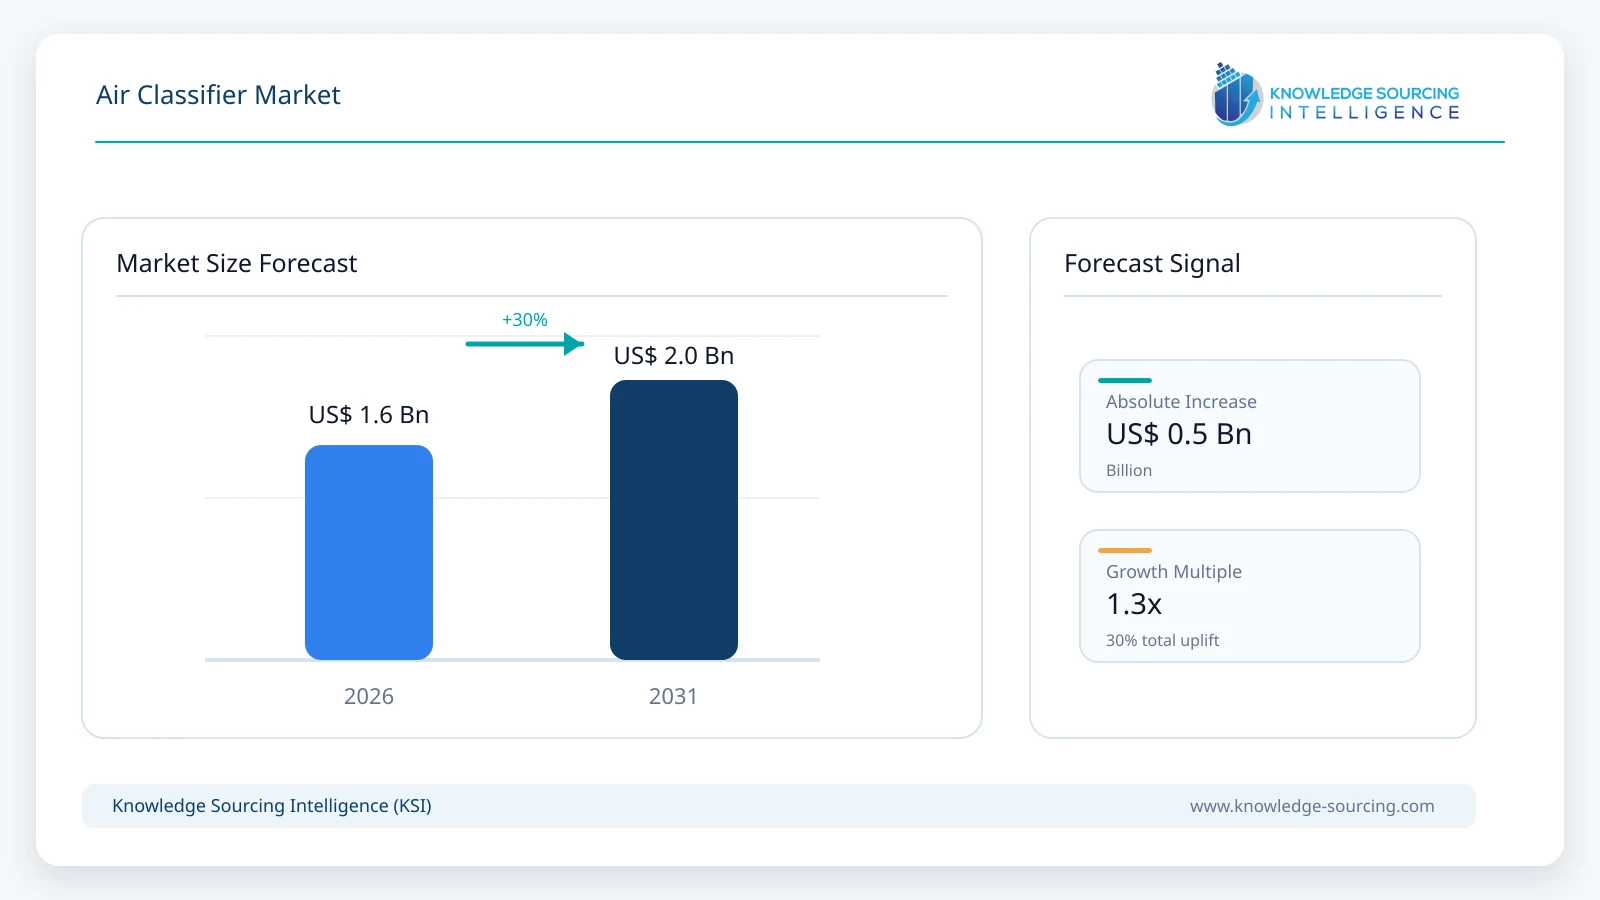
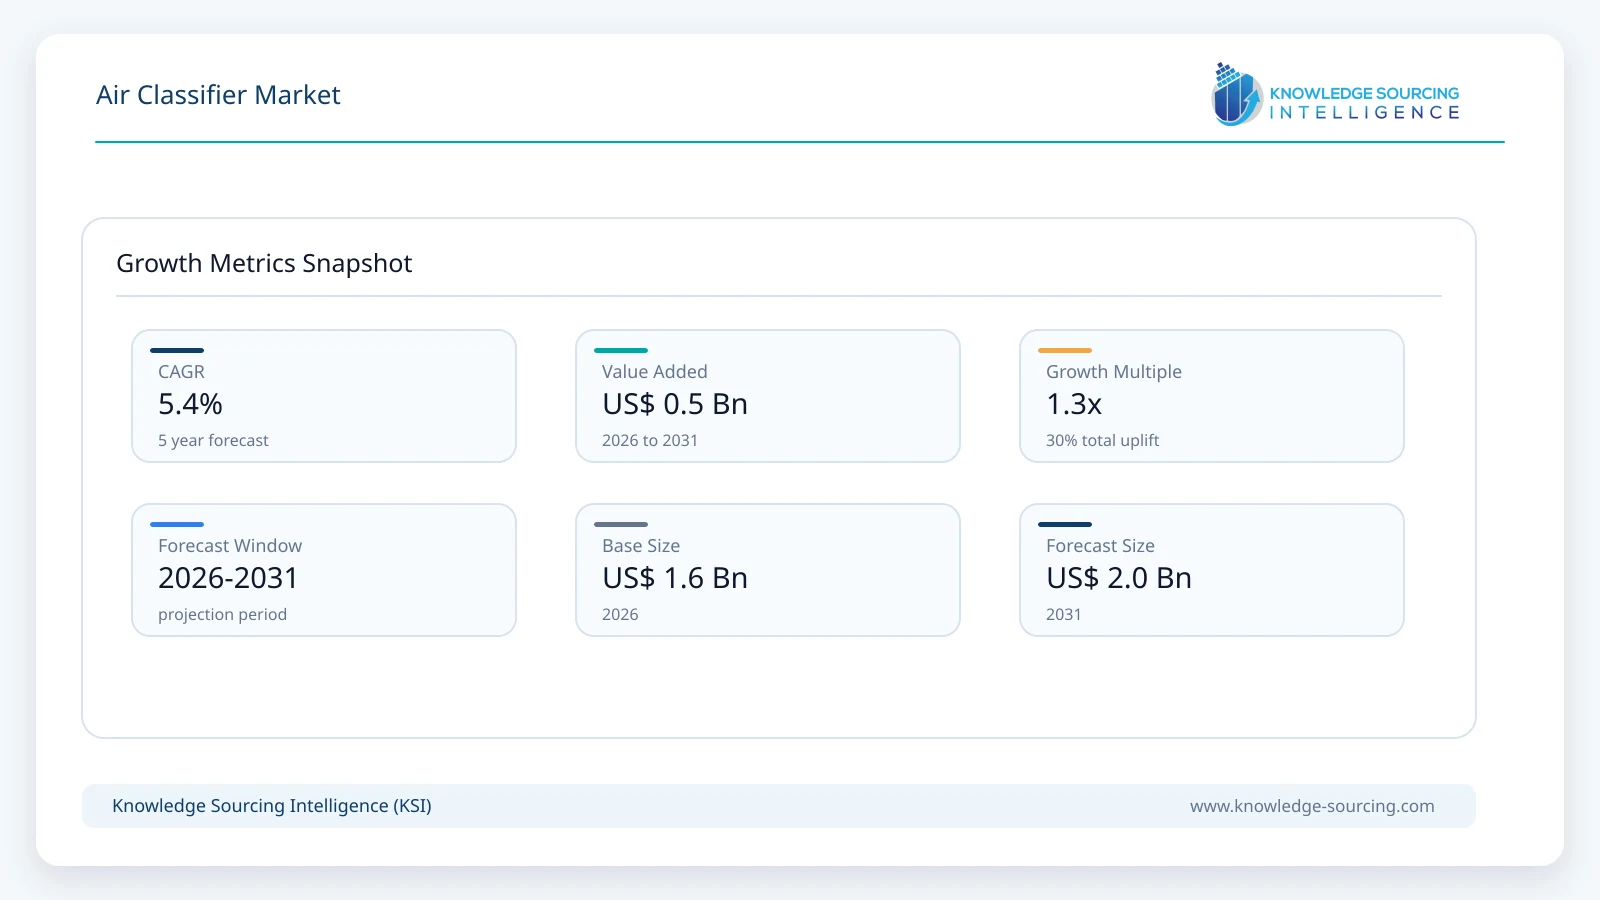
The Air Classifier Market is projected to grow from USD 1.562 billion in 2026 to USD 2.035 billion in 2031, at an annual growth rate of approximately 5.42% during the forecast period.
Highlights:
- 1Centrifugal classifiers occupy a central position in fine-powder processing because rotor speed and airflow provide a controllable particle-size cut.
- 2Mineral processing remains an important application, spanning calcium carbonate, silica, talc, clay, graphite and other industrial powders.
- 3Dry classification can eliminate a wet-washing step in selected aggregate and filler processes, although feed moisture and dust handling still govern feasibility.
- 4Food producers are testing dry fractionation for pulse proteins, where separation performance must preserve functionality and product safety.
- 5Wear protection, process trials and control of oversize carryover are important competitive factors, particularly for abrasive feed materials.
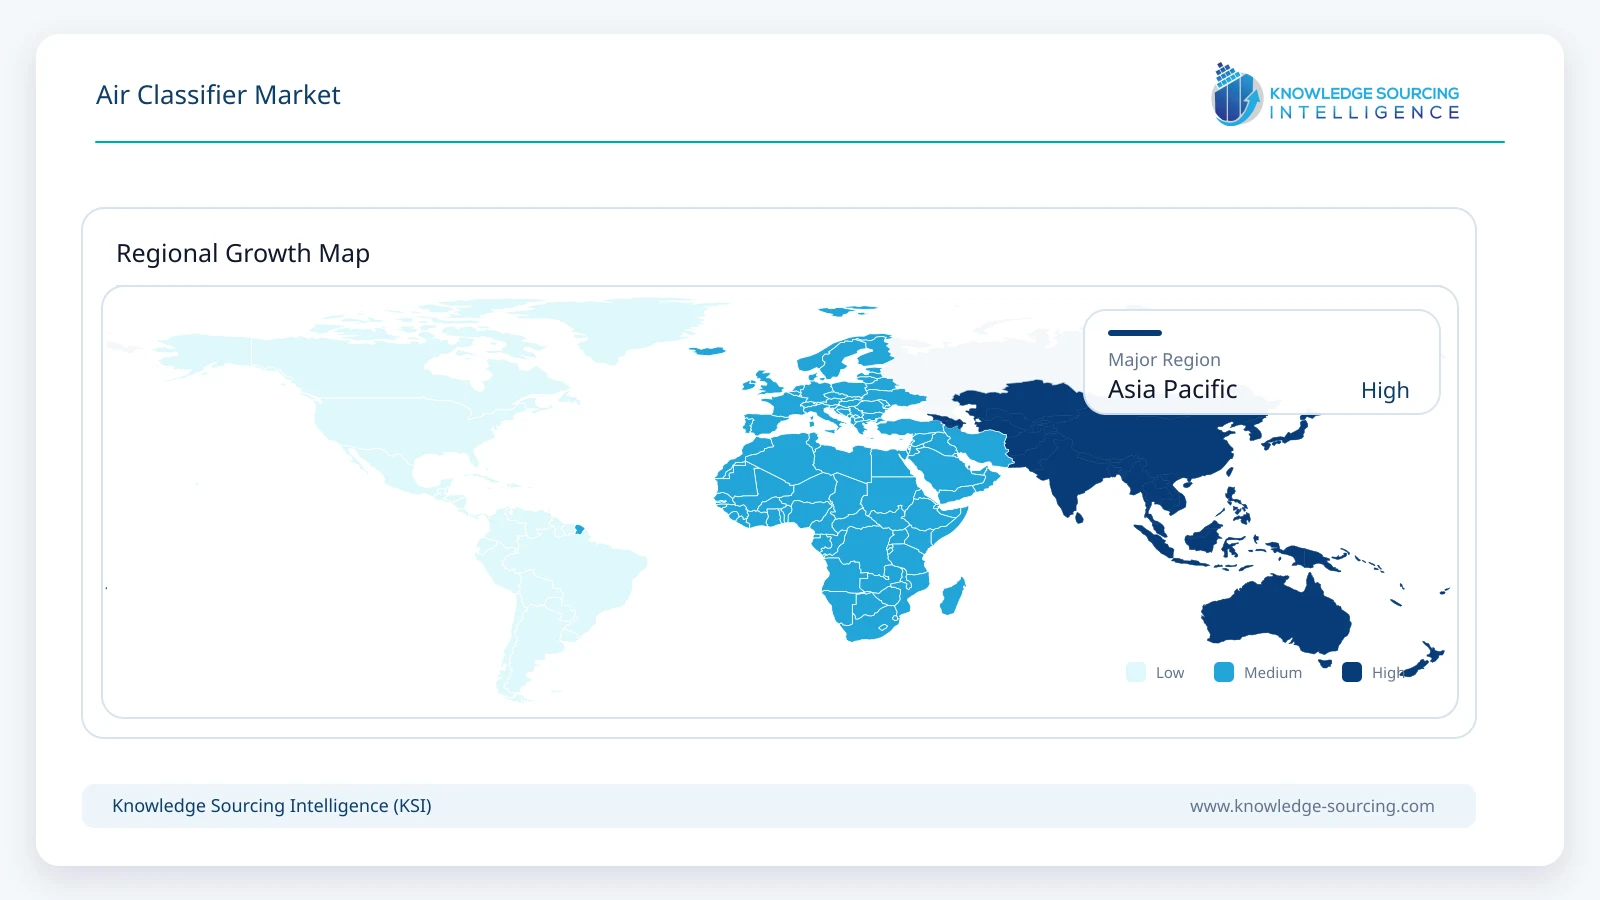
- 6Asia Pacific has a broad manufacturing and minerals customer base, while projects in the Middle East and Africa are adding interest in dry mineral upgrading.
Air classifiers separate dry particles through aerodynamic drag, gravitational settling, centrifugal force or a combination of these effects. The market includes purpose-built standalone separators, classifier assemblies and the classification function embodied in integrated classifier mills. Typical installations combine a feed and air-handling circuit with a selector, cyclones or filters, and controls for airflow or rotor speed. Although the process is frequently described as size separation, particle shape and density also affect the result, which makes laboratory trials important before a large plant orders equipment.
The market intersects several adjacent equipment categories without being identical to them. A classifier is not an ordinary sieve, a baghouse, an entire cement plant or a standalone grinding mill without air-based separation. Integrated classifier mills can be commercially relevant where the classifier is an essential part of the supplied package. Buyers also purchase spare classifier wheels, liners and technical services over the equipment lifecycle. The resulting industry combines specialist machinery companies and larger process-system integrators that sell classification as one function within a wider powder processing line.
Industrial air classification addresses a common operational problem: grinding creates a distribution of sizes, but downstream users frequently accept only part of that distribution. A pigment maker may reject a small coarse fraction that affects surface finish; a recycled mineral processor may need to reduce contamination by light material; a dry ingredient manufacturer can use particle size and density differences to enrich a fraction. Producers therefore value repeatable product cuts, not simply the nominal fineness shown in an equipment catalogue.
Manufacturer specifications illustrate the substantial diversity in the sector. Hosokawa Alpine markets its MZM/MZF zigzag classifiers for gravity separation at roughly 0.1–10 millimetres, whereas its ATP family handles much finer fractions. Sturtevant lists Whirlwind models for approximately 38–150 micrometres and SuperFine systems for still smaller cuts. Prater's MAC standalone classifier is described for protein and starch fractionation, while its classifier mills circulate oversize material back to a grinding chamber. These operating regimes are not interchangeable; configuration must be matched to the material's moisture, density, friability and abrasiveness.
Retrofit demand is also consequential. Mills and existing powder lines can be upgraded with a new selector, airflow arrangement or protective liner when the downstream specification tightens. These jobs are commercially different from greenfield installations: the customer must work within an existing duct layout, motor capacity and dust-collection system. Commissioning trials that establish recovery, energy use and particle-size consistency can be more persuasive than laboratory fineness figures in isolation.
Market Trends
Tighter Cuts for Industrial Mineral Fillers
Paints, sealants and engineered plastics place increasing emphasis on the particle-size distribution of calcium carbonate and other fillers. The commercial loss from coarse-particle contamination can exceed the value of an incremental tonne of powder. In April 2026, EPIC Powder described a Greek calcium carbonate installation using an MJW classifier mill for finer, more consistent material destined for coatings applications. Such projects favour independently adjustable classification and engineered recirculation over fixed, single-pass designs.
A purchaser seeking a higher-value filler grade must nevertheless account for lower fines recovery at a stricter cut point, greater fan demand and abrasion of separator internals. The credible equipment proposal therefore states both fineness and throughput, supported by a feed-specific trial. Those considerations shape maintenance contracts and aftermarket demand alongside initial machine orders.
Modular Pilot Systems Reduce Scale-Up Risk
Hosokawa Alpine's July 2026 addition of the UPZ 100 III module to its multi-processing concept shows how equipment builders are shortening the path from powder tests to plant selection. The module itself is a mill rather than a classifier, but its ability to share peripherals with classification equipment is commercially relevant. Buyers can compare processing routes before making commitments to different machines and line layouts.
This flexibility matters in pharmaceuticals, chemicals and emerging materials where feed behaviour is not fully predictable. Pilot trials reveal whether agglomerates must be dispersed, whether the powder is heat-sensitive and whether a single-stage classifier can achieve the specification. The plant contractor that can reproduce pilot results at commercial scale has an advantage over a supplier offering only equipment dimensions.
Separation of Light Fractions Creates Recycling Applications
An air classifier can separate light contaminants from dense or coarse material without relying entirely on water-based cleaning. In September 2026, Hosokawa Alpine reported that the University of Augsburg had commissioned an MZM/MZF zigzag classifier for research on ash, demolition materials, composite waste and photovoltaic-module fractions. Its millimetre-scale gravitational separation differs fundamentally from the micron-scale powder applications of high-speed rotor machines.
Recycling applications add variability that is often absent from a standardized mineral feed. Mixed particle shapes, dust, films and shifting contamination rates place greater demands on feed preparation. Commercial adoption depends on whether the recovered fractions achieve an acceptable purity and whether the waste handling costs offset the value recovered.
Dry Fractionation Gains Importance in Food Ingredients
Fine milling followed by air separation can concentrate protein-rich fractions in pulses and other plant materials. The equipment must separate starch and protein fractions without undermining colour, flavour or functional properties. Bühler and Hosokawa Alpine have collaborated on pulse processing; Bühler's 2026 training materials also describe air classification and compaction within dry protein fractionation workflows.
Food processors examine hygiene and changeover time as closely as throughput. Easy access to product-contact surfaces, low retained material and validation of cleaning are important for suppliers serving multiple recipes. Strong performance on a dry mineral trial does not establish suitability for an allergen-sensitive ingredient line.
Energy and Wear Costs Influence Retrofit Decisions
Every additional pass through a grinding and classification circuit adds mechanical and fan load. More precise separation can reduce unnecessary overgrinding, but high rotor speeds and restrictive filters can raise electricity use. Abrasive quartz, mineral fillers and recycled powders accelerate erosion of classifier wheels and duct bends. Suppliers are responding with replaceable liners, ceramic contact components and more flexible control of air movement.
The cost calculation varies by use case. In a high-volume aggregate installation, avoiding wet-washing and water treatment may justify the retrofit. For micron-scale chemical powders, higher yield and lower product rejection may be more important than energy savings alone. Equipment comparisons that ignore the full line tend to overstate what a classifier can deliver independently.
Air Classifier Market Segment Analysis
By Type
Centrifugal
Centrifugal classifiers are commercially important in fine-powder operations because rotating wheels impose a controllable separation force against a moving stream of air. Adjusting classifier speed shifts the cut point without physically exchanging a screen. Product families from Hosokawa Alpine, RSG and ALPA illustrate a market extending from laboratory units to high-throughput industrial configurations.
The rotating-wheel category represents approximately USD 1.016 billion in 2026 and could reach USD 1.363 billion in 2031, reflecting sustained demand for fine, adjustable separation. These values indicate the commercial weight of precise product grades rather than a universal replacement of gravity-driven equipment. In manufactured sand or coarse waste separation, a simpler gravitational system can be more economical when the required cut lies above the fine-powder range. That adjustability is especially useful where grade changes are frequent or final-powder tolerance is narrow. A classifier supplied for calcium carbonate cannot simply be transplanted into fine pharmaceuticals, however. Cleaning requirements, protective linings, dust explosibility and product contamination risks determine whether a machine's design is viable. Gravitational systems remain valuable for coarser and lighter fractions, including selected recycling flows.
By Application
Mineral Processing
Mineral processing is a major demand centre because physical upgrading can materially affect selling price. Producers classify limestone, talc, kaolin, silica and graphite to meet size and purity specifications for building products, coatings or industrial chemistry. In March 2026, EPIC Powder reported an MBS-3 installation processing quartz sand at a nominal six tonnes per hour with a targeted D97 of 75 micrometres. The example illustrates customer emphasis on stable oversize control, though vendor case-study results require independent acceptance testing.
On the forecast trajectory, mineral processing accounts for about USD 594 million in 2026 and may approach USD 794 million by 2031. The growth opportunity extends from throughput-intensive minerals to higher-value functional fillers, where a small improvement in upper-size control can support a different customer specification. Equipment orders nevertheless remain tied to the mineral producer’s processing route and the recoverable value of each classified fraction. Mineral projects are sensitive to feed mineralogy and abrasiveness. A classifier may preserve a high-value fine product, but it cannot remove every chemical impurity, and it does not substitute for flotation where mineral chemistry rather than aerodynamic behaviour defines the separation task. Engineering trials must therefore confirm attainable grades and rejected-material disposition.
By Industry Vertical
Building & Construction
Construction materials consume classified sands, fillers, limestone powders and certain recovered mineral streams. Product quality requirements differ by end use: manufactured sand needs control of excess fines, while coating fillers often require an upper particle-size limit in the micron range. Sturtevant's Whirlwind and Side Draft equipment illustrate the coarse-to-intermediate cuts considered by aggregate producers, while high-fineness classifier mills serve downstream filler applications.
Building and construction is estimated at approximately USD 547 million in 2026, advancing to USD 692 million by 2031. Aggregate producers seek dependable fine-content removal, while cementitious-material suppliers require controlled limestone and supplementary-cementitious-powder grades. The classification duty therefore varies between high-tonnage, relatively coarse separation and lower-volume filler processing, which prevents simple comparisons of average equipment prices across projects. Construction buyers place considerable weight on reliability and throughput during the production season. Space for a new classifier, available electrical capacity, dust-emission controls and access to wear parts often determine the selected configuration. Mining and specialty materials also remain major downstream markets, but their economic drivers differ from the plant-specific needs of construction aggregates.
Market Drivers
Higher Value from Precisely Graded Minerals
Premium mineral fillers often command a higher unit value when suppliers can assure a narrow particle distribution. Coarse fractions can impair surface finish in coatings or affect dispersion in polymer compounds. A classifier allows processors to recover an acceptable fines fraction and return oversize to a mill, rather than selling all output as a lower-grade bulk product. This provides a commercial rationale for plant upgrades even when mine output is flat. Equipment suppliers must substantiate yield, cut sharpness and maintenance requirements using feed-specific material tests.
The investment threshold differs sharply by end market. A paint-grade filler producer can price tighter distribution against rejected batches or premium product qualifications; a bulk limestone facility must justify the same equipment against tonnes handled and motor hours. For machinery suppliers, demonstrating both yield and customer-accepted D97 consistency is more persuasive than presenting an unusually fine laboratory cut without a recovery balance.
Growth in Dry Sand and Aggregate Processing
Quarries and building-material plants increasingly evaluate dry fines control where access to water, tailings management or permitted discharge is difficult. Sturtevant markets air classifiers to remove fine material from crushed stone and manufactured sand, potentially reducing reliance on wet screens and washing. The advantage varies with incoming moisture, clay content and the desired final grading. Where a dry process is technically suitable, avoided water-handling capital and reduced settling-pond requirements can support investment in air separation equipment.
Metso’s AC Series demonstrates how gravitational-inertial equipment can remove a selected fine fraction from manufactured sand using controlled primary and secondary airflow. The plant still needs suitable collection equipment and predictable feed conditioning. Where crushed rock contains large proportions of cohesive clay or excess moisture, the economics may favour washing or a combined process rather than dry classification alone. Application testing therefore precedes claims about water savings.
Expansion of Specialty Powder Manufacturing
Chemical, pigment, ceramics and battery-material producers often work to exact size and contamination limits. Some products require high-purity ceramic-lined contact surfaces; others need inert-gas circuits or temperature management. ALPA's catalogue includes fine classifiers for battery materials, chemicals and pharmaceutical powders, indicating the breadth of product engineering required. Demand rises when new formulations or process routes move from pilot scale to routine production. This is a specialized opportunity measured in validated applications rather than simple tonnes of feed processed.
A chemical producer may accept a higher capital cost to secure a consistent upper particle-size limit or avoid metallic contamination in sensitive powders. Hosokawa Alpine’s adjustable-wheel air-classifier families and NETZSCH’s dry classification offerings illustrate the breadth of available cut points. The market opportunity is often in specialized assemblies, suitable contact materials and reproducible changeovers, not merely adding more nominal capacity to an existing grinding circuit.
Pulse Protein and Dry Food Fractionation
Demand for ingredients derived from pulses and grains is supporting trials of grinding plus air classification. The process separates fractions with different particle sizes or densities and can reduce reliance on intensive water-based extraction for selected applications. However, protein recovery, flavour, food safety and plant utilisation determine whether the economics are workable. Bühler's training programme and Prater's established protein-fractionation equipment illustrate supplier interest. Commercial adoption favours firms able to demonstrate ingredient functionality, repeatable production and hygienic cleaning across batches.
Food applications require process guarantees that industrial mineral equipment does not automatically provide. Dry fractionation may reduce the volume of water required for some protein enrichment routes, but protein yield, starch carryover, flavour and retained allergenic residue must be measured together. A classifier manufacturer able to deliver hygienic access, documented cleanability and stable product temperature can command more value than a conventional coarse separator even at lower throughput.
Installed-Base Modernisation and Aftermarket Service
Existing mills and separators create recurring demand for classifier wheels, liners, controls and specialist commissioning. A retrofit may correct persistent oversize, allow a tighter product grade or recover capacity lost to worn internals without replacing the full process line. RSG and Classifier Milling Systems offer equipment and support relevant to such projects. The financial case can be attractive where operators already own fans, collection systems and foundations, but controls integration and process shutdown requirements must be carefully evaluated before procurement.
Plant owners often prefer replacement classifier wheels, ceramic linings or adjustable airflow controls to a complete new milling line. Such projects can be commissioned around shorter shutdowns, but performance depends on the existing fan curve, duct pressure losses and dust-collector capacity. Suppliers with material-testing laboratories and service engineers can capture follow-on business through troubleshooting and graded upgrades, especially when a downstream buyer tightens a long-established powder specification.
Market Restraints
Material Moisture and Feed Variability
Air separation becomes less predictable when material arrives with elevated or fluctuating moisture. Fine particles can agglomerate, making the observed aerodynamic cut different from a dry laboratory result. Clay-rich sand, sticky chemical solids and moist feed ingredients may need drying or conditioning before classification. These preparatory steps increase both operating cost and plant complexity. A separator bought against an ideal feed specification can underperform when deployed on a variable production stream, limiting returns for smaller operators without feed-quality controls.
Operational acceptance should therefore include feed samples drawn from different seasons and stockpile locations. A separation guaranteed on a dry laboratory batch may not hold after rain, variable quarry blending or humid production conditions. Additional dryers, flow conditioning or upstream screening can restore performance, but they raise the capital burden and alter energy calculations. This sensitivity discourages standardised procurement based only on catalogue cut points.
Energy Use and Dust-Collection Requirements
The classifier wheel is only part of the power demand. Fans, filters, pneumatic conveying and oversize recirculation can materially influence electricity consumption and pressure losses. Dust emissions must also be controlled in accordance with local rules and, for combustible powders, a suitable explosion-protection scheme. The operating cost can therefore rise sharply as cut sizes tighten. Buyers who compare separator-drive ratings without modelling the whole air circuit may encounter higher costs than the initial capital proposal suggests.
An accurate assessment must include the entire circuit: mill load, classifier rotor, conveying fan, cyclone losses and filter replacement. Finer classification can reduce overgrinding in a closed loop, yet a smaller cut point may demand more recirculation. Air-emissions permits and combustible-dust controls can also dictate enclosure, ventilation and explosion protection. These requirements can materially change lifecycle cost even when the classifier itself appears mechanically simple.
Wear in Abrasive Mineral Applications
Quartz, high-silica sand and other hard mineral feeds erode classifier internals, ducts and bends. Wear can gradually alter the separation geometry and introduce contamination, with downtime required to replace wheels or protective liners. Ceramic and hard-faced components may reduce replacement frequency but increase the acquisition cost. Manufacturers must balance fineness and service life for each material. Where the throughput is high but the product margin is low, replacement-part costs can narrow the commercial case for sophisticated separation equipment.
The rate of wear depends on particle velocity, angle of impact and mineral hardness as well as the selected internal lining. A worn selector can alter product distribution before operators notice obvious mechanical damage. Predictable inspections, replaceable ceramic surfaces and availability of spare assemblies therefore belong in the purchase specification. Long-distance service support is particularly important at mines and remote filler plants where an unplanned outage also disrupts downstream deliveries.
Qualification Costs for Food and Pharmaceutical Lines
Process equipment used for food ingredients or regulated pharmaceutical powders must satisfy stricter expectations on cleanability, product traceability and safe containment. Multiple ingredients on one line create cross-contamination risks, while operator access and design dead spots complicate cleaning validation. Commercial purchases may consequently depend on documentation, factory acceptance testing and qualification support rather than solely on particle-size performance. These requirements raise the cost of entry for equipment manufacturers whose experience is concentrated in minerals or aggregates.
Documentation, material traceability and access for cleaning are crucial where several products share the same classifier or mill. A supplier may need to demonstrate acceptable residue after disassembly, limit heat rise and avoid introducing new contact-surface risks. For pharmaceutical ingredients, plant validation and dust containment can be more expensive than the separating module. This narrows the addressable pool for low-price general-purpose machines and favours specialist process-engineering providers.
Capital Cyclicality in Mining and Construction
An air classifier is frequently purchased as part of a larger process expansion rather than as a recurring consumable. Mine investment, construction-material demand and plant financing therefore influence order timing. Operators can defer replacement when utilization is weak, even if a better separator would improve process efficiency. International machinery sales also face freight, engineering and site-installation costs. These factors create uneven order intake and make continuous annual expansion less certain than a multiyear forecast might suggest.
Demand also arrives in uneven project batches. A mine expansion may order several classifiers with the rest of a process train, then produce limited new-equipment revenue for years. Replacement parts and smaller retrofits provide some resilience, but they cannot fully offset delayed greenfield spending. Suppliers exposed to both bulk minerals and food, chemicals or recycling may be better placed to manage those cycles than companies dependent on one regional construction market.
Regional Outlook
Asia Pacific
Asia Pacific represents the largest regional opportunity in the current outlook, at approximately USD 625 million in 2026 and USD 834 million by 2031, an implied annual increase of about 6.0%. China combines mineral upgrading, construction-material capacity and extensive domestic powder-equipment manufacturing, while India contributes demand from limestone, chemicals, fillers and new mineral-processing investments. Japan and South Korea support more specialised powders where cleanliness, narrow distributions and documented process performance are central purchasing requirements.
The regional mix is not uniform: coarse sand classifiers may operate at very high tonnage, whereas specialist plants buy fine rotor systems for pigments, fillers or food ingredients. EPIC Powder’s 2026 quartz and calcium-carbonate examples indicate active equipment selection around a specified product grade, although supplier-reported savings are not independent industry averages. Buyers will continue to value application trials, locally available wear parts and engineering support capable of handling abrasive, variable feeds.
Middle East and Africa
From a smaller baseline, the Middle East and Africa could increase from roughly USD 109 million in 2026 to USD 193 million in 2031, equivalent to approximately 12.1% annual growth. Mineral beneficiation, limestone processing and cement-related materials are prominent opportunities. In water-constrained locations, dry separation has a practical advantage when feed conditions permit it, although capital projects must still fund efficient dust collection and spare-parts access.
The faster percentage growth chiefly reflects a smaller starting equipment base and a limited number of prospective mineral and construction-material projects. Classifier orders in the region can be highly sensitive to an individual mine or process-plant decision, making annual sales less even than in established Asian and European markets. Customers may need suppliers to design the complete air circuit, including feed handling and collection, instead of furnishing only the separating chamber.
Competitive Landscape
The market combines established powder-engineering groups and independent classifier specialists. Hosokawa Alpine supplies stand-alone centrifugal and zigzag units alongside integrated mills; NETZSCH offers fine-grinding and classification systems. Sturtevant and Bradley Pulverizer address industrial-mineral and aggregate applications, while Prater and Classifier Milling Systems compete in integrated milling and fine-powder processing. RSG operates in high-precision mineral classification; ALPA and EPIC Powder sell wide classifier ranges into price-sensitive and high-throughput markets. Atritor is active in classifying mills. Bühler participates through plant-processing integration and dry-fractionation partnerships rather than the same product mix as a dedicated separator manufacturer.
Competitive differentiation often emerges after a test run rather than during a catalogue review. Throughput at a specified cut point, rotor or liner life, spare-part logistics and the ability to engineer a complete air circuit determine whether a machine is acceptable to the buyer. Supplier performance in food or pharma also depends on documented cleanability and process support. A headline market share comparison would not capture these application-specific advantages without equivalent definitions of standalone classifiers and bundled milling systems.
Recent Developments
September 2026: Hosokawa Alpine
Augsburg University's materials-resource institute commissioned the company's MZM/MZF zigzag classifier to support work on ash, construction waste, composites and related recovery streams. The installation demonstrates research demand for coarse and density-based air separation.
July 2026: Hosokawa Alpine
The UPZ 100 III fine-impact-mill module joined Alpine's multi-processing platform. It expands interchangeable pilot processing options and supports trials of grinding configurations used alongside classifier modules; the announcement was not a stand-alone classifier launch.
April 2026: EPIC Powder
A Greek calcium carbonate installation using an MJW air classifier mill was documented for higher-grade filler powder. The supplier reported improvements in product-size consistency and plant economics; results are site-specific rather than independent market-wide measurements.
May 2026: EPIC Powder
The manufacturer published an Indian carbon-black processing example using an air-classifier-mill arrangement targeting a fine powder specification. The development points to process-engineering demand from industrial carbon applications, with outcome figures presented by the supplier.
March 2026: EPIC Powder
A quartz-sand case described an MBS-3 air classifier operating toward a D97 of 75 micrometres at about six tonnes per hour. The case illustrates the importance of abrasive-feed wear resistance and stable cut size.
September 2025: Hosokawa Alpine
The company introduced the Alpine Dual Mill ADM classifier mill, combining features of ACM and ZPS platforms for chemical and food applications. Multiple classifier wheel geometries allow users to target different fineness requirements.
Market Outlook
Through 2031, purchase decisions should increasingly hinge on demonstrated separation economics: quantity of on-specification product recovered per unit of energy, ability to hold the particle-size cut as feed changes and cost of maintaining the machine over its life. Mineral fillers, dry construction materials and specialty powders supply different demand streams, reducing reliance on any one end market. Integrated classifier mills will win orders where grinding and separation are best engineered together, while stand-alone gravity and centrifugal classifiers will retain value in existing process circuits.
The pace of adoption is likely to remain project-led. Producers facing higher quality requirements can justify upgrades quickly; buyers operating at low utilisation or processing unstable wet feed may defer them. Suppliers with credible pilot testing, local service and clear performance guarantees are positioned to capture the higher-value portion of equipment demand.
Air Classifier Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.562 billion |
| Total Market Size in 2031 | USD 2.035 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.42% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Industry Vertical, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Gravitational
Centrifugal
Others
By Application
Mineral Processing
Sand Manufacturing
Material Processing
Others
By Industry Vertical
Building & Construction
Mining
Food & Beverage
Pharmaceuticals
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Higher Value from Precisely Graded Minerals
3.1.2. Growth in Dry Sand and Aggregate Processing
3.1.3. Expansion of Specialty Powder Manufacturing
3.1.4. Pulse Protein and Dry Food Fractionation
3.1.5. Installed-Base Modernisation and Aftermarket Service
3.2. Market Restraints
3.2.1. Material Moisture and Feed Variability
3.2.2. Energy Use and Dust-Collection Requirements
3.2.3. Wear in Abrasive Mineral Applications
3.2.4. Qualification Costs for Food and Pharmaceutical Lines
3.2.5. Capital Cyclicality in Mining and Construction
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Separation Mechanisms and Cut-Point Control
4.2. Rotor, Wheel and Wear-Liner Designs
4.3. Grinding and Classification Integration
4.4. Process Automation and Dust Control
5. AIR CLASSIFIER MARKET BY TYPE
5.1. Gravitational
5.2. Centrifugal
5.3. Others
6. AIR CLASSIFIER MARKET BY APPLICATION
6.1. Mineral Processing
6.2. Sand Manufacturing
6.3. Material Processing
6.4. Others
7. AIR CLASSIFIER MARKET BY INDUSTRY VERTICAL
7.1. Building & Construction
7.2. Mining
7.3. Food & Beverage
7.4. Pharmaceuticals
7.5. Others
8. AIR CLASSIFIER MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. Israel
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Australia
8.5.6. Indonesia
8.5.7. Thailand
8.5.8. Taiwan
8.5.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions and Agreements
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Hosokawa Alpine AG (Hosokawa Micron Group)
10.2. NETZSCH Grinding & Dispersing
10.3. Sturtevant, Inc.
10.4. Prater Industries
10.5. RSG Inc.
10.6. Bradley Pulverizer Company
10.7. Qingdao EPIC Powder Machinery Co., Ltd.
10.8. ALPA Powder Technology
10.9. Classifier Milling Systems (CMS)
10.10. Atritor Limited
10.11. Bühler Group
10.12. Metso Corporation (air classification equipment)
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected Air Classifier Market size by 2031?
The Air Classifier Market is projected to reach USD 2.035 billion by 2031.
What is the Air Classifier Market's annual growth rate?
The Air Classifier Market is projected to grow at approximately 5.42% CAGR until 2031.
Which Air Classifier type is central for fine-powder processing?
Centrifugal classifiers occupy a central position in fine-powder processing.
What is a major application for air classifiers?
Mineral processing remains an important application area.
Which geographic region shows a broad customer base?
Asia Pacific has a broad manufacturing and minerals customer base.
What is a key opportunity for air classifier adoption?
Dry classification can eliminate wet-washing steps, offering opportunity.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Air Classifier Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/air-classifier-market