
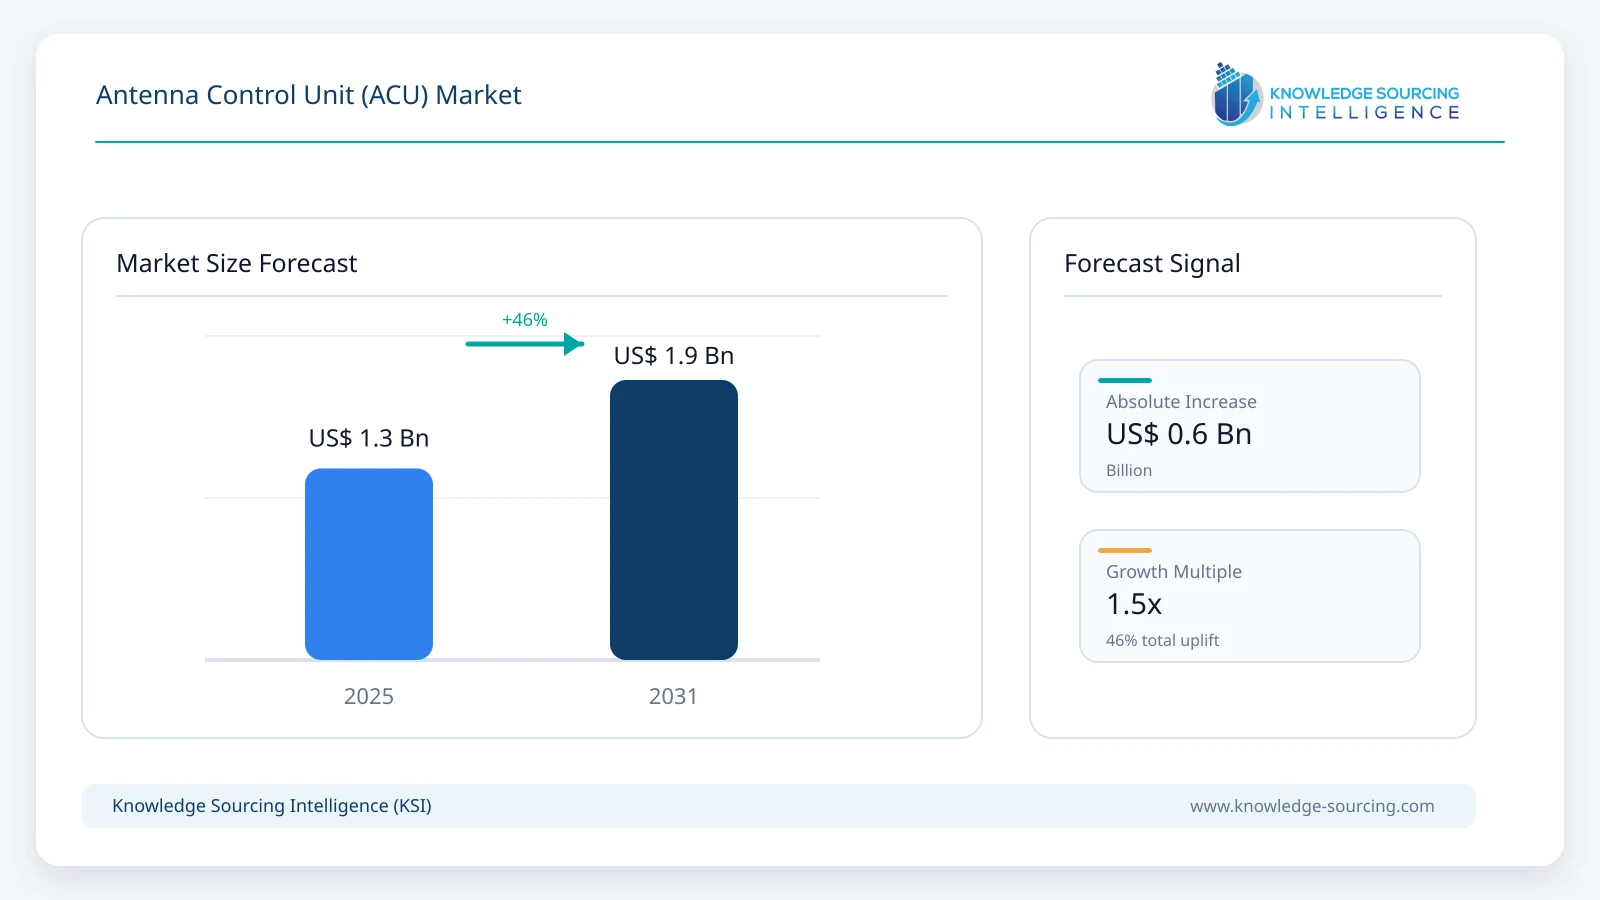
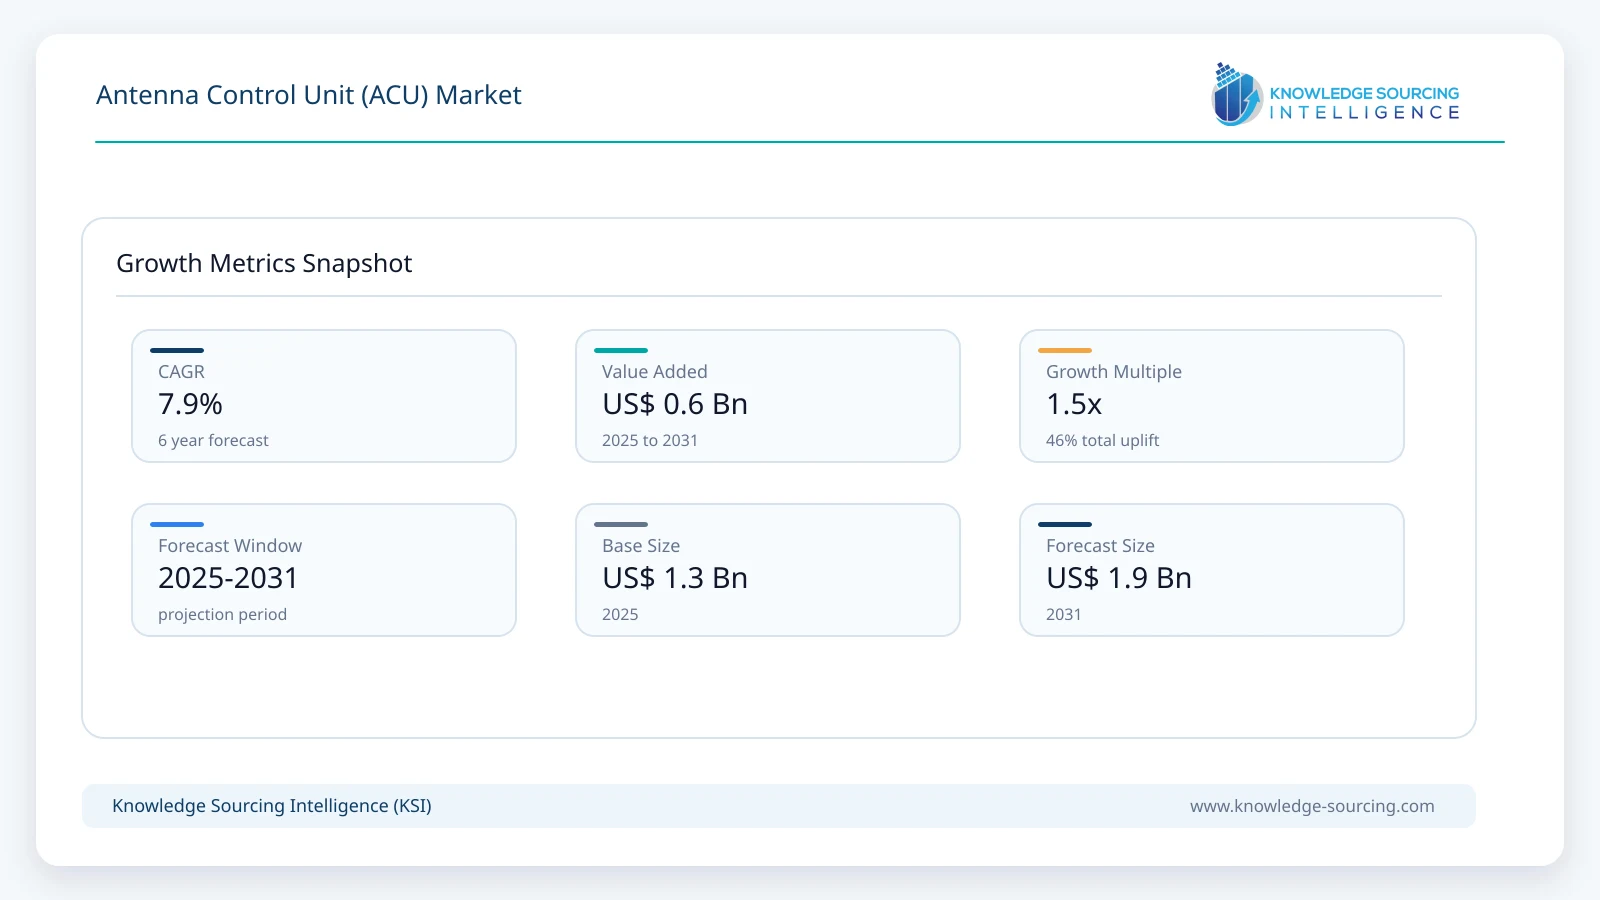
The Antenna Control Unit (ACU) Market is forecast to grow at a CAGR of 7.9%, reaching USD 1.93 billion in 2031 from USD 1.32 billion in 2026.
Highlights:
- 1The Antenna Control Unit market is expanding at a CAGR of 7.9%, reaching USD 1.93 billion by 2031, driven by multi-orbit satellite networks and automated tracking demands.
- 2Defense applications are capturing approximately a 40% share while commercial SATCOM and mobility segments are steadily gaining traction through resilient connectivity needs.
- 3North America is holding the leading regional share near 35%, as defense modernization and commercial space programs continue strengthening antenna control requirements.
- 4Multi-orbit architectures are increasingly requiring continuous tracking precision, software integration, and automated switching across LEO, MEO, and GEO environments.
- 5Electronically steered and software-defined ACU solutions are advancing rapidly, supporting real-time beam pointing and lifecycle automation in dynamic operations.
- 6Maritime and aviation connectivity is driving rising demand for stabilized, high-performance antenna control systems under mobile and adverse conditions.
Key Highlights
Market Overview
Demand for Antenna Control Units is increasingly being shaped by the transition toward multi-orbit satellite networks, software-defined ground infrastructure, automated antenna operations, and higher-performance communications rather than by conventional equipment replacement alone. Recent developments from the European Space Agency (ESA), U.S. Space Force, and satellite technology providers demonstrate that ground systems are being designed to support increasingly dynamic satellite environments spanning LEO, MEO, and GEO. ESA’s ongoing projects emphasize integrated ground infrastructure, multi-orbit connectivity, network orchestration, automation, and cybersecurity, increasing the importance of sophisticated antenna-control capabilities that can manage tracking and communications across changing mission conditions.
Defense and government applications remain important demand areas because secure and resilient SATCOM increasingly depends on the ability to maintain reliable links in contested and operationally demanding environments. In August 2025, the U.S. Space Force’s Space Systems Command demonstrated Protected Tactical Waveform SATCOM using five PTW-enabled terminals, including frequency hopping under variable interference conditions and secure communications capabilities. Such requirements reinforce the need for ground and terminal infrastructure capable of precise, responsive, and dependable antenna operations.
At the same time, the expansion of LEO and multi-orbit connectivity is creating new requirements for automated tracking and flexible antenna infrastructure. In May 2025, the Space Systems Command selected companies to develop the Joint Antenna Marketplace, a secure cloud-based platform designed to connect satellite operations centres with commercial and government-owned antennas and dynamically schedule satellite contacts and data-transport workloads. In May 2026, SSC highlighted the challenge of communicating with thousands of satellites using a limited number of ground antennas, positioning dynamic antenna access and scheduling as an important element of future satellite operations.
Technology development is also moving toward electronically steered and highly automated antenna architectures. ESA’s Ka-Q-EPA project places an Antenna Control Unit at the centre of antenna operation, where it manages panel coordination, beam pointing and real-time satellite tracking for dynamic airborne environments. The project’s technology phase runs from 2025 through 2026, illustrating the continuing development of advanced control technologies for electronically steered antennas.
Commercial investment further demonstrates the expanding requirement for advanced tracking and ground infrastructure. In August 2026, Kratos announced multi-million-dollar orders for Orbit’s GAIA 100 tri-band ground-station systems, including advanced Ka-band tracking and support for LEO, MEO and GEO missions. In February 2026, Gilat announced an order exceeding $10 million to support ground-infrastructure deployment for a leading LEO constellation, while July 2026 orders exceeding $20 million from a global satellite operator covered advanced ground-segment systems, network management and multi-orbit connectivity.
Purchasing priorities are therefore extending beyond basic mechanical positioning. Operators increasingly value tracking precision, multi-orbit compatibility, electronically assisted beam steering, software integration, automation, interoperability, network management, cybersecurity and lifecycle support. Industry developments also point toward greater digitization of ground infrastructure, with Comtech highlighting standardized digital interfaces, software-defined reconfiguration and automated resource management as important components of next-generation satellite ground systems.
The market opportunity consequently spans defense SATCOM, satellite ground stations, Earth-observation missions, maritime and aviation connectivity, commercial satellite networks, and emerging non-terrestrial network infrastructure. Recent developments from Kratos, Gilat, ESA and the U.S. Space Force indicate that antenna systems are increasingly being integrated into broader software-enabled and multi-orbit architectures rather than operating as isolated hardware components. This shift is expected to keep ACU technology central to accurate satellite tracking, automated operations, resilient communications and scalable ground-network management through the forecast period.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Multi-orbit SATCOM adoption | Expansion of GEO, MEO and LEO networks | Requires ACUs capable of continuous multi-orbit tracking. |
Defense communications investment | Continued government SATCOM modernization (2025-2026) | Supports procurement of ruggedized antenna control systems. |
ESA space activity | ESA Annual Report 2024 | Ongoing European space programs sustain demand for mission communication infrastructure. |
Company investment | Viasat expanding defense and space communications activities | Commercial and government programs increase demand for integrated antenna control technologies. |
Market Drivers
Migration toward multi-orbit satellite communication architectures. Operators increasingly deploy hybrid GEO, MEO, and LEO satellite networks to improve coverage, resilience, and network capacity. Unlike conventional GEO systems, these architectures require antenna control units capable of continuous satellite acquisition, automatic switching, and highly accurate tracking. Commercial airlines, maritime operators, military users, and enterprise communication providers increasingly procure terminals supporting multiple orbital layers, encouraging suppliers to integrate advanced control algorithms and higher-performance motion systems into ACU platforms.
Defense communication modernization and resilient tactical connectivity. Military organizations continue replacing legacy satellite communication infrastructure with platforms capable of supporting secure, mobile, and resilient communications. Modern defense operations increasingly depend on uninterrupted satellite links across land, naval, airborne, and expeditionary platforms, requiring highly reliable antenna stabilization and pointing systems. Company disclosures indicate continued investment in tactical networking, mission systems, government SATCOM, and protected communications, while defense-oriented suppliers continue expanding ruggedized terminal portfolios supporting NATO and allied requirements.
Growth in mobile satellite communication across maritime and aviation sectors. Commercial vessels, offshore operations, government fleets, airlines, and emergency response organizations increasingly rely on continuous broadband connectivity. Maintaining reliable communication during vessel movement, aircraft maneuvers, and adverse environmental conditions requires antenna control systems capable of rapid stabilization and automatic tracking. Satellite communication providers continue expanding managed connectivity services, while equipment manufacturers are introducing integrated antenna platforms designed for higher operational reliability and simplified fleet management.
Software integration and automation becoming procurement priorities. Buyers increasingly evaluate complete control architectures rather than individual hardware components. Automatic calibration, remote diagnostics, predictive maintenance, software updates, cybersecurity, and compatibility with network management systems have become important purchasing criteria because they reduce operational downtime and maintenance costs. Suppliers therefore continue investing in software-defined control platforms that improve lifecycle support while allowing customers to upgrade communication capabilities without replacing entire antenna systems.
Market Restraints and Challenges
Lengthy qualification and certification requirements. Defense, aerospace, and space communication customers require extensive validation before antenna control units enter operational service. Environmental testing, electromagnetic compatibility assessments, vibration qualification, software verification, and cybersecurity certification extend procurement schedules and increase development costs. These requirements create high entry barriers for smaller suppliers while limiting the speed at which new technologies reach operational deployment, particularly for military and spaceborne applications.
Dependence on specialized electronic and electromechanical components. Precision motion controllers, servo systems, inertial sensors, processors, radio-frequency interfaces, and other specialized components remain essential for high-performance antenna control units. Several satellite communication suppliers continue identifying supply-chain resilience and component availability as operational priorities, particularly for government programs requiring long product lifecycles. Component shortages or supplier concentration can extend manufacturing lead times, delay contract execution, and increase inventory costs across the value chain.
Integration complexity across heterogeneous communication systems. Modern communication networks frequently combine multiple satellite constellations, terrestrial networks, legacy infrastructure, and software-defined networking platforms. Antenna control units must therefore support numerous communication protocols, interfaces, positioning systems, and cybersecurity requirements while maintaining reliable performance. System integrators often face additional engineering effort during deployment, particularly when upgrading older infrastructure that was not originally designed for multi-orbit satellite operations. This increases implementation cost and lengthens customer acceptance timelines.
Cybersecurity requirements for satellite communication infrastructure. Satellite communication networks increasingly support defense operations, critical infrastructure, transportation, and emergency response. As network complexity expands, antenna control systems become part of broader cyber-resilient communication architectures. Operators therefore require secure software updates, authentication mechanisms, encrypted communications, and protection against spoofing or unauthorized access. Meeting evolving cybersecurity requirements increases development effort, testing obligations, and lifecycle support costs for ACU manufacturers while strengthening barriers to entry for new suppliers.
Major Segment Analysis
Defense and Military Application
Defense and military applications represent the most commercially important demand category for antenna control units because operational communications increasingly depend on uninterrupted satellite connectivity across fixed installations, mobile command posts, aircraft, naval vessels, and tactical ground vehicles. Military users prioritize pointing accuracy, stabilization under dynamic conditions, resistance to electronic interference, cybersecurity, and interoperability with multiple satellite networks. Procurement decisions also consider long service life, environmental durability, software support, and compliance with military communication standards. NATO members and several Indo-Pacific countries continue expanding satellite-enabled command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) capabilities, sustaining demand for advanced antenna control technologies.
Competition within this segment extends beyond hardware performance. Suppliers increasingly differentiate their offerings through integrated software, remote diagnostics, automated calibration, and lifecycle support that reduce operational downtime. Defense customers generally award long-term programs after extensive qualification, creating relatively high switching costs once systems enter service. Commercial SATCOM applications continue to expand, but defense procurement remains a critical source of recurring revenue because modernization programs typically include maintenance, upgrades, software support, and integration services throughout the equipment lifecycle.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Defense SATCOM modernization, commercial satellite investment, space programs | Lengthy defense procurement and certification |
Europe | Space missions, defense cooperation, secure communications | Fragmented procurement across national programs |
Asia Pacific | Satellite manufacturing, defense modernization, expanding commercial connectivity | Dependence on imported high-end electronic components |
Middle East and Africa | Military communications, border security, maritime connectivity | Budget variability and project implementation timelines |
North America
The United States remains the largest source of demand owing to sustained investment in military satellite communications, commercial satellite services, and civil space activities. The U.S. Department of Defense continues expanding resilient satellite communication capabilities, while NASA and commercial launch providers support a growing ecosystem of ground stations and mission control infrastructure. Canada also contributes through defense modernization and Arctic communication requirements. Buyers emphasize cybersecurity, interoperability, and lifecycle support, encouraging suppliers to develop integrated software-centric control platforms.
Europe
European demand is supported by coordinated investment in secure communications, Earth observation, navigation, and scientific missions. Programs managed through the European Space Agency, together with national defense modernization initiatives, continue generating demand for reliable antenna control systems. Manufacturers increasingly emphasize compliance with European standards, software interoperability, and long-term service capability. Procurement remains relatively distributed across member states, resulting in diverse technical specifications and qualification requirements.
Asia Pacific
Government-backed satellite programs, expanding defense budgets, and commercial satellite communication services continue supporting demand across China, Japan, India, South Korea, and Taiwan. Regional manufacturers are increasing domestic production capabilities while governments invest in indigenous satellite infrastructure and space technologies. Commercial maritime activity, aviation connectivity, and disaster management applications further expand procurement opportunities. However, high-performance motion control components and specialized electronics remain partially dependent on international supply chains.
Middle East and Africa
Defense modernization, maritime surveillance, offshore energy operations, and secure government communications remain the principal demand drivers. Gulf countries continue investing in satellite-enabled command systems and critical infrastructure resilience. Maritime communication requirements also support procurement for commercial shipping and offshore operations. Adoption varies across African markets because investment levels depend on national communications infrastructure, public-sector funding, and long-term defense procurement priorities.
Competitive Landscape
The Antenna Control Unit market exhibits characteristics of a technology-driven and qualification-intensive industry where product reliability, software capability, certification experience, and long-term customer support often outweigh price competition. Companies including Viasat Inc., Cobham Limited, CPI Satcom & Antenna Technologies, Kongsberg Defence & Aerospace, L3Harris Technologies, Indra Sistemas S.A., Honeywell Aerospace, Orbit Communication Systems Ltd., RTX Corporation (Raytheon), ST Engineering iDirect, Antech Space S.r.l., Radeus Labs Inc., and Savronik Elektronik compete across defense, commercial SATCOM, aerospace, and maritime communication programs.
Competitive differentiation increasingly depends on integrated antenna systems, software-defined control architectures, cybersecurity capability, precision tracking performance, and lifecycle service offerings. Several suppliers continue expanding partnerships with satellite operators, defense integrators, and government agencies to strengthen program participation. Long qualification cycles and demanding customer certification requirements create substantial barriers to entry, while established supplier relationships and extensive installed bases contribute to recurring upgrade and maintenance revenue.
Recent Developments
June 2026: Viasat secured a U.S. Space Force Protected Tactical SATCOM-Global production contract for dual-band military satellite systems. The program strengthens demand for advanced antenna control units supporting secure pointing, tracking, beam management, and resilient ground infrastructure.
March 2026: Intellian introduced new satellite antenna technologies and gateway solutions at Satellite 2026, showcasing innovations supporting electronically controlled tracking, multi-orbit communications, and advanced antenna control architectures for commercial and government SATCOM applications.
March 2026: Kymeta introduced the KuKa 8-Series multi-band terminal, featuring a simultaneous Ku/Ka electronically steered antenna supporting multi-orbit connectivity. The platform advances compact antenna control technologies for defense, mobility, and government SATCOM applications.
March 2026: Orbit Communication Systems unveiled the OrBeam MIL electronically steerable antenna at Satellite DC 2025. The phased-array solution enables seamless LEO, MEO, and GEO connectivity while enhancing antenna pointing accuracy and autonomous control performance.
February 2025: Holkirk Communications developed an M & C Common Interface Platform, Antenna Interface Module, for use in the Land Terminal range. It offers mobile command and control for ensuring efficient antenna positioning, BUC monitoring, multiple satellite locations, and inclined orbit tracking across C, X, Ku, and Ka-Band frequencies, for systems from 60cm up to 2.5M.
Regulatory and Policy Environment
Defense procurement regulations, spectrum management rules, cybersecurity requirements, export controls, and satellite communication standards collectively shape market participation. Military customers generally require compliance with stringent environmental, electromagnetic compatibility, and information assurance standards before antenna control units are approved for operational deployment. These requirements increase development costs but also strengthen confidence in long-term system reliability.
Commercial applications are influenced by national telecommunications regulators and international spectrum coordination frameworks administered through the International Telecommunication Union (ITU). Space missions must additionally comply with national launch regulations, satellite licensing frameworks, and mission assurance requirements established by civil space agencies. Export controls applicable to sensitive communication technologies continue influencing cross-border technology transfer, supplier selection, and manufacturing localization strategies.
Outlook and Strategic Implications
Demand during the 2026–2031 forecast period is expected to remain closely linked to defense communication modernization, expansion of multi-orbit satellite networks, maritime digitalization, commercial aviation connectivity, and continued investment in civil and commercial space infrastructure. Buyers are expected to prioritize integrated antenna control platforms capable of supporting multiple satellite constellations, automated calibration, secure software management, predictive maintenance, and interoperability with evolving communication architectures.
Strategic priorities across the value chain are likely to include:
Expansion of software-defined antenna control capabilities supporting hybrid satellite networks.
Greater investment in cybersecurity, remote diagnostics, and lifecycle software services.
Localization of selected manufacturing activities to improve supply-chain resilience.
Stronger collaboration between antenna manufacturers, satellite operators, and system integrators.
Continued focus on modular product architectures that simplify upgrades without replacing complete antenna systems.
Companies able to combine precision tracking performance with software flexibility, regulatory compliance, and long-term service capability are expected to remain well positioned for defense, commercial satellite communication, maritime, aviation, and space-sector procurement programs throughout the forecast period.
Antenna Control Unit (ACU) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2025 | USD 1.32 billion |
| Total Market Size in 2031 | USD 1.93 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.9% |
| Study Period | 2020 to 2031 |
| Historical Data | 2020 to 2023 |
| Base Year | 2024 |
| Forecast Period | 2025 – 2031 |
| Segmentation | Platform, Antenna Type, Component, Geography |
| Companies |
|
Market Segmentation
By Platform
Ground-Based
Airborne
Naval
Spaceborne
By Antenna Type
Fixed Antenna ACUs
Mobile Antenna ACUs
Tracking Antenna ACUs
By Component
Hardware
Software
Services
By Application
Defense and Military
Satellite Communications (SATCOM)
Commercial Telecommunications
Broadcasting and Media
Space Exploration and Launch Systems
Maritime Communications
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ANTENNA CONTROL UNIT (ACU) MARKET BY PLATFORM
5.1. Introduction
5.2. Ground-Based
5.3. Airborne
5.4. Naval
5.5. Spaceborne
6. ANTENNA CONTROL UNIT (ACU) MARKET BY ANTENNA TYPE
6.1. Introduction
6.2. Fixed Antenna ACUs
6.3. Mobile Antenna ACUs
6.4. Tracking Antenna ACUs
7. ANTENNA CONTROL UNIT (ACU) MARKET BY COMPONENT
7.1. Introduction
7.2. Hardware
7.3. Software
7.4. Services
8. ANTENNA CONTROL UNIT (ACU) MARKET BY APPLICATION
8.1. Introduction
8.2. Defense and Military
8.3. Satellite Communications (SATCOM)
8.4. Commercial Telecommunications
8.5. Broadcasting and Media
8.6. Space Exploration and Launch Systems
8.7. Maritime Communications
8.8. Others
9. ANTENNA CONTROL UNIT (ACU) MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Platform
9.2.2. By Antenna Type
9.2.3. By Component
9.2.4. By Application
9.2.5. By Country
9.2.5.1. USA
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Platform
9.3.2. By Antenna Type
9.3.3. By Component
9.3.4. By Application
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Platform
9.4.2. By Antenna Type
9.4.3. By Component
9.4.4. By Application
9.4.5. By Country
9.4.5.1. United Kingdom
9.4.5.2. Germany
9.4.5.3. France
9.4.5.4. Spain
9.4.5.5. Others
9.5. Middle East and Africa
9.5.1. By Platform
9.5.2. By Antenna Type
9.5.3. By Component
9.5.4. By Application
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. UAE
9.5.5.3. Others
9.6. Asia Pacific
9.6.1. By Platform
9.6.2. By Antenna Type
9.6.3. By Component
9.6.4. By Application
9.6.5. By Country
9.6.5.1. China
9.6.5.2. Japan
9.6.5.3. India
9.6.5.4. South Korea
9.6.5.5. Taiwan
9.6.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Viasat Inc.
11.2. Cobham Limited
11.3. CPI Satcom & Antenna Technologies
11.4. Kongsberg Defence & Aerospace
11.6. Indra Sistemas S.A.
11.7. Antech Space S.r.l.
11.8. Honeywell Aerospace
11.9. Orbit Communication Systems Ltd.
11.10. Radeus Labs Inc.
11.11. Savronik Elektronik Sanayi ve Ticaret A.?.
11.12. RTX Corporation (Raytheon)
11.13. ST Engineering iDirect
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key benefits for the stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











