
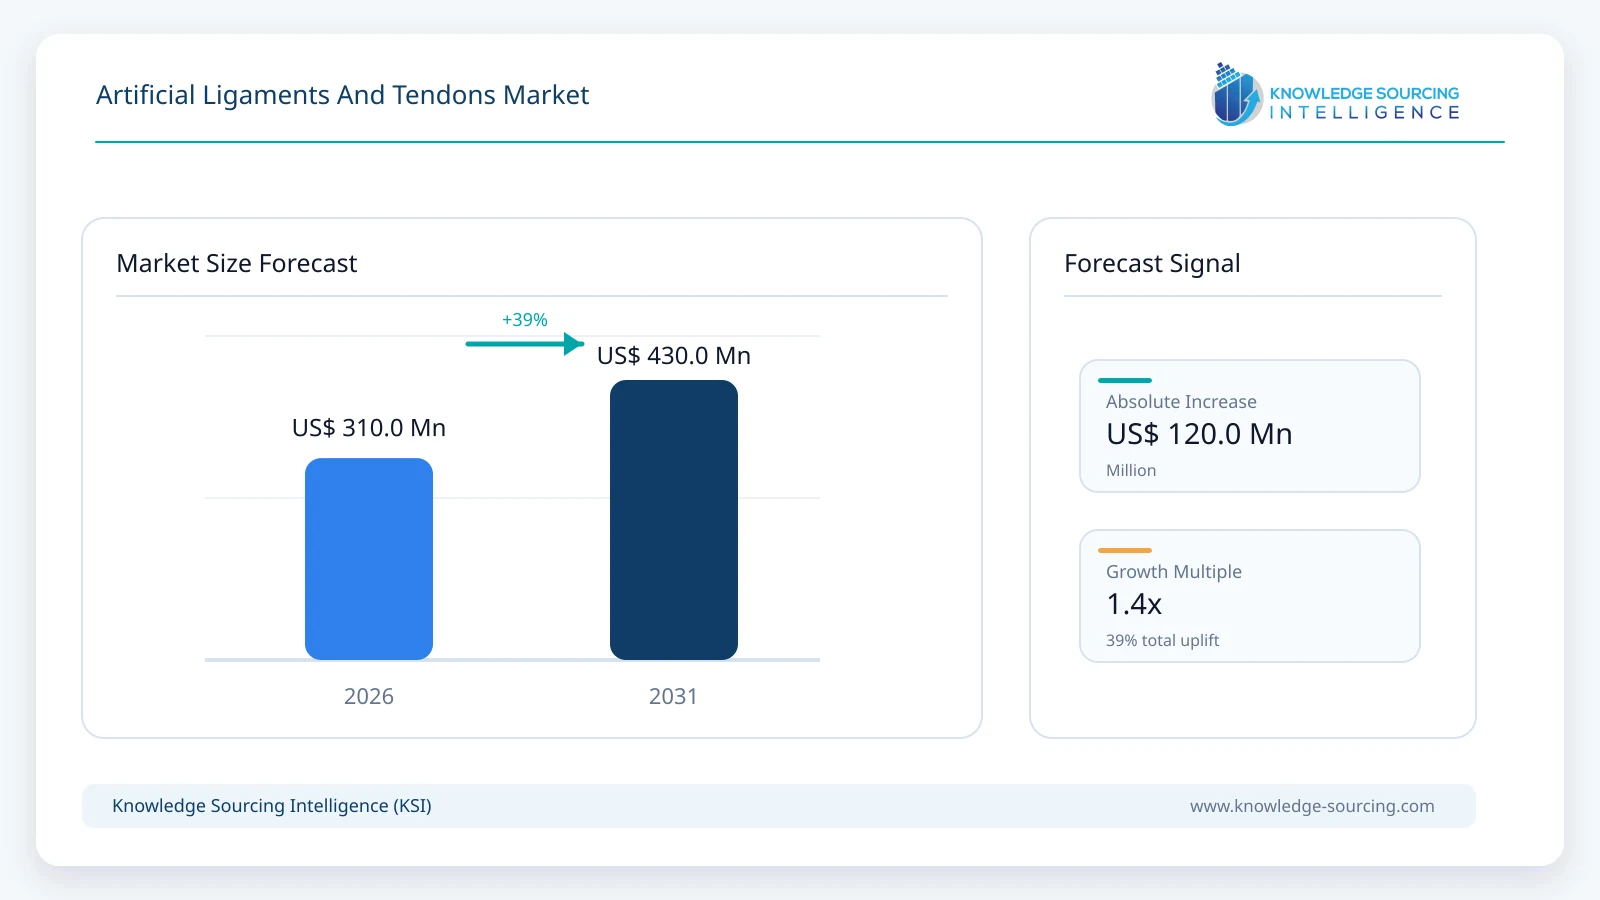
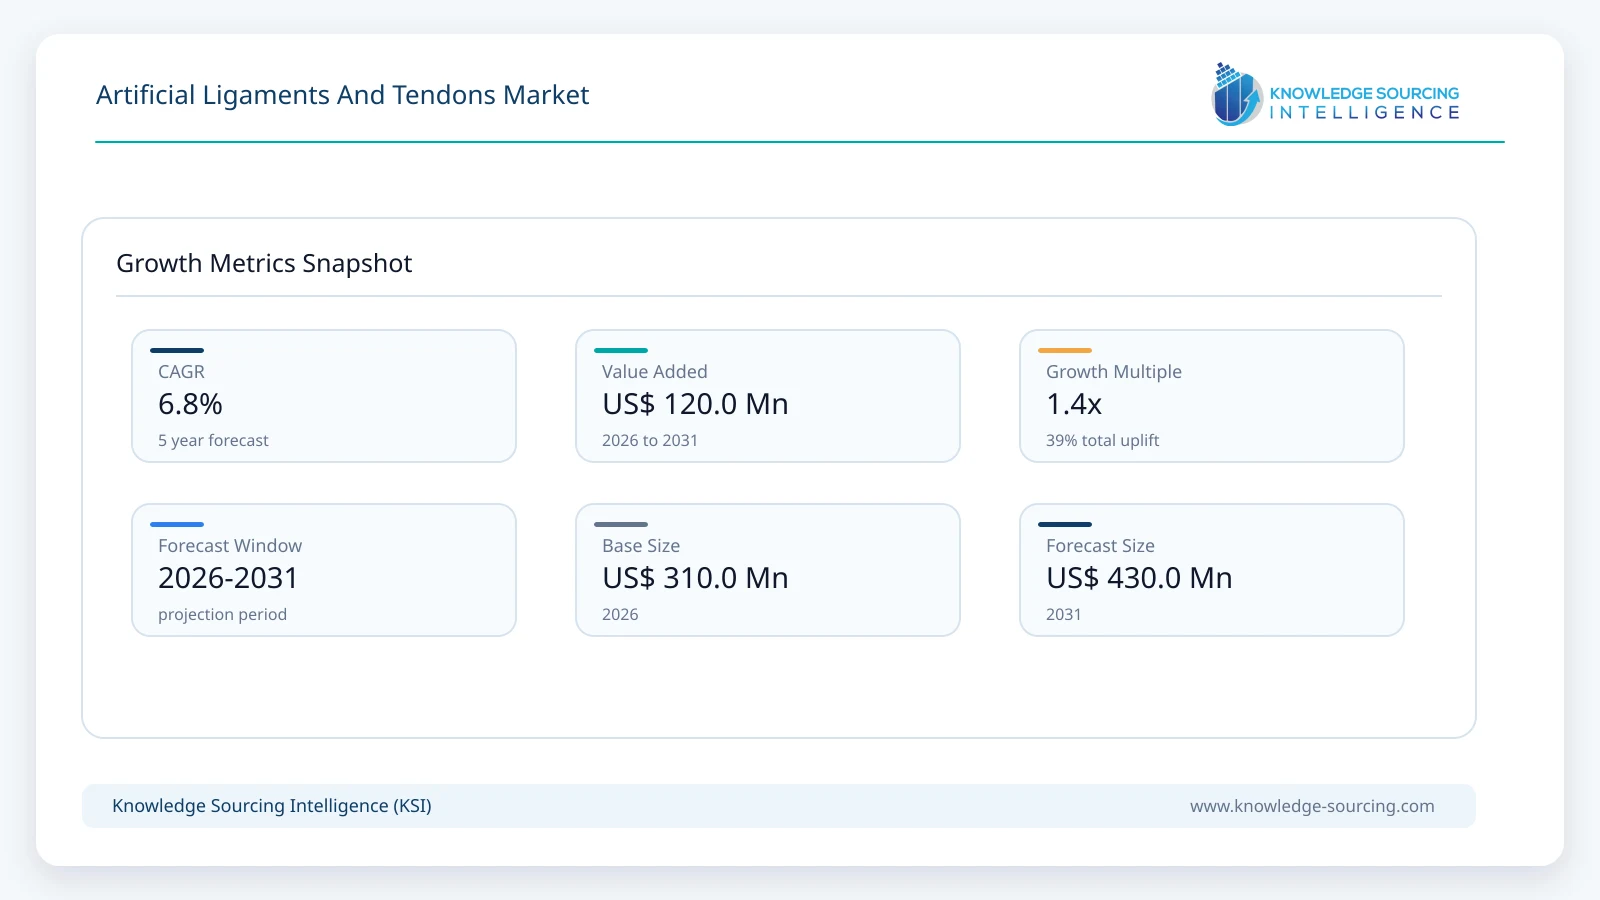
The artificial ligaments and tendons market is forecast to grow at a CAGR of 6.8%, reaching USD 430.0 million in 2031 from USD 310.0 million in 2026.
Highlights:
- 1The market is moving from conventional permanent synthetic grafts toward bio-integrative and augmentation-oriented constructs that combine immediate mechanical reinforcement with gradual host-tissue incorporation. This shift is expanding the addressable opportunity beyond complete ligament replacement into primary repair reinforcement, revision surgery, tendon reconstruction, and complex soft-tissue stabilization.
- 2Clinical demand is supported by the persistent burden of musculoskeletal injuries. The World Health Organization estimates that approximately 1.71 billion people globally live with musculoskeletal conditions, making musculoskeletal disorders one of the largest contributors to disability and rehabilitation needs worldwide. The burden is expected to increase as populations grow and age.
- 3Knee reconstruction remains the most commercially important application because ACL injuries generate a substantial pool of reconstruction procedures, particularly among younger and physically active populations. Published U.S. evidence reports ACL injury incidence of approximately 68.6 per 100,000 person-years, while healthcare-system data show that ACL reconstruction utilization has been recovering following the pandemic-related decline.
- 4Regulatory requirements continue to favor manufacturers capable of generating clinical evidence, maintaining quality systems, and supporting post-market surveillance. In Europe, the mandatory rollout of the first four EUDAMED modules began on May 28, 2026, increasing the importance of traceability, device registration, notified-body information, and market-surveillance readiness.
- 5Product innovation is increasingly concentrated around synthetic scaffolds, knitted or braided polymer structures, reinforcement tapes, adjustable fixation systems, and resorbable implants. This is creating a continuum between traditional artificial ligaments and biologically assisted repair technologies rather than a single homogeneous product category.
- 6Large orthopedic companies are strengthening their soft-tissue portfolios through acquisitions, product launches, and geographic expansion. Stryker's integration of Artelon and its 2026 launch of ProCinch in Japan demonstrate the industry's broader movement toward integrated sports-medicine and ligament-reconstruction portfolios.
The Artificial Ligaments and Tendons Market represents a specialized segment of orthopedic and sports-medicine devices used to reconstruct, reinforce, or support damaged ligaments and tendons. Products range from permanent synthetic ligament prostheses and polyester-based grafts to resorbable scaffolds, reinforcement meshes, synthetic tapes, and dynamic augmentation systems. The commercial opportunity is increasingly influenced by the ability of manufacturers to balance immediate mechanical stability with biological compatibility and tissue integration.
Unlike conventional autografts, synthetic solutions can be supplied as standardized, sterile, off-the-shelf devices and can avoid tissue harvesting from a second anatomical site. This can be particularly relevant in revision procedures, multi-ligament injuries, poor-quality native tissue, delayed tendon repairs, and situations in which an adequate autograft is unavailable. However, artificial ligaments are not a universal replacement for biological grafts. Surgeon selection depends on anatomy, injury severity, patient age, activity level, fixation method, tissue quality, clinical evidence, and the specific regulatory indication of the device.
The competitive direction of the market is therefore shifting from simply producing a mechanically strong synthetic cord toward engineering structures that can manage load during the healing period, minimize excessive stiffness, permit tissue ingrowth, and maintain performance under repetitive loading. Stryker's Artelon portfolio illustrates this direction: the company's Dynamic Matrix technology is designed to provide load sharing while gradually integrating with connective tissue over approximately four to six years.
Artificial Ligaments and Tendons Market Analysis
Growth Drivers
The growing number of ligament and tendon injuries associated with sports, occupational activity, falls, and aging is a fundamental demand driver. ACL injuries are particularly relevant because reconstruction remains a common orthopedic procedure and because synthetic augmentation can be attractive where surgeons want to reinforce a biological repair or address inadequate graft quality. U.S. literature places annual ACL incidence at approximately 68.6 cases per 100,000 person-years, while historical clinical sources report hundreds of thousands of ACL reconstructions annually.
Recent epidemiological evidence also confirms that soft-tissue injury remains a significant healthcare burden outside the ACL category. A 2025 analysis using U.S. National Electronic Injury Surveillance System data estimated approximately 7.4 million ankle sprains treated in emergency departments from 2010 to 2024. Although the annual incidence declined over the period, adolescents aged 15–19 recorded the highest incidence and more than half of the estimated sprains occurred among individuals aged 10–24. This creates a sustained clinical environment for ankle ligament reconstruction, augmentation, and related soft-tissue fixation products.
Demographic aging provides a second structural driver. The United Nations Population Division's latest data portal indicates that people aged 65 years and older represented approximately 10.6% of the global population in 2026, compared with 9.76% in 2022, and the share is projected to rise further over the following decades. Aging is associated with declining tissue quality, degenerative tendon pathology, falls, and reduced healing capacity. The WHO also identifies osteoarthritis and other musculoskeletal disorders as important conditions associated with older age.
A third driver is the growing emphasis on rapid rehabilitation and preservation of native tissue. Modern sports-medicine procedures increasingly seek constructs that provide mechanical reinforcement without unnecessarily restricting movement. This supports demand for tapes, meshes, and dynamic scaffolds that can augment a patient's own tissue rather than completely replacing it.
Finally, the availability of standardized synthetic products can reduce dependence on graft harvesting and biological tissue availability. This is especially relevant in revision ACL reconstruction and complex multi-ligament cases where the patient's own graft inventory may be limited. The commercial implication is that synthetic products can capture value not only from primary reconstruction but also from technically difficult cases in which conventional graft strategies are less attractive.
Challenges and Opportunities
The principal challenge remains long-term clinical performance. A synthetic implant must withstand repetitive mechanical loading while avoiding excessive stiffness, abrasion, foreign-body reaction, infection, migration, or loss of fixation. Permanent polymer structures may provide high initial strength but can create concerns about long-term tissue response, while resorbable systems must maintain adequate mechanical performance during the biologically important healing window.
Another challenge is clinical evidence. Artificial ligaments and tendons compete directly with well-established autograft and allograft procedures. Surgeons are therefore unlikely to adopt a new synthetic device solely on the basis of mechanical strength or laboratory testing. Long-term clinical outcomes, failure rates, revision requirements, patient-reported outcomes, tissue integration, and rehabilitation performance are increasingly important purchasing and adoption criteria.
Regulatory complexity is an additional constraint. The U.S. FDA classification database shows that orthopedic ligament-reinforcement meshes can fall under Class II and be reviewed through the 510(k) pathway, while resorbable ACL-repair implants are also classified as Class II devices under product code QNI. Therefore, it is inaccurate to characterize all artificial ligament and tendon products as Class III devices; classification depends on the device's design, intended use, claims, and applicable product code.
The largest opportunity is the convergence of artificial ligament technology with biologically oriented augmentation. Instead of treating synthetic material as a permanent substitute for native tissue, manufacturers are increasingly developing porous, permeable, resorbable, or dynamic scaffolds that provide temporary mechanical support and facilitate tissue incorporation. This creates opportunities in ACL repair, tendon reinforcement, rotator cuff augmentation, ankle stabilization, patellar and quadriceps tendon reconstruction, and revision procedures.
Raw Material and Pricing Analysis
Artificial ligaments and tendons are manufactured from specialized medical-grade polymers and textile structures rather than ordinary commodity plastics. Polyethylene terephthalate (PET) remains important in permanent synthetic ligament products because of its tensile strength and established textile-processing characteristics. Other systems use polyurethane-based materials, resorbable polymers, polyester tapes, and proprietary polymer blends designed to achieve a specific balance between strength, elasticity, porosity, and biological response.
Material cost is only one component of the final device price. Specialized knitting, braiding, weaving, cutting, surface modification, sterilization, packaging, quality inspection, and validation can have a larger effect on unit economics. A small implant can therefore command a relatively high selling price compared with its raw polymer content because manufacturers must maintain tightly controlled processes suitable for implantable medical devices.
Pricing is also affected by regulatory documentation, clinical evidence generation, distribution margins, surgeon training, inventory requirements, and specialized fixation components. Products supplied as procedure-specific systems or kits may command a premium because they combine the implant with instruments or accessories that simplify surgical workflow. The April 2026 FDA clearance of Artelon Convenience Kits provides a current example of how product configuration and procedural integration are becoming part of the competitive proposition. The FDA recorded the device as substantially equivalent through the 510(k) pathway on April 9, 2026.
Supply Chain Analysis
The supply chain is characterized by relatively low production volumes compared with commodity medical devices but high requirements for consistency and traceability. The upstream chain includes medical-grade polymer suppliers, specialty textile producers, coating and surface-treatment providers, sterilization companies, packaging suppliers, and precision medical-device manufacturers.
Manufacturing requires strict control over polymer specifications, fiber diameter, textile architecture, tensile properties, porosity, dimensional tolerances, cleanliness, bioburden, sterilization compatibility, and packaging integrity. Consequently, switching suppliers can require substantial qualification work and may affect regulatory submissions or quality documentation.
Downstream distribution is generally organized through specialized orthopedic sales channels, hospital procurement departments, ambulatory surgical centers, orthopedic distributors, and direct manufacturer sales teams. The increasing use of outpatient orthopedic procedures creates an additional supply-chain requirement: products must be available in standardized, sterile, easy-to-use configurations with predictable lead times.
Supply-chain resilience has become increasingly important because orthopedic procedures are schedule-sensitive. A shortage of a specialized implant, fixation component, or compatible accessory can disrupt an entire procedure. Manufacturers are therefore incentivized to maintain qualified alternate suppliers, regional inventory, validated sterilization capacity, and standardized product configurations.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
|---|---|---|
USA | U.S. Food and Drug Administration (FDA); 510(k) and other applicable premarket pathways | Regulatory classification is product-specific. FDA records show non-resorbable orthopedic ligament-reinforcement mesh under Class II and resorbable ACL-repair implants under Class II with 510(k) review. This creates a meaningful evidence and quality-system burden while avoiding the assumption that every artificial ligament is automatically a Class III product. |
Europe | Medical Device Regulation (EU) 2017/745; EUDAMED | MDR has increased requirements for clinical evaluation, technical documentation, post-market surveillance, vigilance, and traceability. From May 28, 2026, the first four EUDAMED modules became mandatory, strengthening device and manufacturer traceability. |
China | National Medical Products Administration (NMPA) | Market access requires compliance with China's medical-device registration framework and applicable domestic standards. Local clinical and registration requirements can increase development time for foreign manufacturers, while domestic device development and localized manufacturing can improve competitive positioning. |
Japan | Pharmaceuticals and Medical Devices Agency (PMDA) and Ministry of Health, Labour and Welfare | Implantable orthopedic devices are subject to detailed classification, review, quality, and post-market requirements. PMDA's 2026 review information continues to show active evaluation of orthopedic and implantable medical technologies, reinforcing the importance of Japan-specific regulatory planning. |
Regulation is increasingly becoming a competitive capability rather than simply a market-entry requirement. Manufacturers with mature clinical evidence, quality systems, post-market surveillance processes, and established notified-body or regulatory relationships can bring products into major markets more efficiently than smaller companies with limited regulatory infrastructure.
Europe is undergoing a particularly important transition. In December 2025, the European Commission proposed targeted changes intended to simplify and digitalize aspects of the medical-device regulatory framework while maintaining patient-safety objectives. The proposal is not itself binding law until adopted by the EU legislative process, so manufacturers must continue to operate under the applicable MDR requirements. In April 2026, the European Commission also updated MDCG guidance on medical-device classification, demonstrating that regulatory interpretation continues to evolve.
In-Depth Segment Analysis
By Application: Knee Injury
The Knee Injury segment remains the most commercially important application because ACL reconstruction and related ligament procedures represent a large and technically demanding pool of orthopedic interventions. Synthetic products are used in different ways across this segment: as complete ligament prostheses, reinforcement structures, augmentation devices, or scaffolds intended to support biological repair.
Demand is strongest where the clinical advantages of an off-the-shelf implant can solve a specific surgical problem. Revision ACL procedures are particularly relevant because patients may have already used hamstring or patellar tendon grafts during primary reconstruction. In such cases, the surgeon may have fewer autograft options available, creating an opportunity for synthetic augmentation or alternative graft strategies.
Another important cohort is highly active patients who place significant functional demands on the reconstructed knee. However, the market opportunity should not be interpreted as evidence that synthetic grafts universally provide faster or better recovery than autografts. Product selection remains dependent on clinical evidence and physician judgment. The strongest commercial proposition is therefore increasingly based on targeted indications where the mechanical and workflow benefits of synthetic reinforcement complement biological tissue healing.
Recent U.S. evidence supports continued procedure demand. A large integrated healthcare-system study recorded 23,082 ACL reconstructions between 2017 and 2023. ACL reconstruction incidence fell sharply during the 2020 pandemic shutdown but subsequently increased from 38.6 to 42.3 per 100,000 members between 2021 and 2023, indicating recovery of surgical utilization.
Competition within the knee segment is also broadening beyond conventional reconstruction. On January 13, 2026, the FDA determined the BEAR Bridge-Enhanced ACL Restoration Implant from Miach Orthopaedics to be substantially equivalent under the 510(k) pathway. The device is classified as a resorbable ACL-repair implant rather than a permanent artificial ligament. Its regulatory progress nevertheless demonstrates the broader movement toward biological repair and resorbable augmentation technologies that compete for clinical attention within the same ACL treatment pathway.
Therefore, the knee segment is expected to remain a central growth engine, but its future composition is likely to include a greater proportion of augmentation and biologically integrated devices rather than only permanent synthetic replacements.
By End-User: Hospitals and Clinics
Hospitals and clinics remain the principal end users because they provide the specialist surgical infrastructure required for ligament and tendon reconstruction. Large hospitals typically have orthopedic trauma services, sports-medicine departments, advanced imaging, arthroscopy capabilities, anesthesia services, postoperative rehabilitation, and access to revision surgery. These capabilities allow hospitals to treat the full range of indications for artificial ligaments and tendons.
Ambulatory surgical centers are becoming increasingly important for selected soft-tissue procedures because many sports-medicine operations can be performed without prolonged hospitalization. This creates demand for sterile, standardized products with simple instrumentation and predictable operating-room workflows. Manufacturers that reduce preparation time, simplify fixation, or package implants with procedure-specific components can therefore gain an advantage.
Hospitals also remain important centers for clinical evidence generation. Surgeons at high-volume orthopedic institutions influence adoption by publishing clinical outcomes, participating in training programs, and evaluating new implant technologies. As a result, commercial success depends not only on procurement price but also on surgeon familiarity, clinical evidence, training support, product availability, and long-term patient outcomes.
Geographical Analysis
United States Market Analysis (North America)
The United States is one of the most commercially developed markets for artificial ligament, tendon-repair, augmentation, and sports-medicine technologies. The market benefits from a large orthopedic device industry, advanced sports medicine, extensive specialist networks, and relatively rapid adoption of technologies supported by strong clinical evidence.
ACL reconstruction is a major demand anchor. U.S. clinical literature reports an annual ACL incidence of approximately 68.6 per 100,000 person-years, while more recent research continues to document substantial procedure volumes and persistent demand for reconstruction.
The FDA environment also supports a differentiated pathway for innovative soft-tissue technologies. The 2026 FDA clearance of Artelon Convenience Kits under the orthopedic ligament-reinforcement mesh classification demonstrates continued regulatory activity around synthetic augmentation products.
Competition is increasingly shifting toward integrated sports-medicine portfolios rather than standalone implants. Companies that can combine fixation, arthroscopy, biologic repair, ligament augmentation, and rehabilitation technologies can strengthen surgeon relationships and increase procedural share.
Brazil Market Analysis (South America)
Brazil represents an important emerging market because of its large population, extensive sports culture, expanding private healthcare sector, and need for orthopedic trauma and sports-medicine services. Soccer-related knee and ankle injuries contribute to the clinical relevance of ligament reconstruction.
The market has a dual healthcare structure, with public-sector procurement emphasizing cost efficiency and private hospitals generally offering greater access to premium orthopedic devices. Artificial ligament and tendon products that demonstrate predictable performance while minimizing surgical complexity can therefore have an opportunity in private orthopedic centers and specialized sports-medicine facilities.
Market development is also influenced by the availability of trained orthopedic surgeons, reimbursement policies, import requirements, and local distributor networks. Manufacturers seeking broader adoption must balance premium technology positioning with local affordability and supply reliability.
Germany Market Analysis (Europe)
Germany remains a major European market for advanced orthopedic devices because of its established hospital infrastructure, specialist orthopedic care, strong medical-device manufacturing ecosystem, and emphasis on clinical evidence and quality.
The European regulatory environment is undergoing an important operational transition. EUDAMED's first four modules became mandatory from May 28, 2026, covering actor registration, UDI/device registration, notified bodies and certificates, and market surveillance. This increases traceability requirements for artificial ligament and tendon manufacturers operating in Germany and other EU member states.
German demand is supported by both sports-related reconstruction and the broader aging population. The commercial opportunity is particularly strong for devices that can demonstrate durable performance, predictable fixation, and a clear clinical role in complex or revision procedures.
Saudi Arabia Market Analysis (Middle East and Africa)
Saudi Arabia represents a developing opportunity for advanced orthopedic and sports-medicine technologies. Investment in specialized healthcare infrastructure, sports participation, hospital modernization, and specialist medical services is expanding the environment in which advanced orthopedic implants can be adopted.
The country's growing emphasis on sports and physical activity increases the relevance of knee, shoulder, ankle, and tendon injuries. Internationally trained orthopedic specialists and modern private hospitals can facilitate adoption of new synthetic augmentation and reconstruction systems, particularly when products have established regulatory approvals in major markets.
However, market expansion depends on procurement processes, reimbursement, distributor capabilities, local regulatory requirements, and the availability of surgeons trained in specific synthetic reconstruction techniques.
Japan Market Analysis (Asia-Pacific)
Japan combines an advanced medical-device ecosystem with a rapidly aging population and high expectations for quality, safety, and minimally invasive orthopedic procedures. The country's demographic structure creates demand for solutions addressing tendon degeneration, falls, joint instability, and soft-tissue reconstruction alongside sports-related injuries.
Japan also represents an important strategic market for global orthopedic companies. In September 2026, Stryker Japan announced the nationwide launch of ProCinch, an adjustable suspensory fixation device for knee ligament reconstruction, and stated that the launch represented a full-scale entry into ACL reconstruction within its sports-medicine strategy. The company also highlighted its existing portfolio of arthroscopy, meniscal-repair, and artificial-ligament products.
This development demonstrates the competitive importance of complete ACL procedure ecosystems. Rather than competing only through the implant itself, manufacturers are increasingly developing fixation, instrumentation, and sports-medicine platforms that can capture a larger share of the reconstruction workflow.
Competitive Environment and Analysis
The Artificial Ligaments and Tendons market consists of large multinational orthopedic companies, specialized synthetic-implant manufacturers, and companies focused on tissue reinforcement or biologically integrated scaffolds. Competition is increasingly based on clinical evidence, biomaterial architecture, fixation compatibility, surgeon familiarity, distribution reach, regulatory capability, and the ability to provide complete procedural solutions.
The market is also moving toward a distinction between permanent synthetic replacements and temporary or semi-permanent augmentation technologies. Permanent PET-based devices compete primarily through mechanical strength, textile architecture, durability, and long-term clinical experience. Dynamic or resorbable scaffolds compete through tissue integration, load sharing, and their ability to complement native healing.
Artelon / Stryker
Artelon's integration into Stryker remains one of the most significant competitive developments in the synthetic soft-tissue segment. Stryker completed its acquisition of Artelon in July 2024, adding Artelon's synthetic soft-tissue technology to its Foot & Ankle and Sports Medicine portfolios. At the time of completion, Stryker stated that Artelon had been used in more than 60,000 implantations worldwide.
The Artelon portfolio is based on Dynamic Matrix Technology, which is designed to reinforce ligament and tendon repairs while maintaining flexibility and allowing progressive tissue integration. Stryker describes the scaffold as retaining at least 90% of its original strength during the first year and gradually integrating over approximately four to six years.
A notable 2026 regulatory development occurred on April 9, when the FDA determined the Artelon Convenience Kits substantially equivalent through the 510(k) pathway. This indicates continued expansion of the Artelon platform toward procedure-oriented configurations and supports Stryker's strategy of integrating soft-tissue reinforcement into a broader orthopedic offering.
Orthomed S.A.S.
Orthomed S.A.S. is positioned within the European synthetic-ligament segment through its LIGASTIC portfolio. The company's product strategy centers on synthetic ligament reconstruction using textile-engineered structures, particularly PET-based designs. The competitive rationale for such products is based on predictable mechanical properties, standardized implant geometry, and the ability to provide an off-the-shelf alternative for selected reconstruction procedures.
Orthomed's positioning remains differentiated from newer bio-integrative scaffolds because permanent synthetic ligament systems emphasize mechanical reconstruction and long-term structural support. The principal competitive requirement is therefore continued clinical evidence demonstrating durability, functional outcomes, and acceptable tissue response.
Xiros / Neoligaments
Xiros has consolidated its surgical products under the Xiros name, with the company explicitly stating that Neoligaments and Xiros Surgical products are now available under one brand. Its portfolio covers ACL reconstruction, MCL reconstruction, MPFL reconstruction, patellar and quadriceps tendon reconstruction, Achilles tendon repair, rotator cuff reinforcement, and other soft-tissue procedures.
The company's 2026 activity provides evidence of continued development around synthetic ligament and tendon solutions. Xiros added a JewelACL clinical summary in February 2026, a Poly-Tape patient information resource in June 2026, and new Infinity-Lock Tape resources for spring-ligament reconstruction in July 2026. It also published a further JewelACL clinical summary in August 2026.
The breadth of this activity is strategically important because it demonstrates how specialist manufacturers can compete through procedure-specific solutions rather than a single artificial-ligament product. Xiros also markets Poly-Tape for patellar and quadriceps tendon reconstruction. Its published product information describes a 30 mm open-weave tape designed for tendon reconstruction and notes a clinical history involving 88 knees across published studies since 2008.
Recent Market Developments
September 2026: Stryker Japan launched ProCinch for knee-ligament reconstruction across Japan. The company stated that the launch represented a full-scale entry into ACL reconstruction and strengthened its Sports Medicine offering. ProCinch uses Stryker's IntelliBraid technology and provides adjustable-loop and other fixation configurations for all-inside ACL procedures.
September 2026: Stryker showcased new Foot & Ankle technologies at the 2026 American Orthopaedic Foot & Ankle Society meeting, reflecting the company's broader expansion of technology-enabled orthopedic solutions. Although these launches are not themselves artificial ligaments, the development demonstrates continued investment in the same Foot & Ankle ecosystem in which Artelon's soft-tissue reinforcement technology is commercially positioned.
August 2026: Xiros published a new JewelACL clinical summary, extending its 2026 clinical-resource activity around its synthetic ACL reconstruction platform. The company also published a JewelACL patient information leaflet earlier in August, indicating continued commercialization and surgeon/patient education around its ACL solution.
July 2026: Xiros released a surgical technique manual and animation for Infinity-Lock Tapes in spring-ligament reconstruction. This development broadens the company's synthetic soft-tissue portfolio beyond ACL reconstruction and supports additional foot and ankle applications.
June 2026: Xiros published a Poly-Tape patient information leaflet, supporting its broader tendon-reconstruction portfolio. The company's product range includes Poly-Tape solutions for patellar and quadriceps tendon reconstruction.
May 2026: The European Union began mandatory use of the first four EUDAMED modules, covering actor registration, UDI/device registration, notified bodies and certificates, and market surveillance. This raises the importance of digital traceability and regulatory-data readiness for artificial ligament and tendon manufacturers selling in the EU.
April 2026: The U.S. FDA determined Artelon Convenience Kits substantially equivalent through the 510(k) pathway. The submission was received in January 2026 and received a substantial-equivalence decision on April 9, 2026. The device was reviewed under the Class II resorbable orthopedic ligament-reinforcement mesh framework.
April 2026: The European Commission published an updated MDCG classification guidance revision, reflecting the continuing evolution of the EU medical-device regulatory framework. For artificial ligament and tendon manufacturers, classification remains important because regulatory requirements vary according to intended purpose, implant characteristics, duration of use, and applicable device rules.
Artificial Ligaments And Tendons Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 310.0 million |
| Total Market Size in 2031 | USD 430.0 million |
| Forecast Unit | Million |
| Growth Rate | 6.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Application
Knee Injury
Foot and Ankle Injury
Shoulder Injury
Others
By End-User
Hospitals and Clinics
Ambulatory Surgical Centers
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
UK
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of End-Users
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. ARTIFICIAL LIGAMENTS AND TENDONS MARKET BY APPLICATION
5.1. Introduction
5.2. Knee Injury
5.3. Foot and Ankle Injury
5.4. Shoulder Injury
5.5. Others
6. ARTIFICIAL LIGAMENTS AND TENDONS MARKET BY END-USER
6.1. Introduction
6.2. Hospitals and Clinics
6.3. Ambulatory Surgical Centers
7. ARTIFICIAL LIGAMENTS AND TENDONS MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. UK
7.4.4. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Taiwan
7.6.6. Thailand
7.6.7. Indonesia
7.6.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Emerging Players and Market Lucrativeness
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. Orthomed
9.2. Neoligaments
9.3. Cousin Biotech
9.4. FX Solutions
9.5. Corin Group
9.6. Arthrex Inc.
9.7. Mathys AG Bettlach
9.8. FH Orthopedics
9.9. Stryker Corporation
9.10. Artelon
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











