
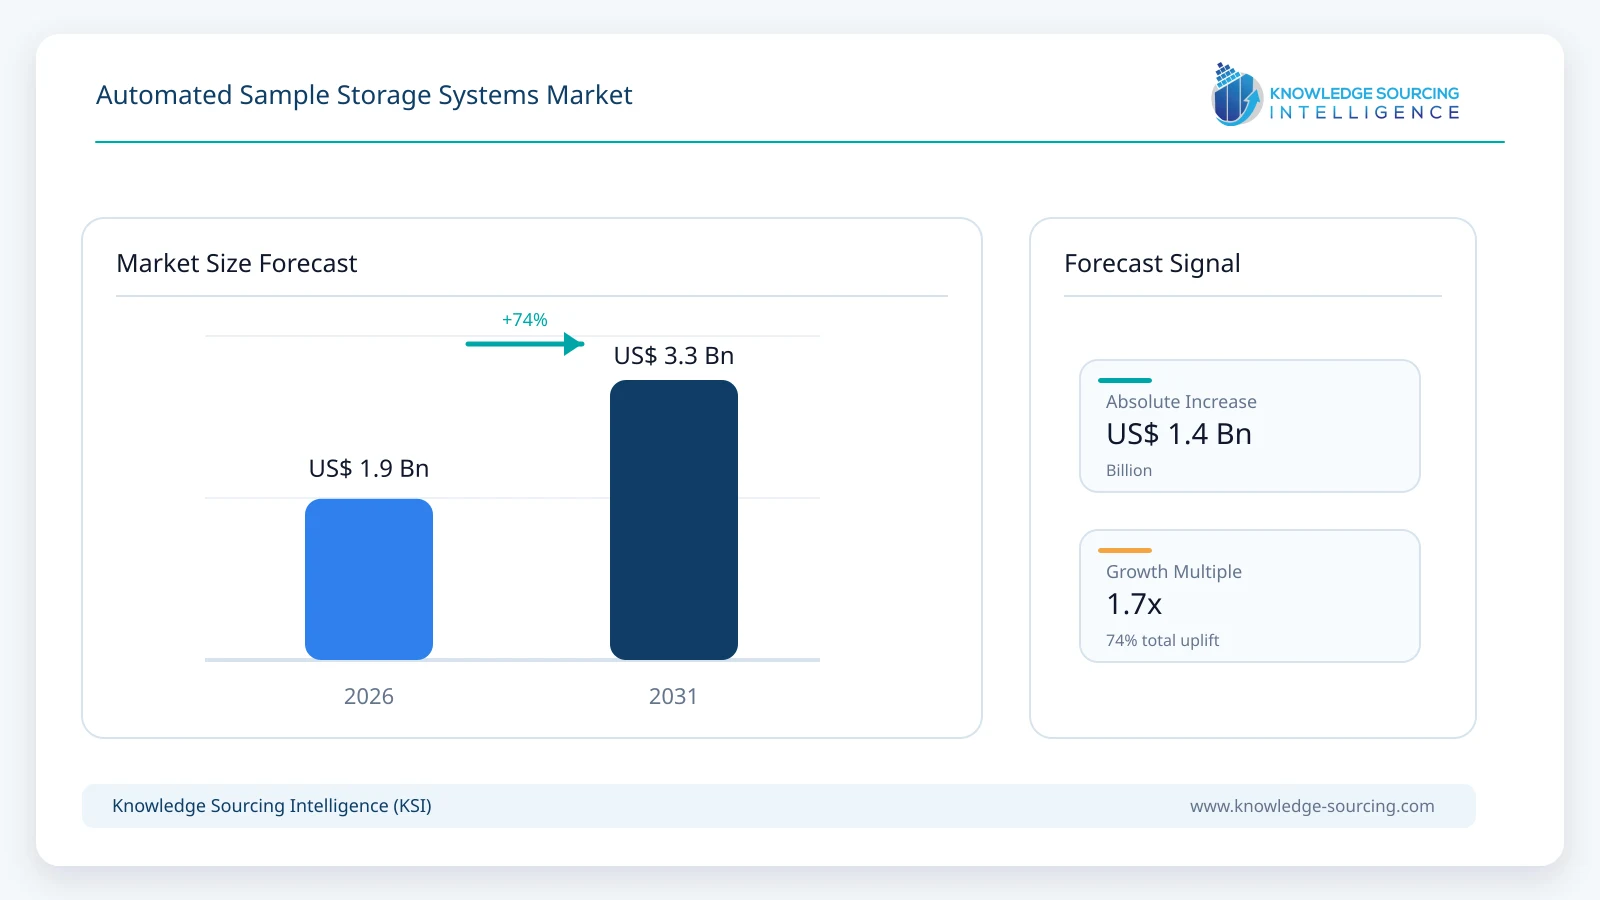
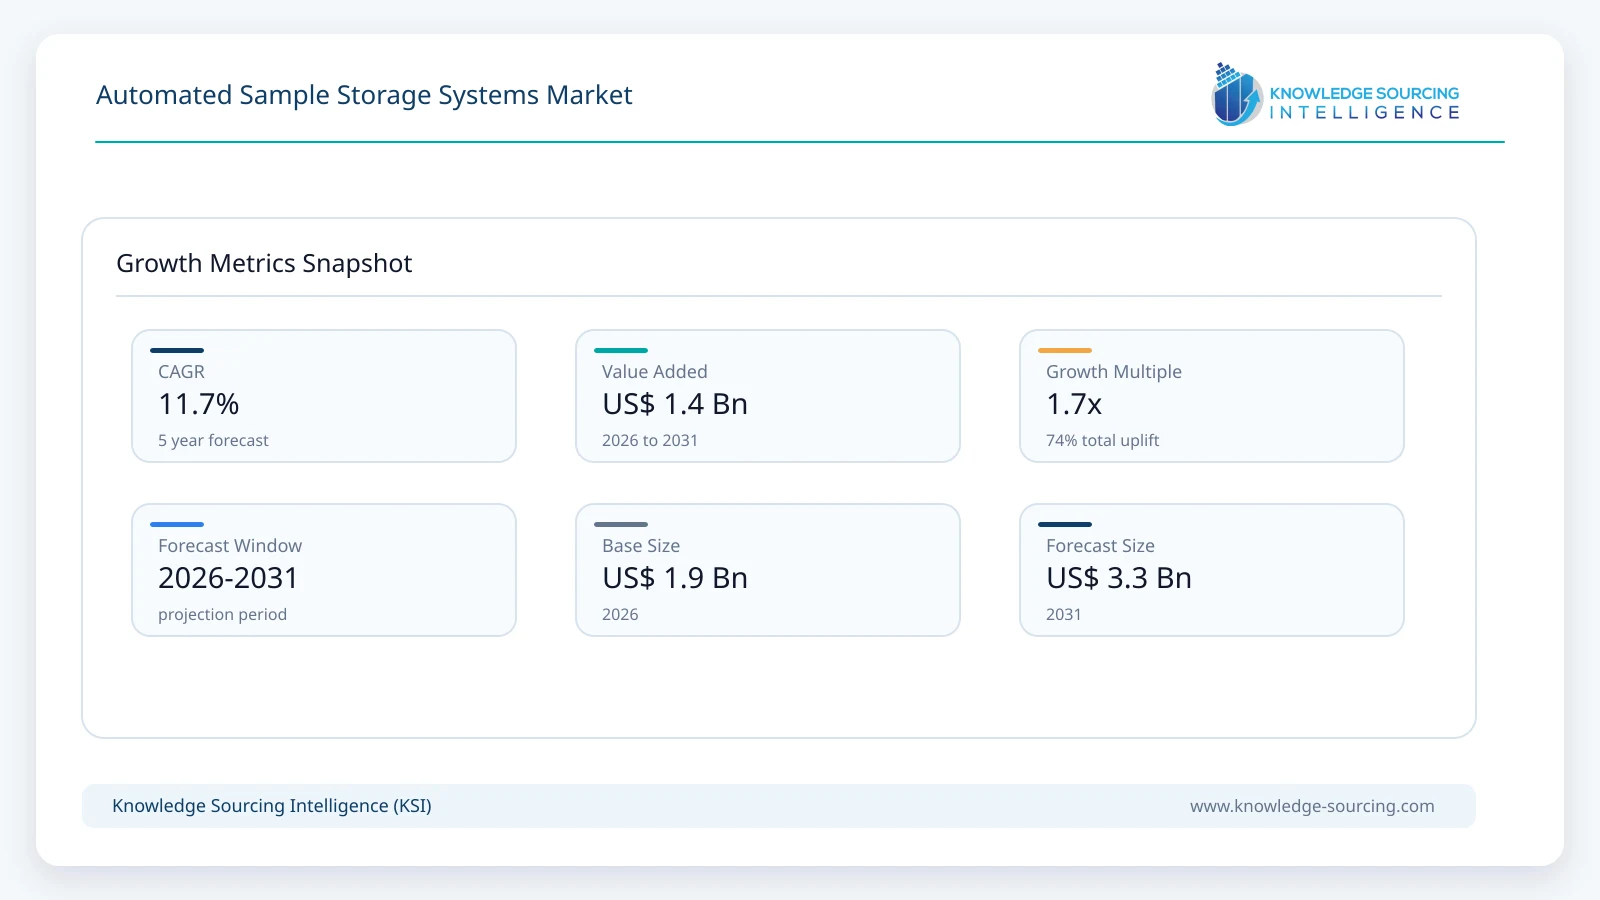
The Automated Sample Storage Systems Market is projected to grow from USD 1.90 billion in 2026 to USD 3.30 billion by 2031, at a CAGR of 11.7% during the forecast period.
Highlights:
- 1Fully automated platforms represent an estimated 65% of 2026 value as robotic retrieval displaces repeated manual access.
- 2Large-capacity systems support centralized repositories serving pharmaceutical development and population-scale biospecimen collections.
- 3Biological samples contribute an estimated 58% of demand amid expanding genomic and clinical research collections.
- 4Pharmaceutical and biotechnology customers remain the principal purchasing group for compound and specimen management systems.
- 5North America remains the leading market, while Asia Pacific benefits from expanding research infrastructure and biobank capacity.
- 6Integrated inventory software, thermal stability and service resilience increasingly shape supplier selection.
Automated sample storage serves laboratories that must preserve a large number of specimens while ensuring reliable, traceable retrieval. The market includes automated cold and cryogenic stores, eligible storage-linked equipment, inventory-control interfaces, replacement modules and consumables used with these systems. Installations range from compact laboratory units to high-density biorepository systems holding millions of tubes. Their commercial value reflects not only cooling capacity but the ability to identify, move and return specific samples without compromising inventory integrity.
Hamilton markets BiOS for automated storage at minus 80 degrees Celsius and Verso for ambient-to-minus-20-degree compound management. Azenta supplies SampleArc, BioArc and CryoArc systems across low-temperature and cryogenic conditions, while LiCONiC and ASKION offer configurations for biobanks with demanding temperature and handling requirements. Procurement commonly combines equipment selection with labware compatibility, software integration, service coverage and facility design; buyers therefore assess the installation as a working sample-management environment rather than a standalone freezer.
Biological sample collections create operating requirements that differ markedly from conventional laboratory refrigeration. Freezer capacity alone does not resolve the risk of misidentified vials, repeated removal of neighbouring specimens or gaps in chain-of-custody records. Automated systems pair barcode-based identification with controlled movement inside temperature-managed storage, allowing an individual tube or rack to be requested, located and delivered through a managed workflow. Maintaining temperature during picking is particularly important for longitudinal cohorts, nucleic acids and other specimens whose usefulness depends on stable preservation conditions.
Large repositories place a premium on high-density architecture. Azenta’s BioArc Ultra accommodates up to 16 million samples, while Hamilton’s BiOS product family can be scaled from research-centre collections into multimillion-sample installations. In contrast, LiCONiC’s compact STT designs and SPT Labtech’s arktic platform address laboratories that need automated retrieval without committing to a purpose-built repository building. ASKION’s C-line extends automation into nitrogen-vapour cryogenic handling, where transfer temperatures and robotic operation have to be validated together.
Sample-management economics depend on more than the price of robotics. Refrigeration power, facility footprint, emergency redundancy, storage-format migration, sample-order frequency and preventive maintenance determine the cost of sustaining a collection over several years. The value of inventory software also rests on connectivity with laboratory information-management systems and on dependable identity records. Systems that accommodate established tube formats and phased expansion are better suited to laboratories whose sample holdings grow unevenly or whose research priorities change.
Market Trends
Ultra-Low-Temperature Picking Moves Closer to the Stored Specimen
Automated retrieval increasingly takes place within temperature-controlled sections of the storage system rather than after a full tray has been removed. Hamilton’s BiOS maintains minus-80-degree handling through inventory management and order processing, while Azenta’s BioArc architecture combines dense storage with selective access. Laboratories using long-lived serum, plasma, DNA and tissue collections seek to reduce repeated warming caused by manual rack searches.
The engineering consequences extend to robotic positioning, frost control and failure recovery. A storage purchase must be qualified against expected picking frequency, the number of different labware formats and the time required to move specimens to downstream equipment. Faster retrieval is valuable only when samples remain correctly identified and temperature excursions are bounded.
Storage Equipment Is Being Connected to Downstream Laboratory Workcells
Compound libraries are most productive when robotic stores exchange sample identities and work orders with screening and liquid-handling platforms. Hamilton’s INSTINCT S software provides interfaces for laboratory information-management systems and automation workstations. Azenta offers an automation interface module that can transfer rack-based formats to external equipment, bringing storage into the same workflow as sample preparation.
Integration changes the system specification. Buyers must define the tube formats, audit records, user permissions, scheduler interfaces and recovery procedures before commissioning. Laboratories with several instrument vendors often prefer documented application programming interfaces because a closed storage workflow can constrain later upgrades elsewhere in the facility.
High-Density Freezer Replacement Is Becoming an Energy Decision
Long-term biobanks use substantial floor area and power when samples are dispersed across many manually accessed freezers. Hamilton reported in February 2026 that its automated storage portfolio was available with natural refrigerants and described reduced energy consumption at established BiOS installations. Azenta’s BioArc Ultra similarly positions refrigeration efficiency and sample density as central aspects of its equipment design.
Economic comparisons must account for building services, standby capacity and real retrieval demand. The acquisition cost of a robotic repository can be substantial, but avoiding additional freezers, maintenance calls and repeated manual handling may alter its lifecycle cost. Energy benefits cannot be assumed to be identical across differently sized installations or operating schedules.
Cryogenic Automation Is Expanding Beyond Conventional Freezer Rooms
Cell-therapy materials and biological collections that require cryogenic conditions create more demanding transfer requirements than ordinary minus-20-degree compound stores. ASKION C-line supports robotic handling at very low temperatures, while Azenta’s CryoArc portfolio covers nitrogen-based storage. The engineering emphasis is on maintaining a controlled cold chain during location tracking, picking and transfer, not simply on reaching a low set-point temperature.
Cryogenic installations require careful consideration of liquid-nitrogen supply, oxygen monitoring, operator access, backup arrangements and long-term maintenance. Their adoption therefore tends to follow the availability of sufficiently valuable collections and technical staff capable of validating specialized workflows. Suppliers that provide both automation and cryogenic expertise have an advantage in these projects.
Automated Sample Storage Systems Market Segment Analysis
By Product Type
Fully Automated Systems
Fully automated systems lead purchasing because robotic movement and software-managed retrieval eliminate repeated manual searches within a cold chamber. The segment is projected to account for approximately USD 2.31 billion by 2031 as large sample collections and high-frequency access requirements favour integrated stores. Hamilton BiOS and Azenta BioArc illustrate installations where storage, picking and inventory history form a single operational environment.
Purchasers evaluate system uptime and predictable handling across multiple sample formats alongside raw capacity. The most demanding projects involve extensive legacy collections that must be migrated without interrupting research operations. Compact automated units are also commercially important, allowing smaller laboratories to adopt digital retrieval without building a dedicated high-density facility.
By Capacity
Large Capacity
National biobanks and established pharmaceutical compounds centres frequently purchase large-capacity systems because the cost of manually locating and moving individual vials rises as collections expand. Warehouse-scale repositories benefit from dense storage layouts, multiple picking stations and linked inventory systems that enable researchers to request specimens without entering freezer rooms.
Large-capacity systems are modelled to grow at approximately 15.3% annually through 2031, faster than smaller installations. Their growth is tied to funded multiyear studies and centralisation projects rather than universal adoption by laboratories. Project phasing, sample migration and building infrastructure remain substantial determinants of contract timing.
By Sample Type
Biological Samples
Biological specimens account for the largest storage workload in biobanks serving clinical research, genomics and translational medicine. Serum, plasma, nucleic acids and tissue-derived material frequently require long-term traceability across repeated access events, making thermal stability and secure inventory records central to system selection. Automated management also reduces the handling burden associated with releasing individual samples to collaborating investigators.
The biological-sample category is projected to reach approximately USD 2.01 billion by 2031. Demand increasingly includes collections supporting longitudinal research programmes, where consistent sample identity across years matters as much as short-term retrieval speed. Chemical compounds remain a separate important market, with stronger emphasis on screening workflows and diverse storage conditions.
By End-User
Pharmaceutical and Biotechnology
Pharmaceutical and biotechnology laboratories purchase automated sample stores to maintain compound libraries, development-stage biological materials and clinical-study specimens. High-throughput discovery facilities place frequent and varied orders for selected sample sets, while biopharmaceutical programmes place greater emphasis on cold-chain continuity and access control. These different workloads favour suppliers with configurable capacity and compatible tube-handling systems.
The segment is expected to reach approximately USD 1.45 billion in 2031. Expenditure decisions often involve research operations, laboratory informatics and facilities teams jointly because the system remains in service across several product-development cycles. Academic institutions, diagnostic laboratories and contract research organisations provide additional demand, particularly when operating volumes justify centralised sample management.
Market Drivers
Rising Requirements for Sample Identity and Preservation
Biobanks supporting multi-year research cannot rely on freezer maps or informal tracking once large numbers of specimens move between studies. Automated inventory records identify the requested tube, its location and the events associated with storage and retrieval. Hamilton and Azenta both integrate identification and software controls with their robotic stores, bringing sample integrity into equipment purchasing rather than leaving it to a separate paper process.
Laboratories evaluating these systems place considerable weight on traceability failures because replacing a valuable research specimen may be impossible. The purchasing case becomes more compelling as collaborating institutions request reproducible sample histories and selective release of archived material.
Expansion of Pharmaceutical Compound Libraries
Large drug-discovery groups repeatedly screen and rescreen selected compounds against different targets, making retrieval frequency a significant operating cost. Storage environments must support many tube and plate formats while allowing precise ordering and return. Azenta SampleArc and Hamilton Verso are designed around automated sample access and operational links to downstream screening tools.
Growth in the range of testing workflows increases the importance of configurable storage software. Laboratories buying additional assay equipment often reassess storage capacity and interfaces to prevent the sample library from constraining screening throughput.
Consolidation of Biorepositories and Shared Research Facilities
Centralising samples previously dispersed across multiple freezers can make temperature monitoring, access permissions and maintenance more consistent. UK Biocentre’s selection of Azenta BioArc Ultra demonstrates the operating scale possible when millions of specimens are brought under automated management. The investment case also depends on the ability to migrate legacy formats while keeping collections available to researchers.
Central repositories are frequently long-lived infrastructure assets. Their procurement tends to favour suppliers capable of phased installations, documented service response and expansion without wholesale replacement of the original storage equipment.
Lower Labour Exposure During Repetitive Retrieval
Manual freezers require technicians to search racks, manage frost accumulation and repeatedly open cold chambers. High-frequency picking is particularly burdensome where a sample bank receives many requests for only a few tubes at a time. Robotic picking can shift those operations into a controlled enclosure, reserving staff time for preparation, quality checks and sample distribution.
The financial effect varies by institution and cannot be estimated from technician wage rates alone. It also includes avoided search errors, queue delays and time devoted to rebuilding incomplete sample inventories.
Efficiency Improvements in Refrigeration and Facility Use
Automated storage vendors are changing refrigeration design as buyers scrutinise the cost of operating ultracold archives. Hamilton’s natural-refrigerant transition and Azenta’s high-density BioArc platform show that manufacturers are competing on operating costs as well as capacity and retrieval performance. Hospitals and biobanks increasingly compare the power and space used by central automated storage against separate manual units.
Savings are strongest where a facility can remove or avoid a meaningful number of older freezers. Sites with modest sample collections may see a weaker economic case, but increasing capacity and ageing equipment create opportunities for replacement projects.
Market Restraints
Large Upfront Commitment and Irregular Project Timing
High-density automated stores involve cold infrastructure, robotics, inventory software, installation services and contingency systems. The initial capital commitment can exceed the budget of a small research laboratory, especially where several existing freezers still have usable life. Procurement may require a multiyear business case rather than a routine equipment replacement request.
Large orders are also sensitive to building readiness and institutional funding cycles. A postponed repository construction project can shift supplier revenue between years even while the long-term need for storage remains unchanged.
Migration of Legacy Tube Formats and Incomplete Records
Older biological collections often contain inconsistent vial geometries, labels, box layouts and freezer inventories. Moving them into robotic storage can require reformatting, relabelling or additional verification, each of which introduces cost and handling risk. Supplier compatibility claims must therefore be tested against the actual historic holdings rather than a representative new tube.
Migration planning becomes particularly difficult when collections must remain accessible throughout the changeover. Laboratories may phase installations or preserve a manual archive for material that cannot be converted economically.
Thermal Failure and Service-Continuity Requirements
A densely populated automated store concentrates substantial sample value in one integrated installation. Cooling redundancy, uninterrupted power, emergency access and supplier response arrangements are essential to reducing the consequences of equipment failure. A technically advanced retrieval robot provides limited protection if refrigeration reliability or recovery procedures are inadequate.
Long service-life expectations place pressure on spare-parts availability and software support. Hospitals and research repositories may prefer a less complex design when they cannot secure suitable local maintenance coverage.
Integration and Data-System Qualification Costs
Automated storage interfaces must exchange reliable sample identifiers and work orders with laboratory information systems. Validation is more demanding when institutions use several legacy databases, custom record fields or independently managed research cohorts. The main difficulty is not simply connecting software systems but preserving correct identity, access rights and transaction history when workflows change.
Commissioning can extend as facilities develop exception-handling processes, audit-record retention policies and user training. As a result, qualified implementation teams and documented interfaces influence vendor selection alongside equipment performance.
Facility Constraints at Cryogenic and Ultra-Low Temperatures
Large automated ultracold or nitrogen-based repositories require space for machinery, heat removal, service access and safety systems. Existing buildings may lack the floor loading, utilities or emergency infrastructure required for these installations. ASKION’s cryogenic configurations illustrate how storage specifications involve nitrogen handling and continuous preservation of the cold chain as well as sample retrieval.
Construction modifications can become a substantial part of project economics. In research centres with limited space or uncertain collection growth, smaller modular units may be adopted instead of a single high-capacity system.
Regional Outlook
North America
North America accounts for an estimated 37% of global revenue in 2026, reflecting extensive pharmaceutical discovery facilities, commercial biorepositories, hospital laboratory networks and research infrastructure in the United States. Hamilton Storage and Azenta maintain prominent North American technology and service operations. Demand includes both replacement of dispersed freezer inventories and purpose-built automated systems associated with clinical specimen banks and large compound collections.
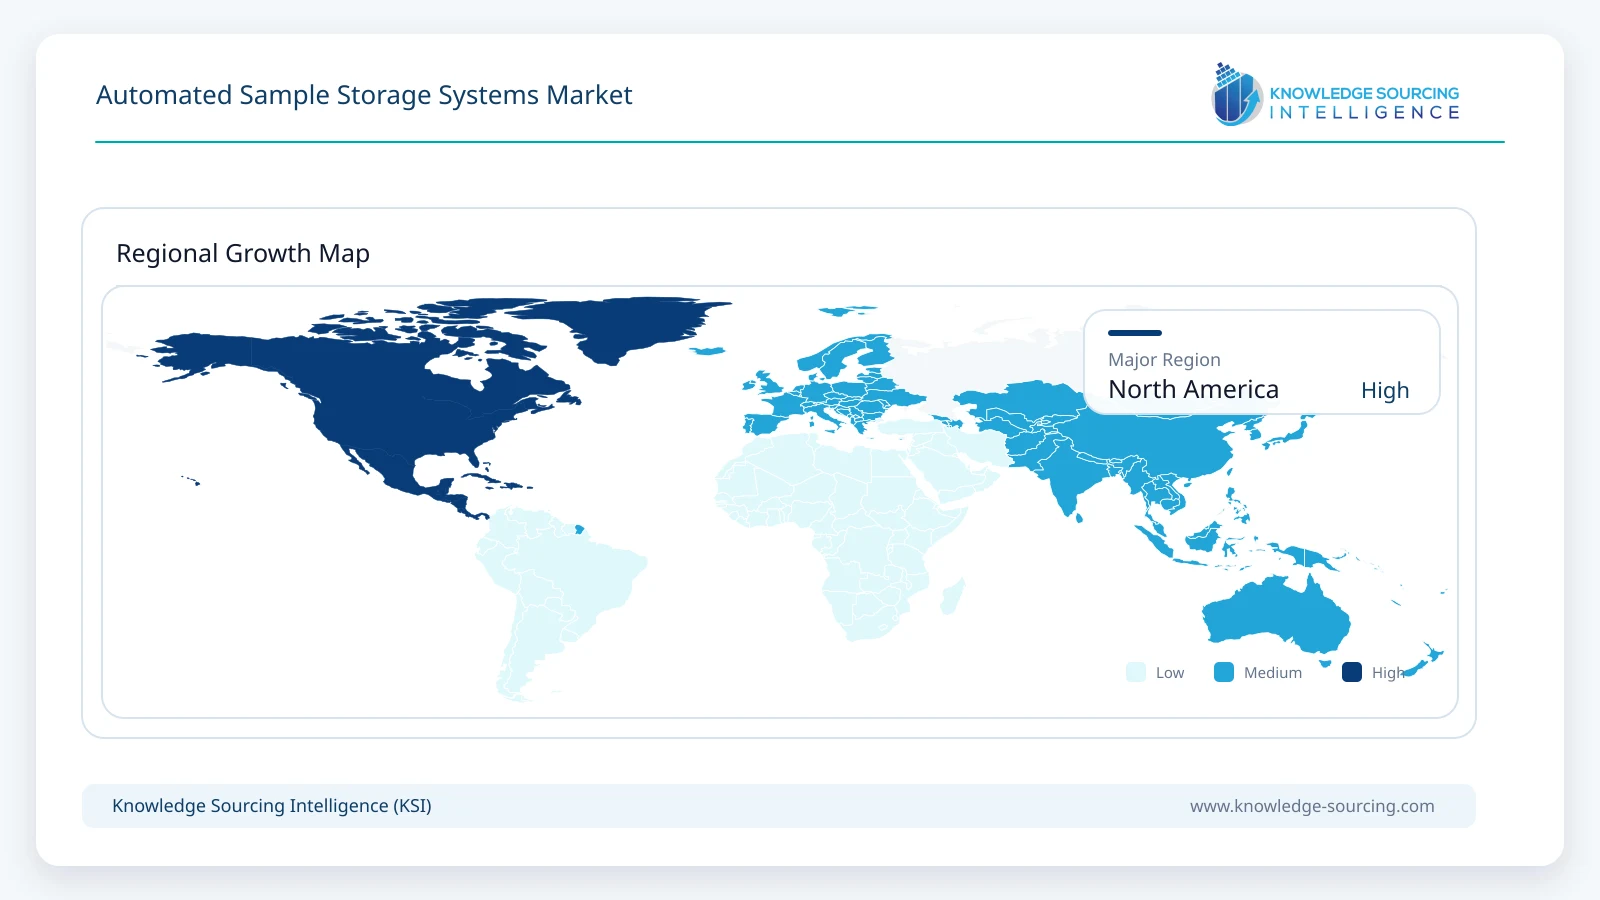
By 2031 the region is projected to represent approximately USD 1.12 billion. Its share moderates as installations grow faster in Asia Pacific, but North American customers retain strong requirements for validated temperature performance, integrated sample informatics and long-term support. Major procurement decisions are likely to depend on repository consolidation economics and continuity of scientific programmes rather than the lowest initial equipment price.
Asia Pacific
Biopharmaceutical capacity expansion, genomic research and the development of institutional sample banks are broadening the purchasing base for automated storage across China, India, Japan and South Korea. Large-scale installations coexist with demand for compact systems suited to hospitals, academic laboratories and newly established research facilities. The presence of regional laboratory automation manufacturers strengthens the available supplier and service network.
Asia Pacific is expected to grow at approximately 16.6% annually during 2026–2031, making it the fastest-growing region. Its expansion is supported by a lower starting penetration of automated specimen repositories and the continuing need to standardise sample identification. Local engineering support, energy infrastructure and affordability will influence whether customers choose high-capacity central stores or distributed modular systems.
Competitive Landscape
The automated-storage market is structured around a relatively small group of specialised engineering suppliers rather than general laboratory freezer manufacturers. Hamilton competes through BiOS and Verso platforms with integration into laboratory robotics and software, while Azenta combines a broad automated-store family with sample-management services and consumables. LiCONiC and ASKION differentiate their offerings through low-temperature handling, labware flexibility and cryogenic automation. SPT Labtech serves compact storage and retrieval applications through its arktic product heritage.
Smaller installations and specialised applications create additional space for Haier Biomedical and Tsubakimoto, both of which supply automated cold-storage or sample-picking technology. Commercial differentiation depends on maintaining stable temperatures during retrieval, accommodating archived specimen formats, supporting verifiable electronic records and delivering reliable local service. Revenue from maintenance and compatible consumables can strengthen supplier relationships long after the initial system is commissioned.
Recent Developments
March 2026: Azenta completed its acquisition of UK Biocentre, adding an established sample-processing and storage operation to its European network and expanding its ability to deploy automated repositories for large research programmes.
February 2026: Hamilton Storage announced that its automated storage portfolio was available with natural refrigerants, extending an efficiency-oriented refrigeration approach across BiOS and other controlled-temperature platforms.
January 2025: Azenta announced that UK Biocentre selected BioArc Ultra for a major repository expansion, adding planned capacity for approximately 16 million samples alongside existing automated stores.
September 2024: Azenta introduced the SampleArc, BioArc and CryoArc names for its automated-storage families and ARCON for its store-controller software, establishing a common platform identity across temperature ranges.
July 2024: Hamilton introduced Verso Dx for automated post-analytical clinical sample storage, combining specimen tracking, controlled-temperature retrieval and options for laboratory-track loading.
Market Outlook
Through 2031, automated sample storage will be shaped by the economics of protecting large collections as much as by new laboratory construction. High-density systems are likely to gain a larger proportion of new project spending where institutions can centralise specimens and justify the expense of sample migration. Compact and modular stores will remain important for laboratories that need traceable retrieval but cannot commit to a dedicated repository building.
The most durable competitive advantages should come from predictable retrieval under defined thermal conditions, support for varied labware, software interoperability and maintenance reliability. Improvements in energy use will matter where automated installations replace dispersed ultracold freezers, while cryogenic systems will follow the needs of cell-focused research and biobanking. Procurement will remain project-sensitive, particularly when customers must coordinate repository facilities, validation and scientific programmes over several budget cycles.
Automated Sample Storage Systems Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.90 billion |
| Total Market Size in 2031 | USD 3.30 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Capacity, Sample Type, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
Manual Systems
Fully Automated Systems
Accessories and Consumables
By Capacity
Small Capacity
Medium Capacity
Large Capacity
By Sample Type
Biological Samples
Chemical Compounds
Environmental Samples
Others
By End User
Pharmaceutical and Biotechnology
Academic and Research Institutions
Hospitals and Diagnostics Centres
CROs
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
UAE
Saudi Arabia
Others
Asia Pacific
China
Japan
South Korea
India
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings and Market Size, 2026–2031
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Rising Requirements for Sample Identity and Preservation
3.1.2. Expansion of Pharmaceutical Compound Libraries
3.1.3. Consolidation of Biorepositories and Shared Research Facilities
3.1.4. Lower Labour Exposure During Repetitive Retrieval
3.1.5. Efficiency Improvements in Refrigeration and Facility Use
3.2. Market Restraints
3.2.1. Large Upfront Commitment and Irregular Project Timing
3.2.2. Migration of Legacy Tube Formats and Incomplete Records
3.2.3. Thermal Failure and Service-Continuity Requirements
3.2.4. Integration and Data-System Qualification Costs
3.2.5. Facility Constraints at Cryogenic and Ultra-Low Temperatures
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Automated Retrieval and Sample Identification
4.2. Ultra-Low and Cryogenic Storage Systems
4.3. Software Interfaces and Laboratory Informatics
4.4. Refrigeration Efficiency and Redundancy
5. AUTOMATED SAMPLE STORAGE SYSTEMS MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Manual Systems
5.3. Fully Automated Systems
5.4. Accessories and Consumables
6. AUTOMATED SAMPLE STORAGE SYSTEMS MARKET BY CAPACITY
6.1. Introduction
6.2. Small Capacity
6.3. Medium Capacity
6.4. Large Capacity
7. AUTOMATED SAMPLE STORAGE SYSTEMS MARKET BY SAMPLE TYPE
7.1. Introduction
7.2. Biological Samples
7.3. Chemical Compounds
7.4. Environmental Samples
7.5. Others
8. AUTOMATED SAMPLE STORAGE SYSTEMS MARKET BY END-USER
8.1. Introduction
8.2. Pharmaceutical and Biotechnology
8.3. Academic and Research Institutions
8.4. Hospitals and Diagnostics Centres
8.5. CROs
9. AUTOMATED SAMPLE STORAGE SYSTEMS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Country
9.2.1.1. USA
9.2.1.2. Canada
9.2.1.3. Mexico
9.3. South America
9.3.1. By Country
9.3.1.1. Brazil
9.3.1.2. Argentina
9.3.1.3. Others
9.4. Europe
9.4.1. By Country
9.4.1.1. Germany
9.4.1.2. France
9.4.1.3. United Kingdom
9.4.1.4. Spain
9.4.1.5. Others
9.5. Middle East and Africa
9.5.1. By Country
9.5.1.1. UAE
9.5.1.2. Saudi Arabia
9.5.1.3. Others
9.6. Asia Pacific
9.6.1. By Country
9.6.1.1. China
9.6.1.2. Japan
9.6.1.3. South Korea
9.6.1.4. India
9.6.1.5. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Hamilton Company (Hamilton Storage)
11.2. Azenta, Inc. (Azenta Life Sciences)
11.3. LiCONiC AG
11.4. ASKION GmbH
11.5. SPT Labtech Ltd.
11.6. Haier Biomedical
11.7. Tsubakimoto Chain Co.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for automated sample storage systems?
Market to reach $3.30 billion by 2031, growing at 11.7% CAGR.
Which sample type drives the highest demand?
Biological samples contribute an estimated 58% of overall demand.
What platform type holds the largest market share?
Fully automated platforms represent 65% of the 2026 market value.
Which region leads the market for automated sample storage systems?
North America remains the leading market, followed by Asia Pacific.
Who are the principal purchasers of these systems?
Pharmaceutical and biotechnology companies are the primary purchasing group.
What factors increasingly shape supplier selection?
Integrated software, thermal stability, and service resilience are key factors.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Automated Sample Storage Systems Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automated-sample-storage-systems-market