
The Autonomous Vehicle Robotics Components Market is expected to grow at a high CAGR over the forecast period.
Highlights:
- 1ADAS provides the volume foundationMandatory and increasingly sophisticated driver-assistance functions create component demand before widespread Level 4 deployment.
- 2High-performance computing is gaining strategic importanceAutonomous systems require substantial real-time processing capacity for sensor fusion, perception, planning, and vehicle control.
- 3LiDAR remains important for higher automationProduction and development programs continue to use LiDAR where precise three-dimensional perception and redundancy are commercially justified.
- 4North America remains a major development and deployment centerU.S. federal safety oversight and state-level testing and deployment frameworks support continued technology validation.
- 5Regulation is shaping component specificationsSafety, cybersecurity, data reporting, type approval, and automated-driving requirements influence component selection and system architecture.
- 6Platform integration is becoming a competitive differentiatorSuppliers increasingly combine processors, sensors, software, validation, and safety capabilities rather than competing solely on individual components.
The Autonomous Vehicle Robotics Components Market covers the hardware and software technologies that enable vehicles to perceive their surroundings, determine position, process sensor information, make driving decisions, and execute vehicle-control functions with limited or no human intervention. The market spans cameras, LiDAR, radar, ultrasonic sensors, GNSS and inertial measurement units, automotive semiconductors, processors, domain controllers, and supporting software.
Its commercial boundary sits between conventional automotive electronics and autonomous mobility systems. Components are increasingly purchased as integrated computing and sensing architectures rather than as isolated parts. This shift changes supplier economics because automakers now evaluate sensor accuracy, computing performance, functional safety, cybersecurity, thermal characteristics, software compatibility, upgradeability, and lifecycle support together.
Demand exists across passenger vehicles, commercial vehicles, robotaxis, automated shuttles, delivery vehicles, logistics fleets, and specialized vehicles operating in controlled environments. The commercial case differs substantially by application. Passenger vehicles prioritize cost, packaging, energy consumption, safety ratings, and feature scalability. Commercial operators place greater weight on uptime, route availability, fleet utilization, redundancy, remote supervision, maintenance, and total cost of ownership.
The most immediate volume opportunity is not necessarily fully autonomous Level 4 or Level 5 vehicles. Components are also entering vehicles through Level 0–2 safety and driver-assistance functions. Regulatory requirements are reinforcing this installed base. The European Commission states that new vehicles sold in the European Union have required multiple advanced driver-assistance features since July 2024, including intelligent speed assistance, reversing detection, attention warnings, emergency stop signals, and, for cars and vans, lane-keeping and automated braking systems.
This creates two distinct procurement channels. The first is high-volume ADAS deployment, where automakers demand lower unit costs, high reliability, and semiconductor efficiency. The second is high-autonomy deployment, where suppliers compete on sensor redundancy, perception performance, compute capacity, safety certification, validation tools, and system integration.
The hardware category therefore remains commercially central, while software captures a growing share of system value. A modern autonomous architecture can require multiple cameras, radar units, LiDAR, ultrasonic sensors, high-performance processors, networking components, storage, positioning equipment, and safety-related controllers. NVIDIA's current DRIVE Hyperion architecture illustrates the component intensity of higher automation, combining multiple cameras, radars, LiDAR and ultrasonic sensors with high-performance in-vehicle computing.
Buyer behavior is also changing. Automakers increasingly prefer platforms that can support several vehicle programs rather than one-off engineering solutions. A common compute architecture can reduce validation duplication and simplify software deployment across vehicle variants. At the same time, Tier-1 suppliers and semiconductor companies are attempting to move closer to system-level offerings because individual component differentiation becomes harder when perception, compute, and software operate as one safety-critical system.
The revenue opportunity consequently depends on more than autonomous vehicle production volumes. It is influenced by the number of sensing channels per vehicle, computing requirements, redundancy levels, software content, regulatory equipment requirements, and the degree to which components become standard equipment rather than optional features.
Market Drivers
Expansion of Advanced Driver-Assistance Content
The strongest near-term demand mechanism is the expansion of vehicle safety functionality below full autonomy. Automakers can commercialize cameras, radar, ultrasonic sensors, processors, and software at much higher volumes through Level 0–2 applications than through Level 4 robotaxis alone.
The European Union provides a clear regulatory example. Its General Safety Regulation requires new vehicles to incorporate multiple assistance and monitoring technologies, creating a structural equipment requirement rather than relying entirely on consumer willingness to pay.
For component suppliers, this changes the sales proposition. Winning a high-volume ADAS program can provide significantly larger production volumes than an early robotaxi program. Suppliers therefore need architectures that can scale from entry-level safety functions toward higher automated-driving configurations.
Rising Computational Requirements Inside Vehicles
Autonomous driving requires continuous processing of data from multiple sensors under strict latency and safety constraints. As sensor counts increase and perception algorithms become more computationally demanding, conventional distributed electronic architectures become less attractive for advanced programs.
This supports demand for automotive processors, domain controllers, high-speed networking, memory, and specialized AI accelerators. NVIDIA's current platform strategy demonstrates the direction of the market: its DRIVE architecture combines in-vehicle computing with a validated multimodal sensor suite and software stack for applications extending from advanced driver assistance toward Level 4 autonomy.
For automakers, compute procurement is increasingly tied to software roadmaps. A processor selected today must provide sufficient headroom for future functions while remaining within vehicle power and thermal limits. This favors scalable architectures and creates opportunities for semiconductor suppliers with long automotive qualification cycles.
Commercial Deployment of Higher-Level Automation
Level 3 and Level 4 deployment creates a different demand profile from conventional ADAS. Higher automation requires greater redundancy, more sophisticated perception, stronger computing capability, and extensive validation.
The commercial case is particularly attractive where vehicles operate in defined operating domains. Japan, for example, has supported Level 4 deployment through regulatory and subsidy mechanisms. Japan's Ministry of Land, Infrastructure, Transport and Tourism reports that its FY2025 autonomous-mobility implementation program supported multiple municipalities and that Level 4 services had already moved into practical operation in specific areas.
Specialized applications can therefore reach commercial deployment before unrestricted autonomous passenger vehicles. Airports, logistics facilities, fixed shuttle routes, and other controlled environments reduce the complexity of the operating domain and allow suppliers to validate component configurations against narrower requirements.
Increasing Demand for Sensor Redundancy
Autonomous systems cannot depend on a single perception modality for every operating condition. Cameras provide visual information, radar performs well in adverse weather and provides velocity measurements, LiDAR contributes three-dimensional spatial information, and ultrasonic sensing supports close-range detection.
This creates a multi-sensor procurement environment. The value proposition is not simply sensor quantity but complementary coverage and failure tolerance.
NVIDIA's production-oriented Hyperion architecture demonstrates this approach by combining cameras, radar, LiDAR, and ultrasonic sensing with redundant computing and safety mechanisms.
Suppliers capable of demonstrating reliable performance across the complete sensing architecture can therefore gain an advantage over vendors selling technically strong but difficult-to-integrate individual components.
Market Restraints and Challenges
High System Cost and Vehicle-Level Economics
Autonomous systems can add substantial hardware, computing, software, validation, and maintenance costs. This creates a difficult economic equation for passenger vehicles, where customers remain price-sensitive and automakers must justify expensive hardware against expected feature utilization.
The challenge is particularly acute for LiDAR and high-performance compute. Their inclusion must deliver sufficient safety, functionality, or differentiation to justify additional bill-of-materials cost.
Suppliers are responding by reducing component size, integrating functions, lowering power consumption, and developing scalable architectures. NXP's June 2026 radar SoC announcement, for example, emphasized reduced system cost and simplified thermal management for L2/L2+ applications.
Functional Safety and Validation Requirements
Autonomous components operate within safety-critical systems. Hardware failures, sensor degradation, software errors, communication faults, or incorrect environmental interpretation can affect vehicle control.
Consequently, procurement decisions extend beyond conventional performance metrics. Automakers evaluate functional safety processes, redundancy, diagnostic capability, cybersecurity, validation evidence, failure handling, and software lifecycle support.
NHTSA's automated-vehicle framework also illustrates the importance of real-world safety evidence. Its amended Standing General Order requires specified manufacturers and operators to report qualifying incidents involving ADS and Level 2 ADAS. The third amendment became effective June 16, 2025.
The commercial implication is clear: suppliers must support extensive documentation and validation throughout the vehicle lifecycle, increasing development costs and qualification barriers.
Semiconductor and Component Supply Constraints
Autonomous vehicles require processors, memory, power-management devices, radar chips, communication components, imaging devices, and other electronics. These components must satisfy automotive qualification and long lifecycle requirements.
Supply disruptions can therefore affect vehicle production disproportionately because replacing a qualified semiconductor is not equivalent to replacing a conventional commodity component. Hardware changes can trigger software, thermal, electromagnetic, safety, and validation work.
Suppliers with diversified manufacturing and established automotive qualification processes can reduce this exposure. Automakers are also increasingly seeking platform standardization to reduce the number of unique electronic configurations across vehicle programs.
Regulatory Fragmentation
Autonomous-driving rules remain geographically differentiated. The United States combines federal vehicle-safety oversight with state-level testing and deployment permissions. Europe operates through a type-approval framework with specific technical rules. Asian markets use their own combinations of road-traffic, vehicle-safety, and pilot-program regulations.
This affects suppliers because a component architecture approved for one market may require additional validation or modifications elsewhere.
California illustrates the complexity. As of August 12, 2026, the California Department of Motor Vehicles listed multiple organizations with autonomous-vehicle testing permits and separate authorizations for driverless testing and deployment under specified operating conditions.
Major Segment Analysis
Hardware
Hardware represents the most commercially important component segment because autonomous driving depends on a physical perception-and-compute architecture before software can generate vehicle-level functionality.
The segment includes cameras, LiDAR, radar, ultrasonic sensors, GNSS and IMU systems, semiconductors and processors, automotive computing and domain controllers, and associated hardware. Each category serves a different layer of the vehicle's perception and decision architecture.
Cameras remain commercially attractive because they provide rich visual information and support multiple applications, including object recognition, lane interpretation, traffic-sign recognition, driver monitoring, and parking. Their relatively mature automotive supply chain also supports integration into high-volume ADAS programs.
Radar provides a complementary sensing capability. It can measure range and relative velocity and remains valuable in conditions where optical sensing can be constrained. Continental reported in May 2025 that it had produced 200 million radar sensors, illustrating the scale already achieved by automotive radar supply chains.
LiDAR occupies a different position. Its higher cost historically limited broad passenger-vehicle adoption, but higher automation increases the value of detailed three-dimensional sensing. Valeo reported in January 2025 that its SCALA LiDAR had already entered passenger-car production and highlighted its deployment in Mercedes-Benz's Drive Pilot system.
The strongest commercial change, however, is occurring in computing. Higher automation increases the amount of sensor data that must be processed locally with predictable latency. Domain controllers consolidate functions that previously relied on numerous electronic control units, allowing automakers to manage increasingly centralized vehicle architectures.
The buyer's decision is therefore shifting from individual component specifications toward system economics. A processor that delivers higher performance but imposes excessive power or thermal requirements may not be commercially attractive. Likewise, a sensor with strong technical specifications may lose a vehicle program if its packaging, software interface, diagnostics, or validation requirements increase integration costs.
Supplier differentiation increasingly rests on complete development ecosystems. NVIDIA's Hyperion architecture, for example, combines sensors, computing, software, safety mechanisms, and development infrastructure.
This integration trend favors suppliers that can demonstrate production readiness, automotive-grade reliability, software compatibility, safety compliance, and global support. It also increases the strategic importance of partnerships between semiconductor companies, Tier-1 suppliers, automakers, and specialized sensor developers.
Regional Analysis
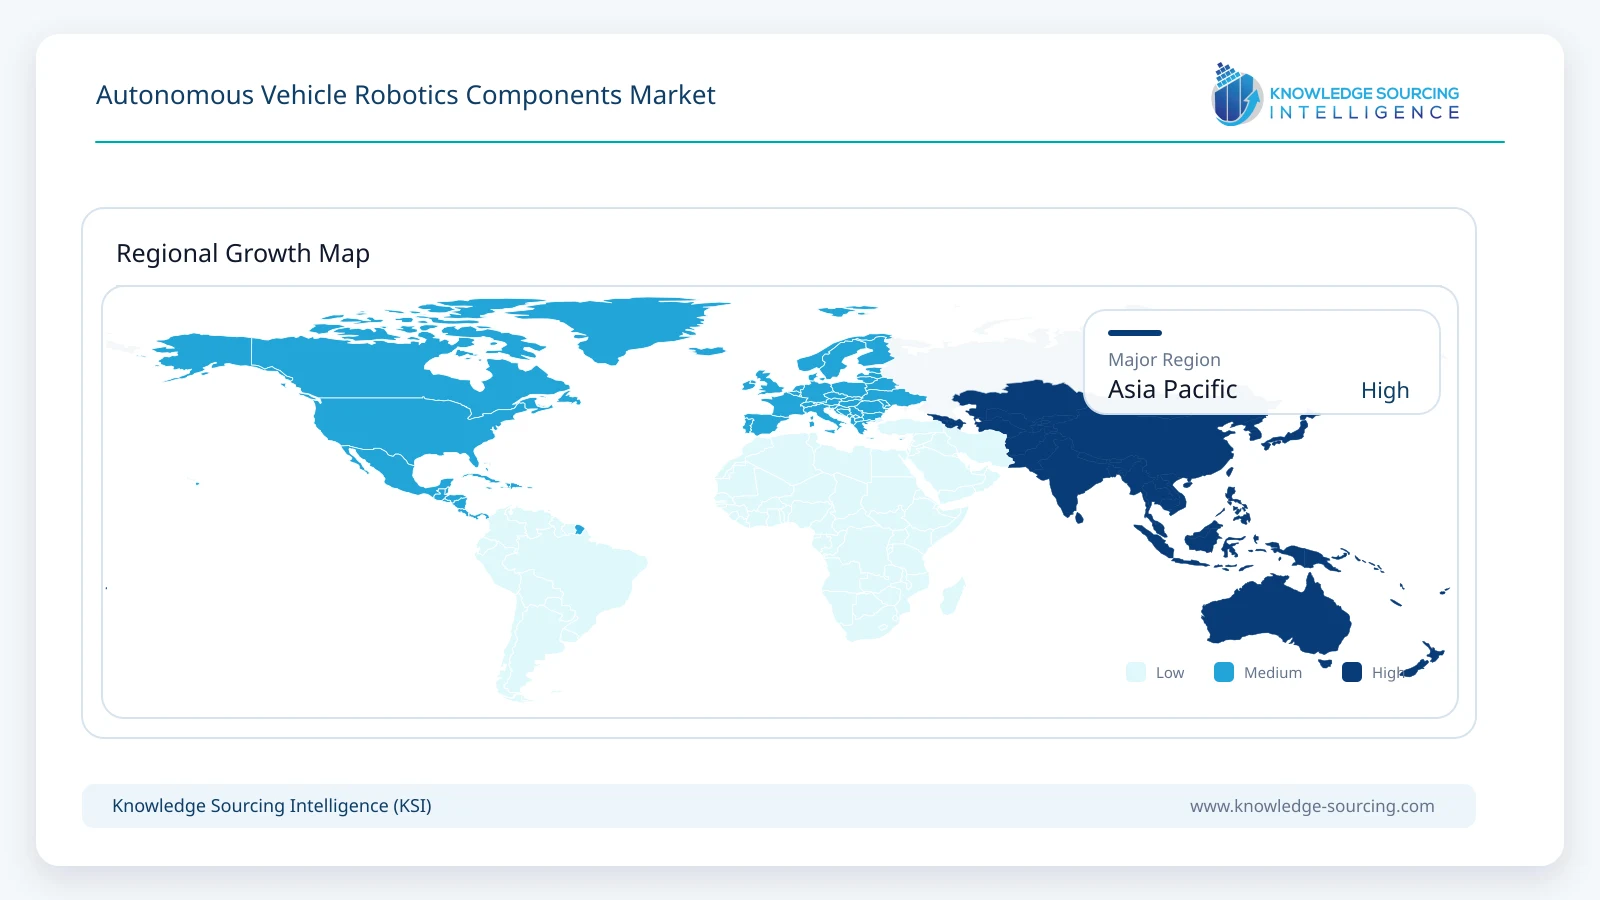
North America
North America remains an important market because the United States combines advanced automotive electronics development, major semiconductor companies, autonomous-vehicle testing, and substantial technology investment.
The U.S. regulatory environment is particularly influential. NHTSA's Standing General Order provides federal authorities with structured crash information from specified ADS and Level 2 ADAS systems. The agency's 2025 framework also initiated work to modernize federal vehicle-safety standards for automated vehicles.
California remains an important deployment and testing center. Its permitting framework creates defined operating domains and therefore provides a practical route for validating autonomous systems under real traffic conditions.
Canada contributes through automotive manufacturing and technology development, while Mexico provides manufacturing relevance through its integration into North American vehicle supply chains. The region's principal constraint remains regulatory and commercial uncertainty surrounding large-scale Level 4 passenger-vehicle deployment.
Europe
Europe has a strong installed base of automotive electronics suppliers and a regulatory framework that directly influences ADAS content.
The EU General Safety Regulation has already made several assistance technologies mandatory for new vehicles. The Commission also maintains technical legislation governing fully automated vehicles, including Level 4 systems.
Germany remains particularly important because of its vehicle-manufacturing base and established automated-driving development programs. France, the United Kingdom, Italy, and Spain provide additional demand through automotive production, logistics, mobility services, and government-supported testing.
European buyers place considerable emphasis on functional safety, cybersecurity, type approval, and regulatory conformity. This can increase qualification requirements but also favors suppliers with mature automotive engineering and compliance capabilities.
Asia Pacific
Asia Pacific combines large vehicle production volumes with government-backed autonomous-mobility programs and substantial semiconductor capability.
China represents a major demand center because of its vehicle production scale and development of intelligent connected vehicles. Japan has established a regulatory path for Level 4 vehicles and continues to support implementation programs. Japan's MLIT reports that the country amended vehicle legislation for Level 3 systems, established Level 4 safety standards, and supported municipal Level 4 mobility implementation.
In June 2026, Japan also announced agreement at the UN World Forum for Harmonization of Vehicle Regulations on international automated-driving requirements covering Level 3 and Level 4 systems. The requirements address traffic-rule compliance, collision avoidance, safe stopping, organizational safety processes, monitoring, and defect improvement, with an expected entry into force around January 2027.
South Korea benefits from automotive manufacturing and semiconductor capabilities, while India offers long-term potential through vehicle production, commercial mobility, and expanding electronic-content requirements. Thailand adds importance through its automotive manufacturing ecosystem.
The principal regional challenge is uneven deployment readiness. Technology capability can advance faster than infrastructure, regulatory authorization, mapping, fleet economics, and consumer acceptance.
Middle East & Africa
The Middle East is developing autonomous-mobility programs around smart-city initiatives, logistics, public transport, and controlled operating environments. The UAE and Saudi Arabia are particularly relevant because large-scale mobility projects can provide suitable environments for pilot deployments.
Commercial opportunities are likely to concentrate on fleet applications rather than unrestricted consumer autonomy during the earlier stages. Controlled routes, defined service areas, and managed infrastructure can reduce system complexity.
Africa remains more fragmented. Demand depends heavily on urban infrastructure, vehicle affordability, public transport requirements, and availability of investment capital. Component suppliers are therefore more likely to encounter specialized fleet opportunities than broad passenger-vehicle penetration.
South America
South America represents a smaller autonomous-component opportunity than North America, Europe, or Asia Pacific, but Brazil provides the strongest regional base through its automotive manufacturing sector and large domestic vehicle market.
Adoption is likely to follow the global progression from safety and driver-assistance functions toward higher automation. Commercial fleets, logistics, mining, agriculture, and controlled industrial environments may provide more practical early opportunities than unrestricted urban autonomy.
Cost sensitivity remains a major constraint. Suppliers therefore need scalable solutions that can provide safety functionality without imposing premium hardware costs that vehicle buyers cannot absorb.
Competitive Landscape
The competitive structure includes semiconductor manufacturers, automotive Tier-1 suppliers, sensing specialists, computing-platform providers, and integrated mobility technology companies.
The supplied competitive universe—NVIDIA Corporation, Intel Corporation, Aptiv, Valeo, Aeva Technologies, Inc., Qualcomm Incorporated, Denso Corporation, Magna International, NXP Semiconductors, Robert Bosch GmbH, and Continental AG—covers these different competitive layers.
Competition increasingly centers on system integration rather than isolated component performance. NVIDIA and Qualcomm emphasize computing platforms and software ecosystems. NXP competes through automotive semiconductors and sensing technologies. Aeva and Valeo occupy important positions in LiDAR and perception. Bosch, Continental, Denso, Aptiv, Magna, and Valeo can compete through broader vehicle-system integration and Tier-1 relationships.
Partnerships are consequently important because autonomous driving requires multiple technology domains to operate as one validated system. Magna's March 2025 collaboration with NVIDIA provides a direct example: Magna announced integration of NVIDIA DRIVE AGX based on the DRIVE Thor SoC into next-generation automotive technology solutions for ADAS and autonomous driving.
Qualcomm has pursued a similar platform strategy. Its Snapdragon Ride portfolio combines scalable SoCs, software, AI processing, and mixed-criticality capabilities. In September 2025, Qualcomm introduced Snapdragon Ride Pilot, developed with BMW, with an architecture designed to scale ADAS capabilities across highway and urban applications.
This competitive structure favors suppliers capable of securing design wins early in vehicle development. Once a component becomes embedded into an automotive architecture, qualification, software integration, and validation create switching costs. Consequently, engineering relationships and platform compatibility can be as commercially important as component specifications.
Recent Developments
August 2026: Waymo revealed its purpose-built 5nm ASIC for autonomous-driving compute, delivering over 1,000 TOPS for processing and fusing lidar, radar, and camera data in real time.
July 2026: Qualcomm was selected by BMW Group as its lead compute silicon provider for next-generation digital cockpit and automated-driving systems, extending the collaboration through the next decade.
May 2026: Ouster announced its Rev8 OS digital lidar sensors were qualified for NVIDIA DRIVE Hyperion, supporting Level 4 autonomous-vehicle development with native-color lidar capabilities.
April 2026: Innoviz launched InnovizTwo Ultra Long-Range LiDAR with sensing capability up to one kilometer, targeting robotaxis, heavy trucks, and other autonomous physical-AI applications.
March 2026: NVIDIA announced BYD, Geely, Isuzu, and Nissan were adopting DRIVE Hyperion for Level 4 vehicles, combining centralized compute with cameras, radar, lidar, and safety technologies.
Regulatory and Policy Environment
Regulation is becoming a direct determinant of component demand because authorities increasingly specify safety functions, validation expectations, incident reporting, and technical requirements.
In the United States, NHTSA's third amended Standing General Order became effective on June 16, 2025. It requires specified entities to report qualifying incidents involving ADS and Level 2 ADAS. This creates a continuing data and compliance obligation for manufacturers and operators and increases the importance of traceability within autonomous systems.
The U.S. regulatory framework also remains subject to modernization. In September 2025, NHTSA announced three rulemakings intended to modernize Federal Motor Vehicle Safety Standards for vehicles equipped with automated driving systems.
Europe has a more established type-approval structure. Regulation EU 2019/2144 introduced mandatory advanced safety technologies, while subsequent legislation provides technical rules for automated and fully driverless vehicles. The European Commission notes that technical legislation specifically addresses fully driverless Level 4 vehicles.
In March 2026, the European Commission also listed Implementing Regulation EU 2026/481, which amends the procedures and technical specifications for type approval of automated driving systems in fully automated vehicles.
Japan is also strengthening the international regulatory framework. In June 2026, MLIT reported agreement on international automated-driving standards covering Level 3 and Level 4 systems, including requirements for safe stopping, collision avoidance, organizational safety processes, monitoring, and defect correction.
For component suppliers, these rules affect product design directly. Sensors require defined performance and diagnostic characteristics. Processors need safety and cybersecurity considerations. Software requires traceability and validation. Manufacturers must also demonstrate that system behavior remains within the approved operating domain.
The result is a market where regulatory compliance is not a downstream legal exercise. It increasingly forms part of the product specification and procurement process.
Outlook and Strategic Implications
The 2026–2031 period should be assessed as a transition from component experimentation toward repeatable vehicle architectures. The most attractive suppliers will not necessarily be those with the highest-performing individual sensor or processor. They will be those that can meet automotive production requirements while supporting multiple automation levels.
Procurement is likely to favor scalable architectures. Automakers want to avoid developing entirely different electronic platforms for every automation tier. A common architecture that supports Level 2 functions today and higher automation later can spread engineering and validation expenditure across larger vehicle volumes.
Computing capacity will remain a central investment priority. As sensor fusion, perception, planning, and AI-based decision systems become more computationally intensive, domain controllers and automotive SoCs will capture greater strategic importance. Suppliers will compete on performance per watt, thermal efficiency, functional safety, software support, and upgradeability rather than raw processing capability alone.
Sensor procurement will remain diversified. Cameras and radar are likely to benefit from high-volume ADAS deployment, while LiDAR demand should remain more concentrated in higher-automation programs where its additional cost can be justified. Ultrasonic sensing will retain importance in short-range applications, particularly parking and low-speed maneuvering.
Commercial-vehicle applications deserve particular attention. Fleet operators can evaluate autonomous systems through utilization, labor requirements, safety performance, route consistency, and operating cost. This produces a different purchasing logic from private consumers and may allow higher-cost autonomous hardware to achieve economic justification sooner in selected applications.
Regulatory convergence could reduce engineering duplication over time, but differences in operating domains and approval procedures will remain important. The June 2026 international agreement on automated-driving standards provides a constructive direction, yet suppliers will still need market-specific compliance strategies.
The principal strategic risk is overinvestment in hardware architectures that cannot achieve sufficient vehicle-level economics. Suppliers must therefore demonstrate measurable benefits in safety, operating efficiency, system performance, or regulatory compliance.
A second risk concerns technological concentration. When automakers standardize around a small number of computing and software architectures, suppliers outside those ecosystems can face substantial barriers to entry. Conversely, open and scalable platforms can create opportunities for specialized sensor companies to become qualified ecosystem suppliers.
The competitive opportunity therefore lies in interoperability. Suppliers that design sensors, processors, software, and controllers to integrate cleanly into multiple vehicle architectures can address a broader customer base. Partnerships will remain important because no single component company can independently cover every layer of the autonomous vehicle stack.
Overall, the market's commercial development through 2031 will depend on the intersection of ADAS volume, higher-level autonomy deployment, semiconductor economics, sensor cost reduction, regulatory approval, and vehicle-level return on investment. The transition toward autonomy is therefore likely to be commercially strongest where component suppliers can connect technological performance with measurable vehicle economics.
For executive decision-makers, three priorities stand out. First, suppliers should protect high-volume ADAS programs while developing higher-automation technologies. Second, automakers should evaluate component platforms on lifecycle economics rather than initial hardware cost. Third, investors and technology providers should prioritize applications with defined operating domains, repeatable procurement requirements, and clear regulatory pathways.
Data-source basis: Government and regulatory evidence used above includes NHTSA, the European Commission, UNECE/UN vehicle-regulation processes, California DMV, and Japan's MLIT. Company-specific evidence is drawn only from official company materials and releases. No syndicated market-research source has been used.
Autonomous Vehicle Robotics Components Market Scope:
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Level Of Driving Automation, Vehicle Type, Geography |
| Companies |
|
Market Segmentation
By Component
By Level Of Driving Automation
By Vehicle Type
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Sensor Fusion
4.2. Artificial Intelligence and Machine Learning
4.3. Automotive Computing and Domain Controllers
4.4. LiDAR, Radar, and Camera Technologies
4.5. Vehicle-to-Everything (V2X) Connectivity
4.6. Edge Computing and Real-Time Processing
4.7. Software-Defined Vehicles and Over-the-Air Updates
5. AUTONOMOUS VEHICLE ROBOTICS COMPONENTS MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.2.1. Cameras
5.2.2. LiDAR
5.2.3. Radar
5.2.4. Ultrasonic Sensors
5.2.5. GNSS and IMU
5.2.6. Semiconductors and Processors
5.2.7. Automotive Computing and Domain Controllers
5.2.8. Other Hardware Components
5.3. Software
6. AUTONOMOUS VEHICLE ROBOTICS COMPONENTS MARKET BY LEVEL OF DRIVING AUTOMATION
6.1. Introduction
6.2. Level 0
6.3. Level 1
6.4. Level 2
6.5. Level 3
6.6. Level 4
6.7. Level 5
7. AUTONOMOUS VEHICLE ROBOTICS COMPONENTS MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Passenger Vehicles
7.3. Commercial Vehicles
8. AUTONOMOUS VEHICLE ROBOTICS COMPONENTS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Thailand
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
9.5. Competitive Positioning
10. COMPANY PROFILES
10.1. NVIDIA Corporation
10.2. Intel Corporation
10.3. Aptiv
10.4. Valeo
10.5. Aeva Technologies, Inc.
10.6. Qualcomm Incorporated
10.7. Denso Corporation
10.8. Magna International
10.9. NXP Semiconductors
10.10. Robert Bosch GmbH
10.11. Continental AG
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base Year and Forecast Period
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











