
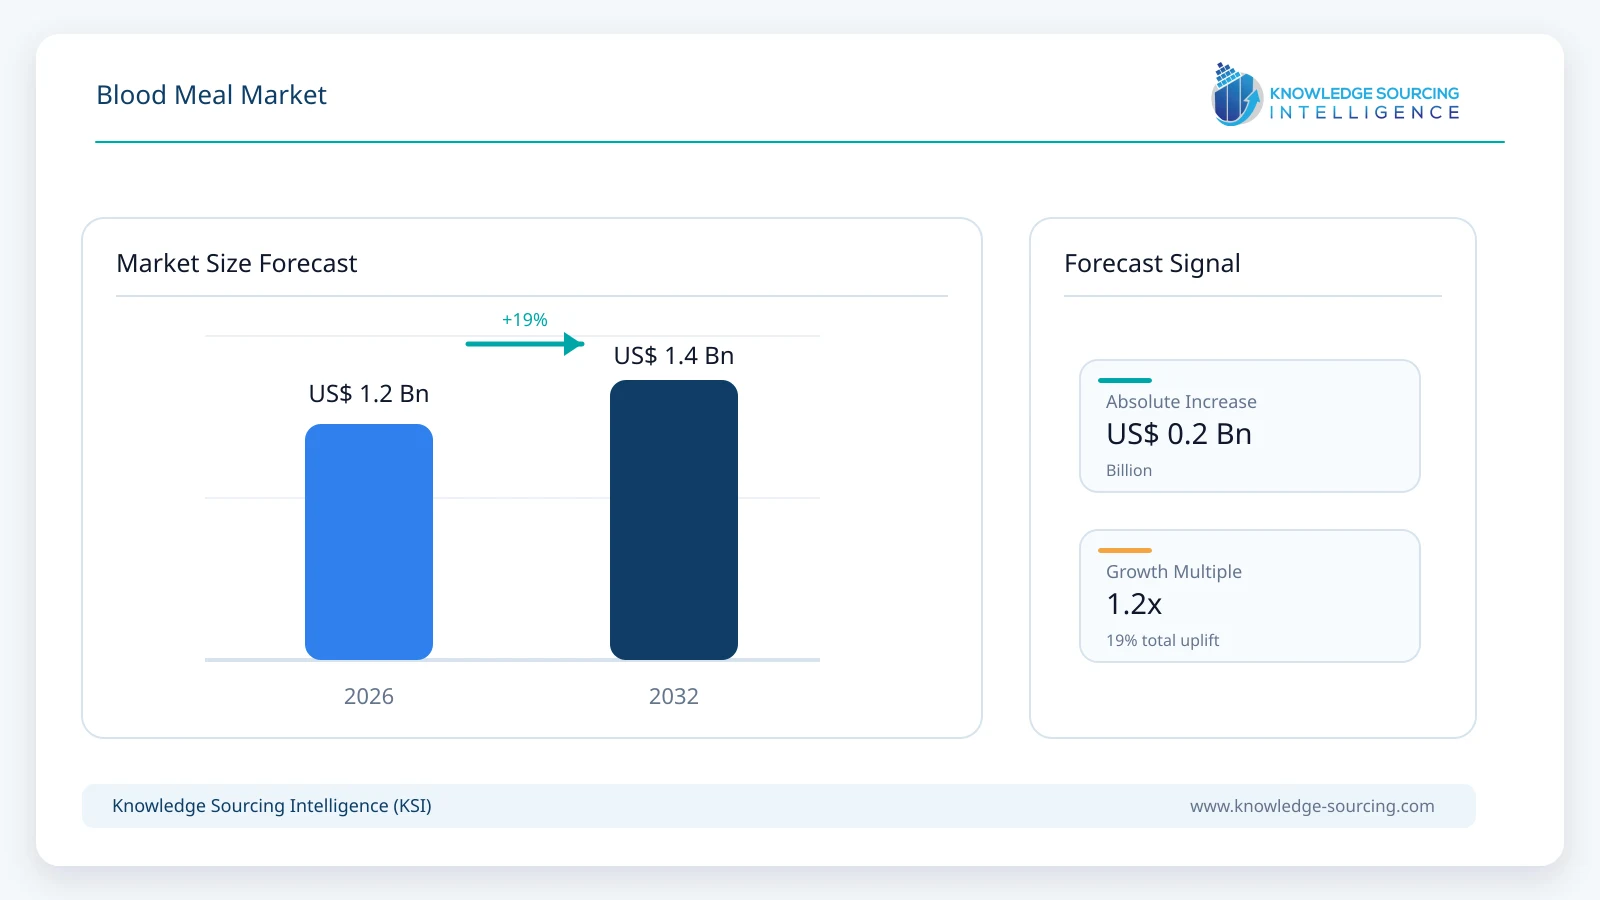
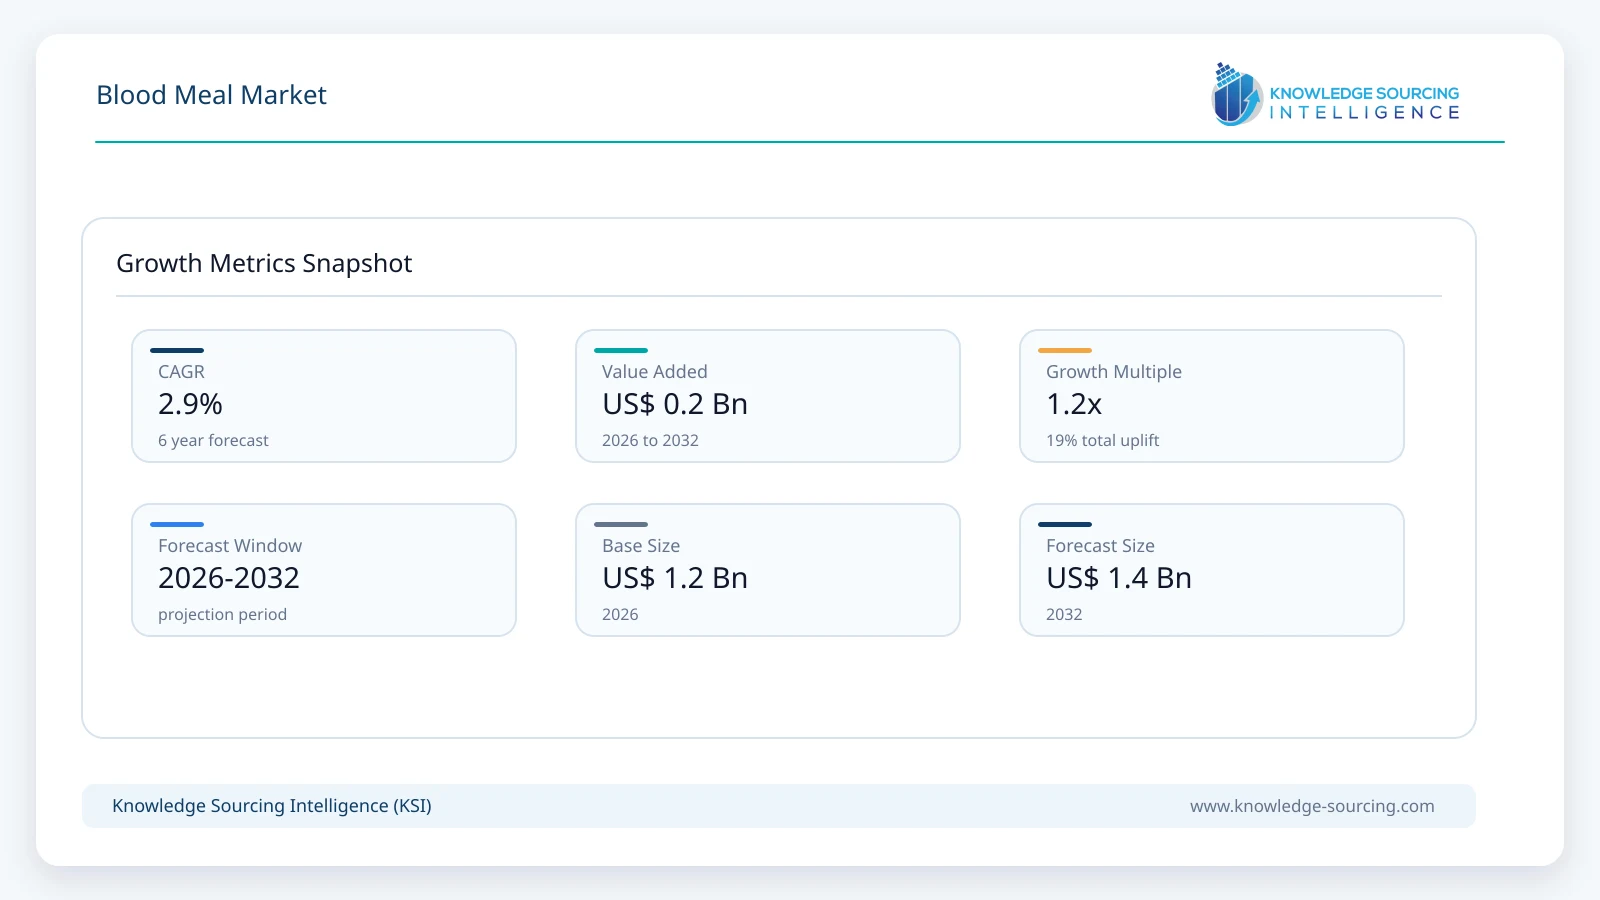
The Blood Meal Market is estimated to increase from USD 1.18 billion in 2026 to USD 1.40 billion in 2032, representing a 2.9% CAGR during the forecast period.
Highlights:
- 1The global merchant market is estimated at US$1.18 billion in 2026 and US$1.40 billion by 2032, equivalent to 2.91% CAGR.
- 2Porcine-derived blood meal accounts for an estimated 46.3% of 2026 revenue, the one source segment selected for the detailed commercial analysis.
- 3Animal slaughter sets the raw-material ceiling, while blood recovery, hygienic collection and dryer capacity determine the merchant supply actually available.
- 4Protein pricing depends on digestible amino-acid value and feed-formulation economics rather than headline crude-protein content.
- 5Cross-species eligibility, traceability and feed-safety requirements constrain the accessible customer base in different jurisdictions.
- 6Higher-value plasma and separated blood fractions must be distinguished from conventional dried whole-blood meal to avoid double-counting.
Demand arises from specialized animal nutrition, aquaculture feed and organic soil amendments, but physical availability originates in slaughterhouses rather than in independently expandable protein manufacturing. Finished meal is produced by collecting blood, controlling microbial quality, removing water and selling the stabilized material into a legally permitted application. Commercial supply therefore depends on the intersection of slaughter throughput, collection systems, drying economics and feed-customer acceptance.
The distinction between blood meal and more processed blood products is commercially significant. Spray-dried plasma and separated red-cell concentrates can command different applications and prices, and they are not substitutes for the whole-blood meal counted in this study. The strongest manufacturing economics are generally associated with plants capable of collecting predictable volumes while limiting storage time and transport costs. Market development is thus uneven: higher livestock slaughter does not automatically generate proportionately more saleable meal, particularly where regulatory, hygiene or processing capacity constraints limit recovery. A sound procurement decision must consider usable protein quality and delivered cost, not gross protein concentration alone.
Market Dynamics
Protein density meets an amino-acid constraint
Blood meal can deliver high concentrations of protein and lysine, making it a useful complement to cereal-based diets that are comparatively short of certain amino acids. Yet crude protein percentage is a poor standalone measure of commercial value because blood meal may be deficient in isoleucine and its digestibility varies with the process used. Overheating during drying can damage amino acids, while inadequate treatment raises microbiological risks, requiring feed formulators to assess both composition and processing history. Boyer Valley's published poultry blood meal specification indicates 85% to 88% protein, illustrating the concentration achievable in a commercial product, but that specification should not be applied indiscriminately to every origin or plant. Feed manufacturers therefore buy on digestible nutrient delivery, validated quality and delivered cost per usable unit of protein rather than nominal protein content alone. Suppliers that invest in batch testing, amino-acid profiling and consistent drying conditions are better placed to secure repeat orders, particularly from integrators whose performance guarantees make formulation variability expensive. Price competition remains relevant, but dependable nutritional specifications often determine whether the ingredient enters a long-term procurement programme.
Slaughter volumes, recovery rates and plant economics
Unlike oilseed meals, which respond to crop production and crushing economics, blood meal originates from slaughterhouse operations that are driven primarily by the meat industry. A renderer cannot expand blood meal output independently of blood availability unless it secures additional collection contracts or improves the portion of blood recovered. Collection must occur rapidly and hygienically because blood deteriorates before it reaches a processing line; plants distant from major slaughter clusters face higher transport costs and greater quality-control requirements. Rendering economics also depend on the proportion of plasma or hemoglobin separated, moisture removal, energy consumption, emissions controls and the alternative value of the resulting materials. These constraints explain why a large livestock population does not automatically translate into a correspondingly large commercial blood meal industry. Integrated processors can secure predictable input streams and optimize logistics, while independent renderers may face greater exposure to changing slaughter schedules and supply concentration. For buyers, supply risk becomes particularly visible when seasonal processing fluctuations coincide with feed-mill demand peaks, raising the value of diversified sourcing contracts, documented material origins and inventory buffers.
Processing quality influences margins and market access
Rendering technology has a direct commercial effect because the processing route determines protein integrity, moisture content, safety and the final ingredient's suitability for different customers. Coagulation followed by drying is commonly used for conventional meal, while spray drying and further fractionation can support products with more specialized functional or nutritional characteristics. These categories should not be confused: spray-dried plasma and red-cell fractions may compete in adjacent applications, but they are not automatically equivalent to whole-blood meal. Processors seeking premium customers must control residence time and temperature, demonstrate microbial reduction and maintain consistent product specifications across batches. High energy requirements and wastewater treatment costs can erode the margin advantage of by-product sourcing, particularly in regions with limited industrial utilities. Conversely, well-integrated sites can improve recovery from slaughterhouse streams while generating materials for feed or other markets. The commercial opportunity lies in selecting a product pathway that matches local collection volumes, energy economics and customer qualification needs, rather than assuming that the highest achievable protein content also delivers the highest return on capital.
Feed economics and substitution are formulation-specific
Blood meal competes with soybean meal, fishmeal, poultry by-product meal and specialized amino-acid supplements, but the relevant comparison is different for each animal species and feeding stage. A poultry nutritionist evaluates digestible amino-acid balance, intestinal performance, ingredient palatability and restrictions on the use of animal-derived proteins. An aquafeed buyer considers protein digestibility, water stability and the effect of ingredient inclusion on feed conversion and animal health. The delivered price of blood meal may appear attractive against fishmeal on a crude-protein basis yet become less competitive after correcting for limiting amino acids or additional processing requirements. Commodity price movements therefore create opportunities for reformulation without guaranteeing a sustained replacement effect. Feed producers typically qualify alternative ingredients through trials, specification limits and supply audits before changing commercial formulations. Suppliers that support this process with dependable laboratory data and traceable lots may maintain stronger customer relationships than sellers relying on spot-market discounts. The outcome is a differentiated market in which nutritional evidence, approved use and shipment reliability together determine achievable selling prices.
Regulation changes the accessible customer base
Regulatory permissions vary materially by animal species, blood origin and product classification, so a global market assessment cannot assume that every blood meal grade is available to every feed customer. In the European Union, the 2021 revision of the transmissible spongiform encephalopathy rules permitted specified non-ruminant processed animal proteins in certain cross-species feeding arrangements under strict controls, while other restrictions remain. The United Kingdom makes a particularly important distinction between non-ruminant blood products and non-ruminant blood meal, with different permitted feed destinations. US FDA guidance treats certain blood and blood products differently from prohibited mammalian proteins under its ruminant feed safeguards. These distinctions determine production segregation, plant approval, labeling, sample testing and product traceability. A supplier may have abundant raw material but still lack access to a high-value application without the relevant approvals and documented processing controls. Buyers consequently evaluate regulatory eligibility alongside amino-acid profile and price. Cross-border trade can add further complexity because destination-country rules may be more restrictive than the processing plant's domestic market.
Circular economy creates value, but not automatic premiums
Converting slaughterhouse blood into saleable ingredients can reduce the burden of waste handling and recover nutrients already present in the meat supply chain. This creates a tangible circular-economy benefit, but commercial returns still depend on collection efficiency, processing costs and the final product's fitness for use. A plant that diverts blood away from wastewater can reduce certain disposal pressures while incurring costs for hygienic transport, drying energy and emissions treatment. The environmental benefit is therefore strongest when recovery is efficient and processing resources are managed carefully. Fertilizer-grade blood meal offers another outlet because its nitrogen content is useful in crop nutrition, although fertilizer represents a commercially adjacent destination and should not be mistaken for demand from feed-grade buyers. Buyers of feed-grade material generally pay for certified nutritional consistency, whereas fertilizer purchasers prioritize nutrient analysis, handling characteristics and agronomic performance. Integrated processors may shift material among eligible outlets depending on quality and price conditions, creating flexibility but also introducing differences in realized selling prices across end markets.
Product and Application Analysis
Porcine-derived blood meal: collection economics and pricing
Porcine-derived blood meal is the largest source category in the current market outlook, valued at approximately US$545.68 million in 2026 and representing 46.3% of global conventional blood meal revenue. The category is projected to reach US$614.38 million in 2032, implying a 2.00% CAGR. Hog processing is concentrated in large integrated facilities in several producing countries, creating opportunities to recover a regular blood stream with controlled origin and predictable drying volumes. However, the economics change sharply with collection efficiency: blood lost during slaughter, mixing with wash water or inadequate temperature management reduces useful solids and increases treatment costs. Processing cost per dry tonne can be sensitive to fuel requirements because most raw blood is water. On the demand side, nutritionists assess heat damage, lysine availability, supply consistency and species-specific feed eligibility before replacing conventional protein ingredients. The value proposition is therefore strongest where a producer combines direct raw-material access, documented traceability and reliable ingredient specification. Producers exposed to volatile slaughter margins or inconsistent collection conditions may struggle to convert physical availability into merchant-grade product at a competitive price.
Other source materials and end uses
Poultry and ruminant sources also contribute to the merchant market, although their commercial characteristics differ. Poultry blood requires careful handling because it has lower dry-matter content than typical pig or cattle blood, making moisture removal comparatively important. Cattle-derived supplies are linked to plant throughput, source segregation and permitted feed outlets. Across these categories, aquaculture, terrestrial feed and organic fertilizer provide different customer specifications rather than interchangeable demand. Suppliers must document blood origin, process temperature, protein and moisture characteristics, and relevant pathogen controls. Specialized plasma, hemoglobin and separated red-cell products remain commercially adjacent but are not included in whole-blood meal volumes. Regulatory acceptance varies across jurisdictions and can alter the accessible application mix even when identical ingredients are manufactured in different countries.
Regional Outlook
Asia Pacific and North America
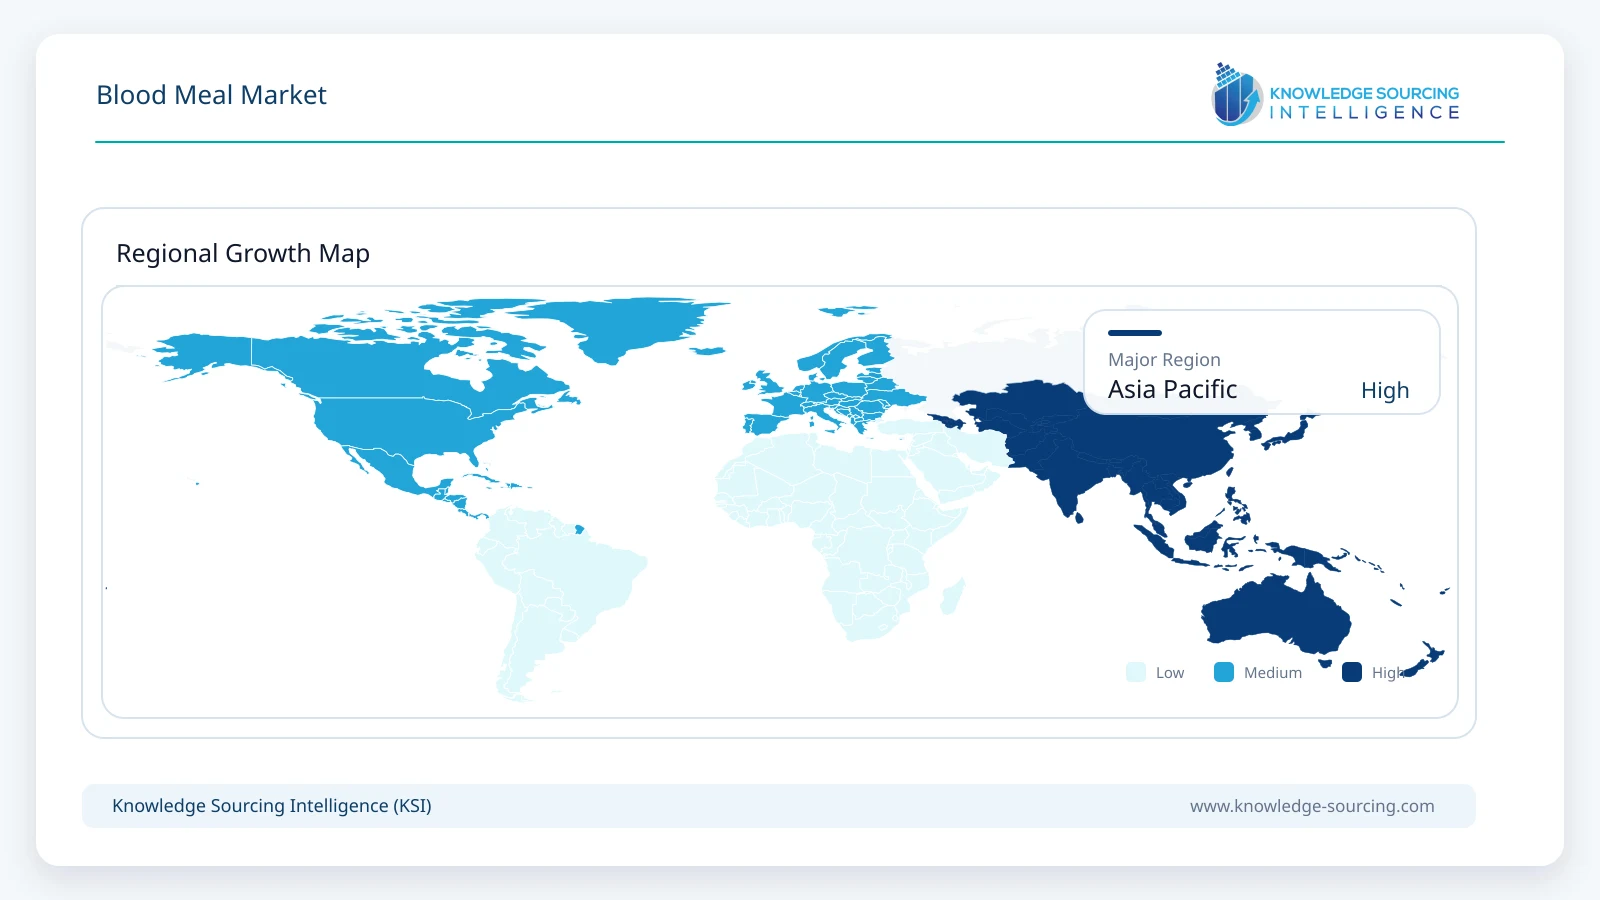
Asia Pacific combines large livestock and aquaculture industries with uneven adoption of dedicated blood collection and rendering infrastructure. China, India and Southeast Asian markets provide substantial animal-processing feedstocks, but commercial supply depends on the fraction collected hygienically, the proportion processed into a consistent meal and the feed outlets authorized to use it. The opportunity is therefore shaped by processor integration rather than slaughter volumes alone. In India, companies with integrated meat plants can capture value from otherwise low-realization by-products, although product testing, logistics and buyer qualification remain decisive. North America follows a different model, with established renderers and specialized distributors able to serve industrial feed buyers that require standardized lots, traceability and documented pathogen controls. Suppliers such as Boyer Valley and West Coast Reduction publish product specifications covering protein content and processing attributes, giving nutritionists a clearer basis for commercial comparison. Across both regions, growth depends more on collection economics, feed formulation acceptance and consistent quality than on unqualified increases in protein demand.
Europe, South America and other markets
European demand is filtered through extensive animal-by-product and feed legislation, making legal eligibility a central part of product-market fit. Processors must manage species segregation, traceable collection, plant authorization and controls against cross-contamination. A higher nominal protein concentration has limited commercial value if the intended feed customer cannot legally use that material. South America presents a different opportunity through large-scale livestock processing and aquaculture feed demand, including integrated Brazilian and Argentine plants that can recover blood at the point of slaughter. Product consistency, drying capacity and downstream distribution determine how much of this material becomes merchant-grade meal rather than alternative by-product outputs. Elsewhere, including Africa and Oceania, the economics depend on abattoir concentration and local feed demand, with larger processors better positioned to invest in drying and quality systems. Geography should therefore be interpreted as a series of different collection and regulatory structures, not a uniform growth ranking based solely on regional livestock population.
Competitive Environment
The blood meal competitive landscape includes vertically integrated renderers, specialist poultry-processors, multinational ingredient suppliers and smaller regional producers. The distinction matters because these businesses face different constraints: integrated facilities control raw-blood collection but incur capital and utility costs, while merchants can offer broader sourcing options without necessarily manufacturing the product. Darling Ingredients operates a large animal-by-product recovery network, with Sonac among its ingredient businesses and FASA within its corporate group. Boyer Valley specializes in poultry blood meal, while West Coast Reduction specifies both ruminant and non-ruminant grades. Sanimax offers several source-specific blood meals, and Ridley lists blood meal among its feed ingredients. Additional directly evidenced manufacturers and suppliers include GePro, PUREA Austria, Alberio, PROCAVI, Frigosinú, ArgenProt, Bush's Proteins and HMA Group. Their commercial differentiation lies in assured blood origin, process design, amino-acid and digestibility specifications, biosecurity, delivery reliability and suitability for authorized uses. Market share cannot be inferred from the existence of product listings, and specialized plasma or red-cell ingredients should not be automatically equated with conventional whole-blood meal.
Market Outlook
The blood meal industry is expected to expand at a measured pace through 2032 because usable supply is constrained by livestock processing volumes and the percentage of blood recovered into a commercial product. The annual revenue outlook rises from US$1,178.52 million in 2026 to US$1,399.58 million in 2032, with gains supported by production growth, modest improvements in collection infrastructure and selective upgrading of drying operations. This is not a uniform premium-pricing opportunity. Feed manufacturers continue to compare ingredient cost per unit of digestible amino acid against soybean meal, fishmeal, poultry by-product meal and synthetic amino acids; pronounced changes in relative prices can reduce inclusion even when blood meal is widely available. For renderers, the commercially attractive investments are those that reduce handling losses, improve moisture and microbial consistency, and lower energy requirements per saleable tonne. Distribution agreements and verified product quality can support access to higher-value customers, but extensive inventories and unqualified cross-species claims can damage profitability. The outlook therefore favors integrated processors that combine raw-material control with documented feed-safety systems and consistent product performance.
Recent Developments
July 2026: Darling Ingredients reported second-quarter Feed Ingredients net sales of US$1.149 billion. The segment covers a broader ingredient portfolio and should not be confused with blood meal revenue.
June 2026: FAO published The State of World Fisheries and Aquaculture 2026, identifying 103 million tonnes of farmed aquatic animal output in 2024. The figure indicates aquafeed-sector scale, not measured blood meal usage.
June 2026: Anchor Ingredients announced a distribution partnership with APC for blood-derived specialty proteins. The arrangement concerns adjacent plasma and red-cell products, rather than conventional blood meal alone.
Blood Meal Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.18 billion |
| Total Market Size in 2032 | USD 1.40 billion |
| Forecast Unit | Billion |
| Growth Rate | 2.9% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Source, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Source
Poultry Blood
Porcine Blood
Ruminant Blood
By Application
Aquafeed
Poultry Feed
Swine Feed
Other Permitted Animal Feed
Organic Fertilizer and Soil Amendments
By Geography
North America
South America
Europe
Middle East and Africa
Asia Pacific
Table of Contents
1. EXECUTIVE SUMMARY
1.1 Global Market Size, 2026–2032
1.2 Key Findings
1.3 Investment and Procurement Implications
2. RESEARCH SCOPE AND METHODOLOGY
2.1 Product Boundary and Blood-Protein Exclusions
2.2 Collection-Yield and Conversion Framework
2.3 Commercial Price Benchmarks
2.4 Market Sizing and Scenario Testing
3. BLOOD MEAL MARKET OVERVIEW
3.1 Livestock Processing and Recoverable Supply
3.2 Value Chain and Cost Structure
3.3 Feed-Grade Product Specifications
4. MARKET DYNAMICS
4.1 Slaughter Throughput and Blood Collection
4.2 Drying, Digestibility and Cost
4.3 Protein Substitution in Feed Formulations
4.4 Regulatory Requirements and Traceability
4.5 Five Forces and Supply Chain
5. BLOOD MEAL MARKET BY SOURCE
5.1 Poultry Blood
5.2 Porcine Blood
5.3 Ruminant Blood
6. BLOOD MEAL MARKET BY APPLICATION
6.1 Aquafeed
6.2 Poultry Feed
6.3 Swine Feed
6.4 Other Permitted Animal Feed
6.5 Organic Fertilizer and Soil Amendments
7. BLOOD MEAL MARKET BY GEOGRAPHY
7.1 North America
7.2 South America
7.3 Europe
7.4 Middle East and Africa
7.5 Asia Pacific
8. COMPETITIVE INTELLIGENCE
8.1 Manufacturing and Supply Networks
8.2 Quality and Regulatory Positioning
8.3 Recent Industry Developments
9. COMPANY PROFILES
9.1 Darling Ingredients (including Sonac and FASA)
9.2 Sanimax
9.3 The Boyer Valley Company
9.4 West Coast Reduction
9.5 Ridley Corporation
9.6 APC
9.7 PUREA Austria GmbH
9.8 GePro Geflügel-Protein Vertriebsgesellschaft mbH & Co. KG
9.9 Alberio S.p.A.
9.10 PROCAVI
9.11 Frigosinú S.A.
9.12 ArgenProt
9.13 Bush's Proteins
9.14 HMA Group
9.15 Berrychem Vetcare Industries Pvt. Ltd.
9.16 LaBudde Group
10. APPENDIX
10.1 Source and Assumptions
10.2 List of Figures and Tables





Frequently asked questions
What is the projected market size of the Blood Meal Market by 2032?
The Blood Meal Market is projected to reach USD 1.40 billion by 2032.
What is the forecasted CAGR for the Blood Meal Market?
The Blood Meal Market is forecast to grow at a 2.9% CAGR from 2026 to 2032.
Which blood meal source segment holds the largest share in 2026?
Porcine-derived blood meal accounts for an estimated 46.3% of 2026 revenue.
What are the primary applications driving blood meal demand?
Specialized animal nutrition, aquaculture feed, and organic soil amendments drive demand.
What key factors influence blood meal commercial supply?
Slaughter throughput, collection systems, drying economics, and customer acceptance affect supply.
What determines blood meal protein pricing and value?
Digestible amino-acid value and feed-formulation economics determine pricing.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Blood Meal Market Size, Share & Forecast (2026–2032). https://www.knowledge-sourcing.com/report/blood-meal-market