Dark Fiber Market - Strategic Insights and Forecasts (2026-2031)
Dark Fiber Market Trends, Size & Growth By Fiber Type (Single-Mode Fiber, Multimode Fiber), Network Type (Metro Networks, Long-Haul Networks), Commercial Model (Recurring Lease, IRU and Long-Term Rights, Custom Build and Other Structures), End User (Telecom and Wholesale Carriers, Hyperscale Cloud and Data Centers, Large Enterprise and BFSI, Government, Education, and Healthcare, Others), and Geography
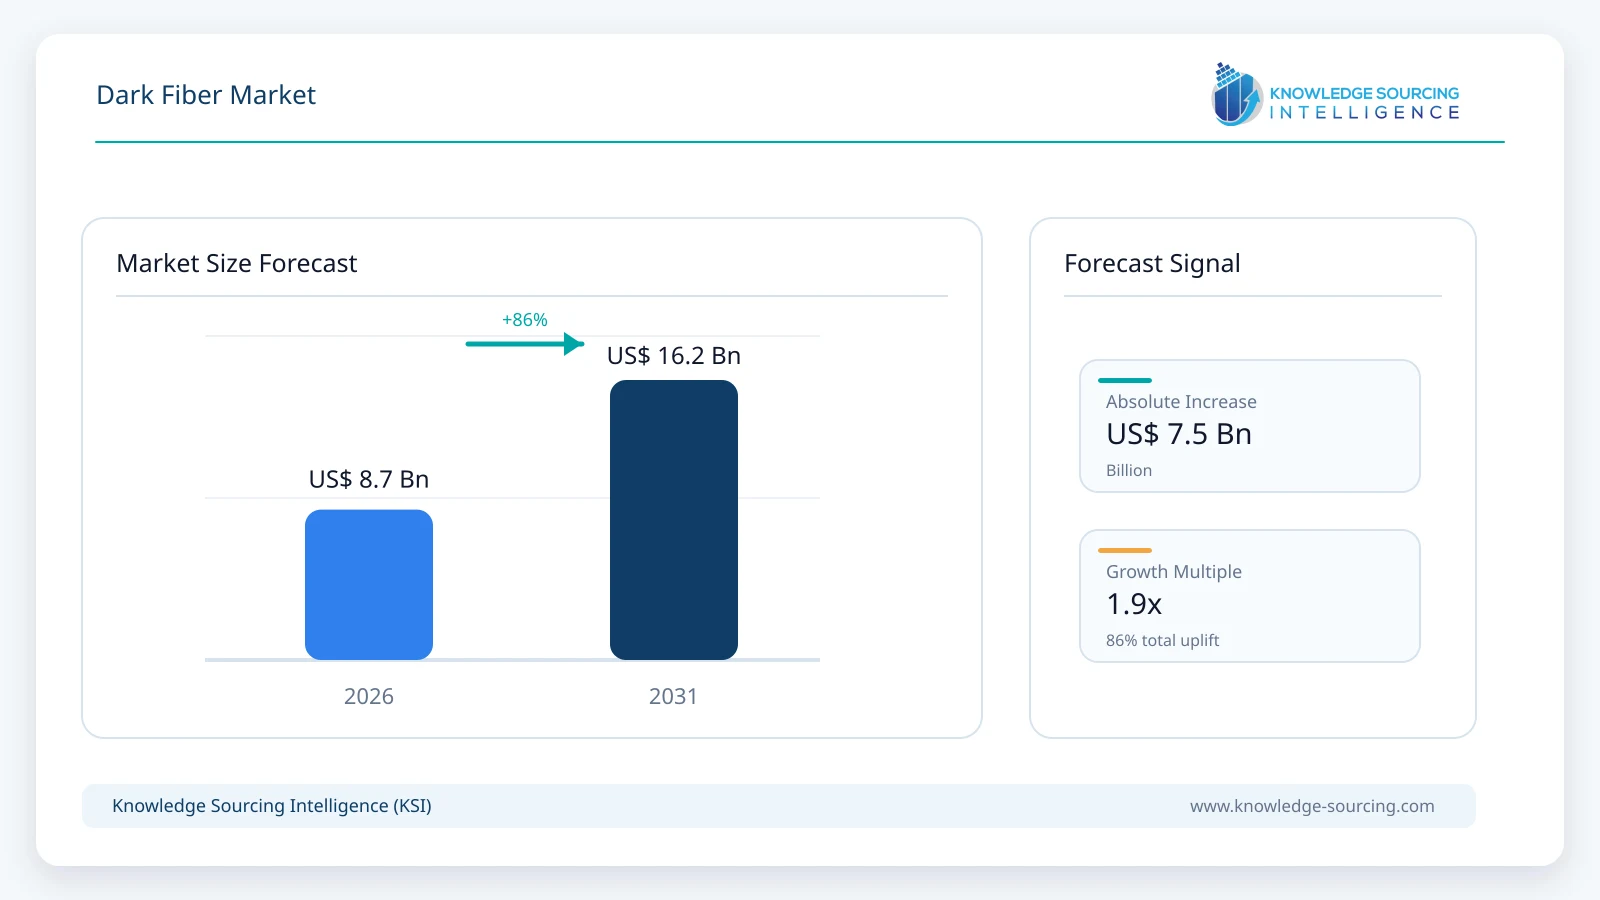
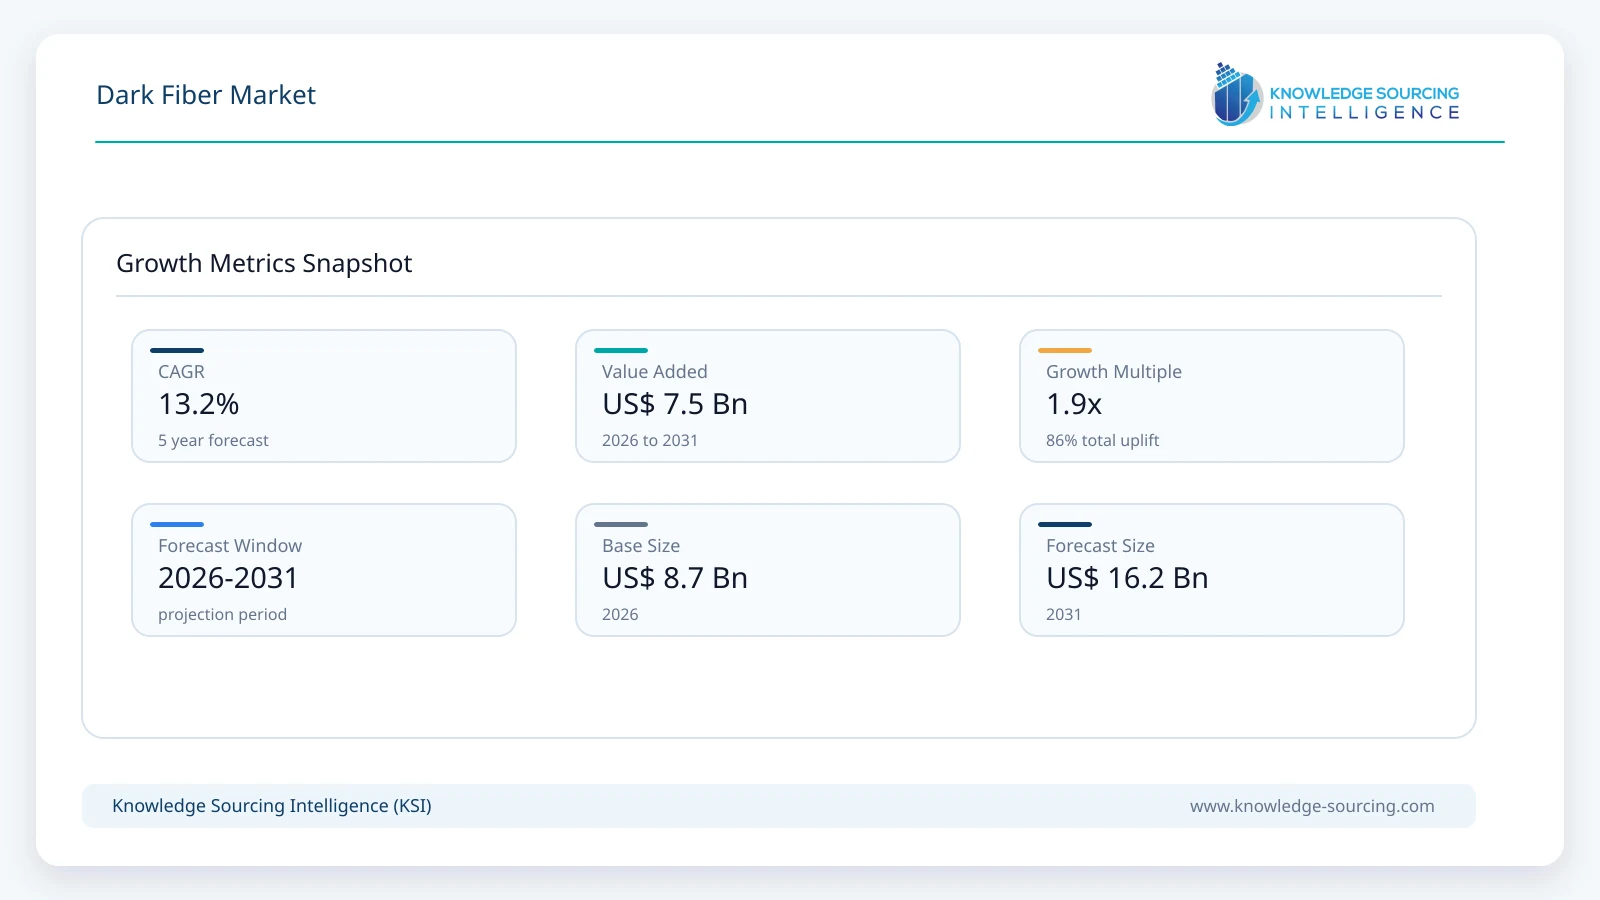
The global dark fiber market is estimated at USD 8.70 billion in 2026 and is forecast to reach USD 16.20 billion in 2031, representing a CAGR of 13.24% during the forecast period.
Highlights:
1
Single-mode fiber accounts for approximately 95.0% of global dark-fiber revenue in 2026.
2
Metro networks represent approximately 56.0% of 2026 revenue as data-center campuses and cloud regions densify.
3
Telecom, wholesale carriers, hyperscalers, and data-center operators form the core demand base for dedicated fiber strands.
4
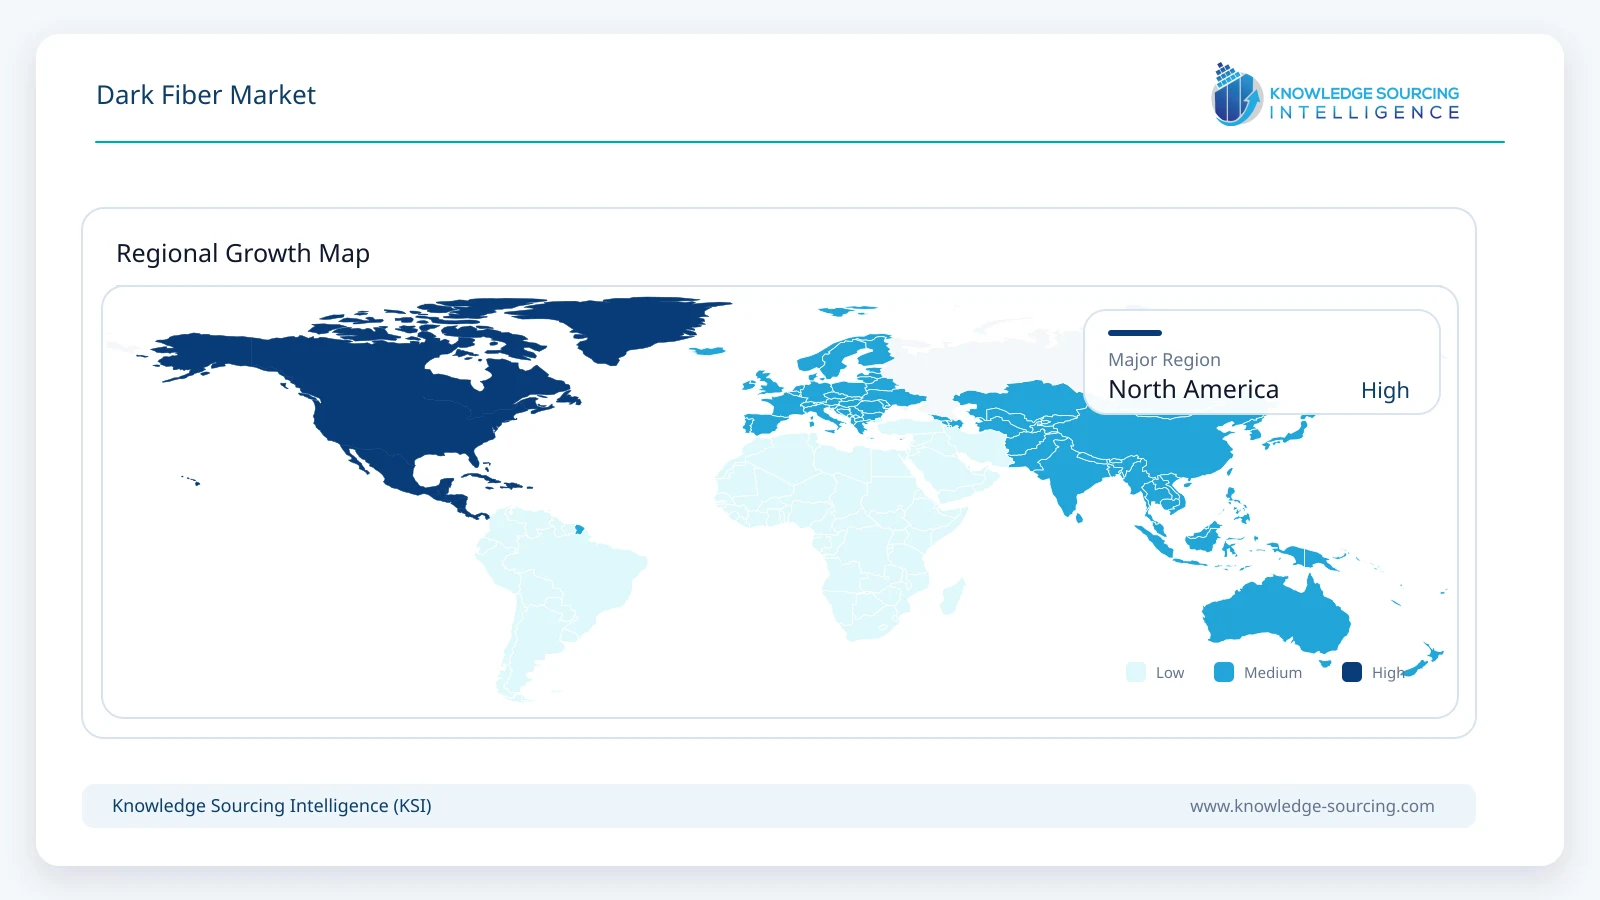
North America accounts for approximately 37.0% of 2026 revenue, supported by dense intercity and metro fiber investment.
5
AI infrastructure is shifting network planning toward route diversity, high fiber counts, and direct ownership or long-duration control of strands.
6
The market is increasingly differentiated by route scarcity, conduit ownership, building access, and time-to-service rather than fiber glass alone.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Key Highlights
Market Overview
Dark fiber refers to installed optical-fiber strands that are not lit by the network owner and are instead leased or granted to a customer that supplies and operates its own optical transmission equipment. The commercial proposition is therefore fundamentally different from managed bandwidth. A dark-fiber customer controls the electronics, wavelengths, upgrade cycle, security architecture, and often the route design, while the infrastructure provider supplies the physical strand, conduit access, splicing, maintenance, and restoration obligations defined in the contract.
The market estimate is based on recurring dark-fiber leases, IRU arrangements, customer-funded builds, cross-connect and installation revenue directly associated with dark-fiber delivery, and long-term route-control agreements. It excludes lit wavelength services, Ethernet, IP transit, broadband access, and raw optical fiber cable sold to construction contractors. This service-market definition is important because mixing cable manufacturing with infrastructure leasing materially overstates the addressable market and obscures the economics of route ownership.
Demand is being reshaped by AI data centers and distributed cloud infrastructure. Zayo completed the acquisition of Crown Castle's Fiber Solutions business in May 2026, adding approximately 90,000 route miles and creating a North American network of roughly 224,000 route miles. Lumen is simultaneously adding new intercity routes such as NorthLine between Seattle and Minneapolis, while Colt, euNetworks, Uniti, Eurofiber and other operators are expanding metro and long-haul infrastructure around data-center clusters. These investments indicate that the physical fiber layer is again becoming a strategic capacity constraint rather than a commoditized utility.
The forecast assumes sustained hyperscale and wholesale demand, growth in metro data-center interconnection, 5G and edge-network densification, public-sector and financial-services requirements for physically diverse paths, and continuing construction of intercity corridors toward power-rich data-center markets. Growth is moderated by high civil-construction costs, permitting and rights-of-way delays, route-specific overbuild risk, and substitution by high-capacity wavelength or spectrum services for customers that do not require strand-level control.
Dark Fiber Market Trends
AI Infrastructure Increases the Value of Strand-Level Control
AI training and inference clusters move exceptionally large east-west data volumes between data centers, cloud regions, storage sites, and network exchange points. When demand is measured in multiple 400G or 800G channels, owning or controlling the underlying fiber strands can become more economical than continually purchasing managed bandwidth. Dark fiber also lets the customer replace optical equipment without renegotiating the physical path, allowing the same fiber pair to scale as transmission technology advances.
The effect is strongest on routes connecting hyperscale campuses and emerging power-rich markets. Providers are responding with higher fiber-count builds, new long-haul corridors, and metro rings designed around data-center density rather than traditional central-business-district traffic patterns.
Metro Fiber Densification Becomes as Important as Long-Haul Scale
Large national backbones remain essential, but the bottleneck is increasingly the last several kilometers between carrier hotels, cloud on-ramps, data-center campuses, enterprise buildings, and edge facilities. Dense metro ownership creates more route combinations, shorter provisioning times, and greater ability to sell diverse paths to the same customer.
Zayo's acquisition of Crown Castle Fiber Solutions and Colt's 2026 Frankfurt metro build illustrate the strategic value of metro density. In mature markets, providers are therefore expanding laterally through acquisitions, lateral builds, and on-net building connections rather than only constructing new intercity routes.
New Intercity Routes Follow Power and Data-Center Development
AI compute is moving toward locations with available power, land, and cooling resources, creating new network corridors outside traditional telecom hubs. Lumen's NorthLine route is one example of fiber construction aligned with emerging northern U.S. data-center and power corridors. Similar patterns are visible in Europe, where operators are strengthening routes between major FLAP-D markets and secondary data-center regions.
This changes route economics. A corridor that was previously marginal can become strategically valuable once multiple campuses are committed, while saturated legacy routes may face slower incremental growth despite high existing traffic.
IRUs and Long-Term Rights Gain Importance for Capacity Certainty
Large cloud, carrier, and data-center customers increasingly use IRUs or long-duration leases to secure physical capacity before all traffic has materialized. These arrangements provide cost certainty and route control while giving network owners upfront or contracted revenue that can support new construction.
The commercial model is becoming more customized, with contracts specifying strand counts, regeneration rights, route diversity, repair service levels, handoff locations, and expansion options. This makes dark fiber a negotiated infrastructure product rather than a standardized bandwidth service.
Security, Sovereignty, and Quantum Networking Create Specialized Demand
Government, financial, research, and critical-infrastructure users value dark fiber because physical-path control reduces dependence on shared transmission systems and allows proprietary encryption or optical equipment. Quantum-network experiments create an additional specialized use case because entanglement distribution and quantum-key systems often require carefully controlled optical paths.
These applications are small relative to hyperscale and carrier demand but can support premium route-specific contracts, particularly where customers require dedicated strands, defined splice counts, low loss, or strict access controls.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Segment Analysis
By Fiber Type - Single-Mode Fiber
Single-mode dark fiber is estimated at approximately USD 8.27 billion in 2026, representing about 95.0% of market revenue. The segment dominates because long-haul, metro backbone, data-center interconnect, mobile transport, and most enterprise carrier-grade networks are designed around single-mode fiber. Its low attenuation and ability to support high-capacity coherent optics over long distances make it the standard physical medium for commercial dark-fiber contracts.
Multimode dark fiber remains relevant inside selected campuses and short-distance environments, but it is rarely the basis for wide-area infrastructure leasing. As 400G, 800G, and future terabit-class optical systems expand, single-mode fiber remains the strategic asset because capacity can be increased by replacing terminal equipment without replacing the buried strand.
By Network Type - Metro Networks
Metro dark fiber is estimated at approximately USD 4.87 billion in 2026, or about 56.0% of the global market. Metro demand is supported by dense clusters of data centers, carrier hotels, enterprise buildings, mobile aggregation sites, universities, government facilities, and cloud access points. Customers often require multiple physically diverse paths within the same metropolitan area, increasing the commercial value of operators with dense conduit and lateral-building access.
Long-haul fiber remains strategically important and is expanding rapidly around AI routes, but metro infrastructure generally supports more customer endpoints and a higher frequency of new connections. The fastest-growing metro opportunities are around hyperscale campuses and secondary data-center markets where power availability is driving new compute capacity.
By Commercial Model - IRU and Long-Term Rights
IRU and other long-term-right arrangements are estimated at approximately USD 3.74 billion in 2026. These contracts are particularly common among carriers, hyperscalers, large enterprises, and infrastructure investors seeking multi-year control of specific strands or routes. The structure can involve upfront payments, recurring maintenance charges, or blended commercial terms.
Recurring leases remain important for customers that prefer operating expenditure and shorter commitments. However, AI-scale network planning is increasing demand for long-duration capacity certainty, which supports IRUs and custom-build structures on constrained corridors.
By End User - Telecom and Wholesale Carriers
Telecom and wholesale carriers are estimated at approximately USD 3.83 billion in 2026, representing about 44.0% of market revenue. Carriers use dark fiber to extend backbone coverage, create protected routes, connect mobile and broadband aggregation sites, and avoid duplicative civil construction where another operator already owns suitable infrastructure.
Hyperscale cloud and data-center customers are the fastest-growing demand pool. Their share is increasing as AI clusters require greater east-west capacity, dedicated data-center interconnection, and direct control over optical equipment. In many markets, the boundary between wholesale carrier and hyperscaler demand is also becoming less distinct because large cloud companies increasingly procure infrastructure directly.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
By Geography - North America
North America is estimated at approximately USD 3.22 billion in 2026, representing about 37.0% of global dark-fiber revenue. The region combines extensive long-haul routes, dense metro fiber ownership, a large colocation market, hyperscale cloud campuses, and rapid AI data-center expansion. Zayo, Lumen, Lightpath, Uniti, FiberLight, Segra, FirstLight, AT&T, and Verizon are among the operators providing or supporting dedicated fiber infrastructure.
Europe is another large market, with Colt, euNetworks, Eurofiber, Arelion, and GlobalConnect serving dense cross-border and metro data-center routes. Asia Pacific is expected to grow strongly through cloud expansion, subsea landing connectivity, 5G transport, and new data-center clusters, although dark-fiber availability varies considerably by country because of local licensing and infrastructure-ownership rules.
Market Drivers
AI and Hyperscale Data-Center Expansion: Large compute clusters require multiple diverse high-capacity paths between campuses, cloud regions, storage locations, and network exchanges. Dark fiber provides customers with physical capacity that can be upgraded by changing optics rather than renegotiating service bandwidth.
Cloud and Data-Center Interconnection: Enterprises and cloud providers increasingly distribute workloads across multiple facilities. Dedicated fiber reduces latency, improves route control, and can lower cost per bit when sustained traffic volumes are high.
5G, Fiber Access, and Edge Densification: Mobile transport and broadband aggregation networks create demand for fiber between towers, central offices, edge sites, and core networks. Infrastructure owners can monetize unused strands to carriers that prefer leasing over new civil construction.
Route Diversity and Resilience: Financial institutions, cloud platforms, government agencies, and large enterprises require physically separate paths to reduce common points of failure. Dense dark-fiber providers can monetize diversity that managed services on a single route cannot provide.
Customer Control and Security: Dark fiber gives customers direct control of encryption, optical equipment, wavelength planning, and network upgrades. This is valuable for regulated, sovereign, and security-sensitive workloads.
Economics at Very High Bandwidth: Once traffic reaches multiple high-capacity wavelengths, leasing strands can be more economical over a multi-year period than repeatedly buying managed capacity, particularly where customers already operate optical engineering teams.
Market Restraints
High Civil-Construction Cost: Trenching, boring, conduit, permitting, traffic management, and restoration represent a large share of network cost. A route can be economically unattractive unless customer density or a long-term anchor contract is sufficient.
Permitting and Rights-of-Way Delays: New routes depend on municipal permits, railway crossings, utility access, pole attachment, and land rights. Delays can extend deployment timelines well beyond the equipment-installation phase.
Route-Specific Oversupply: Dark fiber is not a homogeneous global commodity. Some corridors have scarce strands while others have multiple competing networks. Overbuilding can depress lease rates for years on a specific route.
Customer Optical-Equipment Burden: A dark-fiber customer must purchase and operate transponders, amplifiers, monitoring systems, spares, and engineering resources. Smaller enterprises often prefer wavelength or Ethernet services instead.
Substitution by Managed Wavelengths and Spectrum: Modern coherent optical systems provide very high capacity without requiring customers to manage the physical layer. Where route control is not essential, managed 400G or 800G services can be a simpler substitute.
Consolidation and Limited Building Access: Mergers can reduce the number of independent infrastructure owners in a market, while exclusive building-entry rights or constrained ducts can limit effective competition even when several carriers serve the broader city.
Competitive Environment
The dark-fiber market is led by infrastructure owners rather than optical-equipment manufacturers. Competitive advantage comes from route ownership, conduit rights, spare fiber count, building entrances, regeneration sites, maintenance capability, and the ability to construct laterals quickly. A provider with a smaller but dense metro network can be more competitive for a specific customer than a national carrier whose route passes nearby without entering the required building.
The market is consolidating around scale and density. Zayo's 2026 acquisition of Crown Castle Fiber Solutions materially expanded its U.S. metro footprint, while regional operators continue to acquire routes that deepen specific corridors. At the same time, new builds by Lumen, Colt, Uniti and others indicate that consolidation is not eliminating greenfield construction where AI and data-center demand creates new traffic corridors.
Product differentiation increasingly centers on time-to-service, pre-engineered routes, high fiber counts, path diversity, and customer control. Providers also compete through wavelength, spectrum, colocation, cloud-connect, and managed-network products around the same physical infrastructure, allowing them to serve customers before or after those customers are ready to operate dark fiber directly.
The validated participant set in this report excludes legacy identities that no longer represent the current selling entity. CenturyLink, for example, is not treated as a standalone current company profile; the relevant infrastructure business is represented by Lumen Technologies. Crown Castle Fiber Solutions is also not profiled separately after completion of its sale to Zayo in May 2026.
Recent Developments
September 2026: Eurofiber and Delft Networks announced deployment of dark fiber between Delft and Rotterdam for entanglement-based quantum-network infrastructure, demonstrating a specialized use case for controlled optical paths.
July 2026: Zayo reported that long-haul fiber demand had doubled during 2025 and highlighted sharply higher metro demand associated with AI-ready infrastructure, while continuing a multi-year network expansion program.
May 2026: Zayo completed the acquisition of Crown Castle's Fiber Solutions business, adding approximately 90,000 route miles and bringing the combined North American network to roughly 224,000 route miles.
May 2026: Lumen announced NorthLine, a new Seattle-to-Minneapolis fiber route designed around AI and cloud data movement and expected to be available by the end of 2026.
May 2026: Uniti Wholesale announced additional dark-fiber and colocation expansion across key U.S. markets, extending its ability to serve hyperscale, carrier, and enterprise connectivity demand.
February 2026: Colt announced a major Frankfurt metro infrastructure build adding approximately 200 kilometers of new fiber to support hyperscale cloud and AI growth.
January 2026: Uniti Wholesale announced more than 1,100 route miles of new south-central U.S. fiber backed by a long-term contract valued at more than USD 500 million over 20 years.
Market Outlook
Dark fiber is expected to remain one of the fastest-growing segments of fixed digital infrastructure through 2031 because traffic growth is increasingly concentrated among customers that can economically operate their own optical layer. AI clusters, cloud providers, large data centers, carriers, financial institutions, and government networks will account for the majority of incremental demand.
The strongest value creation will occur on constrained corridors where power availability and data-center construction create new traffic faster than fiber can be permitted and built. Metro route density will remain critical, while selected long-haul corridors gain strategic importance as compute expands into secondary markets.
Single-mode fiber will continue to dominate, and IRU or long-duration arrangements should gain share among the largest customers. Providers with spare conduit, high fiber counts, multiple building entrances, rapid lateral-construction capability, and geographically diverse routes are positioned to capture premium demand. By contrast, operators with legacy low-count cables or routes that do not align with new compute locations may see less benefit from headline traffic growth.
Dark Fiber Market Scope
Report Metric
Details
Total Market Size in 2026
USD 8.70 billion
Total Market Size in 2031
USD 16.20 billion
Forecast Unit
Billion
Growth Rate
13.24%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Fiber Type, Network Type, Commercial Model, End User, Geography