
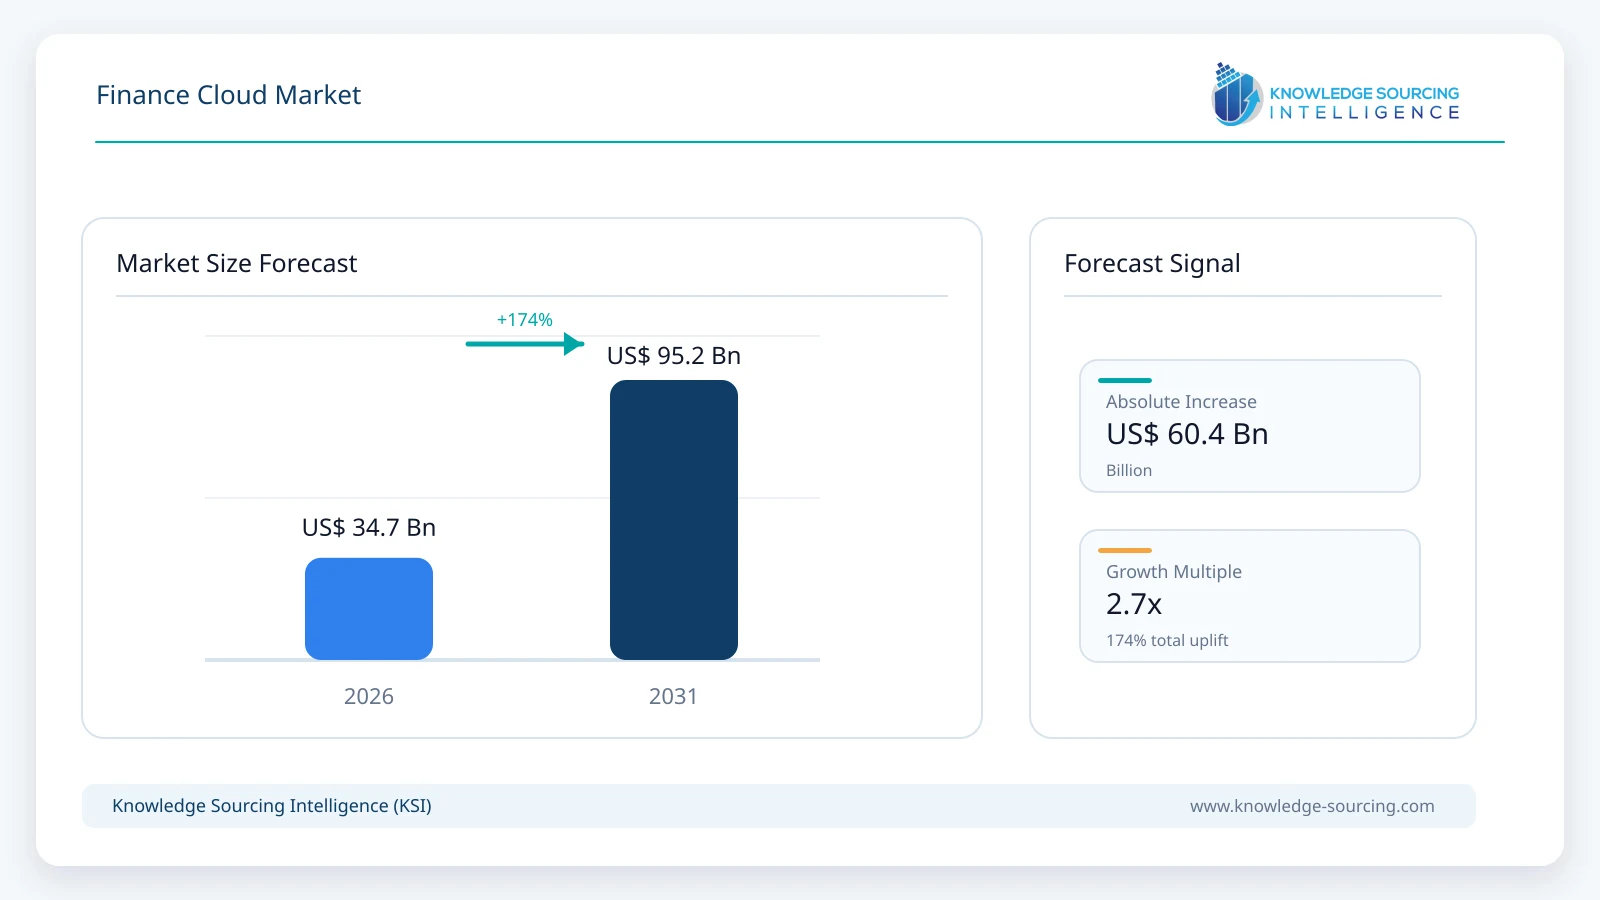
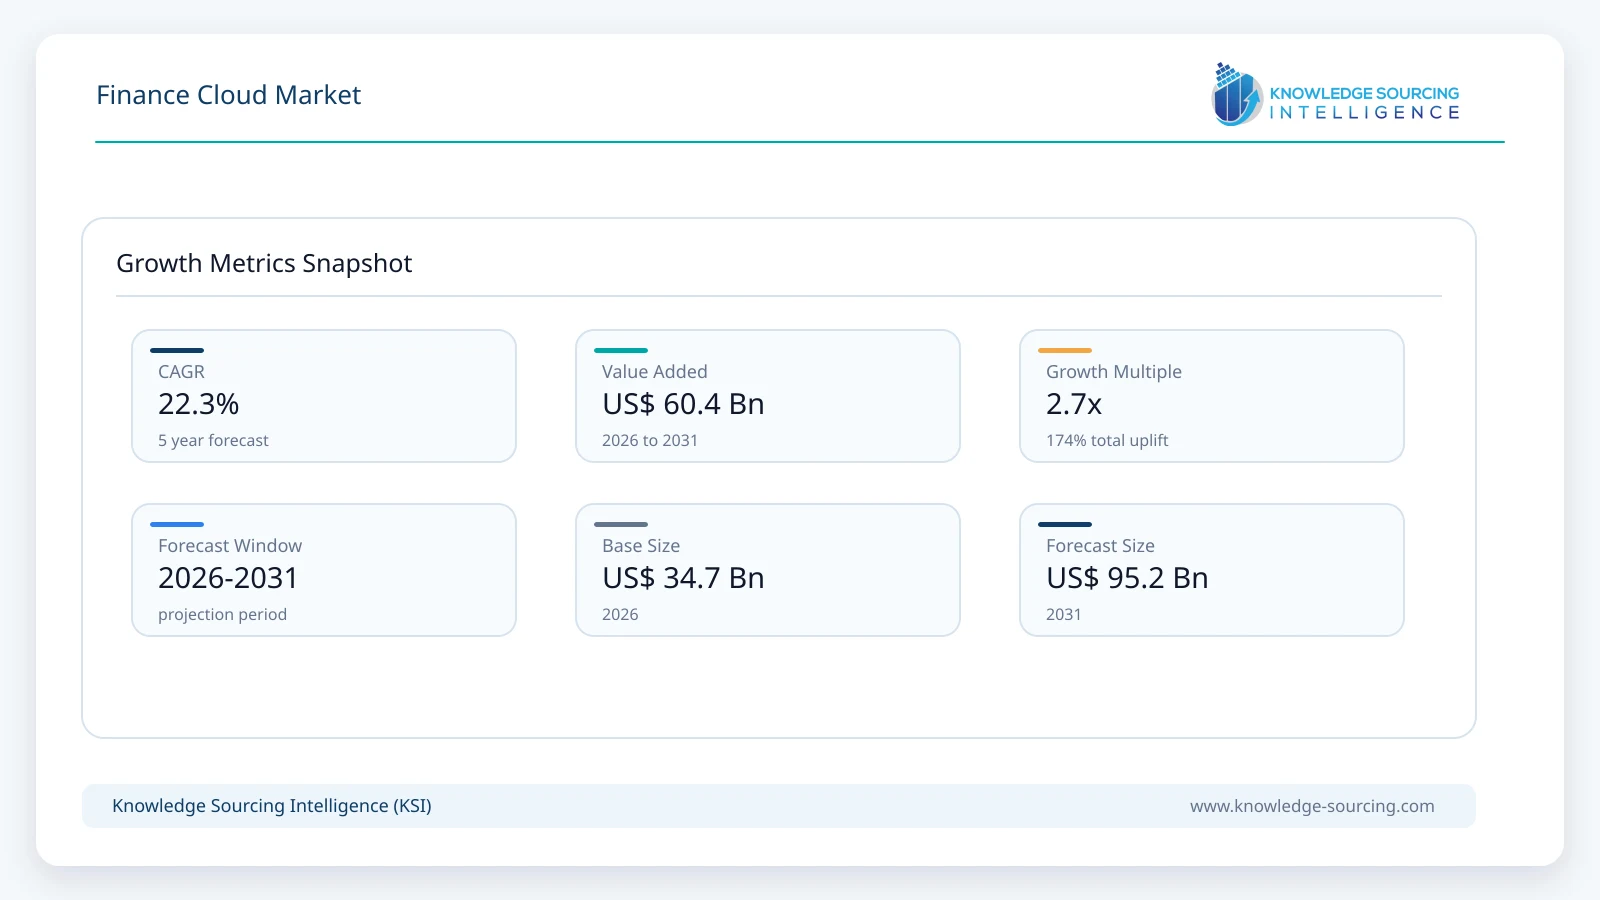
The finance cloud market is forecast to grow at a CAGR of 22.3%, reaching USD 95.2 billion in 2031 from USD 34.7 billion in 2026.
Highlights:
- 1Financial institutions are adopting cloud platforms to modernize core systems, improve operational agility, and support digital financial services.
- 2Cloud-based financial management, analytics, artificial intelligence, and automation are helping institutions streamline reporting and decision-making.
- 3Governance, risk, and compliance capabilities are becoming increasingly important as financial organizations address cybersecurity, regulatory, and third-party technology risks.
- 4Asia Pacific presents significant opportunities through digital payments, expanding financial inclusion, and the modernization of banking and financial infrastructure.
Finance Cloud Market Trends:
The finance cloud market covers cloud-based infrastructure, platforms, applications, and managed services used to support financial management and financial-sector operations. Its scope includes banking, financial services, insurance (BFSI), financial technology companies, corporate finance departments, investment firms, and other organizations handling financial transactions or sensitive financial information. Depending on the solution, finance cloud deployments may support accounting, financial planning, enterprise resource planning (ERP), payments, customer relationship management (CRM), treasury management, fraud detection, risk analytics, and regulatory reporting.
Cloud computing is changing how financial organizations procure technology and manage workloads. Instead of relying exclusively on locally hosted servers and software, institutions can use cloud-based applications and infrastructure to increase computing capacity, integrate data sources, and deploy new services without undertaking the full capital expenditure associated with traditional data centres. Software-as-a-service (SaaS), infrastructure-as-a-service (IaaS), and platform-as-a-service (PaaS) each serve different requirements. SaaS supports ready-to-use financial applications, IaaS provides configurable computing and storage resources, and PaaS enables organizations to build, integrate, and operate custom applications.
A key trend is the integration of artificial intelligence (AI) and advanced analytics into financial workflows. Cloud-based systems can help finance teams identify unusual transactions, prepare forecasts, reconcile accounts, analyze cash flows, and automate document-intensive processes. In banking, similar capabilities can support customer onboarding, fraud investigations, credit assessment, and service operations. However, the value of AI depends on data quality, access permissions, explainability, and appropriate human oversight. Financial institutions must ensure that automated recommendations remain consistent with internal policies and applicable regulatory obligations.
Another important trend is the movement towards connected financial data and integrated enterprise applications. Organizations increasingly need to link accounting, procurement, payments, customer information, treasury, and reporting systems. Disconnected platforms can delay month-end closing, complicate audit preparation, and create inconsistencies between financial records. Cloud-based applications can improve information sharing through common data models, application programming interfaces (APIs), and standardized workflows. The benefits depend on the quality of implementation and whether legacy applications can exchange data reliably.
Hybrid and multi-cloud architectures are also relevant to the finance cloud market. Some institutions retain selected workloads in private infrastructure while using public cloud services for analytics, development, customer-facing applications, or less sensitive operations. Others distribute workloads across providers to address resilience, geographic, technical, and procurement requirements. These arrangements can improve flexibility, but they also introduce integration complexity, inconsistent security configurations, and additional oversight responsibilities. Cloud adoption therefore requires a workload-by-workload assessment rather than an assumption that every financial application should move to the same environment.
Regulatory oversight is shaping purchasing decisions. The European Union's Digital Operational Resilience Act (DORA) became applicable on 17 January 2025 and establishes requirements covering ICT risk management, incident reporting, resilience testing, and third-party risk. The European Commission's [DORA implementation information](https://finance.ec.europa.eu/regulation-and-supervision/financial-services-legislation/enforcement-and-infringements-banking-and-finance-law/monitoring-banking-and-finance-directives/digital-operational-resilience-financial-sector-directive_en) provides an official reference for the framework. These requirements make contractual transparency, incident response, service continuity, and exit planning important considerations when financial organizations select cloud providers.
Overall, the finance cloud market is evolving beyond basic data hosting. Its commercial relevance increasingly rests on the ability to combine reliable infrastructure, connected financial applications, controlled automation, analytics, and demonstrable operational resilience. Vendors that address these requirements without compromising governance are better positioned to serve financial organizations with demanding security and continuity expectations.
Finance Cloud Market Growth Drivers:
Shortened time-to-market for new services: Cloud-based development environments, reusable software components, and automated deployment pipelines can help financial organizations introduce applications and digital services more quickly. Teams can test new functions, scale resources, and deploy updates without waiting for all supporting infrastructure to be procured and configured. This is particularly relevant to fintech companies and digital banking services, where rapid product iteration can influence customer acquisition and retention. Nevertheless, production releases still require security testing, regulatory review, and appropriate change management.
Increased efficiency and cost management: Cloud computing can reduce the need to purchase and maintain some on-premises hardware, while subscription-based software may simplify access to updated applications. Flexible computing capacity can also help organizations manage variable workloads. However, savings are not automatic. Data transfer charges, licensing, migration, integration, specialist staffing, and continuous consumption can increase total costs. Financial institutions therefore need workload-level cost monitoring, contractual review, and regular comparisons between cloud and alternative deployment models.
Security and operational resilience requirements: Major cloud providers offer security capabilities such as encryption, identity management, logging, network controls, vulnerability monitoring, and automated threat detection. These capabilities can strengthen an institution's security architecture when configured and monitored appropriately. However, using a cloud service does not transfer all security responsibility to the provider. Financial organizations remain responsible for appropriate access controls, application security, data classification, incident coordination, supplier oversight, and compliance with applicable laws.
Digital transformation across financial services: Banks, insurers, payment providers, and corporate finance teams are modernizing processes that historically relied on separate systems or manual intervention. Cloud platforms can connect customer information, financial transactions, reporting, and operational data to support faster decisions. Integrated applications may also help reduce repetitive data entry and improve reconciliation. The strongest business cases generally combine technology migration with process redesign, employee training, and clear performance measures.
Expansion of digital payments and financial inclusion: Digital payment adoption is increasing demand for scalable transaction processing, monitoring, analytics, and connected financial services. India's Ministry of Finance reported that retail digital payment transactions reached 22,167.90 crore in FY 2024-25, with a transaction value of ₹849.12 lakh crore. The official [Press Information Bureau release dated 16 March 2026](https://www.pib.gov.in/PressReleasePage.aspx?PRID=2240723&lang=1®=1&trk=article-ssr-frontend-pulse-little-text-block) identifies UPI as accounting for 81% of retail digital payment transactions in FY 2024-25. This provides evidence of the scale of India's digital financial activity, although payment growth alone does not establish the size or growth rate of the finance cloud market.
Growing demand for data analytics and automation: Financial institutions need to process large volumes of transactional and operational information while maintaining traceability. Cloud-based analytics can support liquidity monitoring, forecasting, financial consolidation, anomaly detection, and risk assessment. Automation can reduce repetitive work in accounts payable, reconciliations, reporting, and compliance documentation. Demand is likely to favour solutions that combine reliable data access with audit trails, role-based permissions, and controls for reviewing automated decisions.
Finance Cloud Market Key Players and Products:
Products offered by key companies:
Oracle Corporation: Oracle Fusion Cloud ERP provides cloud-based enterprise resource planning capabilities, including financial management, procurement, project management, and reporting. Its financial applications support accounting processes, payables, receivables, financial close, and performance monitoring. Oracle's portfolio is relevant to organizations seeking to connect financial transactions with wider enterprise operations. Product suitability depends on organizational complexity, integration requirements, implementation resources, and the need to maintain appropriate controls over financial data.
SAP SE: SAP S/4HANA Cloud provides enterprise resource planning capabilities that include finance, accounting, reporting, and operational integration. The platform can help organizations connect financial information with procurement, supply chain, sales, and other business processes. SAP's cloud ERP portfolio supports organizations seeking standardized financial workflows across multiple business units or jurisdictions. Implementation planning remains important, particularly where organizations have complex legacy systems, country-specific accounting requirements, and established financial control procedures.
Microsoft Corporation: Microsoft Dynamics 365 Finance supports financial management, budgeting, cash and bank management, accounts payable and receivable, financial reporting, and related enterprise processes. Its broader cloud ecosystem can support integration with analytics, productivity, data management, and identity services. Financial organizations evaluating Microsoft-based solutions should assess licensing, integration architecture, data residency, access governance, and the suitability of the solution for their specific regulatory environment.
Finance Cloud Market Segmentation Analysis:
Prominent growth in the governance, risk, and compliance segment within the finance cloud market:
Governance, risk, and compliance (GRC) is an important area of the finance cloud market because financial organizations operate under extensive obligations relating to data protection, financial reporting, cybersecurity, fraud prevention, operational continuity, and third-party oversight. Cloud-based GRC applications can consolidate risk registers, compliance evidence, internal controls, audit workflows, policy documentation, and incident records. Centralized information can help organizations identify control gaps and coordinate responses across business units, although effective outcomes still depend on data accuracy and clearly assigned responsibilities.
Demand for cloud-enabled GRC tools is supported by increasingly complex technology environments. Financial organizations may depend on core banking platforms, payment processors, external data services, cloud infrastructure, AI tools, and specialist software providers. Each dependency can create operational or compliance exposure. Automated monitoring, access reviews, workflow tracking, and centralized evidence management can help risk teams evaluate these dependencies more consistently. Organizations also need to determine which controls are managed by the cloud provider and which remain their responsibility.
The EU's DORA framework illustrates why third-party oversight is commercially significant. Financial entities must address ICT risks and the resilience of services that support critical or important functions. Consequently, cloud procurement increasingly involves scrutiny of service-level commitments, subcontracting arrangements, incident notification, audit rights, recovery arrangements, and the practical feasibility of changing providers. The [European Commission's DORA information](https://finance.ec.europa.eu/regulation-and-supervision/financial-services-legislation/enforcement-and-infringements-banking-and-finance-law/monitoring-banking-and-finance-directives/digital-operational-resilience-financial-sector-directive_en) is a primary source for the regulatory context.
AI is adding another layer to GRC requirements. Automated systems may assist with alert prioritization, document review, policy checks, and investigation preparation. Yet institutions must consider model risk, inaccurate outputs, data leakage, unauthorized actions, and inadequate explainability. Human review, documented approval thresholds, access restrictions, and auditable records remain important where automated systems influence consequential financial decisions. GRC platforms that integrate these controls into normal workflows can offer more practical value than tools that simply collect compliance documents.
For market participants, the opportunity lies in making compliance activities more continuous and evidence-driven rather than treating them as periodic reporting exercises. However, the original market material does not provide independently verified segment-level revenue or CAGR figures. Accordingly, GRC can be identified as a strategically important demand area, but a claim that it is definitively the fastest-growing segment should be supported by the report's own segment estimates before publication.
Cloud-based financial management and ERP as a major adoption area:
Cloud-based financial management and ERP form another major application area because they address recurring processes across organizations of different sizes. These solutions can connect general ledger accounting, accounts payable, accounts receivable, budgeting, cash management, financial consolidation, and reporting. Replacing disconnected applications with integrated workflows can reduce reconciliation effort and improve visibility into financial performance. For multinational companies, cloud ERP may also support standardized reporting across subsidiaries, subject to local accounting rules, taxation requirements, and currency arrangements.
The value proposition is particularly relevant when organizations need more frequent reporting, shorter financial closing cycles, and better access to operational data. Automated transaction matching, configurable approval workflows, and integrated dashboards can help finance teams identify exceptions earlier. Embedded AI may support tasks such as invoice processing, variance explanations, and cash-flow forecasting. These functions should be assessed against measurable outcomes, including error rates, processing times, forecast accuracy, and audit findings, rather than assumed to deliver improvements in every implementation.
Small and medium-sized businesses can benefit from subscription-based financial software that reduces the need to maintain extensive internal infrastructure. Larger organizations, meanwhile, may prioritize consolidation, complex entity structures, integration with established systems, and stronger segregation of duties. As a result, buying criteria differ substantially by customer size and application. Vendors that offer flexible deployment, reliable integration, transparent pricing, and appropriate financial controls can address a wider range of requirements.
Finance Cloud Market Geographical Outlook:
Asia Pacific presents significant opportunities in the finance cloud market:
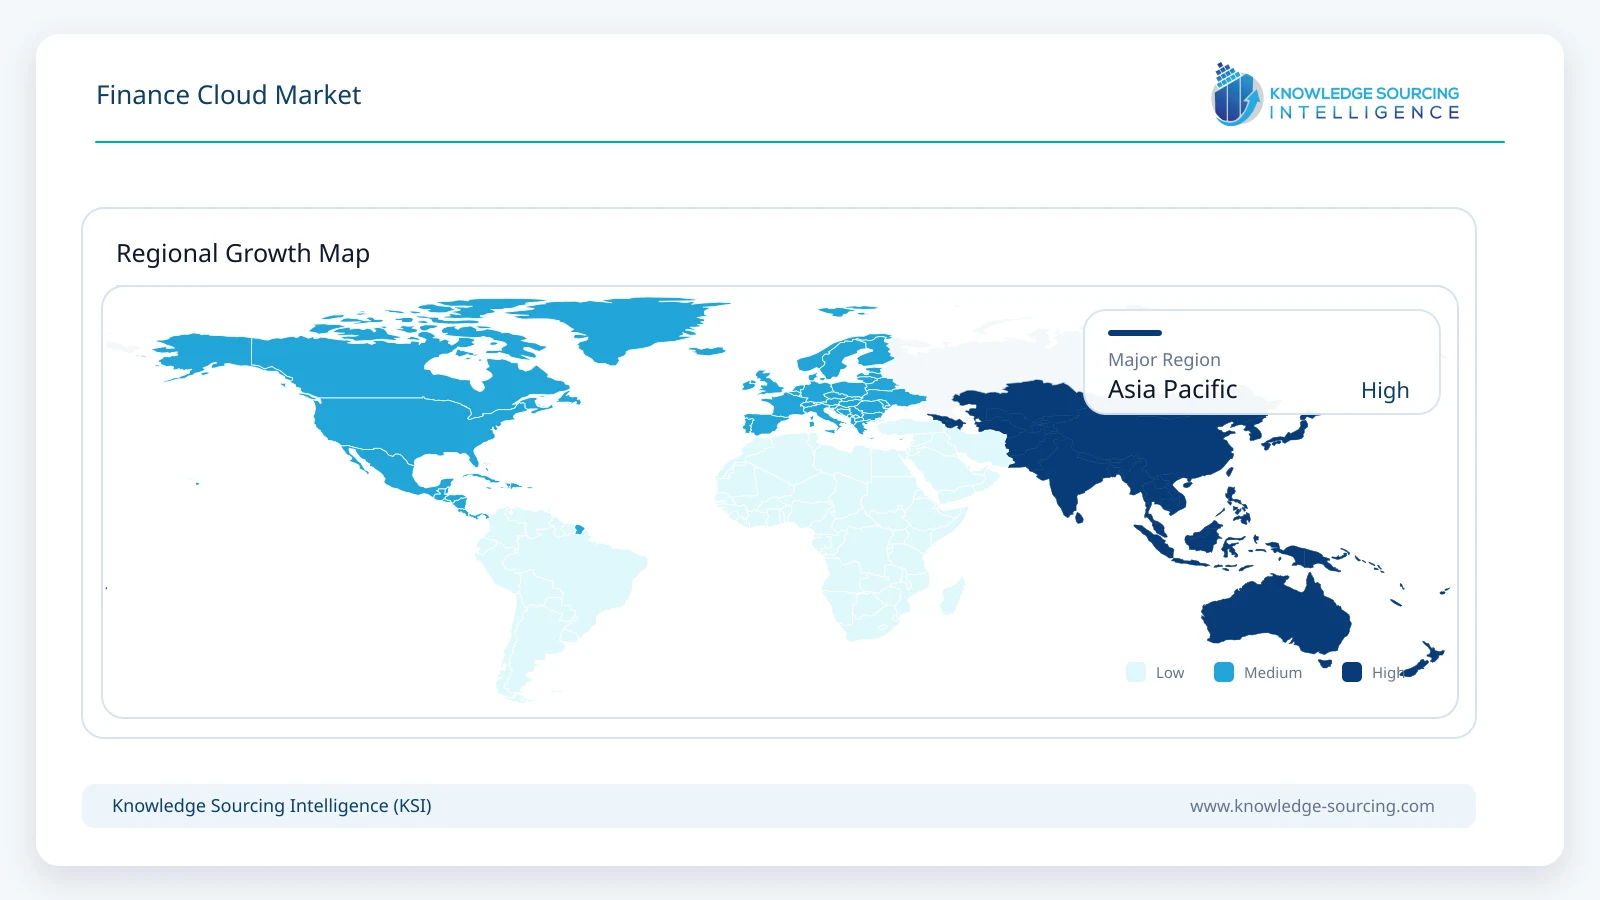
Asia Pacific offers substantial opportunities for finance cloud providers because the region includes large digital payment ecosystems, expanding financial technology sectors, established banking markets, and businesses modernizing their financial infrastructure. Adoption conditions vary considerably between economies. More digitally mature markets may prioritize automation, data analytics, and integration with existing banking systems, while developing markets may place greater emphasis on accessible digital services, scalable infrastructure, and the modernization of financial operations.
India’s cloud infrastructure sector is attracting substantial investment as demand for cloud computing and artificial intelligence grows. In June 2026, Amazon announced an additional USD 13 billion investment to expand AI and cloud infrastructure in India, bringing its total planned investment in these capabilities to more than USD 21 billion between 2026 and 2030. According to the company, the investment will expand AWS data centre capacity in Mumbai and Hyderabad, supporting startups, enterprises, and government organisations with cloud services and AI capabilities. This investment signals continued infrastructure expansion, although it does not independently quantify overall cloud market revenue or adoption.
For cloud vendors, the expansion of digital payments creates opportunities in transaction analytics, fraud monitoring, customer service, data integration, financial reconciliation, and scalable application infrastructure. Banks and payment providers need systems capable of handling changing transaction volumes while preserving availability and appropriate security. Cloud-based analytics and application platforms can contribute to these objectives, although critical payment processing requirements and regulatory expectations must be evaluated before workloads are migrated.
Other regional markets provide distinct opportunities. Singapore and Australia have established financial services sectors with demand for secure digital infrastructure and data-driven operations. Japan and South Korea have sophisticated banking and technology ecosystems, where modernization may involve integrating new cloud services with existing systems. China has a large digital financial ecosystem, but vendor access, data governance, cybersecurity rules, and local operating requirements shape deployment choices. Southeast Asian markets offer opportunities linked to digital banking, financial inclusion, and the growth of online commerce.
Regional adoption also faces challenges. Financial institutions must consider data localization, cross-border transfers, vendor concentration, network reliability, legacy infrastructure, and the availability of skilled cloud professionals. Regulatory requirements differ across jurisdictions, and a deployment model that is appropriate in one country may not be suitable in another. Local partnerships, regional infrastructure, transparent data-handling arrangements, and well-defined incident-response procedures can therefore influence vendor selection.
Asia Pacific should consequently be viewed as an important opportunity area rather than automatically classified as the fastest-growing or largest region. Establishing regional leadership requires comparable revenue, adoption, or forecast data across all geographic segments. The market's geographical ranking should be aligned with the underlying research estimates before the final report is published.
Recent Developments
October 2026: SAP: SAP announced finance-related innovations covering embedded payments, enterprise performance management, consolidation, and expanded AI automation, aimed at connecting financial insights with operational execution.
September 2026: Oracle Financial Services: Oracle announced Oracle Nexus Case Flow and Oracle Nexus Reach, adding agentic AI capabilities to financial crime investigations to support case preparation and investigative workflows with human oversight.
August 2026: Google Cloud: Google Cloud introduced Gemini Enterprise for Financial Services, targeting financial research, credit analysis, and risk modelling through specialized AI capabilities and connections to trusted financial data.
April 2026: Oracle: Oracle introduced Fusion Agentic Applications for finance and supply chain, adding coordinated AI agents to enterprise workflows using organizational data, permissions, policies, and approval structures.
March 2026: Oracle: Oracle announced that Oracle Cloud Federal Financials had joined the US Treasury's FM QSMO Marketplace, providing federal agencies with a cloud-based option for financial management and automated reporting.
List of Top Finance Cloud Companies:
Oracle Corporation
SAP SE
Microsoft Corporation
Sage Intacct Inc.
Unit4
Finance Cloud Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 34.7 billion |
| Total Market Size in 2031 | USD 95.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 22.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution and Service, Deployment, Enterprise Size, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solution and Service
Financial Forecasting
Financial Reporting and Analysis
Governance, Risk, and Compliance
Managed Service
By Deployment
Public Cloud
Private Cloud
By Enterprise Size
Small and Medium
Large
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. FINANCE CLOUD MARKET BY SOLUTION AND SERVICE
5.1. Introduction
5.2. Financial Forecasting
5.3. Financial Reporting and Analysis
5.4. Governance, Risk, and Compliance
5.5. Managed Service
6. FINANCE CLOUD MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Public Cloud
6.3. Private Cloud
7. FINANCE CLOUD MARKET BY ENTERPRISE SIZE
7.1. Introduction
7.2. Small and medium
7.3. Large
8. FINANCE CLOUD MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Oracle Corporation
10.2. SAP SA
10.3. Microsoft Corporation
10.4. Sage Intacct Inc.
10.5. Unit4
10.6. Infosys
10.7. Acumatica Inc.
10.8. Huawei Technologies Co. Ltd
10.9. IBM Corporation
10.10. Google
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size of the Finance Cloud Market by 2031?
The Finance Cloud Market is forecast to reach USD 95.2 billion by 2031.
What is the compound annual growth rate (CAGR) for the Finance Cloud Market?
The Finance Cloud Market is projected to grow at a 22.3% CAGR.
What are the main drivers for finance cloud adoption?
Modernizing core systems, improving agility, and supporting digital financial services.
Which region offers significant growth opportunities in this market?
Asia Pacific presents significant opportunities for market expansion.
What key technologies are driving innovation in finance cloud?
AI, advanced analytics, and GRC capabilities are key trends.
What types of operations does the Finance Cloud Market support?
Financial management, ERP, payments, CRM, risk analytics, and reporting.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Finance Cloud Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/finance-cloud-market