
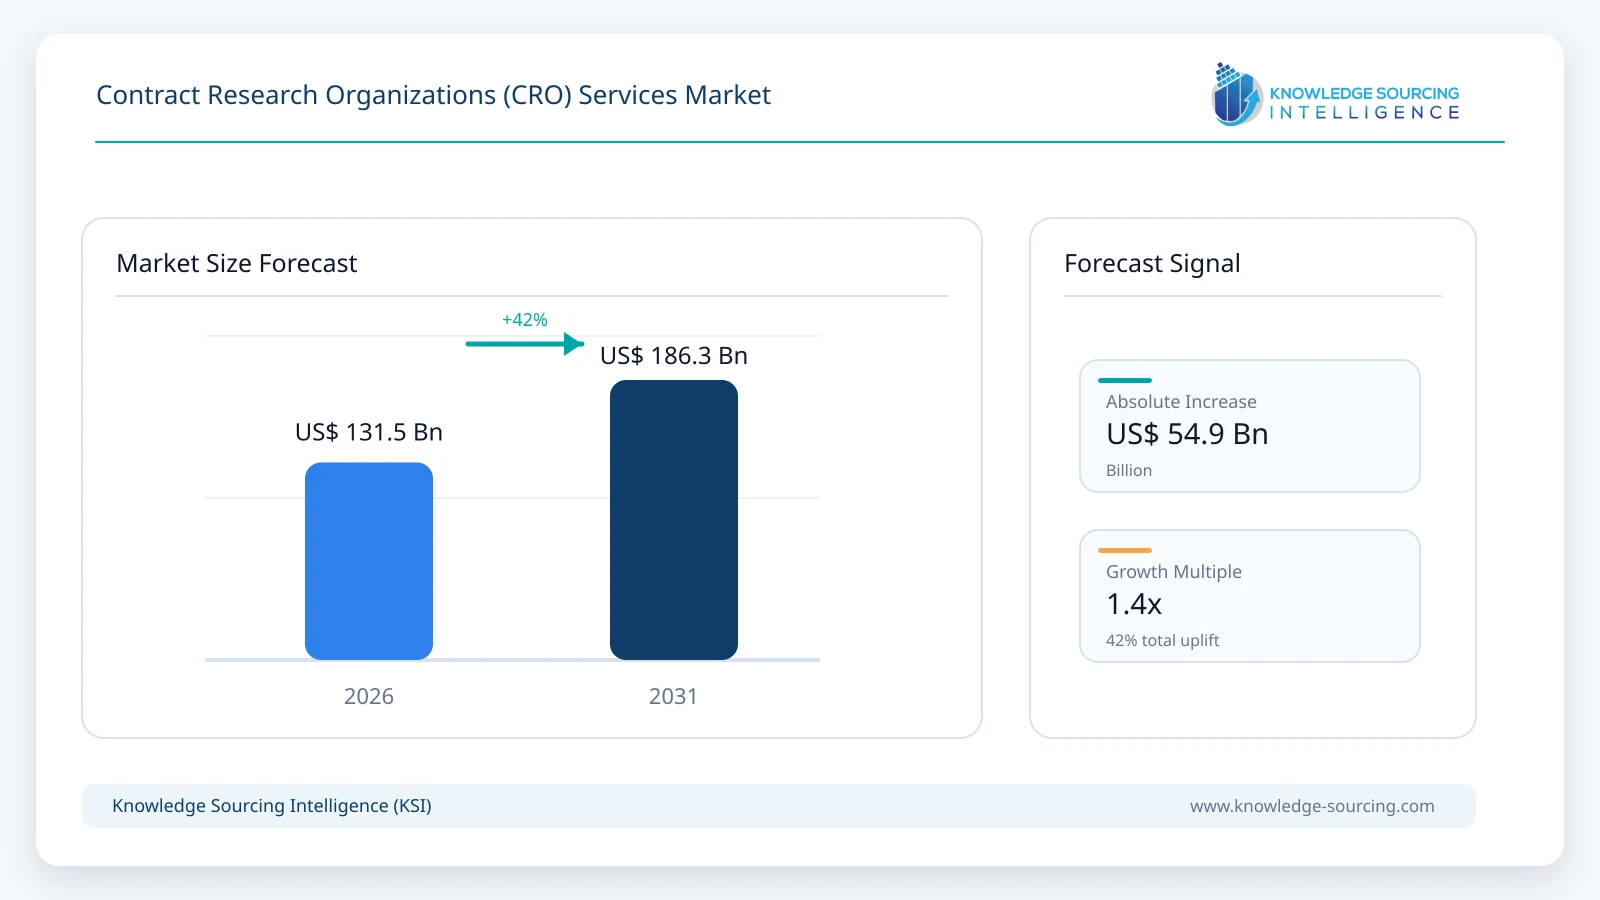
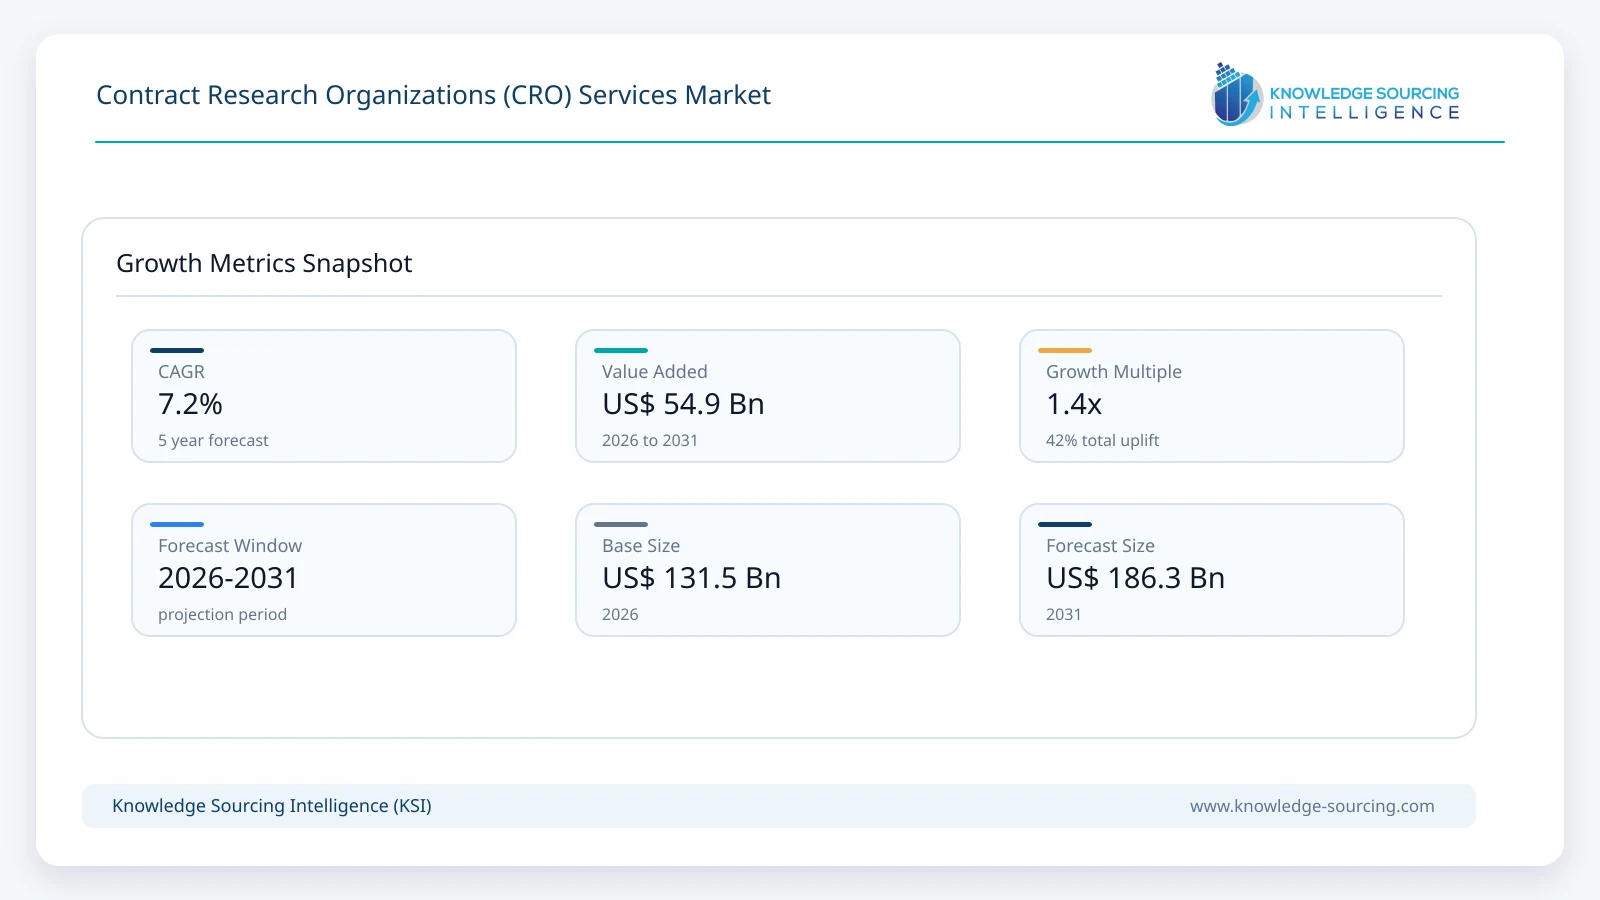
The global contract research organization (CRO) service market is set to reach USD 186.3 billion in 2031, growing at a CAGR of 7.22% from a valuation of USD 131.5 billion in 2026.
Highlights:
- 1The global CRO service market is expanding toward USD 186.3 billion in 2031 at a 7.22% CAGR, with North America commanding the largest regional share.
- 2Rising demand for specialized clinical capabilities is driving sponsors toward full-service outsourcing models amid growing trial complexity and geographic distribution.
- 3Regulatory updates and decentralized trial adoption are increasing reliance on technology-enabled monitoring, patient recruitment, and quality oversight services.
- 4Oncology is holding the dominant therapeutic segment share while cell and gene therapies are reshaping molecule-type demand for advanced bioanalytical support.
- 5Biopharmaceutical firms are leveraging global CRO networks for multi-regional trials, with Asia Pacific gaining share through cost advantages and faster approvals.
Demand drivers across the pharmaceutical ecosystem are reshaping the operating model of drug developers, particularly as clinical development becomes more data-intensive, technology-enabled, and geographically distributed. The increasing complexity of modern clinical programs is encouraging sponsors to rely on specialized external capabilities rather than maintaining every operational function internally. This shift is particularly relevant for small and mid-sized biopharmaceutical companies, which may not possess the infrastructure, specialized personnel, or international operational reach required to execute increasingly sophisticated Phase I-IV programs independently. Medpace’s 2025 Annual Report describes outsourced clinical development as a core model for biotechnology, pharmaceutical, and medical device companies, while emphasizing the value of integrated capabilities and therapeutic expertise for timely clinical development.
Regulatory expectations are simultaneously increasing the operational requirements associated with clinical evidence generation. In September 2025, the U.S. Food and Drug Administration finalized its E6(R3) Good Clinical Practice guidance, introducing greater flexibility around modern trial designs, technologies, data sources, and risk-based approaches while maintaining strong requirements for participant protection, quality by design, and reliable trial results. In December 2025, FDA also issued final guidance on enhancing participation in clinical trials, recommending approaches to improve enrollment of representative populations across demographic and clinical characteristics. These developments increase the need for specialized capabilities in trial design, patient recruitment, data management, monitoring, and quality oversight.
The growing adoption of decentralized and technology-enabled clinical development is further expanding the scope of outsourced requirements. FDA’s finalized September 2024 guidance permits decentralized elements such as telehealth visits, in-home visits, and interactions with local healthcare providers, while its current digital health framework supports remote acquisition of clinical data. These approaches can improve participant accessibility and broaden enrollment but also introduce additional requirements for technology integration, remote monitoring, data management, and operational coordination. Consequently, sponsors increasingly require external partners capable of combining clinical, technological, patient-engagement, and regulatory expertise within a coordinated development model.
Biopharmaceutical developers also depend on globally distributed infrastructure to manage increasingly complex clinical programs across multiple jurisdictions. International studies require coordination among investigators, clinical sites, patients, laboratories, technology platforms, and regulatory stakeholders, creating substantial operational demands for sponsors without established global networks. ICON reported in August 2026 that it supported more than 1,370 clinical studies involving over 411,400 patients during 2025 and operated across 99 locations in 55 countries as of June 2026. Such scale illustrates the infrastructure available through global CRO partnerships for sponsors seeking broader geographic execution capabilities.
Outsourcing therefore increasingly functions as a strategic mechanism for managing operational complexity rather than simply transferring individual clinical tasks. CROs can provide integrated clinical-development services, specialized therapeutic expertise, patient and site capabilities, technology infrastructure, and regional execution support. Parexel’s June 2025 analysis of outsourcing models highlighted the growing relevance of full-service, functional-service-provider, and hybrid approaches as biopharmaceutical companies balance flexibility, operational control, staffing requirements, technology, and regulatory strategy. This evolution strengthens the role of CROs as strategic development partners capable of helping sponsors manage complex clinical programs while improving operational flexibility and maintaining compliance throughout the development lifecycle.
Market Dynamics
Drivers
Rising pipeline concentrations of multi-targeted monoclonal antibodies generate immediate demand for advanced bioanalytical testing capabilities across diverse geographic networks.
Persistent shortages of internal biostatistical and clinical data management talent compel mid-sized biotechs to leverage full-service functional service provider frameworks.
The ongoing expansion of multi-regional clinical trials forces biopharmaceutical sponsors to utilize localized investigator networks to satisfy stringent structural diversity requirements.
Strict decentralized clinical trial mandates drive systemic adoption of remote patient monitoring tools and virtual site execution platforms.
Restraints and Opportunities
Geopolitical trade restrictions and localized data protection frameworks constrain cross-border transmission of patient genomic data, which limits global consolidation of trial registries.
Persistent structural delays in institutional review board approvals create severe operational bottlenecks that disrupt early-phase trial execution timelines.
Rapid integration of machine learning algorithms into data-clearing processes provides immediate opportunities to compress clinical database lock periods from weeks to days.
Growing cell-line manufacturing constraints generate significant high-margin opportunities for contract partners capable of providing integrated chemistry, manufacturing, and controls support.
Supply Chain Analysis
The operational architecture of contract research relies on a complex, linear sequence of high-value inputs that transforms discovery assets into validated clinical data. At the foundational tier, primary suppliers provide specialized reagents, advanced assay kits, and transgenic models necessary for early preclinical screening. These raw inputs transfer directly to analytical laboratories, where specialized machinery parses molecule interaction characteristics under strict regulatory controls.
Information infrastructure providers constitute the next critical link, supplying cloud architecture and decentralized data capture software to link geographically dispersed investigator sites. Site management organizations select, clear, and manage patient cohorts at the clinical execution layer, processing biological samples under strict environmental parameters. The final delivery phase compiles multi-center trial outcomes into secure, regulatory-compliant data packages designed for institutional review.
Systemic bottlenecks frequently emerge at the interface between laboratory logistics and investigator sites due to specialized cold-chain requirements for advanced biologics. A localized breakdown in temperature-controlled shipping instantly invalidates sample integrity, which triggers trial protocol deviations and halts clinical validation timelines. Consequently, contract research networks are integrating specialized logistics providers directly into their central operational platforms to guarantee end-to-end custody validation.
Government Regulations
Regulatory Body | Policy Initiative | Direct Operational Impact on Market |
U.S. Food and Drug Administration (FDA) | FDA Modernization Act 2.0 | Removes the legal mandate for mandatory animal testing, which shifts preclinical demand toward alternative human-centric cell assays. |
European Medicines Agency (EMA) | Clinical Trials Regulation (CTR) No 536/2014 | Harmonizes trial submissions through a single centralized electronic portal, which compresses trial authorization timelines across member states. |
National Medical Products Administration (NMPA) | Fast-Track Review Scheme for Innovative Drugs | Accelerates clinical trial application processing down to thirty working days, which increases early-phase trial velocity within mainland China. |
Key Developments
September 2026: Fortrea announced an agreement to acquire Worldwide Clinical Trials’ Early Phase Services division, adding clinical pharmacology, bioanalytical laboratory, and early-phase development capabilities.
August 2026: Labcorp announced the launch of the next-generation Global Trial Connect, enhancing its clinical-trial services platform with improved digital workflows, visibility and decision-making capabilities.
July 2026: Thermo Fisher Scientific’s PPD clinical research business announced the launch of the PPD CorEvitas Vitiligo Registry to generate real-world evidence on nonsegmental vitiligo treatment outcomes.
June 2026: Parexel launched its Biotech Incubator, connecting early-stage therapeutics companies with clinical and regulatory expertise while partnering with Cape Fear BioCapital to support seed-stage innovation.
April 2026: Parexel acquired Vitrana to enhance AI-driven patient safety and pharmacovigilance solutions, improving automation, compliance, and operational efficiency in clinical development services.
Market Segmentation
By Molecule Type
The structural composition of therapeutic pipelines dictates the operational focus of global contract research infrastructure. Biopharmaceutical developers are rapidly increasing investments in cell and gene therapies, which completely reshapes traditional validation protocols. Legacy clinical operating models fail when handling live cellular constructs because these advanced therapies demand highly compressed, localized vein-to-vein logistical coordination.
Sponsors are reducing discovery allocations for traditional small-molecule therapies due to generic erosion and pricing pressures, which forces a reallocation of research budgets toward complex biological entities. This transition drives immediate structural demand for specialized bioanalytical testing and advanced pharmacokinetic modeling services. Contract research organizations are responding by constructing dedicated advanced therapy processing laboratories adjacent to major clinical trial hubs.
Vaccine development pipelines maintain a distinct structural requirement for large-scale, multi-country seasonal cohort monitoring. The erratic nature of infectious disease outbreaks prevents long-term predictable enrollment scheduling, which forces sponsors to depend on highly elastic clinical trial networks. Contract entities provide the underlying framework by maintaining active, pre-screened patient registries across multiple geographic regions to enable immediate trial activation.
By Therapeutic Area
Therapeutic parameters establish the underlying operational constraints and site selection methodologies for contract validation programs. Oncology protocols dominate active research portfolios, which creates intense competition for specialized investigator sites and highly specific patient subpopulations. The shifting focus toward precise, biomarker-driven oncology treatments isolates exceptionally narrow patient cohorts, which makes conventional mass-recruitment advertising campaigns entirely ineffective.
Sponsors are shifting oncology trial designs toward adaptive, multi-arm master protocols to evaluate multiple mutations simultaneously. This operational complexity places severe structural pressure on data management teams, who must clean and lock complex datasets from disparate clinical sites in real time. Contract research organizations are mitigating this administrative strain by deploying automated, machine-learning-driven electronic data capture systems directly across their site networks.
Central nervous system disorders represent a separate operational challenge characterized by high clinical failure rates and subjective clinical endpoints. Evaluating cognitive changes requires highly standardized, multi-lingual rater training protocols to eliminate inter-site variance across global clinical networks. Cardiovascular and respiratory trials require large-scale, long-term safety observation cohorts, which shifts outsourcing demand toward long-term real-world evidence collection services.
By End-User
The financial architecture and internal resource constraints of drug developers define their specific contract outsourcing engagement models. Multinational pharmaceutical and biopharmaceutical corporations utilize consolidated, long-term strategic partnerships to standardize data collection across global therapeutic portfolios. These large organizations are continuously divesting internal laboratory real estate to replace rigid fixed costs with flexible, full-service outsourcing frameworks.
Emerging biotech and medical device entities operate with severely restricted capital structures, which renders internal laboratory development completely impossible. These smaller developers rely entirely on contract research providers to advance novel assets to proof-of-concept stages to secure venture refinancing. This total operational dependency forces contract partners to provide comprehensive regulatory consulting alongside standard bench laboratory execution.
Academic institutes and public research entities utilize contract networks to bridge basic scientific discovery with regulated clinical implementation. Academic laboratories frequently lack the strict current Good Clinical Practice certification required to generate validation data for official regulatory submissions. Outsourcing these specific validation steps to certified contract laboratories allows public researchers to preserve institutional capital while meeting international regulatory filing demands.
Regional Analysis
North America
The North American clinical research ecosystem operates under intense pressure to optimize protocol efficiency and diversify participant registries. United States biopharmaceutical firms are facing escalating domestic clinical trial costs, which forces a systemic transition toward virtual and decentralized trial models. This operational shift relies on contract research organizations capable of integrating home healthcare networks and remote data collection tools directly into central protocols.
The integration of the FDA Modernization Act 2.0 accelerates the obsolescence of conventional animal-based preclinical safety profiles across the region. Drug developers are demanding immediate access to advanced in-vitro human cell assays and organ-on-a-chip validation platforms to replace rodent testing models. Contract research providers are rapidly consolidating localized specialized laboratories to capture this high-margin preclinical demand shift.
Canadian biopharma developers are leveraging regional tax incentives to expand early-phase clinical trial allocations within the country. This trend increases localized demand for specialized phase I clinical trial facilities capable of rapid healthy volunteer enrollment. Contract entities are responding by expanding their early-phase infrastructure along major Canadian research corridors to capture these regional capital inflows.
Europe
The European contract research environment is undergoing structural realignment driven by centralized regulatory changes and strict data privacy mandates. The mandatory adoption of the Clinical Trials Regulation No 536/2014 unifies trial applications through a single European portal, which compresses trial startup timelines. This regulatory harmonization allows sponsors to execute multi-country trial strategies efficiently, which shifts demand toward contract providers with pan-European footprints.
Strict enforcement of General Data Protection Regulation frameworks limits the cross-border transmission of raw patient medical records to external jurisdictions. This legal constraint prevents the centralized processing of clinical datasets outside the European Union, which forces global sponsors to maintain localized data structures. Contract research organizations are expanding their domestic European data centers to ensure absolute compliance with regional sovereignty laws.
The United Kingdom market is carving a separate operational niche focused on highly accelerated innovative licensing pathways. British regulators utilize agile review cycles to attract early-stage cell and gene therapy trials to domestic medical centers. This localized environment drives constant demand for specialized contract regulatory consultants capable of navigating accelerated lab-to-patient access pathways.
Asia Pacific
The Asia Pacific region is rapidly developing into a high-density clinical trial execution hub due to substantial cost advantages and massive, treatment-naïve patient populations. Mainland China is modernizing its domestic regulatory infrastructure by introducing rapid thirty-day review periods for innovative drug trial applications. This regulatory velocity accelerates early-phase clinical execution, which draws substantial international research capital into Chinese medical centers.
Indian clinical infrastructure is experiencing a structural pivot toward complex bioanalytical testing and advanced biosimilar validation studies. Global pharmaceutical firms are reallocating high-volume stability testing and batch release analytics to certified Indian contract laboratories to reduce fixed operational overhead. This shift requires domestic contract facilities to upgrade their operational standards to achieve perfect alignment with international regulatory bodies.
Japanese healthcare networks maintain highly specific regulatory constraints that require distinct domestic clinical data subsets for historical safety validation. International developers must conduct local bridging studies to obtain Japanese commercial approval, which creates steady demand for domestic contract networks. This structural mechanism insulates local clinical trial providers from global consolidation trends by ensuring a continuous baseline of domestic clinical validation mandates.
Competitive Landscape
Thermo Fisher Scientific Inc.
IQVIA Holdings Inc.
ICON plc
Parexel International Corporation
NAMSA
Labcorp Holdings Inc.
WuXi AppTec Co., Ltd.
Syneos Health, Inc.
Evotec SE
Novotech Health Holdings Pte. Ltd.
CliniExperts Inc.
PharPoint Research, Inc.
Veranex
Company Profiles
Thermo Fisher Scientific Inc.
Thermo Fisher Scientific Inc. positions its outsourced clinical division as a digitally integrated enterprise leveraging proprietary laboratory instrument ecosystems. The company embeds machine learning algorithms directly into its global pharmacovigilance and data-clearing workflows to eliminate manual data entry bottlenecks. This technical integration allows the firm to compress clinical database lock timelines for global trials.
IQVIA Holdings Inc.
IQVIA Holdings Inc. leverages its proprietary healthcare data architecture to deliver advanced predictive analytics for clinical site selection and patient recruitment. The firm integrates real-world patient data assets with advanced clinical trial management software to accurately forecast regional enrollment velocities. This data-centric approach minimizes startup delays for complex, multi-site international oncology protocols.
ICON plc
ICON plc focuses on providing decentralized clinical trial architectures supported by a deeply integrated global site network. The company deploys specialized virtual communication platforms and mobile clinical monitoring units to improve patient compliance and reduce drop-out numbers. This operational infrastructure allows sponsors to execute complex protocols across geographically isolated populations.
Analyst View
Biopharmaceutical developers are fundamentally shifting their operational models toward full-service outsourcing to preserve liquid capital. Contract research organizations that combine advanced machine-learning data clearing with human-centric decentralized site management will capture high-margin validation portfolios. Structural adaptivity across changing regulatory jurisdictions remains the definitive indicator of long-term commercial resilience.
Contract Research Organizations (CRO) Services Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 131.5 billion |
| Total Market Size in 2031 | USD 186.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.22% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Molecule Type, Type, Therapeutic Area, End-User |
| Companies |
|
Table of Contents
1. Executive Summary
2. Market Snapshot
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. Business Landscape
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. Technological Outlook
5.1. Introduction
5.2. Vaccines
5.3. Cell Gene Therapy
5.4. Others
6.1. Introduction
6.2. Early Phase Development Services
6.2.1. Preclinical
6.2.2. Toxicology Testing
6.2.3. Discovery Studies
6.2.4. Chemistry, Manufacturing, and Controls
6.2.5. Pharmacokinetics /Pharmacodynamics
6.3. Clinical Research Services
6.3.1. Phase I
6.3.2. Phase II
6.3.3. Phase III
6.3.4. Phase IV
6.3.5. Phase V
6.4. Laboratory Services
6.4.1. Analytical Testing
6.4.2. Bioanalytical Testing
6.4.3. Physical Characterization
6.4.4. Stability Testing, Batch Release Testing
6.4.5. Raw Material Testing
6.4.6. Other Analytical Testing
6.5. Consulting Services
7.1. Introduction
7.2. Oncology
7.2.1. Breast Cancer
7.2.2. Lung Cancer
7.2.3. Colorectal Cancer
7.2.4. Prostate Cancer
7.2.5. Others
7.3. CNS Disorders
7.3.1. Infectious Diseases
7.3.2. Cardiovascular Diseases
7.3.3. Respiratory Disorders
7.3.4. Diabetes
7.4. Other Therapeutic Areas
8.1. Introduction
8.2. Pharmaceuticals and Biopharmaceuticals Companies
8.3. Medical Devices Companies
8.4. Academic Institutes
9.1. Introduction
9.2. North America
9.2.1. By Molecule Type
9.2.2. By Type
9.2.3. By Therapeutic Area
9.2.4. By End-User
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Molecule Type
9.3.2. By Type
9.3.3. By Therapeutic Area
9.3.4. By End-User
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Molecule Type
9.4.2. By Type
9.4.3. By Therapeutic Area
9.4.4. By End-User
9.4.5. By Country
9.4.5.1. United Kingdom
9.4.5.2. Germany
9.4.5.3. France
9.4.5.4. Spain
9.4.5.5. Others
9.5. Middle East and Africa
9.5.1. By Molecule Type
9.5.2. By Type
9.5.3. By Therapeutic Area
9.5.4. By End-User
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. UAE
9.5.5.3. Israel
9.5.5.4. Others
9.6. Asia Pacific
9.6.1. By Molecule Type
9.6.2. By Type
9.6.3. By Therapeutic Area
9.6.4. By End-User
9.6.5. By Country
9.6.5.1. Japan
9.6.5.2. China
9.6.5.3. India
9.6.5.4. South Korea
9.6.5.5. Indonesia
9.6.5.6. Thailand
9.6.5.7. Taiwan
9.6.5.8. Others
10. Competitive Environment and Analysis
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. Company Profiles
11.1. Thermo Fisher Scientific Inc.
11.2. IQVIA Holdings Inc.
11.3. ICON plc
11.4. Parexel International Corporation
11.5. NAMSA
11.6. Labcorp Holdings Inc.
11.7. WuXi AppTec Co., Ltd.
11.8. Syneos Health, Inc.
11.9. Evotec SE
11.10. Novotech Health Holdings Pte. Ltd.
11.11. CliniExperts Inc.
11.12. PharPoint Research, Inc.
11.13. Veranex
12. Research Methodology
List of Figures
List of Tables
Navigate
Trusted by the world's leading organizations











