
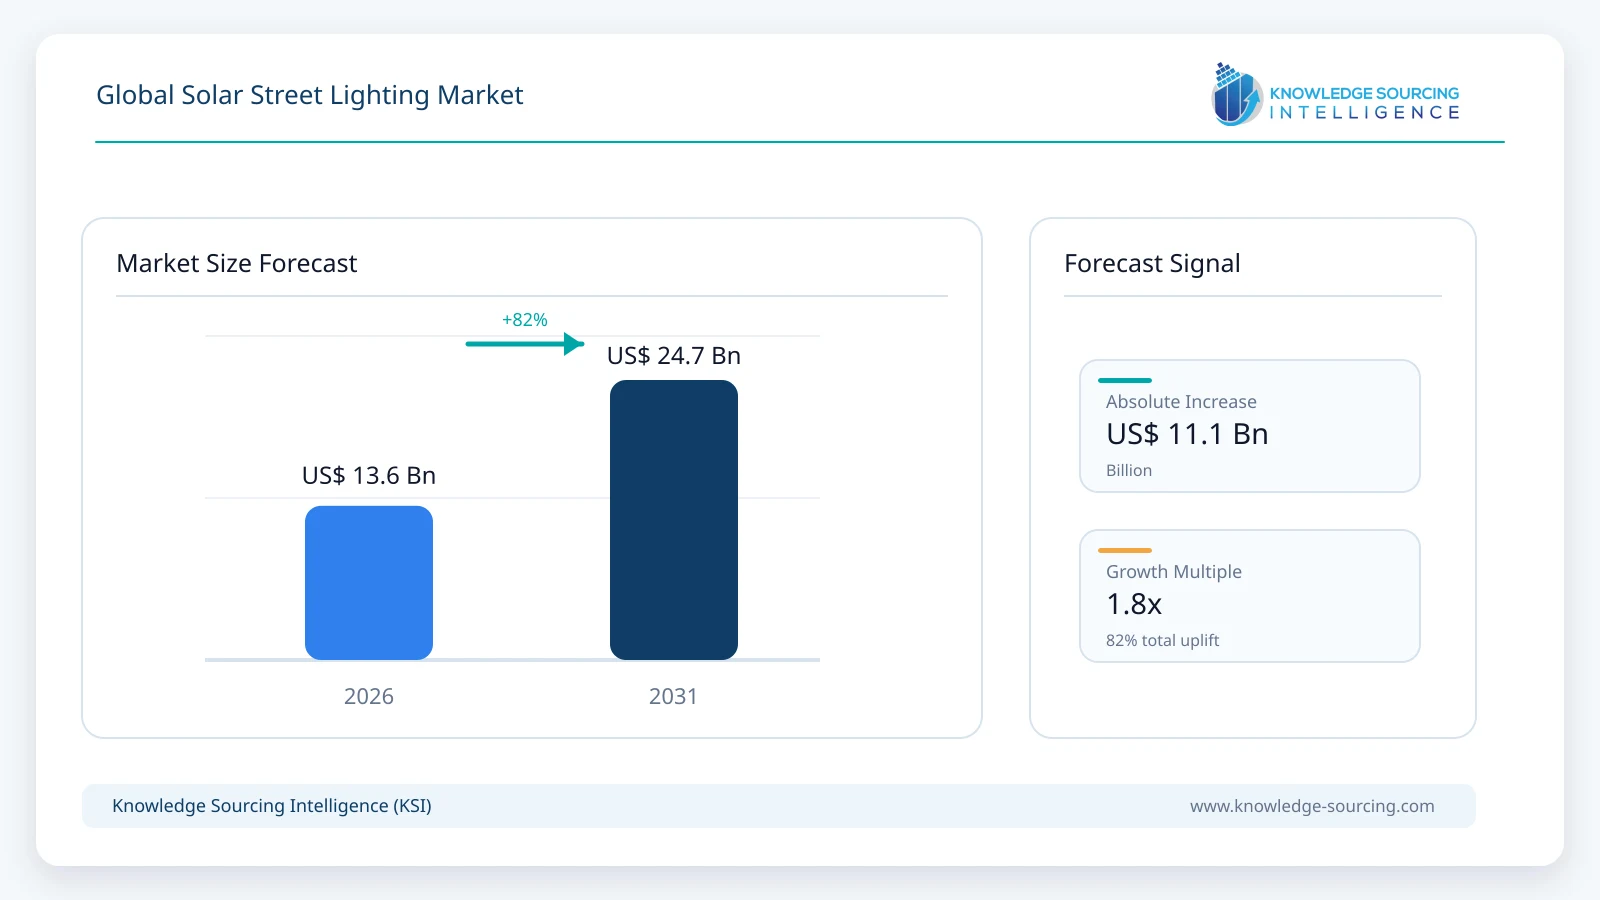
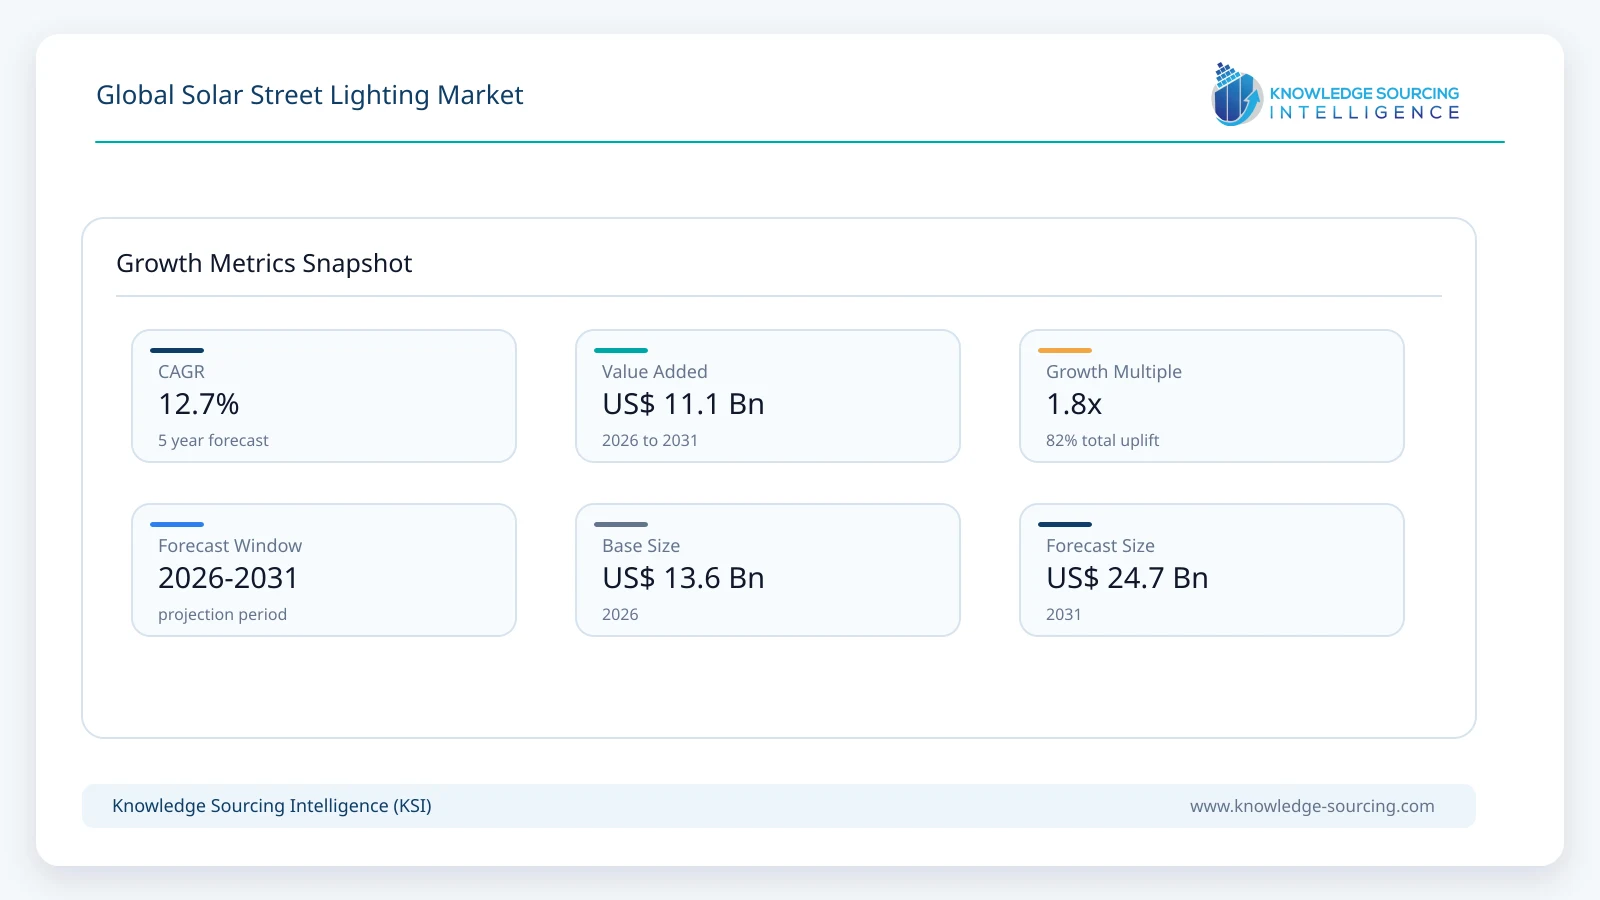
The Solar Street Lighting Market is forecast to grow at a CAGR of 12.7%, reaching USD 24.7 billion in 2031 from USD 13.6 billion in 2026.
Highlights:
- 1Off-grid infrastructure economicsare supporting standalone solar lighting where grid extension, trenching, and electricity supply costs make conventional lighting less attractive.
- 2Roads and streetsrepresent the most commercially important application because municipalities and road authorities require extensive, standardized outdoor illumination.
- 3LED technologyis becoming the preferred lighting source because higher efficacy reduces photovoltaic and battery sizing requirements.
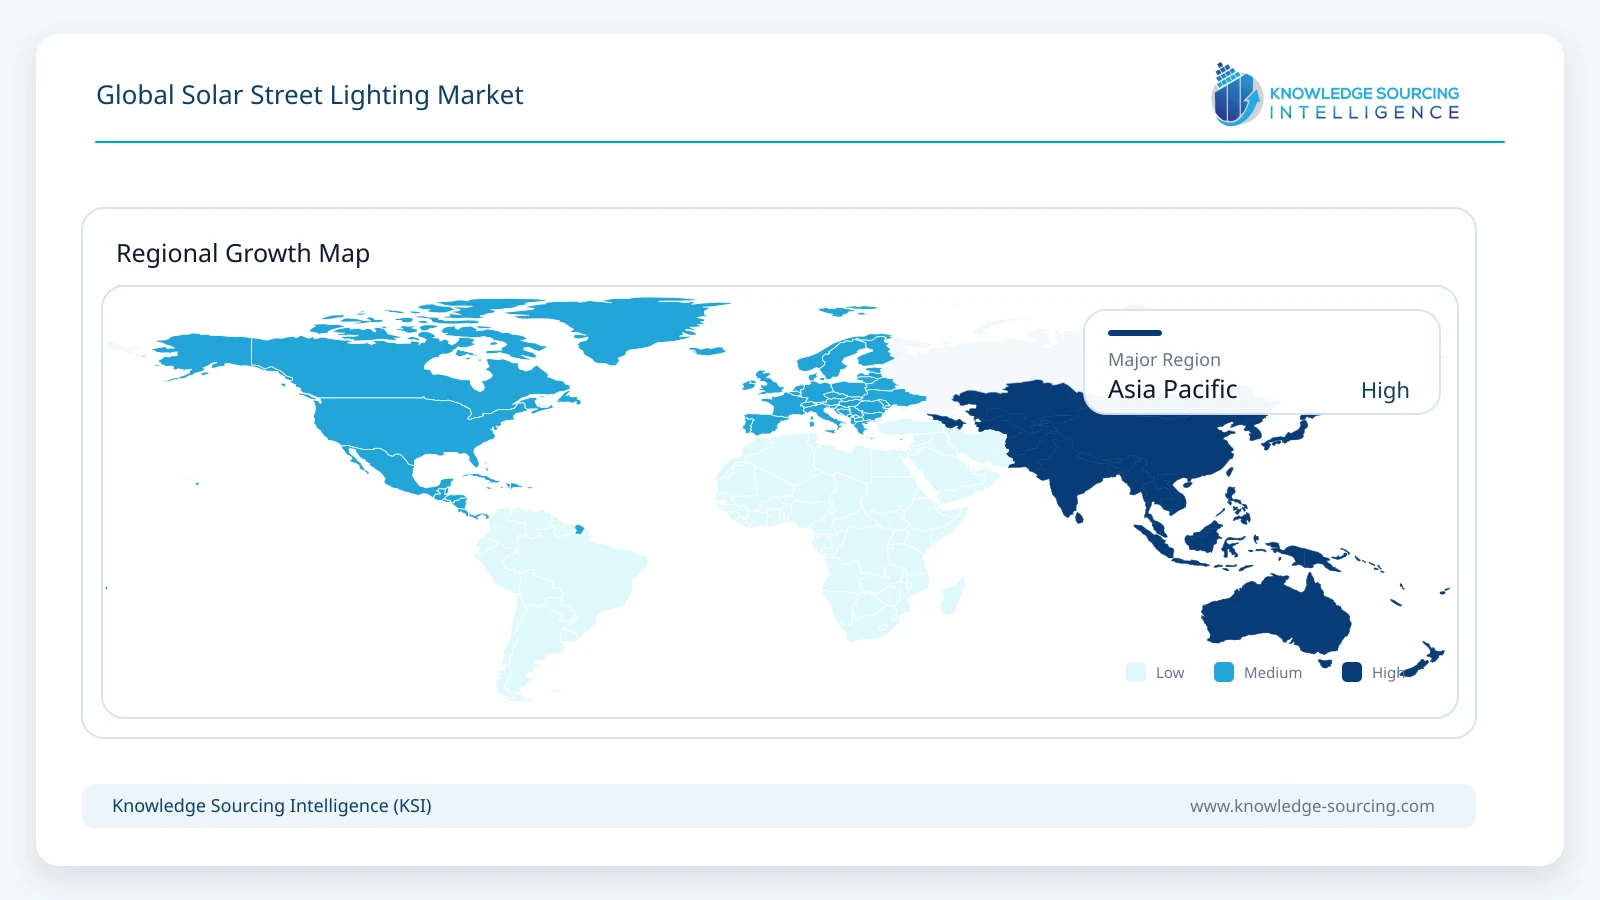
- 4Asia Pacifichas substantial demand potential because of municipal infrastructure expansion, rural lighting programs, solar manufacturing capacity, and large public-sector procurement volumes.
- 5Remote monitoring and adaptive lightingare becoming important procurement criteria as buyers place greater emphasis on lifecycle maintenance and operating reliability.
- 6Technical standards and public procurement rulesare influencing product specifications, warranty requirements, testing, and the eligibility of solar components in government-supported projects.
The solar street lighting market covers the design, manufacture, supply, installation, commissioning, monitoring, and maintenance of lighting systems that use photovoltaic generation to provide outdoor illumination. A typical system combines a solar module, battery storage, charge controller, LED or CFL luminaire, pole structure, and control equipment. Depending on project architecture, the system can operate independently of the electricity grid or interact with a grid-connected power network. The market therefore sits at the intersection of public lighting, distributed solar generation, energy-efficient lighting, municipal infrastructure, and off-grid electrification.
The commercial case for solar street lighting is strongest where conventional grid-connected lighting requires costly distribution extensions, trenching, cabling, transformers, or recurring electricity expenditure. It is also relevant for municipalities seeking to replace aging lighting assets, developers installing lighting in new residential or commercial areas, industrial operators requiring perimeter and access-road illumination, and public agencies extending lighting coverage to rural or remote communities. Solar streetlights can reduce dependence on underground or overhead electrical infrastructure because electricity is generated and stored at the point of use.
Demand is consequently shaped less by lighting requirements alone and more by the economics of infrastructure deployment. Buyers evaluate illumination levels, autonomy, battery chemistry, photovoltaic capacity, pole design, expected operating life, maintenance requirements, environmental resistance, warranty coverage, remote monitoring capability, and total installed cost. Public procurement also places greater weight on documented technical specifications, testing, service capability, and supplier experience. These criteria make solar street lighting a systems market rather than a simple luminaire market.
Government procurement provides an important demand channel. India's Ministry of New and Renewable Energy maintains technical specifications for solar street lights and solar lighting systems, while state-level programs continue to specify equipment performance, warranty, installation, and monitoring requirements. MNRE reports 944,802 solar street lights under its solar off-grid applications, illustrating the role of public programs in establishing installed demand.
The procurement model is also shifting toward lifecycle performance. Haryana's 2026 annual rate contract for 20,000 solar street lighting systems requires remote monitoring systems and a seven-year warranty for the complete system. Such specifications indicate that public buyers are moving beyond the lowest equipment price and examining reliability, after-sales service, monitoring, and long-term operating performance.
The market is not restricted to locations without electricity. In grid-served cities, standalone solar lighting can be economically attractive for parks, pathways, parking areas, campuses, perimeter roads, and new developments where extending existing electrical infrastructure is expensive or administratively difficult. Solar lighting can also provide resilience against grid outages when appropriately designed with sufficient battery autonomy.
Technology economics increasingly favor LED-based systems. LED luminaires provide high luminous efficacy and can be dimmed according to operating schedules, movement, or local activity. This reduces the energy requirement that must be supplied by the photovoltaic module and stored in the battery. Signify's solar street lighting portfolio, for example, integrates LED lighting with photovoltaic generation, lithium iron phosphate batteries, and charge-management systems, while its solar products are designed for road, pathway, campus, industrial, and public-space applications.
Battery performance remains a major determinant of project economics. A system designed for several consecutive nights of autonomy requires sufficient storage capacity and appropriate energy-management controls. Temperature, solar irradiation, dust, shading, nighttime operating profiles, and battery degradation all affect the required system size. Suppliers therefore compete on system engineering rather than only lamp output.
The market has also begun incorporating connected management. Remote monitoring can provide information on battery condition, solar generation, luminaire operation, faults, and lighting schedules. For municipalities operating thousands of units, this can reduce manual inspection requirements and allow maintenance teams to prioritize failed or underperforming assets. Signify's connected street-lighting offering includes remote dashboards, fault alerts, adaptive dimming, and solar integration.
Market Drivers
Expansion of Lighting Infrastructure in Areas Where Grid Extension Is Uneconomic
The strongest structural driver is the ability to provide lighting without constructing a dedicated electricity connection for every lighting point. Conventional street lighting can require poles, cables, distribution equipment, trenching, transformers, and connection approvals. These requirements become particularly expensive on low-density roads, village approaches, remote settlements, industrial access roads, parks, and isolated public facilities.
Standalone solar systems shift the infrastructure requirement from centralized electricity distribution to localized generation and storage. This changes the investment calculation for municipalities and infrastructure developers. Instead of evaluating only the price of the luminaire, buyers compare the complete installed cost of solar lighting with the cost of extending electrical infrastructure.
This model is particularly relevant where roads are being constructed faster than electricity infrastructure can be expanded. Public agencies can procure lighting as an independent infrastructure package, reducing dependence on the timing of grid construction. The result is a demand environment in which solar street lighting competes with conventional streetlights on total project economics rather than electricity consumption alone.
Public Infrastructure Programs and Municipal Procurement
Government programs create an important base of demand because public agencies control extensive road, village, park, institutional, and community lighting infrastructure. Procurement programs also establish technical benchmarks that influence private-sector purchasing.
India provides a useful example. MNRE has maintained technical specifications for solar street lighting and previously supported large-scale installation through off-grid programs. State agencies continue to issue tenders and rate contracts for solar lighting. Haryana's 2026 procurement program includes 20,000 solar street lighting systems, while its 2025 budget-related program provided for solar lighting on village roads and Amrit Sarovars.
For suppliers, government procurement rewards the ability to meet defined performance requirements at scale. Suppliers must demonstrate product conformity, installation capacity, service coverage, documentation, and warranty support. This creates a barrier to entry for companies that can manufacture individual lamps but cannot manage large infrastructure contracts.
Declining Energy Requirements Through LED and Intelligent Controls
LED adoption strengthens the economic case for solar lighting because lower power consumption reduces the size of the photovoltaic array and battery needed to deliver a specified illumination profile. The reduction becomes particularly valuable when projects require several nights of autonomy.
Lighting schedules can further reduce energy consumption. Instead of operating at maximum output throughout the night, controllers can reduce illumination during periods of low activity and increase output when movement is detected or traffic levels rise. Signify's newer solar street lighting systems incorporate motion sensing, adaptive lighting, and configurable operation.
This technology direction affects procurement decisions. Buyers increasingly assess the complete energy-management architecture, including luminaire efficacy, dimming performance, controller intelligence, battery utilization, and monitoring capability. Suppliers that can demonstrate reliable energy management can potentially reduce system size or improve autonomy without proportionally increasing installed equipment.
Growth of Rural, Remote, and Resilient Lighting Requirements
Solar street lighting has a distinct advantage in locations where electricity access is limited or grid reliability is inadequate. Remote communities, rural roads, mountain areas, islands, border regions, parks, and isolated infrastructure can require public lighting even when connecting each location to a reliable grid is expensive.
The same consideration applies to resilience. Public authorities may use standalone solar lights at strategic locations where nighttime visibility must remain available during grid interruptions. Solar streetlights can operate independently when properly sized and maintained, reducing dependence on centralized electricity supply.
This demand is not limited to developing economies. High-cost civil works, difficult terrain, environmental constraints, and requirements for temporary or emergency lighting can also make autonomous systems commercially relevant in developed markets.
Increasing Emphasis on Lifecycle Service and Remote Monitoring
Large solar streetlight deployments create maintenance challenges because failures can occur across geographically dispersed installations. Traditional maintenance models rely on physical inspection, which increases labor and vehicle costs. Remote monitoring changes the service model by identifying battery, controller, luminaire, or communication problems before a technician is dispatched.
Haryana's 2026 procurement requirements provide evidence of this shift, combining remote monitoring with a seven-year complete-system warranty. Sunna Design has similarly developed digital tools for configuration, commissioning, and monitoring of solar lighting installations.
For suppliers, this creates recurring service opportunities while improving the measurable performance of installed assets. For buyers, monitoring can support asset management and reduce unnecessary field visits.
Market Restraints and Challenges
High Upfront System Cost Compared With Basic Grid Lighting
Solar streetlights generally require several integrated components at each lighting point, including photovoltaic generation, battery storage, controller electronics, luminaire, and mounting structure. The initial cost can therefore be higher than a basic grid-connected luminaire, particularly where electrical infrastructure is already available.
The relevant comparison is total cost of ownership rather than lamp price, but public procurement budgets may still favor lower initial expenditure. Suppliers and project developers must therefore demonstrate savings from avoided cabling, reduced electricity purchases, lower civil works, and lower maintenance requirements.
Financing structures can mitigate the constraint. Long-term service contracts, performance-based procurement, and lifecycle-cost evaluation can spread expenditure over the operating period rather than forcing buyers to optimize only for initial capital cost.
Solar Resource Variability and Battery Degradation
System reliability depends on adequate energy generation and storage. Cloud cover, seasonal irradiation, dust accumulation, shading, high temperatures, and unexpected nighttime usage can reduce available energy. Battery degradation further reduces storage capacity over time.
This challenge affects both suppliers and buyers. Manufacturers must correctly size systems for local climatic conditions, while procurement agencies must specify realistic autonomy requirements. Oversizing increases capital cost, whereas undersizing can result in premature nighttime shutdowns.
Advanced energy-management systems, higher-efficiency photovoltaic modules, better battery chemistries, configurable lighting profiles, and appropriate system engineering can reduce the risk, but they do not eliminate the underlying dependence on weather conditions.
Maintenance and Replacement of Distributed Components
Although solar streetlights can reduce recurring electricity costs, they still contain components that require inspection and eventual replacement. Batteries have finite operating lives, photovoltaic modules accumulate dirt, controllers can fail, and luminaires may require replacement after long service periods.
The dispersed nature of installations can make maintenance expensive. A failure at one remote pole may require a dedicated service visit. Suppliers with established service networks therefore have an advantage in public procurement, particularly when contracts include multi-year warranties.
Buyers increasingly address this issue through service-level requirements, spare-parts availability, remote diagnostics, standardized components, and warranty provisions.
Product Quality Variation and Procurement Risk
The market includes systems with substantial differences in photovoltaic capacity, battery chemistry, controller quality, LED efficacy, mechanical construction, environmental protection, and actual autonomy. Two systems with similar advertised wattage can therefore deliver materially different performance.
Government agencies have responded by establishing technical specifications and testing requirements. MNRE maintains specifications for solar street lighting and related systems, while state agencies publish detailed technical requirements in procurement programs.
Standardized testing and documented performance reduce procurement risk, but they also increase compliance costs for manufacturers. Smaller suppliers may struggle to maintain certification, testing, documentation, and service infrastructure at the same level as established vendors.
Local Manufacturing and Supply Chain Requirements
Solar streetlights depend on several upstream industries, including photovoltaic modules, batteries, LEDs, controllers, electronics, aluminum housings, poles, and communications equipment. Supply disruptions or changes in component prices can affect system economics.
Government procurement can add another layer through domestic-content or approved-component requirements. India's solar policy framework illustrates how eligibility rules for photovoltaic modules and cells can influence government and government-assisted projects. MNRE's ALMM framework is periodically updated, including provisions affecting off-grid applications such as solar lights and solar streetlights.
Suppliers therefore need flexible sourcing strategies while maintaining compliance with applicable procurement rules.
Major Segment Analysis
Standalone Segment by Connection Type
The standalone segment is the most commercially important connection category because the fundamental value proposition of solar street lighting is the ability to provide illumination without dependence on a continuous grid connection.
Standalone systems integrate photovoltaic generation and battery storage directly into the lighting asset. This architecture is particularly suitable for rural roads, remote communities, pathways, parks, parking areas, industrial sites, campuses, and new developments where grid connection is unavailable, unreliable, or economically unattractive.
Buyer requirements in this segment are centered on autonomy, reliability, battery life, photovoltaic efficiency, lighting uniformity, environmental resistance, and installation simplicity. Public-sector buyers additionally examine warranty periods, spare-parts availability, service-center coverage, and supplier experience.
The economics of standalone systems improve when civil works for grid extension are expensive. A solar unit can be installed after foundation and pole preparation without requiring a long cable route back to a power source. Sunna Design identifies applications ranging from urban streets and highways to remote and non-electrified roads, while Signify positions integrated solar systems for roads, pedestrian paths, campuses, and other areas.
Competition within the standalone segment is shifting toward complete system performance. Suppliers differentiate through photovoltaic efficiency, battery technology, energy-management algorithms, LED efficacy, mechanical durability, monitoring, warranty coverage, and ease of installation. Sunna Design's EverGen 3, for example, combines a LiFePO4 battery, energy-management system, and high-efficiency photovoltaic technology in a redesigned system architecture intended to simplify installation and reduce maintenance requirements.
The revenue implications extend beyond the initial hardware sale. Large projects can generate installation, monitoring, maintenance, replacement-battery, software, and extended-warranty revenue. Suppliers with strong lifecycle-service capabilities can therefore capture a larger share of project value than manufacturers competing only on equipment price.
The segment should remain central to market development through 2031 because it addresses the infrastructure problem most directly: delivering dependable illumination without first building a conventional electricity distribution connection.
Regional Analysis
North America
North American demand is influenced by municipal infrastructure renewal, parks and recreational facilities, pedestrian infrastructure, parking areas, commercial developments, and locations where extending electrical connections is costly. Buyers generally have high expectations regarding photometric performance, mechanical durability, warranty support, and compliance with local electrical and lighting requirements.
The market is more project-specific than subsidy-dependent. Municipalities and private developers assess solar systems against conventional lighting on installation economics, operating costs, resilience, and site constraints. Solar streetlights can be attractive for pathways, remote parking, parks, campuses, and new infrastructure where trenching would create substantial civil costs.
Competition is therefore centered on engineering quality and application suitability rather than solely on energy-access considerations. Climate exposure also matters, with suppliers needing to design systems for snow, extreme temperatures, hurricanes, dust, and varying solar resources depending on location.
Europe
European demand is influenced by energy-efficiency objectives, public-sector decarbonization policies, urban sustainability programs, light-pollution considerations, and modernization of outdoor lighting infrastructure. Buyers increasingly evaluate illumination quality together with energy consumption and environmental impact.
European suppliers have also placed greater attention on circularity, repairability, and ecological design. Signify's SunStay Pro gen2 mini, launched in 2025, uses an aluminum die-cast housing containing 80% recycled material and incorporates adaptive lighting features.
Sunna Design's product development similarly addresses light pollution and dark-sky considerations. Its Elektra fixture was introduced with optics and warmer LED color temperatures designed to reduce unwanted light impacts.
The primary constraint is that many European urban areas already possess extensive grid-connected lighting infrastructure. Solar systems therefore compete mainly where asset replacement, decentralized deployment, resilience, or difficult civil works create a clear economic case.
Asia Pacific
Asia Pacific represents a major demand center because it combines large urban populations, extensive rural infrastructure requirements, manufacturing capacity, solar-resource availability, and government-supported renewable-energy deployment.
China has a substantial industrial supply base for photovoltaic modules, batteries, LEDs, controllers, poles, and lighting components. This creates opportunities for large-scale production and competitive equipment costs. India is another important market because public agencies continue to procure solar streetlights for rural roads, community areas, parks, and other public infrastructure.
India's policy environment is particularly relevant. MNRE maintains technical specifications for solar street lights, while state programs continue to conduct tenders and rate contracts. Haryana's 2026 procurement of 20,000 systems with remote monitoring and seven-year warranty requirements demonstrates the scale and increasingly formalized nature of public procurement.
Japan, South Korea, Australia, Indonesia, and Thailand offer different demand profiles. Mature economies tend to emphasize infrastructure modernization, resilience, and lifecycle cost, while emerging markets provide opportunities through rural infrastructure, public lighting expansion, industrial development, and new residential areas.
Middle East and Africa
The Middle East and Africa provide strong application relevance because of high solar irradiation in many locations, remote settlements, infrastructure expansion, and the cost of extending conventional electricity networks to dispersed assets.
In the Middle East, demand can include roads, parks, residential developments, industrial areas, logistics facilities, and public spaces. High temperatures place greater demands on batteries, electronics, and luminaire thermal management. Suppliers therefore need products designed for sustained operation in hot environments.
Africa presents a broader off-grid opportunity. Solar streetlights can provide public illumination in settlements where grid access remains limited or where electricity supply is unreliable. They can also support market areas, roads, health facilities, schools, and community infrastructure.
The principal challenges are financing, public procurement capacity, after-sales service, theft or vandalism risk in some locations, and battery replacement logistics. Suppliers that can provide local service networks and durable equipment have an advantage over vendors that only supply hardware.
South America
South American demand is supported by urban expansion, rural roads, public infrastructure modernization, and the availability of solar resources in many areas. Brazil is the largest market in the regional grouping because of its population, extensive road network, municipal infrastructure requirements, and geographically dispersed communities.
Procurement decisions vary considerably between municipalities and project types. Solar streetlights can be attractive where electricity infrastructure is difficult to extend, while urban areas with established distribution networks may prioritize grid-connected LED modernization.
Remote monitoring and durable equipment are relevant where lighting assets are geographically dispersed. Suppliers must also account for humidity, rainfall, heat, and regional differences in solar irradiation.
Competitive Landscape
The competitive structure includes global lighting companies, specialist solar-lighting manufacturers, regional suppliers, and project-oriented system integrators. The companies covered in this analysis are Signify Holding B.V., Omega Solar, Dragons Breath Solar, Solektra International, SOKOYO Solar Group, Sunna Design, Solar Street Lights USA, and Urja Global Limited.
Competition is based on more than luminaire output. Buyers compare photovoltaic capacity, battery chemistry, autonomy, LED efficacy, mechanical construction, control systems, remote monitoring, installation requirements, warranty coverage, and service capabilities. Large public projects can also require suppliers to provide engineering, procurement, installation, commissioning, and maintenance as a combined package.
Signify's competitive position reflects integration with a broad professional lighting portfolio and connected-lighting capabilities. Its 2025 SunStay Pro gen2 and SunStay Pro gen2 mini launches demonstrate a strategy centered on modular solar systems, connected control, adaptive lighting, and application-specific configurations.
Sunna Design competes as a specialist solar-lighting provider with a strong emphasis on autonomous systems, energy management, system durability, and lifecycle services. The company reported more than 160,000 solar lighting solutions deployed across more than 60 countries by January 2025, indicating an established international project base.
SOKOYO Solar Group and the other specialist and regional suppliers listed in the competitive set participate in a market where manufacturing scale, cost control, project execution, geographic reach, and product customization can materially influence contract awards.
Partnerships with distributors, engineering contractors, municipalities, renewable-energy agencies, and infrastructure developers are strategically important because solar street lighting is frequently procured as an installed system. Geographic expansion therefore depends on local tender access and service capability as much as product availability.
Technology positioning is also moving toward integrated systems. High-efficiency LEDs, lithium-based batteries, adaptive dimming, remote diagnostics, improved photovoltaic modules, and modular mechanical designs are becoming important differentiation points. Suppliers able to combine these technologies while maintaining competitive installed costs should be better positioned for large infrastructure contracts.
Recent Developments
August 2026: Streetleaf highlighted solar-powered streetlighting for utility resilience, addressing grid constraints, outages, theft, maintenance backlogs, and infrastructure reliability through off-grid lighting solutions.
August 2026: Inlux Solar launched the DRAGON INL-AIT8 All-In-Two solar street light, supporting higher-capacity LiFePO? storage and configurations for highways, municipal roads, industrial areas and off-grid infrastructure.
August 2026: Sustainability Partners and Sun ’N Lake Improvement District deployed 375 solar-powered LED streetlights across central Florida, using an infrastructure-as-a-service model to improve roadway lighting without conventional grid connections.
February 2026: Haryana's New and Renewable Energy Department published an annual rate contract for the supply, installation, and commissioning of 20,000 solar street lighting systems with remote monitoring and a seven-year complete-system warranty. The procurement illustrates stronger public-sector emphasis on lifecycle performance and monitoring.
October 2025: Sunna Design launched EverGen 3, a new high-power autonomous solar streetlight platform combining a LiFePO4 battery, intelligent energy management, and high-efficiency N-type TOPCon photovoltaic technology. The development targets installation efficiency, energy performance, and lower maintenance requirements.
September 2025: Signify introduced the SunStay Pro gen2 and SunStay Pro gen2 mini connected solar streetlights, adding modular configurations, adaptive lighting, motion sensing, and application flexibility for pathways, campuses, and pedestrian areas. The launch strengthened the role of connected controls within professional solar streetlighting.
Regulatory and Policy Environment
Regulation affects the market through photovoltaic component eligibility, lighting performance requirements, electrical safety, public procurement rules, environmental requirements, and standards governing installation and operation.
In India, MNRE maintains specifications for solar street lights, including requirements covering batteries and 12 W LED solar street lighting systems. These specifications provide a technical reference for government-supported procurement and help standardize minimum system performance.
The Approved List of Models and Manufacturers framework also affects photovoltaic component procurement in government and government-assisted projects. MNRE's current framework includes updated lists for solar PV modules and cells and specific amendments concerning off-grid applications such as solar lights and solar streetlights.
In July 2026, MNRE issued a notification concerning implementation of the Solar Systems, Devices and Components Goods Order 2025. Such product-control measures increase the importance of traceability, conformity, and supplier documentation in the Indian market.
State-level procurement requirements can be even more commercially consequential because they define system specifications, quantities, warranty periods, installation obligations, service arrangements, and monitoring requirements. Haryana's 2026 documents illustrate this approach, including seven-year warranties and remote monitoring for a large solar streetlight procurement.
Lighting standards also influence product design. Road authorities generally require adequate illuminance, uniformity, glare control, appropriate color characteristics, mechanical safety, and dependable nighttime operation. Solar suppliers must therefore engineer the photovoltaic and battery system around the required lighting performance rather than simply maximizing lamp wattage.
Environmental requirements are becoming more relevant as well. Battery disposal, photovoltaic module end-of-life management, material recovery, light pollution, and circular design can affect product specifications and public procurement. Sunna Design's recent product and recycling initiatives illustrate how lifecycle considerations are entering solar-lighting product development.
Outlook and Strategic Implications
The 2026–2031 outlook for solar street lighting will be determined by the economics of decentralized infrastructure, municipal investment cycles, battery performance, LED efficiency, photovoltaic technology, and the ability of suppliers to provide reliable lifecycle service.
Procurement is expected to place greater weight on total cost of ownership. Buyers are likely to compare equipment cost with avoided grid extension, electricity expenditure, civil works, maintenance labor, and replacement requirements. This favors suppliers that can provide credible performance data and long-term service commitments rather than products positioned primarily around low purchase prices.
Standalone systems should remain commercially important because they address applications where conventional grid infrastructure is difficult or expensive to deploy. Rural roads, parks, pathways, remote settlements, industrial perimeters, parking facilities, and new developments can all create demand without requiring a major electricity-network investment.
LED technology will remain central to system economics. Higher luminous efficacy allows suppliers to provide required illumination using less stored energy, creating opportunities to reduce battery and photovoltaic sizing. Adaptive dimming and motion sensing can further improve energy utilization, particularly where pedestrian or vehicle activity varies considerably during the night.
Battery technology will remain a strategic differentiator. Buyers will increasingly examine usable capacity, cycle life, temperature performance, warranty terms, replacement costs, and safety. Lithium iron phosphate batteries are already prominent in modern systems, and suppliers that combine suitable battery chemistry with intelligent energy management can improve reliability while controlling system size.
Remote monitoring is likely to become a standard feature in larger deployments. Municipalities managing thousands of poles need asset-level visibility rather than periodic manual inspection. Monitoring platforms can support predictive maintenance, warranty administration, fault identification, and performance verification. The inclusion of remote monitoring in Haryana's 20,000-unit procurement signals the commercial importance of this capability.
Product architecture is also likely to become more modular. Separating or simplifying photovoltaic panels, batteries, controllers, and luminaires can improve installation, servicing, and component replacement. Suppliers may increasingly offer application-specific configurations rather than one standard unit for every road and climate.
Competitive positioning will increasingly depend on geographic execution. Public lighting projects require local installation, commissioning, maintenance, spare parts, and compliance with procurement rules. A supplier with technically strong products but weak field-service infrastructure can lose contracts to a less technologically sophisticated competitor with stronger local execution.
Regulatory compliance will remain a commercial issue rather than merely an administrative requirement. Changes to photovoltaic component eligibility, product standards, environmental requirements, and public procurement rules can affect sourcing decisions and project economics. Suppliers serving government customers will need stronger documentation and supply-chain visibility.
The principal risks through 2031 include battery replacement costs, extreme weather exposure, inconsistent solar resources, component-price volatility, poor-quality installations, theft or vandalism in some markets, and procurement delays. These risks can be mitigated through appropriate system sizing, durable mechanical design, remote monitoring, local service partnerships, extended warranties, and transparent lifecycle-cost calculations.
Strategically, suppliers should prioritize complete system performance over isolated component specifications. The winning proposition will increasingly combine efficient LED optics, reliable photovoltaic generation, durable battery storage, intelligent energy management, monitoring, installation support, and long-term maintenance.
For investors and infrastructure developers, the most attractive opportunities are likely to occur where solar lighting eliminates substantial grid-extension costs or solves a clear reliability problem. For municipalities, the strongest business case will come from projects where avoided civil works and energy expenditure offset the initial cost of decentralized equipment.
Overall, the solar street lighting market is moving from a basic off-grid lighting application toward a more engineered infrastructure solution. The next phase of market development will be shaped by lifecycle economics, system reliability, public procurement standards, connected asset management, and the ability to deliver consistent lighting performance across diverse climates and applications. Suppliers that can demonstrate measurable operating value, maintain local service capability, and comply with increasingly detailed technical requirements should be best positioned to capture infrastructure spending during 2026–2031.
Solar Street Lighting Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.6 billion |
| Total Market Size in 2031 | USD 24.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Connection Type, Lighting Source, Application, Geography |
| Companies |
|
Market Segmentation
By Connection Type
By Lighting Source
By Application
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Market Trends
3.5. Porter’s Five Forces Analysis
3.6. Industry Value Chain Analysis
3.7. Policies and Regulations
3.8. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. LED Lighting Technology
4.2. Solar Photovoltaic Technology
4.3. Battery Storage Technology
4.4. Charge Controller Technology
4.5. Smart and Connected Solar Street Lighting
4.6. Motion Sensors and Adaptive Lighting
5. GLOBAL SOLAR STREET LIGHTING MARKET BY CONNECTION TYPE
5.1. Introduction
5.2. Standalone
5.3. Grid Connected
6. GLOBAL SOLAR STREET LIGHTING MARKET BY LIGHTING SOURCE
6.1. Introduction
6.2. CFL
6.3. LED
7. GLOBAL SOLAR STREET LIGHTING MARKET BY APPLICATION
7.1. Introduction
7.2. Roads and Streets
7.3. Residential Areas
7.4. Commercial Areas
7.5. Industrial Areas
7.6. Parking Areas
7.7. Parks and Public Spaces
7.8. Pathways and Cycleways
7.9. Rural and Remote Areas
7.10. Others
8. GLOBAL SOLAR STREET LIGHTING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. Indonesia
8.6.7. Thailand
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Product and Technology Comparison
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Signify Holding B.V.
10.2. Omega Solar
10.3. Dragons Breath Solar
10.4. Solektra International
10.5. SOKOYO Solar Group
10.6. Sunna Design
10.7. Solar Street Lights USA
10.8. Urja Global Limited
11. APPENDIX
11.1. Research Methodology
11.2. Currency
11.3. Assumptions
11.4. Base and Forecast Years Timeline
11.5. Key Benefits for Stakeholders
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











