
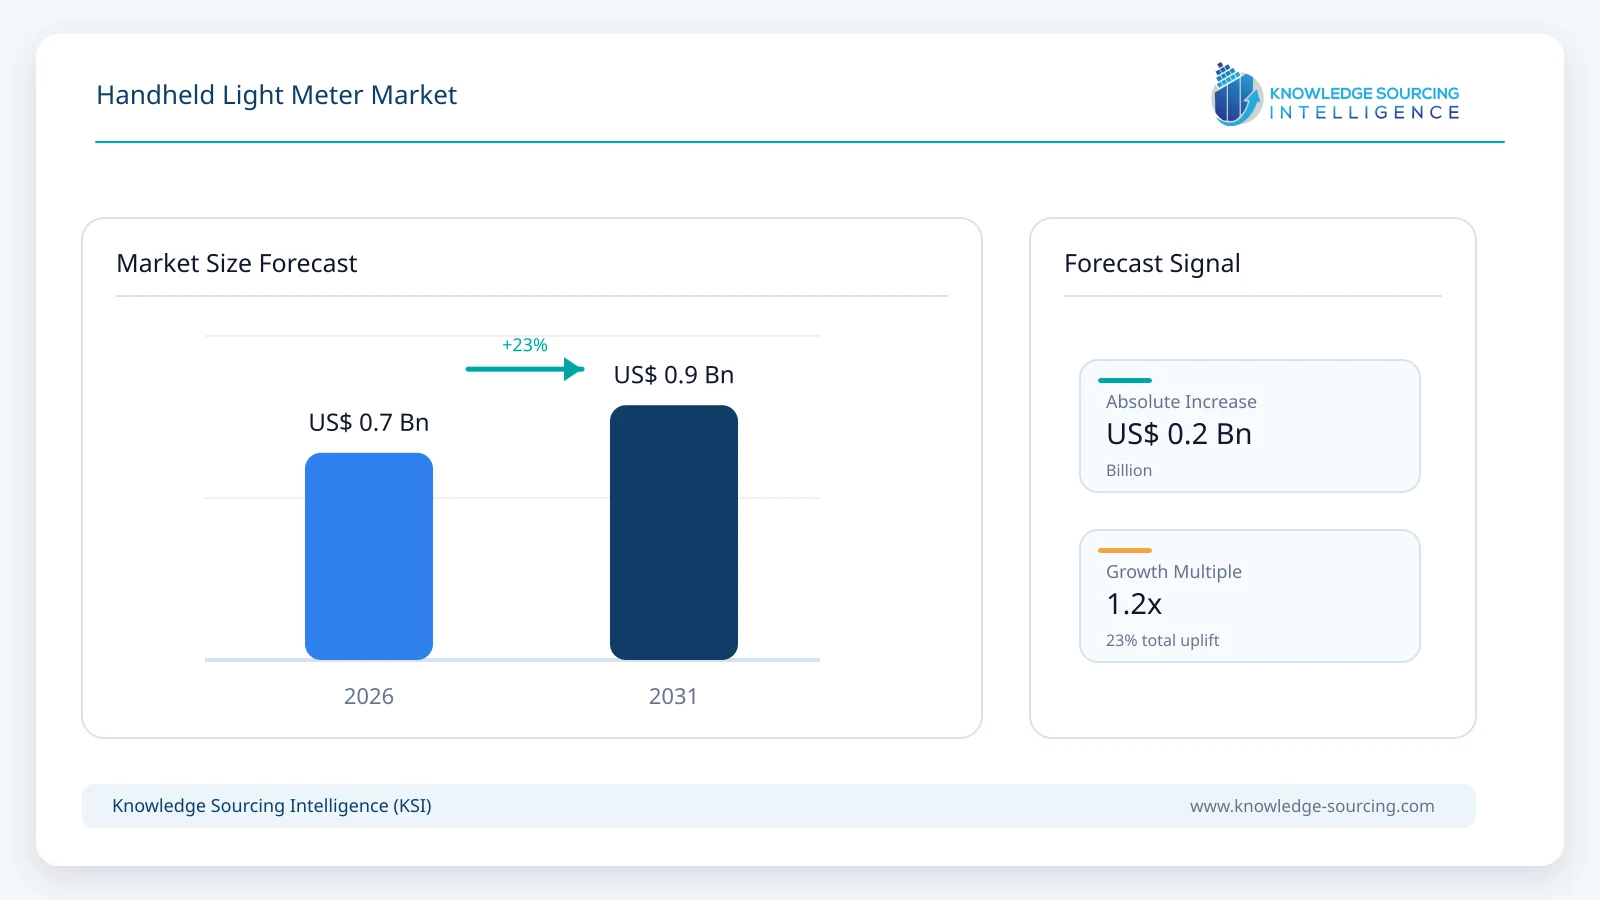
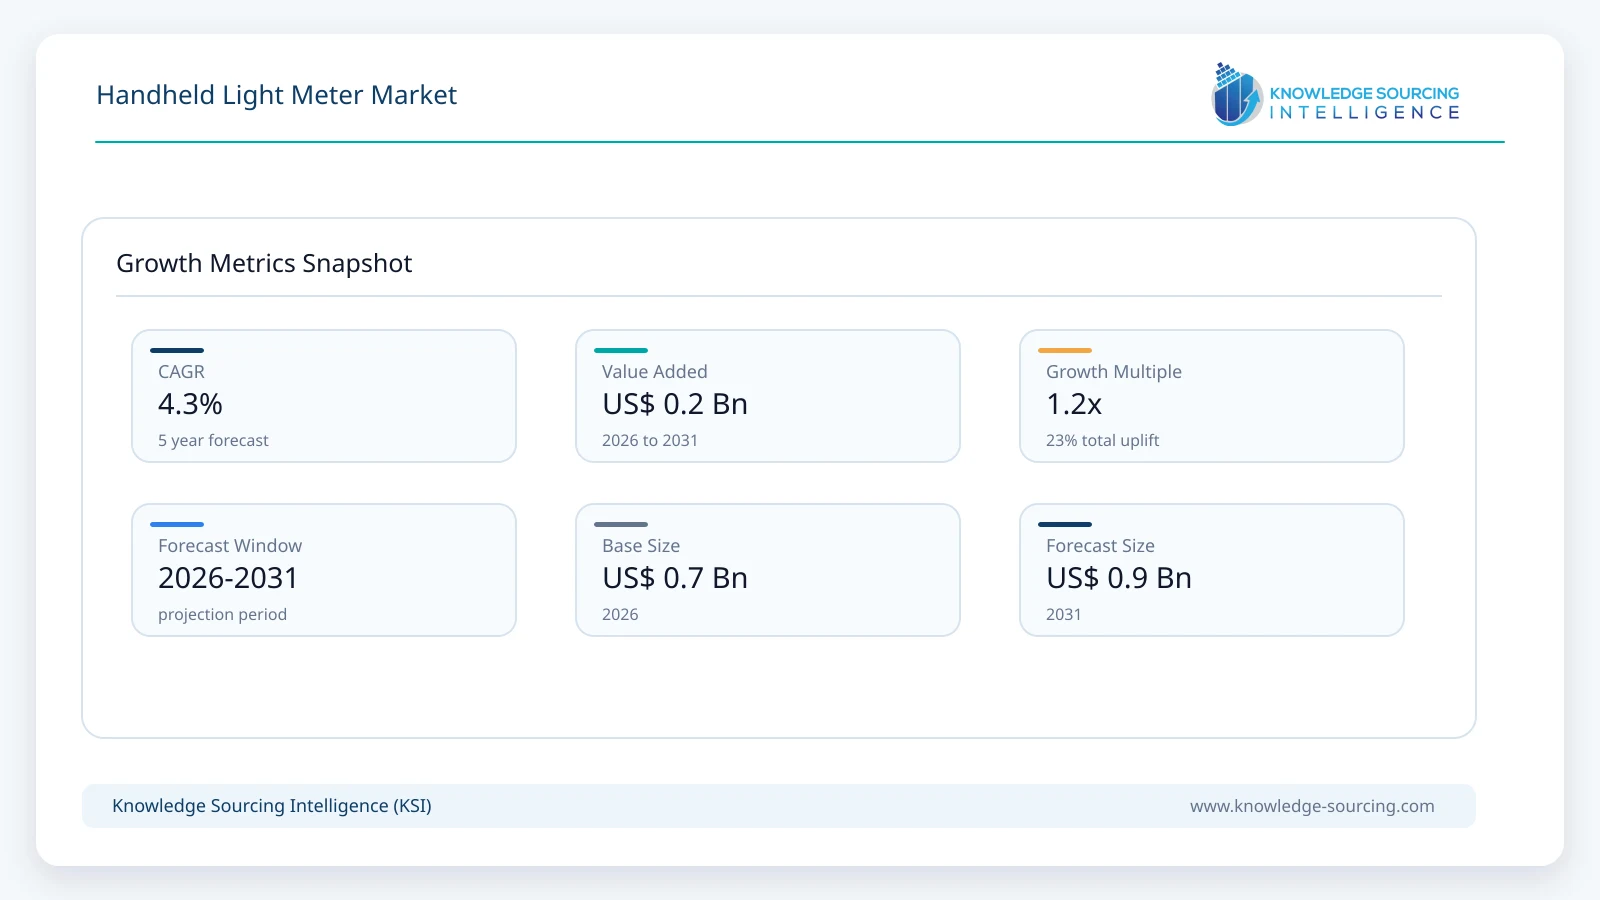
The global handheld light meter market is estimated at approximately USD 0.74 billion in 2026 and is forecast to reach about USD 0.91 billion in 2031, representing a CAGR of approximately 4.27% over the forecast period.
Highlights:
- 1Handheld illuminance and lux meters account for approximately 58.0% of global handheld light meter revenue in 2026.
- 2Standalone digital instruments represent approximately 55.0% of global 2026 market revenue, while app-connected digital meters are the fastest-growing architecture.
- 3Commercial, industrial and facilities lighting applications account for approximately 43.0% of global handheld light meter revenue in 2026.
- 4Asia Pacific accounts for approximately 38.5% of global handheld light meter revenue in 2026 and remains the largest regional market.
- 5Portable spectral and color meters are gaining value share as LED, display, horticultural and cinematography applications require more than basic lux measurement.
- 6Bluetooth connectivity, smartphone workflow integration, LED spectral correction and calibration traceability are becoming important differentiators in professional instruments.
Current product portfolios show a clear split between inexpensive digital illuminance meters and increasingly capable professional tools. HIOKI, Testo, Fluke, Teledyne Extech, PCE Instruments, TES and CENTER continue to sell conventional handheld meters for workplace, electrical, HVAC and environmental measurement. At the higher end, Sekonic, Konica Minolta, Gigahertz-Optik and GOSSEN offer portable instruments aimed at lighting design, photography, cinematography, LED characterization, display work and spectral assessment. The coexistence of these tiers supports a moderate overall growth profile rather than a single high-growth technology curve.
The forecast through 2031 assumes continued LED retrofit and commissioning activity, stricter documentation in workplaces and regulated environments, growth in display and optical-product testing, and broader use of connected measurement workflows. It also assumes that smartphones continue to substitute for casual low-accuracy measurement, limiting the low end of the market. Dedicated handheld instruments retain an advantage where calibrated accuracy, cosine response, spectral matching, traceability, repeatability and professional reporting are required.
Handheld Light Meter Market Trends
Spectral and Color Measurement Moves Into Portable Instruments
Portable light measurement is moving beyond a single lux reading. Sekonic announced its C-4000 Spectrometer in March 2025 for commercial release in April 2025, combining handheld operation with illuminance, correlated color temperature and color-quality measurements. Konica Minolta announced the CL-700A in December 2025, emphasizing faster and more accurate measurement at low illuminance and support for visible-to-near-infrared evaluation. Gigahertz-Optik also markets LIGHTmetric ONE as a compact spectral-lux platform. These products indicate a higher-value submarket in which a field instrument can support LED evaluation, photography, film, lighting design, horticulture and optical-product testing without requiring a laboratory bench system.
App Connectivity Becomes Part of the Measurement Workflow
Bluetooth and app integration are increasingly used to transfer readings, map measurement points and create reports. HIOKI FT3425 supports Bluetooth communication with mobile devices through the GENNECT Cross workflow, while Testo 545 integrates with the Testo Smart App. PCE and other professional suppliers also combine local displays with USB or wireless transfer. The value proposition is not simply remote reading: connected workflows reduce manual transcription, improve traceability and make multi-point surveys faster. This is particularly relevant in facilities management, occupational safety, lighting commissioning and audits where users may need to document tens or hundreds of locations.
LED Sources Raise the Importance of Spectral Matching and Flicker Handling
Modern LED sources can expose limitations in older meters calibrated primarily around incandescent spectra. Manufacturers increasingly highlight LED compatibility, spectral correction, photopic matching and response to modulated light. TES includes LED spectral correction in current digital meters, Testo specifies LED compatibility, and professional spectral meters measure the spectrum directly rather than relying only on a broadband photodiode. As LED installations become more diverse in spectrum, color temperature and pulse-width modulation behavior, measurement quality depends more strongly on sensor design and correction algorithms. This supports replacement of older instruments in professional use even where basic illuminance demand is mature.
Calibration and Traceability Remain Central to Professional Differentiation
Professional buyers differentiate instruments by calibration quality, repeatability, standards classification and the availability of accredited calibration services. Gigahertz-Optik operates ISO/IEC 17025 calibration capabilities for photometric measurement, while vendors such as HIOKI, GOSSEN and Testo position instruments against recognized photometric performance classes. This creates a defensible professional segment because smartphone sensors and low-cost consumer meters generally cannot provide equivalent calibration documentation. Periodic recalibration also creates recurring service revenue and strengthens supplier relationships in laboratories, manufacturing, occupational safety and regulated facilities.
Use Cases Broaden Beyond Traditional Photography
Photography remains an important application for exposure meters, but the broader handheld market is increasingly tied to workplace illumination, building commissioning, LED and luminaire testing, museums, retail environments, horticulture, display evaluation and production quality control. OSHA guidance recommends measuring workplace illumination with a light meter, and current industrial products from Fluke, Testo, HIOKI and Extech are designed for field technicians rather than photographers. The resulting market mix is more diversified than older descriptions centered on camera exposure, reducing dependence on any single creative-industry cycle.
Handheld Light Meter Market Segment Analysis
By Instrument Type
Illuminance and Lux Meters
Handheld illuminance and lux meters are estimated at approximately USD 0.43 billion in 2026, or about 58.0% of global market revenue. They remain the largest instrument category because lux measurement is used across occupational safety, electrical maintenance, HVAC, building commissioning, warehouses, laboratories, retail, schools, cleanrooms and general environmental inspection. Current products commonly span from fractions of a lux to 100,000-400,000 lux and increasingly add data hold, min/max capture, data logging, USB or Bluetooth. Their large installed base limits growth, but LED replacement activity and the need for documented surveys support steady replacement demand.
By Instrument Type
Portable Spectral and Color Meters
Portable spectral and color meters are estimated at approximately USD 0.13 billion in 2026 and are expected to be the fastest-growing instrument type, with an indicative CAGR of about 7.2% through 2031. At that pace, the segment approaches USD 0.19 billion by 2031. Growth is supported by LED spectral diversity, virtual production, cinematography, display testing, horticultural lighting and quality-control applications that require correlated color temperature, spectrum, CRI, TM-30 or other color-quality metrics. Unit volumes are lower than conventional lux meters, but selling prices are materially higher, allowing the segment to gain revenue share.
By Measurement Architecture
Standalone Digital Instruments
Standalone digital instruments account for approximately USD 0.41 billion in 2026, representing about 55.0% of the market. These meters dominate because they are inexpensive, rugged, simple to deploy and sufficient for routine lux checks. Facilities personnel, electrical contractors, HVAC technicians and occupational-safety teams can obtain a calibrated reading without configuring an app or network. The category includes products from Fluke, Extech, TES, CENTER, HIOKI and many regional suppliers. Its share should gradually decline as connected instruments become more common, but absolute revenue remains stable because the installed base is large and replacement cycles continue.
By Measurement Architecture
Connected Digital Instruments
App-connected and PC-connected digital instruments are estimated at approximately USD 0.27 billion in 2026 and are expected to expand at roughly 7.5% annually, reaching about USD 0.39 billion by 2031. Connectivity is most valuable when measurements must be mapped, stored, compared or exported into reports. Bluetooth-enabled field meters reduce transcription errors and can pair measurement data with photographs or locations, while USB interfaces remain important for laboratory and quality-control workflows. The category also benefits from firmware and software updates that extend instrument functionality after purchase, making connectivity a meaningful product differentiator rather than a cosmetic feature.
By End User
Commercial, Industrial and Facilities Lighting
Commercial, industrial and facilities lighting applications are estimated at approximately USD 0.32 billion in 2026, or about 43.0% of the total market. Users include factories, warehouses, offices, schools, hospitals, cleanrooms, electrical contractors, HVAC teams and EHS departments. These environments require repeatable field measurement to verify lighting levels, investigate complaints, commission LED retrofits and document compliance or maintenance. Basic lux meters dominate unit demand, while connected and data-logging meters gain share where audits involve many measurement points or recurring monitoring.
By End User
Laboratory, Product Testing and Optical Manufacturing
Laboratory, product-testing and optical-manufacturing applications are estimated at approximately USD 0.16 billion in 2026 and are expected to grow at about 6.4% annually, reaching roughly USD 0.21 billion in 2031. The segment grows faster than the overall market because LED products, displays, cameras, sensors and other optical systems require characterization beyond a basic lux value. Portable spectrometers and high-grade photometers can be used for incoming inspection, production troubleshooting and field validation. Traceable calibration and lower measurement uncertainty are important purchase criteria, supporting higher average selling prices.
By Geography
Asia Pacific
Asia Pacific is estimated at approximately USD 0.28 billion in 2026, representing about 38.5% of global market revenue. The region combines large electronics and lighting manufacturing bases in China, Japan, South Korea and Taiwan with growing LED deployment, industrial construction and facility auditing across India and Southeast Asia.
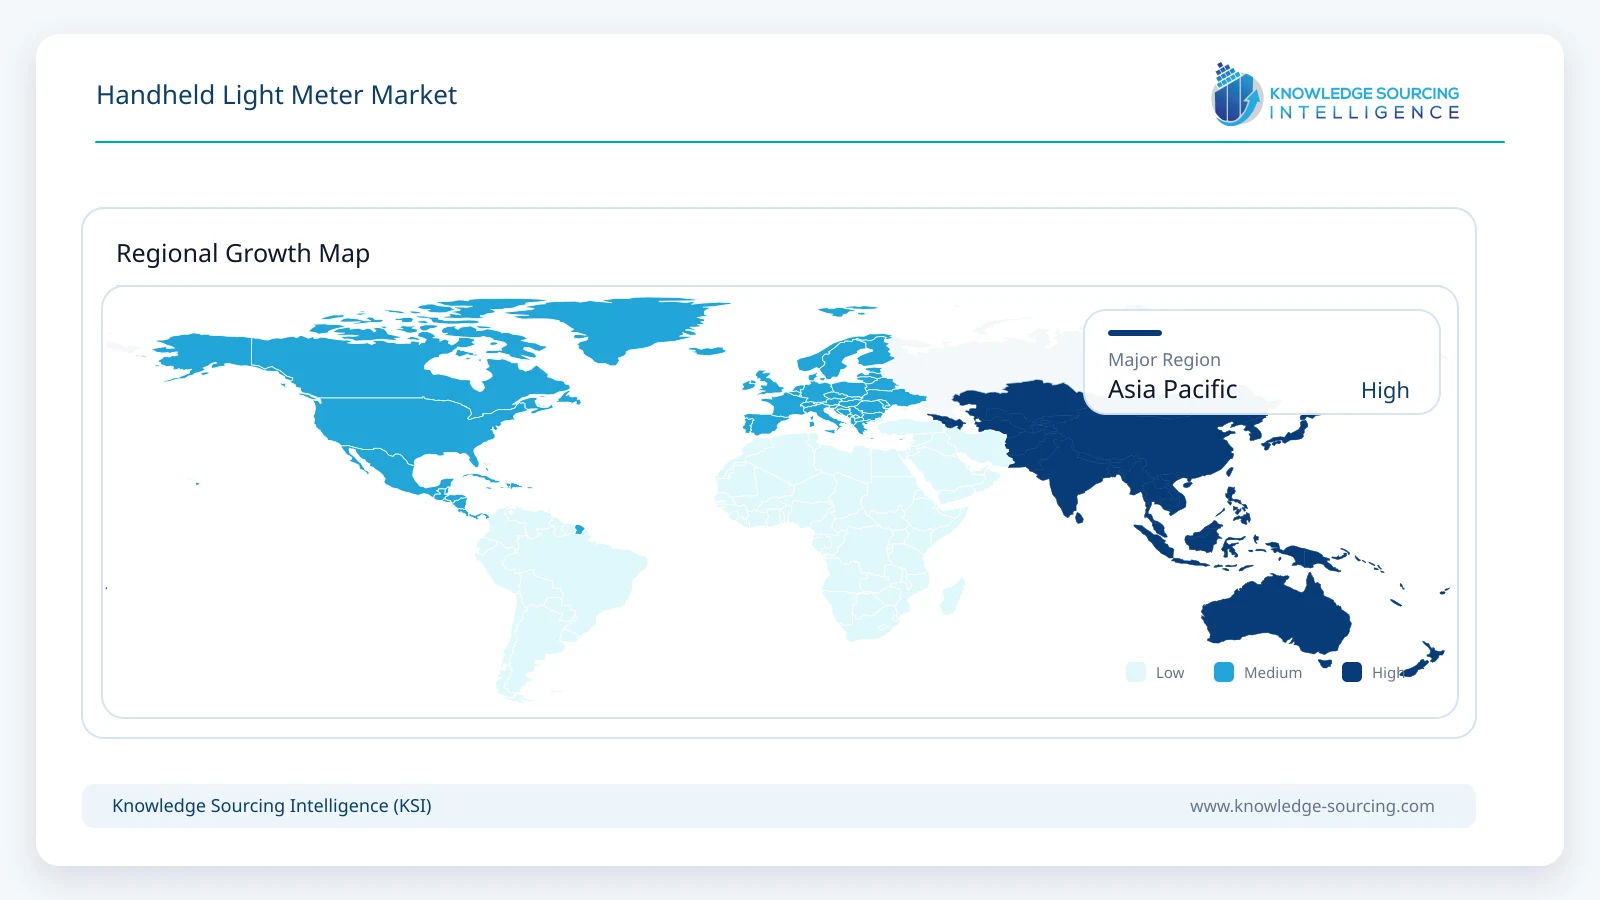
Japan is also home to major instrument suppliers including Konica Minolta, HIOKI and Sekonic. Asia Pacific is expected to remain the largest region through 2031, with growth supported by manufacturing quality control, commercial construction, electronics testing and wider adoption of professional spectral measurement.
Market Drivers
LED Retrofit and Lighting Commissioning
The continuing replacement of fluorescent, incandescent and HID lighting with LEDs creates recurring measurement needs. Installers and facilities teams use handheld meters to verify delivered illuminance, identify dark spots, confirm retrofit performance and compare before-and-after conditions. Because LED spectra differ by product and age, professional projects increasingly benefit from meters designed for LED spectral response rather than older incandescent-calibrated instruments.
Workplace and Building Illumination Verification
Factories, offices, warehouses, healthcare facilities and laboratories need adequate illumination for safety, productivity and task performance. Field light meters provide a rapid method to audit working planes and verify that lighting systems continue to perform as designed. The requirement is particularly durable because it is tied to installed buildings rather than new construction alone, creating replacement and recurring inspection demand.
Growth of Spectral and Color-Quality Measurement
LED lighting, displays, photography, cinematography, virtual production and horticulture increasingly require measurements such as correlated color temperature, color-rendering indexes and spectral power distribution. Portable spectral instruments allow these checks to move from the laboratory to the field. Their higher average selling prices increase market value even when unit volumes remain modest.
Digital Documentation and Connected Field Work
Facilities and quality teams increasingly expect measurement data to be stored, transferred and incorporated into digital reports. Bluetooth and USB connectivity make handheld meters easier to integrate into these workflows. The ability to capture multiple points, add context and export results is especially useful for commissioning, compliance audits and multi-site facilities management.
Optical and Electronics Manufacturing
Manufacturers of luminaires, displays, cameras, sensors and electronic equipment use portable light-measurement instruments for verification and troubleshooting. Asia Pacific production scale and global LED manufacturing support continued demand for calibrated field instruments alongside benchtop laboratory systems. Portable tools are particularly valuable where measurements must be taken directly on production equipment or installed assemblies.
Market Restraints
Smartphone Substitution at the Low End
Smartphone light-meter applications can satisfy casual users who need only approximate illuminance or exposure readings. This limits demand for the least expensive dedicated meters and makes it difficult for suppliers to defend price in consumer channels. Dedicated instruments remain stronger where calibration, repeatability and professional documentation matter, but the low end of the market faces continued substitution pressure.
Long Replacement Cycles for Basic Meters
Conventional digital lux meters contain few moving parts and can remain functional for many years. Users that do not require new connectivity or higher spectral accuracy may replace instruments only after damage, calibration failure or battery-related problems. This slows unit growth in mature facilities and photography applications.
Calibration and Recalibration Costs
Professional accuracy requires periodic calibration, which adds service cost and downtime. Smaller contractors or occasional users may postpone calibration or choose lower-cost instruments without traceable services. The requirement supports premium suppliers but can restrain adoption among price-sensitive customers.
Commodity Competition in Standard Lux Meters
Basic handheld lux meters are widely available from regional and online brands, creating strong price competition. Established suppliers must differentiate through accuracy, ruggedness, calibration, warranty, software and channel support rather than the core measurement function alone. This limits margin expansion in the largest instrument category.
Measurement Complexity Under Modern LED Sources
LED spectral distributions and flicker behavior can make simple broadband measurements less reliable if the sensor has poor spectral matching or insufficient response to modulated light. Users may need more expensive meters or better training to obtain defensible results. This complexity can slow replacement decisions even though it also supports premium product demand.
Competitive Environment
The market combines professional photometric specialists with broad electrical and environmental-test companies. Sekonic and GOSSEN are strongly associated with photographic and professional exposure/light measurement. Konica Minolta and Gigahertz-Optik compete in high-accuracy photometric and spectral measurement. HIOKI, Testo, Fluke, Teledyne Extech and PCE Instruments address technicians, laboratories and industrial users with broader test portfolios. TES, CENTER, Hagner and Senseca/Delta OHM provide additional regional and specialist depth.
Competition varies sharply by price tier. Basic digital lux meters compete on range, accuracy, display quality, ruggedness and channel availability. Professional connected meters compete on standards class, calibration, data logging and app workflow. Portable spectral instruments compete on spectral resolution, low-light performance, color metrics, measurement speed and software. Because the same customer may own multiple instruments for different tasks, the market is not winner-take-all; suppliers defend niches through measurement quality and application support.
Software is becoming more important to product positioning. Connected meters that can export, visualize and document data are easier to integrate into facility and quality workflows. At the premium end, suppliers can create switching costs through calibration services, instrument-specific software and established acceptance within professional communities. This favors companies that combine hardware with calibration, training and application expertise rather than competing solely on sensor cost.
Recent Developments
December 2025: Konica Minolta announced the CL-700A Illuminance Spectrophotometer, emphasizing faster high-accuracy measurement at low illuminance and support for visible-to-near-infrared evaluation across lighting, automotive, smartphone and electrical-product applications.
April 2025: Sekonic began commercial release of the C-4000 Spectrometer following its March 2025 announcement. The handheld instrument combines lux, color-temperature and color-quality measurements with smartphone-oriented workflow flexibility.
May 2025: Gigahertz-Optik introduced LIGHTmetric ONE as a compact spectral lux meter designed for mobile spectral light measurement across lighting, film, horticulture and related professional applications.
2026: PCE Instruments continued to expand professional portable optical measurement with the PCE-PSR 200, a handheld spectrophotometric platform supporting illuminance, spectrum, and color metrics with USB and BLE connectivity.
Market Outlook
The handheld light meter market is expected to remain a moderate-growth professional-instrument market through 2031. Conventional lux meters will continue to account for the largest revenue share because they serve a broad installed base, but their growth is restrained by long replacement cycles and low-cost competition. The strongest value growth is expected in portable spectral/color instruments and connected digital meters that address modern LED sources and digital documentation requirements.
Asia Pacific should remain the largest regional market because of electronics and lighting manufacturing scale, while North America and Europe remain important for professional facility, occupational-safety, film, calibration and laboratory applications. Suppliers that can combine calibrated measurement, LED compatibility, simple connectivity and credible after-sales calibration are positioned to capture premium demand even as smartphones erode casual low-end use.
Handheld Light Meter Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.74 billion |
| Total Market Size in 2031 | USD 0.91 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.27% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Instrument Type, Measurement Architecture, End User, Geography |
| Companies |
|
Market Segmentation
By Instrument Type
Illuminance and Lux Meters
Portable Spectral and Color Meters
Photographic and Cinematographic Exposure Meters
Portable UV, PAR and Specialized Optical-Radiation Meters
By Measurement Architecture
Standalone Digital Instruments
Connected Digital Instruments
Analog Instruments
By End User
Commercial, Industrial and Facilities Lighting
Laboratory, Product Testing and Optical Manufacturing
Photography and Cinematography
Museums, Retail and Hospitality
Horticulture and Controlled Environment Agriculture
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. LED Retrofit and Lighting Commissioning
4.1.2. Workplace and Building Illumination Verification
4.1.3. Growth of Spectral and Color-Quality Measurement
4.1.4. Digital Documentation and Connected Field Work
4.1.5. Optical and Electronics Manufacturing
4.2. Market Restraints
4.2.1. Smartphone Substitution at the Low End
4.2.2. Long Replacement Cycles for Basic Meters
4.2.3. Calibration and Recalibration Costs
4.2.4. Commodity Competition in Standard Lux Meters
4.2.5. Measurement Complexity Under Modern LED Sources
5. HANDHELD LIGHT METER MARKET BY INSTRUMENT TYPE
5.1. Illuminance and Lux Meters
5.2. Portable Spectral and Color Meters
5.3. Photographic and Cinematographic Exposure Meters
5.4. Portable UV, PAR and Specialized Optical-Radiation Meters
6. HANDHELD LIGHT METER MARKET BY MEASUREMENT ARCHITECTURE
6.1. Standalone Digital Instruments
6.2. Connected Digital Instruments
6.3. Analog Instruments
7. HANDHELD LIGHT METER MARKET BY END USER
7.1. Commercial, Industrial and Facilities Lighting
7.2. Laboratory, Product Testing and Optical Manufacturing
7.3. Photography and Cinematography
7.4. Museums, Retail and Hospitality
7.5. Horticulture and Controlled Environment Agriculture
7.6. Others
8. HANDHELD LIGHT METER MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. India
8.5.4. South Korea
8.5.5. Southeast Asia
8.5.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Basic Lux Meter and Premium Spectral Positioning
9.3. Connectivity and Software Differentiation
9.4. Calibration and Standards Positioning
9.5. Recent Developments
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Sekonic Corporation
10.2. Konica Minolta, Inc.
10.3. HIOKI E.E. Corporation
10.4. Testo SE & Co. KGaA
10.5. Fluke Corporation
10.6. PCE Instruments
10.7. Teledyne FLIR LLC (Extech Instruments)
10.8. International Light Technologies, Inc.
10.9. GOSSEN Foto- und Lichtmesstechnik GmbH
10.10. Gigahertz-Optik GmbH
10.11. CENTER Technology Corp.
10.12. B. Hagner AB
10.13. Chauvin Arnoux Group
10.14. Senseca (Delta OHM)
10.15. TES Electrical Electronic Corp.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Abbreviations
Navigate
Trusted by the world's leading organizations











