
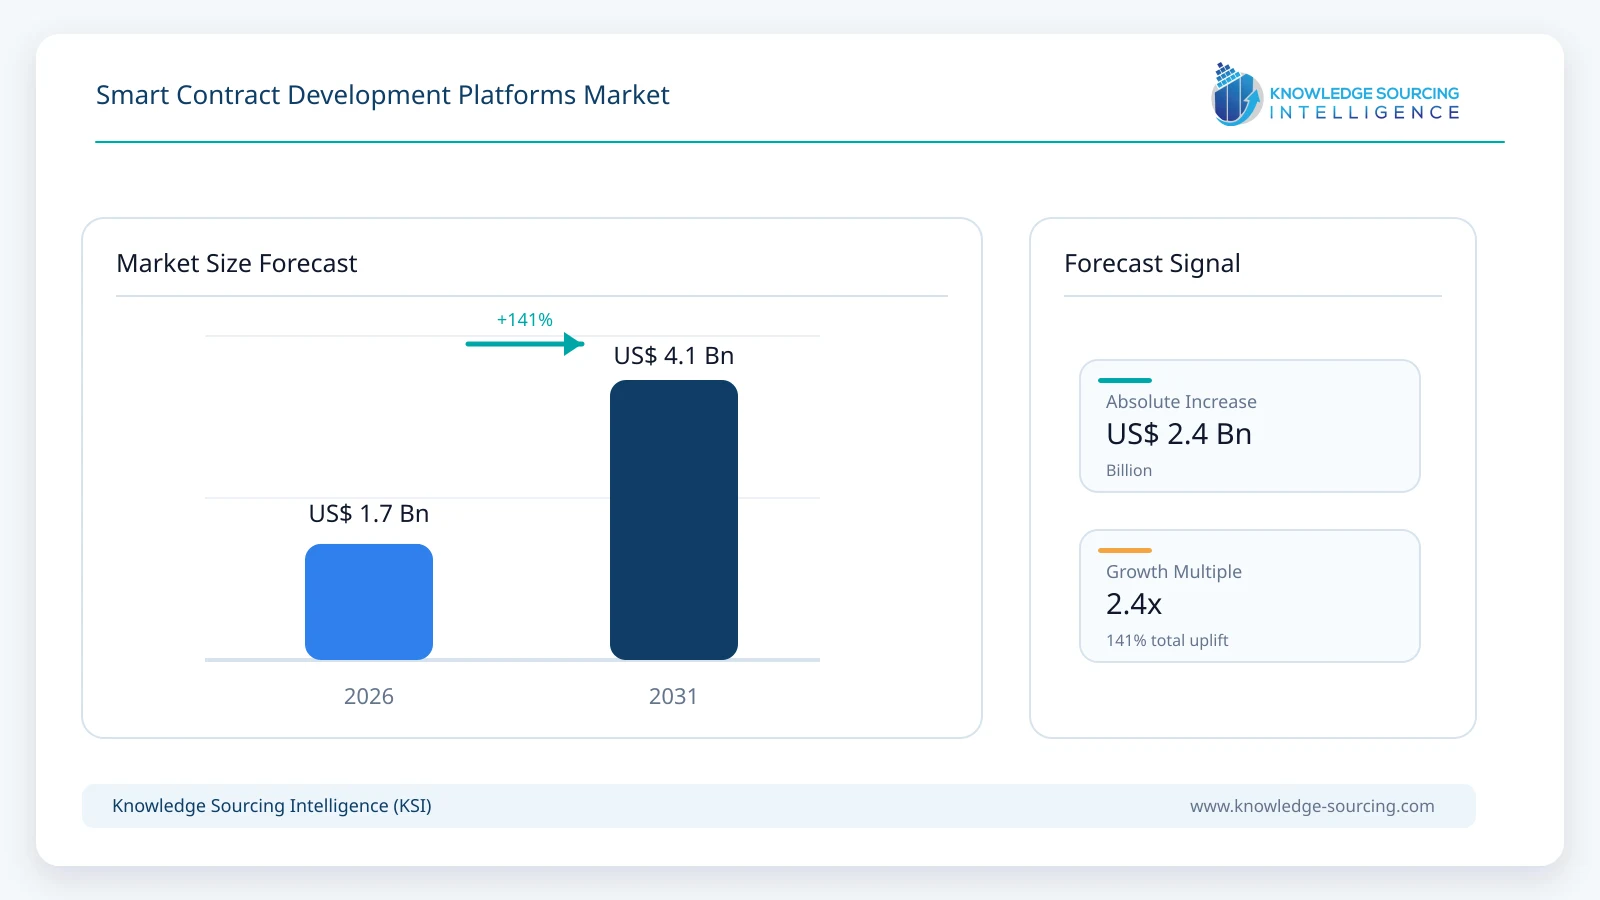
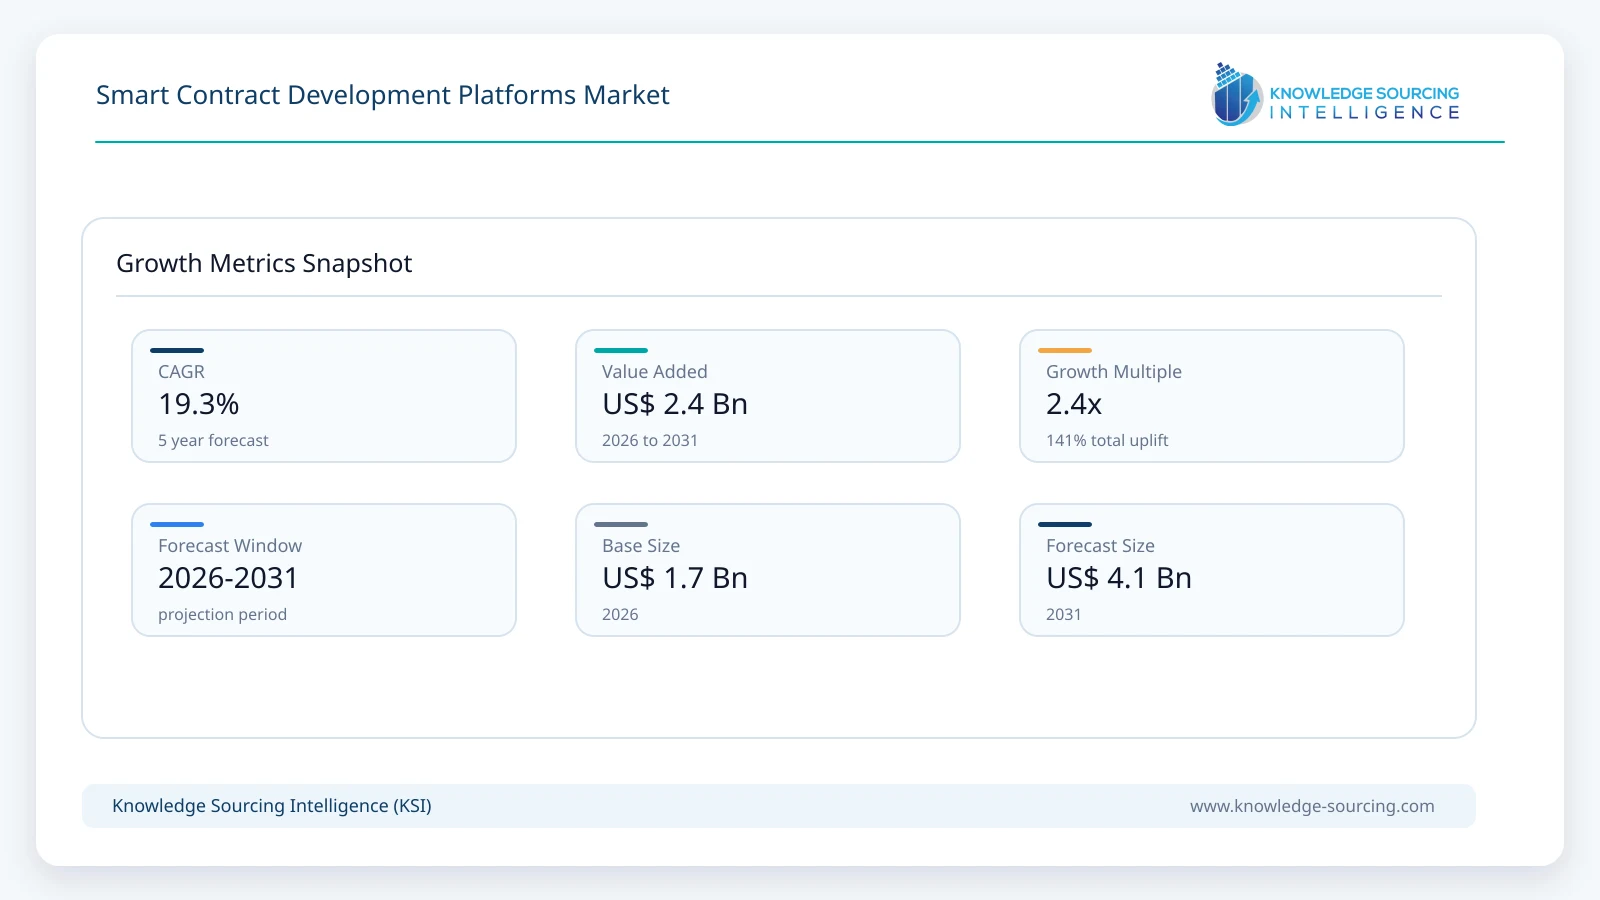
The global smart contract development platforms market is forecast to grow from USD 1.70 billion in 2026 to USD 4.10 billion in 2031, representing a CAGR of 19.3% throughout the forecast period.
Highlights:
- 1Managed developer infrastructure and API platforms are estimated to account for approximately 46.0% of global market revenue in 2026 as developers increasingly outsource node operations, RPC capacity, indexing, streams and production monitoring.
- 2Public EVM-compatible environments are estimated to represent approximately 63.0% of 2026 market revenue because Ethereum and its L2 ecosystem continue to concentrate smart-contract tooling, frameworks, testing, deployment and security activity.
- 3BFSI is estimated to account for approximately 34.0% of global smart contract development-platform spending in 2026, supported by tokenization, stablecoins, payments, custody, capital-markets infrastructure and programmable settlement.
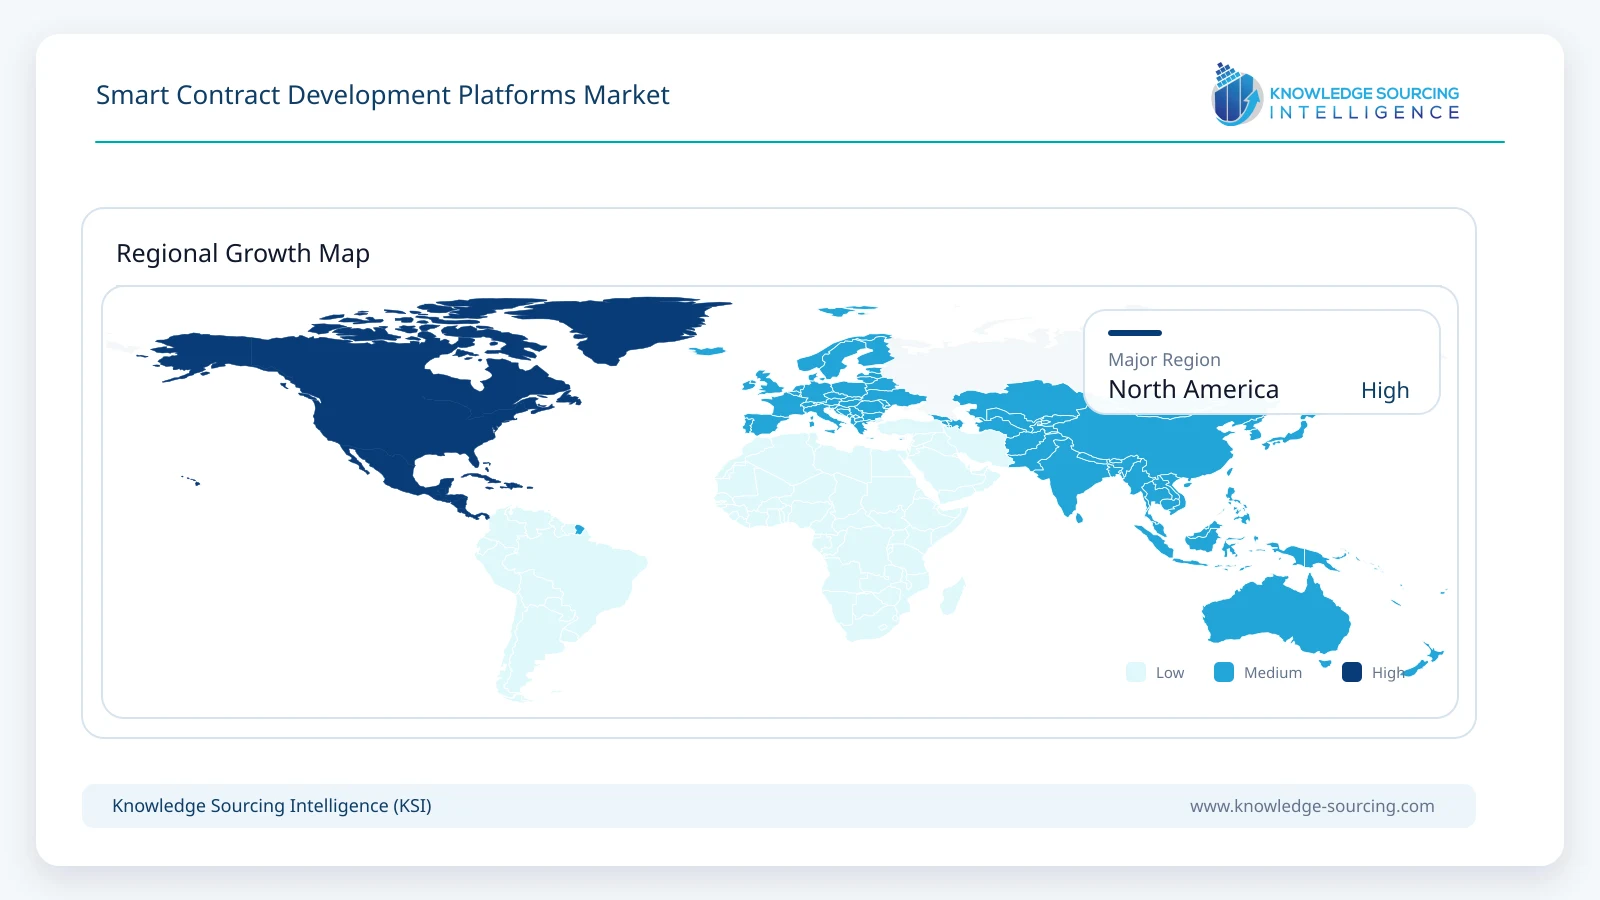
- 4North America is estimated to account for approximately 39.0% of global market revenue in 2026, supported by a dense concentration of commercial blockchain-infrastructure vendors, fintech adopters and institutional onchain initiatives.
- 5AI-assisted development is moving from code generation into contract testing, infrastructure administration, security review and agent-driven blockchain interaction, increasing the value of integrated developer platforms.
- 6The competitive market is shifting away from standalone node access toward full-stack platforms that combine RPC, real-time data, debugging, simulation, deployment, security, account abstraction and production operations.
Commercial activity is increasingly concentrated in full-stack developer platforms. Alchemy supports more than 100 blockchains and states that more than 150,000 teams use its platform, while QuickNode supports around 80 chains and handles hundreds of billions of successful requests per month. thirdweb reports more than two million contracts deployed through its tooling, and Tenderly supports more than 100 EVM-compatible networks across simulation, debugging, virtual testnets, monitoring and production infrastructure.
The market is expanding beyond crypto-native applications. Financial institutions, payment companies, tokenization platforms, gaming companies and consumer applications increasingly require production-grade smart-contract infrastructure with predictable uptime, security controls, observability and developer support. Institutional adoption of tokenized funds, stablecoin payments and programmable assets is particularly important because these workloads require reliable development and production environments rather than experimental tooling alone.
Developer workflows are also becoming more integrated. Teams increasingly select a stack that combines network access, indexing, real-time data, contract testing, deployment, wallet/account tooling and monitoring. This favors vendors able to support many chains through one account and one API model while providing higher-value services above the basic RPC layer.
Market Trends
Full-Stack Developer Platforms Replace Point Tools
Blockchain development platforms are broadening beyond node access. Alchemy, QuickNode, Tenderly and other vendors increasingly combine infrastructure with data APIs, streams, webhooks, simulation, monitoring, transaction tooling and developer automation. This reduces the number of providers a team needs to integrate and creates stronger recurring-revenue relationships.
The shift is particularly important for production applications because smart-contract failures can directly affect financial assets. Development teams therefore value deterministic test environments, debugging, transaction simulation, alerts, historical data and enterprise support alongside basic connectivity.
AI-Native Blockchain Development Becomes a Commercial Feature
AI is moving into blockchain development workflows through coding assistants, natural-language infrastructure management, automated diagnostics and agent-accessible APIs. QuickNode introduced agent-facing capabilities that allow AI assistants to create endpoints and administer blockchain infrastructure, while Alchemy has expanded its intelligent infrastructure and agent tooling.
This changes competition from raw infrastructure performance toward developer productivity. Platforms that expose well-structured APIs, SDKs and agent-compatible interfaces can become the operating layer used by both human developers and automated software agents.
Tokenization and Stablecoin Infrastructure Expand Enterprise Demand
Tokenized funds, stablecoins, deposit tokens and programmable payments are increasing the number of institutional systems that rely on smart contracts. These applications have different requirements from speculative consumer applications, including access controls, observability, compliance integration, transaction simulation and service-level agreements.
As regulated financial institutions move more workloads onchain, development-platform spending is expected to shift toward enterprise-grade infrastructure, private clusters, auditability and managed support rather than free-tier developer access alone.
Multi-Chain Development Becomes the Default
Developers increasingly build across multiple L1 and L2 networks rather than committing to one blockchain. Alchemy supports more than 100 chains, QuickNode around 80, and Tenderly more than 100 EVM-compatible networks. This makes cross-chain support, unified APIs and consistent tooling important purchasing criteria.
Multi-chain demand also raises the value of abstraction. Developers want deployment, monitoring and data services that behave consistently across networks, reducing the need to maintain separate node infrastructure and operational processes for each chain.
Smart Contract Development Platforms Market Segment Analysis
By Platform Type
Managed Developer Infrastructure and APIs
Managed developer infrastructure and API platforms are estimated at approximately USD 0.78 billion in 2026. The segment includes RPC access, managed nodes, indexed data, streams, webhooks, transaction infrastructure and related production services sold to developers and enterprises.
The segment leads market value because production blockchain applications generate recurring infrastructure usage and require high uptime, low latency, global routing and support across multiple networks. Vendors are increasingly layering higher-value data, security and operational products on top of RPC connectivity.
By Blockchain Environment
Public EVM-Compatible Networks
Public EVM-compatible environments are estimated at approximately USD 1.07 billion in 2026. Ethereum, Base, Arbitrum, Optimism, Polygon and a growing number of EVM-compatible chains share Solidity-based development patterns and benefit from a broad ecosystem of testing, deployment, debugging and infrastructure tools.
EVM compatibility lowers switching costs for developers and allows commercial platforms to support many networks through common APIs and workflows. Non-EVM ecosystems remain strategically important, particularly Solana and emerging high-performance networks, but the EVM ecosystem retains the largest commercial tooling base.
By End User
BFSI
BFSI is estimated at approximately USD 0.58 billion in 2026. Banks, asset managers, payment companies, fintechs and market-infrastructure providers increasingly use smart contracts for tokenization, stablecoins, programmable payments, settlement, collateral management and digital-asset services.
The sector has higher requirements for reliability, security, auditability and enterprise support than many experimental Web3 applications. This supports premium infrastructure tiers, dedicated clusters, transaction simulation, monitoring and managed engineering support.
By Geography
North America
North America is estimated at approximately USD 0.66 billion in 2026. The region hosts a large share of leading blockchain developer-platform companies and remains a major center for institutional digital-asset activity, fintech development, venture-backed Web3 infrastructure and enterprise blockchain adoption.
The United States also has a deep base of software developers and financial institutions experimenting with tokenized assets and programmable payments, supporting continued demand for production-grade developer platforms.
Market Drivers
Institutional Tokenization and Programmable Finance
Tokenized securities, funds, stablecoins and programmable payments create durable demand for smart-contract development, testing and production infrastructure. Financial applications require more robust tooling than experimental deployments because software defects can directly affect asset ownership and settlement.
Growth of Layer-2 and Multi-Chain Ecosystems
The expansion of L2 networks and application-specific chains increases the number of environments developers must support. Managed platforms reduce the engineering burden by providing standardized access, indexing and observability across many chains.
Rising Security and Reliability Requirements
Smart-contract exploits and transaction failures increase the value of simulation, debugging, monitoring and pre-deployment testing. Commercial platforms are expanding security-oriented tooling so developers can identify errors before transactions reach production.
Developer Productivity and AI Automation
AI-assisted coding, natural-language infrastructure management and automated operations allow smaller teams to build and maintain more complex onchain applications. Platforms that integrate these capabilities can increase developer productivity and expand the addressable market beyond specialist blockchain engineers.
Market Restraints
Cyclical Web3 Development Activity
Blockchain developer spending remains sensitive to funding cycles, token-market activity and startup formation. Periods of weaker venture investment can reduce experimental projects and pressure usage among smaller customers.
Open-Source and Free-Tier Competition
Foundry, Hardhat, open-source RPC clients and free public endpoints reduce the need to pay for some basic development functions. Commercial vendors must therefore differentiate through scale, uptime, data services, collaboration, security and enterprise support.
Platform Consolidation and Pricing Pressure
As large developer platforms expand across RPC, indexing, data, deployment and monitoring, smaller point-tool vendors face pressure to specialize or integrate. High-volume customers can also negotiate aggressively on infrastructure pricing.
Regulatory Uncertainty Across Digital Assets
Rules governing stablecoins, tokenized assets, DeFi and crypto services vary by jurisdiction. Uncertain regulatory treatment can delay enterprise smart-contract deployments and shift spending between regions or use cases.
Regional Outlook
North America
North America is the largest commercial market, supported by major infrastructure vendors, a deep software-development base and strong institutional interest in tokenized assets and programmable payments. Enterprise adoption increasingly favors managed infrastructure with security controls, dedicated capacity and formal support.
Europe
Europe has an active developer ecosystem and growing institutional blockchain adoption, particularly around tokenization, payments and regulated digital-asset infrastructure. Compliance requirements create demand for auditable infrastructure and controlled deployment environments.
Asia Pacific
Asia Pacific is a major growth region because of strong developer communities, gaming ecosystems, fintech adoption and government-backed blockchain initiatives in selected countries. Singapore, Japan, South Korea, Hong Kong and India provide important developer and enterprise demand centers.
South America and Middle East & Africa
Demand is smaller but expanding through fintech, stablecoin usage, remittances, gaming and digital-asset initiatives. The Middle East is also attracting blockchain infrastructure investment through financial free zones and government digital-asset programs.
Competitive Environment
The competitive environment spans full-stack infrastructure providers, smart-contract development platforms, security and simulation specialists, contract-library vendors and enterprise blockchain service providers. Alchemy and QuickNode compete through broad multi-chain infrastructure and data products; Consensys participates through Infura and adjacent Ethereum developer tooling; Tenderly is differentiated by simulation, debugging and production operations; thirdweb focuses on end-to-end contract deployment and application development.
OpenZeppelin remains important through audited contract libraries and developer/security products, while Chainstack, Blockdaemon, Tatum, Moralis, Gelato, Ankr, GetBlock and other providers compete across managed infrastructure, APIs, deployment and automation. Competitive advantage increasingly depends on the ability to combine reliable infrastructure with developer productivity, security, multi-chain coverage and enterprise support.
The market is likely to consolidate around platforms that can serve the full application lifecycle. Basic RPC access is increasingly commoditized, while real-time data, transaction simulation, agent tooling, account abstraction, security monitoring and dedicated infrastructure provide stronger differentiation.
Recent Developments
June 2026: Alchemy published an updated developer-stack framework emphasizing integrated infrastructure, smart-contract frameworks, wallet tooling and an emerging agentic layer for onchain applications.
April 2026: QuickNode reported new agent-native blockchain infrastructure capabilities, including tools that allow AI agents to query networks, deploy contracts and manage infrastructure across more than 80 blockchains.
2026: QuickNode expanded its unified developer platform with CLI, SDK, MCP and API-based administration alongside RPC, streams, webhooks and indexed data services.
2026: Alchemy expanded support to more than 100 blockchains and continued developing Cortex and enterprise infrastructure for high-volume financial and consumer applications.
2025-2026: Tenderly expanded support to more than 100 EVM-compatible networks and continued integrating simulation, virtual testnets, monitoring and production infrastructure for new L1 and L2 networks.
2026: thirdweb continued operating its end-to-end smart-contract platform, reporting more than two million contracts deployed across its supported EVM ecosystem.
Market Outlook
The smart contract development platforms market is expected to remain a high-growth software and infrastructure category through 2031 as onchain applications move from experimental deployments toward production financial, payment, gaming and consumer systems. Growth will increasingly come from recurring infrastructure usage, data services, security, monitoring and enterprise support rather than from standalone development tools.
Managed developer infrastructure is expected to remain the largest commercial value pool, while AI-native tooling and agent interfaces are likely to become standard platform features. Public EVM-compatible networks will continue to support the largest installed tooling ecosystem, although Solana and other non-EVM environments will capture a growing share of incremental developer activity.
Competitive advantage will depend on multi-chain coverage, uptime, data quality, debugging and simulation capabilities, security, developer experience and the ability to support regulated enterprise workloads. The market is forecast to add approximately USD 2.40 billion in annual revenue between 2026 and 2031.
Smart Contract Development Platforms Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.70 billion |
| Total Market Size in 2031 | USD 4.10 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Platform Type, Blockchain Environment, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Platform Type
Managed Developer Infrastructure and APIs
Smart Contract Development, Testing and Deployment Tooling
Monitoring, Simulation and Security Platforms
Low-Code, No-Code and Managed Development Services
Others
By Blockchain Environment
Public EVM-Compatible Networks
Other Public Blockchains
Private and Permissioned Blockchain Environments
By End User
BFSI
Supply Chain and Logistics
Gaming and Media
Retail and Consumer Applications
Healthcare and Life Sciences
Government and Public Sector
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Switzerland
Others
Middle East and Africa
UAE
Saudi Arabia
Others
Asia Pacific
Singapore
Japan
South Korea
India
Hong Kong
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Growth Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Institutional Tokenization and Programmable Finance
4.1.2. Growth of Layer-2 and Multi-Chain Ecosystems
4.1.3. Rising Security and Reliability Requirements
4.1.4. AI-Assisted Developer Productivity
4.2. Market Restraints
4.2.1. Cyclical Web3 Development Activity
4.2.2. Open-Source and Free-Tier Competition
4.2.3. Platform Consolidation and Pricing Pressure
4.2.4. Regulatory Uncertainty
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Developer Workflow and Toolchain Analysis
4.6. Enterprise Adoption Trends
5. SMART CONTRACT DEVELOPMENT PLATFORMS MARKET BY PLATFORM TYPE
5.1. Introduction
5.2. Managed Developer Infrastructure and APIs
5.3. Smart Contract Development, Testing and Deployment Tooling
5.4. Monitoring, Simulation and Security Platforms
5.5. Low-Code, No-Code and Managed Development Services
5.6. Others
6. SMART CONTRACT DEVELOPMENT PLATFORMS MARKET BY BLOCKCHAIN ENVIRONMENT
6.1. Introduction
6.2. Public EVM-Compatible Networks
6.3. Other Public Blockchains
6.4. Private and Permissioned Blockchain Environments
7. SMART CONTRACT DEVELOPMENT PLATFORMS MARKET BY END USER
7.1. Introduction
7.2. BFSI
7.3. Supply Chain and Logistics
7.4. Gaming and Media
7.5. Retail and Consumer Applications
7.6. Healthcare and Life Sciences
7.7. Government and Public Sector
7.8. Others
8. SMART CONTRACT DEVELOPMENT PLATFORMS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Switzerland
8.4.5. Others
8.5. Middle East and Africa
8.5.1. UAE
8.5.2. Saudi Arabia
8.5.3. Others
8.6. Asia Pacific
8.6.1. Singapore
8.6.2. Japan
8.6.3. South Korea
8.6.4. India
8.6.5. Hong Kong
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Developer Infrastructure Positioning
9.3. Testing, Simulation and Security Competition
9.4. Market Share Analysis
9.5. Partnerships, Acquisitions and Ecosystem Expansion
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Alchemy
10.2. QuickNode
10.3. Consensys / Infura
10.4. thirdweb
10.5. Tenderly
10.6. Chainstack
10.7. Blockdaemon
10.8. Tatum
10.9. Moralis
10.10. OpenZeppelin
10.11. Gelato Network
10.12. Ankr
10.13. GetBlock
10.14. Sequence / Horizon Blockchain Games
10.15. Kaleido
11. APPENDIX





Frequently asked questions
What is the forecast market size for smart contract development platforms by 2031?
The Smart Contract Development Platforms Market is projected to reach USD 4.10 billion by 2031.
What is the projected CAGR for the Smart Contract Development Platforms Market?
The Smart Contract Development Platforms Market is forecast to grow at a 19.3% CAGR (2026-2031).
Which technology segment dominates smart contract development platforms revenue?
Public EVM-compatible environments represent 63.0% of 2026 market revenue.
Which industry accounts for the largest share of platform spending?
BFSI is estimated to account for 34.0% of spending in 2026.
Which region is estimated to dominate the smart contract platforms market?
North America is estimated to account for 39.0% of global revenue.
What is a key strategic shift in the competitive market?
The Smart Contract Development Platforms Market shifts towards full-stack integrated developer platforms.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Smart Contract Development Platforms Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/smart-contract-development-platforms-market