
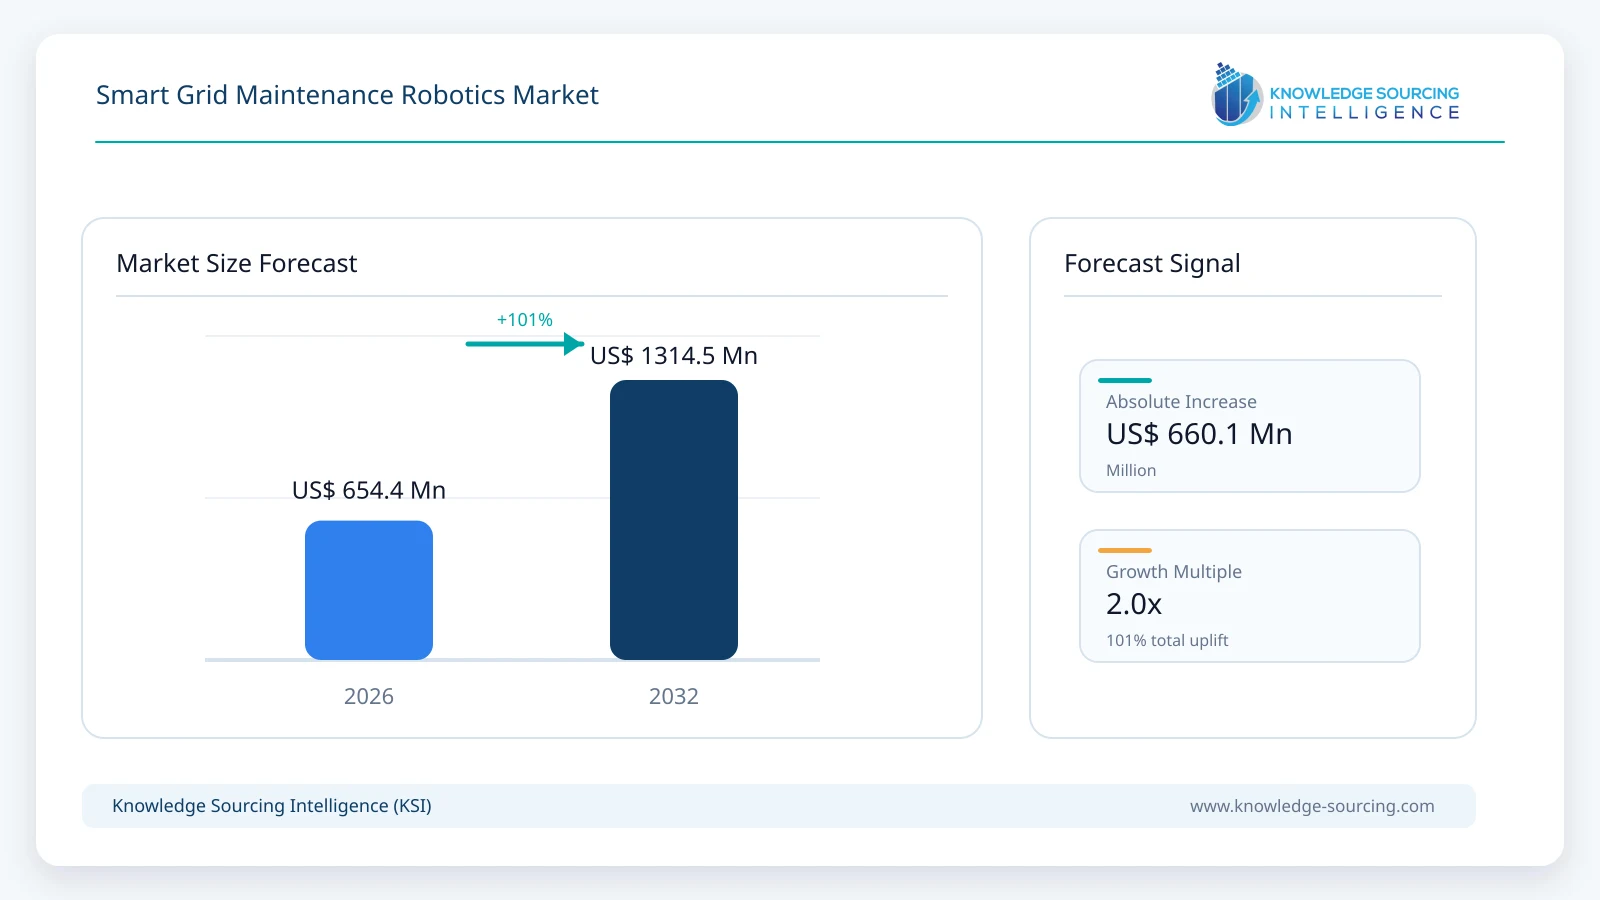
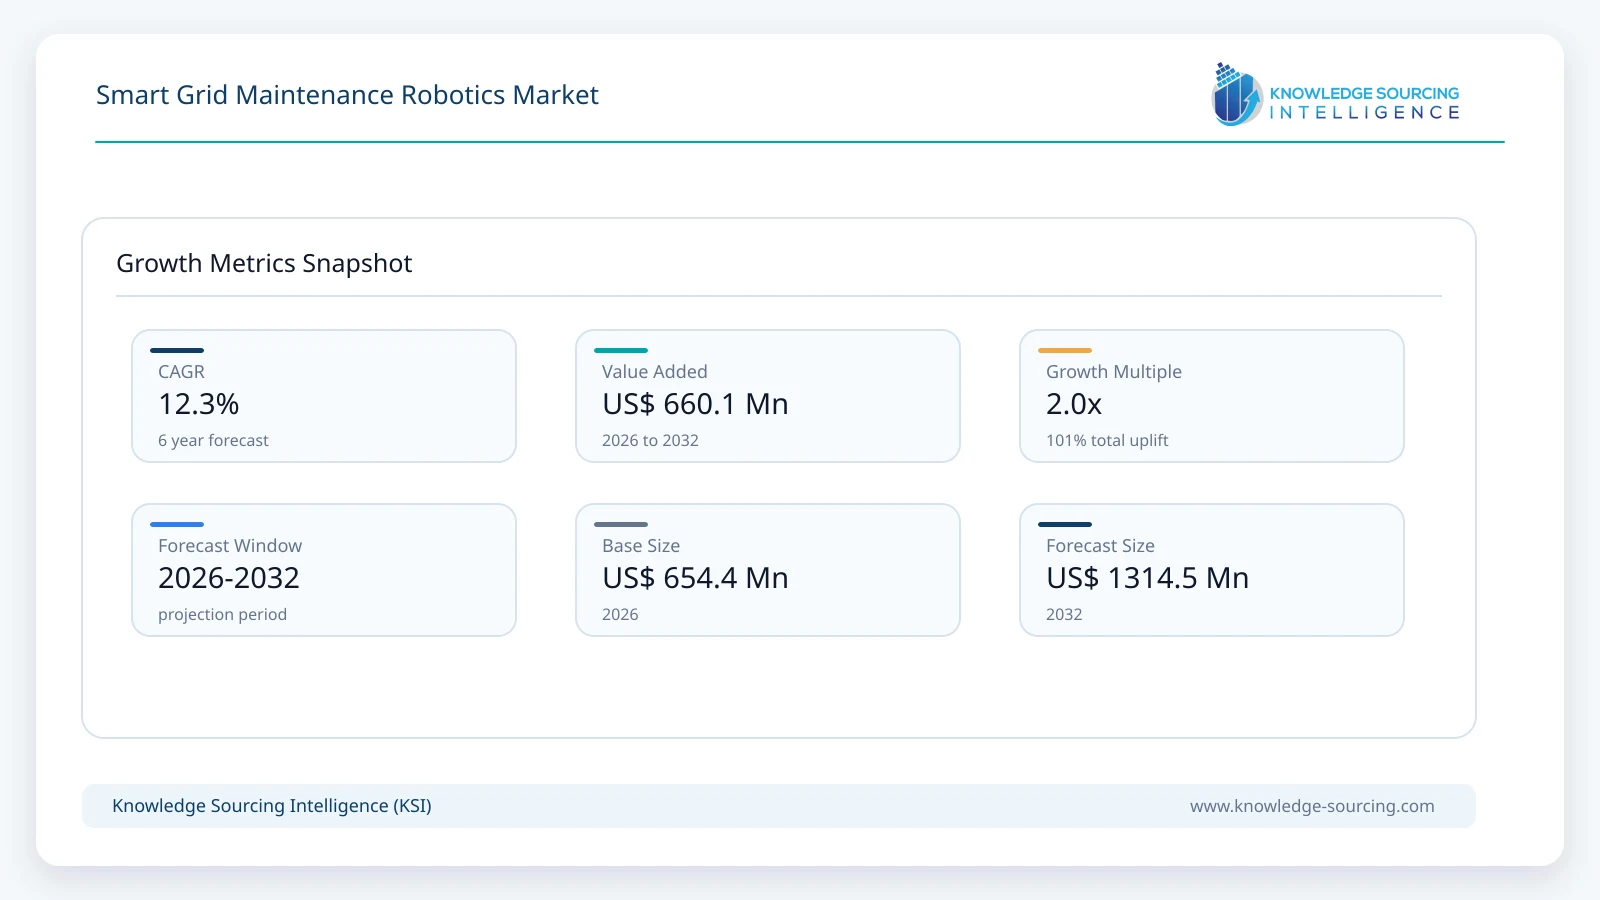
The smart grid maintenance robotics market is estimated at USD 654.4 million in 2026 and projected to reach USD 1,314.5 million by 2032, growing at a CAGR of 12.3% during the forecast period.
Highlights:
- 1Transmission-line inspection and maintenance is estimated at US$325.00 million in 2026, representing 49.7% of global revenue.
- 2This application is projected to reach US$612.58 million by 2032, growing at an 11.14% CAGR.
- 3Utility buyers increasingly value repeatable inspection evidence and faster fault identification over stand-alone robotic hardware capability.
- 4Autonomous inspection drones and specialized conductor-handling robots address different requirements, from identifying defects to installing line hardware.
- 5Aviation approvals, energized-line safety, cybersecurity and validation of robotic inspection findings remain significant barriers to wider deployment.
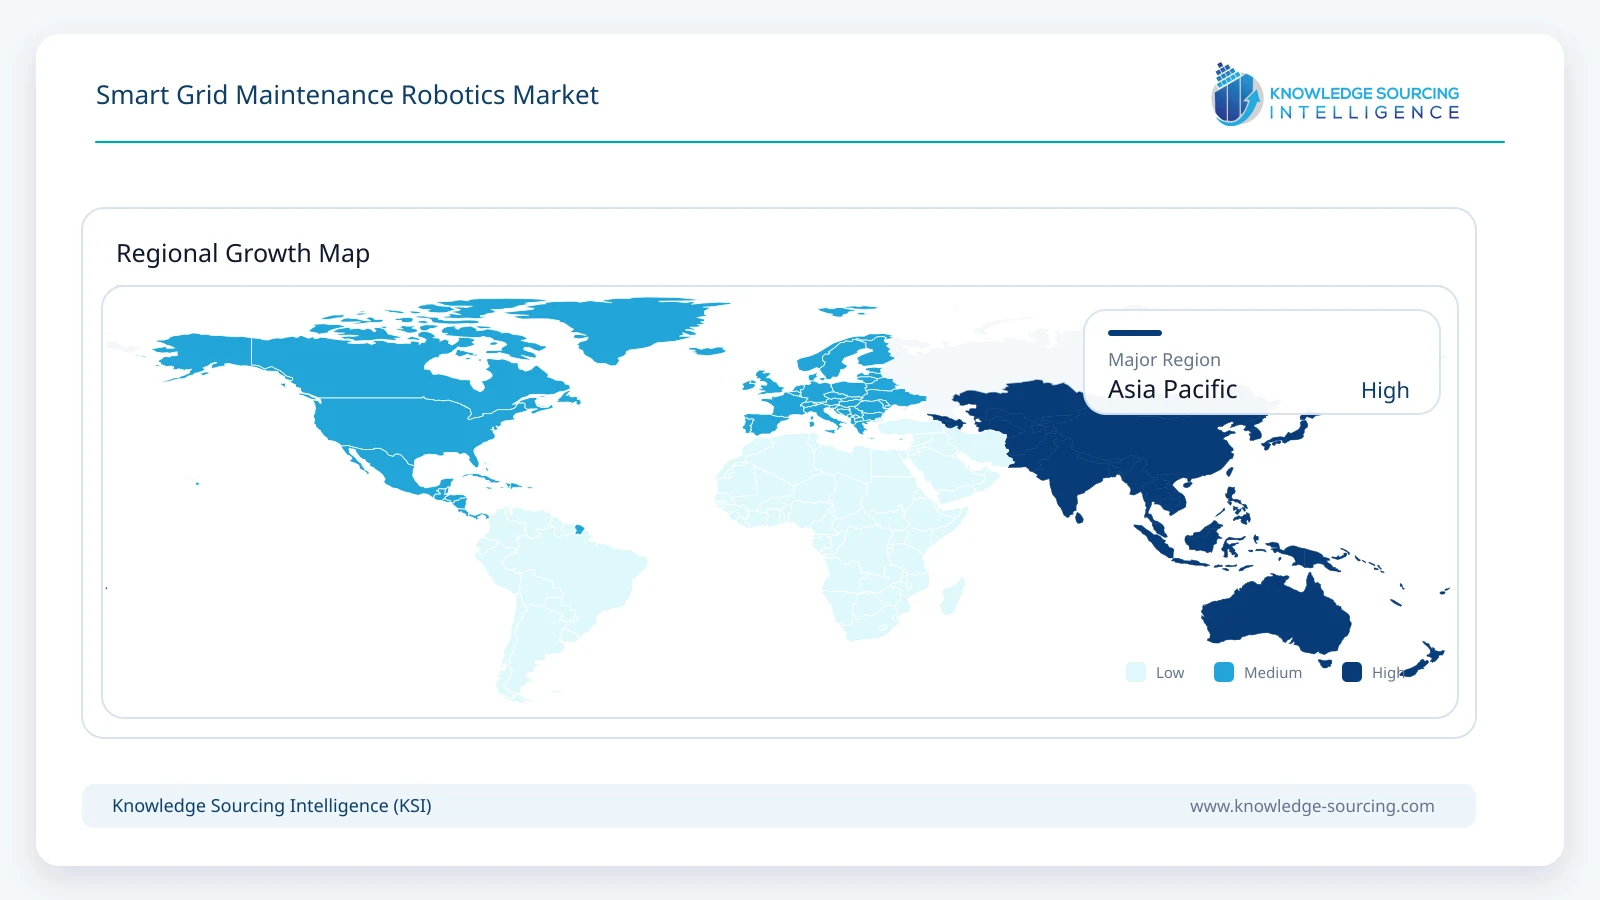
- 6North American utilities prioritize grid resilience and inspection productivity, while Asia Pacific demand reflects expanding and increasingly complex power networks.
The opportunity covers robotic equipment, inspection software and specialist operations directly attributable to transmission lines, distribution assets, substations, transformers and grid-interconnection infrastructure. It does not include broad smart-grid management platforms, conventional helicopter patrols, manual line maintenance, or robots used solely to service wind turbines and solar panels. This distinction is commercially important because a drone manufacturer's entire enterprise revenue cannot be booked as grid-maintenance spending. Demand is becoming less dependent on one-off technology demonstrations as utilities deploy repeatable visual, thermal and LiDAR inspection workflows. National Grid's 2025 deployment of centrally supervised autonomous drone inspections demonstrates the shift toward routine operations, while EPRI's substation field evaluations show that ground robotics still needs proof of navigation, sensor usefulness and reliable reporting. Suppliers therefore compete on actionable defect identification, operational permissions, system integration and lifetime deployment economics, not on robot hardware performance alone.
The underlying grid investment cycle creates substantial demand for better inspection productivity, but not every dollar of grid expenditure becomes robotics revenue. The International Energy Agency reports that more than 2,500 GW of renewable, storage and large-load projects remain stalled in connection queues globally, while electricity networks need greater visibility and faster asset interventions. A robotic inspection contract becomes commercially attractive when it increases patrol frequency, resolves inaccessible inspection points or cuts the number of dispatched crews without compromising safety. Transmission operators can schedule repeated tower, conductor and insulator surveys; distribution companies can examine poles and switching equipment after storms; and substation owners can monitor thermal anomalies around assets that are otherwise difficult to access safely. Hardware budgets remain significant, yet inspection as a managed service is gaining importance because operators need certified pilots, regulatory authorizations, analytics and secure data custody. Those operating requirements help explain why autonomous inspection providers and specialist line-work robotics companies occupy different competitive positions despite serving the same infrastructure owners.
Market Dynamics
Market Drivers
Grid complexity is raising the economic value of repeatable condition data. Expanding transmission corridors, distributed generation and higher load variability increase the consequences of missed equipment defects, while ageing components require more frequent decisions about repair or replacement. The IEA's September 2026 grid analysis highlights how better sensing, maintenance and operation can raise utilization of existing infrastructure, rather than treating expansion as the only response to congestion. For robotics suppliers, the commercial opportunity lies in shortening the interval between field observation and approved maintenance action. A thermal image alone has limited value; georeferenced anomaly records, consistent asset identification, work-order integration and audit trails enable utilities to prioritize scarce crews. National Grid's deployment with sees.ai illustrates this shift by combining remotely supervised drone operations with close-quarter inspection data across live power infrastructure. As inspection missions become standardized, revenue can expand through recurring contracts, fleet orchestration and analytics. However, utilities will judge these systems against established patrol procedures and safety outcomes, which restrains adoption where robotic outputs are not yet trusted.
Market Restraints and Commercial Barriers
Physical access and regulatory permission remain the largest barriers to scaling robotic maintenance. Aerial operations near energized conductors require reliable separation, repeatable flight paths and permission for remote or beyond-visual-line-of-sight missions, while weather and electromagnetic interference can disrupt performance. Inside substations, mobile platforms must traverse uneven gravel, work around live equipment and identify thermal or acoustic anomalies consistently. EPRI's evaluation of multiple robot platforms demonstrates that selecting a mobile robot is only the first step; useful deployment also requires validated payloads, communications, cybersecurity and integration with maintenance systems. Procurement complexity creates another bottleneck because the organization paying for the drone may differ from the utility team responsible for approving inspection results or dispatching work. A pilot may therefore succeed technically but fail commercially if its data are not accepted into the formal maintenance workflow. Vendors that can demonstrate insurance compliance, incident procedures, repeatable accuracy and low supervisory costs have a clearer route from trial to multi-site contracts than companies selling isolated hardware.
Market Opportunities
The most promising growth opportunities combine inspection automation with high-consequence maintenance work. Inspection drones can cover long corridors efficiently, but companies that physically manipulate conductors or place line hardware address an additional source of utility cost: the time and exposure involved in sending crews to height. PLP and FulcrumAir's LineFly and LineSpider systems show how specialized robotics can install bird diverters or spacers with fewer personnel and vehicles, while Hydro-Québec's conductor-traversing platforms demonstrate the technical feasibility of inspecting energized lines. These are distinct commercial models. Aerial inspection providers are often paid through platform, fleet or service contracts; line-work robot providers may generate equipment revenue or project-specific installation income. Utilities can also use compact autonomous ground systems for recurring substation rounds, particularly where staffing constraints make frequent inspection expensive. Suppliers should prioritize clearly defined asset classes, documented time savings and repeatable operations across multiple sites rather than marketing undifferentiated artificial intelligence capabilities. Partnerships with grid hardware manufacturers and inspection contractors can accelerate procurement because those organizations already understand utility specifications and safety practices.
Major Segment Analysis
Transmission Line Inspection and Maintenance
Transmission line inspection and maintenance represents an estimated US$325.00 million in 2026, or 49.7% of global smart grid maintenance robotics revenue. KSI projects this application at US$612.58 million in 2032, equivalent to an 11.14% CAGR. The segment includes robot-enabled overhead-line visual and thermal surveys, conductor-crawling inspection and robotic placement or servicing of line components, with revenue allocated to the associated equipment and attributable services. Transmission operators obtain the strongest benefit where inspection points are geographically dispersed, line access is difficult and crew deployment involves substantial travel or working-at-height risk. National Grid's move to centralised autonomous drone inspection illustrates the inspection side, while PLP and FulcrumAir's automated diverter installation demonstrates physical intervention. Their economics differ: repeat survey missions require high-volume data acquisition and consistent defect triage, while line-work robotics must prove safe mechanical placement under field conditions. Growing corridor lengths therefore support both recurring survey revenue and a smaller but technically differentiated line-maintenance equipment opportunity.
A larger addressable network does not automatically translate into equal growth for every transmission-robotics supplier. Utilities increasingly require photographs, LiDAR measurements and thermal signatures to map directly onto asset identifiers and historical inspection records; otherwise the inspection output can create additional engineering review work. Repeated autonomous flights offer savings when a single trained team can supervise multiple inspection sites, but supervision costs and aviation authorization must be included in contract economics. Physical maintenance robots face a different utilization challenge: highly specialized tools may only suit selected conductor configurations or particular hardware, making deployment frequency and crew mobilization crucial determinants of realized revenue. PLP's documented project experience illustrates how repeatable hardware placement on large line projects can scale beyond prototype use. Competitive advantages therefore arise from operational proof, platform uptime, utility-specific qualification and a field-service network. Over the forecast period, vendors able to combine defect detection with work planning and verified maintenance outcomes should capture higher-value contracts than providers whose offering stops at image collection.
Other Segment Developments
Outside transmission-line applications, substation inspection is expected to expand more rapidly as utilities evaluate robotic rounds for thermal, visual and acoustic monitoring. Its growth is supported by demand for repeated observations around transformers, breakers, connectors and ancillary equipment without routine human presence. Transformer-specific robotic inspection remains narrower: internal inspection of oil-filled units may reduce confined-space hazards and avoid some preparatory work, but each project depends on asset design, technical qualification and outage planning. Grid-interconnection inspection for solar and wind projects involves substations and connection corridors, not routine servicing of turbines or solar modules themselves. By robot type, aerial platforms serve dispersed overhead assets, ground robots cover substations, and conductor-crawling or specialized intervention systems perform physical tasks along energized lines. The component dimension must allocate each contracted deployment across hardware, associated software and services exactly once. Software sold independently without a robotic deployment should not be included. These boundaries allow the distinct application, robot-type and component perspectives to describe the same market without adding their totals together.
Regional Analysis
North America
North America remains an important commercialization market because utilities face extensive transmission and distribution networks, wildfire exposure in selected states and increasing pressure to inspect assets without unnecessary field risk. In the United States, aerial inspections are becoming part of recurring reliability and storm-response programs, while companies such as Skydio and Percepto offer remote operations and analytics intended for electric utilities. EPRI's test programs provide a useful qualification framework for substation platforms by evaluating navigation, payload integration and the quality of repeated observations under field conditions. Canada contributes a complementary line-robotics technology base through Hydro-Québec's LineRanger and earlier inspection systems, although a technology's existence does not establish commercial market share. Mexico offers growing opportunities around network reinforcement and remote asset access, where procurement economics may favor service providers over expensive permanently installed robot fleets. Across the region, customers assess cybersecurity, flight authorization, inspection traceability and crew savings alongside equipment prices. This favors providers with local field support and utility-specific validation rather than general-purpose robotics vendors.
South America
South American demand is concentrated around the practical difficulty of inspecting long lines across complex terrain and maintaining reliable connections to geographically dispersed generation sites. Brazil has a large and varied grid footprint that creates opportunities for aerial surveys, vegetation assessment and thermal detection of conductor or insulator problems, particularly where crew movement is costly. Argentina presents similar needs in selected transmission corridors and remote utility assets, although investment cycles and currency constraints affect procurement timing. Utilities can adopt an inspection service without developing an entire autonomous robotics organization, which may make contractor-led deployments more accessible than full fleet ownership. The commercial case is strongest when suppliers can turn inspections into prioritized asset interventions and provide evidence that the approach reduces helicopter sorties or repeated field visits. Adoption should not be equated with broad smart-grid modernization spending; remote sensing from fixed monitors, conventional drones used for mapping and manual maintenance remain outside this market unless tied to a qualifying robotic inspection or intervention workflow. Consequently, utilization and contract conversion matter more than announced infrastructure budgets.
Europe
Europe combines mature transmission networks, strict operational requirements and rising pressure to connect new renewable capacity. The United Kingdom provides a particularly strong reference case: National Grid moved sees.ai's autonomous aerial inspections from testing into routine network operations in September 2025, demonstrating a repeatable utility use case rather than an isolated demonstration. Germany and France present sizable opportunities around ageing substations, dense transmission interfaces and utility digitalization, although each buyer requires national operating permissions and secure integration with existing asset systems. Italy is relevant through its large utility and equipment ecosystem and the need for regular condition assessments across diverse terrain. European suppliers must address aviation permissions, critical-infrastructure cybersecurity, maintenance-data ownership and rigorous evidence of inspection performance. Inspection robots may lower worker exposure without replacing engineering judgement, because identifying a defect is only one step in authorizing a repair. Commercial momentum therefore depends on converting autonomous imagery into asset-specific recommendations, traceable records and properly prioritized maintenance work. Repeatable inspection services should outperform one-off hardware deployments where utilization can be spread across multiple assets.
Middle East and Africa
The Middle East and Africa market is uneven, reflecting different grid expansion priorities and operational resources. Gulf utilities face high ambient temperatures, dust and geographically dispersed high-voltage assets, conditions that increase the relevance of thermal inspections while placing demands on vehicle endurance and optical reliability. Saudi Arabia and the United Arab Emirates are likely to be important early buyers where utility digitalization and infrastructure investment support inspection automation; permanent robotic substation rounds must nevertheless prove reliability under local operating conditions. In parts of Africa, long travel distances and hard-to-access lines favor contract-based aerial inspection, but financing and specialized maintenance support may limit large autonomous fleets. Vendors should distinguish operational grid-inspection contracts from the much larger construction and renewable generation budgets reported across the region. Procurement decisions are likely to favor ruggedized equipment, strong safety documentation and local service partners. Predictive analytics can add value when field data are consistently captured and verified, but promises of autonomous fault repair should not be generalized from inspection-only deployments.
Asia Pacific
Asia Pacific represents a substantial opportunity because grid expansion, dense urban distribution infrastructure and complex mountainous corridors coexist across the region. China has long developed specialized transmission and substation inspection robotics, and its procurement landscape supports a range of ground platforms and line-inspection systems. India has explicitly identified transmission-line, substation and transformer inspection robotics in its National Electricity Plan, but such policy recognition must be distinguished from actual procurement or deployed revenue. Japan and South Korea have advanced inspection technology capabilities and demanding reliability standards, favoring tightly integrated robotic systems over generic aerial survey tools. Taiwan's network resilience priorities add incentives for repeatable condition monitoring around critical electricity assets. The region's scale should not obscure highly different purchasing behaviors: some utilities buy equipment, some commission managed inspection programs, and others develop systems internally. Revenue attribution should follow the commercial supplier contract rather than simply assigning value to every robotic inspection conducted by a utility. Vendors with validated local reference deployments and qualified service partners are best placed to capture recurring business.
Competitive Environment
The competitive landscape spans three business models. First, aerial robotics providers such as DJI Enterprise, Skydio, Percepto and sees.ai deliver inspection platforms, autonomous operations or grid-specific workflows. Second, specialized line-intervention firms such as PLP and FulcrumAir engineer robotic installation methods that can reduce the physical exposure and mobilization time associated with working on conductors. Third, robotics and software specialists such as Boston Dynamics, Hitachi Energy, Buzz Solutions and Hepta Insights supply ground platforms, transformer-focused inspection or anomaly analytics. These groups should not be ranked using undifferentiated robotics revenue because their addressable grid-maintenance services differ. EPRI's substation evaluations confirm that general-purpose robot hardware can be relevant when qualified for electrical assets, but the qualification stage does not establish broad commercial adoption. Suppliers with utility case studies, a repeatable inspection workflow and defensible evidence of crew savings are better positioned than businesses whose energy involvement is limited to unrelated automation products. Accordingly, competitive assessment must examine verified applications, customer evidence, recurring-service capability and product ownership before discussing market share.
Recent Developments
September 2026: The IEA published Modernising Grids in the Age of Electricity, emphasizing the role of digital observation, maintenance and operational technologies in maximizing existing grid capacity.
August 2026: sees.ai published a detailed case study documenting its National Grid autonomous inspection rollout, building on the network-wide operational launch in September 2025.
February 2026: PLP and FulcrumAir announced a multi-year partnership to develop robotic systems for overhead-line hardware installation, extending their LineFly and LineSpider collaboration.
Smart Grid Maintenance Robotics Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 654.4 million |
| Total Market Size in 2032 | USD 1,314.5 million |
| Forecast Unit | Million |
| Growth Rate | 12.3% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Robot Type, Component, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Robot Type
Aerial Robots
Ground-based Robots
Conductor-Crawling and Specialized Line-Work Robots
By Component
Hardware
Software
Services
By Application
Transmission Line Inspection and Maintenance
Substation Inspection
Transformer Monitoring
Solar/Wind Farm Grid Connectivity
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Aerial Inspection, Thermal Imaging and LiDAR
4.2. Ground-Based Autonomous Substation Robotics
4.3. Conductor-Crawling and Robotic Line-Work Systems
4.4. Inspection Data Analytics, Cybersecurity and Integration
5. SMART GRID MAINTENANCE ROBOTICS MARKET BY ROBOT TYPE
5.1. Introduction
5.2. Aerial Robots
5.3. Ground-based Robots
5.4. Conductor-Crawling and Specialized Line-Work Robots
6. SMART GRID MAINTENANCE ROBOTICS MARKET BY COMPONENT
6.1. Introduction
6.2. Hardware
6.3. Software
6.4. Services
7. SMART GRID MAINTENANCE ROBOTICS MARKET BY APPLICATION
7.1. Introduction
7.2. Transmission Line Inspection and Maintenance
7.3. Substation Inspection
7.4. Transformer Monitoring
7.5. Solar/Wind Farm Grid Connectivity
8. SMART GRID MAINTENANCE ROBOTICS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. Japan
8.6.2. China
8.6.3. India
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. DJI Enterprise
10.2. Skydio
10.3. Percepto
10.4. sees.ai
10.5. Preformed Line Products (PLP)
10.6. FulcrumAir
10.7. Boston Dynamics
10.8. Hitachi Energy
10.9. Hydro-Québec / IREQ
10.10. Buzz Solutions
10.11. Hepta Insights
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market size for smart grid maintenance robotics by 2032?
The Smart Grid Maintenance Robotics Market is projected to reach USD 1,314.5 million by 2032.
What is the estimated CAGR for the Smart Grid Maintenance Robotics Market?
The Smart Grid Maintenance Robotics Market is projected to grow at a 12.3% CAGR (2026-2032).
Which application segment holds the largest share in this market?
Transmission-line inspection holds 49.7% of 2026 global revenue.
What are the primary drivers for smart grid robotics market growth?
Grid resilience, faster fault identification, and inspection productivity drive demand.
Which regions show significant demand for smart grid maintenance robotics?
North America and Asia Pacific are significant demand regions.
What are the key barriers to wider smart grid robotics deployment?
Aviation approvals, safety, cybersecurity, and validation remain significant barriers.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Smart Grid Maintenance Robotics Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/smart-grid-maintenance-robotics-market