
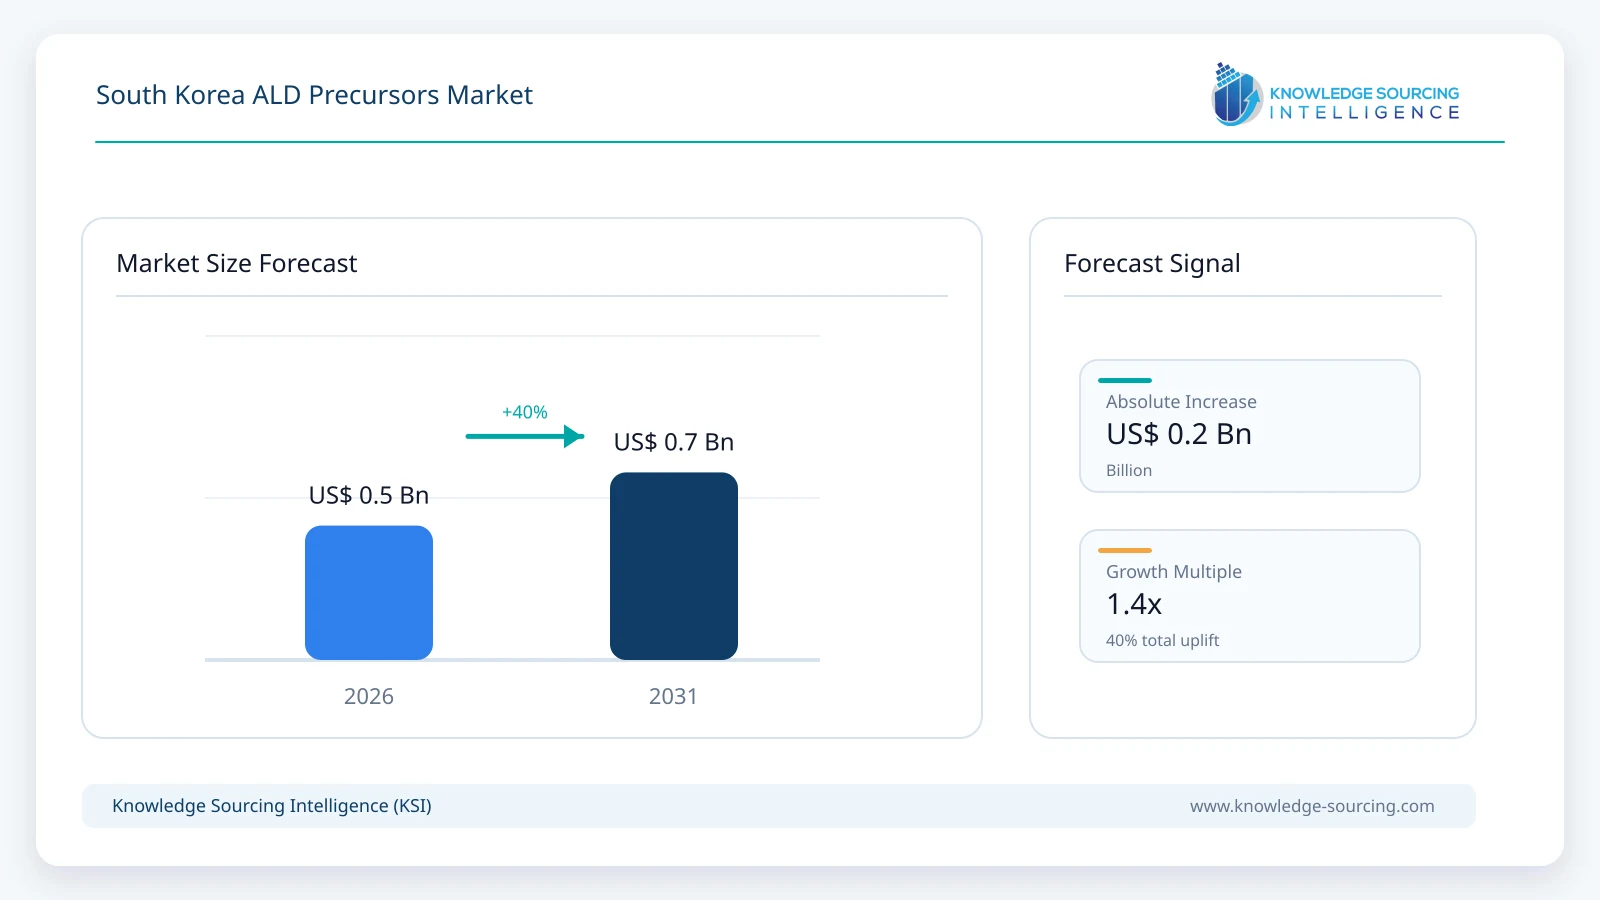
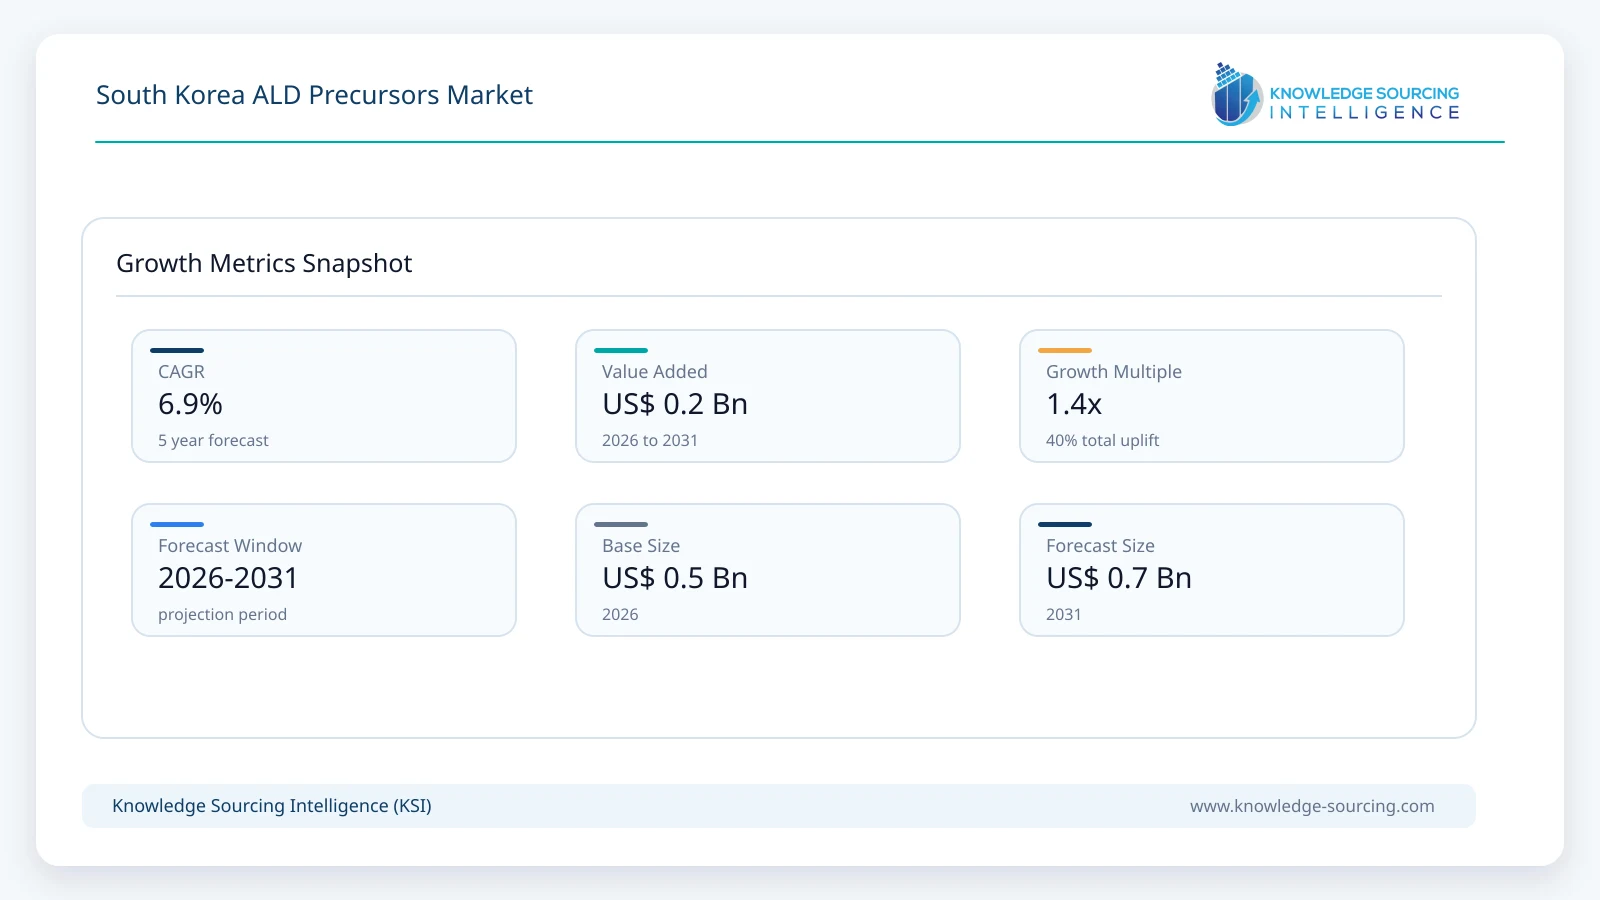
South Korea ALD Precursors Market is forecast to grow at a CAGR of 6.9%, reaching USD 0.67 billion in 2031 from USD 0.48 billion in 2026.
Highlights:
- 1South Korea's semiconductor manufacturing base remains the primary source of ALD precursor demand.
- 2Memory technology migration is increasing consumption of high-purity metal-organic precursor chemistries.
- 3Domestic material localization continues to reshape supplier qualification and procurement strategies.
- 4AI-driven memory and advanced packaging investments are expanding precursor requirements beyond front-end fabrication.
- 5Product purity, process repeatability, contamination control, and supply security remain the principal purchasing criteria.
- 6Local suppliers continue expanding precursor portfolios alongside multinational specialty chemical companies.
Demand is closely tied to advanced logic, DRAM, NAND flash, display manufacturing, and emerging packaging technologies, where increasingly complex device architectures require conformal deposition that conventional thin-film processes cannot consistently achieve. Purchasing decisions increasingly prioritize precursor purity, batch consistency, impurity control, delivery reliability, and compatibility with evolving deposition equipment rather than price alone. Semiconductor manufacturers typically undertake lengthy qualification procedures before approving new precursor suppliers because even minor chemical variations can reduce wafer yield or process stability. This creates long commercial relationships between fabs and qualified material vendors while raising barriers for new entrants.
South Korea's position as a global manufacturing hub for memory semiconductors continues to shape market dynamics. Investments by Samsung Electronics and SK hynix in advanced DRAM, high-bandwidth memory (HBM), NAND scaling, and advanced packaging require increasingly specialized precursor chemistries that support thinner films, lower thermal budgets, and higher aspect-ratio structures. Equipment manufacturers have likewise accelerated development of next-generation ALD platforms optimized for advanced nodes, further increasing demand for specialized precursor formulations.
Domestic specialty chemical producers are responding through product localization, expanded manufacturing capacity, and broader research collaborations with semiconductor manufacturers. International suppliers continue to compete through proprietary chemistries, extensive intellectual property portfolios, and global supply capabilities, resulting in a market where technical qualification, production consistency, and long-term customer support often outweigh pricing considerations.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Semiconductor chemicals remain Soulbrain's largest business | 83% of 2025 revenue | Demonstrates the importance of semiconductor materials within domestic specialty chemical demand. |
Primary domestic semiconductor customers | Samsung Electronics, SK hynix | Customer concentration increases qualification requirements but provides stable long-term demand. |
Product portfolio | High-k, barrier-layer, CVD/ALD precursor materials | Suppliers continue expanding advanced precursor chemistries for next-generation fabrication. |
Manufacturing focus | Advanced DRAM, 3D NAND, HBM | Memory technology migration increases precursor consumption per wafer. |
Customer qualification | Long validation cycles | Creates high switching costs and supports established supplier relationships. |
Market Drivers
Migration toward increasingly complex memory device architectures.
South Korea's memory manufacturers continue increasing layer counts, shrinking feature sizes, and adopting more complex transistor and capacitor structures, raising dependence on ALD processes that provide uniform coatings across high-aspect-ratio features. DRAM capacitor scaling, HBM production, and continued NAND evolution require precursor chemistries that produce defect-free dielectric and metal films under tightly controlled process conditions. Equipment suppliers including ASM identify advanced-node logic, HBM, and AI-related semiconductor demand as continuing drivers for next-generation ALD technologies, while domestic precursor suppliers continue expanding high-k dielectric and barrier-layer material portfolios to support these manufacturing requirements.
Localization of semiconductor material supply chains.
South Korea continues strengthening domestic production of strategic semiconductor materials following heightened attention to supply-chain resilience. Local chemical manufacturers have expanded production of high-purity semiconductor chemicals, including ALD precursors, to reduce dependence on imported specialty materials while shortening customer response times. Soulbrain reports supplying process chemicals to Samsung Electronics, SK hynix, Samsung Display, and LG Display while continuing new material development to address changing fabrication requirements. Overseas manufacturing investments also demonstrate efforts to support customers operating global fabrication networks while maintaining technology collaboration with domestic production facilities.
Expansion of advanced packaging and heterogeneous integration.
Demand for ALD precursors increasingly extends beyond front-end wafer fabrication into advanced packaging, where conformal dielectric and barrier films improve interconnect reliability and enable increasingly dense package architectures. AI accelerators and high-performance computing devices require advanced packaging solutions combining multiple chips within compact assemblies. These applications require deposition processes capable of coating complex three-dimensional geometries while maintaining electrical performance and thermal stability. Equipment manufacturers and materials suppliers are consequently investing in precursor development for packaging-specific applications alongside conventional semiconductor process materials.
Market Restraints and Challenges
Lengthy material qualification and customer approval cycles.
Introducing a new ALD precursor into semiconductor production remains a resource-intensive process because customers require extensive contamination testing, reliability verification, process optimization, and yield validation before commercial adoption. Qualification often extends across multiple production stages and product generations, delaying revenue realization for suppliers even after technical development has been completed. The challenge is particularly pronounced for smaller chemical producers attempting to enter supply chains already served by established vendors with extensive operational histories and proven manufacturing consistency. Established customer relationships therefore remain an important competitive advantage across South Korea's semiconductor materials industry.
Ultra-high purity requirements increase manufacturing complexity.
ALD precursors are manufactured under exceptionally stringent purity specifications because trace metallic or organic contaminants can reduce wafer yield, affect film properties, and shorten equipment maintenance intervals. Producing electronic-grade precursor materials therefore requires specialized synthesis, purification, analytical testing, and packaging infrastructure. Companies including SK Materials, Soulbrain, Hansol Chemical, Merck, and Entegris continue investing in purification technology, analytical capability, and contamination-control systems to satisfy increasingly demanding customer specifications. These investments raise production costs and create barriers for smaller suppliers lacking advanced quality-control infrastructure.
Dependence on imported precursor intermediates and specialty raw materials.
Although South Korea has strengthened domestic production of semiconductor chemicals, portions of the precursor value chain remain dependent on imported organometallic compounds, specialty ligands, fluorinated intermediates, and high-purity process gases. Export controls, geopolitical tensions, logistics disruptions, or shortages of specialty chemicals can therefore affect production schedules and inventory management. Several suppliers have responded by expanding local synthesis capability, qualifying alternative raw-material sources, and increasing inventory buffers. However, complete localization remains difficult because certain precursor chemistries require specialized manufacturing expertise concentrated in only a limited number of countries.
Accelerating technology transitions shorten product life cycles.
Semiconductor technology evolves more rapidly than most specialty chemical markets. New transistor structures, higher-layer NAND devices, advanced DRAM generations, gate-all-around architectures, and increasingly sophisticated packaging technologies frequently require modified or entirely new precursor formulations. Material suppliers must therefore sustain high research and development expenditure while supporting legacy products that remain qualified in existing fabrication lines. This increases development costs and technical risk, particularly when customer qualification timelines extend over several years while technology roadmaps continue advancing.
Major Segment Analysis
Electronics and Semiconductors End-user Segment
Electronics and semiconductor manufacturing represents the most commercially important end-user segment because ALD precursors directly influence thin-film quality, device reliability, and manufacturing yield across advanced integrated circuit production. South Korea's concentration of memory fabrication facilities, together with continued investment in AI-oriented DRAM, HBM, and advanced NAND technologies, creates sustained demand for increasingly specialized metal, dielectric, and barrier-layer precursor chemistries. Buyers place greater emphasis on purity, repeatability, contamination control, delivery reliability, and long-term technical support than on purchase price alone, reflecting the high cost of process interruptions within semiconductor fabrication plants.
Competition within this segment extends beyond chemical formulation. Suppliers differentiate themselves through process-development support, analytical characterization, application engineering, local technical service, and the ability to manufacture at commercial scale under rigorous quality standards. Long qualification cycles increase switching costs and encourage long-term supplier relationships, while ongoing technology migration continues creating opportunities for companies capable of developing precursor chemistries compatible with increasingly complex deposition processes. Display manufacturing, energy storage, and research applications continue contributing demand, although their purchasing volumes generally remain below those associated with semiconductor fabrication.
Competitive Landscape
Competition in the South Korea ALD precursors market is technology-driven and qualification-intensive, with suppliers competing primarily on chemical purity, process compatibility, manufacturing consistency, and long-term technical support rather than pricing alone. The market combines established domestic specialty chemical manufacturers with multinational materials suppliers that possess extensive intellectual property, global manufacturing networks, and broad semiconductor customer relationships.
SK Materials, Soulbrain, Hansol Chemical, and Wonik Materials have strengthened their positions by expanding semiconductor material portfolios, increasing domestic manufacturing capability, and collaborating closely with Korean chip manufacturers on process qualification. International suppliers including Merck KGaA, Air Liquide Korea, Entegris, Linde Korea, ADEKA Corporation, and UP Chemical (Yoke Technology) continue competing through proprietary precursor chemistries, integrated material supply, global logistics, and advanced analytical capabilities. Across the industry, suppliers are investing in research and development, production automation, contamination-control systems, and localized supply chains to meet increasingly stringent customer specifications while reducing supply-chain risks associated with imported specialty materials. High qualification costs, extensive customer validation, and rigorous purity standards continue to create substantial barriers for new entrants.
Recent Developments
August 2026: Merck reported continued semiconductor-material demand in its second-quarter results, with Semiconductor Solutions performance supported by advanced materials serving next-generation semiconductor manufacturing applications.
July 2026: Merck presented its expanding ALD precursor technology portfolio at ALD 2026, including new precursor development for low-growth-rate aluminum oxide and advanced high-k semiconductor applications.
February 2026: Applied Materials launched the Spectral ALD system. Targeted heavily at Korean fabs, it selectively deposits molybdenum instead of tungsten, shifting transistor contact wiring strategies.
October 2025: SK Hynix and Samsung Electronics signed letters of intent to supply advanced DRAM wafers for OpenAI's $500 billion Stargate AI data centers. This partnership boosts South Korea's role in AI infrastructure, with joint construction of two facilities in Korea, enhancing ALD precursor demand for high-density HBM production.
June 2025: ASM International advanced local capabilities during the ALD 2025 conference on Jeju Island, showcasing Pulsar ALD platforms upgraded to reduce chemical waste and improve precursor efficiency.
Regulatory and Policy Environment
South Korea's semiconductor materials industry operates within a regulatory framework that combines industrial policy, environmental regulation, workplace safety requirements, export control measures, and chemical management legislation. The Korean Act on Registration and Evaluation of Chemicals (K-REACH) requires manufacturers and importers to register chemical substances, evaluate associated risks, and maintain compliance before commercial distribution. The Chemical Control Act (CCA) establishes additional requirements governing hazardous chemical handling, transportation, storage, and workplace safety.
Government industrial policy continues to support domestic semiconductor manufacturing through initiatives designed to strengthen supply-chain resilience, encourage advanced manufacturing investment, expand semiconductor research, and improve strategic material self-sufficiency. These measures have encouraged greater investment in high-purity specialty chemicals, including ALD precursors, while promoting collaboration between semiconductor manufacturers, universities, research institutes, and domestic material suppliers.
Environmental regulations also influence precursor manufacturing by requiring tighter emissions control, improved waste management, and safer handling of hazardous process chemicals. Compliance increases operating costs but also encourages investment in cleaner manufacturing technologies and advanced purification systems that improve product quality alongside regulatory performance.
Outlook and Strategic Implications
Demand for ALD precursors in South Korea is expected to remain closely aligned with investment in advanced semiconductor manufacturing rather than overall electronics production. Continued migration toward higher-density memory, gate-all-around logic devices, heterogeneous integration, and advanced packaging will increase demand for increasingly specialized precursor chemistries capable of supporting complex three-dimensional device architectures.
Commercial opportunities are likely to favor suppliers capable of shortening development cycles while maintaining stringent purity standards and reliable large-scale production. Material innovation alone will not determine competitive success. Customers increasingly expect application engineering support, rapid technical collaboration, dependable logistics, and long-term supply security throughout product qualification and commercial manufacturing.
Key strategic implications include:
For material suppliers: Expand high-purity precursor portfolios while strengthening domestic production and analytical capabilities.
For semiconductor manufacturers: Maintain diversified qualified supplier networks to improve supply resilience without compromising process consistency.
For investors: Companies with established customer qualifications, proprietary precursor technologies, and scalable manufacturing infrastructure are likely to remain better positioned than suppliers competing primarily on cost.
For policymakers: Continued support for semiconductor material localization, chemical innovation, and research collaboration can strengthen South Korea's position within the global semiconductor supply chain while reducing dependence on imported specialty materials.
South Korea ALD Precursors Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.48 billion |
| Total Market Size in 2031 | USD 0.67 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, Technology, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
By Technology
By End-user
Geographical Segmentation
- North America
- South America
- Europe
- Middle East and Africa
- Asia Pacific
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. SOUTH KOREA ALD PRECURSORS MARKET BY APPLICATION
5.1. Introduction
5.2. High-k Dielectric
5.3. Metal Gate Electrodes
5.4. Moisture Barriers and Encapsulation
5.5. Surface Passivation
5.6. Barrier Layers
5.7. Advanced Packaging
5.8. Others
6. SOUTH KOREA ALD PRECURSORS MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Plasma-Enhanced ALD
6.3. Thermal ALD
6.4. Spatial ALD
6.5. Roll-to-Roll ALD
6.6. Area-Selective ALD
7. SOUTH KOREA ALD PRECURSORS MARKET BY END-USER
7.1. Introduction
7.2. Electronics and Semiconductors
7.3. Display Manufacturing
7.4. Solar Energy
7.5. Automotive
7.6. Energy Storage
7.7. Research and Development
7.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. SK Materials Co., Ltd.
9.2. Soulbrain Co., Ltd.
9.3. Hansol Chemical Co., Ltd.
9.4. Wonik Materials Co., Ltd.
9.5. Merck KGaA
9.6. Air Liquide Korea
9.7. Entegris, Inc.
9.8. Linde Korea
9.9. ADEKA Corporation
9.10. UP Chemical (Yoke Technology)
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key benefits for the stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected growth and market size of the South Korea ALD Precursors Market from 2026 to 2031?
The South Korea ALD Precursors Market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 6.9% between 2026 and 2031. This growth is expected to increase the market size from USD 0.48 billion in 2026 to an estimated USD 0.67 billion by 2031, reflecting the expanding semiconductor manufacturing base.
Which specific industries and technological advancements are primary drivers for ALD precursor demand in South Korea?
Demand is primarily driven by South Korea's advanced logic, DRAM, NAND flash, display manufacturing, and emerging packaging technologies. Key technological advancements include memory technology migration, requiring high-purity metal-organic precursor chemistries, and investments in AI-driven memory and advanced packaging.
Who are the key players and what factors determine market competition in the South Korea ALD Precursors Market?
The South Korea ALD Precursors Market features competition between local suppliers, such as Soulbrain (a major domestic semiconductor chemical supplier), expanding portfolios through localization, and multinational specialty chemical companies. Competition is primarily based on proprietary chemistries, extensive intellectual property, global supply capabilities, and rigorous technical qualification, often outweighing pricing considerations due to lengthy qualification procedures by manufacturers like Samsung Electronics and SK hynix.
What are the most critical purchasing criteria for semiconductor manufacturers in the South Korea ALD Precursors Market?
Principal purchasing criteria include product purity, process repeatability, contamination control, and supply security. Additionally, batch consistency, impurity control, delivery reliability, and compatibility with evolving deposition equipment are paramount, as even minor chemical variations can reduce wafer yield or process stability.
How do strategic investments by major South Korean semiconductor companies influence the ALD precursors market?
Investments by Samsung Electronics and SK hynix in advanced DRAM, high-bandwidth memory (HBM), NAND scaling, and advanced packaging significantly expand precursor requirements. These investments drive demand for increasingly specialized precursor chemistries that support thinner films, lower thermal budgets, and higher aspect-ratio structures for next-generation ALD platforms.
What unique dynamics position South Korea as a critical hub for the ALD precursors market and how do domestic factors impact it?
South Korea's position as a global manufacturing hub for memory semiconductors, coupled with substantial investments from industry giants, makes it critical. Domestic material localization continues to reshape supplier qualification and procurement strategies, fostering expanded manufacturing capacity and research collaborations between local specialty chemical producers and semiconductor manufacturers.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). South Korea ALD Precursors Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/south-korea-ald-precursors-market