
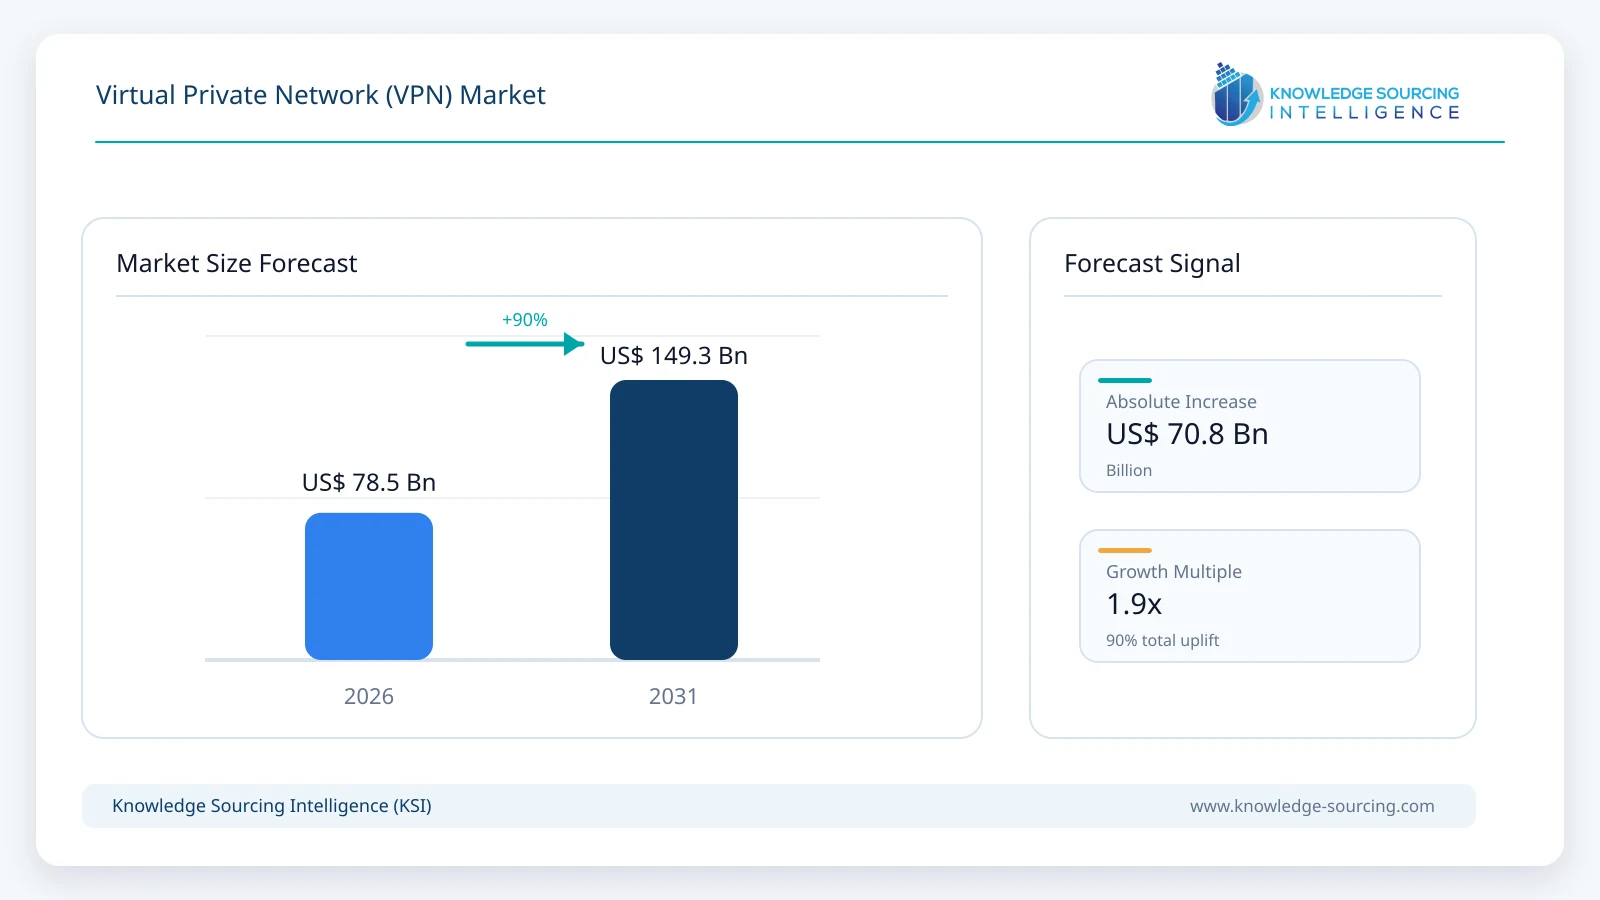
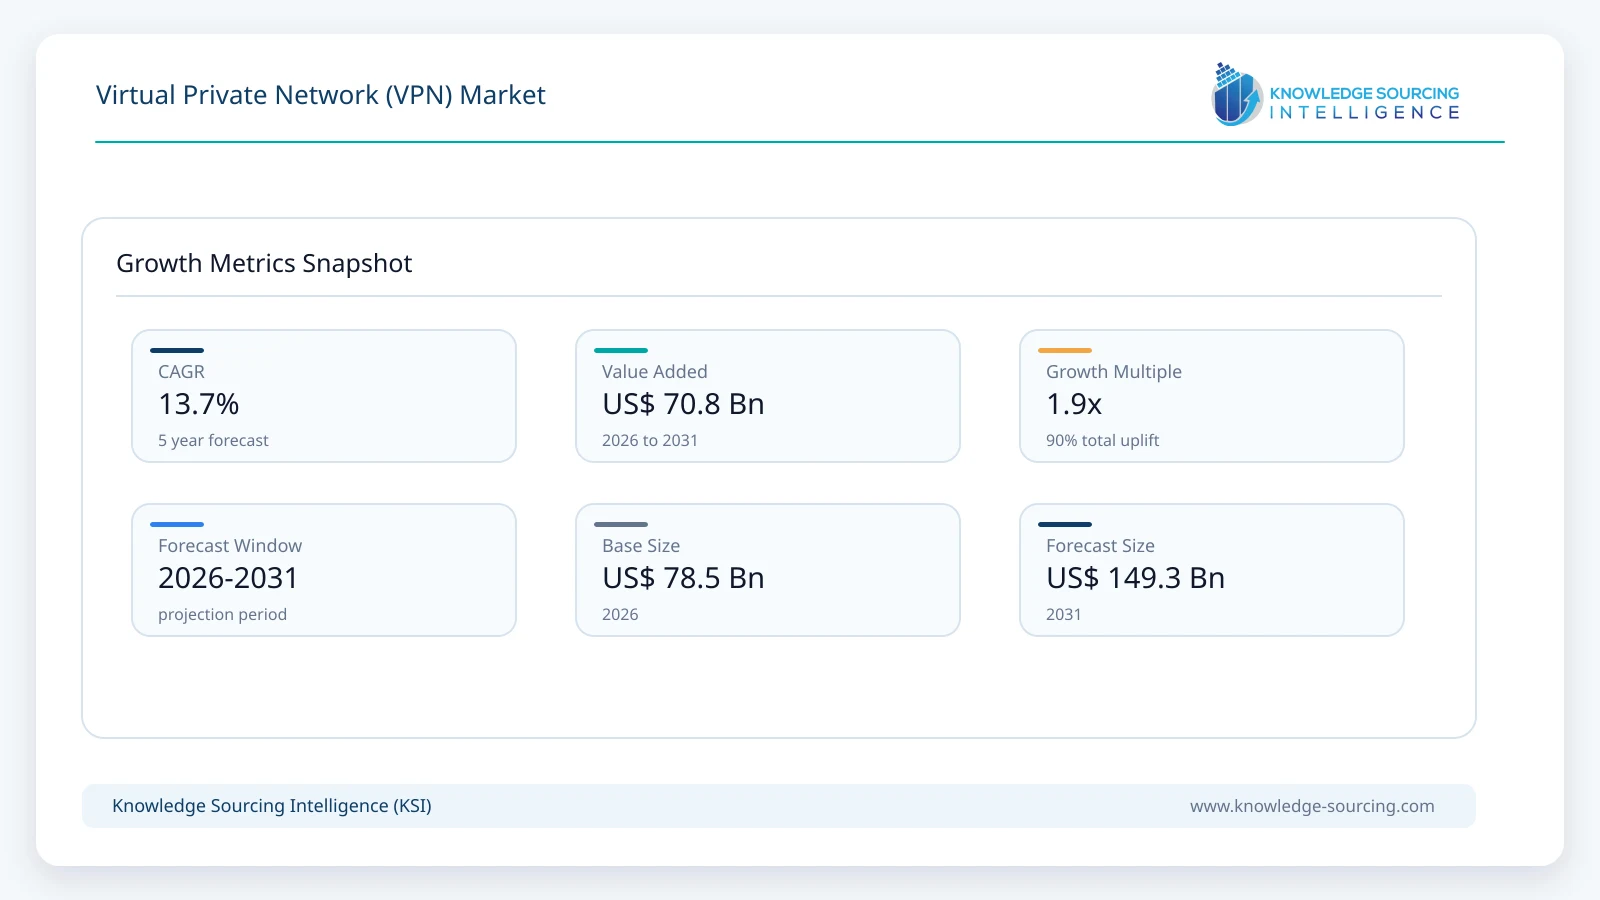
The global VPN market is forecast to grow at a CAGR of 13.7%, increasing from USD 78.5 billion in 2026 to USD 149.3 billion by 2031.
Highlights:
- 1Enterprise and commercial use accounts for the largest share of global VPN revenue in 2026.
- 2Cloud-managed VPN services are expanding faster than traditional appliance-only deployments.
- 3Remote-access VPN remains commercially important even as zero-trust application access gains adoption.
- 4AWS rebuilt its Client VPN application in August 2026 with CLI support and centralized administrative controls.
- 5Consumer VPN protocols are moving toward post-quantum protection and stronger censorship resistance.
- 6North America remains the largest regional market, while Asia Pacific records faster adoption growth.
VPNs continue to provide a foundational mechanism for encrypting traffic across untrusted networks, but the architecture of the market is changing. Traditional enterprise VPNs extend network access to remote users or connect sites through encrypted tunnels. Modern deployments increasingly combine VPN with identity, endpoint posture, DNS security, CASB, secure web gateway and zero-trust controls. Cisco Secure Access, Fortinet FortiClient, Palo Alto Networks GlobalProtect and NordLayer all illustrate this convergence. For market-sizing purposes, however, KSI counts only the VPN-specific or directly attributable secure-tunneling revenue rather than the full value of these broader security suites.
Cloud platforms are also making VPN a managed infrastructure service. AWS Client VPN provides managed remote-user access to AWS and on-premises resources, while AWS Site-to-Site VPN connects networks to cloud virtual private clouds. Microsoft Azure VPN Gateway supports site-to-site and point-to-site encrypted connectivity and added new certificate-authentication and user-group capabilities in 2026. These services shift spending away from self-managed concentrators toward subscription or consumption-based connectivity and reduce the operational burden associated with hardware appliances.
Consumer VPN competition follows a different commercial model. NordVPN, ExpressVPN, Proton VPN and PureVPN compete on privacy, speed, server coverage, multi-device support, censorship resistance and protocol design. ExpressVPN's Lightway protocol now includes post-quantum protection based on ML-KEM, while Proton VPN introduced a new protocol codebase in August 2026 designed to improve performance and prepare for post-quantum encryption. These developments show that protocol engineering is becoming a visible product differentiator rather than a background infrastructure choice.
Market Trends
VPN Is Converging with Zero-Trust Access Rather Than Disappearing
Zero-trust network access is often described as a replacement for legacy VPN, but enterprise environments increasingly operate both models together. Cisco Secure Client supports both VPN and Zero Trust Access modules, while FortiClient combines VPN-encrypted tunnels with universal ZTNA. Palo Alto Networks continues to support GlobalProtect remote-access VPN alongside Prisma Access. The commercial transition is therefore gradual: organizations keep VPN for broad network connectivity, administrative access, legacy applications and site-to-site links while moving higher-risk or application-specific use cases toward identity-aware zero-trust access.
Cloud-Managed VPN Is Reducing Dependence on Dedicated Concentrators
Cloud-managed VPN services remove the need to purchase and operate dedicated head-end hardware for many use cases. AWS Client VPN is fully managed and expanded into four additional regions in July 2026 before introducing a rebuilt cross-platform client in August. Azure VPN Gateway provides managed site-to-site and point-to-site connectivity and is consolidating older gateway SKUs onto availability-zone-capable platforms. OpenVPN CloudConnexa similarly provides global private networking with zero-trust access policies, DNS filtering, IDS/IPS and centralized management. These models shift the market toward recurring service revenue and improve scalability for distributed organizations.
Mesh and Identity-Aware Networking Are Reshaping Remote Connectivity
Mesh VPN platforms reduce reliance on centralized concentrators by allowing devices, servers and services to create encrypted peer-to-peer connections. Tailscale operationalizes WireGuard through a managed control plane and identity integrations, serving more than 40,000 companies and over 2.5 million active devices according to its current enterprise disclosures. This architecture is especially attractive to software, DevOps and multi-cloud teams because connectivity policies can be tied to users, roles and resources rather than static network location. Mesh VPN is therefore becoming a distinct growth path within software-defined enterprise connectivity.
Post-Quantum Protection Is Becoming a Consumer VPN Differentiator
Consumer VPN vendors are beginning to protect encrypted sessions against future harvest-now-decrypt-later threats. ExpressVPN includes post-quantum protection in Lightway by default and now uses ML-KEM, while Proton VPN's 2026 protocol roadmap explicitly prepares its next-generation client architecture for post-quantum encryption. Cloudflare WARP also uses post-quantum cryptography when tunneling traffic over its MASQUE-based connection. These features currently support differentiation more than immediate revenue expansion, but they increase the technical expectations placed on premium VPN services.
Market Drivers
Hybrid Work and Multi-Cloud Infrastructure Sustain Secure Remote Connectivity Demand
Enterprise applications and workloads are distributed across SaaS platforms, public clouds, private clouds, data centers and branch offices. Employees and contractors also connect from unmanaged or remote networks. VPN remains one of the simplest mechanisms for creating encrypted connectivity across these environments, particularly where organizations must support legacy applications, administrative protocols or broad network access. Cloud VPN gateways and software clients make deployment faster than traditional appliance-only architectures and allow capacity to scale with workforce demand.
Cybersecurity and Data-Privacy Requirements Support Encrypted-Tunnel Adoption
Organizations need to protect data in transit across public networks, while consumers increasingly use VPNs to reduce tracking and improve privacy. Enterprise VPN platforms now incorporate multifactor authentication, device-posture checks, certificate authentication, identity-provider integration and centralized policy. Microsoft added site-to-site certificate authentication and user-group support to Azure VPN Gateway in May 2026, while Cisco and Fortinet integrate VPN with zero-trust and endpoint-security controls. These capabilities support continued spending even as security architectures modernize.
Consumer Privacy, Censorship Resistance and Travel Use Cases Expand Subscription Demand
Consumer VPN services address a different set of needs from enterprise VPNs, including privacy on public Wi-Fi, secure browsing, location shifting, censorship resistance and access while traveling. Leading providers are extending beyond basic tunnels with dedicated IP addresses, password management, threat blocking and other privacy tools. Proton and ExpressVPN also emphasize anti-censorship and protocol-level innovation. Subscription models allow vendors to monetize recurring demand globally without the hardware deployment requirements of enterprise VPN infrastructure.
Market Restraints
ZTNA Substitution, Performance Overhead and Regulatory Restrictions Constrain Growth
Traditional remote-access VPN can expose broad network segments once a user is authenticated, which conflicts with least-privilege security principles. Organizations are therefore shifting selected workloads toward application-level ZTNA, reducing the share of enterprise security budgets assigned to conventional VPN. Encryption and tunnel routing can also add latency, particularly when traffic is backhauled through central gateways. Consumer VPN services face blocking or regulatory restrictions in some countries, while free or low-cost providers can reduce willingness to pay. These factors do not eliminate VPN demand, but they shift growth toward cloud-managed, identity-aware and performance-optimized offerings.
Segment Analysis
By Application - Commercial / Enterprise
Commercial and enterprise applications are estimated at approximately USD 51.0 billion in 2026 and remain the largest application segment. Revenue includes employee remote access, site-to-site connectivity, managed VPN services, cloud VPN gateways and directly attributable secure-access appliances. Consumer VPN remains a substantial independent segment driven by privacy and location flexibility, while government and specialized institutional use contributes additional demand. Enterprise growth increasingly comes from managed and cloud connectivity rather than stand-alone concentrator hardware.
By Offering - VPN Solutions and Software
VPN software and solution revenue is estimated at approximately USD 45.5 billion in 2026 and forms the largest offering segment. The category includes consumer clients, enterprise remote-access software, VPN gateway software and cloud-managed VPN platforms. Services are expanding through managed connectivity, implementation and subscription support, while dedicated hardware represents a smaller share as functionality moves into firewalls, cloud gateways and software-defined platforms. Hardware remains important where high throughput, branch connectivity or regulated on-premises deployment is required.
By Connection Type - Remote Access VPN
Remote-access VPN is estimated at approximately USD 35.0 billion in 2026 and remains the largest connection-type segment because distributed users require secure access to enterprise networks and cloud resources. Site-to-site VPN remains critical for branch, data-center and cloud connectivity and is more stable than consumer-facing demand. Mesh VPN and identity-aware private networking are emerging as faster-growing forms of secure remote connectivity, especially among cloud-native and developer-led organizations.
By Deployment - Cloud-Managed
Cloud-managed VPN is estimated at approximately USD 44.0 billion in 2026 and has become the largest deployment model when managed cloud gateways and subscription-based VPN services are combined. AWS Client VPN, Azure VPN Gateway, OpenVPN CloudConnexa, NordLayer and cloud-delivered SASE platforms illustrate the shift. On-premises VPN remains important for regulated enterprises, legacy infrastructure and organizations that require direct control of gateway hardware, but new deployments increasingly favor software-defined or managed service models.
By Organization Size - Large Enterprises
Large enterprises remain the largest organization-size segment because they operate more locations, clouds, users and regulated applications. They also purchase higher-throughput gateways, redundancy, premium support and broader identity or endpoint integrations. Small and medium-sized businesses are expected to grow faster as cloud-managed VPN and SASE products remove the need for specialist network-security teams. NordLayer's SMB-focused business browser and OpenVPN's seat-based CloudConnexa pricing reflect the effort to simplify secure connectivity for smaller organizations.
By Geography - North America
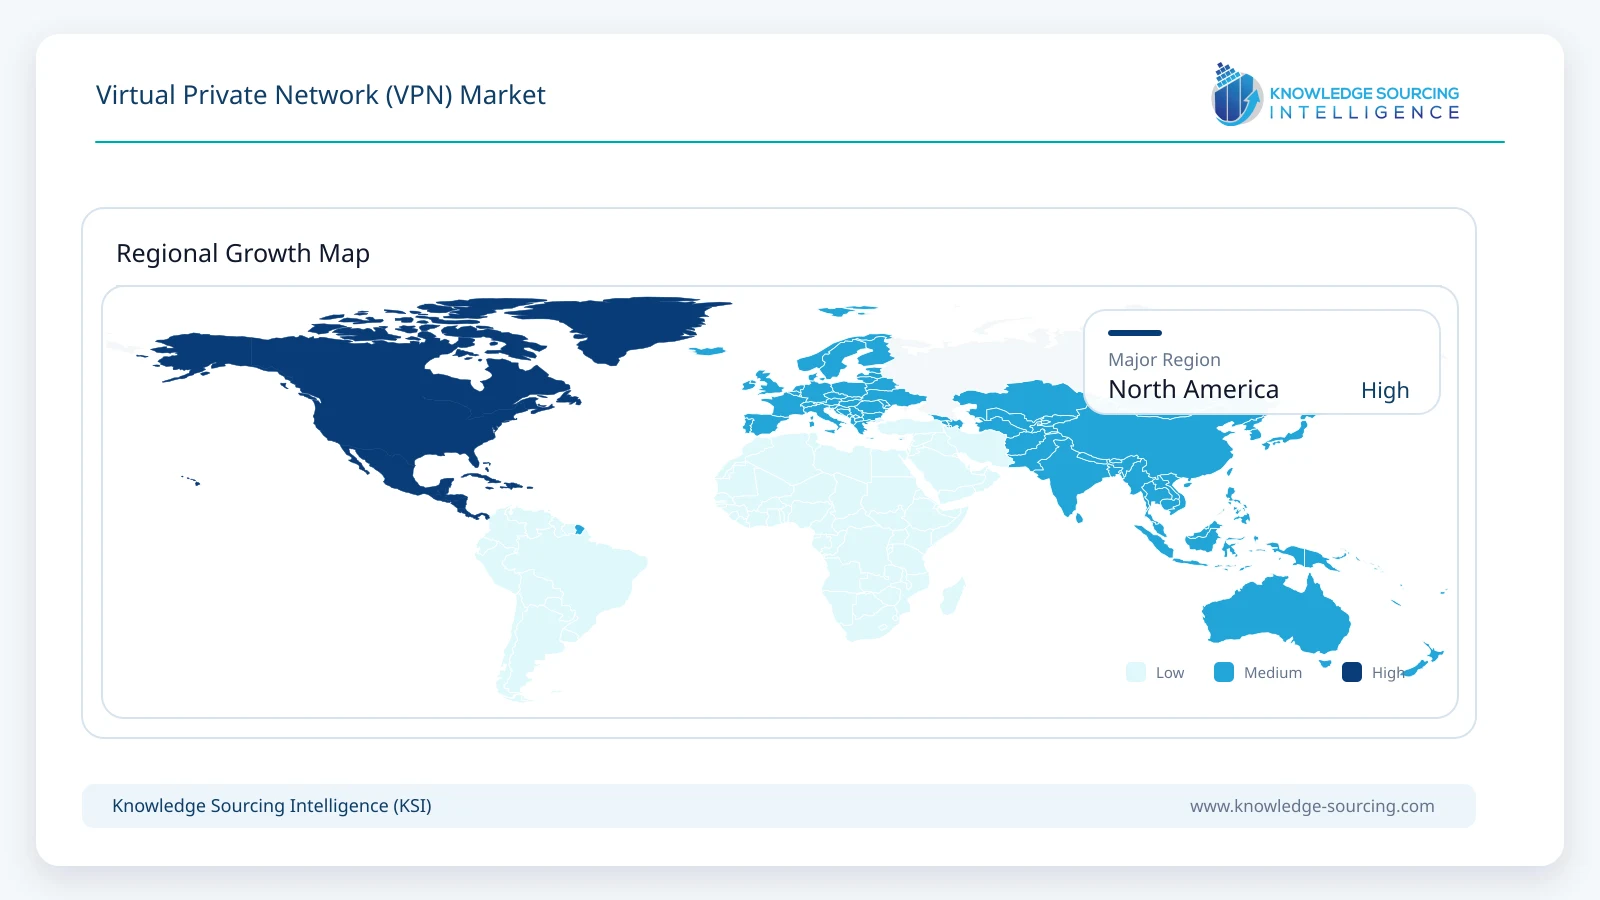
North America is estimated at approximately USD 28.3 billion in 2026 and remains the largest regional market. The United States has high enterprise cloud adoption, a large remote workforce, extensive cybersecurity spending and major VPN suppliers including Cisco, Fortinet, Palo Alto Networks, Microsoft, AWS, Cloudflare, F5 and OpenVPN. Europe remains a large privacy- and enterprise-security market, while Asia Pacific is expected to grow faster as cloud adoption, distributed work and consumer privacy demand expand across India, Southeast Asia, Japan and other digital economies.
Competitive Environment
The VPN market spans enterprise network-security vendors, hyperscale cloud providers, open-source and software-defined networking companies, and consumer privacy brands. Cisco, Fortinet, Palo Alto Networks, Check Point, F5, WatchGuard, Ivanti and SonicWall compete in enterprise secure access and gateway environments. Microsoft and AWS provide managed cloud VPN gateways, while Cloudflare integrates encrypted tunneling into its broader connectivity and zero-trust platform. OpenVPN and Tailscale provide software-centric alternatives that reduce dependence on traditional appliance architectures.
Consumer competition is concentrated around subscription brands with large international server networks and proprietary protocols. Kape Technologies is profiled once as the parent of ExpressVPN, CyberGhost and Private Internet Access to avoid counting related brands as separate independent companies. Nord Security is likewise represented at parent level for NordVPN and NordLayer. Proton AG provides Proton VPN as part of its privacy ecosystem, while PureVPN remains an independent consumer and business VPN provider. Company selection has been verified against active 2026 product portfolios rather than historical brand lists.
Recent Developments
September 2026: Cisco updated Secure Access regional and VPN requirements as its cloud-delivered VPN and zero-trust services expanded across global regions.
August 2026: AWS launched a rebuilt Client VPN application with CLI automation, centralized administrative controls and faster connection establishment using OpenVPN3.
August 2026: Proton VPN introduced a new client-side protocol codebase designed to improve performance and prepare for post-quantum encryption.
July 2026: AWS Client VPN expanded to four additional regions, including Canada West, Mexico Central, New Zealand and Taipei.
April 2026: NordLayer launched NordLayer Browser for SMB security while continuing to integrate VPN connectivity into its SASE platform.
January-March 2026: ExpressVPN retired legacy application versions and moved users to its current app generation with continued post-quantum Lightway protection.
Virtual Private Network (VPN) Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 78.5 billion |
| Total Market Size in 2031 | USD 149.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 13.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, Offering, Connection Type, Deployment, Organization Size, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
Consumer
Commercial / Enterprise
Government and Other Institutional Use
By Offering
Solutions and Software
Services
Hardware / Appliances
By Connection Type
Remote Access VPN
Site-to-Site VPN
Clientless / Browser-Based VPN
Mesh and Other VPN Architectures
By Deployment
Cloud-Managed
On-Premises
By Organization Size
Small and Medium-Sized Enterprises
Large Enterprises
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Spain
Italy
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Others
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Hybrid Work and Multi-Cloud Infrastructure Sustain Secure Remote Connectivity Demand
3.1.2. Cybersecurity and Data-Privacy Requirements Support Encrypted-Tunnel Adoption
3.1.3. Consumer Privacy, Censorship Resistance and Travel Use Cases Expand Subscription Demand
3.2. Market Restraints
3.2.1. ZTNA Substitution, Performance Overhead and Regulatory Restrictions Constrain Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. IPsec and IKE VPN
4.2. TLS / SSL VPN
4.3. WireGuard and Mesh VPN
4.4. Cloud-Managed VPN Gateways
4.5. VPN and Zero-Trust Convergence
4.6. Post-Quantum VPN Protocols
5. GLOBAL VPN MARKET BY APPLICATION
5.1. Introduction
5.2. Consumer
5.3. Commercial / Enterprise
5.4. Government and Other Institutional Use
6. GLOBAL VPN MARKET BY OFFERING
6.1. Introduction
6.2. Solutions and Software
6.3. Services
6.4. Hardware / Appliances
7. GLOBAL VPN MARKET BY CONNECTION TYPE
7.1. Introduction
7.2. Remote Access VPN
7.3. Site-to-Site VPN
7.4. Clientless / Browser-Based VPN
7.5. Mesh and Other VPN Architectures
8. GLOBAL VPN MARKET BY DEPLOYMENT
8.1. Introduction
8.2. Cloud-Managed
8.3. On-Premises
9. GLOBAL VPN MARKET BY ORGANIZATION SIZE
9.1. Introduction
9.2. Small and Medium-Sized Enterprises
9.3. Large Enterprises
10. GLOBAL VPN MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. Germany
10.4.2. United Kingdom
10.4.3. France
10.4.4. Spain
10.4.5. Italy
10.4.6. Others
10.5. Middle East & Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. South Africa
10.5.4. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. India
10.6.3. Japan
10.6.4. South Korea
10.6.5. Australia
10.6.6. Indonesia
10.6.7. Thailand
10.6.8. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Enterprise VPN, Cloud VPN and Consumer Privacy Positioning
11.3. VPN-to-ZTNA and SASE Migration Strategy
11.4. Protocol, Post-Quantum and Product Development
11.5. Competitive Dashboard
12. COMPANY PROFILES
12.1. Cisco Systems, Inc.
12.2. Fortinet, Inc.
12.3. Palo Alto Networks, Inc.
12.4. Check Point Software Technologies Ltd.
12.5. Microsoft Corporation
12.6. Amazon Web Services, Inc.
12.7. Cloudflare, Inc.
12.8. F5, Inc.
12.9. WatchGuard Technologies, Inc.
12.10. Ivanti, Inc.
12.11. SonicWall Inc.
12.12. OpenVPN Inc.
12.13. Nord Security
12.14. Kape Technologies plc
12.15. Proton AG
12.16. Tailscale Inc.
12.17. PureVPN
12.18. Sophos Ltd.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected growth of the global VPN market from 2026 to 2031?
Market to grow from $78.5B (2026) to $149.3B (2031) at 13.7% CAGR.
Which segment accounts for the largest VPN revenue share in 2026?
Enterprise and commercial use holds the largest revenue share in 2026.
Which region dominates the global VPN market, and which is growing fastest?
North America dominates; Asia Pacific records faster adoption growth.
What key trend is shaping the modern VPN market architecture?
VPN is converging with zero-trust access and identity solutions.
How are VPN deployments evolving regarding management and services?
Cloud-managed VPN services are expanding faster than traditional appliance deployments.
What are the emerging trends in consumer VPN protocols?
Consumer VPNs are moving toward post-quantum protection and stronger censorship resistance.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Virtual Private Network (VPN) Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/virtual-private-network-vpn-market