
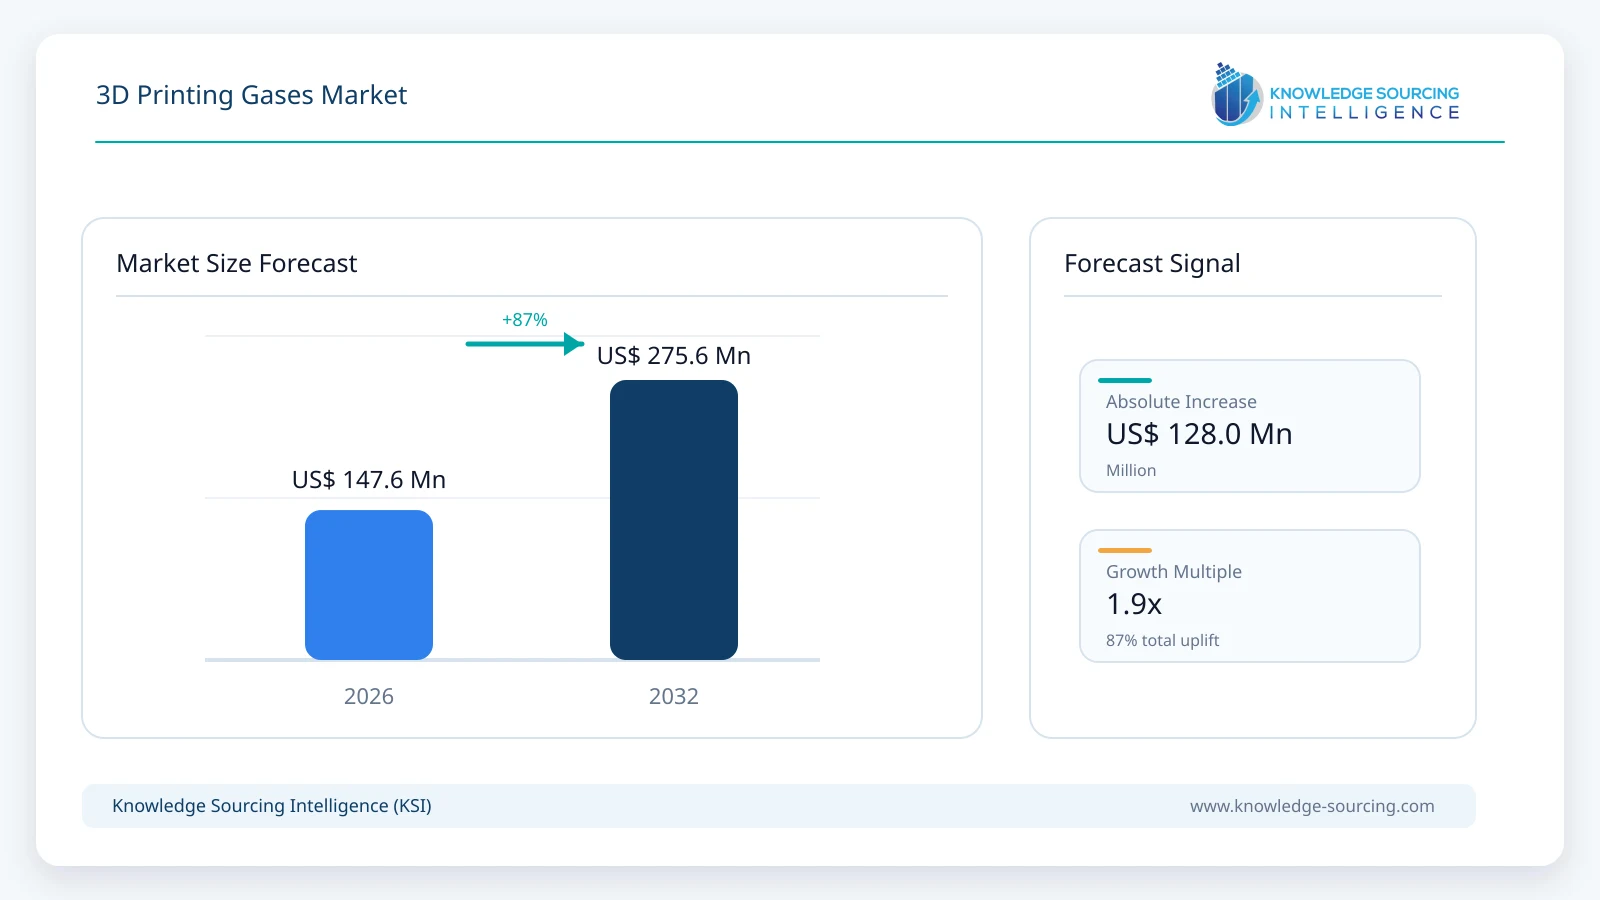
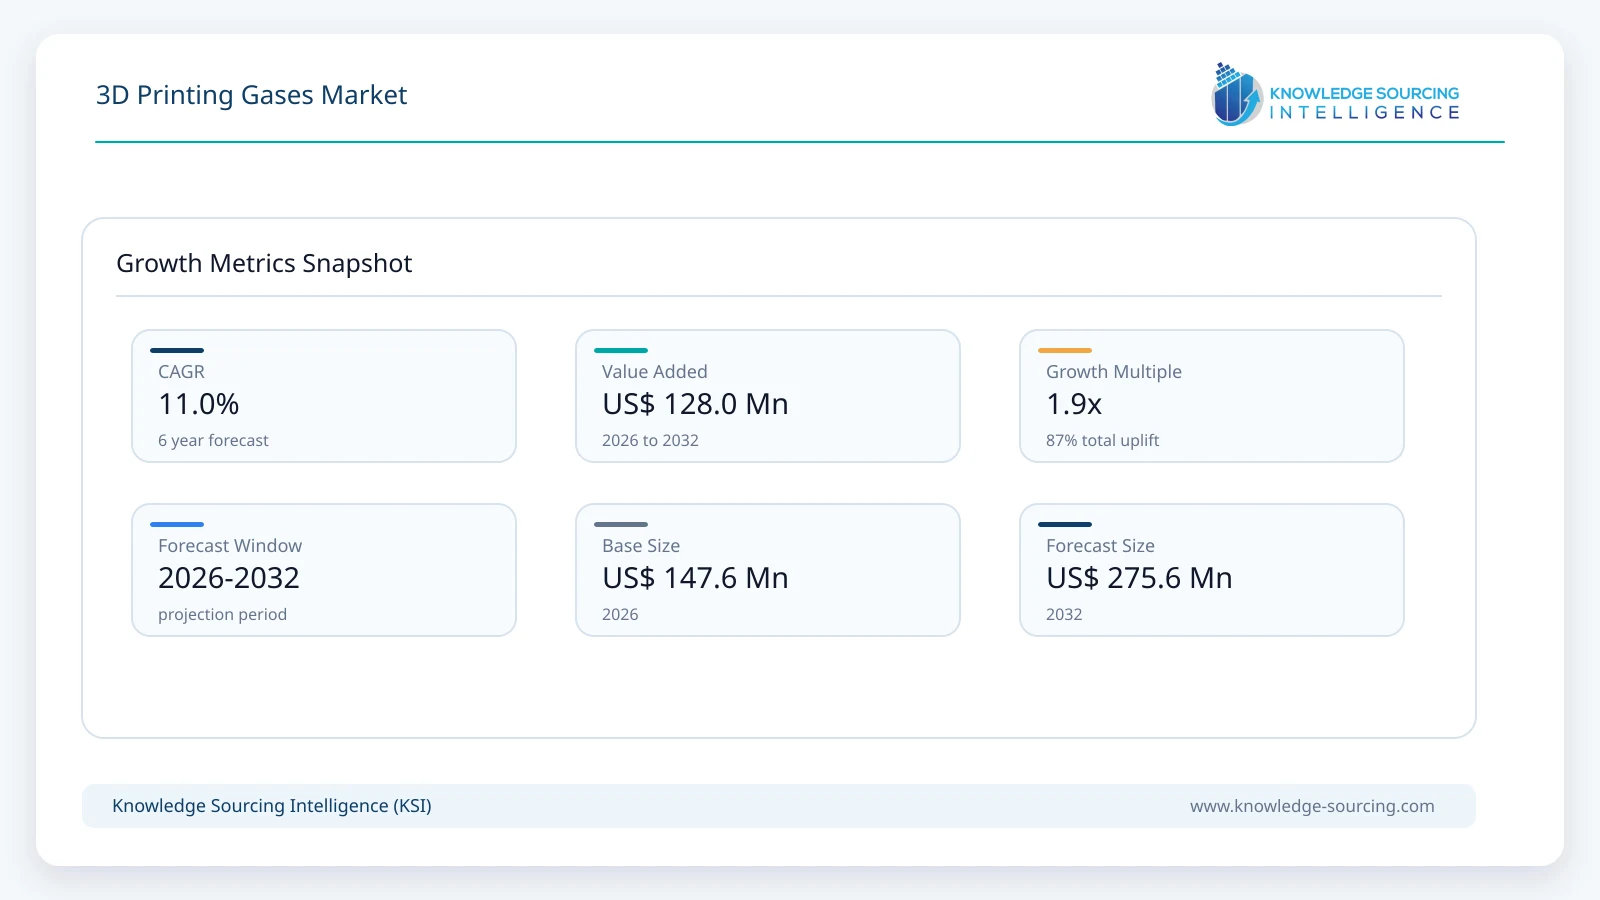
The 3D printing gases market is estimated at USD 147.6 million in 2026 and is projected to reach USD 275.6 million by 2032, representing a CAGR of 11.0% during the forecast period.
Highlights:
- 1Argon is estimated to account for 71.1% of global 3D printing gas revenue in 2026. Its position reflects widespread use in titanium, nickel alloy, aluminum and other atmosphere-sensitive metal-printing processes, alongside a higher delivered price than nitrogen.
- 2Global demand increasingly reflects the installed and utilized production fleet rather than new printer shipments alone. Wohlers Associates reported 3,793 metal additive-manufacturing system shipments in 2023, while industry shipment data show differing trajectories across powder bed fusion and directed energy deposition.
- 3Process-gas requirements vary materially between platforms. Renishaw has documented argon feed below 30 liters per hour for its AM250 system, whereas EOS M290 research specifies an approximately 1.034 m³ initial flooding volume followed by 0.2658 m³ per hour during printing; the resulting spread makes machine-level engineering important to market estimates.
- 4Specialty mixtures are developing around process qualification and part quality. Linde's argon–helium ADDvance Laser230 and argon–hydrogen ADDvance Sinter250 address different performance requirements, making gas chemistry a more valuable differentiator than generic purity claims.
The market comprises argon, nitrogen and specialty gas mixtures purchased for metal additive manufacturing processes that require controlled atmospheres, melt-pool shielding, or gas-assisted debinding and sintering. The forecast reflects the active production fleet, productive machine hours, fresh-gas consumption, gas selection and realized supply economics rather than an assumed rate of growth for the overall 3D printing industry.
Commercial demand is increasingly determined by the economics of qualified metal-part production. A metal printer consumes protective gas to manage oxygen exposure, powder oxidation, fumes or shielding around the deposited metal. Yet its expenditure depends as much on whether the machine is designed to recirculate the chamber atmosphere and how frequently it is purged as on the number of installed lasers. Suppliers therefore face a market in which additions to the machine fleet generate recurring gas demand, while more efficient atmosphere-control systems and larger bulk-delivery contracts can reduce gas spending per finished part. This makes gas consumption a less straightforward indicator of metal-printing growth than machine revenue or powder shipment volumes.
The estimate focuses on purchased gases consumed during laser powder bed fusion, directed energy deposition and wire-arc additive manufacturing, and gas-assisted debinding or sintering linked to binder jetting and bound-metal material extrusion. The value of upstream powder atomization, standalone hot isostatic pressing, general factory welding, gas-generation equipment and unrelated polymer printing is not included. This definition distinguishes recurring process-gas sales from the considerably larger industrial-gas value chain serving metal fabrication generally.
3D Printing Gases Market Trends
Gas consumption is becoming more closely linked to productivity than installed hardware alone. The industry's transition from low-utilization development work toward recurring aerospace, defense and industrial programs changes the amount of gas used per machine. Wohlers Associates' 2026 assessment identifies increasing utilization of existing AM capacity as an important market characteristic, even as equipment sales fluctuate. Consequently, gas suppliers serving production customers may experience demand growth despite weak equipment order cycles. In contrast, installations that remain in research or qualification mode can hold capital-intensive machines without generating comparable volumes of recurring gas purchases. The decisive variable for gas revenue is the combination of operating hours, process recipe and purchased gas lost through printing, purge and handling operations.
Machine architecture is placing downward pressure on gas volume per productive hour. Renishaw describes an atmosphere-generation method that first evacuates its chamber before introducing roughly 600 liters of argon, permitting low replenishment rates during the build. Research published in 2026 on an EOS M290 reports an initial inert-gas fill of 1,034 liters and a continuous flow of 265.8 liters per hour. These are equipment-specific measurements rather than interchangeable fleet averages. They demonstrate why applying a common gas-flow figure to every system can materially overstate market demand. Suppliers must therefore anticipate that wider deployment of oxygen monitoring, localized gas-flow optimization and recirculation can partly offset demand from additional printing capacity.
Process-specific mixtures are creating a premium layer of the market. Linde's ADDvance Laser230 combines argon and helium to improve the process atmosphere in selected laser powder bed fusion applications. Linde reports improvements in redeposition, porosity and productivity for specified alloy and parameter configurations. The financial value for a customer is not simply the price of the gas mixture, but the extent to which more consistent builds reduce rework or qualification risk. Specialty blends must nevertheless be evaluated application by application, because a benefit demonstrated for one alloy or machine recipe cannot automatically be transferred to another. Suppliers with application engineering and metallurgical testing capabilities can compete on qualified process outcomes rather than commodity delivery alone.
3D Printing Gases Market Growth Drivers
Serial metal-part production is enlarging the recurring addressable gas base. In June 2026, EOS announced an agreement for Beehive Industries to receive 30 EOS M4 ONYX systems over the following year, taking Beehive's total to 50 EOS metal AM machines. A separate June 2026 announcement described Incodema3D's purchase of five systems and an agreement for nine additional printers. Such capacity decisions demonstrate how a single qualified manufacturing program can translate into multiple recurring gas-consuming production lines. Actual gas revenues, however, arise as machines become operational and their utilization increases; announced machine orders should not be treated as an immediate one-for-one increase in gas sales.
Atmosphere stability is a quality-control requirement in high-value alloys. Air Products identifies oxygen intrusion and insufficiently controlled protective-gas flow as causes of oxidation, porosity, powder degradation and reduced powder recyclability. For aerospace or medical components, these effects can extend beyond material waste because an inconsistent build may require inspection, repeat manufacturing or further validation. The procurement decision is consequently influenced by purity consistency, traceable supply and monitoring performance in addition to cost per cubic meter. High-purity argon retains an important role where nitrogen exposure may be unsuitable for the alloy or metallurgical specification.
A broader range of delivery modes is improving the economics of production-scale facilities. Cylinder supply is convenient for intermittent demand and geographically dispersed users but tends to carry higher delivered costs per cubic meter. Regularly operating print farms can justify microbulk or liquid merchant supply, while sufficiently concentrated demand may favor contracted on-site or managed gas arrangements. Linde and Airgas both offer additive-manufacturing customers multiple supply modes, including packaged gases, bulk logistics and monitored supply. The commercial transition is important because revenue can shift between distribution channels without the same percentage change in physical gas consumption. Suppliers able to consolidate deliveries and provide uninterrupted supply stand to benefit as qualified manufacturing programs scale.
3D Printing Gases Market Restraints
Gas-efficient printing equipment limits the growth of purchases per installation. Chamber evacuation, improved sealing, optimized purging and lower make-up flow reduce consumption without reducing the quantity of printed metal parts. A 2024 study of powder bed fusion shielding-gas delivery also showed the engineering opportunity to localize and homogenize protective-gas flow. As users pursue lower total cost per component, capital investment in process-gas management can moderate purchased volumes. Forecasts based solely on the number of laser powder bed fusion machines therefore risk overstating long-term gas revenue unless they incorporate gradual improvements in gas-use efficiency.
Pricing and operating patterns vary considerably by region and delivery contract. An Indian industrial-gas supplier publishes indicative argon quotations of INR 220–250 per normal cubic meter, while North American packaged-gas price references can be substantially higher on a volume-equivalent basis. These are different delivery and purity situations, not directly comparable globally traded prices. A single quoted cylinder price cannot represent a liquid-gas contract, and a process-gas supplier's revenue may contain service or rental elements that require separation from the gas itself. These differences introduce uncertainty into a global average realized price and make country-level supplier interviews particularly valuable.
Not every additive-manufacturing method requires meaningful process-gas expenditure. Many stereolithography, conventional material-extrusion and PolyJet operations do not use dedicated industrial shielding gases during the printing stage. Electron-beam processes operate under a vacuum and may use small amounts of helium rather than conventional continuous argon flow. Likewise, the relative suitability of nitrogen and argon depends on metal chemistry and validated part requirements. Treating all additive manufacturing equipment as a uniform gas-consuming installed base would substantially distort demand, competitive positioning and future procurement opportunities.
3D Printing Gases Market Segment Analysis
By Gas: Argon
Argon is the leading gas category in the 3D printing gases market because it offers a stable inert environment across a broad range of reactive metals and industrial alloys. Its purchasing significance is especially pronounced in titanium, aluminum, nickel-based superalloys and other applications where uncontrolled oxygen or nitrogen pickup could change part properties. The gas is used both to establish a protective print-chamber atmosphere and to maintain it as a build progresses, with requirements varying across machine size, purge strategy, powder characteristics and process parameters. Argon also contributes to shielding in selected directed energy deposition and wire-arc processes.
The gas represents an estimated US$104.95 million of market revenue in 2026 in the new bottom-up forecast. This is a modeled value based on the number of active qualifying production lines, their operating hours, gas consumption during printing and purging, gas mix, and delivered supply prices. Its economic significance extends beyond its share of the shielding-gas bill. Customers qualifying aerospace or medical components may be unwilling to substitute a lower-cost gas if a material or validated build procedure specifies argon, because requalification can cost more than the annual gas saving. The result is a relatively resilient demand base in applications where the atmosphere forms part of the approved manufacturing process.
The relationship between gas purity and part quality is not linear, however. Oxygen control, moisture, particulates and flow distribution may determine whether an additional purity premium is economically justified. Renishaw reports a machine approach that establishes a highly controlled environment through evacuation and argon refill; Linde offers process monitoring intended to measure oxygen and moisture and maintain stable PBF-LB atmospheres. These examples illustrate why the competitive offer is evolving from delivery of a commodity gas toward integrated atmospheric control. For a gas supplier, instrumented delivery and process support can improve customer retention, even where consumption per component declines.
Supply configuration becomes more important as individual facilities accumulate printers. A workshop running several machines irregularly may prefer cylinders because fixed storage and infrastructure costs outweigh the unit-price advantage of liquid supply. A multi-machine production site operating throughout the week faces a different trade-off: cylinder changes, delivery frequency and stockout risk can interrupt expensive equipment, making bulk or microbulk arrangements more attractive. Suppliers must assess both annual gas volume and peak-demand reliability. Even an efficient machine may require high instantaneous gas flow during purging, making storage sizing and pressure control relevant to the overall delivered solution.
For laser powder bed fusion, the gas-consumption range is wide. Renishaw reports an AM250 replenishment requirement below 30 liters per hour, while an EOS M290 research model specifies approximately 266 liters per hour after chamber flooding. These published references do not establish a fleet-wide average; larger platforms and different process recipes introduce further variation. As a result, argon revenue forecasts must be based on machine-family mix rather than a single headline growth rate for metal 3D printing. This is particularly important when high-throughput systems replace smaller machines: the value of printed output can increase faster than the gas volume required per dollar of production.
Alternative gas mixtures provide the other direction of product development. Linde's argon–helium Laser230 offering is intended to improve fume and spatter behavior in selected alloy and printing conditions. Where a mixture reduces defect rates or increases productive throughput, a customer may accept a higher price per cubic meter despite attempts to reduce total gas usage. The supplier captures part of the value through application-specific formulations and process support, rather than simply greater argon tonnage. For buyers, the relevant comparison is therefore the gas cost per accepted and qualified component, not the lowest available argon quotation.
Other Gas Segments
Nitrogen remains a lower-cost option for suitable alloys and processes, particularly where users can maintain the required atmosphere without the metallurgical risks associated with nitrogen-sensitive materials. Its estimated market revenue grows from US$14.15 million in 2026 to US$25.88 million by 2032. Specialty gas mixtures are projected to record a 12.93% CAGR across the forecast period, supported by application-specific argon–helium and sintering-atmosphere solutions. Their faster growth does not imply that mixtures can replace pure argon across all alloys; qualification and safety constraints remain central.
By Technology
Laser powder bed fusion forms the largest application for purchased printing-process gases because of its sizeable installed metal-printing fleet and widespread reliance on controlled chamber atmospheres. The segment is forecast to account for US$86.10 million in 2026. Directed energy deposition, including wire-arc additive manufacturing, relies on shielding around an exposed melt pool and requires gas volumes that depend on torch configuration, deposition rate and the extent of local or enclosure-based protection. This segment is projected to expand at a 13.18% CAGR, reflecting a combination of installed line growth, increasing utilization and gas-intensive operating configurations. Gas-assisted debinding and sintering associated with binder jetting and bound-metal extrusion is a smaller but growing application, with demand centered on qualified furnace atmosphere control rather than the polymer-binder deposition stage itself.
By Supply Mode and End Use
Cylinder and packaged gas distribution is estimated to represent US$90.00 million in 2026, particularly because of the number of dispersed small and medium metal-printing installations. Merchant bulk and microbulk services are projected to increase as production clusters expand and users prioritize lower handling costs and fewer interruptions. Managed on-site supply is forecast to grow at an 18.2% CAGR from a smaller base, although such contracts require sufficient throughput to justify the supply infrastructure. Aerospace and defense is the largest end-use industry in the model at US$56.06 million in 2026, reflecting demanding alloy and part-qualification requirements, while automotive, medical and general industrial applications provide different utilization and material-mix profiles.
3D Printing Gases Market Geographical Outlook
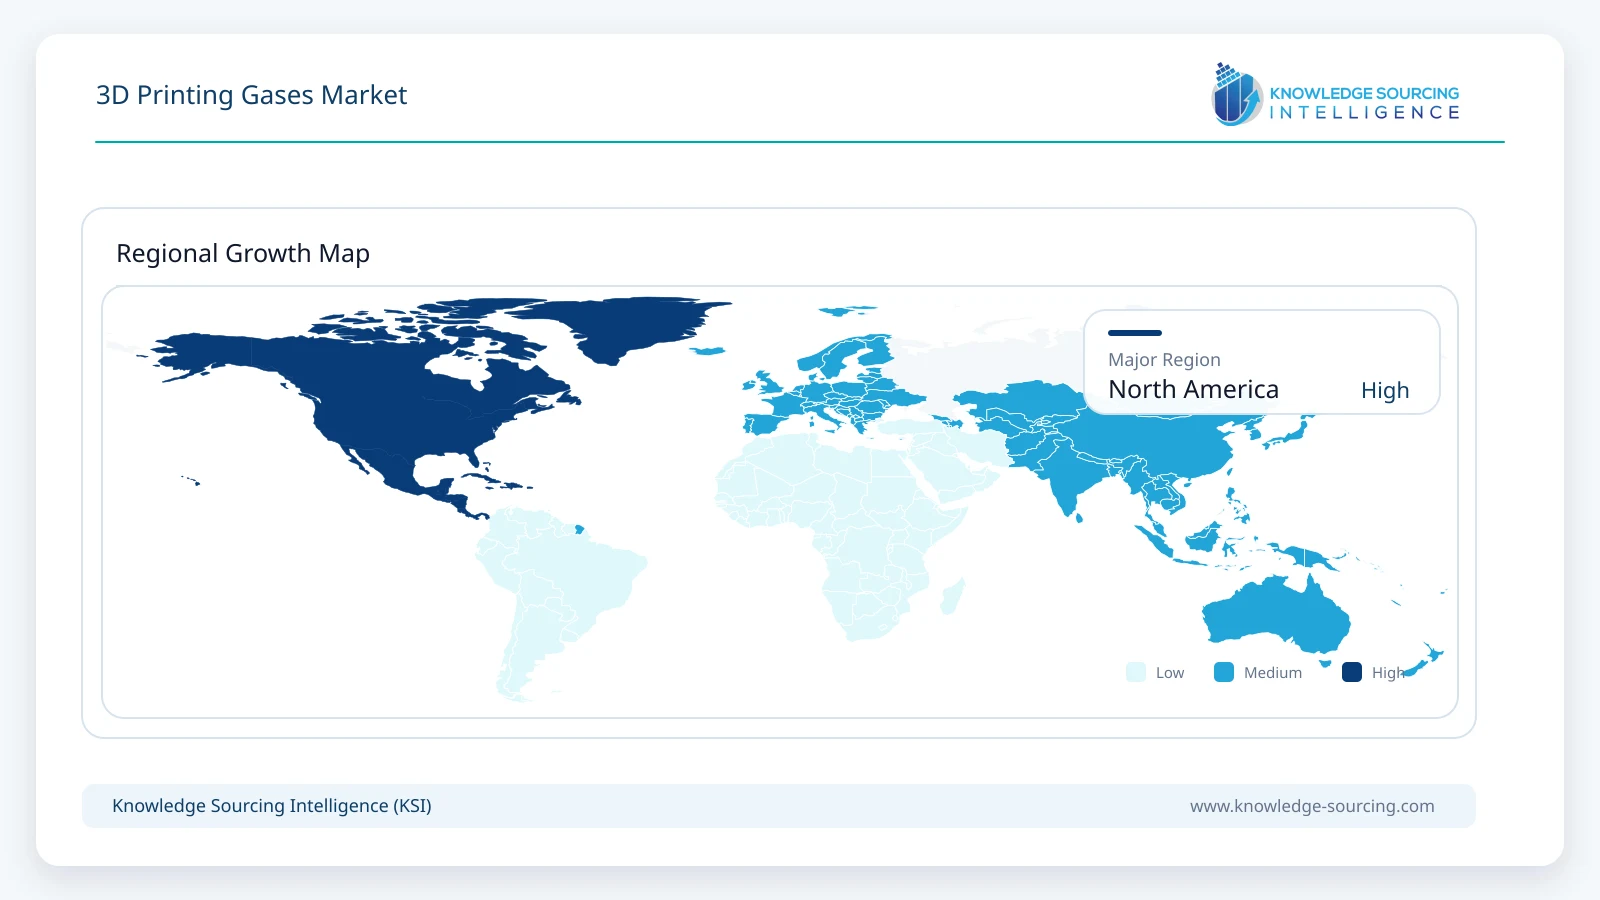
North America is estimated at US$48.80 million in 2026, supported by a substantial installed base of industrial metal additive-manufacturing equipment and production programs in aerospace, defense, energy and specialist manufacturing. The region's demand is strengthened by the transition from design-validation work toward repeatable qualified output, but realized gas spending remains sensitive to the share of equipment operating at production utilization rather than sitting idle. EOS's June 2026 announcements regarding Beehive Industries and Incodema3D illustrate concentrated investments that may support future recurring process-gas demand once equipment is installed and qualified.
Asia Pacific is expected to expand faster than Europe in the central model, supported by additional metal-printing capacity and industrial applications in China, Japan, India and other regional manufacturing centers. The region is forecast to reach US$91.56 million by 2032. Its revenue potential is moderated by a different delivered gas-price mix and the adoption of bulk supplies in high-volume industrial clusters. Europe continues to benefit from aerospace production, advanced manufacturing and established industrial-gas distribution networks, while South America and the Middle East and Africa represent smaller opportunities associated with selective industrial capacity development. Regional demand should therefore be evaluated using both equipment deployment and prevailing gas procurement arrangements rather than manufacturing output alone.
3D Printing Gases Market Competitive Landscape
Competition primarily involves industrial and specialty gas suppliers with the purification, logistics and process engineering capabilities to support demanding metal additive-manufacturing operations. Linde and Air Liquide, including its Airgas business, market dedicated additive-manufacturing gas solutions; Air Products and Messer likewise serve protective-atmosphere applications. SIAD specifies high-purity argon, nitrogen and helium for different metal AM processes. Other relevant supply organizations include Nippon Sanso Holdings and its Matheson operations, Air Water, SOL Group, INOX Air Products and regional industrial-gas distributors. Supplier differentiation rests on gas purity, material-specific recommendations, technical service, supply security and the ability to migrate customers from cylinders to high-volume delivery modes. Separate subsidiaries or legacy brands should not be counted as independent corporate groups in competitive share analysis.
Recent Developments
October 22, 2026: EOS announced Evology Manufacturing's acquisition of an M 400-4 metal AM system, expanding its EOS fleet to ten machines across metal and polymer technologies.
September 23, 2026: EOS appointed Axiomatek as its distribution partner in Mexico for industrial metal and polymer laser powder bed fusion solutions.
September 2, 2026: Nikon announced additional Japanese Space Strategy Fund support for developing and evaluating large metal additively manufactured rocket components.
July 7, 2026: EOS and Constellium announced a partnership to expand industrial aluminum alloy offerings for additive manufacturing.
June 17, 2026: EOS announced Beehive Industries' planned acquisition of 30 EOS M4 ONYX systems for U.S. propulsion-system production.
3D Printing Gases Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 147.6 million |
| Total Market Size in 2032 | USD 275.6 million |
| Forecast Unit | Million |
| Growth Rate | 11.0% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Gas, Technology, Supply Mode, End-Use Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Gas
Argon
Nitrogen
Specialty Gas Mixtures, Including Helium- and Hydrogen-Containing Mixtures
By Technology
Laser Powder Bed Fusion
Directed Energy Deposition / Wire-Arc Additive Manufacturing
Gas-Assisted Debinding and Sintering
By Supply Mode
Cylinders and Packaged Gases
Merchant Bulk and Microbulk Supply
On-Site Generation and Managed Gas Supply
By End-Use Industry
Aerospace and Defense
Medical and Dental
Automotive and Transportation
Industrial Manufacturing, Energy and Research
By Geography
North America
United States
Canada
Mexico
Europe
Germany
France
United Kingdom
Italy
Others
Asia Pacific
China
Japan
India
South Korea
Others
South America
Brazil
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. RESEARCH SCOPE AND METHODOLOGY
3. 3D PRINTING GASES MARKET OVERVIEW
3.1. Market Size and Forecast, 2026–2032
3.2. Metal AM Installed Base and Utilization
3.3. Fresh-Gas Consumption, Purging and Recovery
3.4. Gas Pricing, Purity and Delivery Economics
3.5. Value Chain and Market Structure
4. MARKET DYNAMICS
4.1. Drivers
4.1.1. Serial Production of Qualified Metal Parts
4.1.2. Demand for Controlled Atmosphere and Process Yield
4.1.3. Expansion of DED and Wire-Arc Applications
4.1.4. Shift from Cylinder to Bulk Supply at Production Sites
4.1.5. Specialty Gas Mixtures and Process Optimization
4.2. Restraints
4.2.1. Lower Gas Use from Chamber Recirculation and Purge Optimization
4.2.2. High-Purity Gas Pricing and Logistics Variability
4.2.3. Technology- and Alloy-Specific Gas Restrictions
4.2.4. Low Utilization in Nonproduction Printer Installations
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
5. PROCESS AND TECHNOLOGY LANDSCAPE
6. 3D PRINTING GASES MARKET ANALYSIS BY GAS
6.1. Introduction
6.2. Argon
6.3. Nitrogen
6.4. Specialty Gas Mixtures, Including Helium- and Hydrogen-Containing Mixtures
7. 3D PRINTING GASES MARKET ANALYSIS BY TECHNOLOGY
7.1. Introduction
7.2. Laser Powder Bed Fusion
7.3. Directed Energy Deposition / Wire-Arc Additive Manufacturing
7.4. Gas-Assisted Debinding and Sintering
8. 3D PRINTING GASES MARKET ANALYSIS BY SUPPLY MODE
8.1. Introduction
8.2. Cylinders and Packaged Gases
8.3. Merchant Bulk and Microbulk Supply
8.4. On-Site Generation and Managed Gas Supply
9. 3D PRINTING GASES MARKET ANALYSIS BY END-USE INDUSTRY
9.1. Introduction
9.2. Aerospace and Defense
9.3. Medical and Dental
9.4. Automotive and Transportation
9.5. Industrial Manufacturing, Energy and Research
10. 3D PRINTING GASES MARKET ANALYSIS BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. Europe
10.3.1. Germany
10.3.2. France
10.3.3. United Kingdom
10.3.4. Italy
10.3.5. Others
10.4. Asia Pacific
10.4.1. China
10.4.2. Japan
10.4.3. India
10.4.4. South Korea
10.4.5. Others
10.5. South America
10.5.1. Brazil
10.5.2. Others
10.6. Middle East and Africa
10.6.1. Saudi Arabia
10.6.2. United Arab Emirates
10.6.3. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Company Strategy and Competitive Positioning
11.2. Gas Purity, Mixture and Delivery-Mode Comparison
11.3. Partnerships, Investments and Capacity Expansion
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Linde plc
12.2. Air Liquide S.A. (Including Airgas)
12.3. Air Products and Chemicals, Inc.
12.4. Messer SE & Co. KGaA
12.5. Nippon Sanso Holdings Corporation (Including Matheson)
12.6. SIAD S.p.A.
12.7. SOL S.p.A.
12.8. Air Water Inc.
12.9. INOX Air Products Limited
12.10. Iwatani Corporation
12.11. Gulf Cryo
12.12. Yingde Gases Group
13. APPENDIX
13.1. Currency and Units
13.2. Market Definition and Forecast Timeline
13.3. Bottom-Up Model and Sensitivity
13.4. Research Methodology
13.5. Abbreviations





Frequently asked questions
What is the 3D printing gases market size in 2026?
The 3D Printing Gases Market is estimated at USD 147.6 million in 2026.
What is the projected market value by 2032?
The 3D Printing Gases Market is projected to reach USD 275.6 million by 2032.
What is the forecast CAGR for 3D printing gases?
The 3D Printing Gases Market is forecast to grow at an 11.0% CAGR through 2032.
Which gas dominates the 3D printing gas market?
Argon is estimated to account for 71.1% of global revenue in 2026.
What are the key drivers for 3D printing gas demand?
Demand reflects the active production fleet and qualified metal-part production economics.
Which additive manufacturing processes consume these gases?
Processes include powder bed fusion, DED, WAAM, and gas-assisted debinding/sintering.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). 3D Printing Gases Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/3d-printing-gases-market