
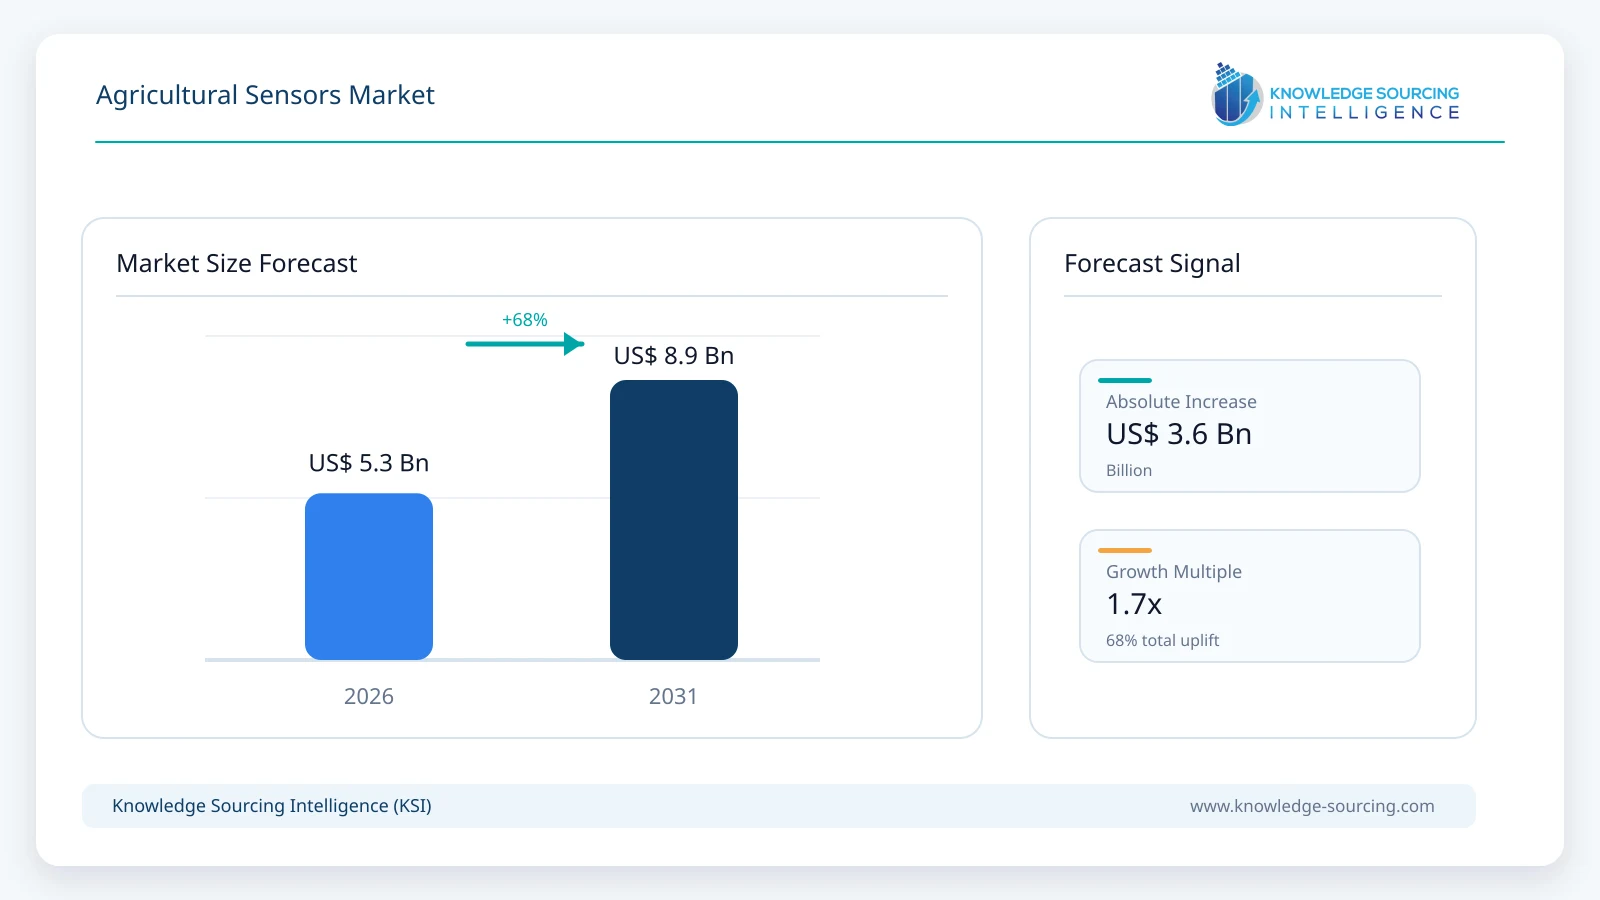
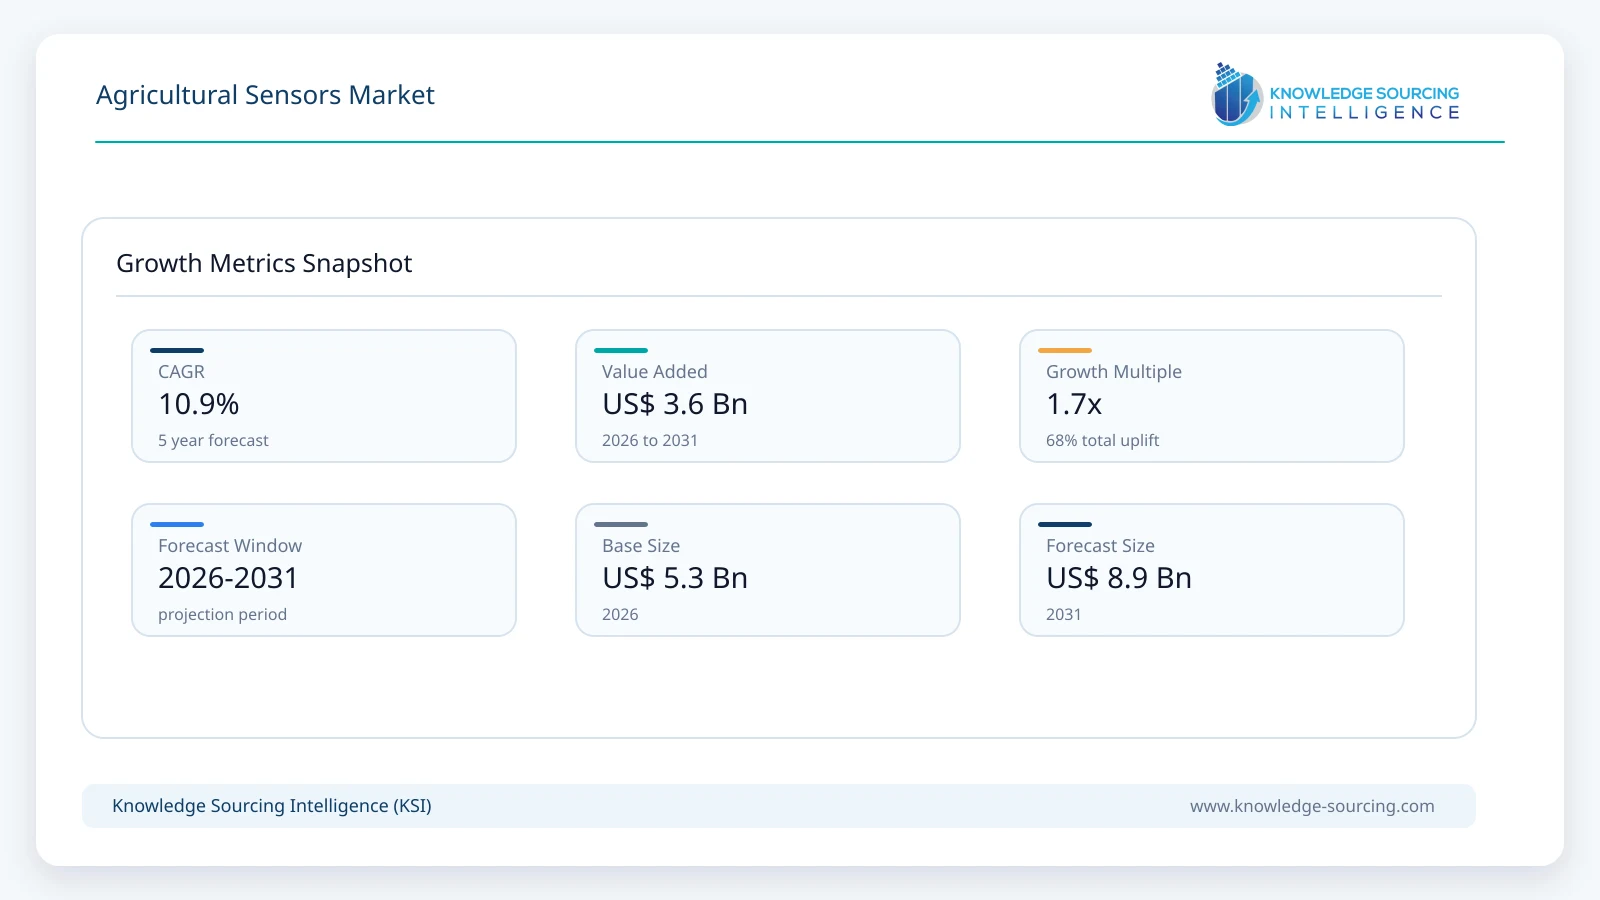
The Agricultural Sensors Market is projected to grow at a CAGR of 10.9%, reaching USD 8.9 billion in 2031 from USD 5.3 billion in 2026.
Highlights:
- 1Soil sensors represent an estimated 23% of 2026 market value, reflecting demand for root-zone monitoring across irrigation-intensive crop systems.
- 2Water management is a large application pool because accurate measurements can influence pumping energy, irrigation timing and water-use efficiency.
- 3Hardware represents approximately 65% of 2026 value, while connected analytics and installation support gain importance as monitoring networks become more complex.
- 4Optical crop sensing increasingly informs targeted field operations, although camera performance must be judged against crop-specific detection accuracy.
- 5North America remains the leading regional market, while Asia Pacific is expanding more rapidly as monitoring spreads into irrigated farming and high-value horticulture.
- 6Platform integration and field service influence purchasing as much as sensor sensitivity, particularly for multi-location agricultural operators.
Agricultural sensing systems provide measurements of soil water, salinity, local weather, crop condition and livestock activity that can be acted on during routine farm operations. The commercial product may be a single soil probe, an instrument network, a field-imaging sensor or a complete monitoring package with directly related analytics and support. Sensor-linked software, calibration and site-specific services complement device sales. Standalone farm-management products without sensing content and the full value of agricultural machinery are not included.
Growers increasingly compare monitoring equipment by the decisions it helps them make, the reliability of readings and the cost of sustaining an installation over several seasons. Farms with multiple irrigation zones may require deeper soil profiles and continuous data, whereas a dairy operation needs wearables and monitoring algorithms suited to animal behaviour. Hardware specifications remain relevant, but suppliers have to provide practical interfaces with the irrigation controllers, farm software or advisory services already used by the customer.
Market Overview
CropX introduced its Apex instrument in April 2026 with readings at four-inch intervals through the measured root profile. Moisture, soil temperature and electrical conductivity are presented within the same digital agronomy platform. The product illustrates the practical shift from a single averaged soil value to a profile that can distinguish a wet surface from a drying root zone. For an irrigated orchard, that distinction may change the timing or length of the next watering cycle. Whether it changes expenditure depends on reliable placement and an irrigation system that the grower can adjust.
Farm conditions frequently expose the limits of generalized recommendations. Two fields receiving the same rainfall can have materially different infiltration, drainage and salinity profiles. A canopy image can reveal crop stress but cannot by itself identify whether poor water availability, disease or nutrient loss is responsible. Instrument combinations are therefore valuable when they narrow the causes of a problem, not simply when they increase the volume of readings. Arable, for example, offers an integrated field station with weather, crop imagery and plant measurements, with optional soil and irrigation inputs.
The market includes inexpensive standalone instruments and more complex deployments extending across multiple irrigation blocks. In lower-value crops, probe density and cellular subscriptions can overwhelm the benefit from tighter scheduling. In high-value permanent crops, relatively small changes in fruit quality, crop loss or water productivity may justify a larger deployment. Suppliers serving both groups must offer different price and support models rather than relying on a single universal configuration.
Market Trends
Root-Zone Profiles Replace Single-Depth Readings
Apex from CropX, METER Group’s TEROS 54 and established profile-probe systems from Sentek illustrate sustained demand for readings through several soil layers. Water applied at the surface does not necessarily reach the active roots, particularly where infiltration is uneven or salinity constrains uptake. Growers use depth profiles to distinguish a short irrigation pulse from a deeper recharge and to recognize drainage below the useful root zone. Installation remains consequential: poorly seated probes or an unrepresentative field position can create an apparently precise but misleading recommendation.
Depth-resolved monitoring has commercial value beyond selling a higher-priced probe. It lets irrigation advisers explain the consequence of their scheduling decisions and may reduce arguments about whether a field was overwatered or an irrigation event failed. The strongest demand comes where fields have heterogeneous soils or where a prolonged water deficit damages quality before visible wilting appears.
Computer Vision Moves from Scouting into Equipment Control
John Deere’s May 2026 See & Spray Gen 2 enhancements combine boom-mounted cameras and machine learning with crop-specific weed discrimination. The immediate use is selective herbicide delivery rather than passive image collection. Deere also added crop compatibility and biomass-informed variable-rate functions. Imaging suppliers selling to machinery manufacturers consequently compete on both camera reliability and the precision of the overall field operation.
Separate imaging providers still compete where farms need stand counts, crop-vigor maps or scouting records without replacing a sprayer. Sentera, acquired by Deere in 2025, illustrates the strategic value of bringing aerial imagery closer to farm-operation software. Optical sensing competes on detection reliability, image processing and agronomic interpretation; sensor resolution by itself is an incomplete measure of field value.
Field Measurements Are Feeding Agronomy Workflows
The August 2026 acquisition of SCIO extends CropX’s measurement portfolio into near-infrared assessment of crop quality and composition. CropX is combining those results with its existing soil, crop and weather records, making it possible to compare agronomic decisions with outcomes later in the production cycle. Reinke’s earlier integration of CropX information into ReinCloud 3 also shows how irrigation-equipment channels can make monitoring information accessible at the point where water applications are scheduled.
Integrated accounts can generate recurring software receipts, but data ownership and portability matter. An agricultural retailer operating several irrigation brands may favor a platform that accepts third-party readings. Proprietary data structures can protect a vendor’s installed base while raising the eventual cost of conversion for the customer.
Durability and Communications Shape Ownership Costs
Field instruments work in wet soil, saline conditions, heat, mechanical vibration and locations with limited power or cellular coverage. A failed node during the critical irrigation period may be more expensive than the annual software fee. Arable emphasizes a solar-powered, cellular field station; Soil Scout sells buried wireless instruments for subsurface measurements; specialist suppliers offer both direct-read and cloud-connected configurations. These are not interchangeable installations.
Buyers increasingly examine calibration drift, battery life, available telemetry, replacement procedures and the number of technician visits required each season. Providers that make maintenance predictable have an advantage in geographically dispersed farms, even if the instrument itself carries a higher initial price.
Sensor Data Extends into Contract and Research Programs
CropX joined the Lincoln University and McCain Foods NextGen Regenerative Farm initiative in October 2026 to provide soil, evapotranspiration and weather monitoring. Such programs require comparable measurements through multiple seasons because researchers and buyers evaluate farming practices, not only immediate irrigation events. Instrument providers must document sensor placement, accuracy and the continuity of field records if those measurements are intended for research or supply-chain reporting.
This channel supports installations with a longer analytical life, though a pilot or research collaboration does not automatically imply large commercial volumes. Procurement can remain limited until a buyer demonstrates that the collected data improves its primary operational or compliance objective.
Segment Analysis
By Type: Soil Sensor
Soil sensors are the leading product group, with continuing demand for measurements of root-zone water, temperature and electrical conductivity in fields where irrigation or fertilizer scheduling can change within days. A capacitance probe and a water-potential instrument answer different agronomic questions: volumetric readings indicate how much water occupies a measured soil volume, while water potential indicates how difficult that water is for roots to extract. Crop type, rooting depth and soil heterogeneity determine the appropriate instrument, so purchasing rarely turns on the number of reported parameters alone.
With a forecast revenue pool of approximately USD 2.14 billion by 2031, this segment benefits from improved multi-depth monitoring and easier integration with irrigation platforms. CropX Apex, METER TEROS and Acclima equipment represent different approaches to sensor deployment and measurement quality. Orchards and irrigated crops offer attractive repeat business where calibration and local service can be delivered consistently; the complete value of the pump or irrigation machinery is not part of sensor sales.
By Application: Water Management
Water management is estimated to grow by approximately 12.2% annually between 2026 and 2031 as growers use soil moisture and actual evapotranspiration measurements to refine irrigation scheduling. This is a particularly direct application of field sensing: the readings can affect a scheduled irrigation event, applied water and electricity expense. Higher-value crop producers have the strongest incentive to maintain instruments through the season, although the benefit differs sharply between areas with full pump control and districts using fixed irrigation turns.
Reinke’s integration with CropX reflects the importance of making monitoring output visible beside existing irrigation controls. Commercial implementation still requires sensible sensor spacing and familiarity with soil variability: one correctly placed probe may be more informative than multiple badly installed devices. Service providers that combine measurements with practical local advice can win business where growers lack time to interpret changes in moisture profiles or rainfall forecasts themselves.
By Offering: Hardware
Field hardware remains the principal revenue-bearing offering because soil probes, weather instruments, plant cameras and livestock monitoring devices must be installed before their measurements can be sold or analysed. Connected units add telemetry, power management and protection against wet soil, dust or mechanical damage. Customers frequently rely on irrigation dealers and regional agronomists for installation and replacement; vendors with robust instrument construction and open interfaces therefore compete on lifetime maintenance expenditure rather than acquisition price alone.
Hardware is projected to reach about USD 5.07 billion by 2031, even as software and related services take a larger share of spending. Open-protocol specialists such as Acclima can fit mixed monitoring networks, whereas integrated suppliers such as CropX and Arable package sensors with recurring data workflows. Neither model is uniformly better: the choice depends on whether a farm values system flexibility, direct agronomy support or a single accountable supplier for the complete installation.
Market Drivers
Water Productivity and Energy Costs
Irrigation decisions affect water bills, pump electricity or diesel use and the probability of crop-quality losses. Sensor-led scheduling is compelling where growers can vary irrigation duration and capture the savings. A root-zone profile that exposes drainage below the crop’s active roots can be more useful than a weather forecast alone. The opportunity is concentrated in high-value horticulture, orchards and irrigated row crops, but its size differs greatly between farms. Providers need reliable local agronomic baselines to justify deployment, rather than generalized water-saving promises.
For irrigated orchards and vegetable production, this purchasing case is strongest where a grower can change application duration or frequency after observing a developing deficit. Higher energy tariffs also make avoiding unnecessary pumping more valuable. Suppliers need to connect readings to water movement through the root profile; a sensor that merely reproduces local rainfall data does not justify the same service fee.
Broader Adoption of Precision Farm Operations
USDA Economic Research Service reported in December 2024 that 70% of large U.S. crop-producing farms used guidance autosteering in 2023, illustrating the infrastructure already available for more advanced farm data use. Guidance adoption is not a direct measure of sensor sales, yet it matters because these farms already maintain trained staff, connected equipment and digital field records. Sensor projects become easier to operationalize when farm managers can connect measurements with existing systems and assess results across seasons.
The USDA evidence on larger U.S. farms adopting precision tools more widely is relevant to sensor distribution, but not equivalent to a measured global device penetration rate. Equipment dealers and agronomy advisers can extend sales beyond early adopters when installation procedures are repeatable and monitoring works with existing farm records. In regions with small fragmented holdings, shared monitoring and advisory services may be more economical than individual subscriptions.
Crop Monitoring Between Physical Field Visits
Canopy cameras, in-field weather instruments and wireless soil probes give agronomists more frequent observations across widely distributed farms. CropX Vision, introduced in March 2026 for vineyard water-stress assessment from images, demonstrates how monitoring can support decisions between manual visits. Instruments do not remove the need to inspect pests or verify an unexpected reading. They can, however, direct attention to the blocks where a site visit or treatment is likely to be most valuable, making farm advisory labor more productive.
Portable equipment and remotely accessible records are useful where crop consultants supervise many farms across large areas. Field imagery can identify where scouting should be concentrated, while temperature or moisture alarms indicate that a condition is changing between planned visits. These services have to control false alarms and support local agronomic interpretation or the additional information can simply increase the grower’s workload.
Equipment Makers Embedding Optical Sensing
Crop discrimination and machine-mounted cameras create a new route for agricultural sensors within sprayers and other equipment. Deere’s See & Spray development makes the sensor part of a real-time control loop rather than a separate purchased instrument. That raises the value of dependable detection, processors and software updates, while allowing machinery makers to bundle the sensing function with equipment sales or technology fees. Specialist sensor suppliers may gain component orders but lose direct contact with the grower.
An imaging module embedded in a sprayer is purchased under different terms from a standalone field probe. A supplier may sell cameras and inference hardware to an OEM while the manufacturer charges growers for application software. Customers ultimately evaluate herbicide savings and reliable weed detection, so optical-device revenue grows with demonstrable equipment fitment rather than with every announced machine-learning improvement.
Commercialization of Farm Data Services
Agribusinesses increasingly need consistent agronomic records across supply areas. Connected sensor networks can support irrigation advice, field research and selected traceability programs when measurements are comparable and verifiable. CropX’s October 2026 participation in the McCain-linked research farm is a concrete example of this institutional use. The commercial opportunity lies in reliable collection and defensible interpretation over time; not every data-monitoring project will translate into a large subscription, and service providers must show practical business value.
Service revenue tends to persist when farm data remain comparable after crop rotations, seasonal maintenance and sensor replacements. Long-term records can support irrigation decisions and buyer documentation, but platform operators face pressure to export historical readings in usable formats. A grower locked into expensive hardware changes may postpone renewal even when the software has technically improved.
Market Restraints
Installation Economics on Small Farms
A sensor’s quoted unit price understates the investment required for representative monitoring. Multi-depth placements, telemetry, software fees and a local adviser can multiply the initial hardware outlay. Small or rainfed farms may lack sufficient irrigation flexibility to recover those costs. Systems designed for large irrigated enterprises consequently have a limited addressable market when offered unchanged to fragmented farms. Financing arrangements and shared advisory services can help, but neither guarantees a satisfactory return.
The hurdle is not necessarily the sensor’s unit price. Batteries, telemetry gateways, labour for installing representative stations, annual software fees and advice can make the complete expense considerably higher. Distributor-led packages and shared advisory programs may reduce the burden, while low-value rainfed crops often lack the immediate water-saving case that supports more sophisticated monitoring.
Site Calibration and Unrepresentative Sampling
Soil texture, salinity, stone content and installation contact can alter measurement accuracy. A probe placed in an unrepresentative management zone may generate consistent data without representing the rest of a field. Optical readings face cloud cover, crop-stage and lighting constraints; livestock devices can require animal-specific validation. This uncertainty raises the cost of field trials and agronomic support, particularly when marketing claims are transferred across dissimilar climates or crops without local evidence.
Calibration practices also change with measurement principle. Saline soils can interfere with some dielectric readings, and a probe disturbed by installation may respond differently from the surrounding root zone. Users need access to field-specific checks and procedures for replacing faulty data. Inconsistent measurements are particularly damaging where software converts them automatically into watering recommendations.
Connectivity and Power Reliability
Wireless instruments must operate through foliage, uneven terrain and areas beyond dependable cellular coverage. Batteries, solar panels, base stations and communications subscriptions introduce failure points that growers may not be equipped to diagnose. Off-grid equipment can improve reach, but its cost and maintenance requirements remain relevant. Remote diagnostic tools and local service networks are therefore necessary parts of many commercial offerings rather than optional conveniences.
A cellular subscription cannot improve an installation if the instrument loses power or the signal cannot pass reliably from a buried node to its gateway. Farms with remote pivots and dispersed orchards may require solar supplies, local storage or relay networks. Suppliers that ignore these field requirements can face repeated service calls, eroding margins on deployments that appeared profitable at the point of sale.
Fragmented Platforms and Data Ownership
Agricultural monitoring is sold by irrigation specialists, machinery groups, sensor manufacturers and software providers using different interfaces. A grower may operate several brands of controllers, mapping software and telemetry. Export limitations or proprietary formats make it difficult to compare seasons or switch suppliers. Integration work can delay implementation and erode the benefit of inexpensive instruments. Data-access terms and long-term support commitments often deserve the same scrutiny as sensor specifications.
Farm data often originate from several technology generations, with different timestamps, units and calibration procedures. An agronomic adviser may need to compare readings from weather stations, direct soil probes and field imagery within one seasonal record. Closed interfaces complicate that work; suppliers offering documented exports and reliable application programming interfaces can benefit even without owning the full farm-management platform.
Uncertain Measurement-to-Outcome Attribution
A field trial may show water savings or improved yields, but isolating the sensor’s contribution from weather, crop variety and changes in farm practice is difficult. Purchasers cannot assume that benefits observed in a vineyard translate to broad-acre cereals or livestock units. Contracts based on precise savings claims carry performance risk. Suppliers that avoid inflated promises and document comparable, repeatable outcomes are better positioned for repeat orders, although producing that evidence consumes time and funding.
Attributing a specific yield increase to one instrument is difficult when weather, crop variety, fertilization and irrigation scheduling change together. Farm trials and repeated seasonal evidence can strengthen the buying decision, but suppliers should avoid universal returns-on-investment claims. Buyers are more likely to renew where the monitoring system documents an operational correction they could not have made confidently without the data.
Regional Outlook
North America
North America represents approximately 35% of global Agriculture Sensor Market value in 2026, the largest of the five regional markets. U.S. and Canadian growers have an established base of precision-agriculture dealers, irrigation contractors and advisers to support installed instruments. USDA research shows pronounced differences in precision-technology adoption between farm sizes, so uptake is concentrated in operations with the equipment scale and technical support to maintain reliable monitoring. Crop-scouting providers also benefit from their links to established machinery channels, illustrated by John Deere’s acquisition of Sentera.
Regional market revenue is forecast to approach USD 2.94 billion by 2031, equivalent to an estimated 9.6% annual increase. A farm with older soil probes or an existing weather station is often more interested in compatible new instruments than replacing its entire monitoring environment. That favours suppliers capable of integrating varied devices and providing responsive seasonal support; recurring subscriptions will be harder to sustain if readings do not translate into better scheduling, input use or crop performance.
Asia Pacific
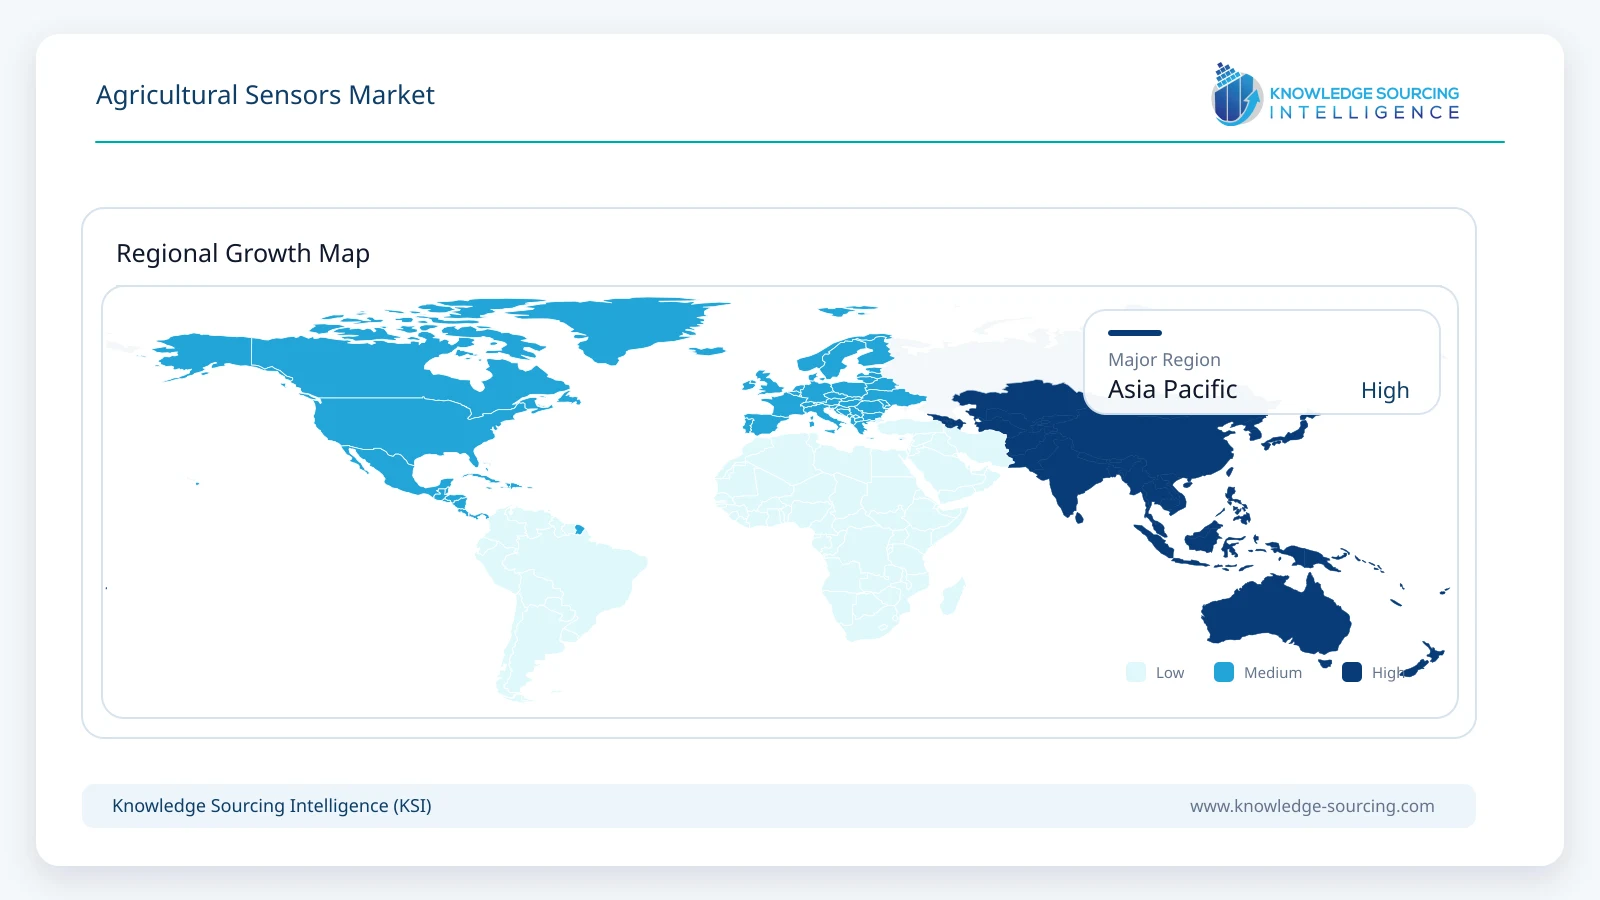
The Asia Pacific agriculture sensor market is projected to expand at approximately 14.0% annually through 2031, making it the fastest-growing region in the forecast. Export horticulture and commercial irrigation in China, India and several Southeast Asian countries provide different entry points from protected cultivation and intensive farming in Japan and South Korea. For larger farms, profile probes and connected field stations can support differentiated management zones; smaller holdings may procure sensing through irrigation companies, producer groups or fee-based agronomy providers.
Asia Pacific revenue is estimated to increase from USD 1.43 billion in 2026 to approximately USD 2.76 billion in 2031, with its share rising from 27% to 31%. This gain is not a uniform change across countries. Hardware affordability, reliable communication networks, language-specific interfaces and access to technical support influence actual purchase decisions. Where farms cannot control the timing of water delivery, monitoring still informs crop management, but the immediate savings case is less direct than in automated irrigation systems.
Competitive Landscape
The competitive field spans instrument specialists, integrated crop-monitoring platforms and equipment manufacturers. METER Group, Acclima, Sentek, Campbell Scientific and Vegetronix compete in measurement hardware and associated logging capabilities; CropX, Arable, Sensoterra and Pessl Instruments pair monitoring products with agronomic or weather-data services. Deere participates through machine sensing and its ownership of Sentera. Livestock sensing follows a different route, including dairy-monitoring businesses such as Afimilk. These companies should not be treated as having identical product coverage.
The distinction between component revenue and application revenue is commercially important. A camera used within a complete sprayer, an agricultural weather station, and a stand-alone buried moisture probe face different purchase approval and replacement cycles. Suppliers with a reliable service network, integration capability and product evidence can preserve pricing power even where basic sensors are becoming more widely available.
Recent Developments
13 October 2026 - CropX joins regenerative research farm: CropX announced that it would provide soil sensing technology to Lincoln University and McCain Foods’ NextGen Regenerative Farm, extending the use of field measurements into a multi-party farm research program.
26 August 2026 - CropX acquires SCIO: CropX announced its acquisition of SCIO to strengthen the connection between agronomic measurement, analytics and operational decisions across the growing cycle.
11 May 2026 - Deere updates machine-mounted sensing: John Deere outlined See & Spray Gen 2 enhancements, including broader crop compatibility and additional biomass-informed application functions; the camera system performs real-time crop-versus-weed discrimination.
7 April 2026 - CropX adds Apex: CropX launched a configurable multi-depth root-zone sensor integrating soil moisture, temperature and electrical conductivity readings into its digital agronomy platform.
24 March 2026 - CropX introduces Vision: CropX launched AI-powered CropX Vision for vineyard water-stress assessment from canopy photographs, broadening its monitoring methods beyond buried field probes.
17 November 2025 - Reinke and CropX deepen integration: Reinke and CropX announced a unified platform integration that makes CropX information available through the ReinCloud 3 environment, reducing the need for separate monitoring interfaces.
Market Outlook
Farm sensor demand through 2031 will depend less on the number of parameters a device can measure than on its ability to support a repeatable decision. Root-zone instruments will retain commercial relevance in irrigation, imaging will extend crop scouting and equipment control, and livestock devices will continue to be judged through distinct herd-management economics. Larger buyers are likely to favor systems that reconcile these data sources without requiring the farm to commit every function to one vendor.
Pricing will remain differentiated. Commodity probes face intense unit-price competition, whereas validated monitoring services can command recurring revenue when local support, data continuity and measurable outcomes are supplied. Integration and after-sales capability are therefore likely to influence supplier selection at least as much as advances in instrument specifications. Investment is expected to concentrate where water availability, farm labor, crop value or buyer documentation creates an identifiable return.
Agricultural Sensors Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.3 billion |
| Total Market Size in 2031 | USD 8.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Offering, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Humidity Sensor
Electrochemical Sensor
Mechanical Sensor
Airflow Sensor
Optical Sensor
Pressure Sensor
Water Sensor
Soil Sensor
Livestock Sensor
Others
By Application
Dairy Management
Soil Management
Climate Management
Water Management
By Offering
Hardware
Software
Services
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Water Productivity and Energy Costs
3.1.2. Broader Adoption of Precision Farm Operations
3.1.3. Crop Monitoring Between Physical Field Visits
3.1.4. Equipment Makers Embedding Optical Sensing
3.1.5. Commercialization of Farm Data Services
3.2. Market Restraints
3.2.1. Installation Economics on Small Farms
3.2.2. Site Calibration and Unrepresentative Sampling
3.2.3. Connectivity and Power Reliability
3.2.4. Fragmented Platforms and Data Ownership
3.2.5. Uncertain Measurement-to-Outcome Attribution
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. AGRICULTURAL SENSORS MARKET BY TYPE
5.1. Introduction
5.2. Humidity Sensor
5.3. Electrochemical Sensor
5.4. Mechanical Sensor
5.5. Airflow Sensor
5.6. Optical Sensor
5.7. Pressure Sensor
5.8. Water Sensor
5.9. Soil Sensor
5.10. Livestock Sensor
5.11. Others
6. AGRICULTURAL SENSORS MARKET BY APPLICATION
6.1. Introduction
6.2. Dairy Management
6.3. Soil Management
6.4. Climate Management
6.5. Water Management
7. AGRICULTURAL SENSORS MARKET BY OFFERING
7.1. Introduction
7.2. Hardware
7.3. Software
7.4. Services
8. AGRICULTURAL SENSORS MARKET BY GEOGRAPHY
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. South Africa
8.5.5. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Indonesia
8.6.8. Australia
8.6.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. CropX Technologies
10.2. Deere & Company (including Sentera)
10.3. METER Group
10.4. Pessl Instruments GmbH
10.5. Campbell Scientific, Inc.
10.6. Acclima, Inc.
10.7. Sentek Technologies
10.8. Arable Labs, Inc.
10.9. Sensoterra
10.10. Vegetronix, Inc.
10.11. Libelium Comunicaciones Distribuidas, S.L.
10.12. Afimilk Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth rate for the Agricultural Sensors Market?
The Agricultural Sensors Market is projected to grow at a 10.9% CAGR from 2026 to 2031.
What is the forecasted market value for agricultural sensors by 2031?
The Agricultural Sensors Market is forecasted to reach USD 8.9 billion by 2031.
Which regional market leads in agricultural sensor adoption?
North America remains the leading regional market.
Which sensor type holds the largest market share in 2026?
Soil sensors represent an estimated 23% of the 2026 market value.
What application drives significant demand for agricultural sensors?
Water management is a large application pool for accurate measurements.
What is the primary component value in the 2026 market?
Hardware represents approximately 65% of the 2026 market value.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Agricultural Sensors Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/agricultural-sensors-market