
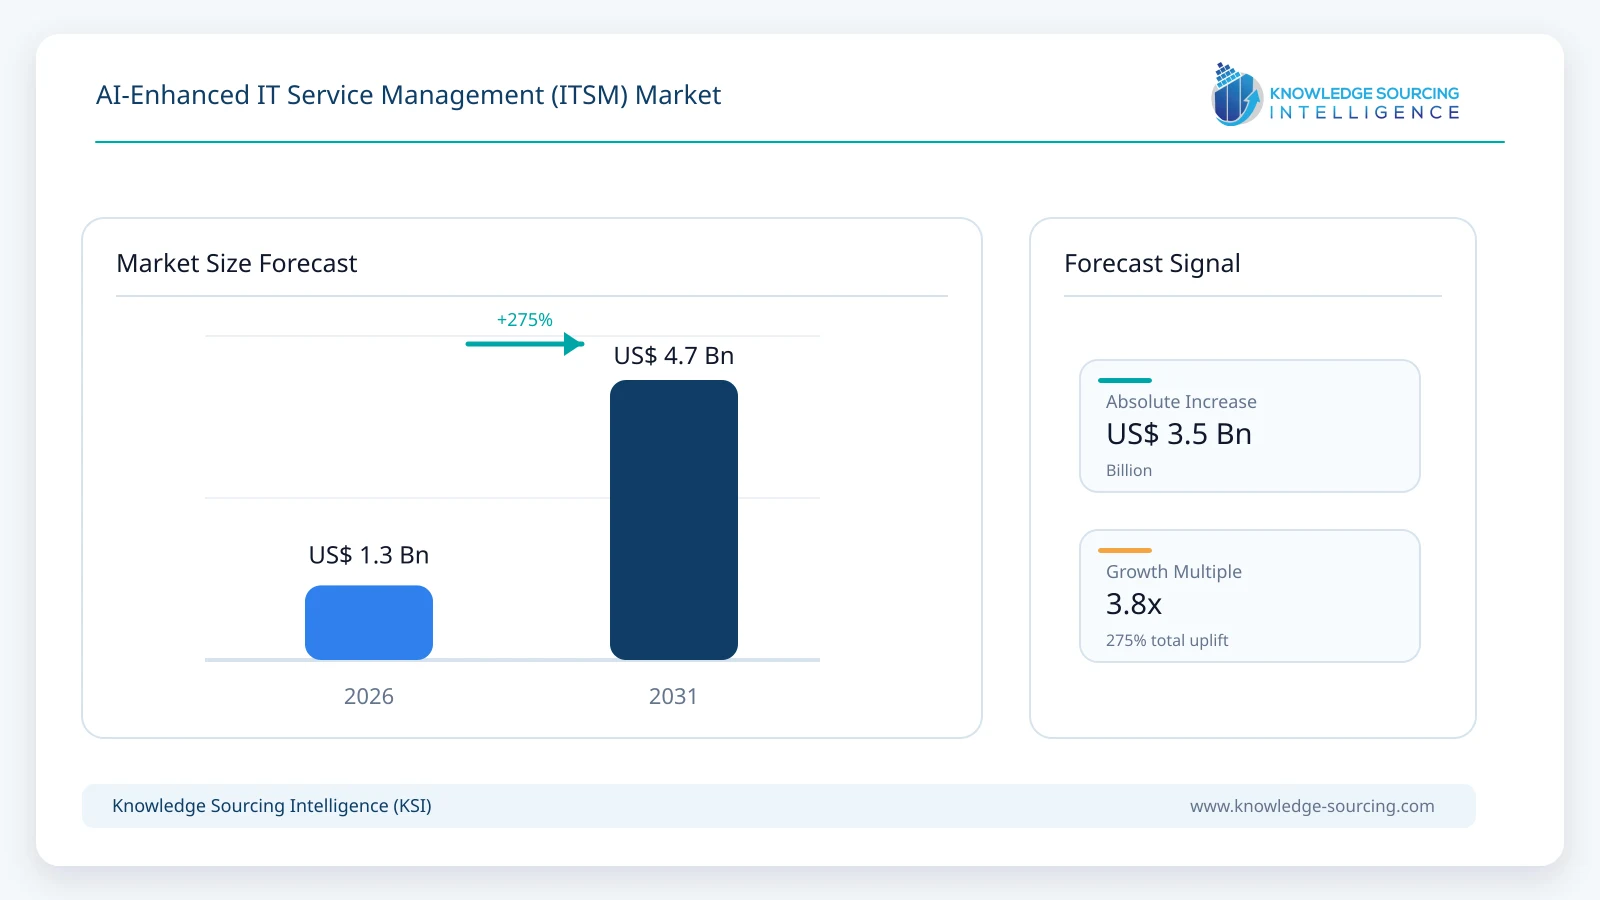
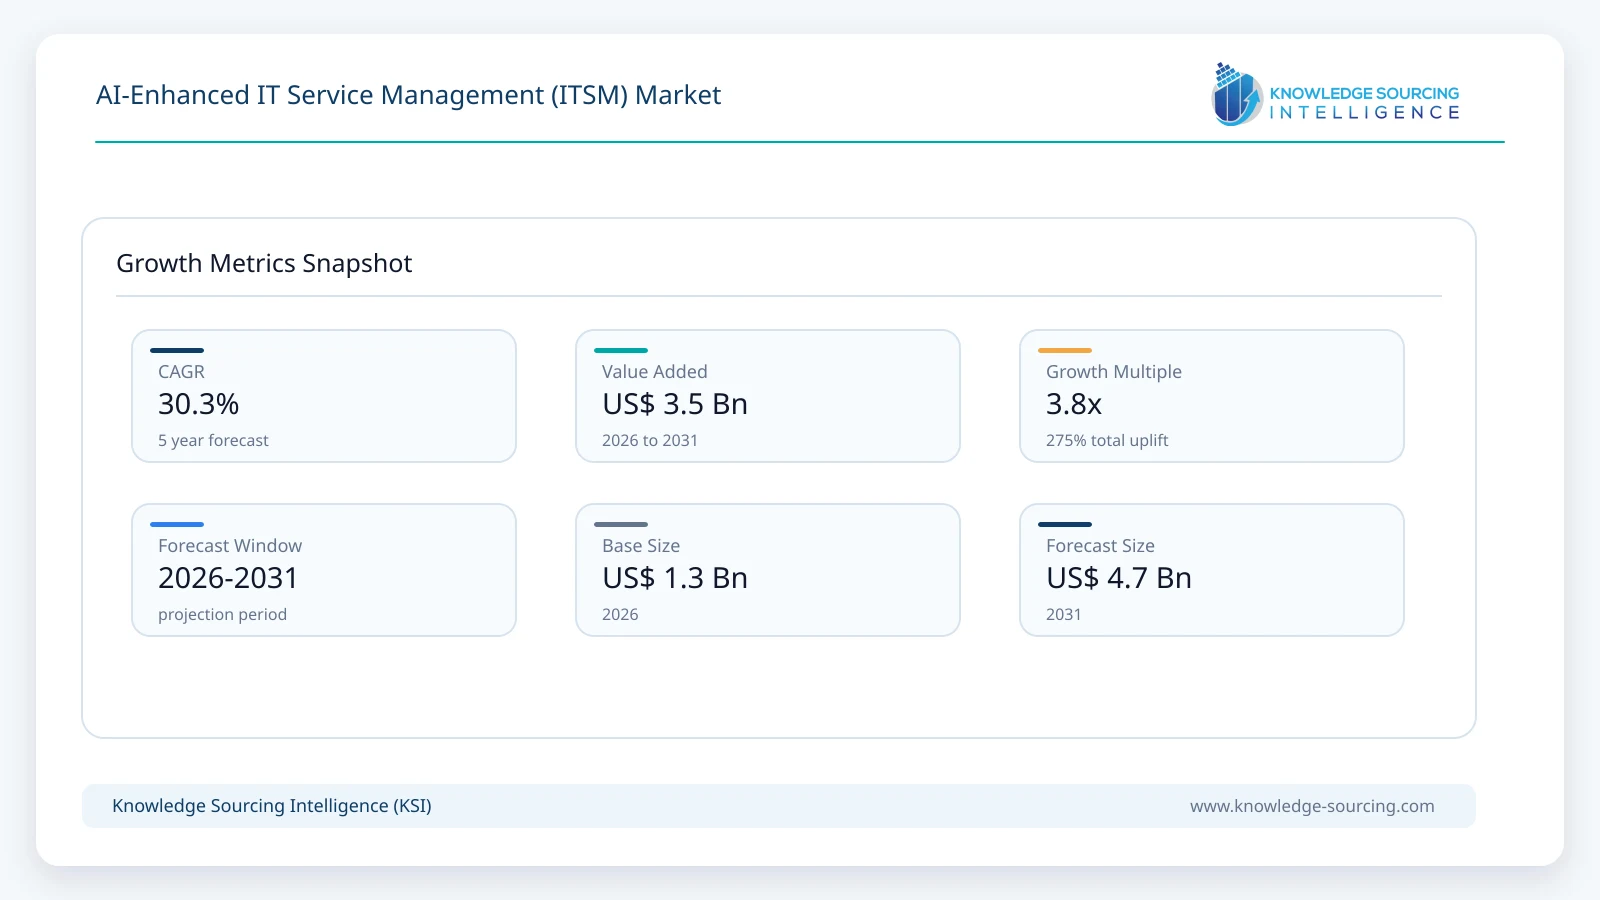
The global AI-Enhanced IT Service Management (ITSM) Market is expected to grow at a CAGR of approximately 30.3%, increasing from USD 1.26 billion in 2026 to USD 4.73 billion in 2031 during the forecast period.
Highlights:
- 1Cloud-based deployments account for an estimated 83% of 2026 value, helped by frequent software releases and hosted AI infrastructure.
- 2Large enterprises contribute approximately 75% of estimated 2026 demand, reflecting service volumes and complex integration requirements.
- 3Incident and problem management represent an estimated 43% of 2026 revenue, with AI increasingly used beyond ticket classification.
- 4IT and telecommunications generate roughly 35% of estimated 2026 demand through service-intensive operating environments.
- 5The shift from AI-assisted responses toward controlled task execution is changing how vendors demonstrate and price successful outcomes.
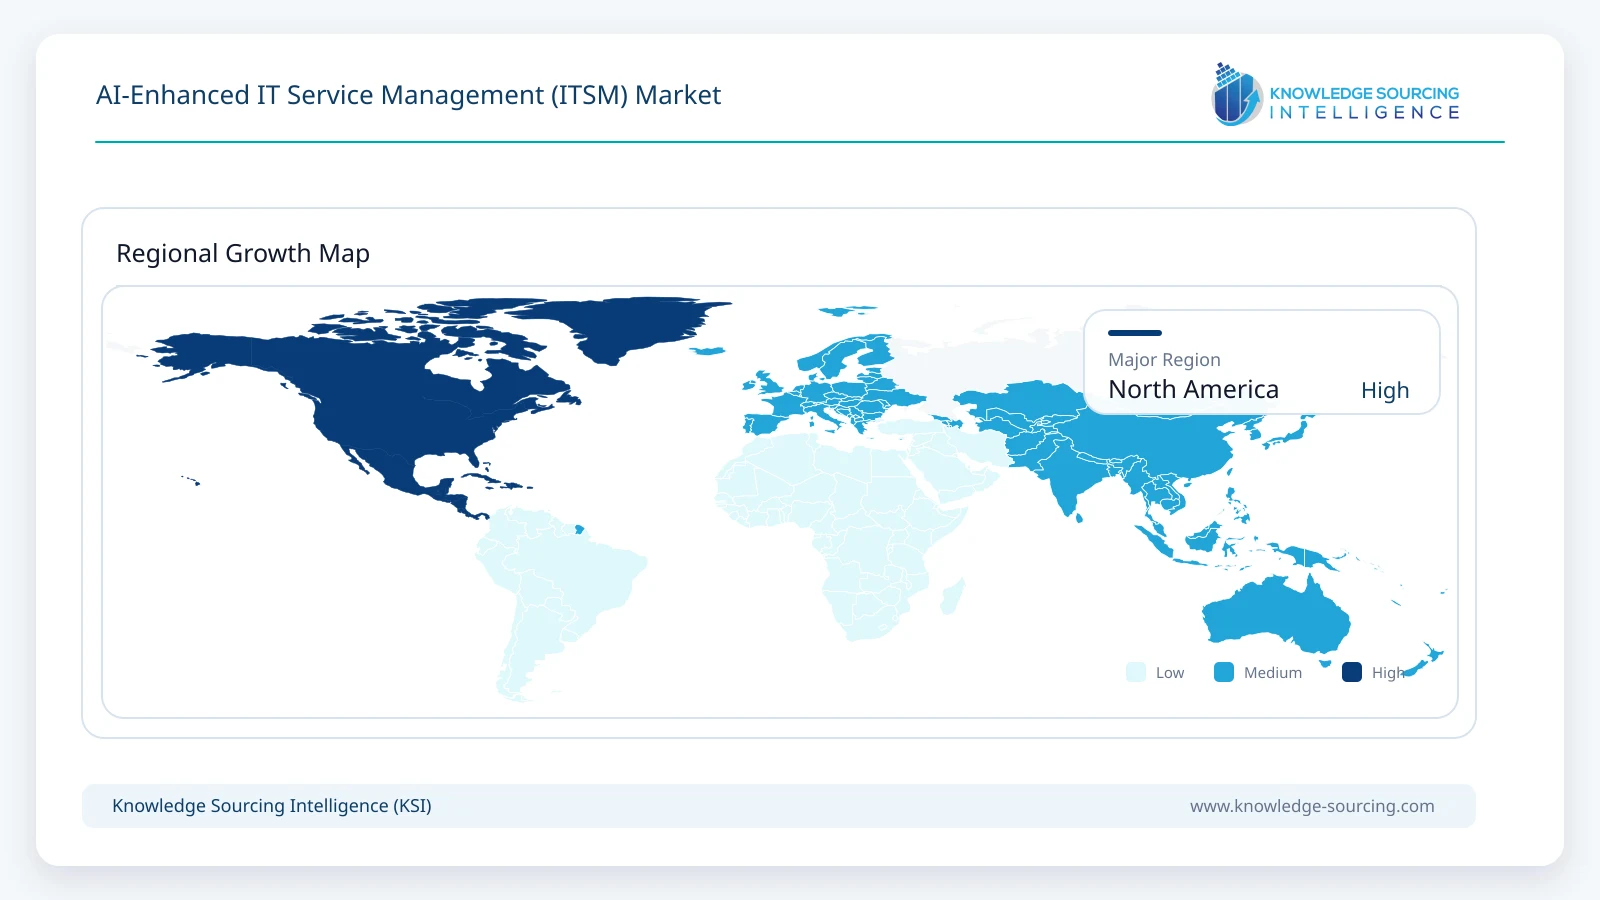
- 6North America leads current purchasing, while Asia Pacific offers the fastest modeled growth as cloud service operations expand.
AI-enhanced IT service management encompasses AI functions deployed within service desk, incident, problem, request, change and selected IT operations workflows. Commercial offerings range from intelligent classification and knowledge assistance to virtual support agents, governed remediation and predictive incident analysis. Suppliers earn attributable revenue through AI product tiers, usage-based services and directly related configuration or integration work; general enterprise AI subscriptions and conventional ITSM features with no separately identifiable AI value fall outside the defined market.
ServiceNow, Atlassian, BMC, Freshworks, Ivanti, ManageEngine and specialist ITSM vendors compete through different combinations of workflow depth, agent tooling and deployment economics. A proposed automation must work with current ticket records, configuration relationships and security permissions.
A service request asking for a password reset appears simple until the workflow must verify the employee, inspect access policy, call an identity system and confirm that the action succeeded. ServiceNow's L1 IT Service Desk AI Specialist represents one approach: the system can receive assigned incidents, review knowledge and historical records, take authorized steps and escalate exceptions. At the City of Raleigh, a published October 2026 implementation links AI-assisted service operations to reductions in service-desk cost; the reported outcome is specific to that deployment and cannot be extrapolated to every enterprise.
Freshworks introduced AI Agent Studio for Freshservice on 14 May 2026, offering tools to configure agents against service data and available business applications. Atlassian's September Jira Service Management updates brought Rovo assistance into service work items, including change-risk evaluation and in-context agent invocation. Different products therefore address different points in the workflow: an agent-facing assistant may shorten diagnosis, whereas an execution-oriented system must negotiate permissions, record actions and manage failure.
Commercial scale remains difficult to infer from technology announcements alone. ServiceNow reported that its cross-platform AI annual contract value exceeded USD 1 billion in the second quarter of 2026, but that amount includes workflow domains beyond ITSM. Vendors also bundle AI with base software or meter high-volume transactions separately. Purchasers are consequently testing cost per resolved incident, reopen rates and the engineering needed to maintain integrations rather than accepting claims of autonomous service delivery without deployment evidence.
Market Trends
Agent Execution Moves into the Production Service Desk
ServiceNow's 2026 L1 specialist assigns an autonomous worker to routine incidents within established service queues, while BMC Helix's April 2026 release added a Ticket Resolver capability. These products are narrowing the gap between conversational self-service and the controlled execution of support tasks. The practical dividing line is whether the system can complete an approved change, capture its result and return unresolved work to a technician with the full context intact.
Initial rollouts remain bounded by incident priority and tool access. Network outages, account permission changes and other consequential actions can require human approval or change windows even when diagnosis is automated.
Service Context Is Becoming a Product Requirement
Jira Service Management's September 2026 Rovo updates put agent suggestions and change-risk assessments closer to the underlying work item. Retrieval quality and the freshness of configuration records affect the accuracy of the proposed response more directly than a general-purpose model benchmark.
The cost of keeping knowledge valid is moving into implementation budgets. Permissions and source-of-truth maintenance determine whether a model can cite the correct runbook or identify a related incident.
AI Pricing Is Shifting toward Work Performed
ServiceNow's Flow, announced on 1 October 2026, brings conversational service work into chat channels, while Freshworks has expanded tools for configuring and monitoring agents. Vendors may charge through premium subscription tiers, named service workers, usage allowances or incremental automation consumption. Contract comparison therefore requires an understanding of how many requests are eligible for automated action and how often a human must intervene.
Procurement teams increasingly seek evidence of durable resolution rather than chat deflection alone. An answer that closes a conversation but produces a reopened ticket offers limited labour savings.
Service Management Is Linking More Closely with Operations Data
Incident triage becomes more useful when service records can be matched to monitoring signals, endpoint status and configuration changes. BMC Helix integrates IT operations and service-management workflows, while established platform vendors are enriching ticket records with events and machine-generated context. This improves the prospects for identifying recurring problems and suppressing duplicate investigations without obliging the service desk to replace every infrastructure monitoring tool.
Operational autonomy still depends on the boundary between observation and action. A service agent can suggest a remediation on the basis of a probable root cause, but changing a production system requires protected credentials, approval logic and a safe rollback. The value of AI-enabled ITSM lies in coordinating these workflows, rather than claiming every observability licence as service-management revenue.
Controls for Agent Behaviour Are Entering Standard Product Releases
ManageEngine's March 2026 Zia Agent Studio lets administrators specify knowledge sources, connected tools and operating boundaries for service-desk agents. Ivanti's 2026 Neurons release similarly highlights policy and approval guardrails for an AI self-service agent. The trend is commercially consequential in banks, government and healthcare, where privileged access and personal information can move through a support request.
Versioned instructions, activity logs, least-privilege execution and exception handling create recurring configuration and validation work.
AI-Enhanced IT Service Management (ITSM) Market Segment Analysis
By Deployment
Cloud-Based
Cloud-based delivery is well suited to fast-changing AI workloads because vendors can update models, agent orchestration and connectors without customers maintaining each inference environment. Freshservice, ServiceNow and Jira Service Management also benefit from hosted service data and centralized policy administration. Sensitive ticket content and model interaction logs nevertheless require enterprise-level controls, especially where the support platform interacts with identity stores and regulated records.
By 2031, the cloud-based submarket is projected to approach USD 4.30 billion, with spending supported by adoption among both existing customers and new service-desk accounts. A cloud license can reduce local administration but does not remove the need for integration engineering, access reviews or change testing.
By Enterprise Size
Large Enterprises
Large enterprises are projected to generate around USD 3.31 billion in AI-enabled ITSM value by 2031. Their purchasing case depends on high volumes of service records, complex entitlement structures and the operational cost of slow incident handoffs. A multinational business might operate separate identity, endpoint and network teams, making consistent data ownership as important as the model used to recommend a fix.
Although enterprise buyers can fund sophisticated agent governance, lengthy service-catalogue rationalization and procurement review can constrain rollout speed. Smaller businesses have less integration complexity and may adopt bundled AI features faster, especially as self-service products require fewer administrators. The difference is between potential contract size and speed of uptake, not simply organizational enthusiasm for AI.
By Application
Incident & Problem Management
Repeated symptoms, resolution histories and support queue records create useful training and retrieval material for incident classification. ServiceNow's L1 specialist, BMC Helix Ticket Resolver and SysAid's purpose-built agents target different parts of this workload. Automated analysis can shorten the first stage of diagnosis, while problem-management work requires identifying the causes of recurring incidents rather than merely processing each occurrence as a separate ticket.
Incident and problem management revenue is projected at approximately USD 1.80 billion in 2031, although its share moderates as operations and performance use cases gain ground. Technicians remain necessary for high-severity events, inconsistent logs and changes with significant blast radius. AI's financial value is greatest when lower reopen rates and fewer duplicate investigations persist beyond the initial trial.
By End-User
IT and Telecommunications
IT service providers and telecommunications operators maintain interconnected systems, numerous access paths and service commitments that make fast incident correlation financially relevant. Their exposure extends beyond employee password requests to network changes, customer-facing application incidents and dependencies between operations teams. An AI service workflow that maps symptoms to service impact can improve escalation decisions, provided the network evidence is reliable.
The IT and telecommunications segment is projected to expand at approximately 28% annually through 2031. Banking and healthcare buyers place comparatively greater weight on data classification and approval traceability, which can support higher-value implementations even where deployment is more cautious.
Market Drivers
Service Volumes and the Cost of Repetitive Support
High-frequency issues such as access requests, endpoint setup and routine software failures consume technician capacity even when the resolution is well documented. AI becomes economically attractive when it performs an authorized step and prevents the ticket from returning, not when it merely drafts a quicker response.
ServiceNow's Raleigh deployment demonstrates measurable productivity in a specific operating environment, strengthening the purchasing case for carefully scoped automation. The purchasing constraint is not ticket volume alone: service catalogues and resolution rights must be standardized enough for repeated, safe execution.
Greater Complexity across Hybrid Infrastructure
A single incident may involve SaaS credentials, a private network, an endpoint agent and an application change made by another team. Fragmented tooling increases investigation time and can obscure the service actually affected.
AI-enhanced ITSM gains value when it connects authorized observations to a case record and directs the next decision. Integration expenditure is often determined by service ownership and record quality rather than model training, making current configuration links a meaningful supplier advantage.
Configurable Agent Tools Reduce Deployment Friction
Freshworks AI Agent Studio and ManageEngine Zia Agent Studio make structured workflows and external connections accessible to service administrators rather than only software developers. Templates reduce initial engineering work, while deployment analytics expose which tasks fail repeatedly.
This creates an economic route for midmarket buyers and an implementation opportunity for specialist partners. Complex entitlements still require testing, so easier configuration should not be confused with instant production readiness. Customers can extend a tested workflow to adjacent service categories only after the permissions, error cases and operational owner are established.
Employee Experience Is Influencing Service Contracts
Support users increasingly expect a request to progress from chat to completion without re-entering the same information in a portal. ServiceNow's Moveworks acquisition brought a conversational interface into a wider workflow portfolio; Atlassian is embedding Rovo inside familiar ticket surfaces.
The competitive value is continuity of context and a trustworthy status update. Products that shift work invisibly between chat and ticket queues may frustrate employees despite faster initial response times. For buyers, visible request completion and responsible escalation increasingly determine whether an AI interface merits a higher subscription tier.
AI Performance Measurement Is Becoming More Rigorous
Service owners are moving beyond the number of AI conversations toward reopen rates, durable resolution, escalation quality and staff time returned. ServiceNow's May 2026 release notes distinguish autonomously resolved incidents from self-service guidance in the specialist's dashboard.
Comparable operational measures help chief information officers justify premium software expenditure and identify workflow categories that are unsuitable for autonomous action. Implementation partners can strengthen their position by testing those measures through software upgrades rather than reporting only the first month of results.
Market Restraints
Incomplete Knowledge and Configuration Records
Outdated articles and unreliable configuration relationships give automated support systems a weak basis for diagnosis. The problem grows when AI is allowed to execute a task using information that is correct for one business unit but invalid for another.
Establishing record ownership, checking retrieval permissions and removing superseded procedures can require prolonged preparation. Organizations sometimes postpone agent rollouts when the cleanup cost exceeds the expected near-term labour saving. The remedial work can span different teams and budgets, particularly when document ownership has never been assigned at the application level.
Privileged Access and Sensitive Service Data
Incident records can contain credentials, infrastructure details and personal information, while remediation agents may need production-system privileges. Healthcare, financial and government buyers require clear restrictions on which records leave the platform and which actions an agent can perform.
Model logging, third-party processors and temporary access tokens complicate these reviews. Deployments may remain in a recommendation-only mode until the supplier demonstrates adequate segregation of duties and auditable execution. Procurement delays may therefore originate in identity architecture and contract terms rather than the AI model itself.
Customized Legacy Service Workflows
Enterprises that have used ITSM for a decade may rely on custom scripts, undocumented approval paths and multiple service catalogues. A new AI agent must handle these differences without bypassing existing change controls or generating duplicate tickets.
Prebuilt connectors address only part of the work; exceptions can require individual redesign. This lengthens implementation and may reduce the financial benefit of adding a new autonomous workflow to an otherwise stable service desk. Where legacy scripts cannot be safely exposed to agent tools, customers may retain assisted diagnosis instead of authorizing automated completion.
Uncertain Usage Fees and Outcome Definitions
Some vendors count a conversation as deflected when no ticket is created, while customers may count it as successful only if the underlying request remains resolved. AI tiers, consumption allowances and additional integration services also complicate comparisons with conventional ITSM licensing.
Procurement teams need pilots that measure unsuccessful attempts, human review and reopened requests alongside usage cost. Without consistent definitions, a low-priced AI feature can carry an unexpectedly high cost per completed task. Budget approval becomes easier when vendors publish precise billing events and allow customers to export independent measures of quality.
Operational Risk from Incorrect Remediation
An inaccurate summary inconveniences a technician; a wrongly executed production change can disrupt a business service. Autonomous steps therefore require permission boundaries, service impact checks and a recoverable path if an external tool fails.
Incident priority and change category influence which actions can be approved without a human. Vendors that cannot prove deterministic guardrails will face a slower path to high-value remediation use cases, even where their diagnostic model is effective. For high-severity incidents, supervised decision support may continue to be the appropriate paid product even as lower-risk actions become autonomous.
Regional Outlook
North America
North America accounts for an estimated 42% of 2026 market value, supported by the presence of major platform vendors, mature service-management estates and significant enterprise AI software budgets. The region's projected value reaches approximately USD 1.80 billion by 2031. The United States is the main customer base, spanning technology companies, financial institutions, healthcare systems and government agencies with demanding IT service requirements.
Purchasing decisions are moving from exploratory assistants to governed, measurable workflows. ServiceNow's October 2026 Raleigh case establishes a production reference for municipal IT service automation, although outcomes vary with knowledge quality and scope. Large customers are increasingly distinguishing employee-facing conversational tools from back-office AI specialists that can handle incidents and approvals. Governance costs and the complexity of older installations limit how quickly new features translate into billable deployments.
Asia Pacific
Asia Pacific is forecast to be the fastest-growing region, expanding at approximately 37.4% annually from 2026 to 2031 and reaching about USD 1.42 billion in the final year. Adoption is supported by rising cloud-service penetration, large outsourced IT operations teams and service modernization in India, Japan, China and South Korea. Suppliers must accommodate different languages, compliance requirements and infrastructure architectures instead of offering one unchanged deployment pattern.
India's systems-integrator ecosystem can support configuration and ongoing service-agent maintenance, while Japan and South Korea place particular emphasis on dependable enterprise operations and documentation. ServiceNow's October 2026 AI Workflow Factory announcement in Mumbai illustrates investment in regional workflow delivery capabilities, though the initiative is broader than ITSM alone. Regional demand is expected to move increasingly toward subscription platforms with local support and tested integrations.
Competitive Landscape
ServiceNow and BMC compete for complex service estates where incident, change and operations data need to remain consistent across several teams. ServiceNow's completed Moveworks acquisition expands its employee-facing interface; BMC's Helix platform addresses tightly linked ITSM and operations workflows. Atlassian benefits when customers already use Jira and Confluence and want agent assistance without moving their service records. Broad ecosystems and established configuration data can offset the appeal of isolated AI features.
Freshworks, ManageEngine, SysAid and Ivanti offer different combinations of agent builders, service workflows and governance. Atera's autonomous IT tools are more relevant to lean IT teams and managed providers, while Halo Service Solutions, TOPdesk, InvGate and TeamDynamix compete through established service management products with varying AI functionality. Customers should verify which features are generally available, what is licensed separately and whether provider demonstrations rely on nonproduction knowledge or unusually simple tickets.
Recent Developments
October 2026: ServiceNow- Reported that the City of Raleigh had placed its IT Service Desk AI Specialist in production, including autonomous support workflows and published operational outcomes.
October 2026: ServiceNow- Introduced Flow, an AI-native conversational service desk; the announcement described controlled availability and a broader regional rollout expectation.
September 2026: Freshworks- Detailed updates to Freddy AI Copilot in Freshservice, including a more proactive and contextual support interface.
September 2026: Freshworks- Outlined enhancements to Freddy AI agent configuration, cross-channel service use and copilot assistance.
August 2026: ServiceNow- Published general availability of its L1 Service Desk AI Specialist, designed for governed end-to-end handling of routine incidents.
May 2026: Freshworks- Unveiled AI Agent Studio in Freshservice with configurable Freddy agents and associated governance and integration functionality.
Market Outlook
AI in ITSM is likely to be adopted first where workflows repeat often, permissions can be narrowly defined and successful outcomes can be measured. Service providers will add retrieval and reasoning to established ticket queues, but the largest economic change comes when completion steps are executed safely and case records update automatically. Growth in agent usage will not translate uniformly into higher subscription fees if vendors include basic summarization and search in standard licences.
The value available to suppliers should increasingly favour governed automation, tested connectors and information management that can be reused across multiple departments. Large enterprise accounts will remain important because of workflow scale, while cloud-native services can expand into smaller IT departments. Contract economics, knowledge maintenance and the need for human oversight will keep autonomous remediation narrower than the industry's promotional claims suggest.
AI-Enhanced IT Service Management (ITSM) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.26 billion |
| Total Market Size in 2031 | USD 4.73 billion |
| Forecast Unit | Billion |
| Growth Rate | 30.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Deployment, Enterprise Size, Application, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Deployment
On-Premise
Cloud-Based
By Enterprise Size
Large Enterprises
Small and Medium-sized Enterprises
By Application
Operations & Performance Management
Network Management
Incident & Problem Management
Others
By End-User
IT and Telecommunications
Banking, Financial Services, and Insurance (BFSI)
Healthcare
Government
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Thailand
Others
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Service Volumes and the Cost of Repetitive Support
3.1.2. Greater Complexity across Hybrid Infrastructure
3.1.3. Configurable Agent Tools Reduce Deployment Friction
3.1.4. Employee Experience Is Influencing Service Contracts
3.1.5. AI Performance Measurement Is Becoming More Rigorous
3.2. Market Restraints
3.2.1. Incomplete Knowledge and Configuration Records
3.2.2. Privileged Access and Sensitive Service Data
3.2.3. Customized Legacy Service Workflows
3.2.4. Uncertain Usage Fees and Outcome Definitions
3.2.5. Operational Risk from Incorrect Remediation
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. AI Service Agents and Workflow Execution
4.2. Knowledge Grounding and Retrieval
4.3. Predictive Incident Analytics
4.4. AI Governance and Privileged Tool Access
5. AI-ENHANCED IT SERVICE MANAGEMENT (ITSM) MARKET BY DEPLOYMENT
5.1. Introduction
5.2. On-Premise
5.3. Cloud-Based
6. AI-ENHANCED IT SERVICE MANAGEMENT (ITSM) MARKET BY ENTERPRISE SIZE
6.1. Introduction
6.2. Large Enterprises
6.3. Small and Medium-sized Enterprises
7. AI-ENHANCED IT SERVICE MANAGEMENT (ITSM) MARKET BY APPLICATION
7.1. Introduction
7.2. Operations & Performance Management
7.3. Network Management
7.4. Incident & Problem Management
7.5. Others
8. AI-ENHANCED IT SERVICE MANAGEMENT (ITSM) MARKET BY END-USER
8.1. Introduction
8.2. IT and Telecommunications
8.3. Banking, Financial Services, and Insurance (BFSI)
8.4. Healthcare
8.5. Government
8.6. Others
9. AI-ENHANCED IT SERVICE MANAGEMENT (ITSM) MARKET BY GEOGRAPHY
9.1. Global Overview
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East & Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Thailand
9.6.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. ServiceNow, Inc.
11.2. Atlassian Corporation
11.3. BMC Software, Inc.
11.4. Freshworks Inc.
11.5. Ivanti
11.6. Zoho Corporation (ManageEngine)
11.7. SysAid Technologies Ltd.
11.8. Atera
11.9. Halo Service Solutions Ltd.
11.10. TOPdesk
11.11. TeamDynamix
11.12. InvGate
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for AI-Enhanced ITSM?
The AI-Enhanced IT Service Management (ITSM) Market will reach $4.73 billion by 2031 at 30.3% CAGR.
Which deployment model dominates the AI-Enhanced ITSM market?
Cloud-based deployments lead, accounting for approximately 83% of 2026 value.
Which enterprise segment primarily drives AI-Enhanced ITSM demand?
Large enterprises contribute about 75% of estimated 2026 demand.
Which ITSM workflow area generates the most revenue?
Incident and problem management represent 43% of 2026 revenue.
Which region currently leads AI-Enhanced ITSM purchasing, and which shows fastest growth?
North America leads purchasing; Asia Pacific offers the fastest growth.
Which industry vertical primarily adopts AI-Enhanced ITSM solutions?
IT and telecommunications generate roughly 35% of 2026 demand.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). AI-Enhanced IT Service Management (ITSM) Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ai-enhanced-it-service-management-itsm-market