
The AI in Telecom Operations Market is anticipated to expand at a high CAGR over the forecast period.
Highlights:
- 1Growing network complexity across 5G, fiber, and cloud-native infrastructure is accelerating investment in AI-driven telecom operations.
- 2Network optimization remains one of the most commercially important applications because of its direct influence on service quality and operating expenditure.
- 3Asia Pacific represents an important opportunity due to continued telecom infrastructure investment and expanding mobile subscriber bases.
- 4Generative AI and intelligent automation are expanding beyond customer support into network engineering, service assurance, and operational planning.
- 5Data governance, cybersecurity regulations, and AI governance frameworks are influencing procurement decisions and deployment architectures.
- 6Competition increasingly centers on platform integration, telecom domain expertise, ecosystem partnerships, and cloud interoperability.
The AI in Telecom Operations market comprises software platforms, analytics engines, automation tools, and associated services that apply artificial intelligence across telecom network management, service assurance, customer operations, cybersecurity, and business support systems. The market supports communication service providers (CSPs), infrastructure vendors, managed service providers, internet service providers, and data center operators seeking to improve operational efficiency while managing increasingly complex fixed and mobile networks.
Demand is being shaped by the continued expansion of 5G infrastructure, fiber deployments, edge computing, cloud-native networks, and the growing number of connected devices. Modern telecom networks generate vast operational datasets from radio access networks (RAN), transport infrastructure, core networks, billing platforms, customer interactions, and connected endpoints. Manual analysis is no longer sufficient to manage network performance, fault resolution, fraud detection, and customer experience at scale. Consequently, operators are allocating higher budgets to AI-enabled operational support systems capable of converting operational data into automated actions.
Procurement priorities have also evolved. Buyers increasingly evaluate AI platforms based on interoperability with existing OSS/BSS environments, cybersecurity capabilities, explainable AI functions, deployment flexibility, integration costs, and measurable operational savings. Rather than purchasing isolated AI applications, telecom operators are favoring platforms capable of supporting multiple operational domains through a common analytics architecture.
The industry structure combines global technology providers, telecom equipment manufacturers, hyperscale cloud companies, enterprise software vendors, and specialized telecom AI developers. Revenue is generated through software licensing, cloud subscriptions, implementation services, consulting, systems integration, and managed AI operations. Long-term contracts remain common because AI deployment typically involves extensive network integration, model training, and continuous optimization.
Adoption patterns vary by operator maturity. Large multinational telecom companies are deploying AI across multiple operational functions, including autonomous network management, customer engagement, and predictive maintenance. Mid-sized operators often begin with narrowly defined use cases such as chatbot automation, fraud analytics, or network fault prediction before expanding deployments across broader operational workflows.
Market Drivers
Expansion of Autonomous Network Operations
Telecommunication networks now consist of virtualized cores, distributed cloud infrastructure, software-defined networking, edge computing resources, and large-scale radio deployments. Managing these environments manually creates operational inefficiencies and longer fault resolution times.
Network operators are therefore investing in machine learning models capable of predicting congestion, identifying service degradation, and recommending automated corrective actions. Suppliers are responding by integrating AI into OSS platforms, enabling closed-loop automation that reduces operational expenses while improving service availability. Commercially, operators seek measurable improvements in network utilization, service quality, and workforce productivity before committing to enterprise-wide deployments.
Rising Demand for Superior Customer Experience
Customer retention has become increasingly dependent on service reliability, rapid issue resolution, and personalized digital interactions. Telecom providers face persistent pricing pressure, making customer experience a critical competitive differentiator.
AI enables intelligent virtual assistants, customer sentiment analysis, proactive service notifications, and automated ticket prioritization. Operators are investing in these capabilities because reducing customer churn often delivers greater financial value than acquiring new subscribers. Vendors compete by offering integrated customer analytics platforms capable of combining network performance data with subscriber behavior.
Growing Cybersecurity and Fraud Risks
Telecommunication operators remain attractive targets for cyberattacks, signaling fraud, SIM swap fraud, identity theft, and distributed denial-of-service attacks. As network architectures become more distributed, conventional rule-based security systems struggle to detect sophisticated threats.
AI-driven anomaly detection enables continuous monitoring across network layers while improving fraud detection accuracy. Buyers increasingly prioritize platforms capable of combining security analytics with operational monitoring. This creates additional opportunities for vendors offering unified network intelligence solutions rather than standalone cybersecurity products.
Continued Investment in 5G and Cloud-Native Infrastructure
The transition toward standalone 5G architectures introduces substantially greater operational complexity than previous network generations. Network slicing, distributed edge computing, virtual network functions, and dynamic resource allocation require continuous optimization.
AI supports automated capacity planning, energy optimization, predictive maintenance, and intelligent workload distribution. Equipment manufacturers and cloud platform providers are therefore embedding AI capabilities directly into telecom infrastructure, strengthening recurring software revenues alongside hardware deployments.
Market Restraints and Challenges
Legacy Infrastructure Integration
Many telecom operators continue to operate heterogeneous networks built over multiple technology generations. Integrating AI solutions across legacy OSS, proprietary network equipment, and older business support systems often increases deployment timelines and implementation costs.
These integration challenges primarily affect incumbent operators with extensive legacy assets. Vendors increasingly mitigate this issue through open APIs, cloud-native architectures, and modular deployment approaches that allow phased implementation.
Data Quality and Fragmentation
AI performance depends on accurate, consistent, and well-governed operational data. Telecom organizations frequently maintain separate data repositories across network, customer, billing, and security systems.
Poor data consistency reduces model accuracy and delays AI deployment. Buyers therefore allocate additional investment toward data governance, master data management, and centralized analytics platforms before scaling enterprise AI initiatives.
Regulatory Compliance and AI Governance
Governments are introducing stricter requirements governing AI transparency, privacy protection, cybersecurity, and cross-border data management. Telecom operators handling sensitive subscriber information must demonstrate regulatory compliance while maintaining service quality.
Compliance obligations increase implementation complexity and may lengthen procurement cycles, particularly for cloud-based deployments. Suppliers increasingly provide explainable AI functions, audit capabilities, and regional data hosting options to address regulatory requirements.
Shortage of Specialized AI and Telecom Talent
Successful AI deployment requires expertise spanning telecommunications engineering, cloud computing, cybersecurity, and data science. Many operators face shortages of professionals capable of developing, validating, and maintaining AI models within operational environments.
This skills gap encourages greater demand for managed AI services, systems integration, and long-term consulting engagements, creating additional service revenue opportunities for established technology providers.
Major Segment Analysis
Network Optimization
Network optimization represents one of the most commercially important application segments because it directly influences service quality, infrastructure utilization, and operating profitability. Mobile traffic growth, expanding fiber connectivity, private networks, and enterprise connectivity services require operators to continuously optimize spectrum usage, network capacity, and routing decisions.
Buyers typically prioritize solutions capable of reducing dropped calls, minimizing latency, improving spectrum efficiency, and accelerating fault resolution. Procurement decisions increasingly emphasize interoperability with multi-vendor network environments and compatibility with cloud-native network functions.
Competition within this segment focuses on algorithm accuracy, automation capabilities, real-time analytics, and deployment scalability. Vendors capable of integrating AI with radio access networks, transport infrastructure, and core network management platforms gain stronger commercial positioning because operators prefer consolidated operational platforms over multiple disconnected applications.
Revenue opportunities also extend beyond software licensing through implementation services, continuous model optimization, network consulting, and managed operations. As telecom operators pursue autonomous network strategies, network optimization is expected to remain among the highest-value AI deployment areas.
Regional Analysis
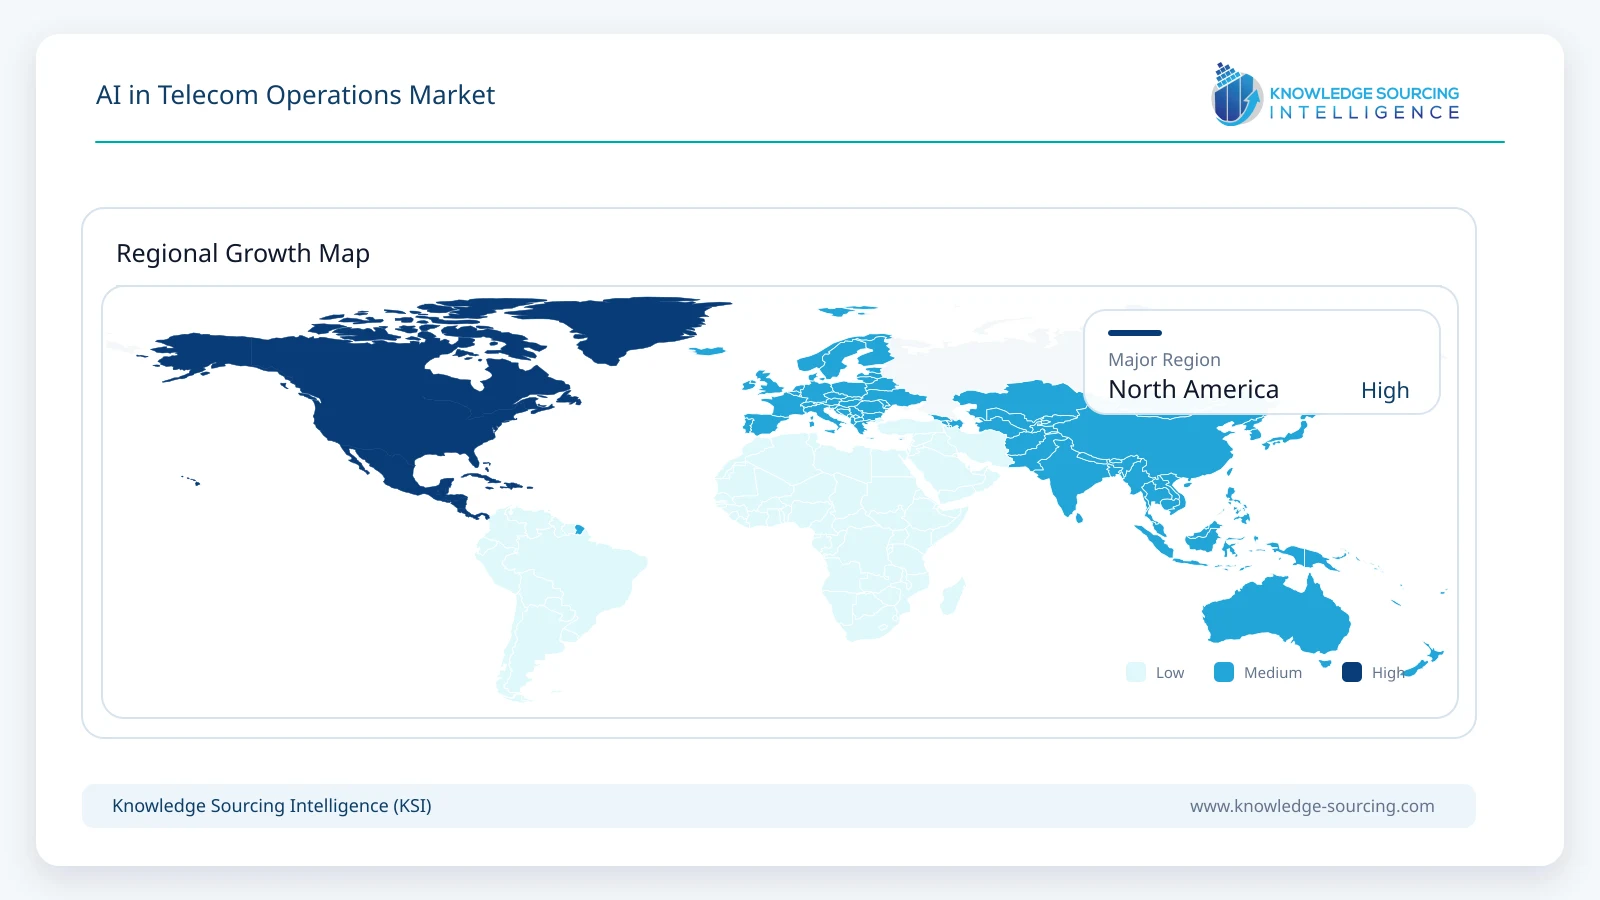
North America maintains a mature adoption environment supported by advanced 5G deployments, large cloud investments, and early implementation of AI-enabled network automation. Telecom operators emphasize operational efficiency, cybersecurity, and customer experience improvements while collaborating extensively with cloud service providers and enterprise software vendors.
Europe demonstrates strong demand supported by extensive fiber expansion, Open RAN initiatives, and regulatory emphasis on trustworthy AI and data protection. Operators often prioritize energy-efficient network management and compliance with evolving digital governance requirements. Procurement decisions place considerable importance on interoperability and regulatory conformity.
Asia Pacific represents one of the largest investment environments due to extensive mobile subscriber populations, continuous 5G infrastructure deployment, expanding data center capacity, and government support for AI innovation. Large telecom operators increasingly deploy AI across network optimization, predictive maintenance, and customer service automation while equipment manufacturers strengthen regional partnerships.
Middle East & Africa continues investing in digital infrastructure, smart city initiatives, and national broadband expansion. Gulf countries are adopting AI-enabled telecom operations as part of broader digital economy programs, although implementation across several African markets remains constrained by infrastructure gaps and investment priorities.
South America experiences gradual adoption driven by network modernization and customer experience initiatives. Operators increasingly evaluate AI solutions that improve operational efficiency while limiting capital expenditure. Budget constraints and varying regulatory maturity continue to influence deployment speed across individual countries.
Competitive Landscape
Competition combines multinational technology companies, cloud platform providers, telecom infrastructure suppliers, and specialized telecom software developers, including IBM Corporation, Google LLC, Microsoft Corporation, Huawei Technologies Co., Ltd., Nokia Corporation, Telefonaktiebolaget LM Ericsson, Cisco Systems, Inc., Amazon Web Services, Inc., Amdocs Limited, Subex Limited, and Hewlett Packard Enterprise Company.
Competitive positioning depends less on standalone AI algorithms than on the ability to integrate with telecom operational environments, deliver measurable operational savings, and support multi-vendor infrastructure. Suppliers increasingly differentiate through cloud-native deployment models, telecom-specific AI models, cybersecurity integration, ecosystem partnerships, and managed AI services. Strategic collaborations between hyperscale cloud providers, telecom equipment manufacturers, and communication service providers continue expanding solution portfolios while improving deployment flexibility across global markets.
Recent Developments
June 2026: Nokia and Google Cloud expanded their partnership by integrating Google Gemini-based AI agents into Nokia's Assurance Center, enabling faster fault resolution, lower operational costs, and higher levels of autonomous telecom network operations.
June 2026: Ericsson introduced AI in RAN, a commercial software offering embedding telco-grade AI models into radios and basebands to improve network performance, energy efficiency, and real-time automation without additional hardware.
May 2026: Nokia launched new agentic AI capabilities for home and broadband networks, enabling telecom operators to automate fiber planning, Wi-Fi optimization, network operations, and service assurance using secure, open AI agents.
March 2026: Nokia expanded AI capabilities within its autonomous network portfolio by introducing enhanced automation functions for service assurance and network operations. Commercial relevance: strengthens operator adoption of closed-loop network management.
February 2026: Google Cloud announced expanded generative AI capabilities for telecommunications customers through new industry-focused AI solutions. Commercial relevance: supports customer service automation and operational analytics across telecom environments.
Regulatory and Policy Environment
The regulatory environment increasingly influences AI adoption within telecom operations. Privacy regulations governing subscriber information require operators to implement secure data processing, controlled access management, and transparent data governance. AI governance frameworks are introducing additional requirements covering explainability, accountability, human oversight, and risk management for high-impact AI systems.
Telecommunications regulators continue encouraging secure network modernization while strengthening cybersecurity obligations for critical communications infrastructure. Industry standards developed by organizations such as 3GPP, ETSI, TM Forum, and GSMA support interoperability, network automation, and standardized operational interfaces. Compliance with these standards reduces deployment risk and improves integration across multi-vendor environments.
Government initiatives supporting national AI strategies, advanced telecommunications infrastructure, cloud computing, and digital connectivity also contribute to long-term investment in AI-enabled network operations.
Outlook and Strategic Implications
Over the next five years, procurement decisions are expected to prioritize AI platforms capable of supporting multiple operational domains through unified analytics architectures rather than isolated point solutions. Buyers will increasingly evaluate vendors according to measurable operational outcomes, cybersecurity resilience, regulatory compliance, and deployment flexibility.
Investment is likely to continue shifting toward autonomous network management, generative AI-assisted operations, predictive maintenance, intelligent security analytics, and energy optimization. Hybrid deployment architectures are expected to remain attractive because they balance regulatory requirements with cloud scalability.
Competitive differentiation will increasingly depend on telecom-specific AI expertise, ecosystem integration, and long-term managed services rather than software functionality alone. Vendors capable of combining domain knowledge with scalable cloud platforms and open integration frameworks should strengthen their commercial position.
Potential risks include evolving AI regulations, cybersecurity threats, data governance challenges, and shortages of specialized technical talent. Nevertheless, sustained investment in 5G, cloud-native infrastructure, and intelligent network management is expected to reinforce long-term demand for AI-enabled telecom operations as operators pursue greater efficiency, service reliability, and operational automation.
AI in Telecom Operations Market Scope
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Application, Technology Type, Deployment Mode, End User, Geography |
| Companies |
|
Market Segmentation
By Component
By Application
By Technology Type
By Deployment Mode
By End User
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. AI IN TELECOM OPERATIONS MARKET BY COMPONENT
5.1. Introduction
5.2. Solutions
5.3. Services
6. AI IN TELECOM OPERATIONS MARKET BY APPLICATION
6.1. Introduction
6.2. Network Optimization
6.3. Predictive Maintenance
6.4. Customer Service Automation and Experience Enhancement
6.5. Fraud Detection and Revenue Assurance
6.6. Network Security and Threat Detection
6.7. Network Planning and Capacity Management
6.8. Energy Optimization
7. AI IN TELECOM OPERATIONS MARKET BY TECHNOLOGY TYPE
7.1. Introduction
7.2. Machine Learning
7.3. Generative AI
7.4. Digital Twins
7.5. Intelligent Automation
7.6. Natural Language Processing
7.7. Deep Learning
7.8. Others
8. AI IN TELECOM OPERATIONS MARKET BY DEPLOYMENT MODE
8.1. Introduction
8.2. Cloud-based
8.3. On-premise
8.4. Hybrid
9. AI IN TELECOM OPERATIONS MARKET BY END USER
9.1. Introduction
9.2. Telecom Service Providers
9.3. Infrastructure Providers
9.4. Managed Service Providers
9.5. Internet Service Providers
9.6. Data Center Operators
10. AI IN TELECOM OPERATIONS MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. By Component
10.2.2. By Application
10.2.3. By Technology Type
10.2.4. By Deployment Mode
10.2.5. By End User
10.2.6. By Country
10.2.6.1. USA
10.2.6.2. Canada
10.2.6.3. Mexico
10.3. South America
10.3.1. By Component
10.3.2. By Application
10.3.3. By Technology Type
10.3.4. By Deployment Mode
10.3.5. By End User
10.3.6. By Country
10.3.6.1. Brazil
10.3.6.2. Argentina
10.3.6.3. Others
10.4. Europe
10.4.1. By Component
10.4.2. By Application
10.4.3. By Technology Type
10.4.4. By Deployment Mode
10.4.5. By End User
10.4.6. By Country
10.4.6.1. United Kingdom
10.4.6.2. Germany
10.4.6.3. France
10.4.6.4. Spain
10.4.6.5. Others
10.5. Middle East and Africa
10.5.1. By Component
10.5.2. By Application
10.5.3. By Technology Type
10.5.4. By Deployment Mode
10.5.5. By End User
10.5.6. By Country
10.5.6.1. Saudi Arabia
10.5.6.2. UAE
10.5.6.3. Others
10.6. Asia Pacific
10.6.1. By Component
10.6.2. By Application
10.6.3. By Technology Type
10.6.4. By Deployment Mode
10.6.5. By End User
10.6.6. By Country
10.6.6.1. China
10.6.6.2. Japan
10.6.6.3. India
10.6.6.4. South Korea
10.6.6.5. Taiwan
10.6.6.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. IBM Corporation
12.2. Google LLC
12.3. Microsoft Corporation
12.4. Huawei Technologies Co., Ltd.
12.5. Nokia Corporation
12.6. Telefonaktiebolaget LM Ericsson
12.7. Cisco Systems, Inc.
12.8. Amazon Web Services, Inc.
12.9. Amdocs Limited
12.10. Subex Limited
12.11. Hewlett Packard Enterprise Company
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











