Aminoglycosides Market - Strategic Insights and Forecasts (2026-2031)
Aminoglycosides Market Size, Share, Forecasts and Trends Analysis By Product (Neomycin, Tobramycin, Gentamicin, Amikacin, Paromomycin, Others), By Route of Administration (Parenteral, Intra-mammary, Topical, Oral, Inhalation), By Application (Veterinary, Skin Infection, Respiratory Diseases, UTI and Pelvic Diseases, Others), and Region
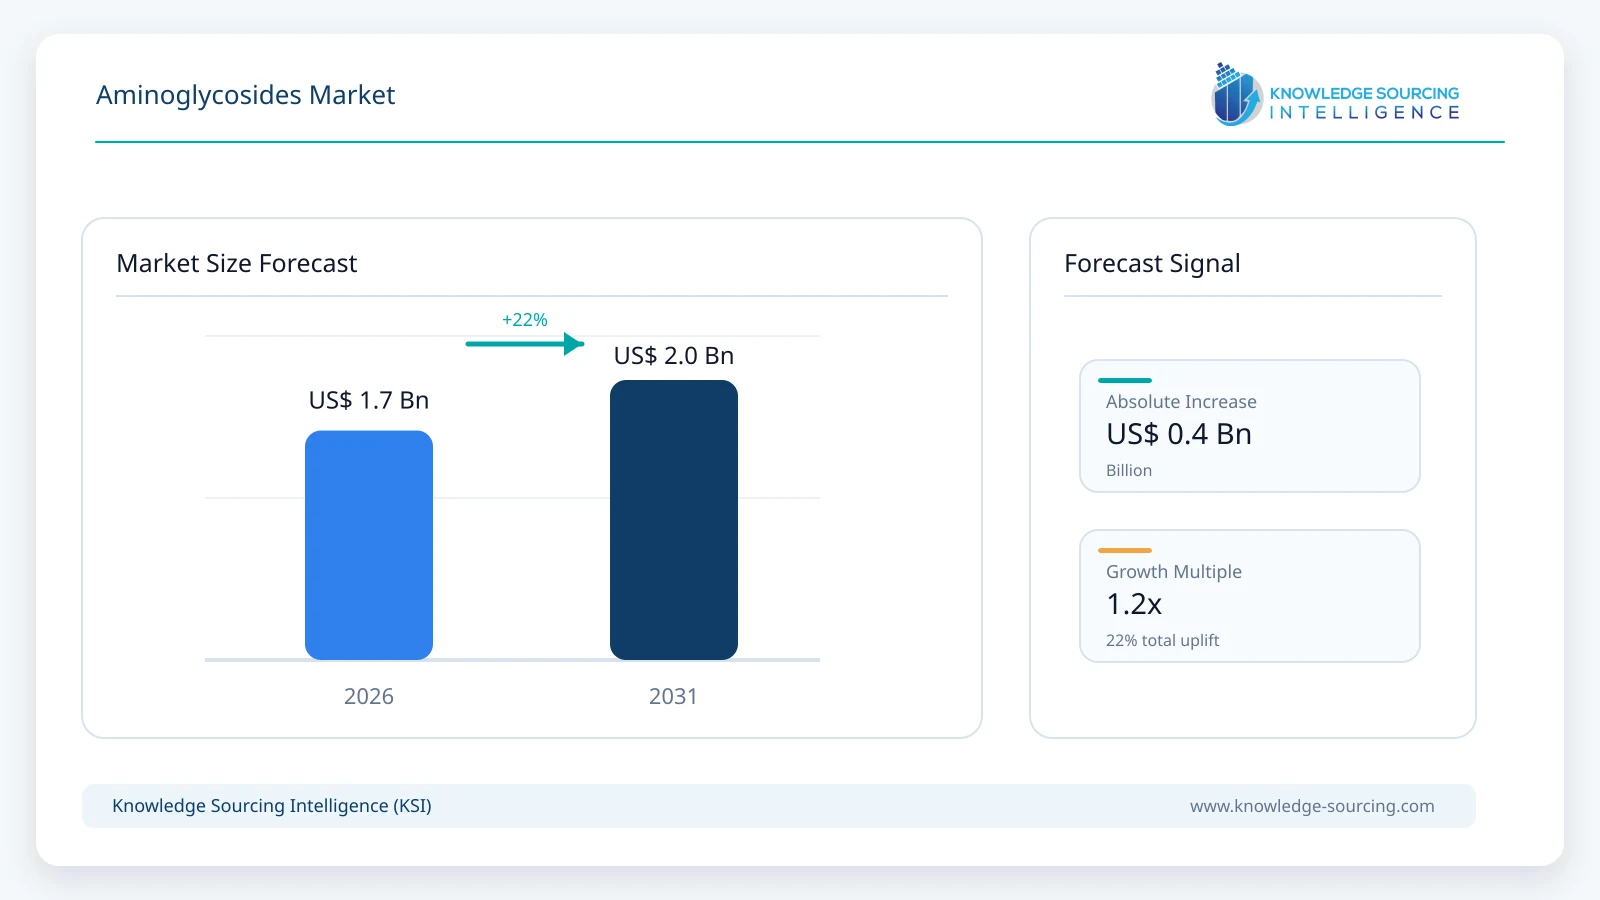
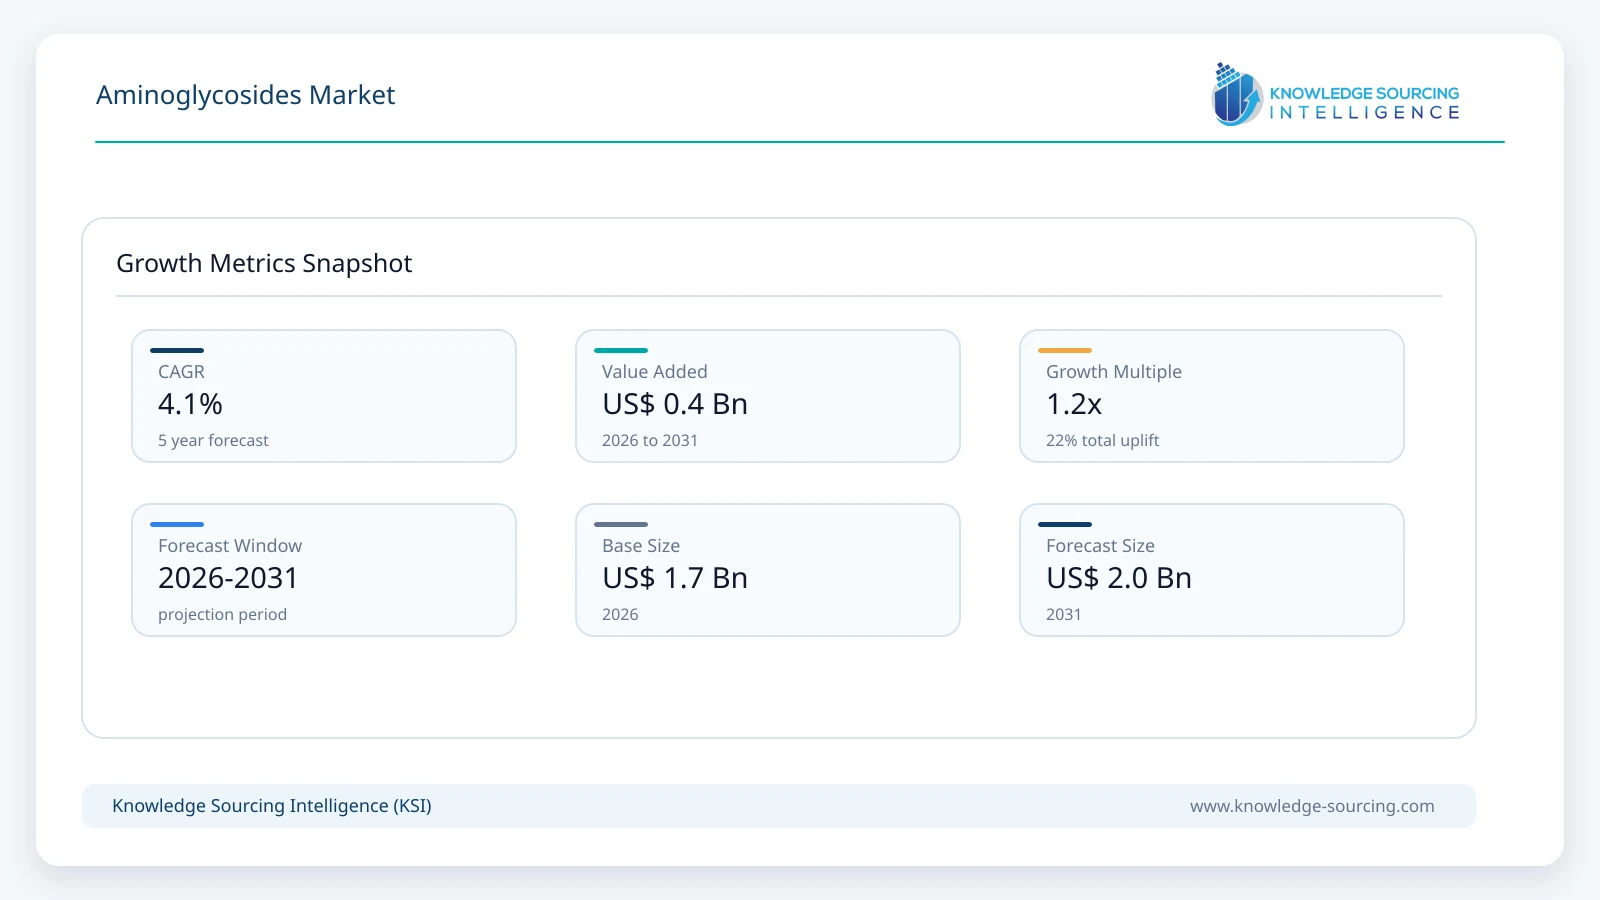
The global Aminoglycosides Market is projected to grow at approximately 4.06% annually, reaching USD 2.05 billion in 2031 from USD 1.68 billion in 2026.
Highlights:
1
Branded liposomal amikacin and generic injectables follow substantially different commercial and clinical pathways.
2
Gentamicin retains broad hospital utility where local susceptibility and renal monitoring support prescribing.
3
Inhaled aminoglycosides underpin specialized pulmonary care and require distinct device-compatible formulations.
4
Sterile manufacturing reliability and tender execution remain essential for conventional injectable suppliers.
5
Asia Pacific combines substantial generic antibiotic demand with expanding microbiology and hospital capacity.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Aminoglycosides are bactericidal antibiotics that act on the bacterial ribosome and are used when the infecting organism, treatment setting and patient condition justify their risks. The commercial portfolio ranges from inexpensive gentamicin injectables and topical preparations to specialized amikacin and tobramycin inhalation products. Product choice follows susceptibility testing, site of infection, renal function and dosing requirements. These medicines are not antivirals; their clinical use is directed at susceptible bacterial and certain mycobacterial infections.
Sales are distributed among manufacturers of sterile injections, ophthalmic and dermatological preparations, inhaled products, oral formulations and selected veterinary medicines. The underlying molecule may be decades old, yet delivery technology, microbiological evidence and manufacturing standards determine whether two products serve the same market. Insmed’s ARIKAYCE, for instance, has a restricted US indication in refractory Mycobacterium avium complex lung disease; generic amikacin injections cannot be assumed to have the same indication or economics.
Across regions, hospital procurement and antibiotic stewardship influence volume in established injectable categories, while product access, monitoring capacity and local resistance patterns influence selection. Manufacturers with reliable sterile supply, traceable quality and differentiated delivery systems are better positioned than companies whose portfolios are limited to undifferentiated commodity molecules.
Market Overview
Insmed reported USD 116.3 million of ARIKAYCE revenue in the second quarter of 2026 and maintained full-year guidance of USD 450–470 million. This branded inhaled amikacin business is material within the total drug class and underlines the need to distinguish specialist respiratory revenue from conventional generic injection sales. In September 2026, the US FDA accepted a supplemental application for expanded use, assigning a January 2027 target action date. Review acceptance does not itself authorize broader treatment; existing US labeling remains limited to refractory MAC lung disease.
In the bulk of the market, gentamicin and amikacin injections remain important for selected severe infections, while tobramycin retains specialist respiratory and ophthalmic applications. Pfizer’s Hospira gentamicin label and Teva’s tobramycin inhalation label demonstrate how routes of administration create separate technical obligations. Sterile vials require potency and particulate controls; nebulized products must perform with designated delivery equipment, and topical preparations have different stability and local-tolerance requirements.
Market development is consequently uneven. Hospitals operating with improved antimicrobial surveillance may reduce inappropriate prescribing while continuing to purchase dependable agents for life-threatening infections. Low-cost generic competition constrains pricing, but shortages or inconsistent supply can raise the value of qualified alternative suppliers. Newer delivery systems can achieve higher revenue per course, though their uptake depends on disease-specific evidence, reimbursement and the ability of clinicians to monitor treatment.
Market Trends
Liposomal amikacin is reshaping the value mix in respiratory medicine
Insmed’s ENCORE study reported a statistically significant difference in respiratory symptoms and culture conversion when ARIKAYCE was added to background treatment in a population with newly occurring MAC lung disease. The company subsequently sought broader US authorization, and the FDA accepted the submission for priority review in September 2026. A broader label, if granted, could alter eligibility and duration of therapy, but the current restricted indication remains in force.
Commercial exposure is concentrated in a few specialty products rather than spread uniformly across the class. Pulmonary specialists, patient selection and payer review shape access, while safety monitoring and delivery-device training affect adherence. The extension from a known molecule into an inhaled liposomal formulation shows how formulation, evidence generation and indication can become more valuable than chemical novelty alone.
Antibiotic stewardship is changing hospital demand quality
Susceptibility reports and institutional protocols increasingly guide whether a clinician chooses gentamicin, amikacin or an alternative agent for a serious Gram-negative infection. The FDA’s October 2025 updates to susceptibility test interpretive criteria underscore the importance of contemporary standards. A broad-spectrum label does not imply equal efficacy across organisms or justify routine empiric use without considering local patterns.
The commercial implication is not uniformly lower consumption. Hospitals still need a dependable selection of aminoglycosides for cases in which treatment is warranted, but protocols can affect the mix of products and course length. Suppliers should expect procurement discussions to emphasize validated availability, clinical compatibility and appropriate use rather than promotional volume expansion.
Monitoring capability is becoming part of procurement value
Nephrotoxicity and ototoxicity require careful patient selection, dosing and follow-up, particularly in complex or prolonged treatment. Clinical practice increasingly uses patient-specific renal assessment and therapeutic drug monitoring when indicated, rather than treating every prescribed milligram as equivalent across patients. Training, laboratory turnaround and pharmacy capacity therefore influence use at hospital level.
Manufacturers cannot independently remove these risks by revising packaging. Commercial differentiation comes through accurate labeling, dependable concentrations, consistent formulation and the availability of specialty delivery routes when supported by evidence. For health systems, avoiding toxicity and therapeutic failure can outweigh marginal differences in injectable acquisition price.
Generic inhalation and topical products compete through formulation reliability
Tobramycin inhalation solution and ophthalmic products address separate indications from systemic therapy. Teva and Dr. Reddy’s have supplied regulated generic inhalation solutions, while Bausch + Lomb markets tobramycin ophthalmic preparations. Nebulizer compatibility, concentration control, preservative requirements and microbial quality differ between these product families.
Competition is therefore more demanding than price per gram of tobramycin suggests. A hospital or home-care service needs a formulation that performs consistently in its intended route and distribution conditions. Established generics can capture recurring demand, but differentiated inhalation systems retain a separate pricing and evidence profile.
Stable injectable sourcing is increasingly strategic for hospitals
Hospitals use injectable gentamicin and amikacin in care pathways where a missed or delayed dose can compromise treatment. Although these molecules are mature, sterile filling capacity and batch release remain capital- and compliance-intensive. Changes to national formularies and product listings can alter which suppliers have access to funded purchasing channels.
Purchasers are likely to maintain alternative qualified sources where feasible. The ability to deliver stable stock, appropriate vial sizes and compliant packaging can determine repeat contracts; low headline unit prices offer little benefit if local availability is intermittent. This favors manufacturers that can maintain quality without overextending their low-margin sterile portfolios.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Segment Analysis
By Product: Amikacin
Amikacin has become the class’s most economically differentiated molecule because the category combines older parenteral formulations with higher-value inhaled treatment for pulmonary MAC disease. Insmed’s commercial ARIKAYCE franchise provides a clear example of this separation. In the 2026 market assessment, amikacin-related products represent approximately USD 539.0 million of global value, although the revenue pool is concentrated in markedly different price and use settings.
The outlook is sensitive to the pending US label review, the uptake of specialist therapy in international markets and the continued availability of generic amikacin injection. Expected growth should not be inferred from historical tuberculosis injections: contemporary drug-resistant TB regimens have shifted toward effective oral options, and older injectable regimens face toxicity and guideline limitations. The opportunity lies in evidence-supported pulmonary treatment and appropriately targeted systemic care.
By Route of Administration: Inhalation
Inhaled delivery creates a distinct commercial category through products intended for the respiratory tract, including liposomal amikacin and nebulized tobramycin. This route is estimated to represent USD 505.3 million of 2026 value, with a different reimbursement and training profile from hospital injections. Nebulized solutions and liposomal suspensions are not interchangeable solely because they share a drug class.
Growth is tied to respiratory indications, specialty-pulmonary referrals and device-compatible formulation quality. Parenteral products continue to support serious systemic infections, while topical and oral categories serve specific localized uses. Route-specific reporting is commercially important because branded inhaled sales would be misrepresented if assigned to injections.
By Application: Respiratory Diseases
Respiratory disease applications encompass inhaled therapy for selected chronic pulmonary infections and hospital use for susceptible severe bacterial respiratory illness. In the 2026 allocation, the category accounts for approximately USD 707.4 million of market revenue. The branded amikacin franchise raises its value relative to older generic products, despite fewer treated patients than in routine community antibiotic markets.
Expansion will depend on microbiologically confirmed indications, pulmonary specialist capacity and the outcomes of product-specific studies. A larger pool of respiratory diagnoses does not translate mechanically into aminoglycoside demand: many cases do not warrant this class, and organism identification, safety and alternatives remain decisive. UTI and pelvic infections continue to generate generic use where sensitivity and local protocols justify selection.
Market Drivers
Severe bacterial infections continue to require dependable treatment options
Gentamicin, amikacin and tobramycin retain roles in treating selected susceptible Gram-negative infections when clinical severity or resistance patterns warrant their use. Hospital formularies therefore maintain access even when newer agents are available. The ability to select a familiar, effective product quickly is valuable for acute-care teams, particularly when laboratory reporting and renal assessment can support subsequent treatment adjustment.
Demand follows case mix and stewardship more closely than general antibiotic prescription growth. Producers with continuous sterile supply and consistent release testing can benefit from repeat hospital purchasing, although the market remains constrained by generic competition and short treatment courses.
Established generics remain relevant to constrained healthcare budgets
Older aminoglycosides offer comparatively inexpensive treatment options in health systems facing pressure on medicine budgets. Gentamicin injection is stocked in numerous national hospital formularies, supporting ongoing demand across acute infection and specific specialist indications. Mature products also benefit from familiar preparation methods and established clinical knowledge.
Generic affordability does not eliminate the cost of administration, monitoring or toxicity management. Hospitals evaluate course-level cost and the likelihood of treatment success, and procurement teams increasingly require strong compliance records. This creates recurring opportunities for reliable manufacturers rather than automatic growth for every low-priced supplier.
Pulmonary specialization is expanding the commercial role of inhaled therapy
ARIKAYCE’s 2026 clinical and regulatory developments show that inhaled amikacin can address clinically distinct pulmonary populations, subject to authorization. Nebulized tobramycin serves a different chronic respiratory use case with established product labeling. Commercial value is generated through disease-specific care pathways and formulation performance rather than a generalized rise in antibiotic usage.
Broader specialist access requires diagnosis, reimbursement approval, clinician training and follow-up. Manufacturers able to support these steps can defend more differentiated prices, while significant clinical uncertainty around new indications continues until regulators complete their reviews.
Susceptibility testing supports rational use of existing molecules
Antimicrobial susceptibility methods and local antibiograms help clinicians identify infections in which aminoglycosides remain useful. The US FDA’s adoption of updated interpretive criteria in October 2025 reflects continued attention to accurate laboratory interpretation. Testing can preserve the utility of established antibiotics by guiding selection and avoiding exposure when a drug is unlikely to work.
For suppliers, effective testing makes demand more selective but also more defensible. Hospitals may prefer manufacturers with consistent concentrations and product availability, especially in facilities where delays in switching between agents are costly.
Manufacturing quality and distribution reach create persistent barriers to entry
Sterile injectables require validated aseptic processes, in-process controls and dependable finished-product release. Home-use inhalation therapies additionally depend on fill accuracy, suitable packaging and stability throughout distribution. These requirements discourage casual entry and create value for facilities with audited quality systems and established distribution.
The advantage is strongest where healthcare purchasers qualify manufacturers over repeated contracts. Tender prices can remain low, but production disruption may carry an operational cost for hospitals. Suppliers combining established sterile capacity with sensible portfolio management can protect long-term relationships.
Market Restraints
Kidney injury and hearing-related toxicity restrict use
Nephrotoxicity and ototoxicity are established risks of aminoglycoside treatment. They become especially important in patients with impaired renal function, prolonged exposure or additional risk factors. Hospitals may need drug-concentration monitoring and dose adjustments, raising the workload and cost of treatment beyond the purchase price of the medicine.
This reduces routine use where a safer effective alternative is available. Manufacturers can differentiate on formulation quality and clinical evidence, but cannot market the class as broadly risk-free. The economic ceiling for generic injectables partly reflects the need for disciplined prescribing rather than unlimited utilization.
Resistance and revised treatment standards change molecule selection
Aminoglycoside-modifying enzymes and ribosomal resistance mechanisms limit activity against certain pathogens. National and international guidelines evolve as better alternatives and new evidence appear, especially in drug-resistant tuberculosis, where older injectable drugs no longer dominate preferred treatment approaches. Historical use is therefore a poor guide to future volumes.
Companies concentrating on one molecule or indication face risk when susceptibility changes or practice standards move away from that therapy. Effective portfolio management requires product-specific epidemiology, not broad extrapolation from total bacterial infections.
Competitive tenders place pressure on established generic margins
Generic gentamicin, amikacin and selected tobramycin preparations are subject to hospital formularies, public procurement and equivalent-product competition. Tender concentration can encourage low bids and limit returns from small-volume presentations. Price competition may reduce the resources available to maintain redundant sterile capacity.
The challenge is compounded by differing container sizes and country labeling requirements. Suppliers with stable processes and larger distribution networks can spread fixed compliance costs, while smaller manufacturers may exit unattractive formulations.
Sterile supply disruptions create clinical and financial exposure
Injectable antibiotic manufacturing is sensitive to contamination events, quality deviations and interruption of filling or raw-material supply. When a hospital relies on a limited set of approved vendors, a shortage may require different presentations or treatment choices. Continuity planning is especially important for drugs used in severe infection.
Increasing capacity requires capital and validation time, but may not be rewarded in routine low-margin tenders. Buyers have reason to evaluate reliability alongside nominal unit cost, even when their purchasing processes have historically favored the lowest acceptable bid.
Specialty pulmonary access depends on reimbursement and label scope
Branded inhaled aminoglycosides can carry substantially higher per-patient expenditure than generic injections. Access is limited by authorized indications, payer criteria and specialist care requirements. Insmed’s accepted supplemental US application in September 2026 remained under review at the time of this report and cannot be treated as an already approved expansion.
Commercial forecasts are consequently sensitive to regulatory timing and the quality of post-approval evidence. A favorable study outcome can improve the case for treatment, but does not automatically convert every eligible patient into a reimbursed prescription.
Regional Outlook
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Asia Pacific: Broad patient base and expanding specialist capabilities
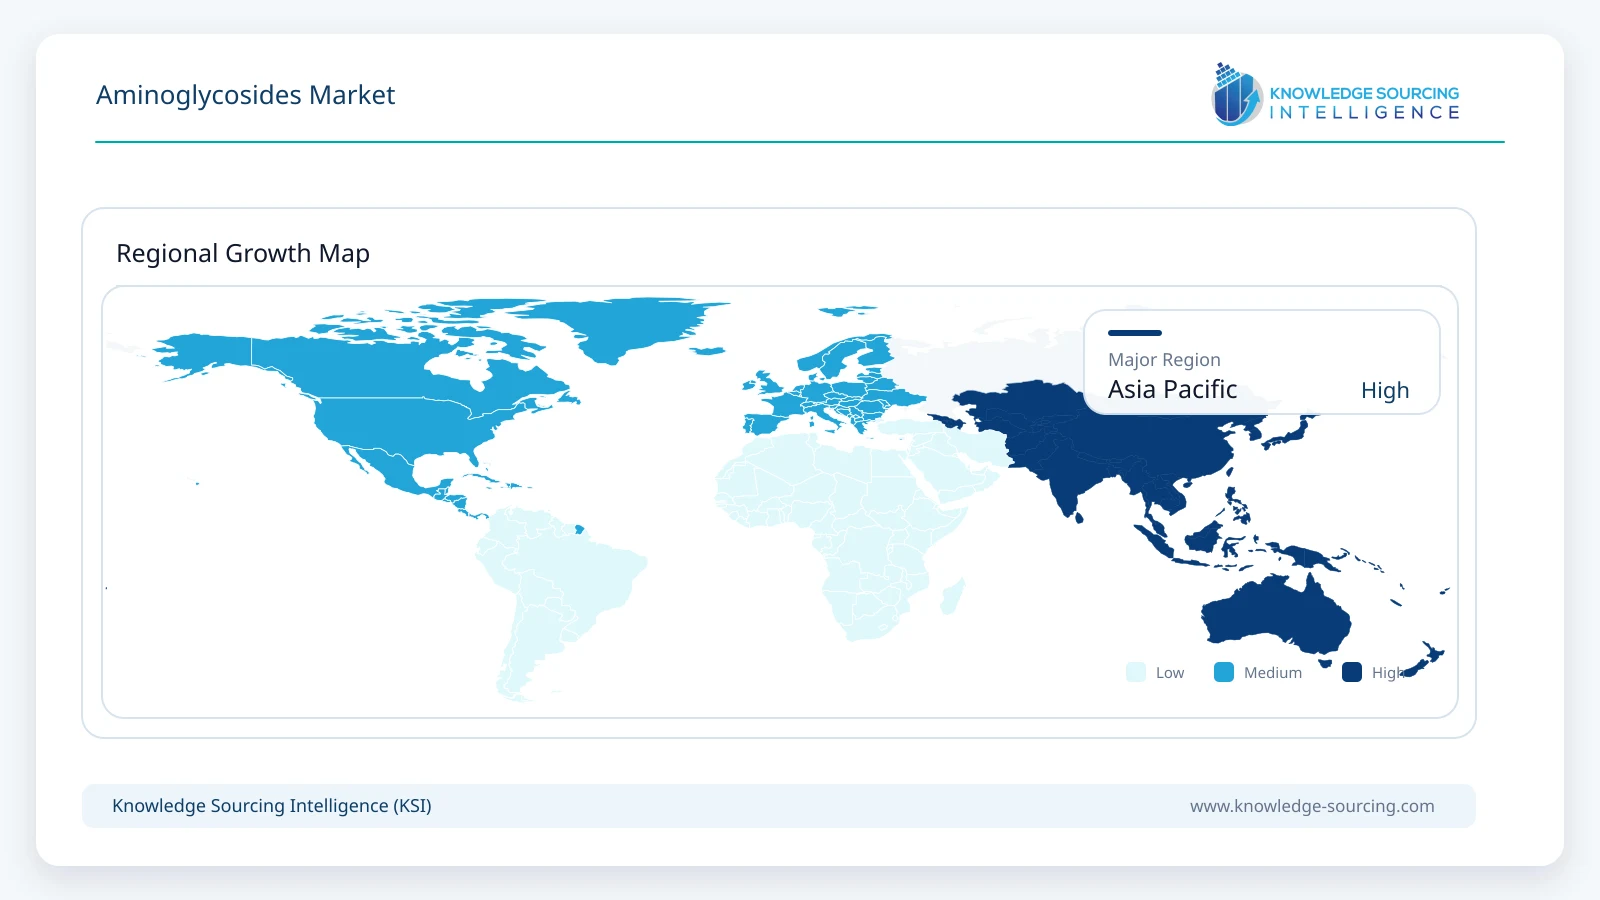
Asia Pacific is estimated to represent approximately 33% of the global Aminoglycosides Market in 2026, equivalent to USD 555.8 million. China, India and Japan together combine substantial medicine production, hospital antibiotic demand and specialized treatment settings. Manufacturers operate across different price tiers: conventional injections are exposed to procurement and generic competition, whereas specialty pulmonary products depend on diagnosis, approved indications and access to specialist physicians.
The region is projected to expand at approximately 5.0% annually through 2031, above the global average within the allocation. Rising hospital capacity and respiratory-care specialization support value growth, but stewardship and affordability will influence adoption. The epidemiology of drug-resistant tuberculosis should not be used to infer automatic growth in older injectable aminoglycosides; current therapeutic standards favor appropriate modern regimens.
North America: Higher-value inhalation therapies and rigorous stewardship
North America is estimated to account for approximately USD 488.5 million in 2026, with the US providing most specialty pharmaceutical revenue. Insmed’s ARIKAYCE business makes the region especially sensitive to clinical and regulatory decisions involving pulmonary MAC disease. The US also has an extensive generic supply chain for gentamicin and tobramycin preparations, with FDA-approved product listings and strict labeling requirements.
At an estimated 4.4% annual growth rate through 2031, the region retains a mature demand profile. Growth is supported by selected respiratory indications and dependable hospital purchasing rather than higher indiscriminate antibiotic use. FDA review timelines, formulary decisions and monitoring standards remain important commercial variables for branded and generic suppliers alike.
Competitive Landscape
Insmed occupies a distinctive commercial position through liposomal amikacin, which combines proprietary formulation, pulmonary clinical evidence and specialist reimbursement. Conventional hospital molecules are supplied by established pharmaceutical groups including Pfizer’s Hospira operation, Eugia and other generic manufacturers. Inhaled tobramycin has an established generic presence, including Teva and Dr. Reddy’s formulations, while Bausch + Lomb competes in ophthalmic aminoglycoside preparations. These portfolios vary by indication and route; they are not direct substitutes at the prescription level.
Pricing power follows the distinction between differentiated therapy and mature generics. Manufacturers of injections compete on product availability, dossier compliance and institutional tender terms. Branded products require ongoing evidence and market-access execution, and their revenues should not be extrapolated from generic consumption volumes. Clinical guidance, therapeutic monitoring and resistance patterns influence competition as strongly as production scale.
Recent Developments
14 October 2026: Insmed Incorporated announced new ARIKAYCE data presentations across CHEST 2026 and IDWeek 2026. The activity extended clinical communication of inhaled amikacin evidence; the announcement did not change the US-approved indication.
21 September 2026:Insmed Incorporated. The FDA accepted the supplemental application for ARIKAYCE and granted priority review, with a target action date of 28 January 2027. The proposed earlier-line indication was still under review.
6 August 2026: Insmed Incorporated reported second-quarter ARIKAYCE revenue of USD 116.3 million and maintained its full-year guidance of USD 450–470 million, providing an observable commercial anchor for inhaled amikacin.
23 March 2026: Insmed Incorporated reported positive topline Phase 3 b ENCORE results for ARIKAYCE plus background therapy in MAC lung disease. The clinical evidence supported further regulatory submission, not immediate expansion of the approved population.
Market Outlook
Through 2031, the class will continue to serve two contrasting revenue opportunities. Commodity parenteral and topical formulations should benefit from essential availability and hospital use where justified, but price competition and stewardship will restrict undifferentiated growth. Specialty inhaled amikacin and tobramycin products offer greater commercial value per eligible patient, supported by formulation complexity and clinical selection requirements.
The principal commercial winners will combine reliable manufacturing with credible evidence, distribution access and disciplined portfolio choices. For generic suppliers, resilience of sterile production may be more valuable than aggressive capacity expansion; for respiratory-focused manufacturers, regulatory decisions and specialist adoption will drive the next stage of market development.
Aminoglycosides Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 1.68 billion
Total Market Size in 2031
USD 2.05 billion
Forecast Unit
USD Billion
Growth Rate
4.06%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Product, Route Of Administration, Application, Geography