
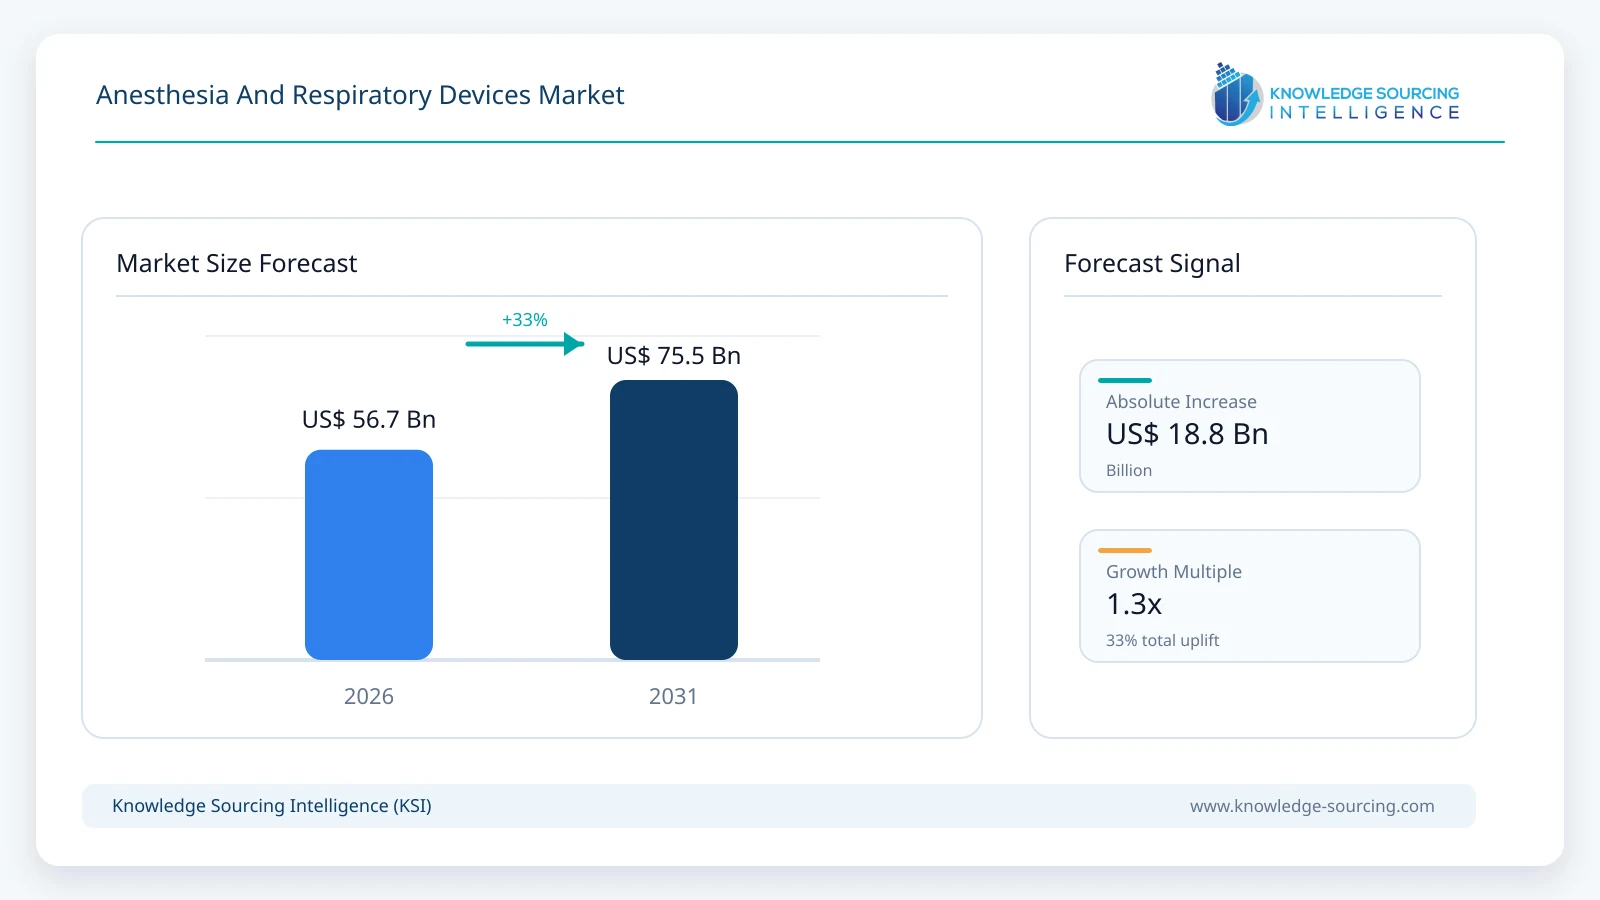
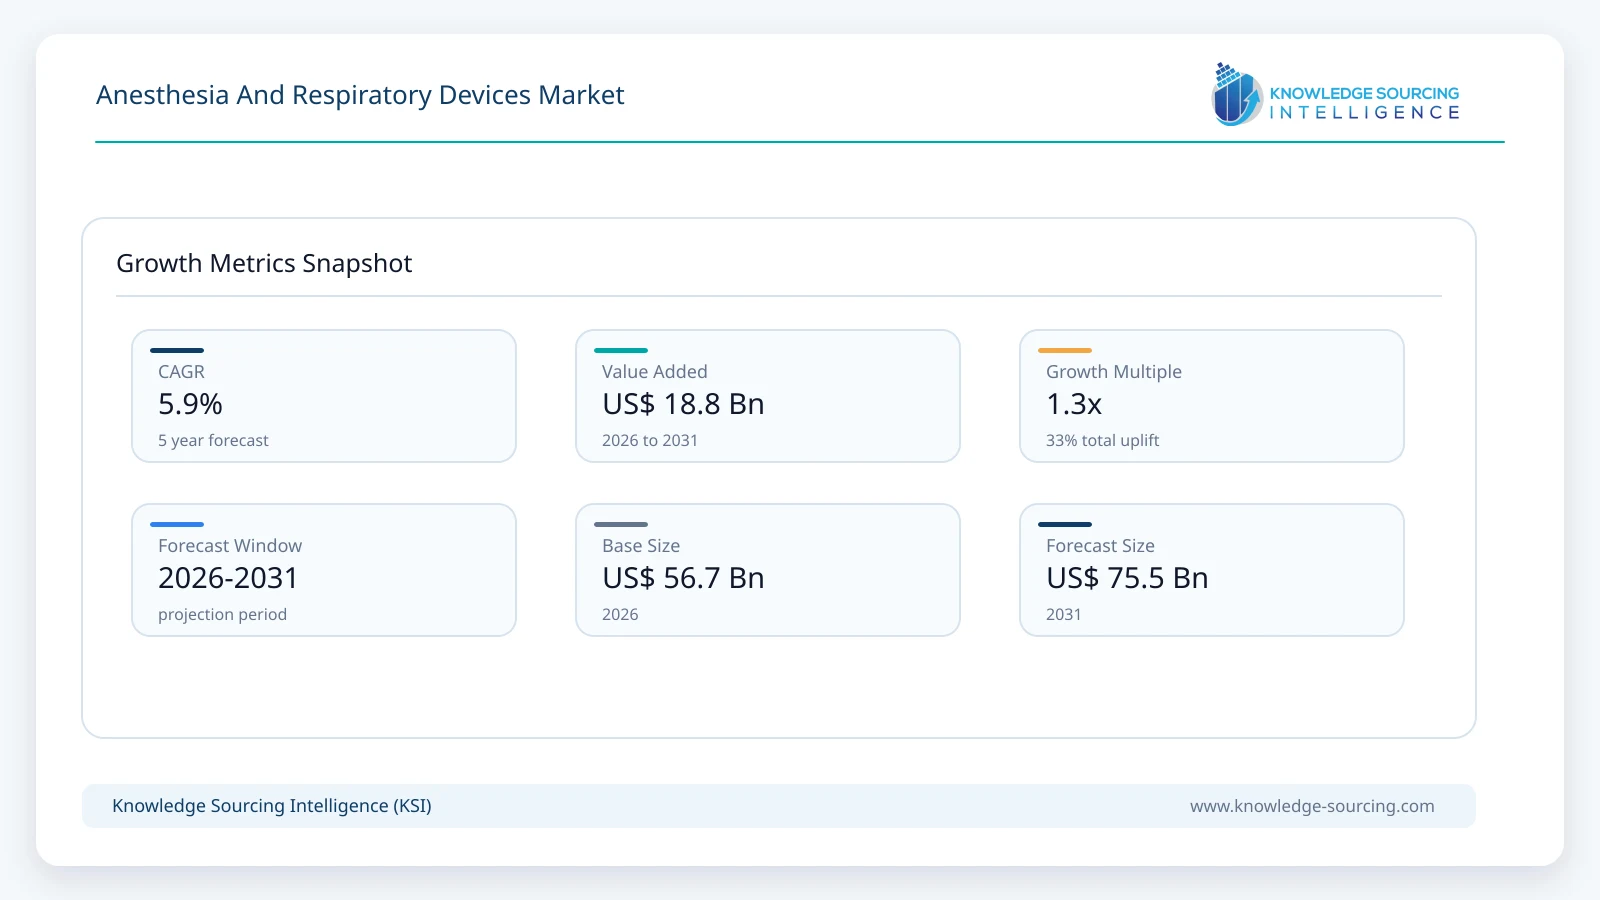
The Anesthesia and Respiratory Devices Market is projected to expand at a CAGR of 5.9%, increasing from USD 56.7 billion in 2026 to USD 75.5 billion by 2031.
Highlights:
- 1Respiratory equipment benefits from demand across intensive care, sleep therapy and chronic breathing disorders.
- 2Hospital purchasing increasingly links anesthesia machines with integrated monitoring, alarm management and gas efficiency.
- 3Homecare devices generate repeat demand for masks, interfaces, tubing and other respiratory consumables.
- 4Non-invasive ventilator replacement is supporting equipment competition among established acute-care suppliers.
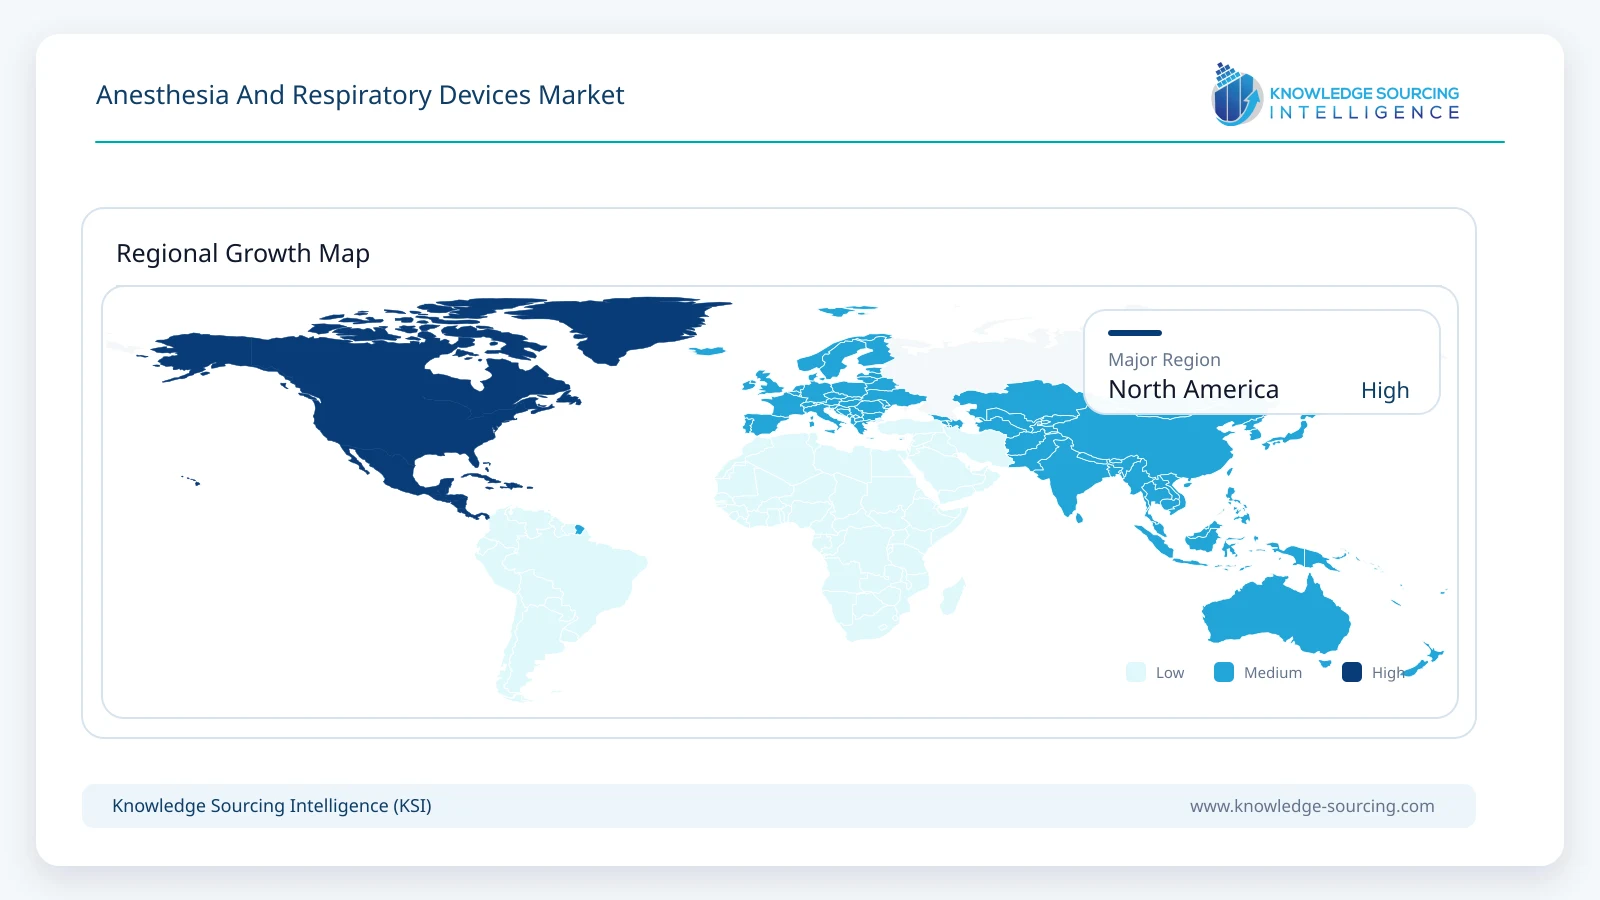
- 5North America leads in high-value respiratory technology purchasing; Asia Pacific is expanding treatment access.
- 6Regulatory clearance, product reliability and service continuity remain central to clinical procurement decisions.
The market covers anesthesia delivery machines, associated breathing circuits and disposables, respiratory therapeutic equipment, single-use respiratory accessories, and devices that measure ventilation and oxygenation. The product mix extends from integrated operating-room anesthesia workstations and intensive-care ventilators to positive-airway-pressure systems, oxygen concentrators, nasal interfaces, capnography and pulse-oximetry products. Procurement requirements are linked to where equipment is used: an anesthesia station must support controlled inhaled-agent delivery and intraoperative ventilation, while a home device must be comfortable, maintainable and practical for patients to use nightly.
In a hospital, ownership cost depends on servicing, calibration, equipment uptime, accessories, and staff familiarity as well as the purchase price. Anesthesia machines and complex ventilators undergo detailed technical review and regulated acceptance before deployment. In home respiratory care, masks, tubing, filters, and humidification components contribute to repeat purchases after the original device is installed. Measurement devices form another purchasing layer, providing oxygen-saturation, carbon-dioxide, and anesthesia-depth information to support clinical decisions. The links among these categories encourage integrated offerings but do not make every product interchangeable.
Growth is being supported by the burden of obstructive pulmonary disease, aging populations, expanded access to surgery and broader management of sleep-disordered breathing. Different conditions require different treatments: supplemental oxygen, non-invasive ventilation and CPAP cannot be treated as substitutes based only on their shared role in breathing support. Manufacturers with strong clinical evidence, dependable interfaces and established service networks are better positioned to convert demand into recurring revenue than companies competing solely on an additional monitoring feature.
Market Overview
Anesthesia and respiratory devices sit at a clinically sensitive intersection of ventilation, gas delivery and physiologic monitoring. The World Health Organization reported in June 2026 that chronic obstructive pulmonary disease caused approximately 3.4 million deaths in 2023, underscoring the need for sustained respiratory treatment and prevention of severe deterioration. Meanwhile, population aging is increasing the number of patients whose surgical or pulmonary care must accommodate multiple long-term conditions. These factors support capital renewal in hospitals and a larger installed base of treatment devices in homes, although reimbursement and clinical eligibility still determine adoption.
Equipment portfolios are becoming more segmented. GE HealthCare's Carestation 850 integrates advanced anesthesia ventilation and low-flow delivery capabilities within a workstation architecture, while Dräger's Atlan range emphasizes configurable gas mixing and ventilation. Mindray entered the North American acute-care ventilator market in March 2026 and subsequently introduced a non-invasive device in September. On the home-therapy side, ResMed continues to develop positive-airway-pressure systems and interfaces, while Fisher & Paykel Healthcare supplies hospital respiratory products and recurring consumables. Each strategy addresses a different decision-maker and clinical workload.
Measurement quality and patient interfaces have become equally important purchasing variables. Masimo's anesthesia-depth and respiratory-risk monitoring developments illustrate continued investment in sensing and algorithms, but a detection feature cannot replace clinical escalation procedures. In hospital departments, technology must fit with established electronic records, biomedical engineering schedules and infection-prevention practices. For home therapy, adherence often depends less on algorithm sophistication than on a mask that seals comfortably, an intelligible support process, and reliable equipment replacement.
Market Trends
Anesthesia Workstations Are Being Reconfigured Around Flexible, Low-Flow Care
Operating rooms are evaluating anesthesia machines for their ability to accommodate varying patient sizes and procedures while controlling volatile-agent consumption. New workstations pair electronic ventilation with a richer view of airway pressure, fresh-gas delivery, and patient monitoring. GE HealthCare's October 2025 Carestation 850 announcement highlighted adaptable applications and improved information display, while Getinge's integrated offering with Philips addresses the workflow between anesthetic delivery and bedside physiologic data.
These systems are not purchased simply for another operating mode. Hospitals have to demonstrate that staff can manage gas flows safely, follow emergency ventilation procedures and obtain dependable technical support. The opportunity for manufacturers lies in simplifying routine workflow without imposing switching costs that outweigh the value of newer interfaces.
Ventilator Replacement Is Creating Competition Beyond Pandemic-Era Demand
Critical-care customers are again differentiating ventilator purchases by ward use, clinical acuity and the training burden of replacing an established fleet. Mindray's March 2026 introduction of the SV900 and SV700 in North America, followed by the SV70 non-invasive ventilator in September, reflects a more application-specific commercial strategy. Replacement of withdrawn or aging ventilator platforms is an immediate procurement need for some providers, separate from the longer-term increase in treated respiratory disease.
A new ventilator must demonstrate dependable modes, intuitive alarms, familiar workflows and equipment service over many years. Buyers may accept a higher initial price when the product reduces fleet fragmentation, but competitive bids will increasingly consider consumable compatibility, software support and the time required to train respiratory therapists.
Home Respiratory Care Is Shifting Toward Connected Treatment and Mask Comfort
Continuous positive airway pressure and bilevel systems support long-term use rather than episodic intervention. Connectivity can help providers identify large leaks, low usage and therapy problems, but commercial success still depends on the patient accepting the interface each night. ResMed's fiscal 2026 reporting showed continued expansion of respiratory device and mask sales, with regional introductions of AirSense and AirCurve systems and newer full-face interfaces.
Manufacturers benefit from recurring accessories as an installed device ages, whereas insurers and home-care suppliers prioritize adherence, resupply logistics and technical support. Sleep devices with easy-to-use controls and comfortable masks may deliver more durable growth than incremental features that patients do not use.
Respiratory Monitoring Is Becoming More Predictive, but Clinical Oversight Remains Essential
Oxygen saturation and capnography remain basic safety measurements in respiratory and anesthetic care. Manufacturers are now using pattern recognition to identify trends that could warrant earlier clinical review. Masimo received CE marking for smartSedLine in August 2026 and subsequently reported an FDA-cleared smartSET expansion addressing physiological patterns including opioid-induced respiratory depression. These systems extend the role of sensing from simple display to monitored interpretation.
Clinical adoption requires carefully designed alerts, training, and evidence about the patients in whom algorithms perform reliably. Too many false alarms can add workload; poorly explained indicators can undermine confidence. Purchasers are therefore weighing workflow integration and reproducibility alongside sensor precision.
Disposable Interfaces and Infection-Control Economics Are Reshaping Supplier Revenue
A ventilator or anesthesia workstation often remains in use for years, but breathing circuits, filters, oxygen interfaces and some patient-contact sensors turn over far more frequently. This creates an equipment-plus-consumable business model with different margin and inventory characteristics. Fisher & Paykel Healthcare reported strong growth in hospital consumables for its financial year ended March 2026, even as respiratory admissions were relatively subdued in some major markets.
Hospital supply teams increasingly compare the lifetime cost of filters, humidification components and reprocessing with the unit price of the machine. Manufacturers with validated consumable compatibility and resilient distribution can secure recurring demand, although customers may resist proprietary accessories when they increase long-term expense.
Segment Analysis
By Products: Respiratory Equipment
Respiratory equipment represents a major purchasing pool because it spans intensive-care ventilators, oxygen-support products, and positive-airway-pressure systems rather than one procedure-specific platform. Products must be selected according to clinical acuity: a home CPAP device cannot take the place of a hospital ventilator, and a non-invasive ward ventilator has different monitoring and emergency requirements from a critical-care system. Mindray's 2026 SV-Series launches and ResMed's continuing sleep-therapy expansion reflect this differentiation across settings.
Respiratory equipment is estimated at approximately USD 19.27 billion in 2026. Replacement of installed systems, investment in high-acuity respiratory services and home treatment provide distinct revenue streams, while price realization is influenced by regulation and tendering. Suppliers that support the full device lifecycle, from initial configuration through patient interfaces and maintenance, are more likely to retain hospital and homecare relationships than hardware-only competitors.
By End-User: Hospitals
Hospitals account for the largest concentration of complex equipment because operating rooms, intensive-care units, emergency departments, and postoperative wards use different but overlapping ventilation and monitoring devices. Procurement committees balance clinical specifications with biomedical engineering support, infection control, and supply-chain resilience. Integrating anesthetic gas data with oxygenation and ventilation metrics can improve the clarity of clinical workflow, although staff must still be able to operate equipment safely if electronic interfaces fail.
Hospital purchases are estimated to represent USD 27.76 billion in 2026. The segment includes recurring device accessories as well as workstation replacement, so its value cannot be interpreted as capital expenditure alone. Ambulatory surgical centers remain a distinct end-user group, generally focusing on compact anesthesia systems and predictable procedural turnover, while homecare depends more heavily on long-term adherence and patient support.
Market Drivers
A Larger Burden of Chronic Respiratory Disease
Chronic obstructive pulmonary disease and other severe breathing conditions produce recurring demand for oxygen therapy, ventilatory support and clinical monitoring. The need extends across exacerbations treated in hospital and more stable conditions managed through outpatient or homecare pathways. WHO's 2026 COPD assessment highlights a persistent global disease burden, although treatment need does not automatically convert into a particular equipment purchase.
Manufacturers benefit when health systems add respiratory care capacity and expand eligible treatment access. The most successful commercial programs combine clinical education, equipment availability, and reliable servicing rather than relying only on disease prevalence.
Health-System Investment in Surgical Capacity
More operating rooms and specialized day-surgery facilities require anesthesia workstations, airway supplies, and monitoring systems. Even an existing hospital may need replacements when a growing procedure mix demands different ventilation and gas-delivery performance. Integration between anesthesia machines and physiologic monitoring, as illustrated by the Getinge–Philips workstation collaboration, can support more consistent staff workflows.
Purchasing cycles are affected by capital approvals, renovation schedules, and surgeon availability, making demand uneven across years. Manufacturers with flexible configurations can address both large tertiary hospitals and smaller surgical sites without treating them as identical buyers.
Demographic Aging and Greater Perioperative Complexity
Older patients often present with multiple comorbidities that make ventilation, oxygenation and recovery monitoring more demanding. The World Health Organization expects the population aged 60 or over to reach approximately 1.4 billion by 2030. Greater clinical complexity can justify more advanced anesthesia delivery and monitoring, particularly when patients require careful lung-protective ventilation or postoperative observation.
This is a quality-of-care driver as much as a volume driver. Equipment suppliers must demonstrate that their technologies support clinicians in managing difficult cases rather than merely advertise the additional number of available settings.
Greater Access to Long-Term Sleep and Breathing Therapy
Treatment of obstructive sleep apnea creates a durable equipment and consumables market because patients may require nightly therapy over many years. ResMed's connected-device platforms illustrate how treatment management can combine device use, patient coaching, and periodic mask replacement. Healthcare systems can expand therapy access through outpatient sleep diagnostics, durable-medical-equipment channels and home support.
Affordability, reimbursement, and patient willingness to maintain treatment govern realized sales. Devices that are too difficult to maintain or uncomfortable to wear can experience weak adherence even where the need for care is well established.
Monitoring Innovation and Replacement of Installed Equipment
Respiratory care teams increasingly seek dependable detection of hypoxemia and other signs of deterioration across perioperative and general-care settings. Masimo's developments in pulse oximetry and anesthesia-depth monitoring add functionality to an established sensing category, while 2026 ventilator launches create opportunities for replacing aging critical-care fleets. Regulatory clearance can support purchasing confidence, although it does not establish superiority in every patient group.
Hospitals frequently choose suppliers according to deployment support, compatibility with established workflows and the cost of maintaining a fleet. That favors manufacturers offering strong field-service networks and stable consumable availability.
Market Restraints
High Lifecycle Cost of Complex Workstations
The price of an anesthesia machine or intensive-care ventilator is only one part of its full ownership cost. Hospitals must fund preventive service, calibrations, replacement components, patient circuits, staff training, and periodic software updates. In markets with constrained capital budgets, this can delay fleet renewal despite demonstrated clinical need.
Integrated platforms may simplify daily operation, but can also lock hospitals into more expensive service arrangements or proprietary consumables. Procurement teams increasingly evaluate five- to ten-year service obligations alongside technical performance and installation cost.
Device Safety Corrections and Regulatory Scrutiny
Anesthesia and respiratory products perform critical functions where a device fault can cause rapid clinical deterioration. The FDA's 2026 recall records covering certain Dräger Atlan workstations illustrate the importance of manufacturing change control and prompt field correction. Such events increase the attention paid to reliability evidence, risk management and service documentation across all suppliers.
A regulatory clearance or launch announcement should not be interpreted as a guarantee of permanent fault-free performance. Hospitals must maintain backup ventilation procedures and assess corrective-action history during equipment selection.
Reimbursement and Home-Therapy Adherence Gaps
A patient may be clinically eligible for positive-airway-pressure therapy without being able to obtain or sustain treatment. Insurance coverage, diagnostic access, replacement-mask policies, and copayments differ among countries and payers. Inadequate mask fit or poor training can reduce usage, undermining outcomes and slowing expansion through homecare channels.
Manufacturers and distributors have to invest in patient onboarding and resupply support. A connected platform can identify some adherence problems, but it cannot eliminate the effects of affordability, discomfort, or inadequate clinical follow-up.
Workforce Shortages and Uneven Clinical Training
Hospitals need qualified anesthetic staff, respiratory therapists, and biomedical engineers to make productive use of advanced devices. A sophisticated ventilator can add complexity if workflows differ across departments or if users are unfamiliar with alarm and ventilation settings. Training becomes particularly costly when a health system operates many generations of equipment.
Device suppliers therefore compete partly on clinical education, interface consistency, and service response. In smaller facilities, limits on specialist staff can outweigh the theoretical benefits of high-end technology.
Supply Chain, Consumable Compatibility and Price Pressure
Respiratory treatment relies on predictable availability of masks, filters, breathing circuits, oxygen interfaces and sensors. Product shortages or changes in specifications can disrupt care even when the primary machine remains functional. Hospital tenders and public reimbursement often constrain the prices manufacturers can charge, while sterilization and packaging requirements raise production costs.
Compatibility questions can prevent customers from switching suppliers or force them to maintain multiple consumable inventories. Companies that provide standardization and transparent lifecycle economics can defend contracts more effectively than those depending on equipment pricing alone.
Regional Outlook
North America: High-Value Equipment and Home Respiratory Demand
The United States has a substantial installed base of operating-room equipment, critical-care ventilation, oxygenation monitors, and home sleep-therapy devices. Replacement cycles are influenced by hospital procurement, FDA clearance requirements, and established reimbursement channels for durable medical equipment. Mindray's 2026 ventilator launches target this environment, where health systems may have to replace withdrawn or aging products while preserving staff training and familiar clinical workflows. Masimo's monitoring innovations also reflect demand for higher-value sensing within operating and postoperative care.
North America is estimated to account for around 37% of market revenue in 2026, equivalent to USD 20.97 billion. The region's principal advantage is the depth of clinically specialized purchasing, but pricing pressure and regulatory scrutiny influence equipment choices. Canada and Mexico provide additional demand through hospitals and expanding respiratory services, though procurement systems and private reimbursement differ materially from the United States.
Asia Pacific: Expansion Through Clinical Capacity and Treatment Access
China, India, Japan, South Korea, Indonesia and Thailand represent diverse demand profiles. Japan and South Korea have established acute-care infrastructure and aging patient populations, while India and Southeast Asia are adding surgical capacity and widening access to diagnostics and respiratory treatment. Modern anesthesia workstations, non-invasive ventilation and oxygen support can be commercially attractive, but buyers vary in their ability to fund maintenance, accessories and specialized clinical training.
Asia Pacific is estimated to record the fastest regional expansion, at approximately 8.9% CAGR through 2031. Growth is supported by investments in hospital capacity and adoption of home respiratory therapies, although it is unlikely to follow a uniform trajectory across countries. Suppliers with local distribution, clinician training and spare-parts support are better positioned than vendors offering only an imported equipment catalogue.
Competitive Landscape
The competitive field separates into three overlapping groups. GE HealthCare, Dräger, Getinge and Mindray concentrate on hospital anesthesia or critical-care platforms, where service capacity, safety and control systems are substantial differentiators. ResMed and Fisher & Paykel Healthcare have extensive exposure to respiratory therapy and consumables, including long-term patient interfaces. Masimo competes in measurement and patient-monitoring technologies, while Medtronic, Teleflex, ICU Medical and other suppliers participate through ventilation, airway management or disposable product portfolios.
Market positions should be judged by product-specific revenue and clinical deployment rather than a company's total healthcare turnover. Manufacturer integrations, channel partnerships and corporate ownership add complexity. Masimo became a Danaher subsidiary in June 2026, while Smiths Medical products belong to ICU Medical following an earlier acquisition. Buyers increasingly favor suppliers that can support equipment and consumable lifecycles, preserve interoperability and deliver training across their installed base.
Recent Developments
17 October 2026: Masimo expands smartSET physiological monitoring. Masimo reported FDA clearance of an atrial-fibrillation detection capability for Radius VSM alongside an earlier cleared respiratory-depression detection feature. The development extends continuous oxygenation monitoring toward earlier risk identification while retaining the need for clinical confirmation and escalation.
15 September 2026: Mindray launches SV70 non-invasive ventilator in North America. Mindray introduced the SV70 to address non-invasive ventilation requirements and replacement of existing hospital equipment. The launch broadens its ventilator portfolio after its March entry into the North American critical-care ventilator market.
18 August 2026: Masimo secures European CE marking for smartSedLine. Masimo announced CE marking for an AI-powered brain-function monitoring system designed to support anesthetic management. The product adds a differentiated monitoring layer to the perioperative device market, rather than replacing anesthesia delivery equipment.
26 May 2026: Fisher & Paykel Healthcare reports growth in respiratory consumables. The company reported fiscal-year revenue of NZD 2.31 billion, with hospital-product revenue reaching NZD 1.51 billion. Its hospital consumables expansion illustrates the recurring revenue associated with respiratory therapy interfaces and humidification products.
21 May 2026: Dräger obtains US clearance for Atlan anesthesia machines. The FDA recorded a substantial-equivalence decision for the Atlan A100/A100 XL and A350/A350 XL variants. The regulatory milestone concerns specific anesthesia workstations and must be distinguished from clinical evidence of superiority over alternatives.
9 October 2025: GE HealthCare unveils Carestation 850 anesthesia platform. GE HealthCare introduced its next-generation workstation emphasizing adaptable ventilation, data visualization, and low-flow practices. The company stated at the announcement that FDA clearance was pending, while European and Australian authorization had been received.
Market Outlook
The commercial balance is moving toward a wider separation between long-lived hospital equipment and recurring respiratory treatment supplies. In operating rooms, integrated workstation capabilities, energy-efficient anesthetic delivery and intuitive alarm systems will determine the attractiveness of capital upgrades. Respiratory therapy manufacturers will continue to compete across high-acuity ventilation, non-invasive support and long-term home treatment, with distribution and service capacity playing a decisive role in realized market growth.
Device manufacturers will find stronger opportunities where they can demonstrate consistent clinical performance and limit the workload associated with use, maintenance and replacement. Connected home therapy and predictive monitoring offer additional differentiation, but their commercial value depends on valid clinical evidence, secure data handling and the patient or clinician actually acting on the information produced. In mature regions, replacement spending should remain significant; in expanding healthcare systems, first-time access to respiratory and perioperative technology will carry greater weight.
Anesthesia And Respiratory Devices Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 56.7 billion |
| Total Market Size in 2031 | USD 75.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Products, End-User, Geography |
| Companies |
|
Market Segmentation
By Products
Anaesthesia Machines
Anesthesia Disposables
Respiratory Equipment
Respiratory Disposable Devices
Respiratory Measurement Devices
By End-user
Hospitals
Ambulatory Surgical Centers (ASCs)
Homecare Settings
Clinics and Diagnostics Centers
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Chronic Respiratory Disease Burden
3.1.2. Investment in Surgical Capacity
3.1.3. Aging and Perioperative Complexity
3.1.4. Access to Long-Term Respiratory Therapy
3.1.5. Monitoring and Equipment Renewal
3.2. Market Restraints
3.2.1. High Lifecycle Equipment Cost
3.2.2. Safety and Regulatory Compliance
3.2.3. Reimbursement and Adherence
3.2.4. Training and Workforce Shortages
3.2.5. Consumable Supply and Compatibility
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Lung-Protective Ventilation and Control
4.2. Low-Flow Anesthesia Systems
4.3. Connected Positive-Airway-Pressure Therapy
4.4. Advanced Oxygenation and Capnography
5. ANESTHESIA AND RESPIRATORY DEVICES MARKET BY PRODUCTS
5.1. Introduction
5.2. Anaesthesia Machines
5.3. Anesthesia Disposables
5.4. Respiratory Equipment
5.5. Respiratory Disposable Devices
5.6. Respiratory Measurement Devices
6. ANESTHESIA AND RESPIRATORY DEVICES MARKET BY END-USER
6.1. Introduction
6.2. Hospitals
6.3. Ambulatory Surgical Centers (ASCs)
6.4. Homecare Settings
6.5. Clinics and Diagnostics Centers
7. ANESTHESIA AND RESPIRATORY DEVICES MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. GE HealthCare Technologies Inc.
9.2. Drägerwerk AG & Co. KGaA
9.3. Getinge AB
9.4. Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
9.5. ResMed Inc.
9.6. Fisher & Paykel Healthcare Corporation Limited
9.7. Koninklijke Philips N.V.
9.8. Masimo Corporation
9.9. Medtronic plc
9.10. ICU Medical, Inc.
9.11. Teleflex Incorporated
9.12. Hamilton Medical AG
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











