
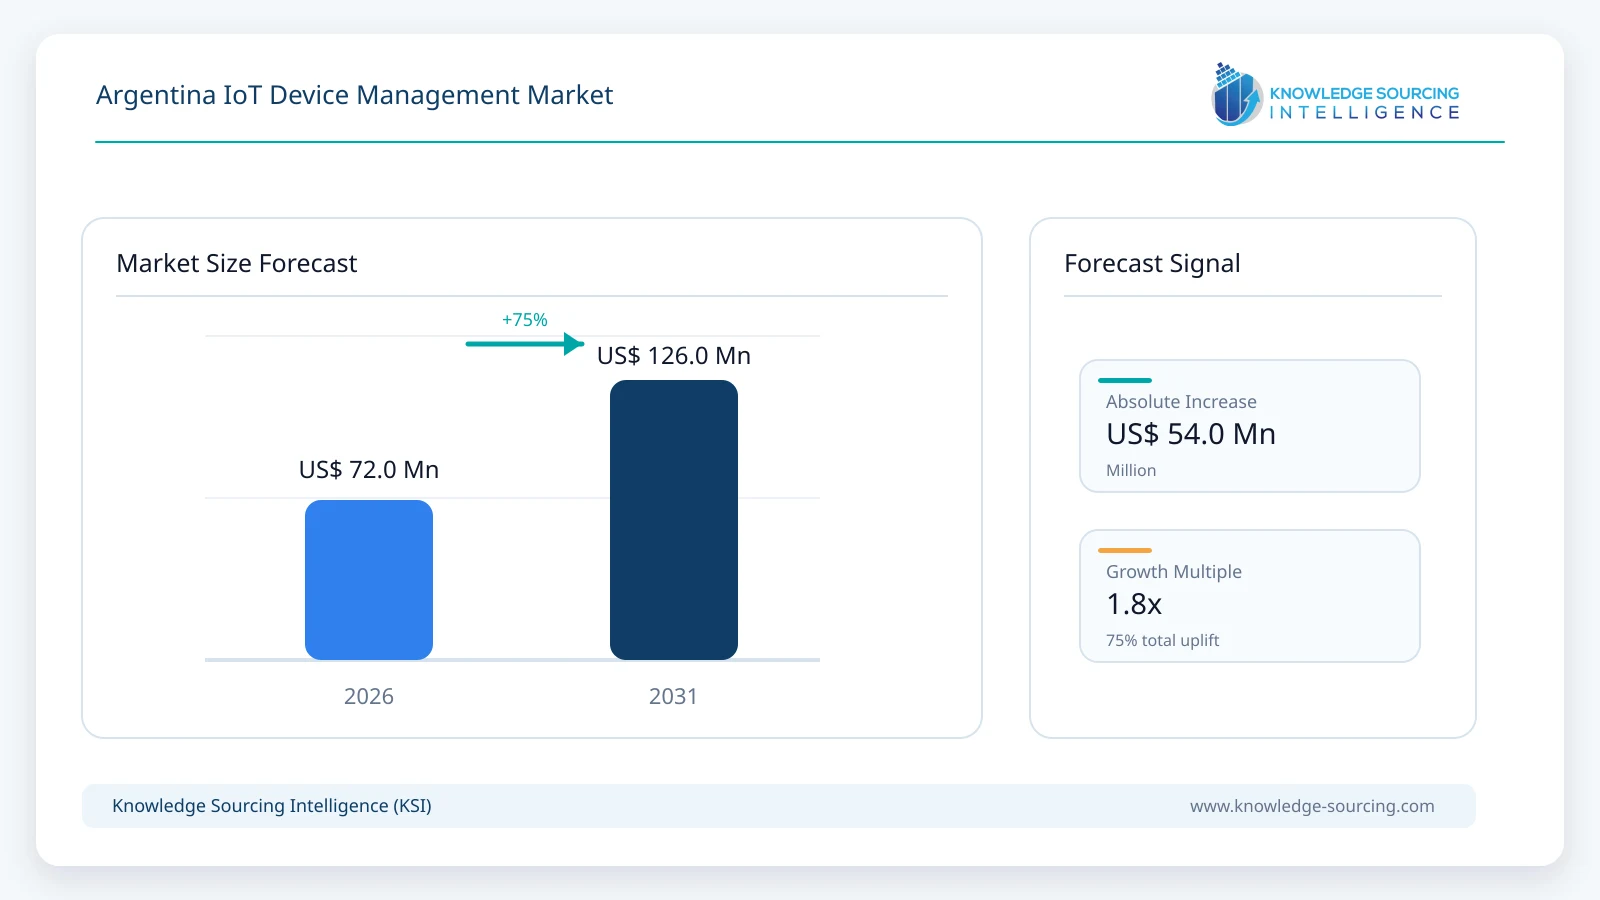
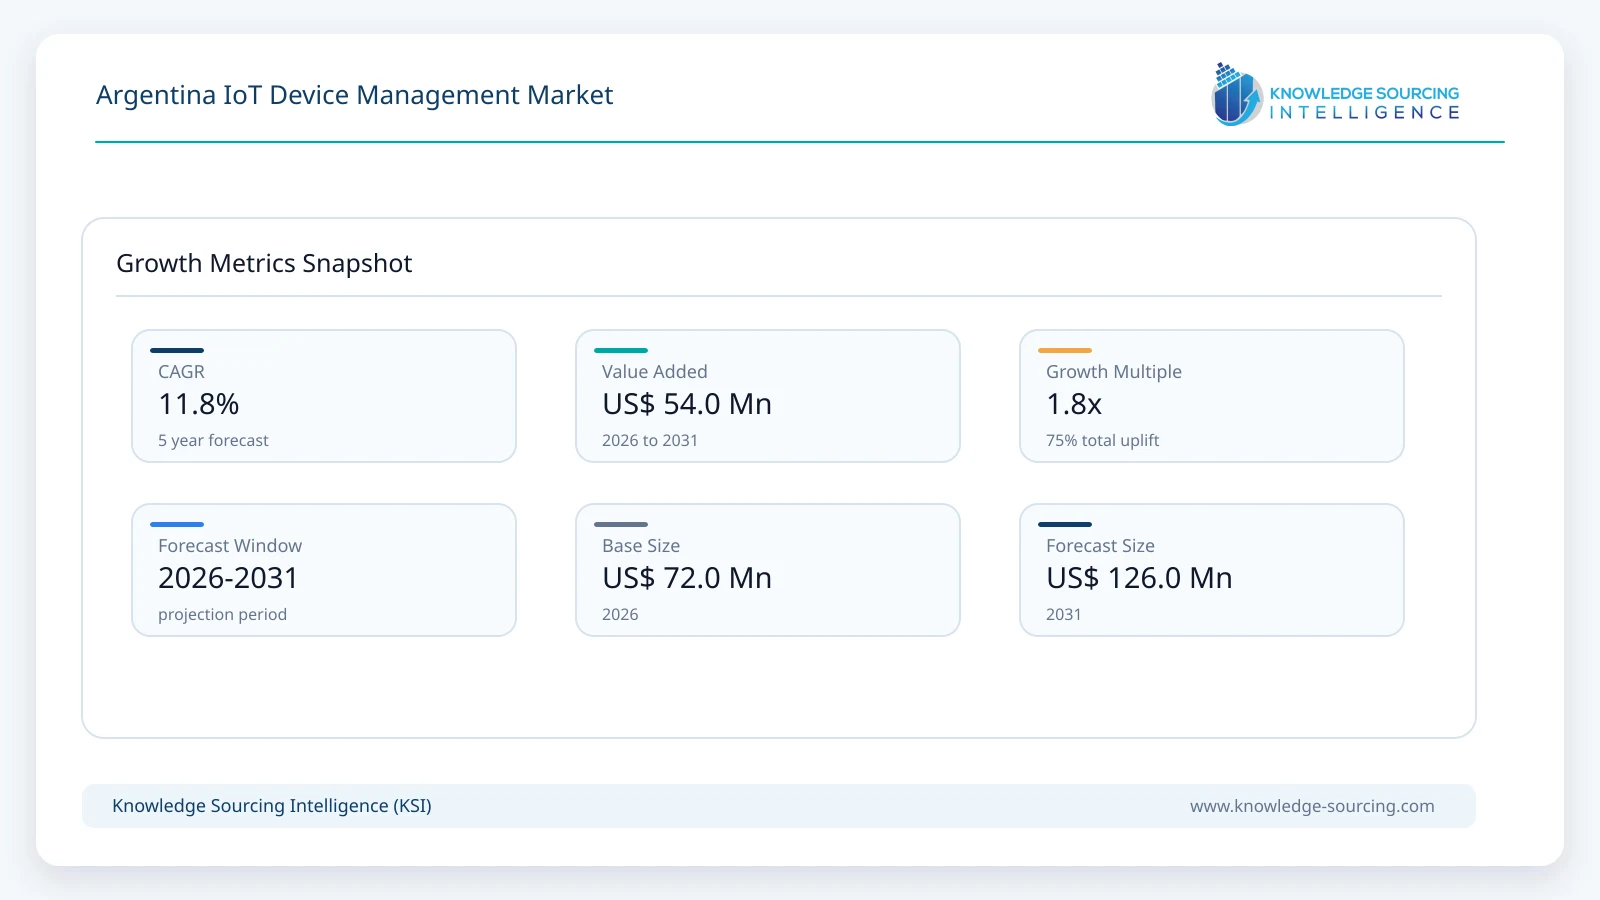
The Argentina IoT Device Management Market is projected to expand at a CAGR of 11.84%, reaching USD 126.0 million in 2031 from USD 72.0 million in 2026.
Highlights:
- 1Cellular-managed fleets lead spending as logistics providers and utilities supervise dispersed assets.
- 2Remote monitoring is the largest solution function, serving uptime-sensitive equipment and field operations.
- 3Hybrid deployment gains traction where industrial sites require local control alongside centralized policy management.
- 4Connected logistics supplies a major application pool through tracking, cold-chain visibility and vehicle telemetry.
- 5Buenos Aires and the capital anchor enterprise procurement; Córdoba expands on manufacturing and agricultural adoption.
IoT device management covers software and attributable services used to register, authenticate, configure, monitor, update, and retire connected endpoints. Argentine customers purchase the capability through cloud platforms, industrial edge software, fleet-management services and managed enterprise contracts. A device's communications subscription, physical sensor or generic data warehouse does not automatically constitute management revenue; the commercially relevant service is control of the endpoint throughout its operating life.
Personal Tech markets IoT connectivity, SIM management, asset traceability, and professional IoT services in Argentina. International suppliers provide complementary layers: AWS offers fleet indexing, jobs and secure remote operations; Microsoft's IoT Hub and Device Registry support provisioning and device administration; Telit Cinterion's deviceWISE covers industrial edge and cloud management. Demand follows qualifying fleet deployments and the complexity of operating them, rather than aggregate mobile-phone subscriptions.
Market Overview
Telecom Argentina's Personal Tech portfolio combines IoT connectivity with SIM management, telemetry, traceability and professional services for corporate customers. Its 2025 annual filing also describes managed LPWAN connectivity, smart-city projects and integrated industrial offerings. These activities point to a recognizable local market for endpoint administration, although not all revenues from a connected-device contract belong to device management. The customer pays for sustained control of devices, credentials and software configurations, while sensor hardware, data traffic and business-application analytics remain separate economic activities.
Argentina's connectivity infrastructure offers a widening base for those services. ENACOM recorded 64.28 million mobile accesses in the second quarter of 2026 and 3,206 operational 5G sites, while Telecom Argentina reported that machine-to-machine subscriptions were contributing to postpaid growth in its June 2026 results. Neither statistic measures paying device-management endpoints directly. They indicate stronger communications availability and enterprise uptake, which can support management platforms when customers have a defined need for provisioning, policy administration, device status, and remote maintenance.
Industrial buyers do not necessarily standardize on one vendor. A transport company may combine a carrier's SIM portal with a specialist vehicle-tracking system; a manufacturer may retain local control gateways while centralizing credentials and firmware releases in the cloud. AWS's metered fleet operations, Azure's managed device architecture and Telit's industrial integration offerings illustrate different contractual models. Procurement therefore depends on integration with existing operational systems, dependable offline behavior, and the ability to establish who is responsible for a device fault.
Market Trends
Remote Firmware Control Is Becoming a Core Fleet Requirement
Firmware updates and configuration corrections increasingly need to reach devices that are already installed on vehicles, pumps, agricultural equipment, and industrial gateways. AWS IoT Device Management supports remote jobs, controlled deployment velocity, and software-package tracking, while Memfault provides staged firmware releases with fleet-health visibility. For Argentine operators with assets scattered across provinces, the avoided service visit can be more economically important than the marginal cloud charge associated with an update.
Production implementations still require a disciplined fallback design. Failed updates, intermittent cellular access, and limited device memory can leave equipment unavailable unless the operator manages rollout cohorts, recovery images, and device-specific compatibility. Providers that combine firmware distribution with post-release diagnostics are positioned to capture more of a recurring management budget than suppliers offering a basic status dashboard alone.
Cloud Registries Are Being Linked More Closely to Industrial Edge Systems
Microsoft's September 2026 guidance for Azure IoT Central users directs future deployments toward IoT Hub, Device Provisioning Service and, where applicable, Azure Device Registry. Its stated transition timetable gives existing installations until September 2029, making migration planning a concrete commercial issue for enterprises already using the managed application. This is a vendor roadmap change, not evidence that Argentine users have migrated en masse.
Industrial plants have different operating conditions from consumer-device networks. Telit Cinterion's deviceWISE links plant-floor protocols and operational systems with cloud services, enabling manufacturers to maintain local control while extending remote visibility. A hybrid architecture can avoid dependence on continuous cloud access for immediate machine functions, but it increases the need to coordinate identities, software versions and permissions across sites.
Device Security Is Moving into Routine Lifecycle Operations
Deployments containing payment terminals, medical equipment, industrial gateways and location trackers require administrators to know which firmware is running, whether credentials remain valid and when devices should be retired. Microsoft's April 2026 refresh of Azure Device Registry preview included automated certificate-renewal functions, while AWS has expanded device-connectivity diagnostics. These functions support security operations through administration and traceability rather than replacing specialized cybersecurity tools.
Argentina's Personal Data Protection Law 25,326 is relevant where device telemetry identifies individuals or reveals sensitive personal activity. The law does not universally require the purchase of a separate IoT-management platform. Buyers instead need to implement appropriate access, data-handling and recordkeeping arrangements within the technology stack they use, particularly when location or health information passes between devices and external services.
Connectivity Diversity Requires a More Consistent Control Layer
Cellular connections are central to remote fleet and field-device management, but factories and buildings also operate Wi-Fi, Bluetooth and low-power wide-area networks. Satellite links can serve selected rural assets where terrestrial coverage is unsuitable. Device managers must therefore reconcile different connection states, sleep patterns and command-delivery methods rather than assume that every endpoint responds continuously to cloud requests.
For agricultural logistics and energy installations, delayed synchronization is often preferable to a design that fails outright after a network interruption. The competitive advantage lies in retaining enough local device state to queue commands, verify completion and diagnose failures once a connection resumes. That requirement favors platforms with protocol flexibility and reliable event histories over interfaces built solely for high-bandwidth, always-online devices.
Fleet Data Is Being Used to Prioritize Maintenance, Not Just Monitor Assets
Telematics platforms are combining location, equipment-state data and remote configuration with maintenance workflows. Personal Tech lists fleet tracking, cold-chain monitoring, industrial telemetry and utility-resource management among its enterprise use cases. Management revenue comes from the ability to supervise endpoints, correct settings and preserve service availability; the separate sale of logistics optimization software or general analytics should not be added again to that same pool.
Manufacturers are also looking to use device-health signals before scheduling on-site service. Better visibility can shorten fault diagnosis, but benefit depends on telemetry quality, device identity, and effective integration into an existing maintenance system. Providers with repeatable connectors to enterprise and operational software can justify longer-term contracts as device fleets grow beyond pilot scale.
Segment Analysis
By Component: Solutions: Remote Monitoring
Remote monitoring is estimated to account for USD 16.5 million of Argentina's 2026 device-management market, making it the largest solution function within the retained component taxonomy. Fleet operators, utilities and industrial users need to distinguish an offline device, a failing sensor and a loss of network coverage without dispatching a technician for each exception. Personal Tech offers telemetring and asset monitoring, while cloud-platform vendors supply device-state records, grouped monitoring and remote commands.
The solution category also includes security, network bandwidth, data management and streaming-analysis functions; expenditure is allocated to a primary purchased function when contracts combine several capabilities. Managed services and professional services are measured separately only where the buyer pays for administration or implementation in addition to the underlying software entitlement.
By Deployment: Public Cloud
Public cloud deployment supports centralized provisioning, asset inventories and remote support across dispersed installations. AWS prices fleet-management activities by metered functions, while Microsoft's cloud services can connect provisioning and device registries to operational workloads. For smaller fleets, this reduces the need to maintain a dedicated management environment; larger buyers may still seek contract controls over access, availability and the location of sensitive data.
The public-cloud segment is projected to reach USD 65.0 million by 2031 as more devices become manageable through standard APIs and shared service infrastructure. Nevertheless, industrial control networks with strict local-response needs often keep operational execution at the edge even when inventory, certificates and policy administration are centralized. That distinction explains continued spending on hybrid and private configurations.
By Connectivity: Cellular
Cellular-linked fleets represent approximately 43.1% of 2026 device-management spending, reflecting the prominence of connected vehicle units, remote meters, security equipment and field-service assets. Telecom Argentina's 2026 filing identifies M2M connections as a source of postpaid subscriber growth, while its enterprise IoT offering includes SIM administration and remote monitoring. Cellular is not counted as management revenue unless a device-control function is separately attributable.
LPWAN remains important for battery-operated metering and agriculture sensors, while Wi-Fi and Bluetooth support building and plant devices. Satellite-linked systems have a smaller management base and frequently use intermittent communications, so their software and support costs cannot simply be priced as though every remote endpoint maintained a permanent terrestrial connection.
By Application: Connected Logistics
Connected logistics is modeled at USD 35.0 million in 2031, supported by tracking devices on freight vehicles, temperature-monitored shipments and equipment moving between farms, warehouses and ports. The management requirement is broader than locating an asset: operators must validate device identity, maintain firmware, replace failed hardware records and oversee communications when a load crosses service areas.
Personal Tech's commercial portfolio addresses traceability and cold-chain monitoring, illustrating the link between connectivity and lifecycle services. Device-management vendors compete on integration with transport applications and reliable command execution under uneven coverage. Analytics sold for route planning or inventory management are outside this segment unless an identifiable share pays for managing the connected endpoints themselves.
By End-User: Transportation
Transportation remains the leading end-user segment, accounting for about 23.6% of modeled 2026 demand. Freight fleets, passenger-service operators and logistics contractors operate devices that can be physically inaccessible for extended periods, increasing the value of remote fault diagnosis and staged configuration changes. Vehicle gateways, trackers and refrigeration monitors create distinct device records that require supervision across deployment, replacement and retirement.
Industrial manufacturing is another substantial purchaser, especially for plants consolidating shop-floor sensors and gateways. The same logistics installation is assigned to the transportation end-user dimension and to connected logistics in the application dimension; these are alternative views of the same revenue, not additive markets.
Market Drivers
Growth in Managed Cellular and M2M Fleets
Telecom Argentina disclosed that M2M services contributed to postpaid customer growth in its June 2026 reporting period. The finding matters for lifecycle-management demand because each corporate deployment creates work beyond activating a SIM: devices must be identified, assigned to customers, monitored and sometimes reconfigured remotely. Operators gain the most recurring value from management services when a fleet is geographically dispersed and failures cannot be resolved cheaply on site.
Industrial Equipment Modernization
Plants adopting connected gateways and machinery monitoring need consistent device inventories across equipment of different ages and brands. Telit Cinterion's deviceWISE supports common industrial interfaces, including PLC and CNC protocols, and can connect plant equipment to enterprise systems. The market opportunity lies in provisioning, monitoring and maintaining that device layer rather than attributing all industrial AI or factory-automation spending to IoT management.
Logistics and Agricultural Asset Traceability
Argentina's export supply chains cover substantial distances between productive areas, consolidation centres and ports. Personal Tech markets solutions for asset traceability, fleet management and cold-chain monitoring, each of which requires a reliable endpoint layer when deployed at scale. A device manager that can preserve status history and coordinate replacements has a clearer purchasing justification than an isolated telemetry interface.
Demand for Remote Maintenance and Firmware Updates
Managing a fleet from one console reduces the need to visit each installed device when certificates, configurations or software versions change. AWS fleet jobs and Memfault's monitored over-the-air deployment functions show how suppliers commercialize the capability. The saving is greatest in remote utilities, refrigeration assets and agricultural installations where travel time and operational interruption are substantial relative to the device cost.
Stronger Attention to Device Identity and Auditability
Corporate buyers managing connected health or location data require reliable controls over identities, permissions and administration records. Microsoft is extending the Azure IoT device-management architecture with registry and certificate capabilities, while Argentina's Law 25,326 governs applicable personal-data processing. Security requirements improve demand for auditable management functions, although regulatory compliance alone does not determine a particular platform purchase.
Market Restraints
Connectivity Gaps and Intermittent Device Access
Remote equipment in agricultural and sparsely populated areas may face variable terrestrial coverage and long periods without a usable data session. Fleet software must queue commands, reconcile device status and tolerate delayed acknowledgements, which adds implementation effort. Satellite or LPWAN options can serve some applications but may have payload and power limits that restrict frequent diagnostics or large firmware transfers.
Industrial Integration and Legacy Protocols
Industrial buyers often operate controllers and instruments installed across several equipment generations. Connecting a cloud device registry to plant-floor systems can require protocol translation, security-zone design and testing around production downtime. Vendors able to support existing control equipment gain an advantage, but the initial engineering effort can postpone deployment beyond a short procurement cycle.
Small-Fleet Purchasing Economics
A modest group of low-cost sensors may not generate sufficient operational savings to justify a separate management subscription, dedicated service contract and integration project. Cloud vendors offer highly granular pricing, but field installation, support and application integration can still dominate total ownership costs. Some buyers therefore rely on features already included with device hardware or connectivity packages instead of purchasing additional software.
Security and Operational Responsibility Across Suppliers
A managed endpoint may involve a hardware maker, network operator, cloud provider and specialist integrator. If an update fails or a device loses authentication, fault resolution depends on clear responsibility for firmware, connectivity, credentials and business applications. Without agreed service boundaries, a multi-vendor architecture can increase support complexity and reduce willingness to expand a pilot into a nationwide fleet.
Foreign-Currency Software Costs and Procurement Uncertainty
Many device-management entitlements and specialist implementation services are priced against international cloud or software contracts. Argentine customers must evaluate those expenses against domestic operating budgets and the risk that currency movements alter renewal costs. Longer purchasing approvals, integration priorities and the availability of local technical support can delay new projects even when a use case has an identifiable operational benefit.
Regional Outlook
Buenos Aires Province and the Autonomous City of Buenos Aires
Buenos Aires Province and the capital account for an estimated 46% of national device-management value in 2026. Corporate headquarters, enterprise technology procurement, distribution activities and a large industrial base make this the country's principal market for cloud platforms and managed IoT services. Telecom Argentina operates enterprise digital and IoT services from a national network, while international software contracts are frequently purchased or administered through the metropolitan business ecosystem.
The combined area's modeled market reaches USD 54.2 million in 2031, although its share decreases as more equipment outside the metropolitan region receives direct management capability. The purchasing base remains diversified across logistics, manufacturing, building systems and service fleets. Revenue allocation follows the customer or installation location rather than assuming that every nationally purchased cloud subscription belongs to the capital.
Córdoba
Córdoba's industrial operations and agricultural-service networks provide a commercially distinct customer base for connected machinery, fleet tracking and remote maintenance. Manufacturing buyers need device gateways that coexist with operational technology, while agri-logistics users place more weight on low-touch administration across remote assets. This mix gives specialist platform and integration services a stronger route to market than undifferentiated connectivity packages.
The province is projected to expand at approximately 15.8% annually between 2026 and 2031, faster than the modeled national rate, increasing its share as industrial devices and logistics fleets move from isolated monitoring projects to managed deployments. The forecast assumes investment in device lifecycle operations rather than treating all sensor or factory-automation purchases as device-management revenue.
Competitive Landscape
The Argentine competitive environment has two principal routes to the buyer: carrier-led managed solutions and globally supplied software platforms. Telecom Argentina's Personal Tech can provide connectivity, SIM administration, monitoring and local professional support within the same commercial relationship. AWS and Microsoft compete where enterprises want cloud-native registration, device identities, remote jobs and integration with their existing application estates. Their prices, architectures and supported regions differ; neither platform's global product announcement should be interpreted as a confirmed Argentine deployment.
Industrial specialists compete on a narrower set of operational requirements. Telit Cinterion's deviceWISE offers OT connectors and edge-to-cloud services; Gurtam provides the Wialon ecosystem for monitored transport assets; Nordic Semiconductor's Memfault business supplies device diagnostics and OTA tooling. Other dedicated management providers include 1NCE, Particle, Losant and ThingsBoard. Supplier selection often turns on the identity and state information a platform can expose, its ability to complete remote actions under poor connectivity and the division of support responsibility among the participating firms.
Recent Developments
30 September 2026: Nordic Semiconductor's Memfault platform documented saved-search alerts and updated OTA release-health workflows, expanding operational monitoring of device fleets.
23 September 2026: Microsoft set out the Azure IoT Central transition, ending creation of new applications while allowing existing applications to operate until September 2029 and recommending newer IoT Hub-based architecture.
10 September 2026: Telit Cinterion's deviceWISE business announced live industrial demonstrations of fault detection and automated recovery using its asset-integration platform at IMTS 2026.
3 June 2026: AWS expanded IoT Device Management's connectivity-status API with MQTT session diagnostics and controlled access to socket metadata for fleet troubleshooting.
15 April 2026: Microsoft refreshed the Azure IoT Hub and Azure Device Registry preview with device-certificate renewal and management features; the preview status limits production conclusions.
14 January 2026: AWS added Wi-Fi Simple Setup for its managed-integrations feature, reducing provisioning steps; the announced feature was then available in Canada Central and Europe Ireland, not a documented Argentina region.
Market Outlook
Between 2026 and 2031, the more durable revenue opportunity will come from managing larger installed fleets and deeper lifecycle functions rather than simply connecting additional sensors. Remote software releases, credential administration, alarm prioritization and fault diagnosis can create a continuing need for software subscriptions and managed support. An enterprise that can reliably update thousands of devices without sending technicians to each location has a clearer basis for sustaining expenditure through equipment refresh cycles.
The relative position of cloud, hybrid and operator-led offerings will depend on workload criticality and procurement design. Buenos Aires and the capital should remain the largest purchasing market, while Córdoba's industrial and agricultural applications offer a faster growth trajectory from a smaller base. Vendors with interoperable device models, credible service arrangements and support for mixed connectivity environments are better placed to convert connected-device pilots into recurring production contracts.
Argentina IoT Device Management Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 72.0 million |
| Total Market Size in 2031 | USD 126.0 million |
| Forecast Unit | Million |
| Growth Rate | 11.84% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Deployment, Connectivity, Application |
| Companies |
|
Market Segmentation
By Component
Solutions
Security Management
Network Bandwidth Management
Data Management
Real-Time Streaming Analytics
Remote Monitoring
Services
Professional Services
Managed Services
By Deployment
Public Cloud
Private Cloud
Hybrid Cloud
By Connectivity
Cellular
LPWAN
Wi-Fi & Bluetooth
Satellite
By Application
Connected Logistics
Digital Health
Smart Manufacturing
Smart Retail
Smart Utilities
Others
By End-user
Automotive
Building & Home Automation
Retail
Healthcare
Transportation
Manufacturing
Consumer Electronics
Others
By Geography
Buenos Aires Province and Autonomous City of Buenos Aires
Córdoba
Santa Fe
Cuyo
Mendoza
San Juan
San Luis
Patagonia
Neuquén
Río Negro
Chubut
Santa Cruz
Tierra del Fuego
Northwest Argentina
Tucumán
Salta
Jujuy
Santiago del Estero
Catamarca
La Rioja
Northeast Argentina
Chaco
Corrientes
Misiones
Formosa
Other Central Provinces
Entre Ríos
La Pampa
Other
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Currency and Units
2.6. Base and Forecast Years
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Growth in Managed Cellular and M2M Fleets
3.1.2. Industrial Equipment Modernization
3.1.3. Logistics and Agricultural Asset Traceability
3.1.4. Demand for Remote Maintenance and Firmware Updates
3.1.5. Stronger Attention to Device Identity and Auditability
3.2. Market Restraints
3.2.1. Connectivity Gaps and Intermittent Device Access
3.2.2. Industrial Integration and Legacy Protocols
3.2.3. Small-Fleet Purchasing Economics
3.2.4. Security and Operational Responsibility Across Suppliers
3.2.5. Foreign-Currency Software Costs and Procurement Uncertainty
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Endpoint Provisioning and Identity
4.2. Remote Diagnostics and OTA Software Management
4.3. Edge-to-Cloud and Hybrid Fleet Architecture
4.4. Protocol Interoperability and Lifecycle Security
5. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY COMPONENT
5.1. Introduction
5.2. Solutions
5.2.1. Security Management
5.2.2. Network Bandwidth Management
5.2.3. Data Management
5.2.4. Real-Time Streaming Analytics
5.2.5. Remote Monitoring
5.3. Services
5.3.1. Professional Services
5.3.2. Managed Services
6. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Public Cloud
6.3. Private Cloud
6.4. Hybrid Cloud
7. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY CONNECTIVITY
7.1. Introduction
7.2. Cellular
7.3. LPWAN
7.4. Wi-Fi & Bluetooth
7.5. Satellite
8. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY APPLICATION
8.1. Introduction
8.2. Connected Logistics
8.3. Digital Health
8.4. Smart Manufacturing
8.5. Smart Retail
8.6. Smart Utilities
8.7. Others
9. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY END-USER
9.1. Introduction
9.2. Automotive
9.3. Building & Home Automation
9.4. Retail
9.5. Healthcare
9.6. Transportation
9.7. Manufacturing
9.8. Consumer Electronics
9.9. Others
10. ARGENTINA IOT DEVICE MANAGEMENT MARKET BY GEOGRAPHY
10.1. Introduction
10.2. Buenos Aires Province and Autonomous City of Buenos Aires
10.3. Córdoba
10.4. Santa Fe
10.5. Cuyo
10.5.1. Mendoza
10.5.2. San Juan
10.5.3. San Luis
10.6. Patagonia
10.6.1. Neuquén
10.6.2. Río Negro
10.6.3. Chubut
10.6.4. Santa Cruz
10.6.5. Tierra del Fuego
10.7. Northwest Argentina
10.7.1. Tucumán
10.7.2. Salta
10.7.3. Jujuy
10.7.4. Santiago del Estero
10.7.5. Catamarca
10.7.6. La Rioja
10.8. Northeast Argentina
10.8.1. Chaco
10.8.2. Corrientes
10.8.3. Misiones
10.8.4. Formosa
10.9. Other Central Provinces
10.9.1. Entre Ríos
10.9.2. La Pampa
10.9.3. Other
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Partnerships, Acquisitions and Technology Agreements
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Amazon Web Services, Inc.
12.2. Microsoft Corporation
12.3. Telecom Argentina S.A. (Personal Tech)
12.4. Telit Cinterion
12.5. Gurtam
12.6. 1NCE GmbH
12.7. Nordic Semiconductor ASA (Memfault)
12.8. Particle Industries, Inc.
12.9. Losant, Inc.
12.10. ThingsBoard, Inc.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits to Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











