
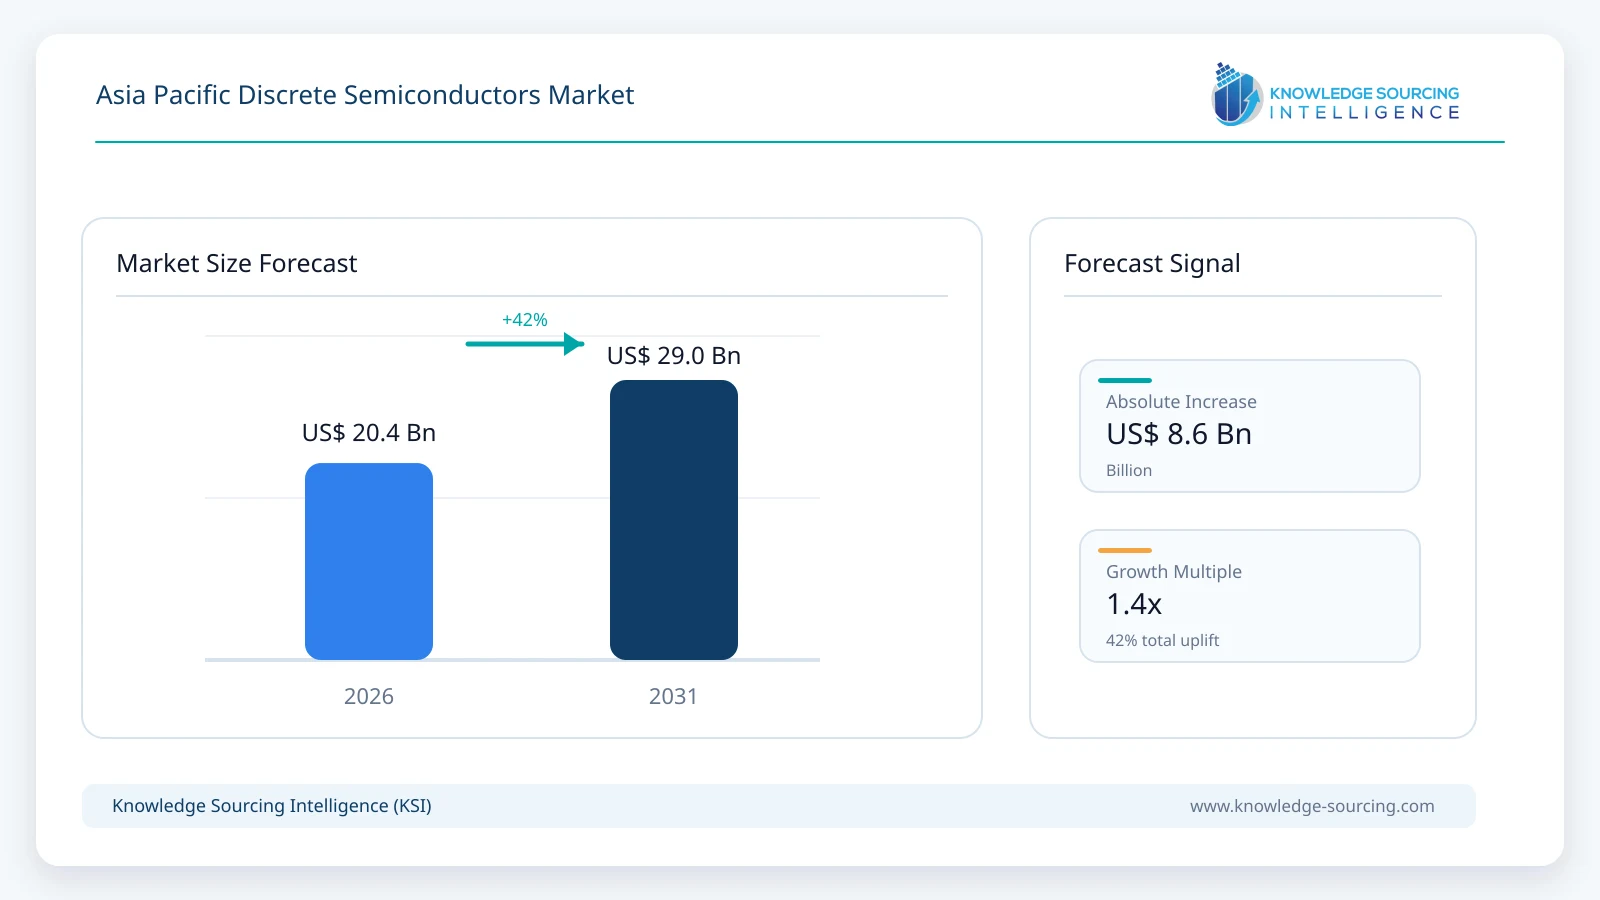
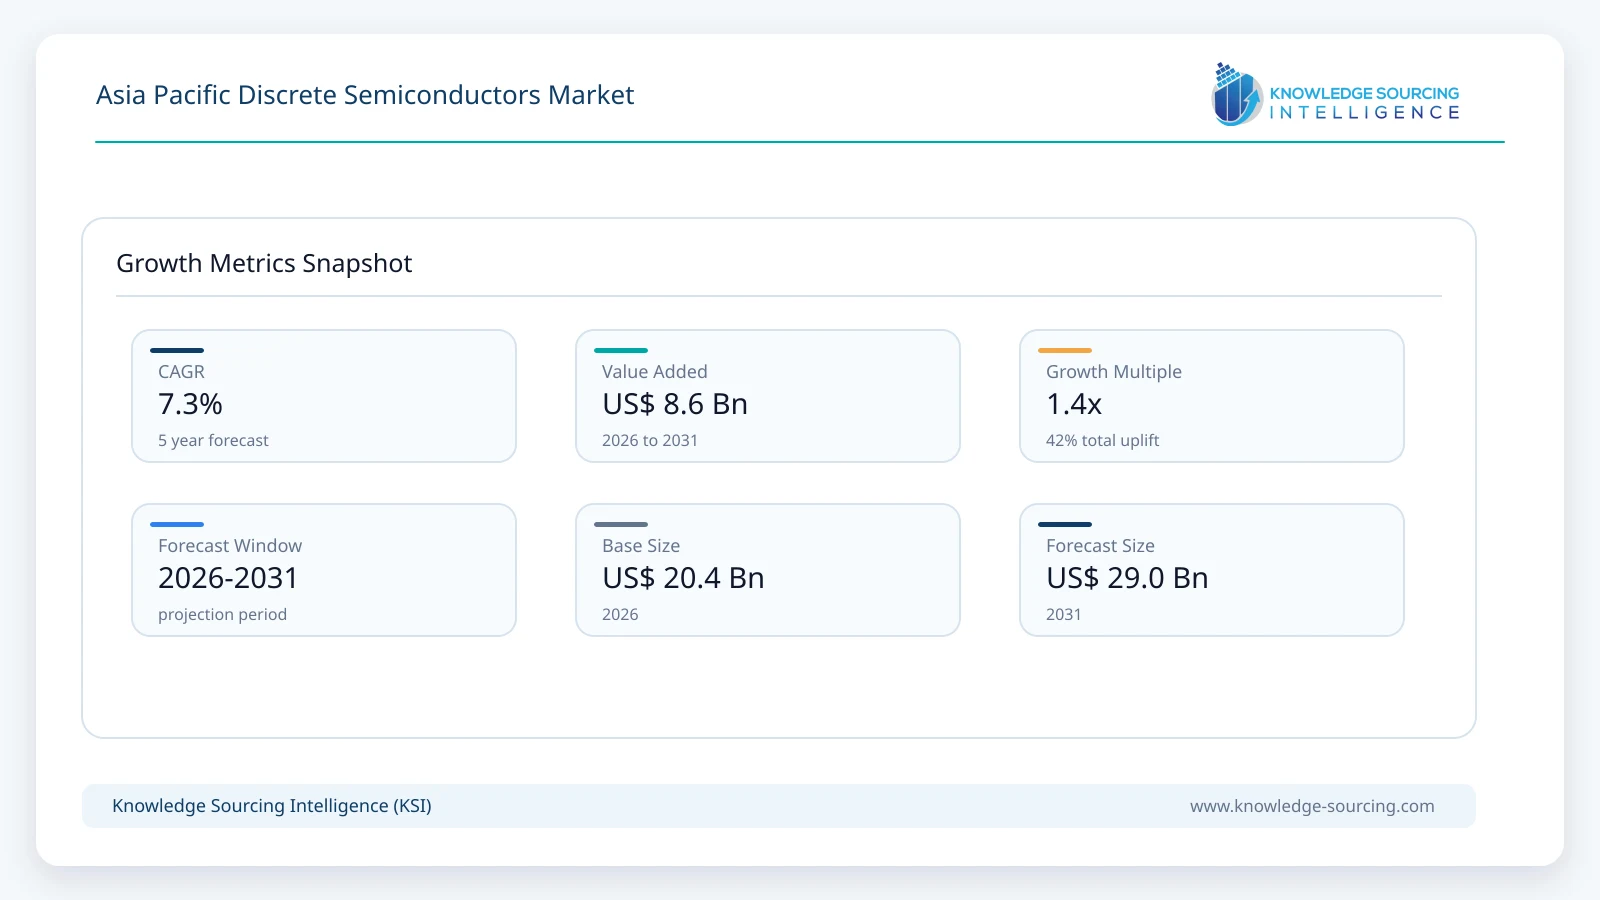
The Asia Pacific (APAC) Discrete Semiconductors Market is forecast to expand at a CAGR of 7.3%, reaching USD 29.0 billion in 2031 from USD 20.4 billion in 2026.
Highlights:
- 1Power transistors represent approximately 45.9% of regional discrete-device value in 2026.
- 2Automotive applications account for about 31.2% of the 2026 market, supported by higher electrical content per vehicle.
- 3China generates roughly 40.8% of regional revenue as the principal electronics and vehicle-production market.
- 4SiC devices are gaining qualification in higher-voltage power conversion, while silicon MOSFETs retain broader volume demand.
- 5India is positioned for the strongest modeled country growth as electronics assembly and industrial electrification expand.
Discrete semiconductors comprise individual packaged semiconductor devices that regulate, switch, rectify or protect electrical current. They include thyristors, rectifiers, power transistors, small-signal transistors and stand-alone diodes. These components are purchased by electronics manufacturers, automotive suppliers and industrial equipment producers, either directly or through distribution channels. Demand follows installed equipment volumes, device content per system and changes in semiconductor performance requirements, rather than tracking total semiconductor industry revenue.
Industrial and automotive power conversion is increasingly demanding devices with lower conduction losses, stronger short-circuit tolerance and tighter thermal behaviour. ROHM supplies SiC and silicon MOSFETs for vehicle and high-voltage equipment, Toshiba continues to develop automotive-grade packaged MOSFETs, and Diodes Incorporated provides rectifiers and power switches for vehicle subsystems. Infineon, onsemi, Vishay and STMicroelectronics also compete across high-volume silicon devices and more specialized power portfolios. Standalone discrete sales are distinguished from finished inverter or power-module revenue, avoiding the attribution of the same device twice.
Market Overview
Power management components are specified at the circuit and system level, where changes in switching losses, voltage withstand capability, or thermal resistance can alter a customer’s complete power design. In an electric vehicle, MOSFETs and diodes serve low-voltage body electronics, onboard chargers and auxiliary motor drives, while higher-voltage conversion can use discrete silicon carbide devices or integrated power modules according to power level. The volume opportunity is therefore broad, but the revenue uplift is concentrated in applications requiring greater reliability, more demanding packaging or higher-performing semiconductor materials.
In China, vehicle manufacturing and electrical-equipment production support large consumption of both commodity and specialist devices. The IEA reported that electric cars represented almost 55% of Chinese new-car sales in 2025; this increases exposure to power switching and charging electronics without implying that each vehicle uses an identical device bill of materials. Japan retains strong device and packaging expertise through Toshiba, ROHM, Renesas and Fuji Electric. Taiwan contributes discrete vendors and electronics-manufacturing networks, while South Korea, Thailand and other ASEAN locations provide major appliance, automotive and industrial assembly capacity.
The market’s technology split is being reshaped by packaging and qualification as much as by semiconductor material. ROHM’s newer wide-safe-operating-area silicon MOSFETs address short-duration automotive safety loads, while Toshiba’s copper-clip and wettable-flank packages improve heat removal and solder-joint inspection. At the same time, manufacturers continue to sell high-volume rectifiers, protection diodes and small-signal transistors at tight prices. Buyers generally qualify several interchangeable devices for ordinary designs, but advanced automotive and high-voltage applications have longer approval cycles and higher engineering barriers.
Market Trends
Automotive Power Switching Is Becoming More Application-Specific
Vehicle electrification is increasing the range of semiconductor operating conditions, from low-voltage body control to high-voltage charging and traction-related power conversion. Toshiba launched a 40 V, 120 A automotive MOSFET in July 2026 for motor drives, solid-state relays and load switching, illustrating the continuing need for optimized silicon devices alongside more expensive wide-bandgap products. The ability to deliver lower on-resistance in a compact package can protect customers’ efficiency targets without requiring a wholesale change in system architecture.
Qualification is as important as peak electrical performance. Automotive design teams examine package inspectability, solder fatigue, avalanche endurance and safe-operating-area limits against defined duty cycles. ROHM’s September 2026 wide-SOA MOSFET announcement addresses transient loads in safety and protection circuitry, where failure tolerance matters more than nominal switching speed. Manufacturers offering both high-volume catalogue parts and application-qualified device families can serve more vehicle subsystems while reducing customer redesign requirements.
Silicon Carbide Broadens Its Role Beyond Vehicle Traction
Silicon carbide MOSFETs and diodes are being evaluated in power supplies, energy storage, charging equipment and industrial conversion because higher switching frequencies and lower losses can reduce cooling or passive-component requirements. In June 2026, ROHM disclosed adoption of a 750 V SiC MOSFET in an AI-server battery backup unit, a concrete application beyond electric-vehicle traction systems. Device adoption depends on complete system efficiency and thermal design, rather than the availability of a higher-voltage part alone.
Cost and reliability prevent a uniform migration from silicon. Many lower-voltage drives, appliance controls and standard converters can meet customer specifications using silicon MOSFETs or IGBTs, and high-temperature stability must be proven before a new SiC part enters mass production. ROHM’s April 2026 fifth-generation device announcement shows progress in high-temperature on-resistance, but a development announcement should not be confused with commercial shipments. The product mix is expected to shift toward higher-value switches gradually, with conventional technologies retaining substantial volume.
Power Packages Are Being Redesigned for Automated Assembly
Toshiba’s June 2026 copper-clip MOSFET package and its wettable-flank product designs address two manufacturing constraints: heat flow from the die and reliable inspection of solder attachment. Packaging changes can improve continuous-current capability and reduce board area without forcing customers to adopt a different semiconductor topology. These benefits are particularly relevant to dense automotive electronics and industrial drives, where thermal cycling and mounting quality influence field reliability.
Asian manufacturing customers increasingly evaluate a device together with its package dimensions, thermal resistance and available automated optical inspection methods. Common package footprints support second sourcing, while proprietary internal structures can still differentiate devices on electrical performance. This interaction keeps package engineering and quality systems central to competitive positioning, even in mature discrete-device categories with limited pricing flexibility.
Manufacturing Automation Sustains Industrial Control Demand
The International Federation of Robotics reported that China installed approximately 354,000 industrial robots in 2025, while India installed almost 10,500. Robot controllers, servo drives, power supplies and associated factory equipment use switching and protection devices, although the relationship between robot installations and semiconductor revenue is indirect. Greater automation also increases demand for motor-control and industrial power electronics in equipment beyond robotics.
Industrial demand is diversified across production machinery, uninterruptible power supplies, motor drives and facility electrification. Power transistors must meet surge, thermal and lifetime specifications, while conventional rectifiers and signal switches remain necessary across power-control boards. Suppliers serving this range can balance cyclical automotive demand with longer-lived industrial equipment programs, but qualification requirements and customer inventory practices still produce uneven ordering patterns.
Localized Manufacturing Is Changing Procurement Choices
India’s semiconductor manufacturing programme explicitly supports compound-semiconductor and discrete-device fabrication alongside assembly, testing and packaging. The government’s 2026–27 programme identifies a substantial investment pipeline, but proposed capacity does not automatically represent qualified commercial output. Manufacturing qualification, wafer yields, customer audits and access to cost-competitive substrates will determine how quickly local facilities become credible sources of finished devices.
Elsewhere in Asia, established suppliers continue to diversify assembly, testing and power-device fabrication locations. Customers may seek local or regional sourcing to reduce lead times and trade exposure, but dual qualification can increase validation work. The likely result is a more distributed manufacturing footprint rather than an immediate redistribution of demand away from China, whose scale in electronic equipment and vehicle production remains difficult to replicate.
Segment Analysis
By Type: Power Transistors
Power transistors are expected to generate approximately USD 14.54 billion in regional value by 2031, supported by standalone power MOSFETs, IGBTs and SiC switching devices used in power conversion and motor-control applications. Inverter efficiency, voltage transients and thermal management influence selection, while customers must decide whether to use separate packaged devices or a ready-made power module. The forecast includes only attributable discrete devices; it does not add the value of complete modules or integrated power controllers.
Infineon’s portfolio differentiates IGBT and SiC discretes from finished module products, and Vishay identifies MOSFETs and diodes as standalone semiconductor product families in its annual filing. The commercial mix gradually favours higher-performance switches in electric vehicles, renewable-energy conversion and server power supplies, although standard silicon MOSFETs continue to account for large unit volumes in automotive auxiliaries, home electronics and industrial control boards.
By Industry Vertical: Automotive
Automotive is modeled to expand at approximately 11.31% annually through 2031 as power switching spreads across charging systems, vehicle safety electronics, thermal-control actuators and auxiliary drives. China is the largest source of demand, and production networks in India and Southeast Asia add incremental opportunities. The market includes direct device content sold into vehicle electronics rather than full vehicle systems or electronics assemblies.
Supplier differentiation is particularly visible at the component qualification stage. Diodes Incorporated’s field-plated rectifiers target reliable automotive DC-DC conversion and protection; Toshiba’s MOSFET launches address low-voltage drive and load-switching circuits. Electric-vehicle penetration increases the addressable application range, but substitution between discrete and integrated power modules and OEM-led cost reduction will moderate revenue growth relative to semiconductor content growth.
Market Drivers
Electrification of Vehicle Auxiliary and Power Systems
The expansion of electric-car production across China and other Asian vehicle hubs raises the number of regulated power paths, protection devices and controlled actuators installed in each platform. Silicon MOSFETs serve numerous 12 V and 48 V loads, while selected high-voltage conversion stages employ SiC devices. IEA data on 2025 electric-car uptake gives evidence of the manufacturing scale supporting these applications. Revenue growth nonetheless depends on the device content and value of each program, since a discrete switch is not interchangeable with the sale of a complete power module.
Industrial Drives and Automation Equipment
Factory automation creates continuing requirements for rectifiers, power switches and circuit-protection devices in motor drives, PLC peripherals and industrial power supplies. The IFR’s September 2026 robotics release documents major installation activity in China and growth in India, supporting the expansion of equipment that uses these components. Longer equipment lifetimes create a market for reliable replacements and recurring production orders, but customers demand verified thermal operation and stable availability rather than performance claims alone.
Efficiency Requirements in High-Density Power Supplies
Server backup units, telecom systems and industrial power equipment are becoming more sensitive to energy losses and thermal density. ROHM’s documented 750 V SiC MOSFET use in an AI-server backup power unit shows how discrete devices can compete on system-level efficiency and package size. Device suppliers that improve conduction and switching characteristics can capture higher-value design positions, although the system architect may select a module or integrate multiple functions where that reduces overall cost.
Expansion of Electronics Assembly Across Emerging APAC Markets
Electronics and vehicle manufacturers are broadening assembly operations in India, Thailand, Vietnam and Indonesia, increasing local procurement of power and protection devices. India’s semiconductor policy includes dedicated support for discrete and compound-device facilities, demonstrating government interest in reducing supply concentration. New facilities require yield stabilization, reliability qualification and customer approvals before they can materially change device shipments, so the forecast builds in a gradual rather than immediate capacity contribution.
Improved Device Packaging and Product Qualification
Higher current density and automated board production make package performance a commercial differentiator. Toshiba’s copper-clip and wettable-flank MOSFET families reduce heat-management and inspection constraints, while ROHM’s wide-SOA products address momentary high-current automotive loads. Such improvements can extend the usable application range of existing silicon devices and reduce design-change costs. Suppliers able to validate package reliability across customer platforms have an advantage over low-price alternatives with limited qualification support.
Market Restraints
Inventory Cycles and Price Competition in Mature Devices
Discrete semiconductor demand is exposed to distributor stock cycles and production swings in consumer, industrial and automotive equipment. WSTS reported that discrete-device revenue remained slightly negative in 2025 even as total semiconductor sales expanded strongly, highlighting the danger of extrapolating logic or memory growth across this category. Commodity diodes and low-voltage transistors face intense price competition, so unit growth may be partially offset by lower realized selling prices or periodic inventory correction.
Qualification Burden for Automotive and Industrial Designs
Automotive and industrial customers require documented performance across temperature, surge conditions, vibration and long service lives. A new device with attractive electrical characteristics may still need extended testing for package attachment, failure behaviour and supply consistency. Multiple device and source qualifications raise engineering expense for both manufacturers and buyers. These cycles delay revenue from announced technologies and create a significant advantage for established vendors with audited factories and field histories.
Trade Exposure and Concentrated Supply Chains
Fabrication and assembly capacity remain concentrated in several Asian countries, creating exposure to export controls, logistics interruptions and trade measures. Some suppliers also depend on imported substrates, specialized materials or testing equipment. Capacity diversification is possible, but establishing a qualified alternative requires engineering and customer approval. These constraints can affect delivery schedules and working capital even when the underlying device technology uses established manufacturing processes.
Substitution by Integrated Power Modules and Controllers
Industrial and vehicle systems may employ integrated power modules or intelligent power stages rather than assembling several standalone switches and diodes. Module integration can simplify cooling, installation and manufacturing for higher-power applications, reducing the portion of project spending attributable to packaged discretes. Conversely, discrete devices can remain attractive in low- and medium-power designs where repairability, layout flexibility or purchasing cost matters. The forecast therefore avoids assuming that every new inverter raises standalone discrete-device sales proportionally.
Cost and Reliability Tradeoffs in Wide-Bandgap Devices
Silicon carbide devices offer potential efficiency gains but require suitable gate-drive design, thermal management and verified endurance under operating stresses. Premium substrate and fabrication requirements can constrain price competitiveness in applications already served adequately by silicon devices. ROHM’s development work on short-circuit robustness and high-temperature on-resistance illustrates the engineering attention still required. As a result, wide-bandgap adoption should be concentrated where measurable system savings justify its additional component and qualification costs.
Regional Outlook
China: Largest Country Market
China accounts for approximately 40.8% of Asia-Pacific discrete semiconductor revenue in 2026, reflecting the breadth of domestic electronics, automotive and industrial equipment manufacturing. Its position is supported by both high-volume standard devices and demand for more complex power switching and protection in EV systems. The IEA reported that China produced the majority of the world’s electric cars in 2025, while IFR recorded 354,000 industrial robot installations, providing concrete indications of equipment markets that use discrete semiconductors.
Domestic supply is expanding alongside demand, although standard-device competition can constrain selling prices. China’s market is forecast to reach approximately USD 12.10 billion by 2031. Supplier success will depend on automotive-grade reliability, accessible packaging capacity and the ability to serve both domestic equipment makers and regional export supply chains. Higher-value switching devices offer a route to revenue growth that is less dependent on sheer increases in component units.
India: Fastest-Growing Country Market
India’s discrete semiconductor market is modeled to grow at about 13.33% annually over 2026–2031, supported by rising domestic electronics assembly, electric-mobility applications and investment in industrial equipment. The government’s 2026–27 semiconductor programme includes facilities for compound semiconductors, discrete fabrication and assembly/testing, but meaningful local device supply will depend on production qualification and customer adoption rather than approval announcements alone.
India’s opportunity also lies in the expansion of its consuming industries. IEA data indicate rising electric-car sales in 2025, while IFR’s latest figures document stronger industrial robot installations. These activities create requirements for power transistors, rectifiers and protection devices, alongside broader demand from communications infrastructure and appliances. Local manufacturing initiatives could improve supply resilience, but international vendors are likely to remain important until domestic processes and device portfolios meet a wider range of industrial and automotive specifications.
Competitive Landscape
Infineon, onsemi, STMicroelectronics and Vishay address broad power and protection-device requirements through global manufacturing and qualification networks. Infineon supplies discrete IGBTs, silicon carbide MOSFETs and diodes in addition to modules, while onsemi combines discrete switches with mixed-signal and power products. Vishay’s reported MOSFET and diode business lines demonstrate the continued scale of conventional device portfolios. Their position in Asia depends on relationships with automotive suppliers, industrial system designers and distribution customers rather than geographic headquarters alone.
Japanese producers ROHM, Toshiba, Renesas and Fuji Electric compete through product architecture, process technology and high-reliability applications. ROHM’s adoption disclosure for AI-server backup power and Toshiba’s 2026 automotive MOSFET releases provide examples of design-led competition. Diodes Incorporated, Nexperia, PANJIT, Taiwan Semiconductor and Yangjie supply a broad mix of rectifiers, MOSFETs and protection components, where package availability, price and delivery reliability strongly influence purchasing decisions. Market-share rankings are not inferred from whole-company revenues because each vendor also sells products outside this market.
Recent Developments
24 September 2026: Diodes Incorporated introduced automotive field-plated Super Barrier Rectifier devices for DC-DC conversion, charging and protection applications, emphasizing low forward voltage and surge endurance.
15 September 2026: ROHM launched its RS4P063BPHZG 100 V wide-safe-operating-area automotive MOSFET for safety and protection circuits; the company reported that mass production had begun in June.
21 July 2026: Toshiba expanded its automotive MOSFET offering with a 40 V, 120 A N-channel device in a thermally enhanced package designed for motor drives and load switching.
4 June 2026: Toshiba introduced a new 40 V N-channel power MOSFET family using a copper-clip SOP Advance(EWF) package for improved automotive thermal and current performance.
3 June 2026: ROHM reported adoption of its 750 V SiC MOSFET in an AI-server battery backup unit, establishing a documented power-supply application for its device.
21 April 2026: ROHM announced development of fifth-generation SiC MOSFET technology with improved high-temperature on-resistance; the disclosure was a technology milestone, not evidence of full-volume rollout.
Market Outlook
Growth through 2031 is expected to come from a shift in the regional device mix rather than a uniform surge across every discrete category. Standard rectifiers, small-signal transistors and circuit-protection devices will remain necessary in high-volume electronics, but power transistors should gain value share as electric vehicles, industrial systems and high-density power supplies adopt more demanding switching designs. Suppliers with qualified silicon and SiC portfolios can address a wider range of design choices without assuming universal migration to wide-bandgap materials.
China will retain the largest demand base, while India offers faster incremental growth from a smaller market. Manufacturing investments across Asia may improve sourcing options, although customer qualification and component-price pressure will determine how much of that investment becomes commercial revenue. The strongest suppliers are likely to combine scalable manufacturing, robust packaging and application-specific engineering support, rather than compete solely on device switching specifications.
Asia Pacific Discrete Semiconductors Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 20.4 billion |
| Total Market Size in 2031 | USD 29.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Industry Vertical, Country |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Thyristors
Rectifiers
Power Transistors
Small Signal Transistors
Diodes
Others
By Industry Vertical
Consumer Electronics
Communication
Automotive
Manufacturing
By Country
China
India
Japan
South Korea
Thailand
Indonesia
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Growth, 2026–2031
1.3. Segment and Country Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Electrification of Vehicle Auxiliary and Power Systems
3.1.2. Industrial Drives and Automation Equipment
3.1.3. Efficiency Requirements in High-Density Power Supplies
3.1.4. Expansion of Electronics Assembly Across Emerging APAC Markets
3.1.5. Improved Device Packaging and Product Qualification
3.2. Market Restraints
3.2.1. Inventory Cycles and Price Competition in Mature Devices
3.2.2. Qualification Burden for Automotive and Industrial Designs
3.2.3. Trade Exposure and Concentrated Supply Chains
3.2.4. Substitution by Integrated Power Modules and Controllers
3.2.5. Cost and Reliability Tradeoffs in Wide-Bandgap Devices
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Silicon and Wide-Bandgap Discrete Technologies
4.2. Device Packaging and Thermal Performance
4.3. Automotive Device Qualification
4.4. Power Conversion and Circuit Protection
5. ASIA PACIFIC DISCRETE SEMICONDUCTORS MARKET BY TYPE
5.1. Introduction
5.2. Thyristors
5.3. Rectifiers
5.4. Power Transistors
5.5. Small Signal Transistors
5.6. Diodes
5.7. Others
6. ASIA PACIFIC DISCRETE SEMICONDUCTORS MARKET BY INDUSTRY VERTICAL
6.1. Introduction
6.2. Consumer Electronics
6.3. Communication
6.4. Automotive
6.5. Manufacturing
7. ASIA PACIFIC DISCRETE SEMICONDUCTORS MARKET BY COUNTRY
7.1. Introduction
7.2. China
7.3. India
7.4. Japan
7.5. South Korea
7.6. Thailand
7.7. Indonesia
7.8. Taiwan
7.9. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Infineon Technologies AG
9.2. onsemi
9.3. STMicroelectronics N.V.
9.4. Vishay Intertechnology, Inc.
9.5. ROHM Co., Ltd.
9.6. Toshiba Electronic Devices & Storage Corporation
9.7. Diodes Incorporated
9.8. Nexperia B.V.
9.9. Renesas Electronics Corporation
9.10. Fuji Electric Co., Ltd.
9.11. PANJIT International Inc.
9.12. Taiwan Semiconductor Co., Ltd.
9.13. Yangzhou Yangjie Electronic Technology Co., Ltd.
9.14. Littelfuse, Inc.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Year Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size of APAC Discrete Semiconductors by 2031?
The Asia Pacific Discrete Semiconductors Market is forecast to reach USD 29.0 billion by 2031.
What is the CAGR for the APAC Discrete Semiconductors market (2026-2031)?
The Asia Pacific Discrete Semiconductors Market is forecast to expand at a 7.3% CAGR.
Which discrete semiconductor type holds the largest market share?
Power transistors represent approximately 45.9% of regional value in 2026.
What is the largest application sector for discrete semiconductors in APAC?
Automotive applications account for about 31.2% of the 2026 market.
Which country is the principal revenue generator in the APAC market?
China generates roughly 40.8% of regional revenue.
Which APAC country is expected to see the strongest growth?
India is positioned for the strongest modeled country growth.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia Pacific Discrete Semiconductors Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/asia-pacific-discrete-semiconductors-market