
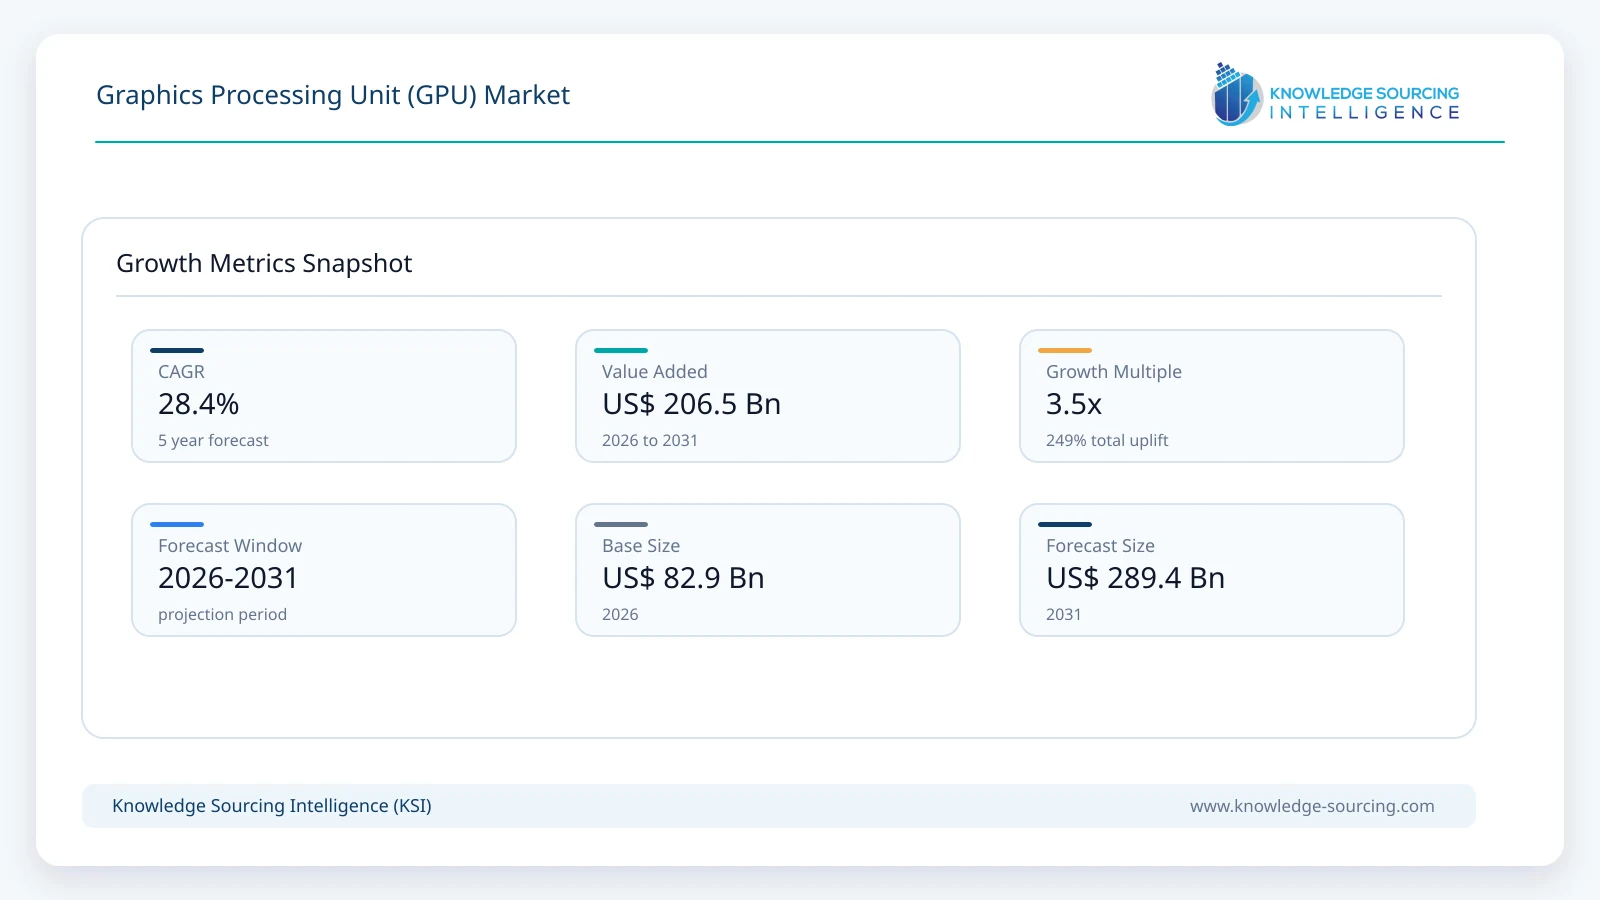
The Graphics Processing Unit (GPU) Market is projected to grow from USD 82.9 billion in 2026 to USD 289.4 billion by 2031, at a CAGR of 28.4% during forecast period.
Highlights:
- 1Growing demand for artificial intelligence, machine learning, and generative computing is accelerating GPU adoption across data centers, cloud platforms, and enterprise applications.
- 2Advancements in gaming, virtual reality, and graphics-intensive applications are driving demand for powerful processors that deliver realistic visuals and smoother performance.
- 3Expanding cloud computing infrastructure is increasing reliance on GPUs for parallel processing, complex simulations, scientific research, and large-scale data analytics.
- 4Rising emphasis on energy efficiency, processing speed, and specialized computing architectures is encouraging innovation across consumer electronics, automotive systems, and industrial applications.
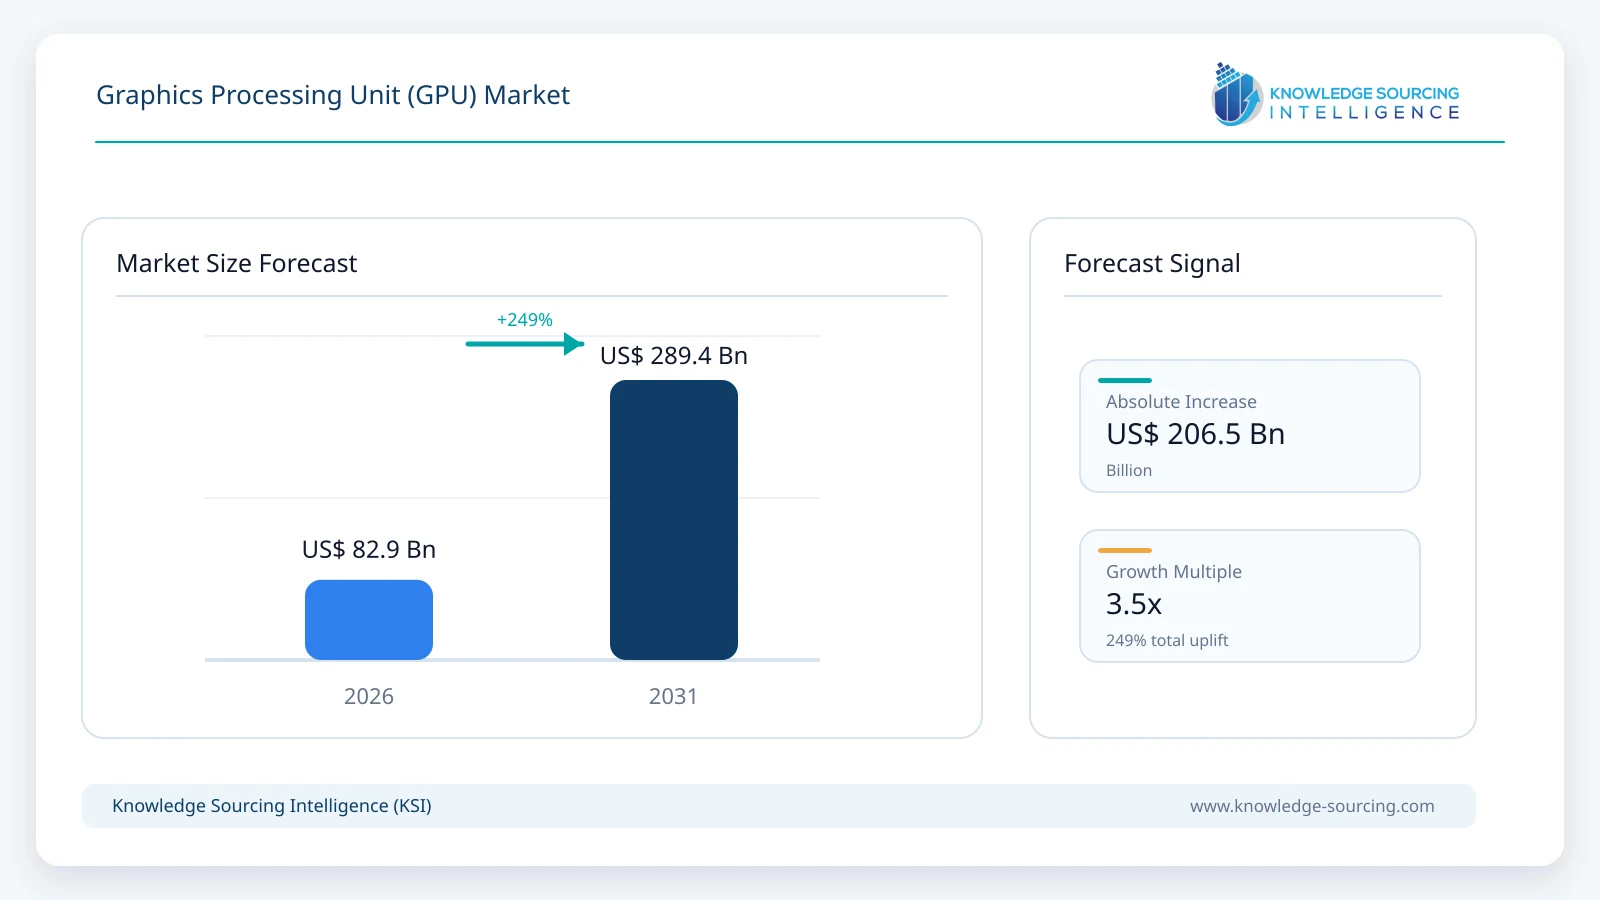
The Graphics Processing Unit (GPU) market is expanding rapidly as artificial intelligence (AI), generative AI, high-performance computing (HPC), cloud computing, gaming, and data-center workloads increase demand for accelerated computing. The market is also shifting toward high-memory, high-bandwidth, rack-scale GPU platforms designed specifically for large-scale AI training and inference.
AI infrastructure is becoming a major driver of GPU demand. The Department of Science & Technology is implementing the National Mission on Interdisciplinary Cyber-Physical Systems (NM-ICPS), approved by the Union Cabinet with an outlay of Rs. 3,660 crores.
NVIDIA is expanding GPU computing toward rack-scale AI systems. Its GB200 NVL72 integrates 72 Blackwell GPUs and 36 Grace CPUs in a liquid-cooled rack-scale platform, with a 72-GPU NVLink domain and 130 TB/s of GPU-to-GPU communication bandwidth, targeting trillion-parameter AI models and HPC workloads.
High-bandwidth memory is becoming a critical differentiator for AI GPUs. AMD's Instinct MI355X features 288 GB of HBM3E memory and 8 TB/s of memory bandwidth, supporting demanding AI training, inference, and HPC workloads.
GPU competition is expanding beyond NVIDIA. AMD is scaling its Instinct MI350 family, while Intel is targeting AI inference and workstation applications with its Arc Pro B60 and B50 GPUs and Gaudi 3 AI accelerators. Intel's Gaudi 3 provides 128 GB of memory and 3.7 TB/s of bandwidth in its PCIe configuration.
GPU demand is increasingly affecting the broader semiconductor and memory supply chain. AMD CEO Lisa Su said the company plans to substantially increase chip supply in 2027 to meet growing AI demand, while Micron has reported strong AI-driven demand for high-bandwidth memory and a substantial increase in customer commitments.
GPU architectures are expanding from traditional graphics into AI inference, edge computing, and enterprise workloads. NVIDIA's RTX PRO Blackwell family targets AI inference, data science, video processing, and professional visualization, while Intel's Arc Pro GPUs address workstation and AI-inference workloads.
Key Takeaways
Discrete GPUs remain a core market segment, supported by AI/HPC, gaming, professional visualization, and data-center applications.
AI and machine learning are emerging as the strongest growth drivers, particularly through generative AI, model training, inference, and reasoning workloads.
Data centers are becoming increasingly important GPU deployment environments, supported by rapid expansion of AI server infrastructure.
HBM capacity and memory bandwidth are becoming increasingly important to GPU performance, with products such as AMD MI355X reaching 288 GB HBM3E and 8 TB/s bandwidth.
Rack-scale GPU platforms such as NVIDIA GB200/GB300 NVL72 are changing the market from individual accelerator deployment toward integrated AI infrastructure combining GPUs, CPUs, networking, memory, and cooling.
Competitive intensity is increasing, with NVIDIA, AMD, Intel, and other GPU/accelerator developers expanding products across AI training, inference, HPC, gaming, workstation, automotive, and edge-computing applications.
Market Drivers
Rising Data Centers Coupled with Growing Computing Applications.
The rapid expansion of data centers, artificial intelligence (AI), generative AI, cloud computing, and high-performance computing (HPC) is driving demand for GPUs. Increasing computational complexity and data-intensive workloads are encouraging enterprises, hyperscalers, and cloud service providers to deploy GPU-accelerated infrastructure for AI training, inference, scientific computing, visualization, and other accelerated workloads.
Global semiconductor sales reached USD 795.6 billion in 2025, increasing 26.2% YoY[as6] , reflecting strong demand across computing, AI, data-center, and other advanced semiconductor applications.
AI-focused data-center infrastructure is expanding rapidly, with increasing computational intensity of AI workloads supporting greater deployment of high-performance GPU accelerators in data centers.
Generative AI and large language models are increasing GPU requirements, as AI training and inference workloads require substantial parallel-processing capabilities, high memory bandwidth, and accelerated computing performance.
Hyperscale cloud and technology companies are increasing investments in AI infrastructure, including GPU servers, high-speed networking, advanced memory, and data-center capacity, creating opportunities for GPU manufacturers.
GPU applications are expanding beyond traditional gaming, with increasing adoption across AI, HPC, scientific computing, professional visualization, autonomous vehicles, robotics, healthcare, and industrial applications.
Leading GPU manufacturers are expanding AI-focused product portfolios, including NVIDIA's Blackwell GPUs, AMD's Instinct MI350 series, and Intel's Gaudi accelerators, supporting the shift toward specialized GPU and accelerated-computing platforms.
In line with this, NVIDIA and Microsoft introduced RTX Spark in May 2026, a 1-petaflop AI superchip designed to enable secure, on-device AI agents and advanced AI, graphics, and gaming workloads on Windows PCs.
Increasing AI model complexity is driving demand for GPUs with higher memory capacity and bandwidth, particularly for large-scale training and inference workloads involving large language models and multimodal AI applications.
Cloud-based GPU services are improving access to accelerated computing, enabling enterprises to deploy GPU resources through public and private cloud environments without making equivalent investments in on-premises infrastructure.
The expansion of AI PCs and edge computing is broadening GPU adoption, as AI-enabled laptops, workstations, autonomous systems, robotics, and edge devices increasingly require local graphics and parallel-processing capabilities.
Graphics Processing Unit (GPU) Market Segment Analysis
Automotive
By end-user industry, the graphics processing unit (GPU) market is segmented into automotive, consumer electronics, telecommunications, industrial & manufacturing, data centers, aerospace & defence, media & entertainment, and others. The data center is expected to grow considerably, fueled by improved installed capacity globally.
Progressive digitization and development of AI-integrated electronics have amplified the market scope for GPU unit installation. The automotive sector is anticipated to grow consistently, fueled by the rapid development of software-defined vehicles.
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 82.9 billion |
| Total Market Size in 2031 | USD 289.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 28.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Deployment, Component, End User Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Continued mobility advancements fueled by investment in ADAS and AI-based displays have played a key role in driving GPU demand in automotive to provide an immersive in-cabin experience from a single architecture.
Moreover, global regions are progressing in software-defined vehicles (SDVs) and autonomous vehicles, which has positively influenced the market trajectory. According to the World Economic Forum’s “Autonomous Vehicles: Timeline and Roadmap Ahead, L2 autonomy accounted for 39% of global vehicles in 2025 and will grow to 42% in 2030. Likewise, L2+ is also expected to grow from 5% to 13% during the same period.
The electrification of the vehicle fleet, with global sales volume reaching up to 20.9 million units in 2025 and projections for 2026 nearing 23.4 million, supports the market trajectory as GPUs support power electronics and thermal management via real-time processing.
Global chip makers such as NVIDIA have collaborated with automakers like Hyundai for its “Blackwell GPU” to accelerate Hyundai’s vehicle automation target. Likewise, the company’s collaboration with BYD, Nissan, Isuzu, and Geely on its “NVIDIA Hyperion Platform”, designed to support level -4 autonomous vehicle development, is expected to further drive demand for high-performance GPUs.
Strong industrial policy such as UNECE’s “WP.29 has established a global framework for fully autonomous driving systems, which is anticipated to accelerate new GPU model development complying with high-level autonomy standards.
Geographical Outlook
North America: the US
The United States graphics processing unit (GPU) market is projected to show significant growth fueled by strong AI workloads and ML development.
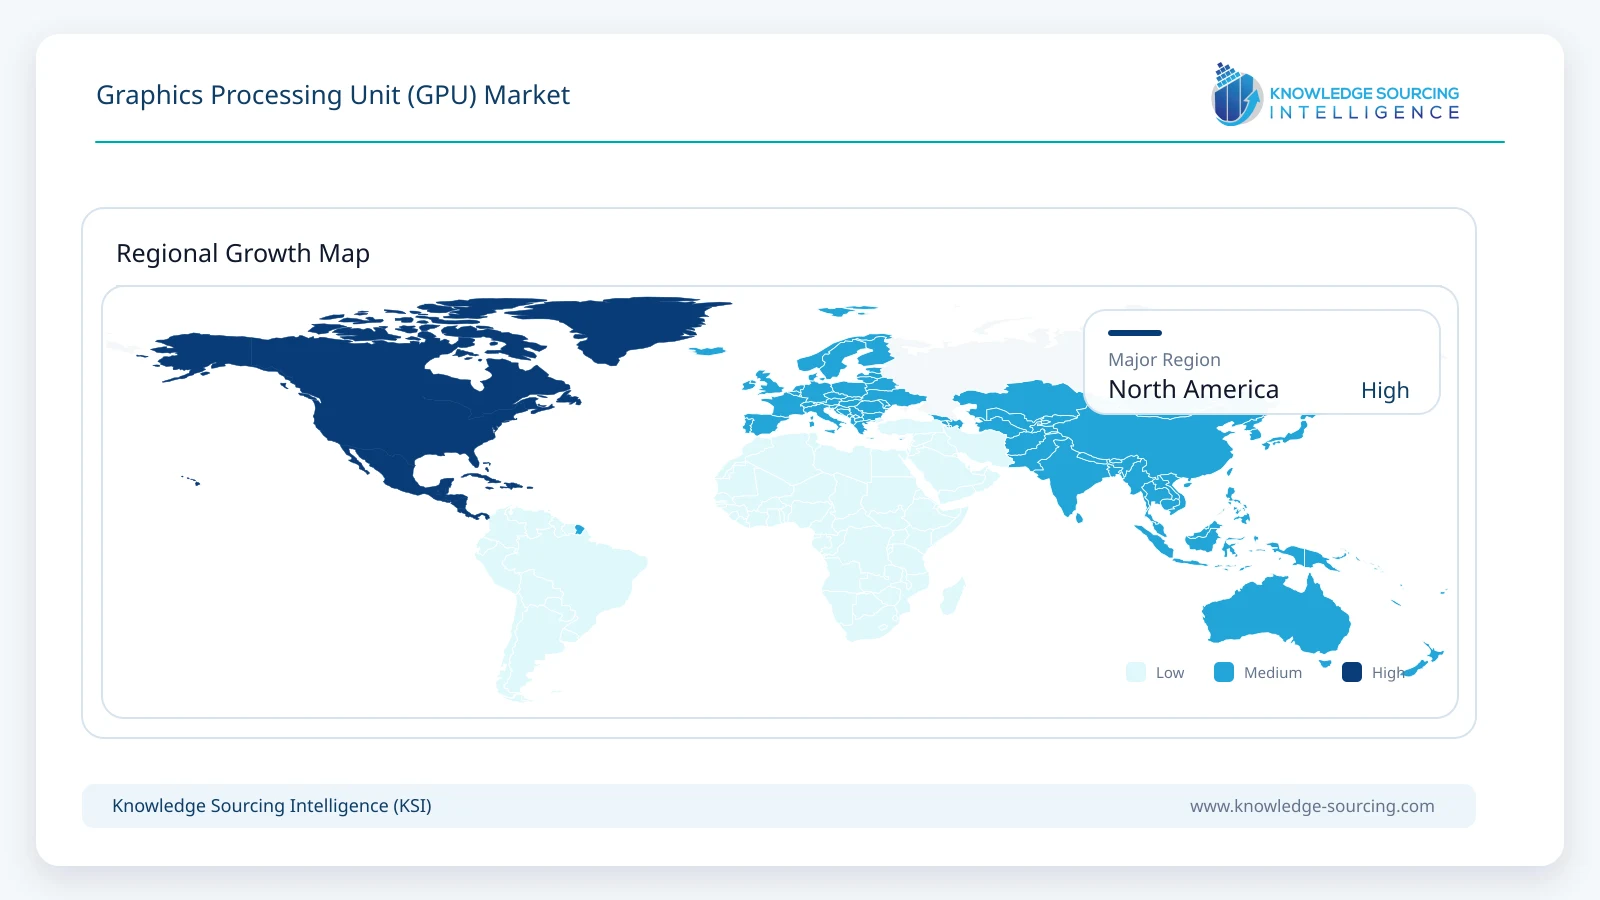
The US’s strong technological maturity has leveraged development in GPU modules. With the country pioneering global spending on artificial intelligence (AI) and machine learning (ML) workloads, the demand for GPUs supporting large parallel processing has escalated in the US.
Continued transformation of gaming applications has propelled the demand for smartphones, advanced PC and consoles in the United States. According to the Entertainment Software Association (ESA), mobile devices are popular for gaming and internet access across 80% of all age groups.
Billions of investments in advanced data center infrastructure development that complies with artificial intelligence (AI) have shaped the market outlook for efficient GPUs. According to the International Energy Agency , in 2025, the installed capacity reached 52 GW, with a projection for 2030 rising to 100 GW.
Progressive industrial automation has amplified robotics installation in major US sectors. According to the International Federation of Robotics, in 2025, robotics installation reached nearly 38,500 units, representing a 12% year-on-year growth. This progressive installation stimulates GPU demand to support parallel computing for modern robots in the US.
Companies have invested in new model development; for instance, Apple’s “M5” features next-generation 10-GPU architecture. Likewise, NVIDIA’s “Blackwell GPU is used in major AI platforms such as OpenAI’s “GPT-6 Astra Ultrafast”.
Company Profiles
Intel Corporation is a global semiconductor and computing technology company headquartered in Santa Clara, California. The company offers a portfolio of client and data-center processors, networking and connectivity products, accelerator graphics, and software. In graphics, Intel expanded from integrated graphics to discrete GPUs under the Intel Arc brand, and in high-performance computing, it offers GPUs and accelerators for professional, edge, and data-center workloads.
Intel covers many segments for its GPU strategy such as consumer gaming, professional workstations, AI inference and edge computing, and automotive, along with data-center applications. Its focus is on developing its Xe architecture with new products based on Xe2, and planned data-center GPUs based upon iterations of Xe. This positions Intel as a key player, making discrete GPUs and a competitor for traditional GPU suppliers.
Key Developments
April 2026: Intel reported MLPerf Inference v6. 0 results for Intel's Arc Pro B70/B65. It showed that four GPUs based on the Arc Pro B70/B65 delivered 128 GB of VRAM in configurations for processing models up to over 120B-parameter, while the Arc Pro B70 scored up to 1.8x times higher performance compared to Arc Pro B60.
October 2025: Intel announced the addition of a future inference-friendly compute GPU called "Crescent Island”, with 160 GB LPDDR5X memory based on Xe3P architecture for the datacenter.
September 2025: Intel and NVIDIA signed a multi-generational agreement with collaboration over dedicated data-center and PC products based on integration of NVIDIA's architecture with Intel's x86 ecosystem.
May 2025: Intel announced expansion of its Arc Pro GPU offerings with the launch of the Arc Pro B60 and B50 GPUs designed for professional workstations and AI inference workloads.
Graphics Processing Unit (GPU) Market Scope:
Market Segmentation
By Type
Discrete
Integrated
Hybrid
By Deployment
On-Premise
Cloud
Public Cloud
Private Cloud
Hybrid Cloud
Edge Computing
By Component
Hardware
Software
Services
By End User Industry
Automotive
Consumer Electronics
Telecommunications
Industrial & Manufacturing
Data Center
Aerospace & Defense
Media & Entertainment
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory & Standards Landscape
4.2. GPU Manufacturing & Component Ecosystem
4.3. Semiconductor & GPU Supply Chain
4.4. Major Suppliers
4.5. Strategic Recommendations
5. GPU TRADE STATISTICS
5.1. Global GPU Import Statistics
5.2. Global GPU Export Statistics
5.3. Major GPU Importing Countries
5.4. Major GPU Exporting Countries
5.5. Trade Volume and Value Analysis
5.6. Major Trade Routes
5.7. Trade Trends and Outlook
6. TECHNOLOGICAL OUTLOOK
6.1. GPU Architecture Evolution
6.2. AI-Optimized GPU Architectures
6.3. GPU Memory Technologies
6.4. High-Bandwidth Memory (HBM)
6.5. GPU Interconnect Technologies
6.6. GPU Virtualization and Cloud Technologies
7. AI IMPACT ON THE GRAPHICS PROCESSING UNIT (GPU) MARKET
7.1. Introduction
7.2. Generative AI and Large Language Models
7.3. AI Training and Inference
7.4. AI Data Center Infrastructure
7.5. Edge AI Applications
7.6. AI-Driven GPU Supply Chain
7.7. AI-Driven Competitive Landscape
8. GRAPHICS PROCESSING UNIT (GPU) MARKET BY TYPE (2021-2031)
8.1. Introduction
8.2. Discrete
8.3. Integrated
8.4. Hybrid
9. GRAPHICS PROCESSING UNIT (GPU) MARKET BY DEPLOYMENT (2021-2031)
9.1. Introduction
9.2. On-Premise
9.3. Cloud
9.3.1. Public Cloud
9.3.2. Private Cloud
9.3.3. Hybrid Cloud
9.4. Edge Computing
10. GRAPHICS PROCESSING UNIT (GPU) MARKET BY COMPONENT (2021-2031)
10.1. Introduction
10.2. Hardware
10.3. Software
10.4. Services
11. GRAPHICS PROCESSING UNIT (GPU) MARKET BY END USER INDUSTRY (2021-2031)
11.1. Introduction
11.2. Automotive
11.3. Consumer Electronics
11.4. Telecommunications
11.5. Industrial & Manufacturing
11.6. Data Center
11.7. Aerospace & Defense
11.8. Media & Entertainment
11.9. Others
12. GRAPHICS PROCESSING UNIT (GPU) MARKET BY GEOGRAPHY (2021-2031)
12.1. Introduction
12.2. North America
12.2.1. By Type
12.2.2. By Deployment
12.2.3. By Component
12.2.4. By End User Industry
12.2.5. By Country
12.2.5.1. United States
12.2.5.2. Canada
12.2.5.3. Mexico
12.3. South America
12.3.1. By Type
12.3.2. By Deployment
12.3.3. By Component
12.3.4. By End User Industry
12.3.5. By Country
12.3.5.1. Brazil
12.3.5.2. Argentina
12.3.5.3. Others
12.4. Europe
12.4.1. By Type
12.4.2. By Deployment
12.4.3. By Component
12.4.4. By End User Industry
12.4.5. By Country
12.4.5.1. Germany
12.4.5.2. France
12.4.5.3. United Kingdom
12.4.5.4. Spain
12.4.5.5. Others
12.5. Middle East and Africa
12.5.1. By Type
12.5.2. By Deployment
12.5.3. By Component
12.5.4. By End User Industry
12.5.5. By Country
12.5.5.1. Saudi Arabia
12.5.5.2. UAE
12.5.5.3. Others
12.6. Asia Pacific
12.6.1. By Type
12.6.2. By Deployment
12.6.3. By Component
12.6.4. By End User Industry
12.6.5. By Country
12.6.5.1. China
12.6.5.2. India
12.6.5.3. Japan
12.6.5.4. South Korea
12.6.5.5. Indonesia
12.6.5.6. Thailand
12.6.5.7. Others
13. COMPETITIVE ENVIRONMENT AND ANALYSIS
13.1. Major Players and Strategy Analysis
13.2. Market Share Analysis
13.3. Mergers, Acquisitions, Agreements, and Collaborations
13.4. Competitive Dashboard
14. COMPANY PROFILES
14.1. Intel Corporation
14.2. NVIDIA Corporation
14.3. Arm Limited
14.4. Advanced Micro Devices, Inc.
14.5. Qualcomm Incorporated
14.6. Apple Inc.
14.7. Samsung Electronics Co., Ltd.
14.8. Imagination Technologies
14.9. Moore Threads Technology Co., Ltd.
14.10. MetaX Integrated Circuits (Shanghai) Co., Ltd.
14.11. VeriSilicon Microelectronics (Shanghai) Co., Ltd.
15. RESEARCH METHODOLOGY
16. LIST OF FIGURES
17. LIST OF TABLES





Frequently asked questions
What is the forecasted GPU market size by 2031?
The GPU market is projected to reach USD 289.4 billion by 2031.
What is the projected CAGR for the GPU market (2026-2031)?
The Graphics Processing Unit (GPU) Market is forecasted to grow at a 28.4% CAGR.
What are the primary growth drivers for the GPU market?
AI, machine learning, cloud computing, gaming, and HPC are key drivers.
Which technological trends are shaping the GPU market?
High-memory, rack-scale AI platforms and HBM are key trends.
How is AI impacting GPU demand in this forecast?
AI infrastructure, training, and inference are major GPU demand drivers.
Who are the key competitors in the GPU market?
NVIDIA, AMD, and Intel are major competitors driving innovation.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Graphics Processing Unit (GPU) Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/graphics-processing-unit-gpu-market