
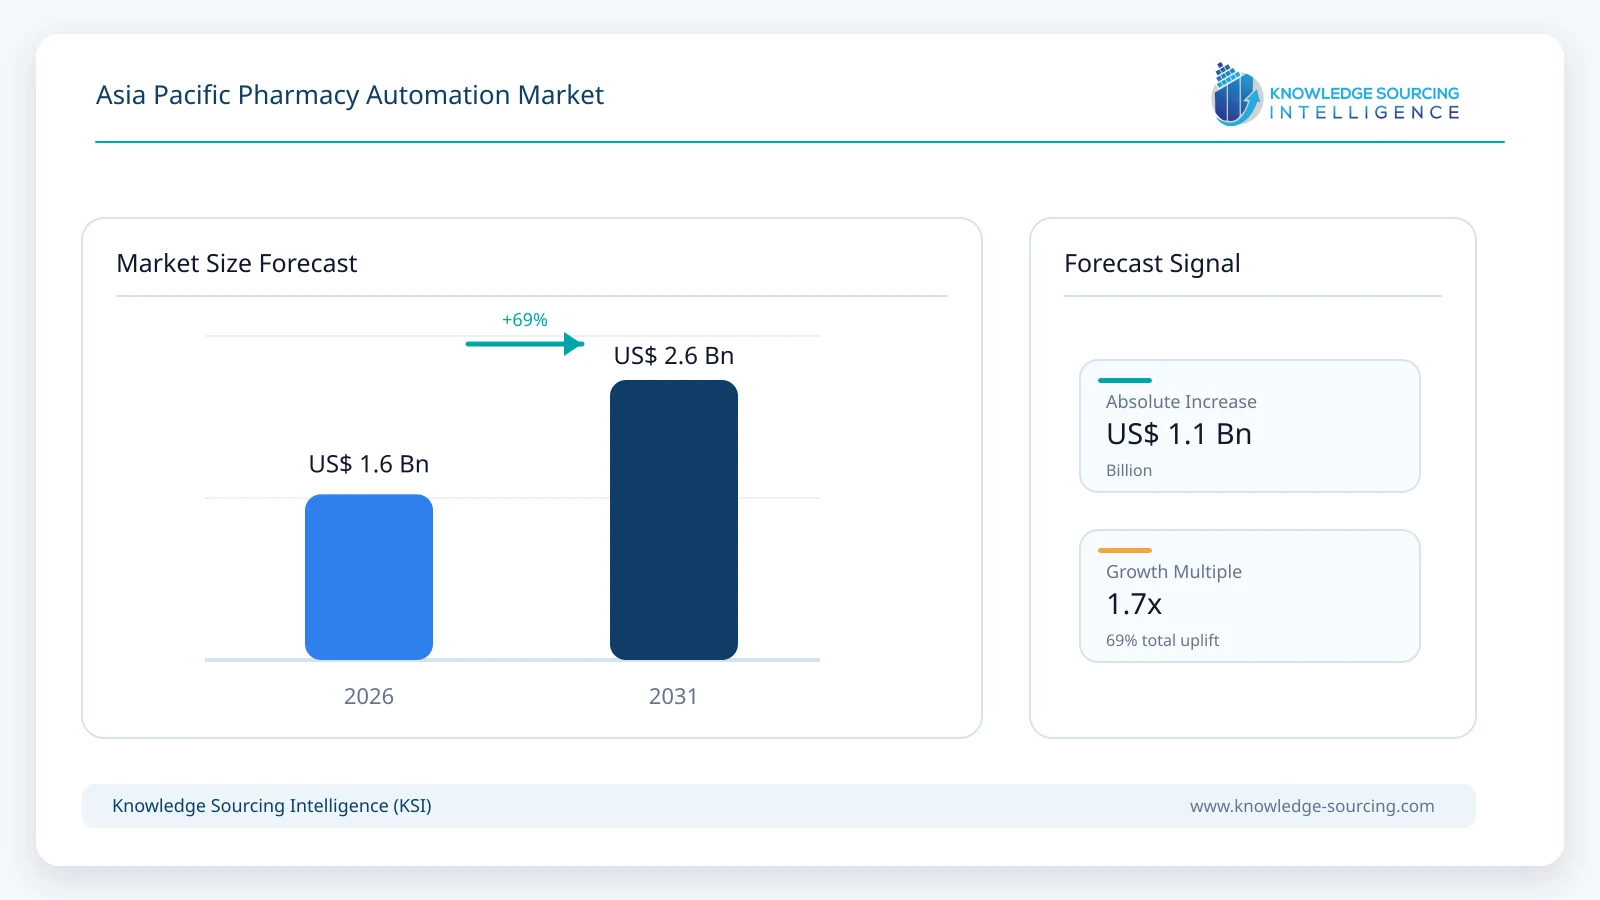
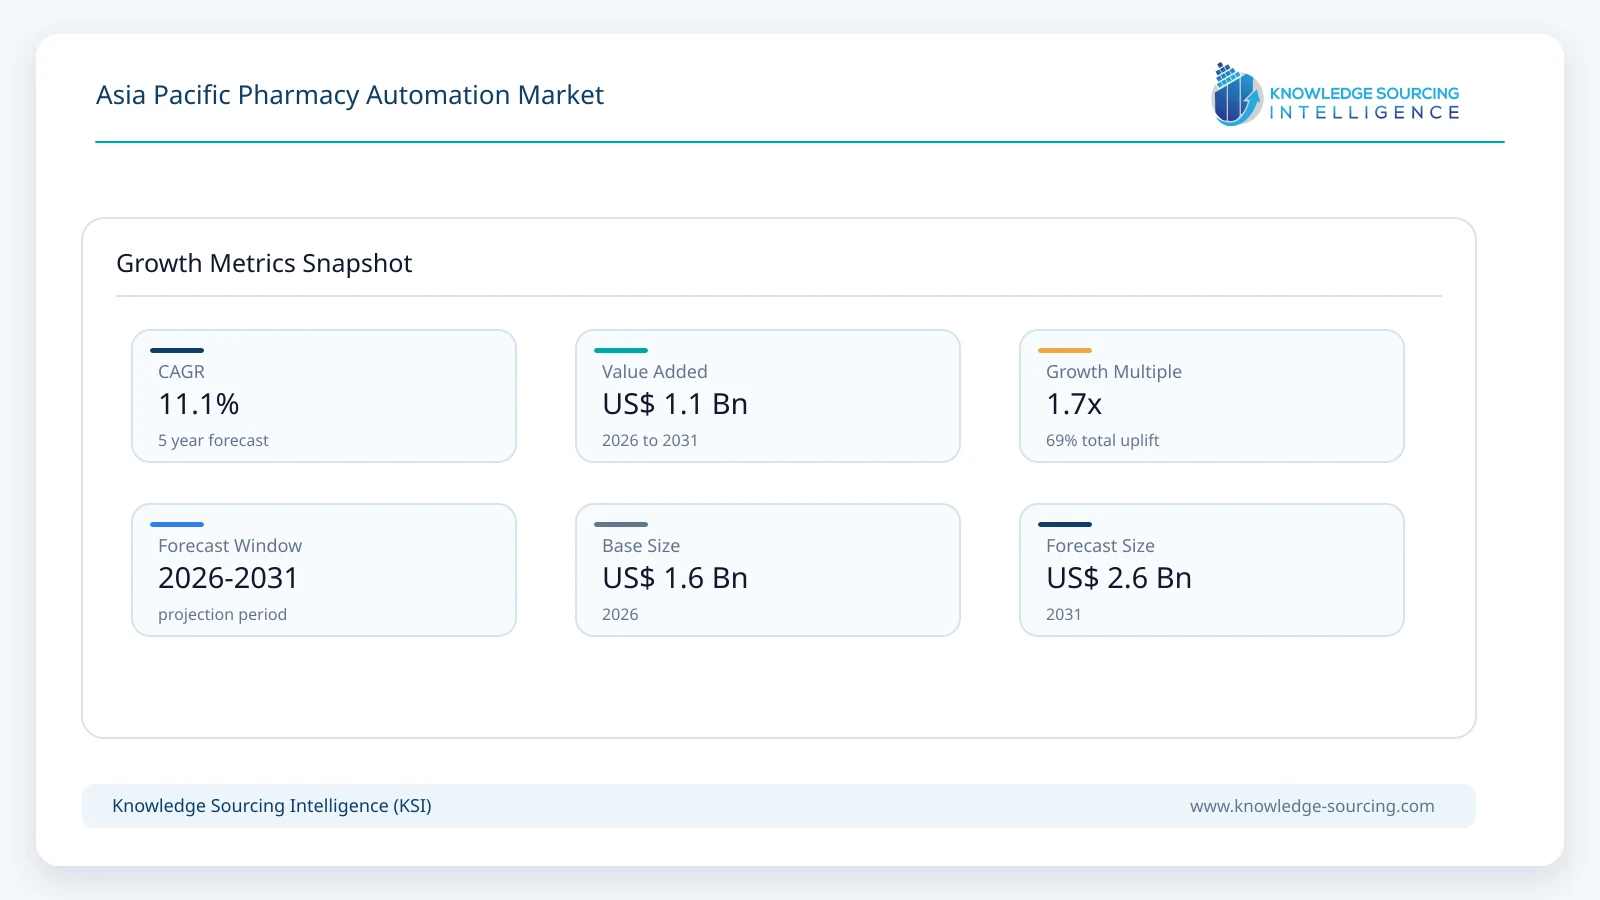
The Asia Pacific Pharmacy Automation Market is expected to expand at a CAGR of 11.1%, reaching a market size of USD 2.62 billion in 2031 from USD 1.55 billion in 2026.
Highlights:
- 1Automated medication dispensing systems represent approximately 28.4% of the 2026 application market.
- 2Hospital pharmacies remain the leading buyers of pharmacy automation equipment and integrated workflows.
- 3China is the largest national market, supported by expanding hospital medication-management installations.
- 4India records the strongest modeled country growth as hospital procurement and local servicing develop.
- 5Japanese manufacturers retain expertise in automated tablet packaging, picking and inspection technologies.
- 6Unit-dose traceability and integration with hospital information systems increasingly influence equipment selection.
Pharmacy automation encompasses systems that dispense, select, count, package, label, store and retrieve medicines for hospital and retail pharmacy operations. Automated medication dispensing cabinets, dose-packaging equipment, robotic picking systems and intravenous compounding devices are purchased to control medication movement from inventory to issue. The commercial market includes equipment, dedicated control software, deployment and directly related support; pharmaceutical product sales, general hospital logistics, and standalone electronic prescribing platforms are separate activities.
Asian procurement spans distinct operating environments. Japan-based Yuyama, TOSHO and Takazono manufacture tablet packaging and dispensing equipment suited to high-volume dispensing pharmacies; Swisslog Healthcare supplies hospital unit-dose and storage platforms, while BD combines secured medication access with workflow software. Large urban hospitals increasingly evaluate pharmacy technology in relation to inventory, patient-level medication administration and the reliability of existing clinical information systems. Smaller pharmacies generally prefer compact, modular equipment whose payback depends on labor savings and dispensing throughput.
Market Overview
China’s hospital market combines growing medication throughput with uneven levels of automation across tertiary institutions and smaller facilities. A dispensing cabinet that electronically restricts access to medicines serves a different workflow from a robot that assembles patient-specific doses, but both address manual picking, stock accuracy and documentation. Project economics depend on the mix of cabinets, central-pharmacy machinery, software interfaces, staff training and service coverage. Hospital buyers generally place more weight on uptime, auditability and compatibility with clinical operations than on equipment speed alone.
Japan has a distinct manufacturing and deployment advantage in tablet and powder packaging. Yuyama markets automated packaging machines with inspection support and cassette-based dispensing, while TOSHO supplies the Xana dispensing range and UNIPUL injection dispensing equipment. These suppliers compete through medication-form compatibility, ease of cleaning, service access and the ability to verify each pouch or dispense. Their established product platforms also support exports and localized installation partnerships in other Asian healthcare systems.
Swisslog Healthcare’s January 2026 expansion in India adds a regional example of supplier capacity moving closer to customers. Its hospital pharmacy portfolio includes PillPick unit-dose automation and BoxPicker storage, although pneumatic-tube transport and unrelated cold-chain equipment are not automatically part of pharmacy-automation revenue. Larger hospital groups can combine several complementary platforms over time. The purchasing opportunity is consequently tied to site-level workflow redesign and lifecycle support rather than a single universal machine configuration.
Market Trends
Hospital Dispensing Is Moving Toward Connected Medication Workflows
Automated cabinets are increasingly evaluated alongside barcode administration, inventory management, and pharmacy dispensing records. A hospital installing secured drug storage on wards must still confirm that the medicine selected by staff corresponds to the authorized order. Systems such as BD Pyxis combine physical access controls with data visibility, and procurement teams are asking how these functions connect with the pharmacy information system and clinical governance processes.
The investment case is strongest where electronic records, formulary data, and medicine identifiers can be reconciled reliably. Older hospitals often have fragmented interfaces, requiring additional validation before automation can reduce manual checking. Vendors able to provide integration assistance, user permissions, transaction logs, and dependable local maintenance have an advantage over equipment-only suppliers.
Japanese Packaging Systems Are Adding Automated Verification
Japanese hospitals and retail dispensaries commonly use tablet pouches for patient-specific dispensing, particularly for complex or recurring medicines. Yuyama’s PROUD-i II and Litrea-i II combine automated tablet packaging with camera-based inspection assistance; TOSHO offers integrated dispensing and tablet-handling equipment. These capabilities address a costly step in dispensing, where technicians otherwise visually check large numbers of pouches and reconcile their contents.
Camera-based checking does not remove the pharmacist’s accountability or resolve every identification problem. Its value is in flagging suspect doses, capturing the inspection record and directing staff to exceptions. Equipment replacement in mature markets therefore increasingly depends on better verification, cassette flexibility and uptime rather than merely increasing the number of packs produced each hour.
Centralized Pharmacy Fulfilment Is Increasing Equipment Scale
Large hospital networks can consolidate selected picking, packaging and storage work in a central pharmacy while retaining clinical review and final controls at care locations. High-density storage and robotic dose assembly help manage broad formularies where manually replenishing thousands of lines becomes cumbersome. Swisslog’s PillPick and BoxPicker systems illustrate the choice between unit-dose processing and automated inventory retrieval.
Centralized designs bring additional engineering requirements: medicines with different temperatures and handling risks, emergency orders, rework procedures, and redundancy when a line stops. The model favors facilities with sustained throughput rather than small hospitals with insufficient volume to use capacity. Supplier revenue consequently includes process design, validation and aftermarket servicing as well as the primary hardware.
Robotic IV Preparation Is Expanding Beyond Conventional Oral Dosing
Sterile preparation requires controlled dose calculation, handling, and verification, particularly for high-risk and oncology medicines. ARxIUM’s RIVA automated compounding system and products from specialized infusion-equipment manufacturers show a commercial category separate from oral tablet packaging. Automation can reduce repetitive preparation tasks while preserving digitally recorded formulation steps when deployed within a validated process.
Such systems must meet rigorous aseptic requirements and accommodate container variations, drug stability and dose changes. Their greater installation complexity and pharmacist validation burden limit near-term adoption to well-resourced hospitals, but they command higher average equipment value than compact retail tablet counters. Aftermarket maintenance and consumable interfaces matter materially to system availability.
Local Service Networks Are Becoming a Purchasing Differentiator
Swisslog Healthcare announced an Indian expansion centered in Gurugram in January 2026, extending its existing Asia-Pacific presence. The announcement matters because a pharmacy robot cannot be managed as an isolated capital purchase: hospitals depend on maintenance response, operator training, validated upgrades and replacement parts to protect daily medication distribution.
Japanese domestic suppliers have mature servicing structures in their home market; international vendors entering India and Southeast Asia must assemble equivalent support through branches or qualified partners. This creates an advantage for companies able to translate product specifications into reliable on-site performance, even when lower-cost equipment alternatives are available.
Segment Analysis
By Application: Automated Medication Dispensing System
Automated medication dispensing systems remain the largest individual application category because hospitals place high value on secure storage and controlled access at the point of care. Cabinet installations can be expanded ward by ward without rebuilding every central pharmacy process, while transaction records help reconcile stock and reduce uncontrolled withdrawals. BD Pyxis and comparable systems are designed around this operating problem, although the functionality delivered depends on integration with local clinical and pharmacy applications.
The segment is forecast to generate approximately USD 700 million in 2031. Expansion is supported by additional dispensing locations, stronger software connectivity and replacement of older cabinet installations. Growth is tempered by hospital tender cycles and the need to qualify the installed equipment against local medicines-management policies, especially where hospitals lack standardized barcoding or reliable digital records.
By End-User: Hospital Pharmacy
Hospital pharmacies account for an estimated 67.1% of 2026 regional expenditure, reflecting the capital intensity of central-fill robots, ward cabinets and sterile compounding platforms. A single institutional procurement can encompass several machines and integrated control functions, unlike many retail installations that address one discrete counting or packaging task. Larger hospitals also need secure handling of controlled drugs and dependable access to urgent medicines outside normal pharmacy hours.
By 2031, hospital pharmacy revenue is projected to approach USD 1.75 billion as multi-site healthcare providers upgrade dispensing and inventory processes. Purchasing remains selective: large hospitals with extensive formularies can justify integrated systems, whereas smaller facilities often begin with a tablet packager or limited cabinet deployment. Supplier competition will depend on demonstrable reliability, clinical workflow compatibility and service support.
Market Drivers
Medication Safety and Traceable Dispensing
Medication errors can arise during drug selection, preparation, issue and administration. The WHO Medication Without Harm initiative identifies unsafe medication practices as a major avoidable clinical burden. Automated cabinets, unit-dose barcodes and dispensing verification create a transaction record and reduce some manual handling opportunities, provided hospitals integrate them with prescription review and staff procedures.
Safety-related procurement is most compelling when clinical managers can identify specific high-risk medicines, error pathways or audit deficiencies. This favors software-linked equipment with user-level tracking, controlled access and exception handling rather than machines evaluated only on hourly speed.
Growing Chronic-Medicine Throughput
Asia-Pacific pharmacy operations must support growing volumes of prescriptions for long-duration therapies as populations age. The WHO has highlighted Japan’s exceptionally high share of older residents, while China faces a similarly large long-term shift in patient needs. Repeat dispensing and multi-dose regimens increase the amount of medication counting, sorting and package checking required per patient.
Automated pouch packaging and inventory picking help pharmacies handle recurring prescriptions without proportionate increases in routine manual work. The strongest demand occurs in facilities with sufficient volume and consistent medicine formats; specialized and frequently changing regimens still require pharmacist intervention.
Pressure on Qualified Pharmacy Labor
Preparing unit doses, checking packs and replenishing medicine cabinets consume technician and pharmacist time that could otherwise support clinical review. Larger urban healthcare networks face the additional challenge of staffing extended operating hours while maintaining accurate dispensing. Automation transfers selected repetitive steps to controlled systems but does not eliminate the need for qualified verification.
Labor economics differ widely across Asia Pacific. High-wage markets can more easily justify premium equipment through productivity, whereas hospitals in price-sensitive markets require evidence of lower wastage, fewer reworks and broader throughput improvements before signing capital contracts.
Expansion of Hospital Digital Infrastructure
Hospital information systems make automated dispensing more useful when medication orders, stock locations and audit events can be exchanged accurately. Procurement increasingly asks equipment suppliers to link robot or cabinet records to pharmacy management tools, barcode workflows and patient-specific medication administration.
Digital maturity is uneven across the region, but every successful integration creates a pathway for subsequent cabinet, picking or storage investment. Vendors with documented interfaces and reliable clinical support can increase the equipment content sold to existing hospital groups without requiring an entirely new customer base.
New Supplier Capacity and Service Presence
The 2026 expansion of Swisslog Healthcare in India demonstrates supplier investment in regions where healthcare facilities are assessing larger automation projects. The company’s local presence can improve consultations, installation planning and after-sales coverage for hospital pharmacy products. Japanese companies provide a separate manufacturing base with established dispensing and packaging machines.
More available service capacity can reduce the perceived implementation risk for hospital buyers. Procurement remains dependent on hospital budgets and contract award dates rather than on supplier announcements alone; local engineering is useful chiefly when it improves installation quality and operating uptime.
Market Restraints
Capital Intensity and Uneven Pharmacy Budgets
Integrated hospital dispensing equipment can require substantial investment in machinery, construction, software interfaces and staff training. Smaller hospitals and independent retail pharmacies often lack sufficient annual prescription volume to recover these costs within an acceptable period.
Tender delays and competing investments in beds, diagnostics or basic medication supply can defer automation even where manual workloads are high. Modular systems reduce the minimum entry cost, but they cannot remove the need for dependable ongoing maintenance.
Clinical-System Integration and Data Quality
Robotic dispensing requires accurate medicine records, packaging identifiers, patient orders and transaction synchronization. Hospitals relying on legacy information systems or inconsistent master data may face lengthy interface development and validation before deploying automation at scale.
Incorrectly mapped drug identifiers or untested exception workflows can compromise the value of an otherwise reliable system. The project often needs close cooperation among the pharmacy, clinical IT, nursing teams and the equipment vendor, extending the purchasing cycle.
Maintenance Burden and Limited Local Technical Support
Packaging machines contain cassettes, feeders, sensors, printers and moving mechanical parts that require maintenance and periodic calibration. Unit-dose lines and central-fill robots can become operational bottlenecks if replacement parts or specialist engineering support are unavailable.
These concerns are particularly material where imported systems serve hospitals far from the supplier’s technical base. Buyers increasingly seek spare-parts commitments, local response times and tested manual fallback procedures before making high-volume dispensing dependent on one machine.
Handling Complexity Across Drug Formats
Automated systems must accommodate different tablet shapes, fragile doses, powders, refrigerated products, hazardous preparations and changing package configurations. Not every medicine is suitable for the same cabinet, robot or pouch packager; complex cases often require manual treatment.
Facilities with diverse formularies may need several complementary devices, increasing capital spending and workflow coordination. This restrains the speed of adoption among small hospitals that cannot economically maintain multiple dedicated automation platforms.
Validation, Cybersecurity and Operational Change
Hospitals cannot assume a new dispensing machine will automatically improve safety. Access rules, data backups, cybersecurity practices, segregation of duties and human override procedures require site-specific validation, especially for controlled medicines.
Pharmacy teams also need training to recognize and correct exceptions rather than relying uncritically on automation output. Equipment replacement therefore depends on governance and change management alongside mechanical performance, and implementation can be postponed when those capabilities are insufficient.
Regional Outlook
China
China represents the largest modeled national market, accounting for approximately 32.3% of Asia-Pacific pharmacy-automation spending in 2026. Demand is concentrated in hospital pharmacies undertaking medication traceability upgrades, high-density storage projects and automated dispensing. The scale of urban tertiary hospitals supports larger systems, while domestic electronics and automation capabilities create room for integration by local suppliers. Purchasing outcomes remain sensitive to hospital budgets, procurement requirements and the quality of installed information systems.
The market is forecast to reach roughly USD 860 million in 2031. Demand should broaden beyond showcase installations as equipment interfaces and service arrangements improve, although hospital-level purchases will continue to be uneven. Hardware suppliers must demonstrate that the robot or cabinet can operate with Chinese medicines records and withstand routine volumes, rather than relying only on claimed automation capacity.
India
India is the fastest-growing separately modeled market, with pharmacy automation projected to expand at approximately 19.3% annually through 2031. The country begins from a much smaller installed base than China or Japan, but large private and tertiary hospitals are increasingly assessing automated storage, dispensing and dose verification to manage complex medication operations. Swisslog Healthcare’s January 2026 expansion in Gurugram is a concrete supplier response to this emerging procurement opportunity.
Hospital digital-system adoption and growing high-acuity clinical services favor investments in larger sites first, rather than rapid installation across every pharmacy. Procurement remains cost-sensitive, and implementation capacity is uneven across states and hospital groups. Projects most likely to proceed are those with demonstrable workload, medication-safety and stock-control benefits, backed by local maintenance support.
Competitive Landscape
The market combines Japanese manufacturers with deep experience in packaging and tablet handling and multinational healthcare automation specialists focused on hospital workflows. Yuyama, TOSHO and Takazono offer equipment spanning automatic tablet packaging, inspection support and dispensing management. Their advantage comes from configurable cassettes, familiarity with Japanese dispensing practices and extensive operating experience, rather than a single universal automation architecture.
BD supplies medication-management systems including Pyxis dispensing, while Swisslog Healthcare provides central pharmacy unit-dose and storage platforms. Omnicell, ScriptPro, ARxIUM, Baxter and other specialized vendors compete in selected dispensing, robotic fulfilment or compounding applications. Large hospital contracts depend on software interoperability, implementation resources, clinical validation and the ability to service multi-device installations. Standalone pharmacy software and generic hospital logistics providers should not be treated as direct equipment competitors unless they manufacture or supply qualifying pharmacy-automation systems.
Recent Developments
14 September 2026: BD announced the first U.S. healthcare deployment of its Vmax 160 pharmacy robot at Fairview Health Services. The development illustrates advances in centralized handling of specialty and refrigerated medicines, although it is not evidence of an APAC installation.
30 April 2026: ARxIUM reported that its RIVA sterile compounding platform had passed 19 million prepared doses in compliant environments, demonstrating sustained use of pharmacy automation in complex sterile preparation.
24 March 2026: Swisslog Healthcare introduced a compact semi-automated strip-packaging addition to its pharmacy portfolio, aimed at facilities requiring adaptable medication packaging within limited space.
11 March 2026: BD and Sinteco announced a technology partnership linking unit-dose robotics and medication management. The initial offering was directed at European hospitals and is relevant as supplier-platform development, not regional sales evidence.
29 January 2026: Swisslog Healthcare announced an expansion of its India operations based in Gurugram, strengthening its regional pharmacy-automation sales and support presence.
1 July 2025: Swisslog Healthcare launched PillPick Octave, a new automated unit-dose platform designed to improve medication handling, system diagnostics and packaging choices.
Market Outlook
Through 2031, growth in Asia-Pacific pharmacy automation will depend on how hospitals translate dispensing accuracy and staff productivity requirements into approved capital projects. China should remain the principal spending market while India contributes a disproportionate share of incremental demand from a lower installed base. Japan will continue to support a substantial replacement and refinement market for high-volume tablet packaging and inspection systems.
Manufacturers that combine dependable mechanisms with clinically validated software interfaces, local servicing and flexible deployment choices will be best positioned. Technology upgrades are likely to focus on packaging verification, stock traceability, secure ward dispensing and targeted compounding automation. Adoption will remain differentiated by pharmacy size and funding capacity, preventing uniform uptake across the region despite rising clinical demand.
Asia Pacific Pharmacy Automation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.55 billion |
| Total Market Size in 2031 | USD 2.62 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 11.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, End-User, Country |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
Automated Medication Dispensing System
Automated Packaging and Labelling System
Automatic Storage and Retrieval System
Robotic Dispensing System
IV Pharmacy
Others
By End-user
Hospital Pharmacy
Retail Pharmacy
By Country
China
Japan
India
Indonesia
Taiwan
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Asia Pacific Pharmacy Automation Market Size, 2026–2031
1.3. Application Outlook
1.4. End-User Outlook
1.5. Country Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Medication Safety and Traceable Dispensing
3.1.2. Growing Chronic-Medicine Throughput
3.1.3. Pressure on Qualified Pharmacy Labor
3.1.4. Expansion of Hospital Digital Infrastructure
3.1.5. New Supplier Capacity and Service Presence
3.2. Market Restraints
3.2.1. Capital Intensity and Uneven Pharmacy Budgets
3.2.2. Clinical-System Integration and Data Quality
3.2.3. Maintenance Burden and Limited Local Technical Support
3.2.4. Handling Complexity Across Drug Formats
3.2.5. Validation, Cybersecurity and Operational Change
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.4.1. Bargaining Power of Suppliers
3.4.2. Bargaining Power of Buyers
3.4.3. Threat of New Entrants
3.4.4. Threat of Substitutes
3.4.5. Competitive Rivalry
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Automated Dispensing and Point-of-Care Cabinets
4.2. Unit-Dose Packaging and Inspection
4.3. Storage and Retrieval Robotics
4.4. IV Compounding Automation
4.5. Pharmacy Software and Integration
5. ASIA PACIFIC PHARMACY AUTOMATION MARKET BY APPLICATION
5.1. Introduction
5.2. Automated Medication Dispensing System
5.3. Automated Packaging and Labelling System
5.4. Automatic Storage and Retrieval System
5.5. Robotic Dispensing System
5.6. IV Pharmacy
5.7. Others
6. ASIA PACIFIC PHARMACY AUTOMATION MARKET BY END-USER
6.1. Introduction
6.2. Hospital Pharmacy
6.3. Retail Pharmacy
7. ASIA PACIFIC PHARMACY AUTOMATION MARKET BY COUNTRY
7.1. China
7.2. Japan
7.3. India
7.4. Indonesia
7.5. Taiwan
7.6. Thailand
7.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Yuyama Manufacturing Co., Ltd.
9.2. TOSHO Inc.
9.3. Takazono Corporation
9.4. Becton, Dickinson and Company
9.5. Swisslog Healthcare AG
9.6. Omnicell, Inc.
9.7. ScriptPro LLC
9.8. ARxIUM, Inc.
9.9. Baxter International Inc.
9.10. Capsa Healthcare
9.11. TouchPoint Medical
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size for Asia Pacific Pharmacy Automation by 2031?
The Asia Pacific Pharmacy Automation Market is projected to reach USD 2.62 billion by 2031.
What is the compound annual growth rate (CAGR) for this market?
The Asia Pacific Pharmacy Automation Market is expected to expand at an 11.1% CAGR.
Which country is the largest national market in Asia Pacific for pharmacy automation?
China is the largest national market, supported by hospital installations.
Which country records the strongest modeled growth in the region?
India records the strongest modeled country growth as hospital procurement develops.
What application segment holds a significant share of the market?
Automated medication dispensing systems represent 28.4% of the 2026 market.
What factors increasingly influence pharmacy automation equipment selection?
Unit-dose traceability and hospital information system integration increasingly influence selection.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia Pacific Pharmacy Automation Market - Strategic Insights and Forecasts (2026–2031). https://www.knowledge-sourcing.com/report/asia-pacific-pharmacy-automation-market