
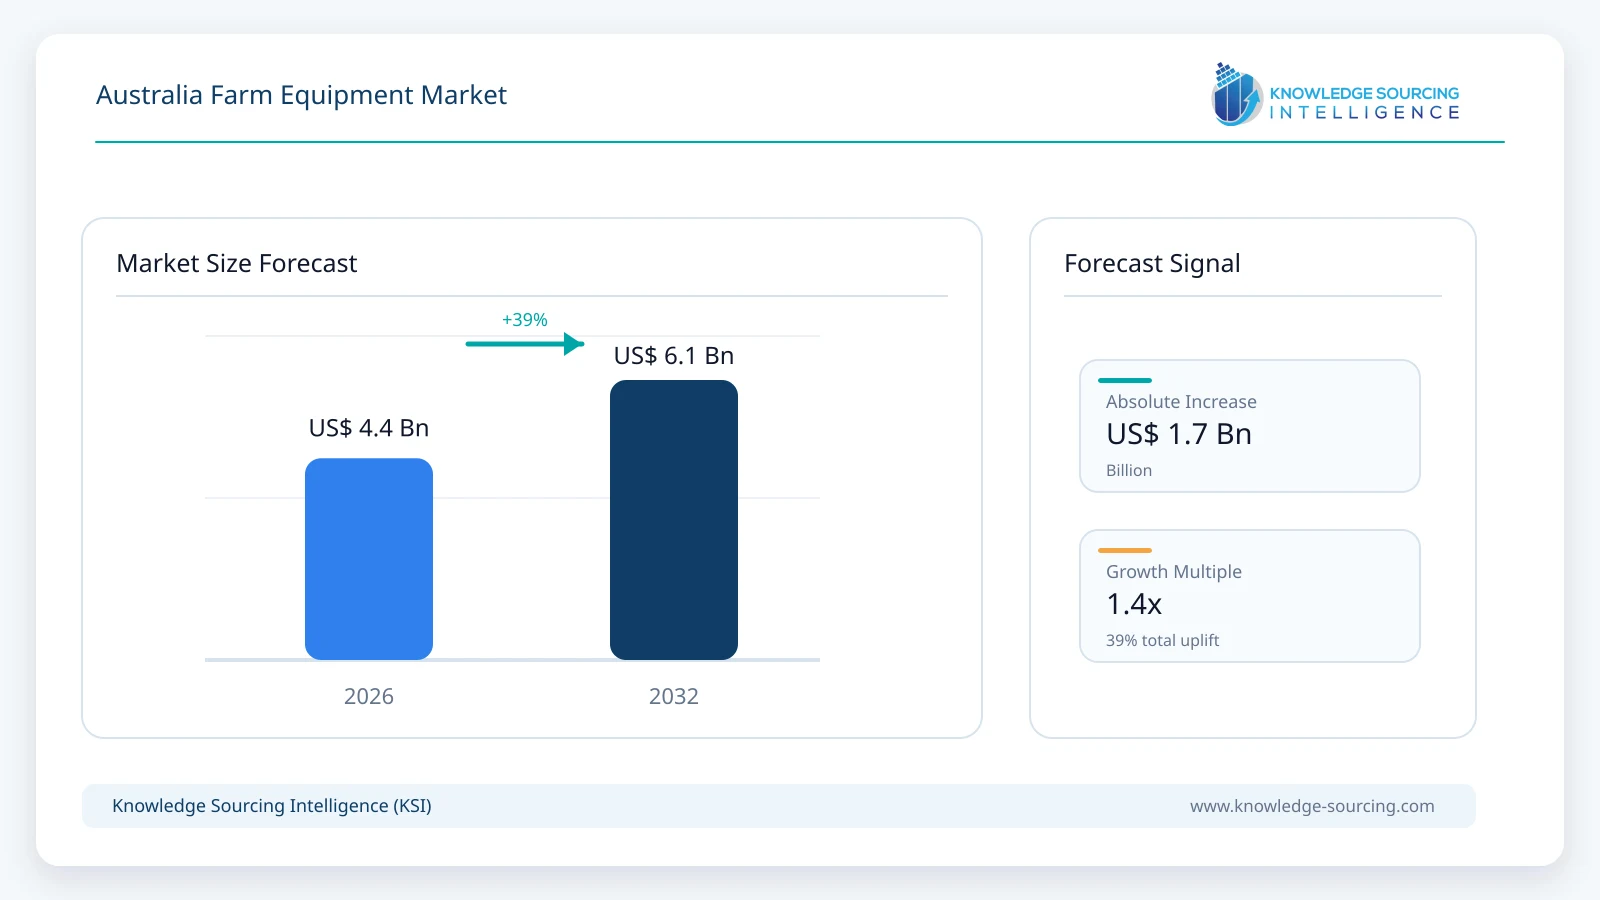
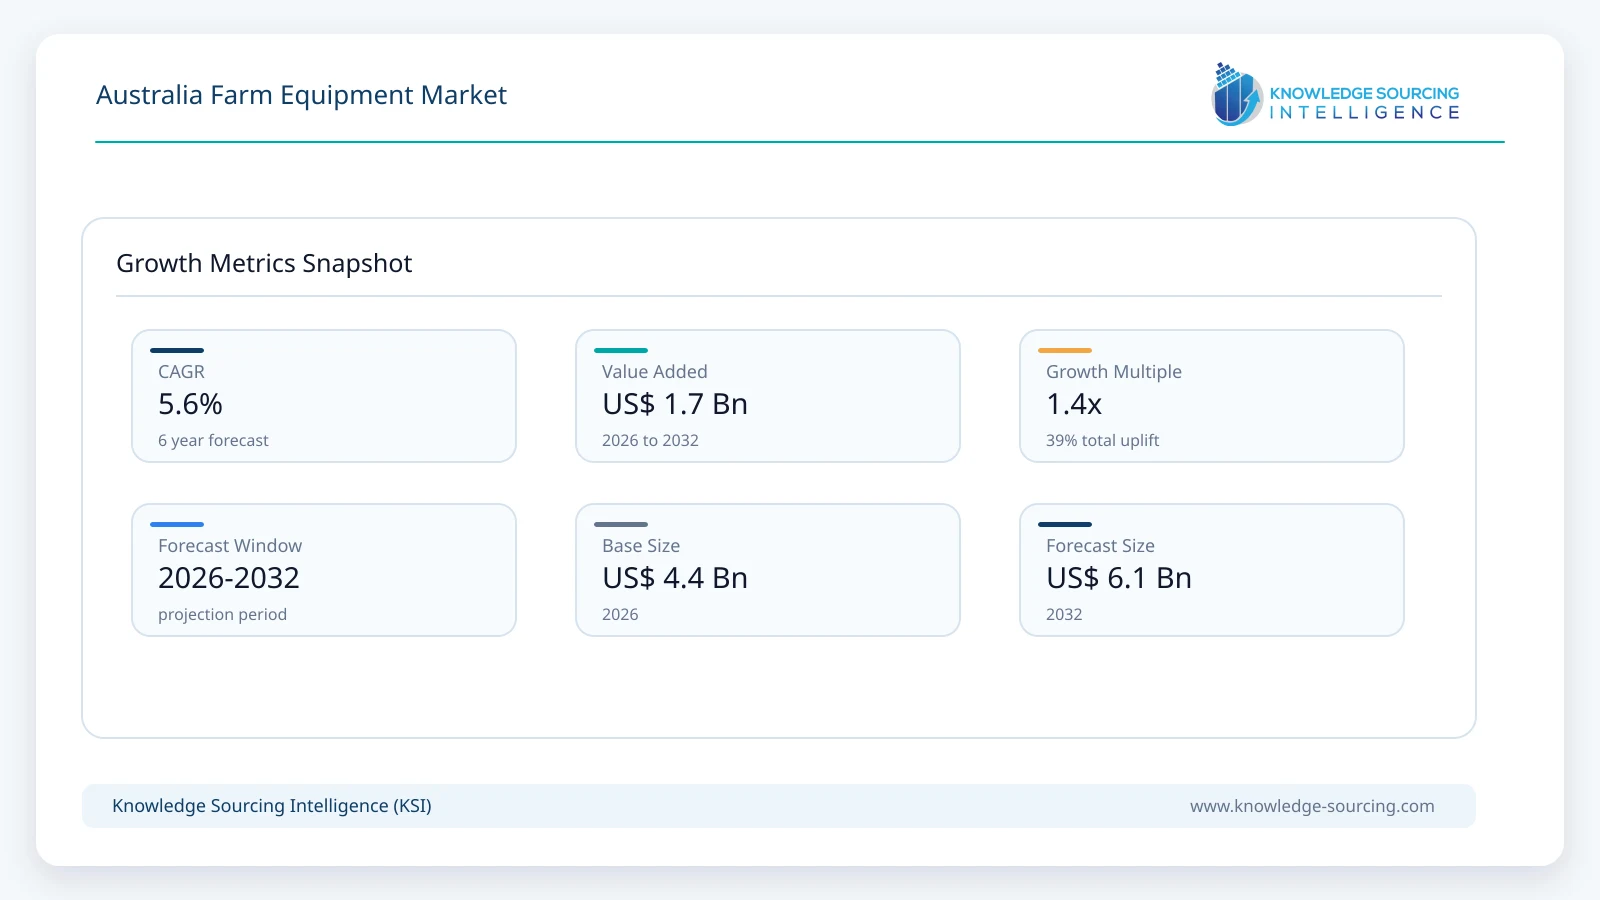
The Australia Farm Equipment Market is projected to grow from A$4.38 billion in 2026 to A$6.08 billion by 2032, registering a compound annual growth rate of 5.61% during the forecast period.
Highlights:
- 1Tractors are estimated to account for 37.7% of market revenue in 2026, supported by their use across broadacre cropping, livestock and mixed farming.
- 2The combines segment is projected to grow at a 6.81% CAGR between 2026 and 2032 as buyers invest in harvesting capacity and automation.
- 3Sprayers are estimated at A$521 million in 2026, reflecting demand for self-propelled and trailed crop-protection equipment.
- 4Planters are projected to reach A$347 million by 2032, supported by investment in planting accuracy and timely crop establishment.
- 5Hay and forage equipment is forecast to grow at a 5.50% CAGR through 2032, serving fodder production and livestock feeding requirements.
- 6Plows are estimated to represent 4.4% of the market in 2026, with demand concentrated in applications requiring soil preparation and cultivation.
Recent industry evidence supports a cautious interpretation of recovery. In its October 2026 update, the Tractor and Machinery Association of Australia reported approximately 700 combine sales over the preceding rolling twelve months, while tractor sales were down 11% year to date through September. These measures cover different reporting periods and should not be combined into a calendar-year market total. They nevertheless indicate that equipment categories are moving at different speeds. Agricultural production also provides an incomplete guide to purchasing capacity. ABARES forecast agricultural production value of A$99.4 billion for 2026–27, alongside pressure on broadacre business profitability. Machinery suppliers must therefore distinguish strong sector output from the cash available for discretionary fleet expansion.
Market Dynamics
The central demand driver is the economic value of completing field operations on time. Planting delays can affect crop establishment, while harvesting delays can expose mature crops to weather damage and quality deterioration. Machinery that improves effective field capacity can consequently protect revenue as well as reduce operating costs. However, additional capacity only creates value when the farm has sufficient acreage, suitable logistics and enough supporting labor to use it. A larger combine, for example, may require greater grain-cart capacity, additional transport and faster storage intake to deliver its expected productivity benefit. Equipment purchasing is therefore a whole-system decision. Suppliers that demonstrate how a machine fits the customer’s existing operation can make a stronger investment case than those relying on horsepower or headline throughput alone. Contractors provide another route to utilization by spreading equipment costs across several customers, although their investment decisions remain sensitive to booked work and payment reliability.
Replacement economics are shaped by financing conditions, trade-in values and the condition of the installed fleet. Farms that brought purchases forward during earlier periods of favorable cash flow may have less immediate need to replace equipment, even when production remains strong. Buyers can extend ownership through repairs, purchase used machinery or outsource particular operations before committing to a new machine. Dealers must therefore manage the relationship between new-equipment pricing and the resale value of traded machinery. Aggressive discounting may stimulate immediate orders but weaken residual values and complicate future trade-ins. Financing packages can improve affordability, although the relevant comparison is the total ownership cost over the intended holding period. Interest charges, servicing, expected resale proceeds and annual utilization all influence that calculation. A gradual improvement in orders is more credible where replacement demand is supported by farm cash generation rather than by temporary promotional activity.
Labor availability strengthens the case for automation, but it does not make every automated machine commercially justified. Guidance and steering systems can reduce repetitive operator tasks and support more consistent field coverage. Automated machine settings may also help less-experienced operators maintain acceptable performance. Nevertheless, farms still need trained personnel to supervise operations, diagnose problems and manage exceptions. The relevant benefit is the productive work completed per labor hour after accounting for setup, supervision and technical support. Connectivity constraints and mixed equipment fleets can reduce the value of advanced functions if data cannot move reliably between systems. This creates opportunities for suppliers offering practical training and dependable installation support. It also favors technology packages with clear operating benefits that can be demonstrated under the customer’s crop, terrain and workload conditions.
Technology and Product Economics
Tractors remain the largest individual product category, with revenue estimated at A$1.65 billion in 2026 and A$2.21 billion in 2032. Their broad role across cultivation, implement operation, materials handling and livestock support creates a more diversified demand base than equipment dedicated to one operation. Customers select power, transmission and hydraulic capability according to their implement fleet and annual workload. Larger machines can improve field capacity, while compact and utility models serve operations where maneuverability and versatility matter more than maximum output. Replacement decisions also depend on service access and expected residual value. This variety supports continued demand across farm types, although the category remains exposed to deferred purchases when existing machinery can meet operational needs.
Combines
The combines segment is estimated at A$770 million in 2026 and is projected to reach A$1.143 billion by 2032, representing a 6.81% CAGR. Its share of Australia farm equipment revenue is expected to rise from 17.6% in 2026 to 18.8% in 2032. This expansion reflects investment in seasonal harvesting capacity, improved grain recovery and automation that helps operators maintain consistent performance. Large broadacre businesses and harvesting contractors evaluate combines according to the area they can cover within available weather windows and the cost of keeping that capacity operational. The segment’s rising revenue contribution reflects both additional equipment demand and investment in more capable machines. Larger purchases nevertheless remain sensitive to farm cash flow, trade-in values and the availability of contracting alternatives. A favorable crop outlook supports utilization, while the replacement decision depends on whether additional capacity or lower operating risk justifies the ownership cost.
Harvesting capacity has value when it reduces delays without transferring the bottleneck to another part of the operation. Higher combine throughput may require additional grain carts, trucks and storage intake capacity to produce the expected improvement in daily output. Buyers therefore assess the complete harvesting system alongside individual machine specifications. Contractors face a related challenge: they need sufficient booked acreage to spread depreciation, finance and servicing costs across a productive season. Automation and improved crop-flow control can strengthen the investment case by supporting consistent operation across changing field conditions. These capabilities also increase the importance of operator training, software support and timely fault diagnosis. Suppliers that demonstrate the performance of a machine within the customer’s existing fleet can make a stronger commercial case than those relying solely on rated capacity. Financing and dependable preseason maintenance further influence the timing of an order.
Commercial demand for combines rests on the relationship between purchase cost and the value of reliable seasonal capacity. High throughput can reduce exposure to weather interruptions, but its financial benefit depends on crop yield, field conditions and the supporting harvest system. Manufacturers compete through grain recovery, operator assistance, fuel efficiency and service support. John Deere’s Australian introduction of the model-year 2025 S7 range in February 2024 illustrates the integration of automation into harvesting equipment. Such features can strengthen a replacement case when customers can demonstrate more consistent performance or fewer operating interruptions. Their presence alone does not establish a shorter payback period. Procurement teams must consider service requirements, subscription charges where applicable, compatibility with existing equipment and expected resale value. During harvest, a dependable local repair response can be more valuable than a small theoretical advantage in rated capacity.
Guidance Systems and Precision Equipment
Guidance systems, automated steering, remote sensing and variable-rate technology address related but different operating requirements. Guidance helps operators follow planned paths; automated steering controls machine movement; remote sensing provides information about crop or field conditions; and variable-rate equipment changes application according to an instruction or measured condition. These technologies can coexist on one machine and should not be treated automatically as mutually exclusive revenue categories. Their economics depend on reducing unnecessary overlap, improving application consistency or enabling better decisions about inputs. Benefits vary with field geometry, implement width, crop requirements and the quality of the underlying data. Retrofit systems can provide an alternative to purchasing a new machine, particularly where the existing mechanical platform remains productive. Suppliers need transparent pricing for hardware, correction services, software and support so customers can compare the full cost of adoption.
Applications and Purchasing Behaviour
Pre-harvest purchasing decisions are closely connected to the sequence of cultivation, planting and crop-protection activities. Farmers assess whether equipment can deliver the required work within available field conditions while maintaining acceptable application quality. A planter that increases daily coverage may have limited value if seed logistics or tractor availability constrain its use. Similarly, a sprayer’s economic contribution depends on coverage, application control, refill time and the ability to operate when conditions permit. Machinery suppliers can strengthen their proposals by addressing these practical constraints rather than presenting isolated equipment specifications. Demonstrations, operator training and compatibility checks help customers assess whether the proposed purchase will improve the existing production system. They can also reduce implementation problems that otherwise erode the expected benefit during the first season.
During and after harvesting, purchasing priorities extend beyond crop collection to handling, transport and residue management. Equipment utilization and the cost of interruption become particularly important because several operations must remain synchronized. Buyers compare outright ownership with contractor services, leasing and used-equipment purchases according to workload certainty and access to capital. Smaller operators may prefer flexible arrangements that avoid carrying expensive capacity between seasons. Larger farms may accept greater fixed costs where ownership provides control over timing and machine availability. Dealers influence these decisions through trade-in offers, finance, preseason inspection and parts support. A competitive proposal therefore includes a credible operating and service arrangement alongside the machine itself. Clear warranty terms and transparent repair responsibilities reduce uncertainty over the ownership period.
Regional Market Outlook
Western Australia presents a substantial broadacre machinery opportunity, with purchasing decisions strongly influenced by the scale and timing of cropping operations. Equipment capacity must be evaluated alongside transport distances, parts logistics and the availability of field service. Large machines can support extensive acreage, but remote operations also face high consequences when critical components are unavailable. Suppliers serving this market need inventory and technical support arrangements that reflect seasonal demand rather than average annual workshop activity. Precision systems can support consistent operation across large fields, although their value depends on integration with existing implements and dependable support. Replacement demand is likely to remain selective where farms can maintain current equipment without materially increasing operational risk.
New South Wales and Queensland combine broadacre cropping, livestock enterprises and more specialized production systems. Their machinery demand is consequently distributed across several equipment classes rather than concentrated in a single product type. Cropping businesses may prioritize planting and harvesting capacity, while livestock and mixed farms purchase tractors, loaders and fodder equipment for different seasonal workloads. Dealers must match their product mix and demonstrations to local applications. A broad national product range does not guarantee effective regional coverage if technicians, wear parts or specialist knowledge are difficult to access. Contractor activity can also influence local demand by concentrating purchases among businesses capable of achieving higher annual machine utilization.
Victoria, South Australia and Tasmania present further variation across grain production, dairy, horticulture and mixed farming. These operations can create demand for compact and utility tractors, hay equipment and machinery adapted to specific field or crop conditions. Maneuverability, implement compatibility and ease of maintenance may carry more weight than maximum horsepower. Customers with varied workloads often value equipment that can perform several tasks without extensive setup changes. Across these markets, regional opportunity should be assessed through the installed fleet, production system and dealer service footprint. A national growth assumption cannot capture the different replacement needs or financing capacity of individual farming regions.
Competitive Landscape and Outlook
The competitive landscape includes Deere & Company, CNH Industrial, AGCO, CLAAS, Kubota and SDF, alongside suppliers serving particular power ranges and applications. These businesses compete through different combinations of equipment breadth, technology, distribution and ownership costs. Broadacre customers may favor integrated harvesting and tractor platforms, while smaller farms may place greater emphasis on affordability and versatility. Dealer performance determines how effectively either proposition reaches the customer. Parts availability, field response and the quality of operator training influence repeat purchasing and the willingness to adopt additional digital functions. Brand-level comparisons should therefore consider the local service arrangement as well as the manufacturer’s global capabilities. Product launches demonstrate competitive activity but do not independently establish Australian market share.
Repair access and information transparency remain relevant to long-term purchasing confidence. The ACCC’s agricultural machinery market study identified concerns involving access to diagnostic tools, technical information and parts, as well as the clarity of warranty conditions. Its recommendations should be distinguished from a claim that a comprehensive agricultural right-to-repair regime is already in force. Commercially, buyers benefit from understanding which repairs can be completed locally, how software affects maintenance and what costs arise when authorized support must travel. Suppliers that explain these conditions clearly can reduce uncertainty in the ownership decision. Through 2032, the strongest competitive positions are likely to combine a credible productivity benefit with manageable operating costs and dependable service. Recovery will depend on financially justified replacement and repeat purchasing, with technology adoption supporting growth where its benefits can be demonstrated under actual farm conditions.
Recent Developments
October 2026: TMA’s September sales update reported a stronger month for combines, with approximately 700 machines sold over the preceding rolling twelve months. Tractor sales remained down year to date, indicating different demand conditions across categories.
September 2026: ABARES forecast Australian agricultural production value of A$99.4 billion for 2026–27. Its outlook also identified pressure on farm profitability, reinforcing the distinction between sector output and machinery purchasing capacity.
September 2025: Mahindra introduced three OJA sub-compact and compact tractor models in Australia, expanding its offering for smaller farms and property owners.
February 2024: John Deere introduced its model-year 2025 S7 combine range for Australia and New Zealand, with updated automation and operator-support capabilities.
Australia Farm Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | A$4.38 billion |
| Total Market Size in 2032 | A$6.08 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.61% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Product Type, Function, Technology Adoption, Application Period |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
Tractors
Combines
Plows
Sprayers
Planters
Hay and Forage Equipment
Others
By Function
Plowing and Cultivating
Sowing and Planting
Plant Protection and Fertilizing
Harvesting and Threshing
Other and Multipurpose Functions
By Technology Adoption
Guidance Systems
Remote Sensing
Variable Rate Technology
Automated Steering
By Application Period
Pre Harvesting
During and Post Harvesting
Operations Across Multiple Periods
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Guidance and Automated Steering
4.2. Remote Sensing and Field Data
4.3. Variable Rate Application
4.4. Equipment Connectivity and Interoperability
4.5. Service Access and Repair Technology
5. AUSTRALIA FARM EQUIPMENT MARKET BY PRODUCT TYPE 2026 TO 2032
5.1. Introduction
5.2. Tractors
5.3. Combines
5.4. Plows
5.5. Sprayers
5.6. Planters
5.7. Hay and Forage Equipment
5.8. Others
6. AUSTRALIA FARM EQUIPMENT MARKET BY FUNCTION 2026 TO 2032
6.1. Introduction
6.2. Plowing and Cultivating
6.3. Sowing and Planting
6.4. Plant Protection and Fertilizing
6.5. Harvesting and Threshing
6.6. Other and Multipurpose Functions
7. AUSTRALIA FARM EQUIPMENT MARKET BY TECHNOLOGY ADOPTION 2026 TO 2032
7.1. Introduction
7.2. Guidance Systems
7.3. Remote Sensing
7.4. Variable Rate Technology
7.5. Automated Steering
8. AUSTRALIA FARM EQUIPMENT MARKET BY APPLICATION PERIOD 2026 TO 2032
8.1. Introduction
8.2. Pre Harvesting
8.3. During and Post Harvesting
8.4. Operations Across Multiple Periods
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers Acquisitions Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Deere and Company
10.2. AGCO Corporation
10.3. CNH Industrial
10.4. CLAAS KGaA mbH
10.5. Kubota Corporation
10.6. SDF Group
10.7. Mahindra and Mahindra
11. APPENDIX
11.1. Currency
11.2. Market Estimation Methodology
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
List of Figures
List of Tables





Frequently asked questions
What is the projected market size for Australia Farm Equipment by 2032?
The Australia Farm Equipment Market's projected to reach A$6.08 billion by 2032.
What is the forecast CAGR for the Australia Farm Equipment Market?
The Australia Farm Equipment Market is forecast to grow at a 5.61% CAGR (2026-2032).
Which equipment segment will lead market revenue in 2026?
Tractors are estimated to account for 37.7% of market revenue.
Which segment shows strong growth in Australia's farm equipment market?
Combines are projected to grow at a 6.81% CAGR (2026-2032).
What are the primary demand drivers for farm equipment in Australia?
Timely field operations and improved effective field capacity drive demand.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Australia Farm Equipment Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/australia-farm-equipment-market