
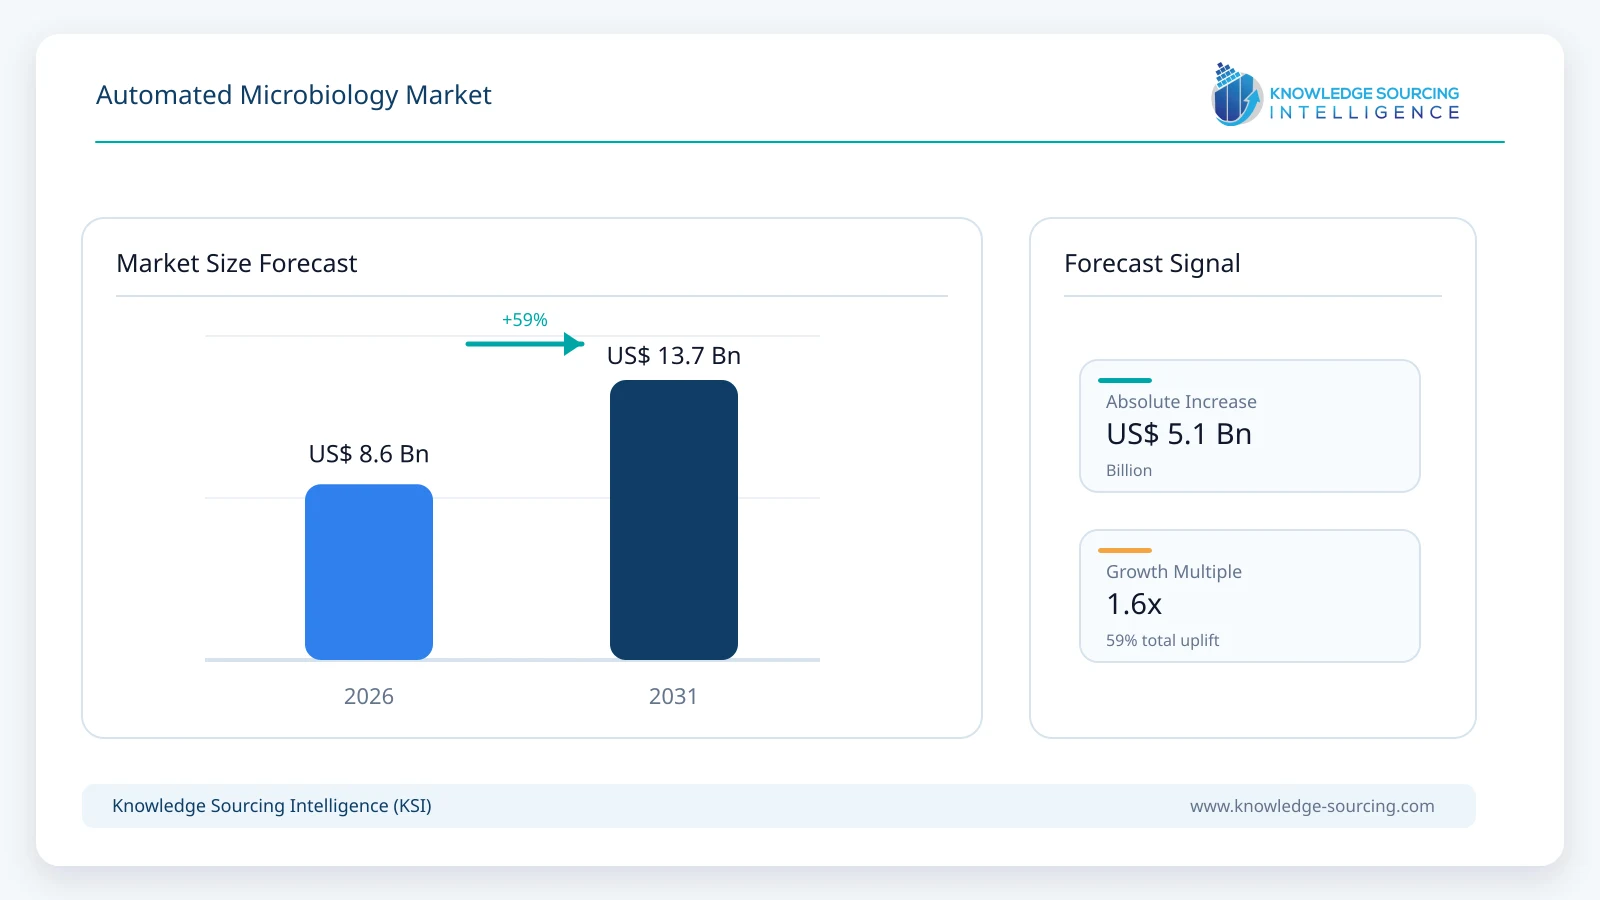
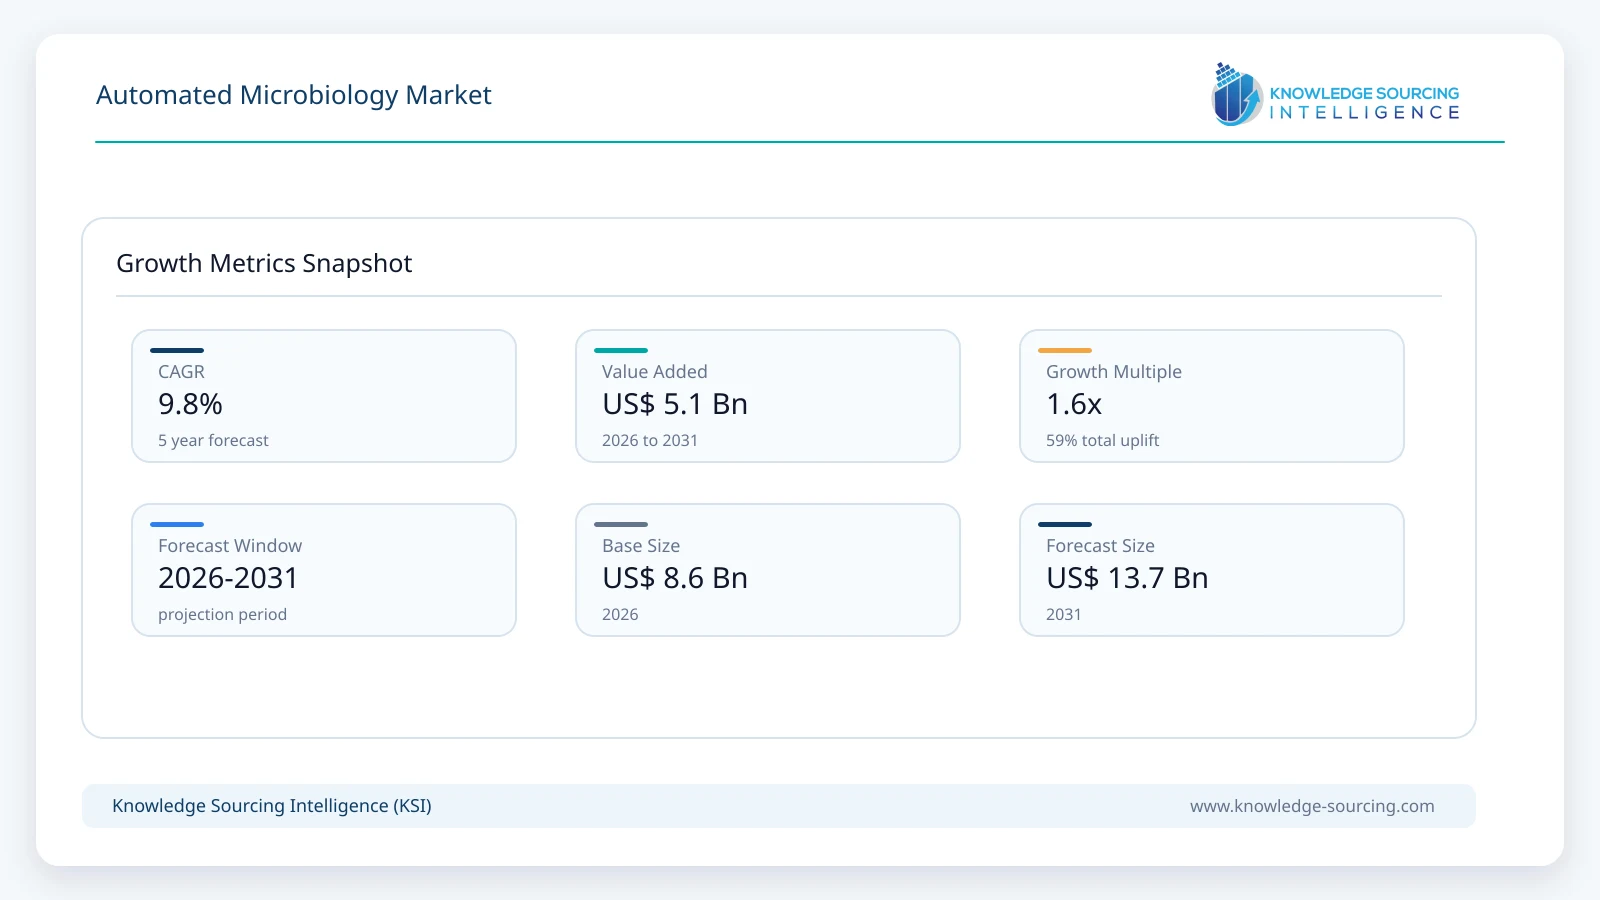
The Automated Microbiology Market is projected to increase from USD 8.6 billion in 2026 to USD 13.7 billion by 2031, growing at a CAGR of 9.8% during the forecast period.
Highlights:
- 1Hardware-led solutions account for an estimated 55% of 2026 market value.
- 2Detection platforms remain the largest technology category as culture and susceptibility testing persist.
- 3Clinical laboratories contribute an estimated 61% of demand across end-user applications.
- 4Rapid bloodstream infection panels are expanding automated pathogen and resistance-marker identification.
- 5Pharmaceutical quality-control automation is supporting documented, reproducible microbial testing workflows.
- 6Asia Pacific adoption is being reinforced by expanding laboratory capacity and molecular diagnostics.
Automated microbiology comprises instruments, software and qualifying lifecycle services that process biological specimens or environmental samples and generate microbial culture, identification, resistance or contamination results. The category includes automated incubation and plate imaging, microbial identification and susceptibility testing, targeted nucleic-acid detection, sequencing-based characterization and dedicated microbial quality-control workflows. Hospitals, reference laboratories and pharmaceutical manufacturers purchase different configurations according to specimen mix, urgency, regulatory obligations and existing laboratory infrastructure.
Clinical demand is associated with antimicrobial resistance, bloodstream infections and staffing pressure, while industrial adoption reflects the need for reproducible quality assurance in sterile and other controlled manufacturing. Recurring instrument-specific testing materials and validated service relationships give established vendors a commercial advantage, but acquisition decisions increasingly weigh interoperability, reagent menus and the consequences of instrument downtime.
Microbiology laboratories must handle several stages that cannot all be compressed into the same analytical step. Clinical cultures require inoculation, incubation, image review, isolation and sometimes susceptibility testing, while molecular tests can identify selected targets without waiting for organism growth. BD Kiestra and Copan WASPLab automate much of the culture pathway; bioMérieux VITEK and Beckman Coulter MicroScan address organism identification and susceptibility testing. Selecting the appropriate sequence is important because a rapid molecular result does not always replace conventional culture or a phenotypic resistance profile.
Instrument architecture increasingly incorporates integrated barcoding, automated sample preparation, digital plate imaging and microbiology-specific informatics. Bruker has expanded MALDI Biotyper identification libraries and workflow software, and QIAGEN has built QIAstat-Dx panels around automated multiplex molecular testing. The laboratories that benefit most have sufficient specimen volume, technical staff and information-system maturity to turn shorter instrument cycles into earlier actionable reports.
Industrial microbiology has different purchasing priorities. Rapid Micro Biosystems’ Growth Direct platform automates microbial quality-control testing in drug manufacturing, where qualification, sample traceability and audit readiness are more important than emergency clinical turnaround. Instrument sales lead to recurring demand for dedicated consumables, maintenance and validation; vendors must nevertheless demonstrate that installed systems deliver reliably across real production schedules rather than relying on nominal throughput claims.
Market Trends
Culture Workflows Are Being Connected End to End
Automated inoculation, controlled incubation and digital imaging are becoming linked stages rather than separate purchases in large clinical laboratories. BD Kiestra combines plate transport, incubation, imaging and Synapsys informatics; Copan’s WASPLab integrates automated processing with a digital bacteriology environment. These systems standardize repeatable tasks but still require qualified scientific review for unusual organisms, mixed growth and clinically sensitive results.
Procurement increasingly turns on sample-routing design, traceability and service resilience. A laboratory with multiple satellite sites may obtain greater value from standardized images and shared reporting practices than from the highest nominal plate capacity. The integration burden remains significant where instruments from several vendors must exchange order, specimen and result data with an existing laboratory information system.
Rapid Identification Is Complementing Conventional Susceptibility Testing
Bruker’s MALDI Biotyper platforms and bioMérieux’s VITEK systems target distinct points in the microbiology pathway: organism identification, resistance assessment and clinical reporting. MALDI-based microbial identification can shorten the interval after sufficient microbial growth is available, while automated susceptibility systems provide information that may be required for antibiotic selection. Neither step eliminates the need to interpret the full clinical picture.
New assays for positive blood cultures are adding faster, targeted information. QIAGEN’s QIAstat-Dx bloodstream panels detect selected pathogen targets and resistance genes in around an hour. A detected marker can guide early intervention, but a negative or incomplete molecular panel does not rule out organisms outside its target menu; phenotypic testing remains essential in many cases.
Digital Interpretation Is Evolving Through Validated Algorithms
Computer-assisted plate interpretation and microbial image analysis can reduce repetitive negative-screening work in high-volume laboratories. Copan’s PhenoMATRIX and BD’s digital culture systems illustrate the move toward structured rule-based review supported by standardized images. The immediate benefit is consistency in triage and audit trails, not unrestricted replacement of microbiologists.
Clinical adoption depends on evidence that software performs across media, specimen types and local protocols. Manufacturers need to manage software changes, data integrity and exceptional-case handling within regulated diagnostic workflows. Algorithms that are effective in a narrow development set can create additional review burden if false alerts or missed abnormalities are not controlled in routine use.
Pharmaceutical Microbiology Is Shifting Toward Automated Release Support
Rapid Micro Biosystems reported its 200th Growth Direct system placement in August 2026, reflecting growing deployment of automated microbial-quality-control systems in biopharmaceutical operations. Unlike hospital testing, these workflows are driven by lot disposition, sterile-process assurance and audit requirements. Throughput must remain reproducible across shifts, facilities and product families.
Commercial penetration depends on method validation and integration with manufacturing quality systems. Multi-site customers can standardize instruments and testing materials, but deployment frequently requires extended qualification and documentation. That creates continuing opportunities for technical services and platform-specific consumables alongside instrument replacement.
Molecular Menus Are Expanding on Existing Automation Platforms
QIAGEN’s 2026 expansion of QIAstat-Dx bloodstream infection panels demonstrates the economic importance of assay-menu breadth for installed molecular instruments. Once a laboratory has invested in a platform, adding clinically relevant panels can increase utilization without rebuilding the entire sample-processing workflow. Roche’s cobas systems illustrate the parallel model in centralized molecular testing, combining reagents, software and automated instrumentation.
Platform expansion is constrained by jurisdiction-specific clearances, test reimbursement and local disease prevalence. A new menu can have substantial clinical utility yet limited demand if it addresses an infrequent specimen category or requires confirmation by other methods. Suppliers that maintain robust menu-development and regulatory capabilities are better placed to support long-term customer contracts.
Automated Microbiology Market Segment Analysis
By Solutions
Hardware
Automated analyzers, sample handlers, incubators and digital plate systems account for the principal installed technology spending. Hardware platforms also depend on instrument-specific test materials, while digital workflow tools and service contracts contribute additional revenue across the installed lifecycle. Capital decisions require facilities to match equipment throughput and physical layout with anticipated specimen mixes.
Hardware is projected to generate approximately USD 6.99 billion in 2031. Its proportion of total revenue moderates as separately contracted software and informatics become more commercially significant. BD, Copan, bioMérieux and Bruker compete through differentiated physical workflows; regulated consumables and replacement parts support recurring engagement with the installed customer base.
By Technology
Detection Technique
The detection category is expected to approach USD 7.26 billion by 2031 as culture imaging, phenotypic antimicrobial susceptibility testing and microbial mass-spectrometry identification remain embedded in routine clinical decisions. Laboratories continue to need organism isolation and resistance characterization even as more molecular assays reach the market. The clinical utility of a new identification workflow therefore depends on its place in the complete specimen pathway rather than a single instrument cycle.
Automated culture and AST vendors differentiate through validated organism databases, interpretive rules, reagent breadth and service coverage. The share of this category eases as targeted molecular testing and microbial sequencing gain relative weight. Nevertheless, established detection systems should retain substantial replacement and consumable demand across reference laboratories and hospital networks.
By End-User
Clinical Laboratories
Hospitals and reference laboratories remain the largest end-user group because infectious disease testing requires repeatable specimen processing and interpretation at substantial daily volumes. Culture, rapid identification, molecular panels and susceptibility work are not interchangeable, which supports a diversified laboratory instrument base. Consolidated laboratory networks can standardize methods and procurement but must account for emergency work, peak volumes and specimen transport.
Clinical laboratories are expected to account for approximately USD 8.22 billion in 2031. Demand is strongest where faster results improve clinical decisions and staff can redirect time from repetitive preparation to complex interpretation. Smaller facilities may favor modular work cells or centralized referral arrangements rather than full-scale automated culture lines.
Market Drivers
Antimicrobial Resistance Requires Reliable Identification and AST
The World Health Organization reported in October 2025 that one in six laboratory-confirmed bacterial infections causing common infections in 2023 involved resistance to antibiotic treatment. For microbiology laboratories, this increases the importance of organism identification, resistance testing and rapid communication with treating clinicians. Automated identification and AST systems help manage high test volumes while maintaining standardized interpretation.
Purchasing is linked to local specimen volumes, antibiotic stewardship protocols and the need to handle emerging resistance patterns. Suppliers compete through the breadth of validated drug panels, breakpoint updates, turnaround time and interoperability with hospital information systems.
Consolidated Laboratories Need Higher and More Consistent Throughput
Reference laboratories and integrated hospital systems increasingly operate with centralized sample streams and extended processing hours. Automated inoculation, incubation and digital reading limit variability between shifts and can reduce manual plate handling. Instruments able to support both routine and urgent cases are especially valuable when sample volume is concentrated at a single site.
The engineering challenge is matching workflow capacity across upstream and downstream stations. A faster incubator creates little value if identification, susceptibility testing or result authorization becomes the new bottleneck. Buyers therefore favor systems that can be expanded modularly and supported with consistent technical service.
Biopharmaceutical Quality Control Is Becoming More Automated
Biologics and sterile drug manufacturers require documented microbiological testing of materials, environments and products. Rapid Micro Biosystems’ Growth Direct orders from large biomanufacturing customers show demand for automated quality-control processes that can be standardized across facilities. Validated testing can support improved release discipline when methods are accepted by quality and regulatory teams.
For suppliers, the financial opportunity combines instruments, customer qualification and repeat-use testing materials. Expanding a system from one site to a manufacturing network depends on the comparability of results and the ability to maintain controlled methods during software and consumable updates.
Rapid Molecular Panels Add Clinically Relevant Test Capacity
Bloodstream infection testing is a priority for hospitals because pathogen detection and resistance information affect early treatment. QIAGEN’s 2026 QIAstat-Dx panel additions extend an existing automation platform into additional diagnostic applications. Laboratories with sufficiently large and diverse specimen flows can improve the usefulness of their installed base as new panels receive authorization.
Incremental assay adoption is not automatic. Labs must weigh target coverage, patient mix, reimbursement and the continued role of conventional culture. Manufacturers with validated menus and compatible workflows are better positioned to support sustained testing revenue.
Laboratory Informatics Is Becoming a Core Procurement Criterion
Digital plate records, barcoded samples, interpretive algorithms and integrated AST data allow laboratories to manage quality at scale. BD Synapsys, Copan software and bioMérieux microbiology informatics are competing elements in the broader automated workflow. Complete traceability is especially important when testing crosses teams or requires retrospective review.
The value of software depends on dependable LIS connectivity, cybersecurity controls and rules that fit local reporting practice. Suppliers able to implement updates without disrupting validated production or clinical routines can deepen customer relationships beyond the original instrument sale.
Market Restraints
High Capital Spending and Facility Integration Costs
A full automated culture line may require equipment purchase, floor-space redesign, utilities, track connections and information-system configuration. Hospitals often prefer staged installation because clinical services must continue while new instruments are validated. Smaller laboratories may not generate enough samples to justify the complete architecture.
Investment returns also depend on actual staff deployment, reagent utilization and maintenance. Procurement teams may postpone modernization when financing is constrained or when existing systems continue to meet essential throughput requirements.
Clinical Validation and Regulatory Approval Requirements
Diagnostic platforms must demonstrate appropriate analytical and clinical performance for their intended use. The European IVDR increases requirements for evidence, conformity assessment and lifecycle surveillance, while US access depends on the applicable FDA pathway. Manufacturers cannot treat a research-use library or a development-stage algorithm as an approved clinical application.
Assay menu expansion can therefore be slower than technical development. Each new organism claim, resistance marker or software interpretation function may require studies, documentation and country-specific authorization before commercial rollout.
Workflow and Data Interoperability Difficulties
Microbiology laboratories often contain instruments from different suppliers across culture, identification, susceptibility and molecular analysis. Routing, result interpretation and specimen identifiers must remain consistent across the laboratory information system. Poor integration can lead to duplicate work, delayed reporting and complex quality investigations.
Implementation requires local interface testing and clearly assigned responsibilities for software changes. Customization creates additional lifecycle cost when laboratories merge, relocate or change their central LIS provider.
Reagent Supply and Platform Dependency
Many automated microbiology systems depend on validated, platform-specific panels, media, test cards and consumables. These materials provide reproducibility but can also limit substitution when a supplier changes availability or delivery terms. Laboratories may need sufficient buffer inventory to maintain critical testing during supply disruption.
Quality-control facilities face additional burdens because alternative materials may require comparability testing or formal method requalification. Supplier reliability and regional distribution capacity influence tender decisions alongside instrument performance.
Skills, Exceptions and Analytical Bottlenecks Remain
Fully automated specimen handling does not remove the need for experienced microbiologists to interpret unusual organisms, mixed cultures and discordant results. Digital algorithms must be supervised where clinical or regulatory consequences are material. Laboratories also need engineers and specialist staff to maintain and troubleshoot complex systems.
Automated capacity can exceed the speed of downstream review or clinical communication. Without revised operating procedures and training, higher instrument throughput may generate more unresolved cases rather than quicker actionable reports.
Regional Outlook
North America
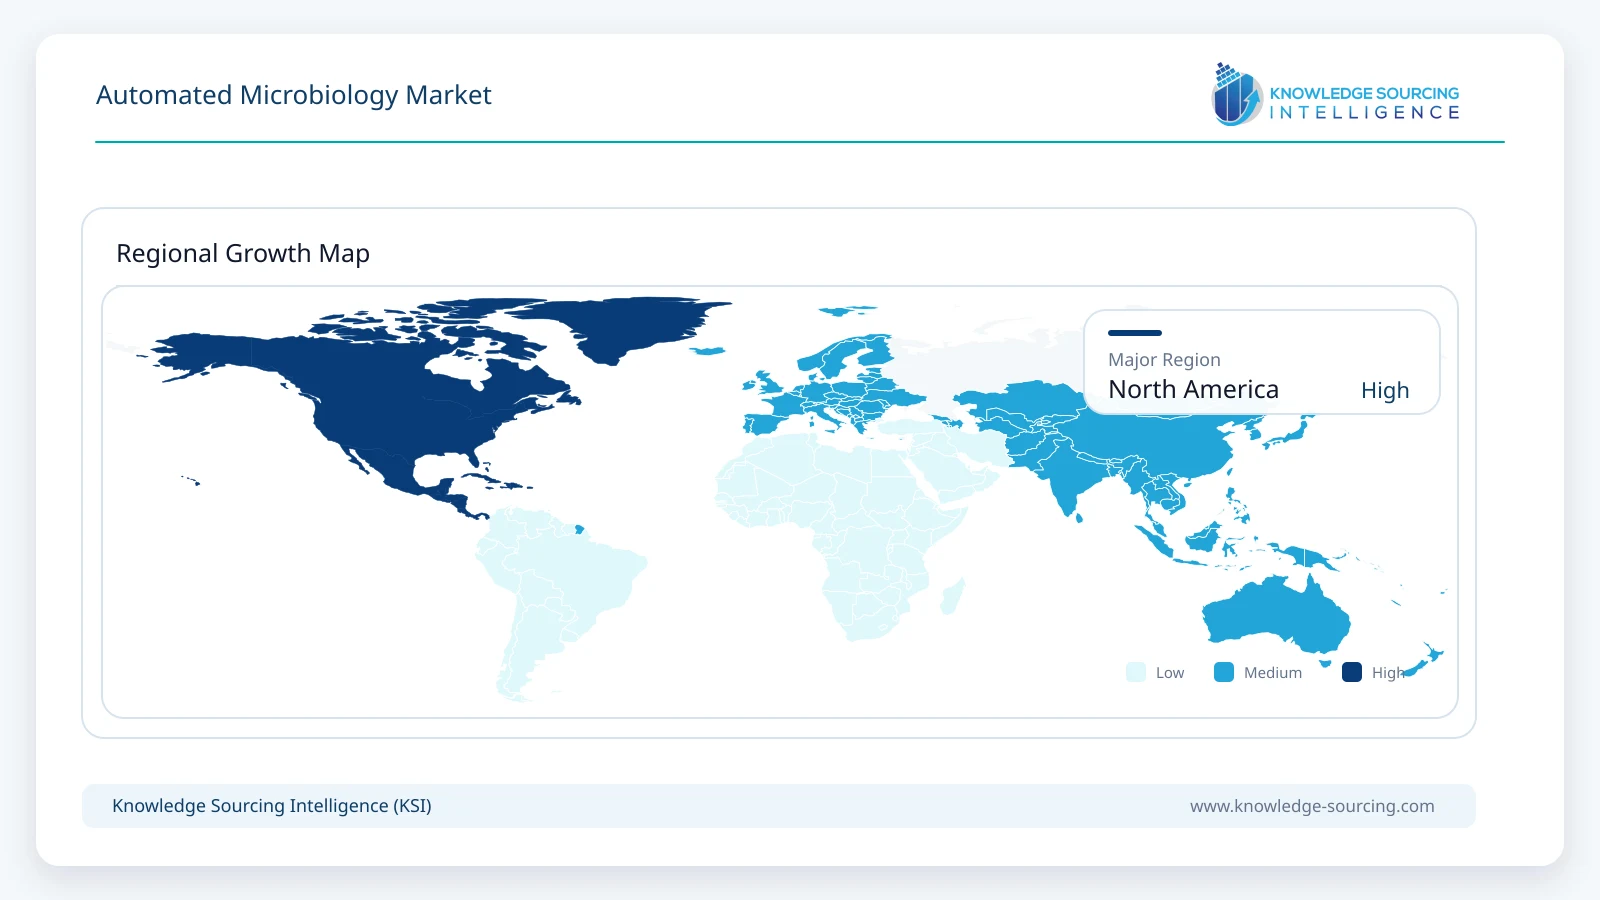
North America represents approximately 36% of global market value in 2026, supported by large US hospital and reference laboratory networks, sophisticated clinical microbiology testing and substantial biopharmaceutical production. Automated culture, identification, molecular diagnostics and regulated manufacturing QC all contribute to demand. The US market is especially important for technologies requiring FDA authorization and for suppliers with extensive technical-support infrastructure.
Reference laboratories continue consolidating testing workloads, while pharmaceutical manufacturers are extending automated microbial monitoring across multiple production sites. Established vendors benefit from instrument fleets and ongoing reagent revenue, but procurement requires evidence that new workflows materially improve laboratory performance.
Asia Pacific
Clinical testing capacity and pharmaceutical manufacturing investment are expanding the market for automated microbiology across China, India, Japan and South Korea. Demand varies substantially: mature Japanese laboratories emphasize performance consistency and support, while Chinese and Indian adoption is also influenced by hospital modernization, competitive pricing and localized product availability. Country-specific diagnostic registration remains important for supplier market access.
Asia Pacific is expected to grow by approximately 13.1% annually through 2031, faster than the global average. Greater use of molecular panels, growing infection-testing volumes and industrial QC standardization support expansion, although differences in reimbursement and laboratory budgets limit uniform adoption across the region.
Competitive Landscape
BD and Copan are particularly active in culture workflow automation, where the integration of specimen processors, incubation, imaging and laboratory software determines system effectiveness. bioMérieux and Beckman Coulter compete in microbial identification and susceptibility testing, while Bruker has an established position in mass-spectrometry-based microbial identification. Thermo Fisher supplies automated phenotypic susceptibility solutions through Sensititre, and Interscience addresses automated incubation and colony enumeration.
QIAGEN, Roche and Hologic participate through integrated molecular platforms and in-scope infectious disease assay menus. Their competitive position is shaped by assay coverage, instrument installed base, analytical throughput, automation level and regulatory authorizations. Rapid Micro Biosystems is more closely concentrated on pharmaceutical microbial quality control, where enterprise rollouts, validation support and consumables carry substantial commercial value.
Suppliers compete less on a single instrument specification than on workflow fit, method performance, service continuity and long-term cost per reportable result. Broad-platform manufacturers can pursue integrated contracts, while specialists may win technically demanding tasks through superior workflow integration or faster quality-control release methods. The most durable relationships typically combine instruments, recurring test materials, software updates and specialist implementation support.
Recent Developments
September 2026: QIAGEN announced FDA clearance of the QIAstat-Dx BCID GN Plus AMR Panel, completing its US bloodstream infection testing menu with complementary gram-negative and gram-positive/fungal panels.
August 2026: QIAGEN received FDA clearance for the QIAstat-Dx BCID GPF Plus AMR Panel, extending its automated syndromic platform into US bloodstream infection diagnostics.
August 2026: Rapid Micro Biosystems reported the placement of its 200th Growth Direct system worldwide, alongside additional system placements and customer validations.
July 2026: QIAGEN launched its CE-IVDR-certified QIAstat-Dx BCID GN Plus AMR Panel in Europe, adding targets for gram-negative pathogens and antimicrobial resistance markers.
June 2026: Bruker presented expanded FDA-cleared MALDI Biotyper CA capabilities and new research-use microbial identification tools at ASM Microbe 2026.
March 2026: Rapid Micro Biosystems announced a follow-on multi-system Growth Direct order from Samsung Biologics for microbial quality-control automation across its manufacturing network.
Market Outlook
Automated microbiology will continue to evolve as a connected set of culture, identification, susceptibility, molecular and quality-control functions rather than a single replacement technology. Laboratories are likely to prioritize applications that reduce time to actionable information and improve reproducibility while preserving appropriate scientific review. Expanding molecular menus and faster organism identification will complement, not eliminate, culture and phenotypic AST in many clinical settings.
Additional software functionality should shift more customer spending toward integrated workflow management, digital interpretation and traceability. The economic benefit will vary with specimen volume, staff availability and the extent to which a laboratory can redesign processes around instrumentation. In pharmaceutical manufacturing, standardization across multiple production sites can justify larger installation and validation programs.
Established manufacturers with broad assay coverage, strong technical service and sustainable reagent supply should remain well positioned. Specialist providers can compete where automated quality control or high-resolution microbial identification solves a narrower, valuable workflow problem. Regulatory evidence, country-specific clearances and reliable system integration will remain decisive factors in commercialization.
Automated Microbiology Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 8.6 billion |
| Total Market Size in 2031 | USD 13.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solutions, Technology, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solutions
Hardware
Software
Services
By Technology
Detection Technique
DNA and RNA Probe Sequencing
DNA Sequencing
Others
By End User
Pharmaceutical and Biotech Companies
Clinical Laboratories
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Antimicrobial Resistance and Identification Demand
3.1.2. Clinical Laboratory Throughput
3.1.3. Biopharmaceutical Microbial Quality Control
3.1.4. Rapid Molecular Panel Adoption
3.1.5. Connected Informatics and Traceability
3.2. Market Restraints
3.2.1. Capital and Facility Costs
3.2.2. Regulatory Approval and Validation
3.2.3. Data and Workflow Interoperability
3.2.4. Proprietary Reagent Supply
3.2.5. Specialist Skills and Exception Review
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Automated Culture and Plate Imaging
4.2. Organism Identification and Phenotypic AST
4.3. Molecular Detection and Microbial Sequencing
4.4. Digital Interpretation and Laboratory Informatics
5. AUTOMATED MICROBIOLOGY MARKET BY SOLUTIONS
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
6. AUTOMATED MICROBIOLOGY MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Detection Technique
6.3. DNA & RNA Probe Sequencing
6.4. DNA Sequencing
6.5. Others
7. AUTOMATED MICROBIOLOGY MARKET BY END-USER
7.1. Introduction
7.2. Pharmaceutical & Biotech Companies
7.3. Clinical Laboratories
7.4. Others
8. AUTOMATED MICROBIOLOGY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Becton, Dickinson and Company
10.2. bioMérieux SA
10.3. Copan Italia S.p.A.
10.4. Bruker Corporation
10.5. Thermo Fisher Scientific Inc.
10.6. Beckman Coulter, Inc.
10.7. QIAGEN N.V.
10.8. Rapid Micro Biosystems, Inc.
10.9. Interscience
10.10. Roche Diagnostics
10.11. Hologic, Inc.
10.12. Merck KGaA
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size and growth rate for automated microbiology by 2031?
Market will reach $13.7 billion by 2031, growing at 9.8% CAGR.
Which technology category holds the largest share in the Automated Microbiology Market?
Detection platforms remain the largest technology category.
Which end-user segment contributes most significantly to market demand?
Clinical laboratories contribute an estimated 61% of demand.
What are the key drivers for clinical demand in automated microbiology?
Antimicrobial resistance, bloodstream infections, and staffing pressure drive demand.
Which region shows strong adoption growth in the Automated Microbiology Market?
Asia Pacific adoption is reinforced by expanding laboratory capacity.
What is the estimated market value share of hardware-led solutions in 2026?
Hardware-led solutions account for 55% of the 2026 market value.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Automated Microbiology Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automated-microbiology-market