
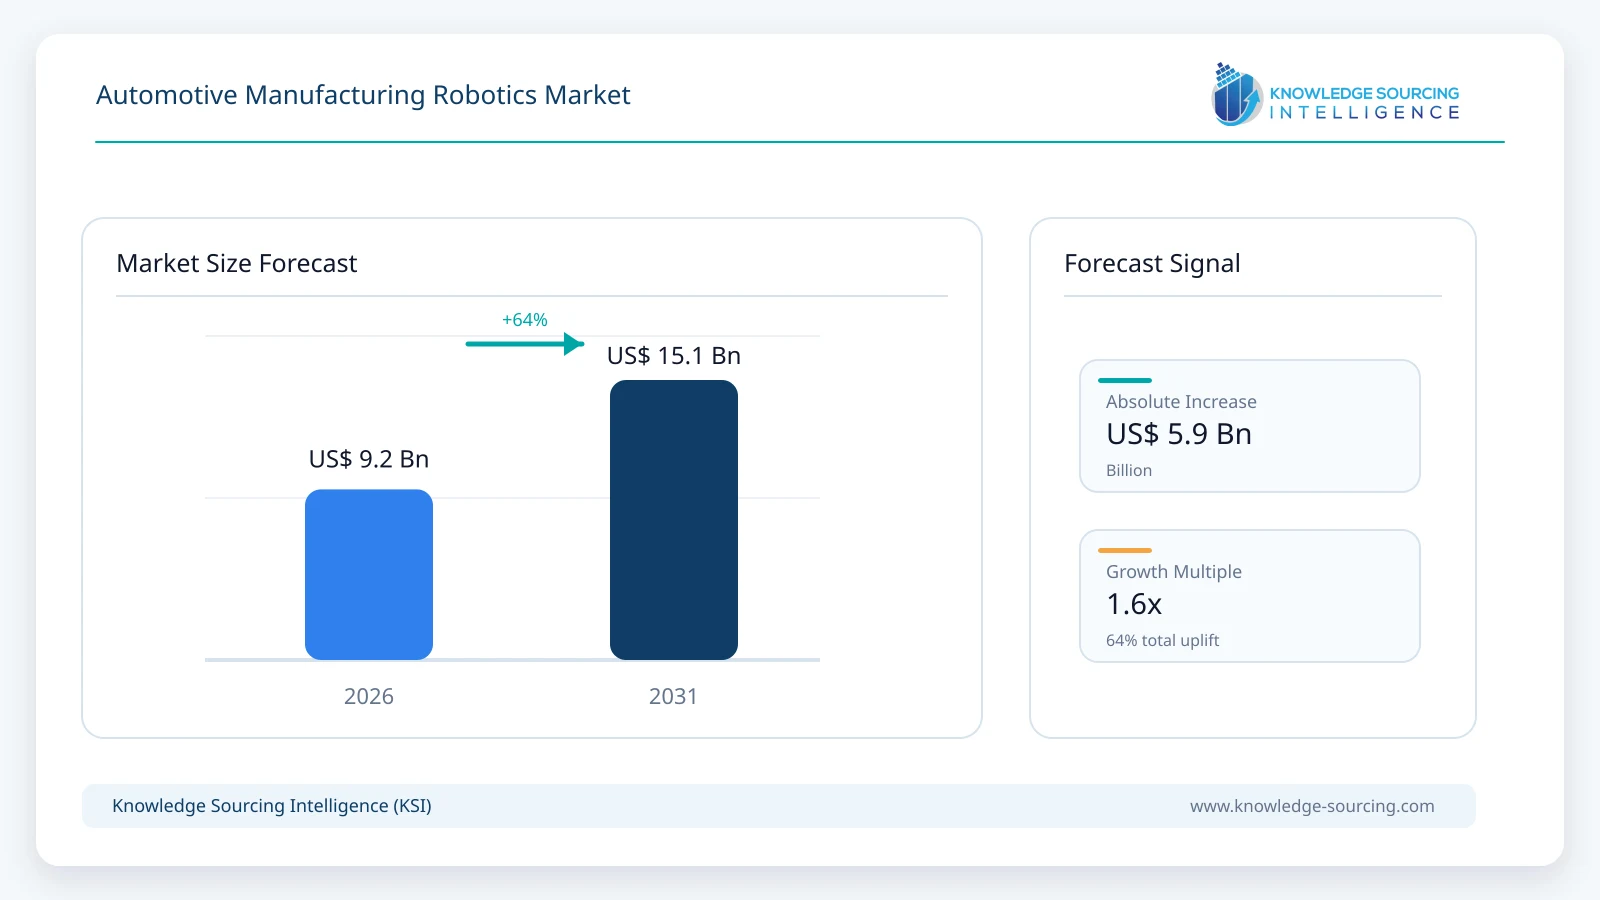
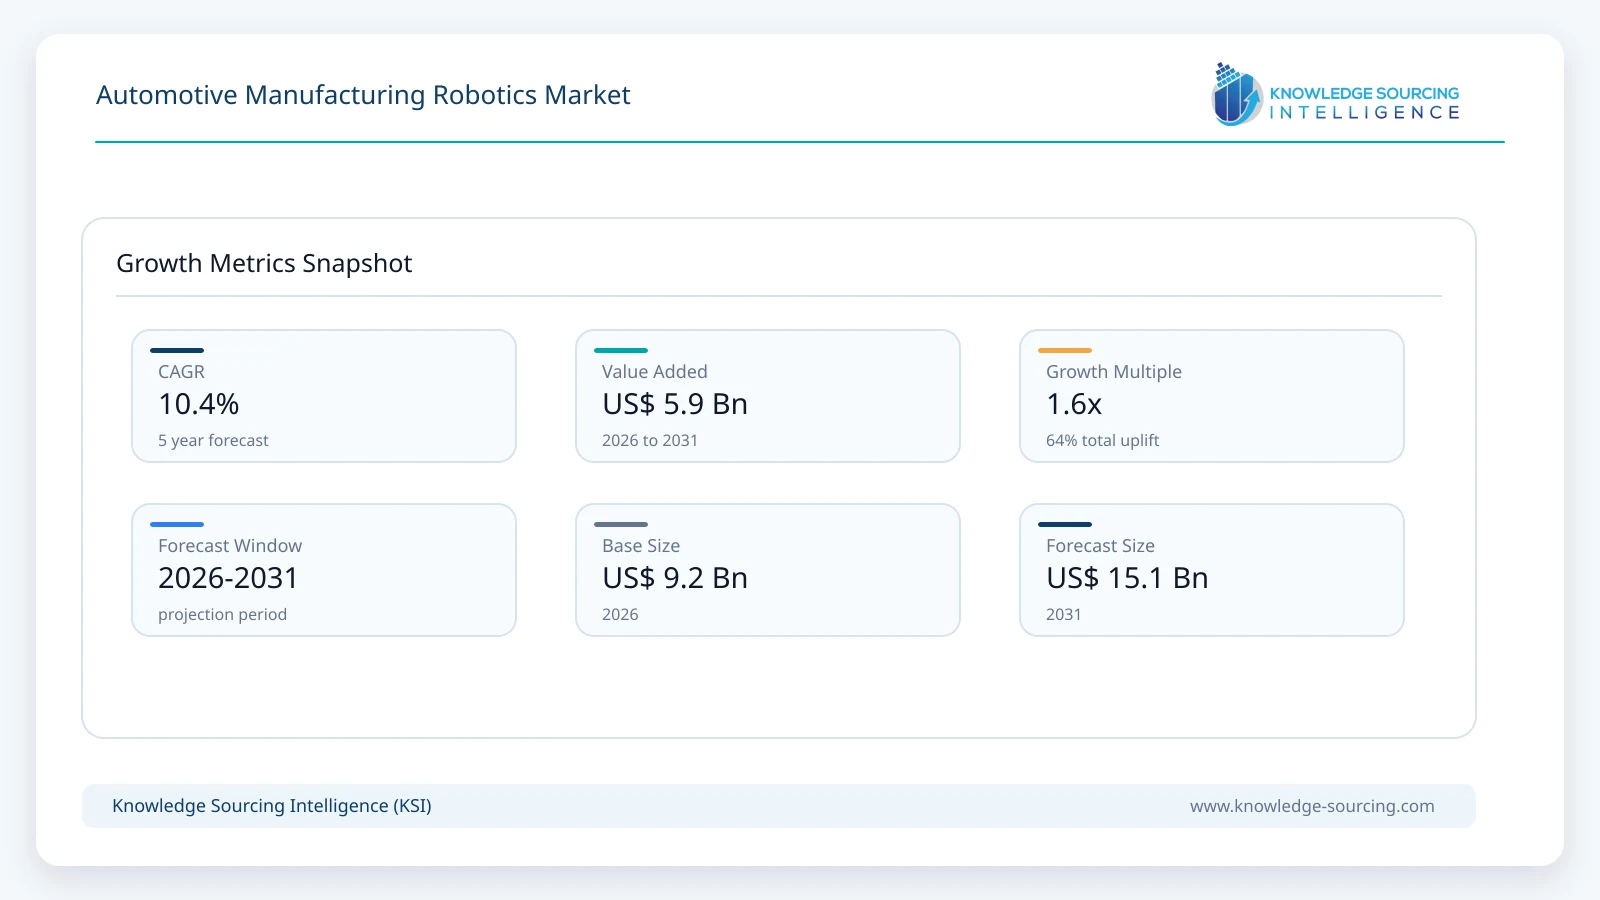
The Automotive Manufacturing Robotics Market is expected to expand at a CAGR of 10.4%, reaching USD 15.10 billion in 2031 from USD 9.20 billion in 2026.
Highlights:
- 1Articulated robots remain the core production technology for welding, painting and heavy handling.
- 2Welding represents roughly 34% of initial market value, anchored in body-in-white operations.
- 3Software and commissioning services gain importance as plants require rapid model changeovers.
- 4Component manufacturers increasingly invest in repeatable battery and electronics assembly processes.
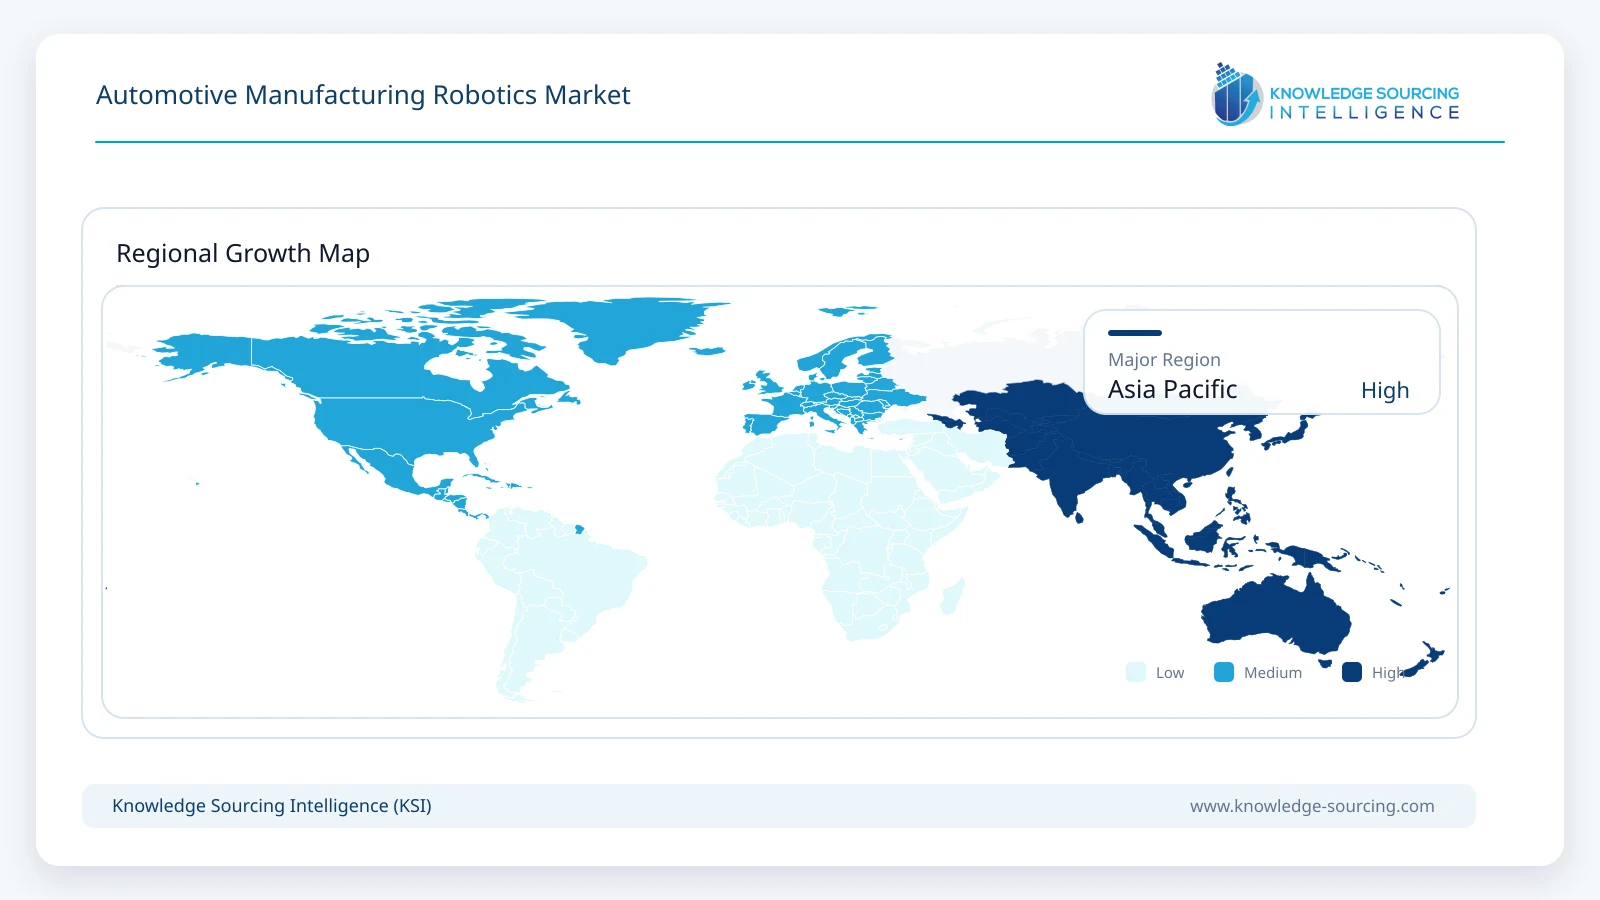
- 5Asia Pacific retains its dominant position, led by China’s automotive manufacturing ecosystem.
- 6South America provides an emerging growth opportunity as Brazilian automotive robot installations recover.
Industrial robots used in vehicle and component production perform repetitive, precisely controlled operations across body construction, paint shops, powertrain and battery manufacturing, and final assembly. Automotive programs purchase articulated, SCARA, parallel, collaborative and Cartesian robots with controllers, programming software and directly attributable installation and lifecycle services. Spending on entire production facilities, standalone conveyors, general factory IT and autonomous mobile fleets is distinct from the industrial robot content evaluated here.
Demand depends as much on program timing and production flexibility as on vehicle output. KUKA supplies body-in-white and friction-stir-welding automation; ABB provides painting, welding, handling and collaborative robot products; FANUC and Yaskawa serve joining and assembly operations through broad articulated-robot ranges. Automation investments are increasingly judged against commissioning time, multi-model reprogramming effort, weld consistency and long-term service availability rather than maximum robot speed alone.
Market Overview
Industrial robot installations in the automotive industry rose by approximately 10% in 2025, according to the International Federation of Robotics, after the industry installed 126,088 units in 2024. The recovery occurred within a global industrial robot market that reached more than 603,000 installations in 2025. For automotive plants, the critical distinction is between robots that replace an existing fixture-and-motion routine and systems that can accommodate revised parts, assembly sequences and inspection requirements without a complete cell rebuild.
Body-in-white joining remains the most robot-intensive operation. Large articulated arms carry spot-welding guns, while smaller six-axis machines handle sealant application, arc welding and component transfer. Battery trays, structural castings and mixed-material vehicle bodies introduce additional process-control requirements. KUKA’s documented use of friction-stir-welding cells for EV battery cases illustrates the engineering value of application-specific robots and tooling; ABB and Yaskawa offer robot families spanning joining, painting and precise material handling.
Manufacturing investment is not uniform. China’s extensive vehicle and component base supports large installation volumes, while Japanese and European suppliers continue to provide advanced robot engineering. In the United States, the IFR recorded approximately 13,500 automotive industrial robot installations during 2025. Buyers increasingly combine conventional robotic arms with simulation, vision and lifecycle services, but high-volume adoption still depends on reliable cycle times, safety engineering, experienced system integrators and equipment support over several vehicle generations.
Market Trends
Robot Cells Are Being Designed for Multiple Vehicle Architectures
Automakers increasingly expect one body or assembly installation to handle vehicles with different dimensions, propulsion layouts or battery packaging. The resulting integration work extends beyond changing a robot program: weld-gun access, clamping forces, part presentation and quality inspection must remain stable across variants. KUKA’s automotive engineering work demonstrates how flexible robotic welding can be embedded into mixed-powertrain production rather than tied to a single vehicle type.
Capital approval increasingly favors cells with reusable robot controllers, configurable end effectors and simulation tools that reduce physical rework. Such flexibility is particularly valuable when new model launch schedules are uncertain. Suppliers able to validate several operating recipes before installation can reduce shutdown windows during plant conversion, although specialized fixtures and safety approvals remain necessary.
Robotic Vision Is Extending Automation Into Variable Assembly Tasks
ABB introduced OmniCore EyeMotion in September 2025 to combine camera information with robot motion, while KUKA and FANUC continue developing vision-enabled control for more complex operations. These tools address positioning variability in material handling and inspection, where every part cannot be assumed to arrive in precisely the same orientation. In final assembly, however, fast robot motion must be coordinated with workers, moving conveyors and product variation.
The immediate opportunity is generally better guidance and shorter commissioning, not fully independent factory operation. Camera calibration, lighting, process validation and fallback logic still determine performance. Vehicle plants purchasing intelligent software will favor functions that improve production uptime and documented defect rates without disrupting existing robot fleets.
Battery and Large-Component Handling Require More Payload Versatility
Battery trays, large castings and heavy vehicle modules create demand for long-reach industrial arms capable of handling awkward loads while preserving repeatability. KUKA’s February 2026 KR TITAN ultra introduction addresses heavy-duty applications that include automotive manufacturing and battery components. Smaller high-speed robot variants remain relevant for fastener installation, parts presentation and subassembly work, making factory design a mix of payload classes rather than a single platform.
Robot specifications increasingly depend on effective payload including the gripper, cable management and tooling, rather than the nominal mass of the component alone. Integration expenses rise where heavy loads require foundation changes, special guarding or longer validation cycles. Equipment suppliers with a broad range and spare-parts support can compete on lifecycle availability as well as initial performance.
Simulation and Security Are Becoming Part of Robot Procurement
RobotStudio, KUKA software and manufacturer-specific offline programming tools are being used to plan robot paths before production stoppages. In July 2026, KUKA reported deployment of its Automation Management Platform at its Ohio automotive operations, showing how production data can be connected to existing automation infrastructure. Although the initial deployment focused on mobile robots, it demonstrates a growing requirement to manage mixed generations of equipment within the same plant.
Connected controllers also increase the importance of network access management and secure software updates. Automotive manufacturers often operate equipment across long program lifecycles, so a controller must be maintainable well beyond the date of first installation. Cybersecurity and interoperability can determine a plant’s supplier selection even when the robotic arm itself meets every mechanical requirement.
Segment Analysis
By Type: Articulated Robots
Articulated robots account for an estimated 76% of automotive manufacturing robotics value in 2026. Multi-axis motion allows the same platform family to support spot welding, painting, adhesive dispensing, machine tending and large-part transfer with different tooling and controller configurations. Their position is reinforced by body shops where hundreds of coordinated arms may operate within one production area.
Higher use of collaborative robots in subassembly and final-assembly tasks gradually changes the product mix, but conventional articulated systems remain dominant through the forecast period. The competitive advantage is increasingly linked to established automotive programming libraries, robust cable dressing and predictable service support, not only reach or payload performance.
By Component: Hardware
Robot hardware continues to carry most initial project value because motors, reducers, structural arms, controllers and safety-rated elements require tightly controlled manufacturing. A vehicle plant typically purchases several sizes of articulated robots along with welding or handling interfaces that must remain available over repeated production cycles. The value of simulation and remote diagnostics is growing, yet hardware reliability still sets the baseline for operating economics.
The hardware segment is projected to reach approximately USD 11.17 billion in 2031. Software and directly attributable services take a greater share of expenditure as commissioning, process tuning and connected support become more demanding. The shift does not imply that software is sold separately in every project; bundled software is attributed once within the commercial robot package.
By Application: Welding
Welding remains the largest robot application in automotive manufacturing, spanning resistance spot welding, arc welding and selected advanced joining processes. Robot arms carry heavy guns and torches along calibrated paths while coordinating clamps, weld timing and quality feedback. Automotive body construction requires repeatable joining at high line rates, while battery and structural applications create additional value for specialized control.
Welding is projected to represent approximately USD 4.68 billion in 2031 as assembly and quality-inspection robotics gain ground. New joining materials and battery enclosure designs can require higher integration spending per cell, but broader final-assembly automation is diversifying the type of robot systems purchased by OEMs and component suppliers.
By End-User: Vehicle OEMs
Vehicle manufacturers purchase coordinated robot fleets when introducing new platforms or modernizing body and paint shops. OEM installations commonly involve multi-robot cells, safety systems and long production validation periods. Their share of market value is supported by high-throughput joining and painting operations that remain difficult to substitute with manual processes in large plants.
OEMs represent approximately 64% of 2026 demand; component manufacturers account for the balance. Suppliers producing battery modules, stamped parts, electronic assemblies and powertrain subassemblies are likely to increase their share as quality requirements tighten and more processes are automated upstream. Supplier procurement tends to favor scalable cells that can be moved or reconfigured between customer programs.
Market Drivers
Automotive Platform Renewal and Re-Tooling
Body shops and assembly plants must adapt to different vehicle platforms even when aggregate production growth is modest. New underbody dimensions, sensor mounting positions and mixed powertrain layouts change weld patterns, fixture arrangements and material flow. OEMs often commission additional robotic capacity during vehicle program changeovers because legacy tooling cannot support the required range of motion or quality checks.
Flexible robot cells allow investment to support multiple product generations, but the equipment still requires engineering validation before launch. Manufacturers with established applications teams and reliable spare parts gain an advantage in tenders where production interruptions are costly.
Precision Requirements in Battery and Structural Assembly
Automotive battery trays, large castings and mixed-material enclosures introduce specialized handling and joining tasks. Robotic friction-stir welding and arc welding can improve repeatability where manual access is difficult or dimensional consistency is critical. KUKA has documented automotive battery-case welding programs, illustrating demand for integrated robot and process packages.
These requirements encourage investment in higher payloads, force control and inspection feedback. The economic case depends on reducing defects and ensuring reproducible processes, not simply substituting labor in an existing line.
Labor Availability and Occupational Safety
Spot welding, heavy part handling and paint-shop operations expose personnel to heat, fumes, repetitive motion and high physical loads. Industrial robots can perform these activities consistently across long shifts while allowing technicians to focus on process setup, maintenance and quality investigations. Staffing constraints in mature automotive markets reinforce the case for automating difficult-to-fill production roles.
Robots do not eliminate skilled labor requirements. Plants require operators, programmers and maintenance technicians, so vendors that provide training and easier-to-use controllers can improve the practical return on automation investment.
Shorter Commissioning Through Offline Programming
Automotive production changeovers often allow limited line downtime, creating a strong incentive to test cell layouts and motion paths before new equipment reaches the factory. Offline programming, digital commissioning and controller simulation reduce the amount of trial work performed on the live line. ABB RobotStudio and KUKA automation tools illustrate how supplier software is connected to installation economics.
Commissioning efficiency matters particularly for suppliers serving several OEM programs. Reusable templates and validated robot libraries can reduce the engineering effort needed to bring a new component into production, strengthening repeat orders for established robot platforms.
Regional Expansion of Automotive Supply Chains
China continues to command the largest industrial robot installation base, while India and Brazil are adding manufacturing capacity. The IFR reported almost 2,100 automotive robot installations in Brazil in 2025, compared with a considerably smaller base a year earlier. Local and international manufacturers are expanding the range of robotic applications that can be justified outside traditional vehicle production centers.
Investment is likely to remain uneven across countries and customers. Service coverage, local integrators and financing terms will influence whether equipment suppliers convert new plant announcements into recurring robot-system revenue.
Market Restraints
Cell Integration and Validation Expenses
A robot purchase is only one part of an automotive automation project. Weld tooling, grippers, guarding, electrical installation, controller integration and final production validation can raise total cell costs substantially above the price of the robotic arm. Plants converting legacy lines must also accommodate existing conveyors, floor space and utilities.
Investment approvals become difficult when the remaining model lifecycle is short or future volumes are uncertain. Modular design and reuse can ease the burden, but project economics differ materially between a greenfield factory and a constrained brownfield site.
Vehicle Program Volatility
Automotive robotics orders are sensitive to launch timing, production mix and capital allocation. A delayed EV platform or an extended life cycle for an existing model can postpone robot procurement even when management expects long-term automation gains. Robot suppliers may see large order fluctuations around individual OEM programs.
Uncertain utilization reduces the attractiveness of highly specialized cells. Manufacturers therefore increasingly value redeployable robotic platforms and programming environments that support multiple applications, but these adaptations cannot remove market cyclicality.
Programming and Skilled-Maintenance Constraints
Advanced robots require knowledgeable technicians to adjust motion sequences, maintain calibrations and diagnose interaction problems with tooling and vision systems. Smaller automotive suppliers often lack dedicated controls teams and may depend on external integrators for routine modifications. This can extend commissioning schedules and increase service expenditure.
New AI-assisted programming tools reduce some repetitive tasks, yet responsibility for machine safety, repeatability and quality remains with the operating plant and its suppliers. Poorly planned skills transfer can limit the productivity of otherwise capable equipment.
Interoperability with Existing Equipment
Vehicle factories frequently operate mixed generations of robots, weld controllers, PLCs and quality databases. New systems must exchange production information reliably without introducing unstable interfaces or compromising proven equipment. Hardware replacement can be harder to justify when older robotic arms remain mechanically sound.
Common interfaces and simulation environments can reduce integration effort, but manufacturer-specific languages and control architectures still create switching costs. This favors suppliers with broad installed bases while making entry more difficult for smaller vendors.
Safety, Cybersecurity and Production Reliability
Collaborative operation requires risk assessments for the complete application, including the end effector, part and motion speed; a cobot designation does not by itself make a cell safe. Connected controllers also create additional requirements for secure remote access and software updates. Automotive plants demand robust operating behavior because downtime can disrupt upstream and downstream lines.
Qualification costs increase as manufacturers add camera-guided functions and data connectivity. The technical challenge is to realize more adaptive automation without sacrificing deterministic motion, documented safety performance or established production quality.
Regional Outlook
Asia Pacific
Asia Pacific accounts for an estimated 49% of automotive manufacturing robotics value in 2026. China’s vehicle production and component networks underpin demand for body joining and parts-handling robots, while Japan and South Korea remain important centers for robot manufacturing and automotive process engineering. The IFR reported 354,000 industrial robot installations across all industries in China during 2025, and automotive continues to be a major customer industry within that larger total.
The region is projected to represent approximately USD 7.85 billion by 2031 as domestic suppliers compete more strongly and Indian automotive manufacturers increase adoption. China’s high installed base provides economies of scale, but robot system value remains dependent on application complexity, integration spending and the relative weight of internationally supplied versus locally produced equipment.
South America
South America is projected to grow at approximately 20.8% annually from 2026 to 2031, making it the fastest-growing region in this model from a relatively small base. Brazil is the principal demand center, with automotive investment driving an unusually strong increase in robot purchases in 2025. Production localization by international vehicle manufacturers and the development of component networks could support additional demand for welding, material handling and quality-control cells.
Regional suppliers face a different commercial environment from mature automotive hubs. Buyers may place greater weight on system integration, financing, training and spare-parts availability because robot engineering resources are less widely distributed. Growth can be volatile as major orders depend on a small number of investment programs, although an expanding local service ecosystem may improve adoption beyond leading OEM plants.
Competitive Landscape
The automotive manufacturing robotics sector is led by suppliers with extensive installed bases and application engineering capabilities. FANUC, ABB Robotics, KUKA and Yaskawa Electric compete in articulated robots and the controllers, programming systems and service networks needed to deploy them at scale. Kawasaki Robotics, DENSO, NACHI-FUJIKOSHI and Stäubli serve selected handling, assembly, welding and precision applications, while Comau combines robotics products with automotive automation engineering. Mitsubishi Electric, OMRON and Hyundai Robotics offer complementary robot classes for component manufacturing and selected automotive operations.
Supplier differentiation is increasingly built around validated automotive processes. Body-in-white customers assess reach, weld-gun handling, path accuracy and coordinated control; paint shops require contamination control, path repeatability and safe operation; assembly operations place greater weight on flexible tooling and vision. KUKA’s integrated welding and production engineering position differs from FANUC’s broad robot/controller portfolio, while ABB and Yaskawa combine extensive product families with emerging vision-enabled and AI-assisted applications.
Industrial robot vendors face competition from Chinese manufacturers in high-volume markets and from specialist automation firms able to integrate complete cells around purchased robots. Revenue should not be equated with an entire turnkey factory project: procurement often combines a manufactured robot, unrelated conveyance equipment and broader plant engineering. Aftermarket support, safety assurance and software maintainability can influence supplier awards as strongly as the initial robot specification.
Recent Developments
28 October 2026: Yaskawa Electric announced its seven-axis MOTOMAN-PA3050HB painting robot, designed for large automotive bodies and bumpers with extended reach and reduced booth interference.
28 October 2026: Yaskawa Electric announced a jointly developed AI-assisted autonomous welding system with GAZOO Racing, implemented at the GR KART workshop in September; MOTOMAN NEXT coordinates weld recognition, execution and post-weld inspection.
12 October 2026: ABB Robotics introduced the IRB 1700 and IRB 1700ID articulated-robot families for precision operations, including automotive arc welding and material handling.
8 October 2026: KUKA introduced iiQKA.AI Vision, an integrated AI-enabled image-processing tool intended to simplify robot vision commissioning for industrial users.
22 April 2026: ABB Robotics launched its PoWa collaborative-robot family with 7–30 kg payload options, broadening robot choices for compact industrial assembly and handling cells.
24 February 2026: KUKA introduced the KR TITAN ultra heavy-duty robot for demanding applications, including large automotive components and battery handling.
Market Outlook
Automotive plants will continue to require conventional high-throughput robots for joining and painting, but the highest incremental content growth is likely to appear in better-equipped robotic cells combining vision, programming and flexible end-of-arm tooling. Investment will follow the schedules of new vehicle platforms and component-production lines rather than expanding smoothly with vehicle output. New production architectures can increase robot spending even in markets where finished-vehicle volumes are stable.
Asia Pacific is expected to remain the main revenue center, while emerging automotive clusters in South America and selected Asian countries may deliver stronger percentage growth from smaller bases. Supplier success will depend on reliable local integration and maintenance infrastructure as much as mechanical specifications. Software capable of handling product variation and validated changeover procedures should become more valuable within long-life automotive automation programs.
Cost control will remain central. Manufacturers will seek to reuse serviceable robot platforms, shorten commissioning cycles and automate quality checks without compromising safety. The most resilient suppliers are likely to combine broad equipment portfolios with documented application performance and support arrangements that extend across successive vehicle generations.
Automotive Manufacturing Robotics Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 9.20 billion |
| Total Market Size in 2031 | USD 15.10 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Component, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Articulated Robots
SCARA Robots
Parallel Robots
Collaborative Robots
Cartesian Robots
By Component
Hardware
Software
Services
By Application
Welding
Painting
Material Handling
Assembly
Quality Inspection
By End-User
OEMs
Component Manufacturers
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Automotive Platform Renewal and Re-Tooling
3.1.2. Precision Requirements in Battery and Structural Assembly
3.1.3. Labor Availability and Occupational Safety
3.1.4. Shorter Commissioning Through Offline Programming
3.1.5. Regional Expansion of Automotive Supply Chains
3.2. Market Restraints
3.2.1. Cell Integration and Validation Expenses
3.2.2. Vehicle Program Volatility
3.2.3. Programming and Skilled-Maintenance Constraints
3.2.4. Interoperability with Existing Equipment
3.2.5. Safety, Cybersecurity and Production Reliability
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Vision-Guided Robotic Control
4.2. Offline Programming and Digital Commissioning
4.3. Collaborative Robot Safety
4.4. Robot Connectivity and Predictive Maintenance
5. AUTOMOTIVE MANUFACTURING ROBOTICS MARKET BY TYPE
5.1. Introduction
5.2. Articulated Robots
5.3. SCARA Robots
5.4. Parallel Robots
5.5. Collaborative Robots
5.6. Cartesian Robots
6. AUTOMOTIVE MANUFACTURING ROBOTICS MARKET BY COMPONENT
6.1. Introduction
6.2. Hardware
6.3. Software
6.4. Services
7. AUTOMOTIVE MANUFACTURING ROBOTICS MARKET BY APPLICATION
7.1. Introduction
7.2. Welding
7.3. Painting
7.4. Material Handling
7.5. Assembly
7.6. Quality Inspection
8. AUTOMOTIVE MANUFACTURING ROBOTICS MARKET BY END-USER
8.1. Introduction
8.2. OEMs
8.3. Component Manufacturers
9. AUTOMOTIVE MANUFACTURING ROBOTICS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. United Kingdom
9.4.3. France
9.4.4. Italy
9.4.5. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Taiwan
9.6.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. ABB Robotics
11.2. FANUC Corporation
11.3. KUKA AG
11.4. Yaskawa Electric Corporation
11.5. Kawasaki Heavy Industries, Ltd.
11.6. Comau S.p.A.
11.7. DENSO Corporation
11.8. NACHI-FUJIKOSHI CORP.
11.9. Stäubli International AG
11.10. Mitsubishi Electric Corporation
11.11. OMRON Corporation
11.12. HD Hyundai Robotics
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size for automotive manufacturing robotics in 2031?
The Automotive Manufacturing Robotics Market is projected to reach USD 15.10 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for this market?
The Automotive Manufacturing Robotics Market is expected to expand at a CAGR of 10.4%.
Which robot technology remains core for automotive production?
Articulated robots are core for welding, painting, and heavy handling.
What application holds the largest initial market value share?
Welding represents roughly 34% of initial market value, anchored in body-in-white.
Which region currently dominates the Automotive Manufacturing Robotics Market?
Asia Pacific retains its dominant position, led by China.
Who are the key suppliers in the Automotive Manufacturing Robotics Market?
KUKA, ABB, FANUC, and Yaskawa are significant suppliers.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automotive Manufacturing Robotics Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-manufacturing-robotics-market