
The environmental nanotechnology market is anticipated to expand at a high CAGR over the forecast period.
Highlights:
- 1Stricter requirements for emerging-contaminant removal are creating demand for selective adsorption, advanced membranes, catalytic treatment, and nano-enabled sensing.
- 2Water and wastewater treatment represents the most commercially accessible application because nano-enabled technologies can be integrated into existing treatment trains.
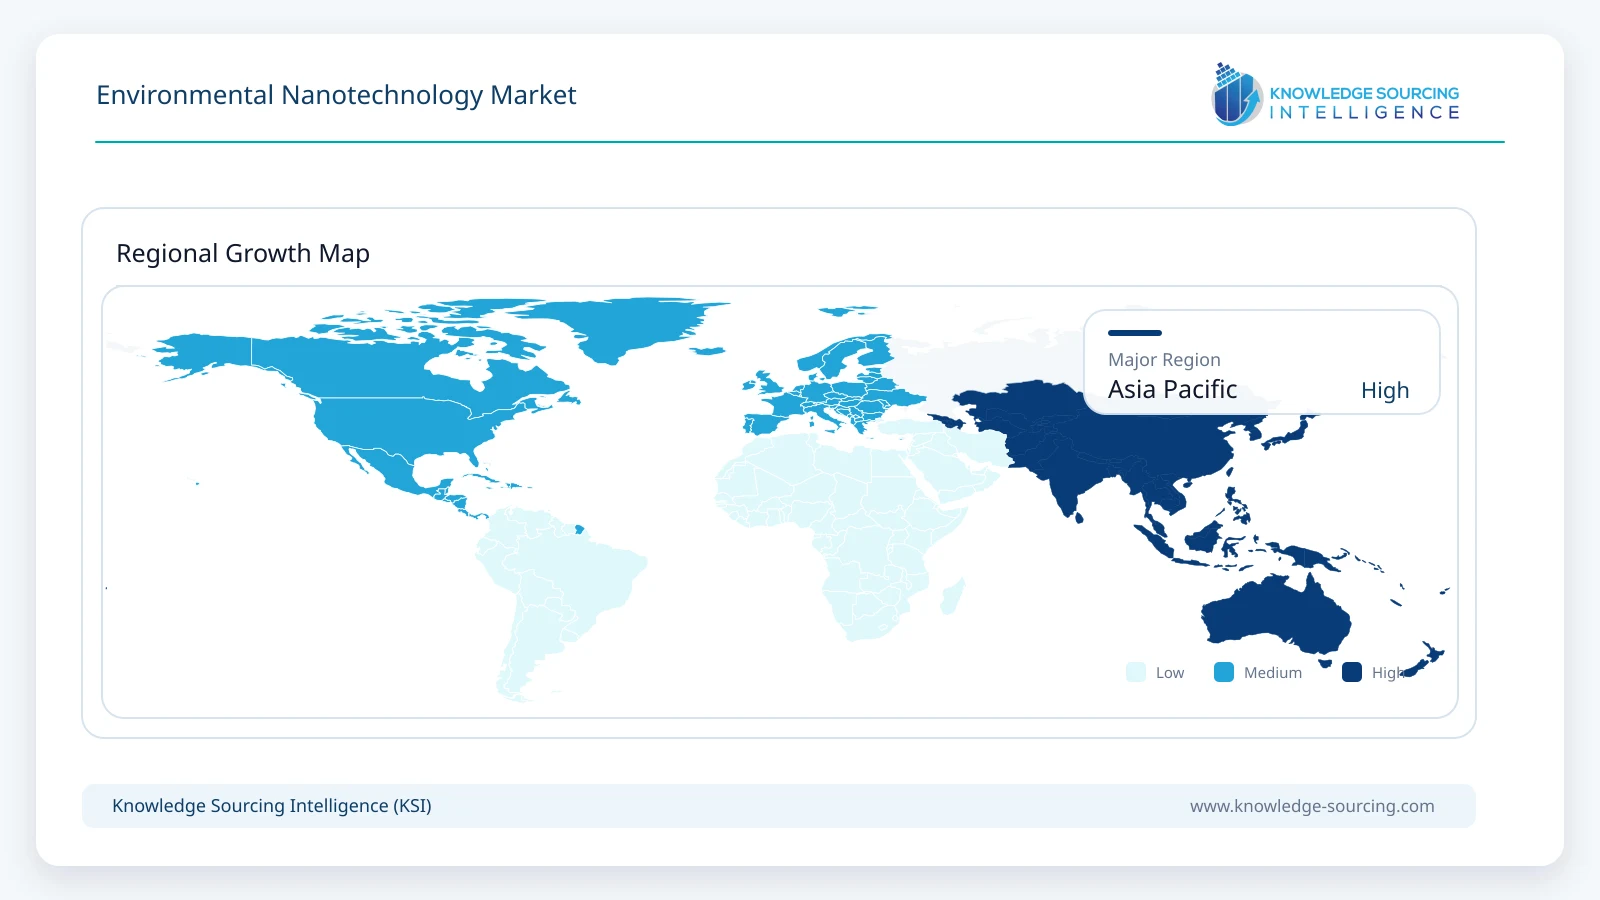
- 3Asia Pacific offers substantial deployment potential through industrial wastewater treatment, water reuse, manufacturing expansion, and environmental infrastructure investment.
- 4Nanocomposites and nanomembranes are gaining commercial relevance where buyers prioritize contaminant selectivity, mechanical durability, fouling resistance, and manageable operating costs.
- 5Regulatory scrutiny is becoming a purchasing consideration as governments require stronger evidence on nanomaterial characterization, environmental fate, exposure, and safe handling.
- 6Suppliers are competing through application engineering, membrane and material performance, lifecycle economics, partnerships, and integrated treatment capabilities rather than material specifications alone.
The Environmental Nanotechnology Market covers the development, manufacture, integration, and deployment of nanoscale materials and nano-enabled systems used to prevent, detect, remove, degrade, or recover environmental contaminants. The market includes nanoparticles and nanoadsorbents, nanocomposites, nanomembranes, nanocatalysts, nanofibers and nanotubes, nanosensors, and related technologies used across water and wastewater treatment, air pollution control, soil and groundwater remediation, waste management, resource recovery, and environmental monitoring.
Environmental nanotechnology occupies a distinct position between advanced materials, environmental engineering, water treatment, pollution control, and analytical technologies. Its commercial value comes from the ability of nanoscale materials to provide high surface area, tailored surface chemistry, selective adsorption, catalytic activity, antimicrobial functionality, and separation characteristics that conventional materials may not provide at the same operating conditions. These attributes make nano-enabled systems relevant where treatment operators face low-concentration contaminants, difficult-to-degrade compounds, complex industrial effluents, water reuse requirements, or increasingly stringent discharge standards.
Water and wastewater treatment represents the strongest commercial pathway because utilities and industrial operators already have established procurement structures for filtration, adsorption, membrane separation, oxidation, disinfection, and advanced treatment. Nanotechnology can therefore enter the market as an enhancement to an existing treatment train rather than requiring a completely new infrastructure model. Nano-enabled membranes, adsorbents, catalysts, and sensing technologies can be incorporated into modular treatment systems, polishing stages, pretreatment processes, or contaminant-specific treatment units.
Demand is also being shaped by the changing composition of pollution. Municipal and industrial systems are being asked to manage contaminants that are difficult to address through conventional biological treatment or basic clarification. PFAS, trace organic compounds, heavy metals, pharmaceutical residues, industrial chemicals, pathogens, and other emerging contaminants are creating demand for treatment technologies with greater selectivity. In the United States, the Environmental Protection Agency's drinking-water framework for PFAS has established enforceable limits for selected PFAS and continues to drive testing and treatment requirements. In May 2026, EPA also proposed changes concerning implementation of the PFAS drinking-water regulation, including an option that could allow certain systems additional time to comply with enforceable limits for PFOA and PFOS.
Buyer decisions in environmental nanotechnology are primarily performance- and risk-based. Municipal utilities generally assess removal performance, treated-water quality, regulatory compliance, energy consumption, chemical requirements, footprint, membrane or media life, maintenance requirements, and total cost of ownership. Industrial customers add process continuity, production yield, water reuse, wastewater discharge costs, resource recovery, and compatibility with existing equipment. Consequently, a nano-enabled material must demonstrate a measurable economic or operational advantage rather than simply offering nanoscale functionality.
The commercial structure remains heterogeneous. Some suppliers concentrate on engineered nanomaterials, adsorbents, membranes, catalysts, or sensors, while others participate through complete treatment systems and application engineering. The resulting competitive model rewards suppliers that can move beyond material supply and demonstrate reliable performance under actual operating conditions. Regeneration, recovery, disposal, fouling resistance, material stability, and prevention of nanoparticle release are particularly important because environmental applications place the technology itself under environmental scrutiny.
Environmental and health considerations also influence procurement. The European Commission recognizes nanomaterials as materials requiring specific consideration because their nanoscale characteristics can create distinct properties and potential risks. Under REACH, nano-specific provisions were introduced through amendments to the regulation, while the European Commission's revised nanomaterial definition has informed implementation across EU legislation.
The market's commercial trajectory will therefore depend less on the novelty of nanotechnology and more on the ability of suppliers to prove lifecycle economics, regulatory compatibility, environmental safety, and repeatable performance. Technologies that combine nano-enabled functionality with established filtration, adsorption, catalytic, membrane, or sensing architectures are likely to encounter fewer adoption barriers than standalone materials requiring major changes to plant design.
Market Drivers
Rising Requirements for Advanced Contaminant Removal
The treatment burden is shifting from conventional suspended solids and readily biodegradable pollutants toward contaminants that occur at lower concentrations and can be difficult to remove economically. PFAS is a prominent example. EPA's drinking-water regulation has increased the importance of reliable detection, treatment selection, and compliance planning for affected water systems. EPA has also made funding available for PFAS testing and treatment, creating an additional procurement pathway for advanced treatment technologies.
This environment benefits nano-enabled adsorbents, nanocomposites, selective membranes, and catalytic materials where their surface properties can be tailored toward particular contaminant classes. Buyers are not purchasing nanotechnology simply because it is nanoscale. They are seeking lower contaminant concentrations at the outlet, higher selectivity, reduced chemical consumption, or treatment configurations that fit within existing infrastructure.
For suppliers, this shifts product development toward application-specific materials. A material that performs well in laboratory water may have limited commercial value if natural organic matter, salinity, suspended solids, competing ions, temperature variation, or fouling reduce its performance in a treatment plant. Consequently, companies that can provide pilot-scale validation and operating data gain an advantage in procurement discussions.
Expansion of Water Reuse and Industrial Wastewater Treatment
Water scarcity, rising discharge costs, and tighter environmental requirements are encouraging industrial facilities to treat wastewater for internal reuse. Industrial customers in sectors such as chemicals, energy, mining, food and beverage, pharmaceuticals, and electronics increasingly evaluate treatment systems according to the quantity and quality of water recovered rather than simply the volume of wastewater discharged.
Nano-enabled membranes and nanocomposite filtration materials can contribute to this model by improving selective separation, contaminant removal, and process-water recovery. The commercial opportunity is strongest where the value of recovered water or avoided discharge costs can offset the additional capital and operating costs associated with advanced treatment.
Recent industry activity illustrates this procurement logic. DuPont reported in 2025 that its Water Solutions business was commercializing reverse-osmosis and nanofiltration elements for industrial wastewater treatment, reuse, and minimal liquid discharge applications, with emphasis on reducing discharge volumes and operating requirements.
Need for Compact and Higher-Performance Treatment Systems
Land availability, retrofit constraints, and the cost of expanding treatment plants are influencing technology selection. Municipal and industrial operators often need to improve treatment capacity without constructing an entirely new facility. Materials with higher adsorption capacity, improved separation characteristics, or enhanced reaction rates can support smaller or more productive treatment stages.
This factor is particularly relevant to nanomembranes and nanocomposites. A membrane or adsorbent that maintains performance under high contaminant loading can reduce equipment footprint or improve throughput. The commercial implication is that suppliers can compete on installed capacity and lifecycle economics rather than material price alone.
The requirement for compact systems is also visible in advanced membrane deployment. Acuriant Technologies states that its Nanostone ceramic ultrafiltration systems target municipal and industrial water applications, including drinking water, wastewater discharge, wastewater reuse, desalination, and industrial process streams.
Increasing Importance of Environmental Monitoring
Environmental regulation depends on accurate measurement. As treatment requirements become more specific, utilities and industrial facilities need sensors capable of identifying contaminants quickly enough to support process control, compliance monitoring, and early intervention.
Nanosensors can offer commercial value when they improve sensitivity, selectivity, response time, portability, or the ability to monitor contaminants that are difficult to detect using conventional field instrumentation. The main buyer question remains whether sensor performance can be translated into reliable field operation, calibration stability, and manageable maintenance.
This creates a different adoption model from bulk treatment materials. Monitoring technologies are often evaluated by environmental laboratories, utilities, industrial process-control teams, and regulatory organizations. Suppliers therefore need to demonstrate not only analytical performance but also reproducibility and compatibility with established monitoring procedures.
Public Investment in Pollution Control Infrastructure
Government funding and environmental programs can accelerate procurement by reducing the capital barrier faced by utilities and industrial operators. Water quality, PFAS remediation, wastewater reuse, pollution prevention, and environmental monitoring programs create opportunities for advanced treatment suppliers.
In Europe, the Zero Pollution Action Plan establishes targets covering air, water, soil, and waste. Its 2026 mid-term review continues to emphasize pollution prevention, remediation, monitoring, and implementation of relevant legislation.
For environmental nanotechnology suppliers, such programs can support pilot projects and technology qualification. However, public procurement generally requires strong evidence on safety, lifecycle performance, and cost, meaning funding availability alone does not guarantee commercial adoption.
Market Restraints and Challenges
High Cost of Commercial-Scale Nanomaterial Production
Laboratory-scale synthesis does not automatically translate into competitive industrial manufacturing. Environmental applications often require substantial quantities of adsorbents, catalysts, membranes, or composite materials. Manufacturing costs can rise because of precursor requirements, surface functionalization, purification, quality control, specialized equipment, and batch-to-batch consistency requirements.
This affects suppliers most strongly when the nano-enabled material competes with low-cost activated carbon, conventional membranes, ion-exchange media, chemical treatment, or established biological processes. Companies must therefore demonstrate either superior contaminant removal, longer operating life, lower regeneration requirements, lower energy consumption, or another measurable economic benefit.
Nanomaterial Release and Environmental Safety Concerns
A technology designed to remove pollution can itself become a concern if engineered nanoparticles escape into treated water, sludge, soil, or air. This creates a commercial contradiction that suppliers must address before large-scale deployment.
Regulators are paying closer attention to nanomaterial characterization, exposure, environmental fate, and toxicological behavior. The European Commission's Joint Research Centre has specifically supported development of testing methods and regulatory approaches for nanomaterials. In December 2025, the JRC highlighted updated OECD guidance covering sample preparation, dosimetry, characterization, toxicological and ecotoxicological effects, and environmental fate for manufactured nanomaterials.
Suppliers are responding through immobilized nanomaterials, nanocomposites, supported catalysts, recoverable nanoparticles, and membrane architectures that reduce the probability of material release.
Scale-Up and Process Reliability
Environmental treatment systems operate continuously and under variable feed conditions. A material that achieves strong removal under controlled laboratory conditions can behave differently when exposed to mixed contaminants, fouling agents, fluctuating pH, high ionic strength, or organic matter.
This challenge affects municipal utilities, engineering contractors, and industrial buyers because treatment failure can create regulatory exposure and operational disruption. Buyers therefore favor technologies with pilot-scale evidence, long-duration operating data, predictable regeneration behavior, and established maintenance procedures.
Uncertain Lifecycle Economics
A high-performance nano-enabled material may still lose a procurement decision if regeneration, replacement, energy, chemical cleaning, disposal, or monitoring costs are high. Environmental buyers increasingly evaluate total cost of ownership instead of initial equipment price.
This creates pressure for suppliers to quantify lifecycle performance. A membrane that operates at lower pressure, an adsorbent that can be regenerated repeatedly, or a catalyst that remains immobilized may command greater commercial interest than a material with better initial removal but rapid degradation.
Regulatory Complexity Across Jurisdictions
Environmental nanotechnology crosses chemical regulation, water quality regulation, waste management, occupational safety, and product-specific requirements. Requirements vary between countries and applications. In Europe, REACH establishes registration and risk-management obligations for chemical substances, while nano-specific provisions address characteristics and information requirements relevant to nanomaterials.
For suppliers operating internationally, regulatory documentation can increase development timelines and compliance costs. Companies must establish consistent material characterization and safety documentation while adapting to local approval and procurement requirements.
Major Segment Analysis
Water and Wastewater Treatment
Water and wastewater treatment is the most commercially important application of environmental nanotechnology because it combines a large installed treatment base with a growing requirement for contaminant-specific removal and water recovery. Unlike some emerging environmental applications, water treatment has established engineering standards, procurement channels, treatment contractors, and measurable performance criteria. This gives nano-enabled technologies a practical route from pilot deployment to commercial adoption.
Municipal buyers are primarily concerned with regulatory compliance, treated-water quality, reliability, plant footprint, energy consumption, and operating cost. Industrial buyers add water reuse, production continuity, discharge avoidance, resource recovery, and process-water quality to the purchasing criteria. These differences create several commercial niches rather than a single homogeneous water-treatment market.
Nanoadsorbents are relevant where targeted removal is required. Their high surface area and engineered surface chemistry can support adsorption of metals, organic pollutants, and other contaminants. Nanocomposites can improve handling and recovery by embedding nanoscale active materials into a more stable support. This addresses one of the principal concerns surrounding free nanoparticles: separation of the treatment material from the treated water.
Nanomembranes represent another commercially relevant pathway because membrane systems are already familiar to utilities and industrial operators. Nano-enabled modifications can target permeability, selectivity, fouling behavior, mechanical strength, or surface characteristics. The commercial question is whether these improvements produce a lower lifecycle cost or higher water recovery rate than conventional membrane systems.
Nanocatalysts can address contaminants that require chemical transformation rather than simple physical separation. They are particularly relevant where persistent organic pollutants or difficult-to-degrade compounds limit the effectiveness of conventional biological treatment. However, catalyst recovery, durability, by-product formation, and chemical requirements remain important procurement considerations.
The commercial opportunity is strongest when nano-enabled treatment is integrated into an existing process rather than sold as a stand-alone technology requiring extensive infrastructure replacement. For example, a nanocomposite adsorption stage can be positioned as a polishing unit, while a nano-enhanced membrane can replace or supplement an existing separation step.
Industrial wastewater reuse provides an additional revenue pathway. Facilities that can recover water internally can reduce freshwater purchases and discharge volumes while improving resilience against water restrictions. DuPont's 2025 commercialization of membrane solutions for industrial wastewater reuse and minimal liquid discharge demonstrates the broader commercial direction toward technologies that link treatment performance with water and resource economics.
The segment's long-term relevance will depend on evidence. Buyers increasingly need performance data under real operating conditions, validated environmental safety, predictable material life, and transparent lifecycle costs. Suppliers that can provide pilot testing, process integration, monitoring, maintenance support, and end-of-life management will have stronger commercial positioning than companies selling nanomaterials solely on laboratory performance.
Regional Analysis
North America
North America represents an important market for environmental nanotechnology because of established municipal water infrastructure, industrial wastewater requirements, environmental remediation programs, and strong research activity. The United States is particularly relevant for advanced water treatment because federal and state regulations can create direct demand for contaminant removal.
PFAS regulation is an important near-term influence. EPA's final drinking-water regulation and subsequent 2026 regulatory actions are increasing the need for treatment evaluation, monitoring, and compliance planning.
Industrial demand comes from chemicals, energy, mining, pharmaceuticals, food processing, and advanced manufacturing. Buyers typically require demonstrated performance and integration with existing systems before committing to full-scale deployment. Canada offers opportunities through water-quality management, resource industries, and municipal treatment, while Mexico provides demand linked to industrial water use and wastewater infrastructure.
Europe
Europe has a strong regulatory foundation for environmental technologies. The EU's Zero Pollution Action Plan covers air, water, and soil, while REACH provides the central framework for managing chemical risks. Nano-specific requirements and scientific work on nanomaterial safety make regulatory documentation a core part of commercialization.
European buyers are particularly sensitive to lifecycle performance, resource efficiency, chemical consumption, energy use, and environmental safety. Germany, France, the United Kingdom, Italy, and Spain offer opportunities across municipal treatment, industrial water reuse, remediation, and advanced monitoring.
The region also supports specialized membrane and filtration manufacturing. The July 2025 formation of Acuriant Technologies through the merger of Nanostone Water and Solecta combined ceramic and polymeric membrane technologies and established manufacturing activities in Germany and the United States.
Asia Pacific
Asia Pacific offers substantial commercial opportunity because industrialization, urbanization, water stress, manufacturing activity, and environmental infrastructure investment create multiple demand channels. China, Japan, South Korea, India, Taiwan, and Australia differ considerably in procurement structures, regulatory maturity, and technology adoption.
China combines large industrial wastewater requirements with significant domestic research and commercialization activity. In 2025, an event at NUS Suzhou Research Institute brought companies together around nanotechnology platforms for energy and environmental applications, including membrane innovation and treatment of difficult industrial wastewater and emerging water pollutants.
India presents opportunities through municipal wastewater treatment, industrial discharge control, water reuse, and remediation. Japan and South Korea have strong technology-development capabilities and sophisticated industrial buyers. Taiwan's semiconductor and electronics industries create demand for high-purity water and advanced wastewater treatment, while Australia has opportunities linked to mining, water scarcity, and resource management.
The main constraint across parts of the region is price sensitivity. Technologies must demonstrate clear advantages over established filtration, adsorption, biological treatment, and chemical treatment systems.
Middle East and Africa
Water scarcity is the primary commercial driver in the Middle East. Saudi Arabia and the United Arab Emirates have significant requirements for desalination, wastewater reuse, industrial water treatment, and water-quality management. Technologies that improve water recovery, reduce energy requirements, or enable treatment of difficult industrial streams can therefore receive attention.
Industrial activity in oil and gas, chemicals, mining, and power generation creates additional applications. However, projects are often capital intensive and procurement can depend on engineering, procurement, and construction contractors rather than direct purchases by end users.
South Africa offers opportunities in municipal water, mining wastewater, acid mine drainage, and industrial treatment. Affordability and infrastructure reliability remain important constraints. Suppliers must therefore combine advanced materials with service, maintenance, and system-integration capabilities.
South America
South America provides demand opportunities through mining, agriculture, food processing, municipal wastewater, and industrial water management. Brazil represents the largest commercial opportunity within the region because of its industrial base and extensive water-management requirements.
Mining operations in Chile, Brazil, Peru, and surrounding markets create opportunities for adsorption, membrane separation, contaminant recovery, and wastewater treatment. Agricultural and food-processing industries also generate wastewater streams requiring treatment and reuse.
Adoption can be constrained by capital availability, fragmented procurement, and limited access to specialized technical services. Suppliers that work through local engineering partners and demonstrate measurable operating savings can improve market access.
Competitive Landscape
The competitive environment consists of specialized nanomaterial developers, membrane manufacturers, water-treatment technology companies, research-driven suppliers, and application engineering firms. Competition is not determined solely by material performance. Buyers typically compare treatment efficiency, lifecycle cost, durability, ease of integration, regulatory documentation, after-sales support, and the supplier's ability to scale deployment.
The competitive set for this market includes Argonide Corporation, EnviroChemie GmbH, DuPont Water Solutions, LG Water Solutions (LG Chem), Nanostone Water (Acuriant Technologies, Inc.), Siontech, InnoNano Research, Advanced Chemical Industries, Nano Research Elements, Applied Nanotech Holdings, and Nanoshell.
Large technology suppliers can compete through broad membrane, filtration, separation, and treatment portfolios, allowing them to combine nano-enabled components with conventional treatment technologies. DuPont, for example, has positioned nanofiltration alongside reverse osmosis, ultrafiltration, ion-exchange, and complete water-treatment systems, allowing customers to select technologies according to process requirements rather than purchasing a single material category.
Specialized companies compete through material or membrane differentiation. Acuriant's formation through the combination of Nanostone Water and Solecta illustrates a consolidation strategy that combines ceramic and polymeric membrane capabilities. The transaction also expanded the company's ability to address municipal water, industrial water, food and beverage, and life-sciences separation requirements.
Partnerships and application engineering are likely to remain important because environmental nanotechnology requires validation under site-specific conditions. Suppliers can strengthen their position through pilot systems, engineering partnerships, academic collaboration, distributor networks, and long-term service agreements.
Product differentiation is increasingly shifting toward measurable lifecycle outcomes. Membrane lifetime, energy use, chemical consumption, recovery rate, footprint, contaminant selectivity, regeneration, and end-of-life management can matter more to a buyer than nominal nanoscale specifications.
Recent Developments
August 2026: Nanostone Water, part of Acuriant Technologies, received the 2026 AURA Award for its ceramic ultrafiltration technology. The company reported lower carbon footprint, reduced energy and chemical use, longer membrane life, and higher treatment capacity for CUF|Flow modules, highlighting the industry's movement toward measurable lifecycle performance.
July 2026: NanoPureUSA highlighted nationwide availability of its NanoPure SSMS™ PFAS/PFOS treatment platform, launched May 1, 2026, using patented hydraulic control for simplified contamination treatment.
June 2026: Moleaer and Xylem announced collaboration to deploy chemical-free nanobubble treatment for harmful algal blooms, low dissolved oxygen, nutrient pollution, and impaired water bodies.
May 2026: Kemira and CuspAI announced AI-designed materials targeting trace-level PFAS removal from drinking and process water, advancing the materials into development and testing.
August 2025: DuPont Water Solutions announced recognition for its work advancing industrial wastewater treatment and reuse through commercialization of FilmTec Fortilife membrane technologies. The development reinforces the commercial focus on higher water recovery, reduced discharge volumes, and lower operating requirements in industrial treatment.
Regulatory and Policy Environment
Regulation is a central commercial factor because environmental nanotechnology operates at the intersection of chemical safety and environmental treatment. Suppliers must demonstrate that the technology removes contaminants without creating unacceptable secondary risks.
In the European Union, REACH is the principal chemical-management framework. It requires manufacturers and importers to identify and manage chemical risks and includes nano-specific provisions introduced through amendments to its technical annexes. The European Commission also maintains an EU Observatory for Nanomaterials to improve information availability concerning nanomaterial uses and safety.
The regulatory environment is becoming more technically demanding. In June 2025, the European Commission's Joint Research Centre announced certified reference materials intended to improve the reliability of nanomaterial testing and support compliance with legislation. Such standardization is commercially important because inconsistent characterization can delay product qualification and complicate regulatory assessment.
The United States regulates environmental applications through multiple frameworks, including the Safe Drinking Water Act, Clean Water Act, chemical-management requirements, and federal and state environmental programs. PFAS requirements are particularly relevant because they can create direct demand for advanced treatment and monitoring. EPA's PFAS program has continued to evolve, with additional proposals issued in May 2026 concerning implementation of the drinking-water requirements.
The OECD and European regulatory authorities are also strengthening technical approaches for nanomaterial safety assessment. Updated 2025 guidance addresses sample preparation, dosimetry, physical and chemical characterization, toxicological and ecotoxicological testing, and environmental fate. For manufacturers, this means safety evidence is becoming part of product commercialization rather than a separate post-development consideration.
In Asia, regulatory approaches differ by country. China has increased attention to emerging pollutants and advanced water-environment technologies, while Japan, South Korea, Australia, and India maintain their own environmental and chemical-management frameworks. Suppliers operating across the region must therefore adapt product documentation and validation procedures to local requirements.
Outlook and Strategic Implications
The Environmental Nanotechnology Market is expected to move toward commercially validated applications rather than broad deployment of unproven nanomaterials. The strongest opportunities will arise where nano-enabled technologies solve a specific treatment problem that conventional processes cannot address economically or within available plant constraints.
Water and wastewater treatment is likely to remain the central commercial application. PFAS, emerging contaminants, industrial wastewater reuse, desalination, resource recovery, and increasingly demanding discharge standards will continue to create requirements for selective separation and advanced treatment. The procurement environment will favor technologies capable of integrating into existing treatment trains because operators generally prefer incremental upgrades over complete plant replacement.
Investment priorities are likely to concentrate on nanocomposites, advanced membranes, immobilized nanoparticles, selective adsorbents, catalytic systems, and nanosensors. Material development will increasingly emphasize stability, recoverability, regeneration, low energy demand, and controlled release characteristics. The commercial value of a nano-enabled product will depend on its entire operating cycle rather than initial removal efficiency.
Procurement models will also become more evidence-driven. Municipalities and industrial companies will increasingly request pilot data, lifecycle-cost assessments, environmental safety documentation, and long-duration performance records before approving full-scale deployment. Suppliers with application engineering and commissioning capabilities will be better positioned than those offering materials without integration support.
Competitive evolution is likely to include portfolio expansion and selective consolidation. The formation of Acuriant Technologies demonstrates how combining complementary membrane technologies can broaden the addressable customer base and reduce the number of specialist suppliers a customer must manage.
Regulatory risk will remain a material consideration. A technology can lose commercial momentum if regulators require additional testing, if nanoparticle release becomes a public concern, or if disposal requirements materially increase lifecycle costs. Companies should therefore incorporate safe-by-design principles, material recovery, environmental fate testing, and end-of-life planning into product development.
The strongest strategic opportunity lies in combining nanotechnology with established environmental engineering. Nano-enabled membranes integrated into conventional filtration trains, immobilized catalysts incorporated into reactors, supported nanoadsorbents used in polishing stages, and nanosensors connected to existing monitoring systems can reduce adoption barriers.
Over the 2026–2031 period, customers are likely to favor technologies that provide a clear answer to four commercial questions: What contaminant is removed, how reliably is it removed, what does the treatment cost over its useful life, and what happens to the nanomaterial afterward? Suppliers able to answer these questions with independent testing, pilot evidence, regulatory documentation, and credible lifecycle economics will be better positioned to convert research activity into recurring commercial revenue.
The market's long-term development will therefore be shaped by a convergence of environmental regulation, water scarcity, industrial reuse economics, advanced materials engineering, and safety science. Environmental nanotechnology is most commercially relevant when its nanoscale properties translate into measurable treatment performance, lower resource consumption, smaller system footprints, or improved contaminant control. That practical connection between material science and operating economics will determine which technologies move from specialized applications into broader environmental infrastructure.
Environmental Nanotechnology Market Scope:
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, End-User Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
By Application
By End-user Industry
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Nanoadsorbents and Nanocatalysts
4.2. Nanomembranes and Nanofiltration
4.3. Nanocomposites and Nanostructured Materials
4.4. Nanosensors and Environmental Monitoring
4.5. Nanoparticles for Environmental Remediation
4.6. Nanotechnology-Enabled Air Pollution Control
4.7. Emerging Environmental Nanotechnology
5. ENVIRONMENTAL NANOTECHNOLOGY MARKET BY TYPE
5.1. Introduction
5.2. Nanoparticles and Nanoadsorbents
5.3. Nanocomposites
5.4. Nanomembranes
5.5. Nanocatalysts
5.6. Nanofibers and Nanotubes
5.7. Nanosensors
5.8. Others
6. ENVIRONMENTAL NANOTECHNOLOGY MARKET BY APPLICATION
6.1. Introduction
6.2. Water and Wastewater Treatment
6.3. Air Pollution Control
6.4. Soil and Groundwater Remediation
6.5. Waste Management and Resource Recovery
6.6. Environmental Monitoring and Sensing
6.7. Others
7. ENVIRONMENTAL NANOTECHNOLOGY MARKET BY END-USER INDUSTRY
7.1. Introduction
7.2. Municipal Water and Wastewater Treatment
7.3. Industrial Water and Wastewater Treatment
7.4. Chemical and Petrochemical
7.5. Energy and Power
7.6. Mining and Metals
7.7. Agriculture
7.8. Food and Beverage
7.9. Pharmaceuticals
7.10. Others
8. ENVIRONMENTAL NANOTECHNOLOGY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By Application
8.2.3. By End-User Industry
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Type
8.3.2. By Application
8.3.3. By End-User Industry
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Chile
8.3.4.4. Others
8.4. Europe
8.4.1. By Type
8.4.2. By Application
8.4.3. By End-User Industry
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Spain
8.4.4.5. Italy
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Type
8.5.2. By Application
8.5.3. By End-User Industry
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. South Africa
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By Application
8.6.3. By End-User Industry
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. India
8.6.4.4. South Korea
8.6.4.5. Taiwan
8.6.4.6. Australia
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Argonide Corporation
10.2. EnviroChemie GmbH
10.3. DuPont Water Solutions
10.4. LG Water Solutions (LG Chem)
10.5. Nanostone Water (Acuriant Technologies, Inc.)
10.6. Siontech
10.7. InnoNano Research
10.8. Advanced Chemical Industries
10.9. Nano Research Elements
10.10. Applied Nanotech Holdings
10.11. Nanoshell
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base Year and Forecast Period
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth trajectory for the Environmental Nanotechnology Market between 2026 and 2031?
The Environmental Nanotechnology Market is anticipated to expand at a high Compound Annual Growth Rate (CAGR) over the 2026-2031 forecast period. This growth is driven by the unique capabilities of nanoscale materials to address complex environmental challenges and increasingly stringent discharge standards, as detailed in the strategic insights report.
Which specific technologies and application areas are analyzed within this Environmental Nanotechnology Market report?
The report covers key technologies including nanoparticles, nanoadsorbents, nanocomposites, nanomembranes, nanocatalysts, nanofibers and nanotubes, and nanosensors. These technologies are explored across critical application areas such as water and wastewater treatment, air pollution control, soil and groundwater remediation, waste management, resource recovery, and environmental monitoring.
What are the primary demand drivers for environmental nanotechnology solutions, particularly in industrial and municipal systems?
Demand is primarily shaped by the changing composition of pollution, requiring management of contaminants difficult for conventional treatment, such as PFAS, trace organic compounds, and heavy metals. Additionally, water and wastewater treatment represents the strongest commercial pathway due to existing procurement structures and nanotechnology's ability to enhance existing treatment trains.
How do regulatory developments, specifically regarding PFAS, impact the Environmental Nanotechnology Market's strategic direction?
Regulatory frameworks, such as the EPA's drinking-water framework for PFAS in the United States, significantly influence the market by establishing enforceable limits and driving testing and treatment requirements. These regulations create demand for advanced, highly selective nano-enabled technologies capable of meeting stringent discharge standards for emerging contaminants.
What competitive advantages do nano-enabled systems offer over conventional materials in environmental remediation?
Nano-enabled systems provide distinct advantages over conventional materials, including high surface area, tailored surface chemistry, selective adsorption, catalytic activity, and antimicrobial functionality. These attributes make them highly effective for treating low-concentration contaminants, difficult-to-degrade compounds, and complex industrial effluents that traditional methods may struggle with.
What role does environmental nanotechnology play in addressing emerging contaminants and water reuse requirements?
Environmental nanotechnology is crucial for managing emerging contaminants like PFAS, pharmaceutical residues, industrial chemicals, and pathogens, which are challenging for conventional biological treatment. Its ability to provide greater selectivity and separation characteristics also makes it highly relevant for fulfilling increasingly stringent water reuse requirements and improving polishing stages in treatment processes.
Cite this report
Knowledge Sourcing Intelligence. (Aug 2026). Environmental Nanotechnology Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/environmental-nanotechnology-market