
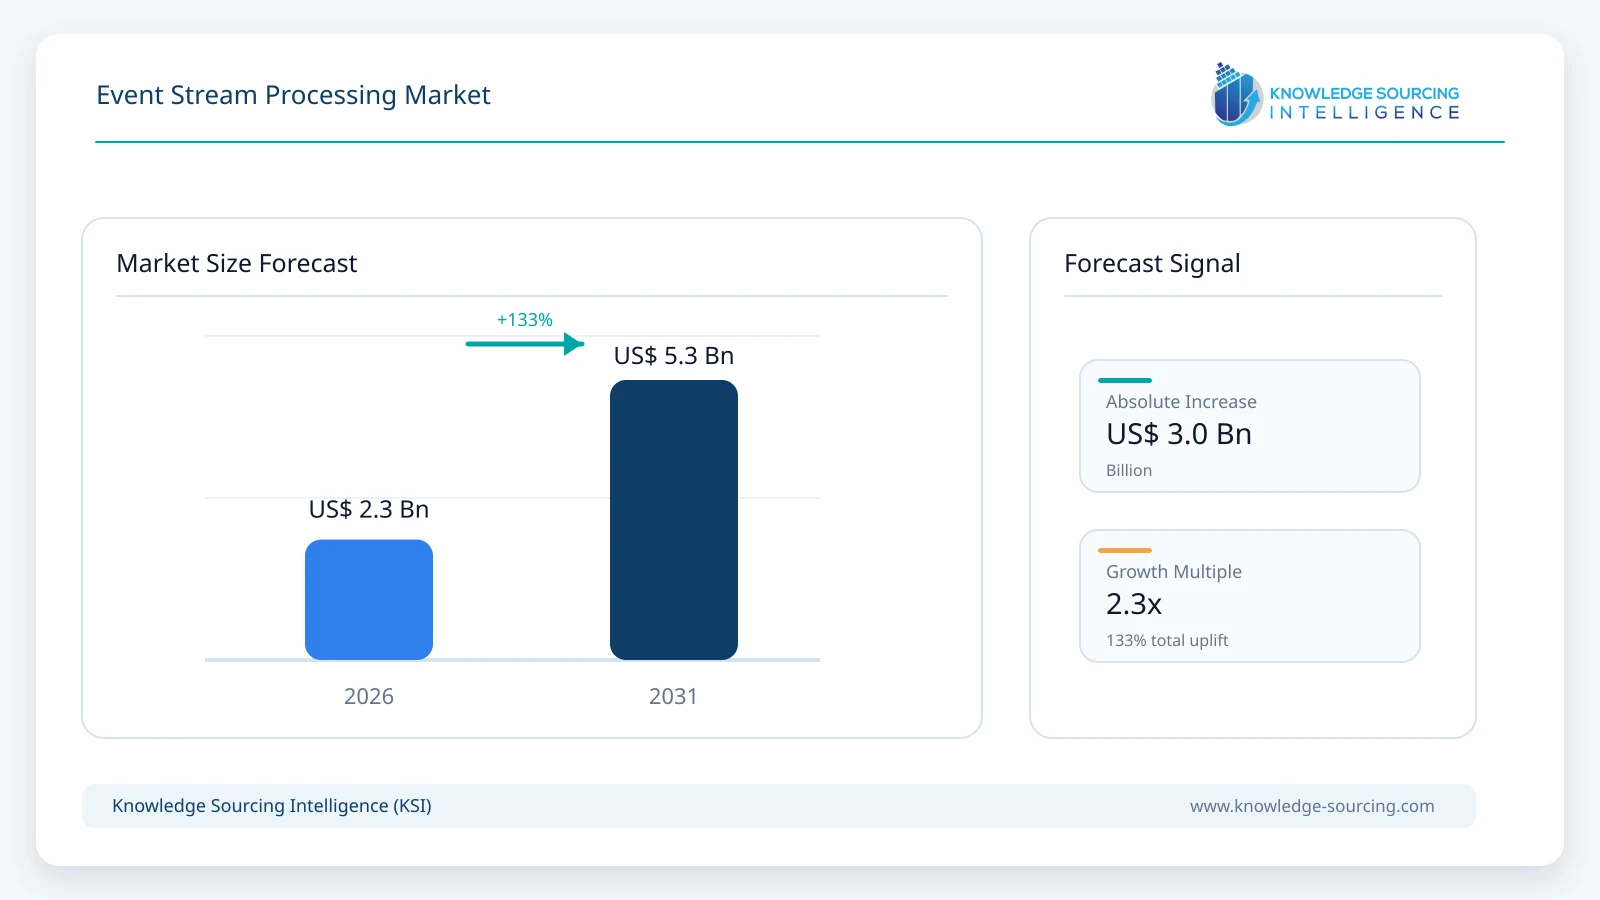
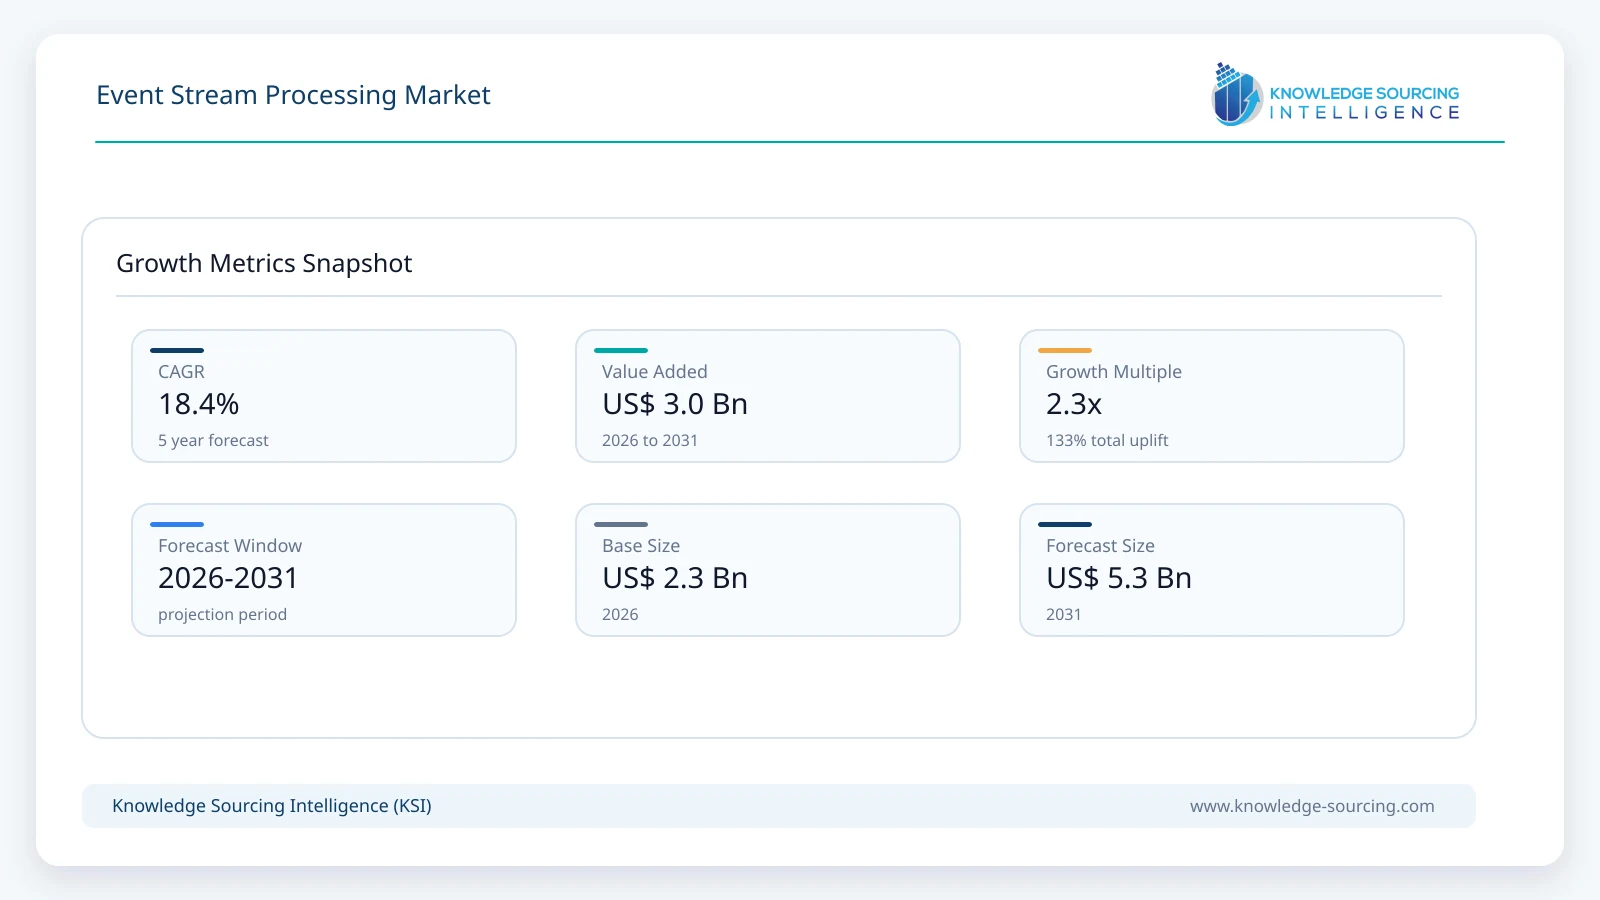
The global event stream processing market is estimated at USD 2.30 billion in 2026 and is forecast to reach USD 5.35 billion in 2031, representing an implied CAGR of approximately 18.4%.
Highlights:
- 1Cloud-managed processing accounts for approximately 63% of 2026 event stream processing revenue.
- 2Software and managed processing platforms represent about 72% of revenue; services account for the remainder.
- 3BFSI is the largest end-user pool at roughly 27% because fraud, risk and trading decisions are latency-sensitive.
- 4North America represents approximately 39% of 2026 revenue, supported by hyperscale cloud and data-platform adoption.
- 5Streaming AI and agentic applications are expanding demand beyond dashboards into real-time inference and automated actions.
- 6The forecast excludes standalone event transport revenue to avoid double counting Kafka, Pulsar and messaging infrastructure.
The 2026 market estimate of USD 2.30 billion is built from five revenue pools: hyperscale managed stream-processing consumption; specialist commercial Flink and streaming-SQL platforms; enterprise complex-event-processing and streaming-analytics licenses; streaming workloads embedded within broader data platforms; and professional services directly tied to stream-processing implementation. The model is cross-checked against current product availability from AWS Managed Service for Apache Flink, Azure Stream Analytics, Google Cloud Dataflow, Confluent Cloud for Apache Flink, IBM Event Processing, Databricks Structured Streaming, Oracle GoldenGate Stream Analytics, SAS Event Stream Processing and Alibaba Cloud Realtime Compute for Apache Flink.
The forecast path is intentionally non-uniform: USD 2.30 billion in 2026, USD 2.68 billion in 2027, USD 3.16 billion in 2028, USD 3.78 billion in 2029, USD 4.51 billion in 2030 and USD 5.35 billion in 2031. Growth accelerates as stream processing becomes part of AI-ready data infrastructure, then moderates slightly as open-source engines, integrated lakehouse platforms and cloud price optimization place pressure on unit economics. The market remains structurally faster-growing than conventional batch analytics because the number of operational decisions requiring fresh context continues to expand.
Event Stream Processing Market Trends
Apache Flink is consolidating its position as the commercial standard for stateful stream processing. AWS now directs customers from the discontinued Kinesis Data Analytics for SQL service toward Managed Service for Apache Flink, Confluent operates fully managed serverless Flink, IBM Event Processing uses Flink behind a low-code interface, Alibaba Cloud has continued to release new Flink engine versions throughout 2026, and Ververica commercializes enterprise Flink with its VERA engine. This common runtime lowers migration barriers while shifting competition toward autoscaling, governance, observability, developer tooling and cost per processed event.
Stream processing is moving closer to AI inference. Confluent added streaming-agent and AI-ready processing capabilities around Flink; Alibaba Cloud integrated model invocation, vectorization and multimodal analysis directly into Flink jobs; and Databricks introduced real-time mode for Structured Streaming with end-to-end latency as low as five milliseconds for supported workloads. The commercial implication is that stream processors increasingly become context engines for fraud models, recommendation systems and AI agents rather than only ETL or dashboard infrastructure.
Unified batch and streaming is eroding the historical separation between data engineering stacks. Google Dataflow uses Apache Beam for both batch and streaming, Databricks Structured Streaming shares Spark APIs with batch processing, Confluent has added snapshot queries to combine historical and live processing, and Ververica is positioning unified stream-and-batch architectures around Flink and streaming storage. Buyers increasingly evaluate whether one platform can support ingestion, transformation, continuous computation and lakehouse delivery without maintaining separate engines.
Consumption-based cloud pricing remains attractive for variable workloads but can become expensive at sustained high throughput. Managed platforms respond with autoscaling, lower-cost state backends, workload isolation and bring-your-own-cloud deployment. This creates a two-speed market: managed serverless services dominate new departmental and cloud-native deployments, while large financial institutions, telecommunications operators and industrial users retain dedicated or hybrid clusters for predictable economics, latency and sovereignty.
Event Stream Processing Market Segment Analysis
By Component
Processing Platforms and Software
Processing platforms and software are estimated at approximately USD 1.66 billion in 2026, equivalent to about 72% of market revenue. The segment includes managed processing services billed by compute consumption, commercial stream-processing engines, enterprise streaming-analytics licenses and processing functionality monetized within broader data platforms. The share is high because much of the market is delivered as software or cloud infrastructure rather than labor-intensive implementation.
Professional and managed services account for the remaining approximately 28%. Services include architecture design, Flink or Spark migration, production tuning, observability, data-contract implementation and operational support. Services grow alongside platform adoption but do not overtake software because cloud providers and commercial platforms increasingly automate scaling, upgrades, recovery and connector management.
By Deployment
Cloud-Managed Processing
Cloud-managed event stream processing is estimated at approximately USD 1.45 billion in 2026, or about 63% of the total. The share is supported by AWS Managed Service for Apache Flink, Azure Stream Analytics, Google Dataflow, Confluent Cloud, IBM Cloud services, Databricks and Alibaba Cloud. Consumption-based deployment reduces the need to maintain JobManagers, state backends, checkpoint storage, cluster upgrades and high-availability control planes.
Customer-managed, private-cloud and on-premises deployments account for approximately 37%. This share remains material because financial trading, regulated data, telecommunications telemetry and high-throughput industrial workloads can justify dedicated infrastructure. Enterprise products from Ververica, Oracle, SAS, TIBCO, IBM and open-source Flink or Spark deployments support these requirements.
By End User
Banking, Financial Services and Insurance
BFSI is estimated at approximately USD 0.62 billion in 2026, representing about 27% of global revenue. The sector combines fraud scoring, payment monitoring, anti-money-laundering signals, market-data processing, algorithmic trading, credit decisioning and operational-risk alerts. These workflows have a direct economic relationship between decision latency and loss prevention or trading performance, supporting higher willingness to pay for resilient low-latency processing.
Retail and e-commerce, manufacturing, telecommunications and IT are the next-largest end-user groups. Retail uses streaming engines for personalization and inventory events; manufacturers use them for predictive maintenance and production monitoring; and telecommunications operators process large volumes of network telemetry. Transportation, media, gaming and healthcare add smaller but fast-expanding workloads.
By Geography
North America
North America is estimated at approximately USD 0.90 billion in 2026, or about 39% of market revenue. The region combines hyperscale cloud providers, a dense base of streaming-software vendors and early enterprise adoption in financial services, technology, retail and digital platforms. Europe represents the second-largest pool, supported by banking, industrial and telecom deployments, while Asia Pacific grows faster as cloud-native data architectures expand in China, India, Japan, South Korea and Southeast Asia.
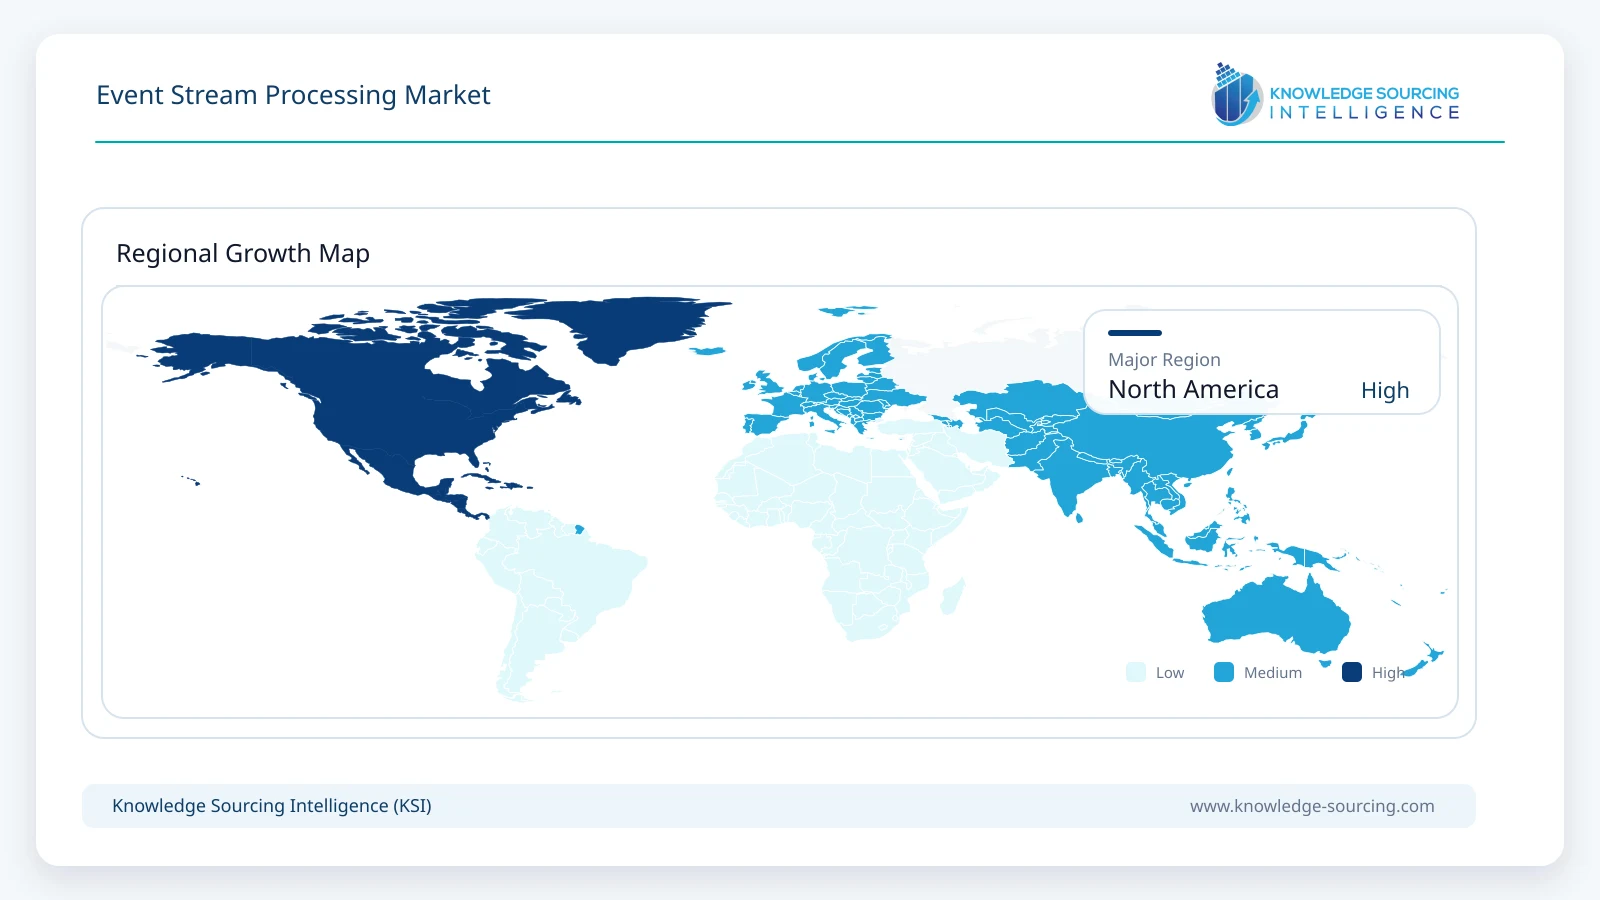
Asia Pacific is estimated at roughly 26% of 2026 revenue and is expected to gain share through 2031. Alibaba Cloud Realtime Compute for Apache Flink provides a large regional commercial platform, while telecommunications, e-commerce, payments and manufacturing generate high-volume streaming workloads. Local data-residency rules also encourage regional cloud deployments rather than centralized global processing.
Market Drivers
Real-time operational decisioning is replacing delayed batch workflows in activities where the value of information decays rapidly. Fraud detection, dynamic pricing, recommendations, fleet monitoring, cyber-security and industrial control all benefit when events are processed immediately instead of waiting for a data warehouse refresh.
AI systems increase the requirement for fresh context. Agentic and predictive applications need continuously updated state about users, transactions, machines and environments. Stream processing supplies this context by enriching events, maintaining state and invoking models or downstream actions as conditions change.
The growth of IoT, connected vehicles, software telemetry and digital transactions expands the volume of machine-generated events. Higher event volume does not automatically translate into proportional revenue because compute efficiency improves, but it expands the number of workloads that require continuous rather than periodic processing.
Managed services lower the skills barrier for Apache Flink and related engines. Autoscaling, serverless pricing, low-code interfaces and integrated connectors allow teams to deploy stateful stream processing without building a specialist platform-engineering function.
Market Restraints
Open-source software constrains licensing economics. Apache Flink, Spark Structured Streaming, Kafka Streams and Apache Beam provide powerful processing capabilities without proprietary license fees. Commercial vendors must therefore monetize operations, governance, support, performance and cloud convenience rather than access to the core engine alone.
Long-running streaming workloads can be expensive in public clouds because compute and state remain active continuously. Large enterprises frequently discover that highly utilized jobs require careful partitioning, state tuning and reserved capacity to avoid cost overruns.
Operational complexity remains significant for stateful workloads. Checkpoint recovery, event-time semantics, late-arriving data, schema evolution, exactly-once guarantees and connector behavior can create production failures that are harder to diagnose than ordinary batch jobs.
The boundary between stream processing, event streaming, CDC, lakehouse ingestion and real-time databases is becoming less distinct. Bundling can reduce the standalone revenue pool even while the underlying processing workload grows.
Competitive Environment
Competition is divided between hyperscale clouds, broad data-platform vendors, specialist Flink providers and established complex-event-processing suppliers. AWS, Microsoft and Google sell managed processing as part of larger cloud data estates. Confluent extends its Kafka-centered data-streaming platform with managed Flink. Databricks embeds Structured Streaming into the lakehouse. IBM, Oracle, SAS and TIBCO retain enterprise event-processing capabilities, while Alibaba Cloud is a significant managed Flink provider in Asia.
Specialist competition centers on Apache Flink performance and operational simplicity. Ververica, created by the original Flink team, sells enterprise Flink and a proprietary compatible execution engine. Smaller streaming database and continuous-query vendors compete by exposing SQL-first experiences or maintaining continuously updated materialized views. Differentiation increasingly depends on state management, autoscaling, cost efficiency, governance, latency, connector breadth and AI integration rather than basic support for filtering and window functions.
Company inclusion is based on currently commercialized stream-processing or event-processing capability, not adjacent message-broker participation alone. Standalone event streaming providers are therefore excluded unless they monetize a processing engine or continuous analytics layer.
Recent Developments
September 2026: Alibaba Cloud released VVR 11.9.0 for Realtime Compute for Apache Flink, extending multimodal AI processing, data ingestion, connector security and asynchronous-computing capabilities.
May 2026: Confluent expanded its AI-ready streaming stack with a dbt adapter for Flink and Materialized Tables, a managed Model Context Protocol server and agent-oriented developer capabilities.
May 2026: Databricks documented real-time mode for Structured Streaming, enabling supported operational workloads with end-to-end latency as low as five milliseconds.
January 2026: AWS completed the discontinuation of Kinesis Data Analytics for SQL applications and directed customers toward Amazon Managed Service for Apache Flink, reinforcing Flink as its strategic managed stream-processing engine.
February 2026: Oracle GoldenGate Stream Analytics 26ai upgraded its Spark and Kafka libraries and added vector-based similarity-search capability for real-time streaming analytics.
Market Outlook
The event stream processing market is expected to reach approximately USD 5.35 billion in 2031. Growth is supported by real-time AI, fraud prevention, operational analytics, telemetry and continuous data products, but the forecast remains below broader data-streaming-market estimates because standalone brokers, event storage and generic messaging are deliberately excluded.
Cloud-managed deployment should gain several percentage points of share through 2031 as serverless Flink and integrated stream-processing services improve. Customer-managed infrastructure remains important at the high-throughput and highly regulated end of the market, particularly where predictable utilization makes dedicated capacity economical.
The biggest forecast uncertainty is product convergence. If vendors increasingly bundle stream processing into lakehouse, integration or messaging subscriptions without separate monetization, standalone market revenue could grow more slowly than workload volume. Conversely, monetization of AI inference inside continuous pipelines could raise average revenue per workload and push the market above the base case.
Event Stream Processing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.30 billion |
| Total Market Size in 2031 | USD 5.35 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 18.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Deployment, Processing Model, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Component
Processing Platforms and Software
Professional and Managed Services
By Deployment
Cloud-Managed
Customer-Managed / On-Premises / Private Cloud
Hybrid
By Processing Model
Stateful Stream Processing
Streaming SQL and Continuous Queries
Complex Event Processing and Pattern Detection
Embedded / Edge Stream Processing
By Application
Fraud, Risk and Transaction Monitoring
Real-Time Personalization and Customer Analytics
Predictive Maintenance and Industrial IoT
Observability, Security and Anomaly Detection
Operational Data Pipelines and Continuous Transformation
Others
By End User
Banking, Financial Services and Insurance
Retail and E-Commerce
Manufacturing
Telecommunications and IT
Transportation and Logistics
Media and Gaming
Healthcare
Others
By Geography
North America
United States
Canada
South America
Brazil
Others
Europe
Germany
United Kingdom
France
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Vendor Revenue and Product Mapping
2.3. Cloud Consumption and Workload Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Real-Time Operational Decisioning
4.1.2. Streaming Context for AI and Agents
4.1.3. Growth of IoT and Machine-Generated Events
4.1.4. Managed-Service Adoption
4.2. Market Restraints
4.2.1. Open-Source Pricing Pressure
4.2.2. Continuous Cloud-Compute Cost
4.2.3. Stateful Processing Complexity
4.2.4. Platform Convergence and Bundling
5. EVENT STREAM PROCESSING MARKET BY COMPONENT
5.1. Processing Platforms and Software
5.2. Professional and Managed Services
6. EVENT STREAM PROCESSING MARKET BY DEPLOYMENT
6.1. Cloud-Managed
6.2. Customer-Managed / On-Premises / Private Cloud
6.3. Hybrid
7. EVENT STREAM PROCESSING MARKET BY PROCESSING MODEL
7.1. Stateful Stream Processing
7.2. Streaming SQL and Continuous Queries
7.3. Complex Event Processing and Pattern Detection
7.4. Embedded / Edge Stream Processing
8. EVENT STREAM PROCESSING MARKET BY APPLICATION
8.1. Fraud, Risk and Transaction Monitoring
8.2. Real-Time Personalization and Customer Analytics
8.3. Predictive Maintenance and Industrial IoT
8.4. Observability, Security and Anomaly Detection
8.5. Operational Data Pipelines and Continuous Transformation
8.6. Others
9. EVENT STREAM PROCESSING MARKET BY END USER
9.1. Banking, Financial Services and Insurance
9.2. Retail and E-Commerce
9.3. Manufacturing
9.4. Telecommunications and IT
9.5. Transportation and Logistics
9.6. Media and Gaming
9.7. Healthcare
9.8. Others
10. EVENT STREAM PROCESSING MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.2. South America
10.2.1. Brazil
10.2.2. Others
10.3. Europe
10.3.1. Germany
10.3.2. United Kingdom
10.3.3. France
10.3.4. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. Japan
10.5.3. India
10.5.4. South Korea
10.5.5. Southeast Asia
10.5.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Managed Cloud Platform Competition
11.2. Apache Flink Commercialization
11.3. Streaming SQL and Developer Experience
11.4. AI and Real-Time Inference Positioning
11.5. Recent Developments
11.6. Competitive Dashboard
12. COMPANY PROFILES
12.1. Confluent, Inc.
12.2. Amazon Web Services, Inc.
12.3. Microsoft Corporation
12.4. Google LLC
12.5. IBM Corporation
12.6. Databricks, Inc.
12.7. Oracle Corporation
12.8. SAS Institute Inc.
12.9. Alibaba Cloud
12.10. Ververica GmbH
12.11. TIBCO Software Inc. / Cloud Software Group
12.12. Hazelcast, Inc.
12.13. Cloudera, Inc.
12.14. Materialize, Inc.
12.15. RisingWave Labs
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Abbreviations
Navigate
Trusted by the world's leading organizations











