
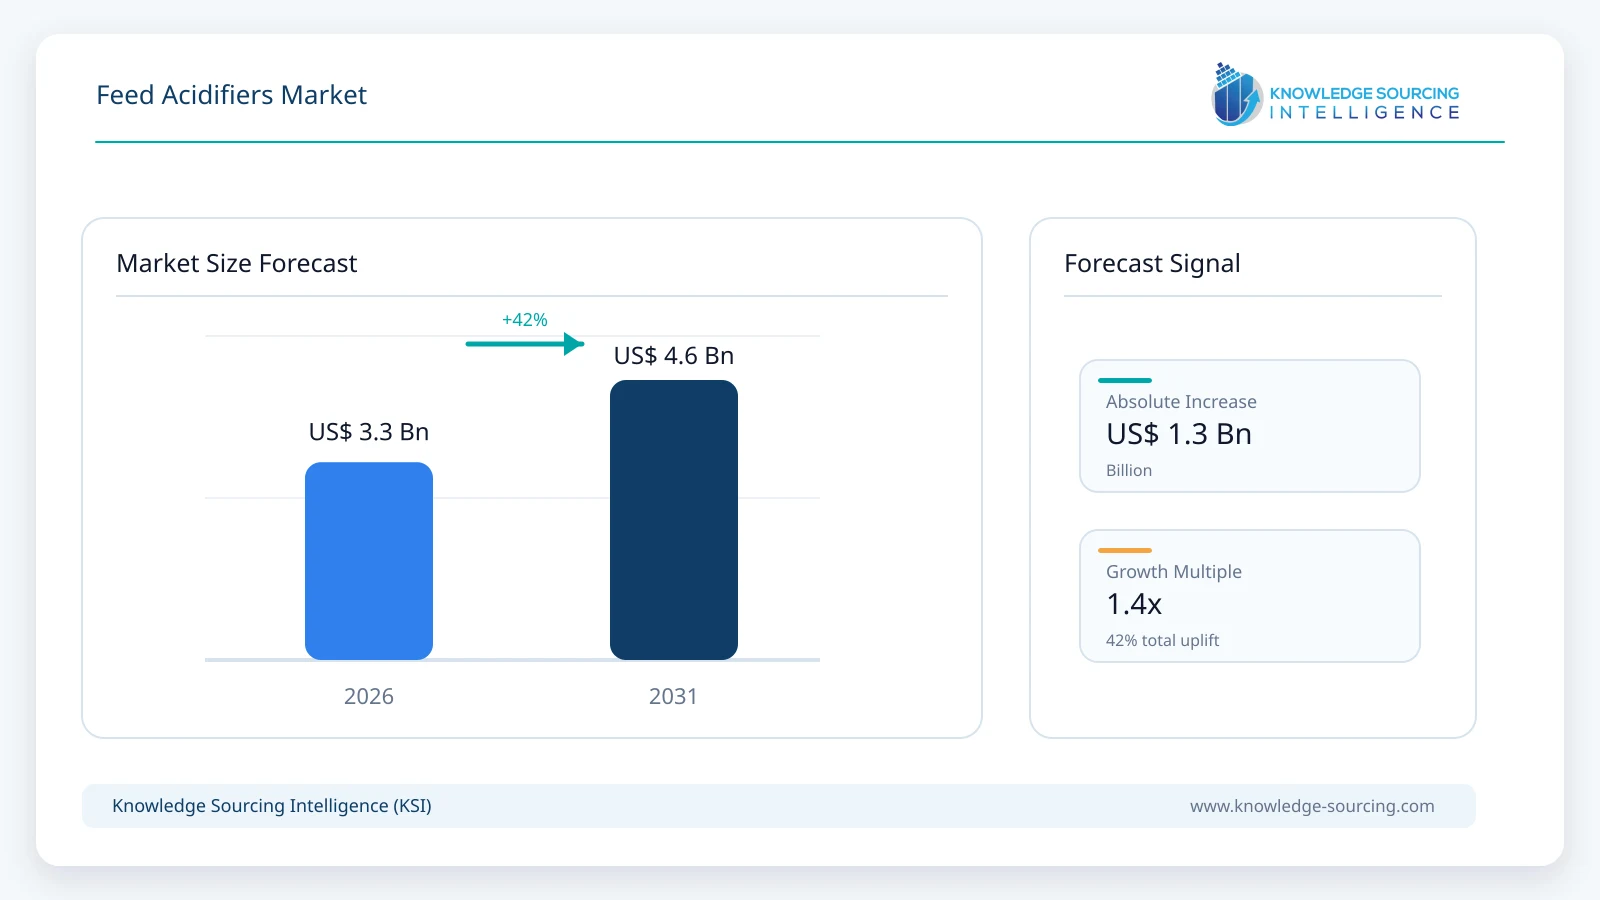
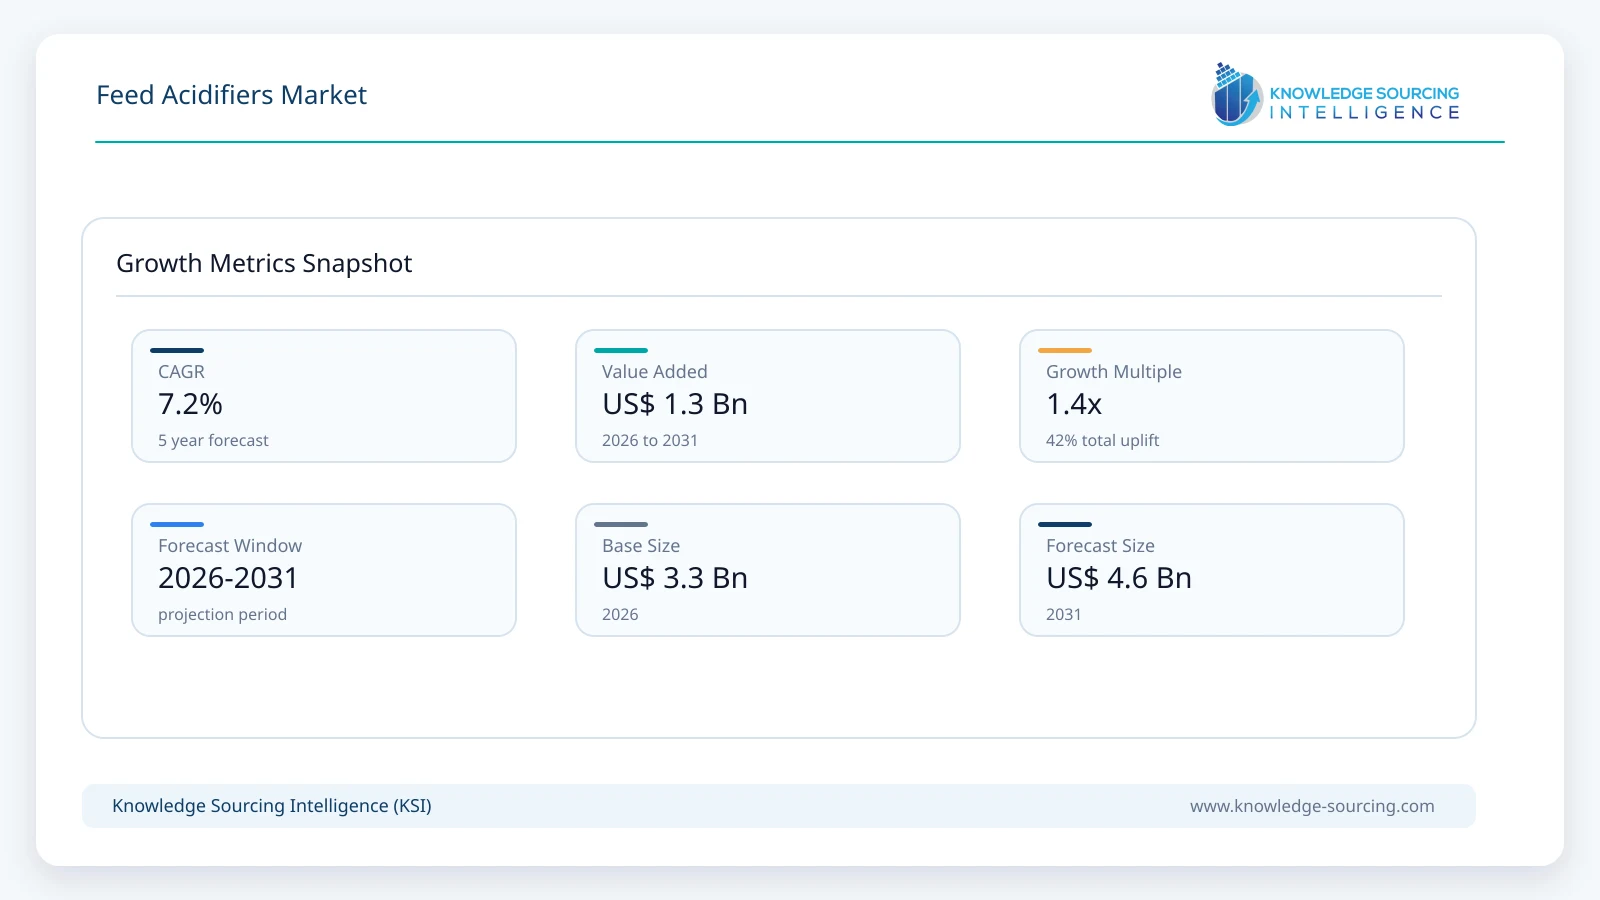
The Feed Acidifiers Market is forecast to grow at a CAGR of 7.2%, increasing from USD 3.25 billion in 2026 to USD 4.60 billion by 2031.
Highlights:
- 1Poultry accounts for approximately 42% of global feed acidifier revenue in 2026.
- 2Asia Pacific contributes about 38% of market value, led by China and Southeast Asia.
- 3Blended acidifier systems represent roughly 64% of 2026 revenue as multifunctional formulations gain preference.
- 4Aquaculture is the fastest-growing major livestock application as commercial feed penetration expands.
- 5Protected and esterified acids gain share by improving handling, stability and lower-gut delivery.
- 6Antimicrobial-stewardship rules continue shifting feed programs toward non-antibiotic gut-health tools.
Feed acidifiers are organic or inorganic acid-based additives incorporated into animal feed, feed ingredients, drinking water or preservation systems to modify pH, inhibit undesirable microorganisms and improve the feed or digestive environment. This report measures revenue from acidifier ingredients, salts, buffered systems, protected or encapsulated acids, esterified organic-acid products and formulated acid blends sold for animal nutrition and feed-hygiene applications. It excludes antibiotics, probiotics, enzymes, phytogenics and general feed preservatives without an acidifying active system. The definition also excludes commodity acids sold into non-feed applications unless their value is attributable to animal-feed use.
The demand base is large because acidifiers sit on top of the global compound-feed industry rather than a narrow specialty-animal market. Alltech estimated 1.44 billion metric tons of feed production in 2025 across 142 countries and 38,837 feed mills. Broiler feed alone reached about 400.4 million metric tons and pig feed 380.9 million metric tons, while layer feed reached 180.1 million metric tons. Aquaculture feed, although much smaller at 55.5 million metric tons, expanded 4.7% in 2025. The largest acidifier opportunity is therefore not only growth in animal numbers, but increasing treatment of existing feed tonnage with higher-value hygiene, preservation and gut-health formulations.
Regulation reinforces this shift. The U.S. Food and Drug Administration has progressively tightened veterinary oversight of medically important antimicrobials used in feed, and in February 2026 finalized guidance encouraging defined durations of use for certain feed-administered antimicrobials. The European Union has long prohibited antibiotics as growth promoters and has strengthened rules governing medicated feed and veterinary medicines. These measures do not make acidifiers direct substitutes for every antimicrobial function, but they raise the value of integrated programs combining organic acids, probiotics, enzymes, phytogenics, biosecurity and improved management.
Market Trends
Blended and Buffered Systems Are Replacing Simple Single-Acid Programs
The market is shifting from undifferentiated use of free formic or propionic acid toward blends designed for feed preservation, pathogen control, digestive support and safer handling. BASF markets combinations of formic and propionic acid alongside buffered propionic systems, while Eastman offers buffered and non-buffered formic-acid blends under its Acitra portfolio. Blends allow suppliers to optimize dissociation characteristics across different pH conditions and reduce the corrosion, odor and handling constraints associated with concentrated free acids. This supports a higher average selling value per treated ton and is one reason market revenue can grow faster than feed volume.
Protected, Encapsulated and Esterified Acids Expand the Functional Addressable Market
Traditional free acids act primarily in feed and the upper digestive tract because they dissociate or are absorbed rapidly. Suppliers increasingly use fat matrices, salts, glyceride esters or encapsulation to deliver acid activity further along the gastrointestinal tract. Kemin markets encapsulated calcium formate and citric acid in FORMYL, Novus uses protected organic-acid systems in PROVENIA and AVIMATRIX, and Perstorp has expanded from basic acidification into tributyrin and valeric-acid ester solutions. This shifts acidifiers from low-value preservative chemistry toward differentiated animal-performance formulations.
Feed Hygiene Is Becoming a Biosecurity Investment Rather Than a Storage-Cost Line
Salmonella, E. coli, molds and other feed-borne organisms can cause both animal-performance losses and downstream food-safety risks. Feed mills increasingly treat acidification as part of a wider biosecurity program that includes raw-material control, thermal treatment, storage management and monitoring. BASF positions formic and propionic acids around preservation and hygiene, Kemin offers multiple acid-based feed-safety products, and Eastman highlights organic-acid blends as alternatives where formaldehyde use faces worker-safety and regulatory scrutiny. This widens demand from simple mold inhibition into pathogen-risk management.
Aquaculture and Emerging-Market Commercialization Create the Next Penetration Wave
Aquaculture feed grew 4.7% globally in 2025, faster than the major terrestrial feed categories, while Africa and Latin America recorded particularly strong gains from smaller bases. The shift from farm-mixed feeds toward commercial compounded diets in parts of Asia and Africa also increases the addressable market for standardized acidifier premixes. These markets often adopt acidifiers initially for preservation and microbial control before moving into more sophisticated gut-health formulations, creating a multi-stage value expansion opportunity.
Market Drivers and Restraints
Antibiotic Reduction and Antimicrobial Stewardship Support Structural Demand
The most durable driver is the global shift away from routine use of medically important antibiotics for growth promotion and indiscriminate disease prevention. Regulatory approaches differ by jurisdiction, but the direction is consistent: veterinary oversight is stronger, durations are more closely defined and producers face customer pressure to document responsible antimicrobial use. Acidifiers are used alongside other eubiotic and biosecurity tools to reduce pathogen pressure, support digestive conditions and protect feed quality, making them an established part of antibiotic-reduced production systems.
Global Poultry and Aquaculture Growth Increases Acidifier-Treated Feed Volumes
OECD-FAO projects poultry to account for 62% of the additional meat consumed globally through 2034, while Alltech already recorded 3.7% growth in broiler feed and 4.7% growth in aquaculture feed during 2025. Both sectors operate with relatively intensive feed programs and high sensitivity to feed conversion, gut health and pathogen control. This creates a favorable demand mix for acidifiers even when growth in cattle feed is slower.
Higher-Value Formulations Raise Revenue per Ton of Feed
The market is not limited to tonnage growth. Protected acids, glycerides, buffered systems, multi-acid blends and acid-plus-functional combinations carry higher formulation value than commodity single acids. Suppliers are increasingly selling technical programs rather than raw acid alone, including application support, dosing systems and combinations aimed at feed mill efficiency, pathogen control or lower-gut delivery. This mix effect adds a second revenue engine beyond animal-feed volume.
Raw-Material Volatility and Formulation Cost Can Limit Inclusion
Feed producers operate under intense cost pressure, especially when grain, energy and protein-meal prices rise. Organic acids compete for formulation budget with enzymes, probiotics, phytogenics, minerals and other performance additives. Some acid systems also require specialized dosing equipment or corrosion-resistant handling. When livestock margins weaken, customers may reduce inclusion rates, switch to lower-cost single acids or prioritize only high-risk production phases. This prevents the market from sustaining the double-digit growth rates sometimes assumed in aggressive syndicated forecasts.
Segment Analysis
By Type - Propionic Acid
Propionic acid remains the largest individual acidifier category because it is widely used for mold inhibition, grain preservation, compound-feed shelf life and silage stability. This segment will be valued at approximately USD 1.04 billion in 2026 and approximately USD 1.40 billion by 2031. Growth is supported by weather-related storage variability, greater feed-mill quality control and demand for buffered or blended propionate systems that are less corrosive than straight acid. Lactic, citric and butyric-derived systems grow faster from smaller bases as suppliers target digestive and lower-gut functions rather than preservation alone.
By Form - Dry Acidifiers
Dry acidifiers account for approximately USD 1.92 billion in 2026 and retain the larger share because they integrate easily into premixes and complete feed, simplify transport and offer safer handling for many feed mills. Growth is increasingly tied to coated, encapsulated and carrier-based formats that survive pelleting and release active compounds further through the gastrointestinal tract. Liquid systems remain important for feed hygiene, grain treatment, drinking-water acidification and applications where precise spraying or rapid microbial action is required.
By Compound - Blended Acidifiers
Blended acidifiers are projected to exceed USD 3.1 billion by 2031 as feed formulators combine acids with different pKa values, salts, monoglycerides, surfactants or other functional components. Multi-acid systems can broaden antimicrobial activity and provide a more balanced compromise between efficacy, handling and corrosion. Single-acid products remain essential for cost-sensitive preservation and standardized applications, but their share of market value gradually declines as producers purchase more differentiated formulations.
By Livestock - Poultry
Poultry is the largest livestock application and is projected to approach USD 1.92 billion of acidifier revenue by 2031. The segment benefits from short production cycles, intensive compound-feed use, tight feed-conversion economics and sustained concern over Salmonella, E. coli, Clostridium and litter quality. Acidifier programs are used in broilers, layers and breeders through feed or drinking water. Aquaculture is the fastest-growing major application, supported by expanding commercial aquafeed volumes and the need to maintain feed stability and gut health under intensive stocking conditions.
By Geography - Asia Pacific
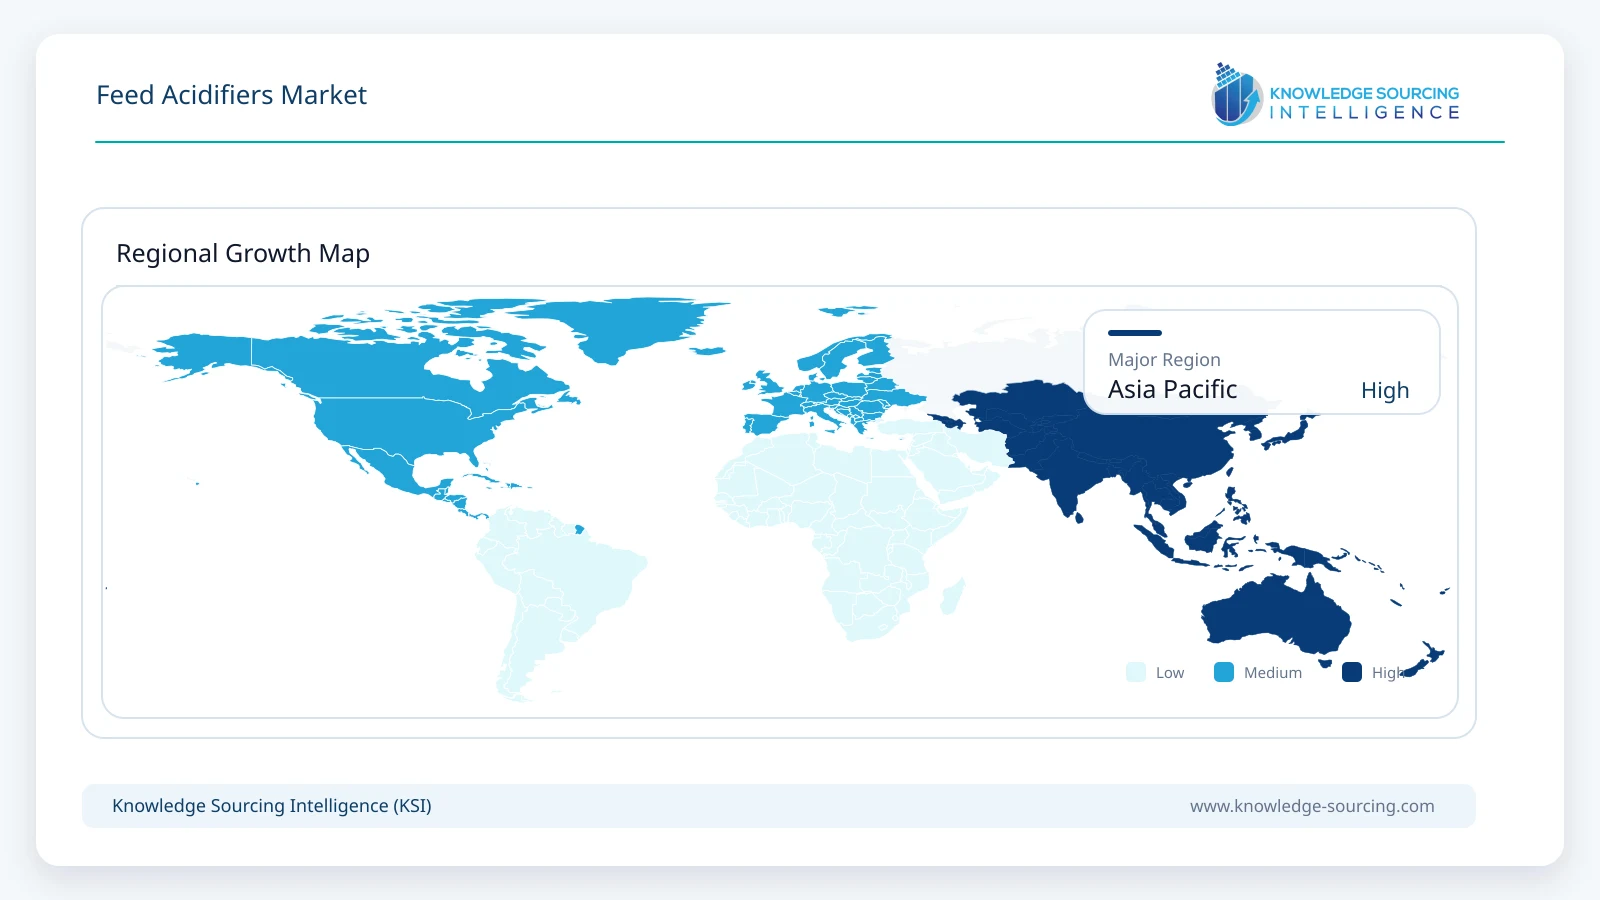
Asia Pacific is the largest regional market and is projected to reach approximately USD 1.85 billion by 2031. The region combines the world's largest feed producer, China, with rapidly growing feed industries in India, Vietnam and Southeast Asia. Alltech reported 559.3 million metric tons of Asian feed production in 2025, and China alone produced about 330.1 million metric tons. Commercialization of livestock production, recovery in swine, poultry growth and rising aquaculture intensity all support acidifier penetration, while price sensitivity favors locally optimized blends and salts alongside multinational premium formulations.
Competitive Environment
The competitive landscape spans vertically integrated organic-acid producers, specialist animal-nutrition formulators and diversified feed-additive companies. BASF, Perstorp and Eastman benefit from direct access to core acid chemistry and use this position to offer preservation, hygiene and gut-health systems. Kemin, Novus, Anpario, Impextraco, Jefo, Nutrex and Vetagro compete more heavily through formulated solutions, encapsulation, application know-how and species-specific technical support. Larger nutrition groups such as dsm-firmenich, Nutreco, Cargill, ADM and Alltech can position acidifiers within broader gut-health or antibiotic-reduction programs rather than as standalone ingredients.
Product differentiation increasingly centers on delivery technology, lower inclusion rates, compatibility with pelleting, reduced corrosion, worker safety and evidence of performance under commercial conditions. Perstorp, for example, emphasizes esterified organic acids and has expanded from preservation chemistry into butyrate and valerate solutions, while Novus uses fat-embedded organic acids for targeted release. Eastman combines short-chain acids with monoglyceride strategies, and Kemin uses encapsulation and blended-acid programs across poultry, swine and feed safety. Competitive advantage therefore depends increasingly on technical service and formulation efficacy rather than acid price alone.
Recent Developments
July 2026: Perstorp highlighted advanced moisture-management and mold-inhibition approaches for feed mills, reinforcing the integration of acid-based preservation with mill-efficiency programs.
April 2026: Alltech reported global feed production of 1.44 billion metric tons in 2025, up 2.9%, with poultry, swine and aquaculture all recording positive growth.
February 2026: The U.S. FDA finalized Guidance for Industry #273 on defining durations of use for certain medically important antimicrobials administered in feed.
January 2026: Perstorp showcased its tributyrin-based ProPhorce SR 130 gut-health platform at IPPE 2026 for North and Latin American feed producers.
2025: Eastman expanded technical communication around combined organic-acid and monoglyceride strategies for post-weaning piglet gut health and performance.
Feed Acidifiers Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.25 billion |
| Total Market Size in 2031 | USD 4.60 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Form, Compound, Livestock, Geography |
| Companies |
|
Market Segmentation
By Type
Propionic Acid
Formic Acid
Lactic Acid
Citric Acid
Fumaric Acid
Butyric Acid and Derivatives
Others
By Form
Dry
Liquid
By Compound
Blended Acidifiers
Single Acidifiers
By Livestock
Poultry
Swine
Ruminants
Aquaculture
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Vietnam
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Antibiotic Reduction and Antimicrobial Stewardship Support Structural Demand
3.1.2. Global Poultry and Aquaculture Growth Increases Acidifier-Treated Feed Volumes
3.1.3. Higher-Value Formulations Raise Revenue per Ton of Feed
3.2. Market Restraints
3.2.1. Raw-Material Volatility and Formulation Cost Can Limit Inclusion
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Buffered and Low-Corrosion Organic Acid Systems
4.2. Protected and Encapsulated Acid Delivery
4.3. Esterified Butyric and Valeric Acid Solutions
4.4. Multi-Acid and Acid-Monoglyceride Blends
4.5. Precision Dosing and Feed-Mill Application Systems
5. FEED ACIDIFIERS MARKET BY TYPE
5.1. Introduction
5.2. Propionic Acid
5.3. Formic Acid
5.4. Lactic Acid
5.5. Citric Acid
5.6. Fumaric Acid
5.7. Butyric Acid and Derivatives
5.8. Others
6. FEED ACIDIFIERS MARKET BY FORM
6.1. Introduction
6.2. Dry
6.3. Liquid
7. FEED ACIDIFIERS MARKET BY COMPOUND
7.1. Introduction
7.2. Blended Acidifiers
7.3. Single Acidifiers
8. FEED ACIDIFIERS MARKET BY LIVESTOCK
8.1. Introduction
8.2. Poultry
8.3. Swine
8.4. Ruminants
8.5. Aquaculture
8.6. Others
9. FEED ACIDIFIERS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Italy
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. South Africa
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Vietnam
9.6.6. Thailand
9.6.7. Indonesia
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. BASF SE
11.2. Perstorp Group (PETRONAS Chemicals Group)
11.3. Eastman Chemical Company
11.4. Kemin Industries, Inc.
11.5. Novus International, Inc.
11.6. dsm-firmenich
11.7. Anpario plc
11.8. Impextraco N.V.
11.9. Jefo Nutrition Inc.
11.10. Corbion N.V.
11.11. ADDCON GmbH
11.12. Nutrex N.V.
11.13. Vetagro S.p.A.
11.14. Nutreco / Selko Feed Additives
11.15. Cargill, Incorporated / Provimi
11.16. ADM
11.17. Yara International ASA
11.18. Borregaard AS
11.19. Alltech, Inc.
11.20. Bluestar Adisseo Company
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











