
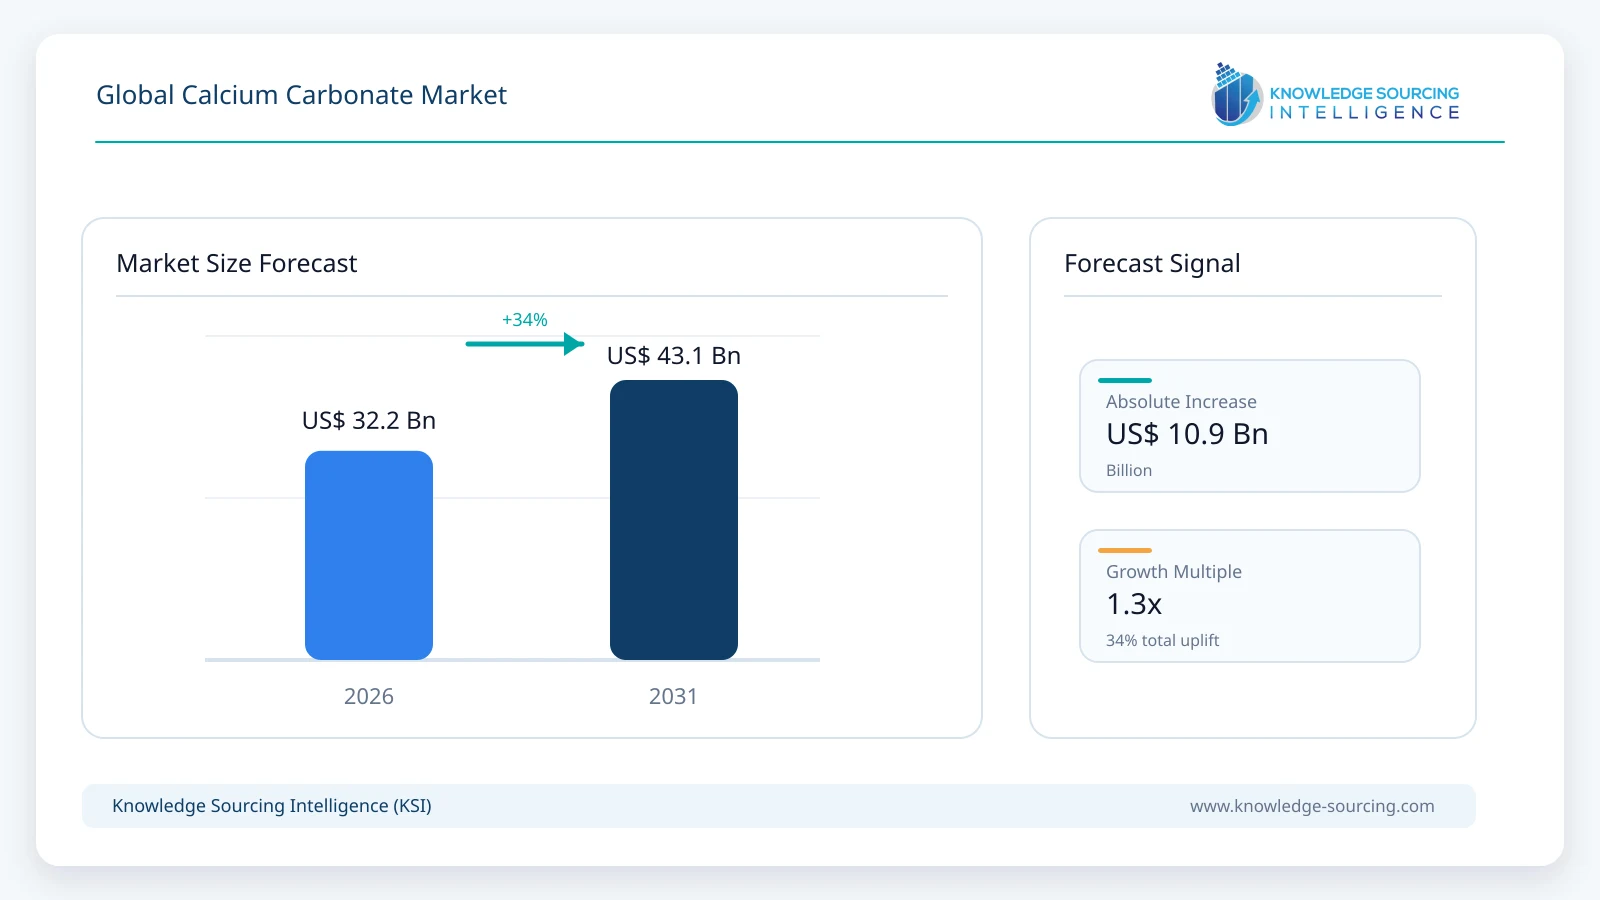
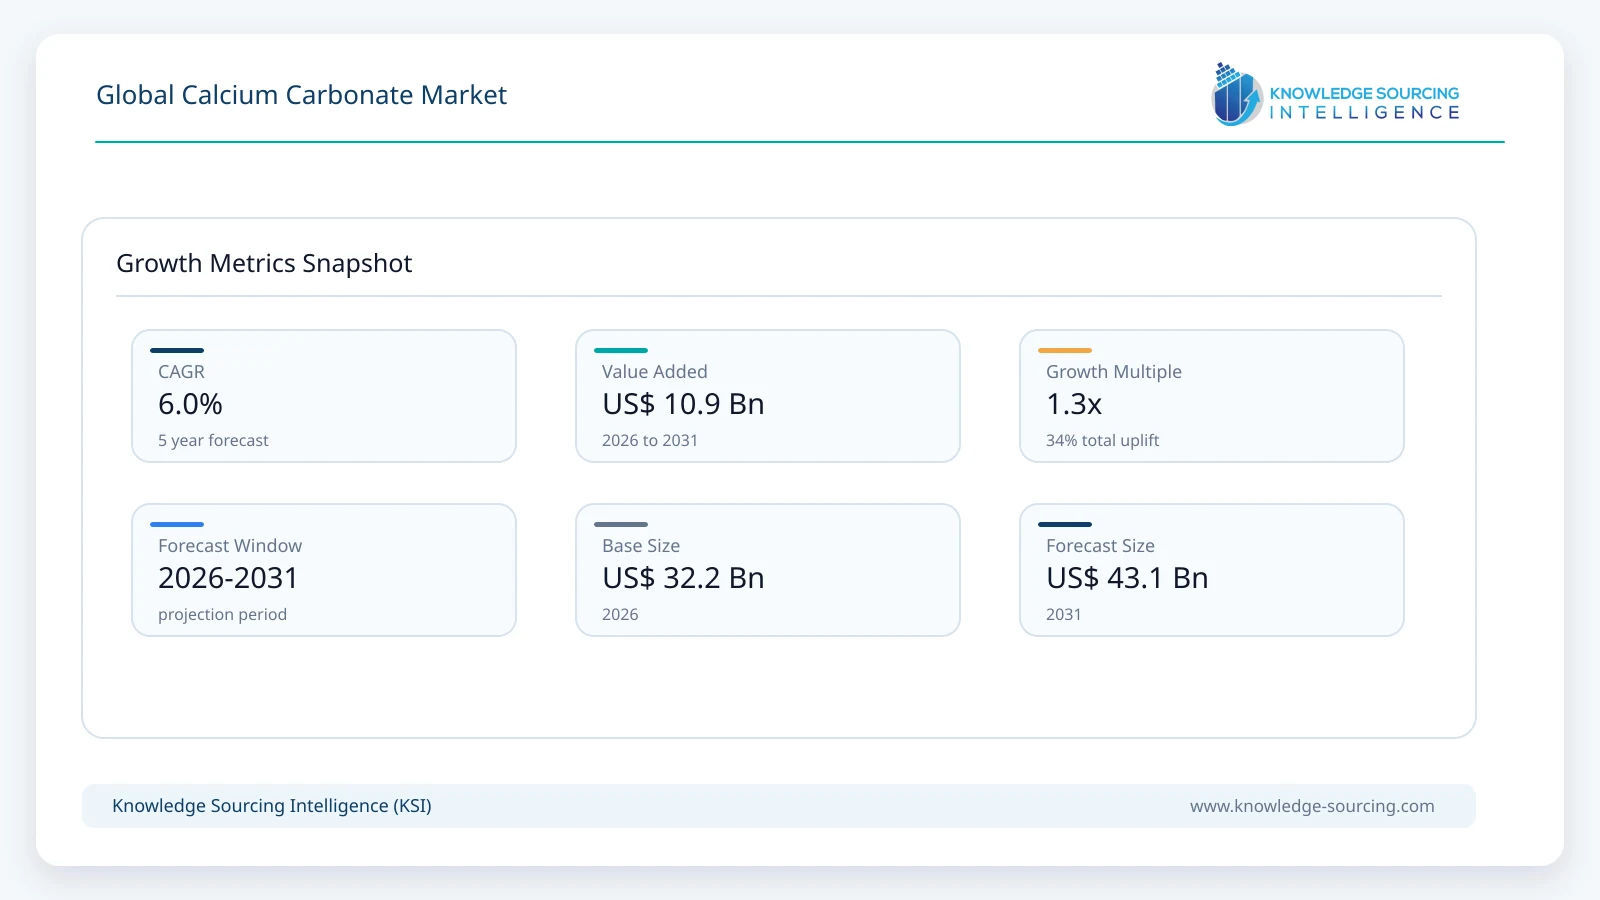
The global calcium carbonate market is forecast to grow from USD 32.2 billion in 2026 to USD 43.1 billion in 2031, representing a CAGR of 6.0% during the forecast period.
Highlights:
- 1Ground calcium carbonate is estimated to account for approximately 73.0% of global market revenue in 2026, supported by high-volume use in paper, polymers, coatings, construction formulations and other industrial applications.
- 2Paper is estimated to represent approximately 27.0% of global calcium carbonate revenue in 2026, reflecting sustained use of GCC and PCC as fillers and coating pigments in paper and paperboard production.
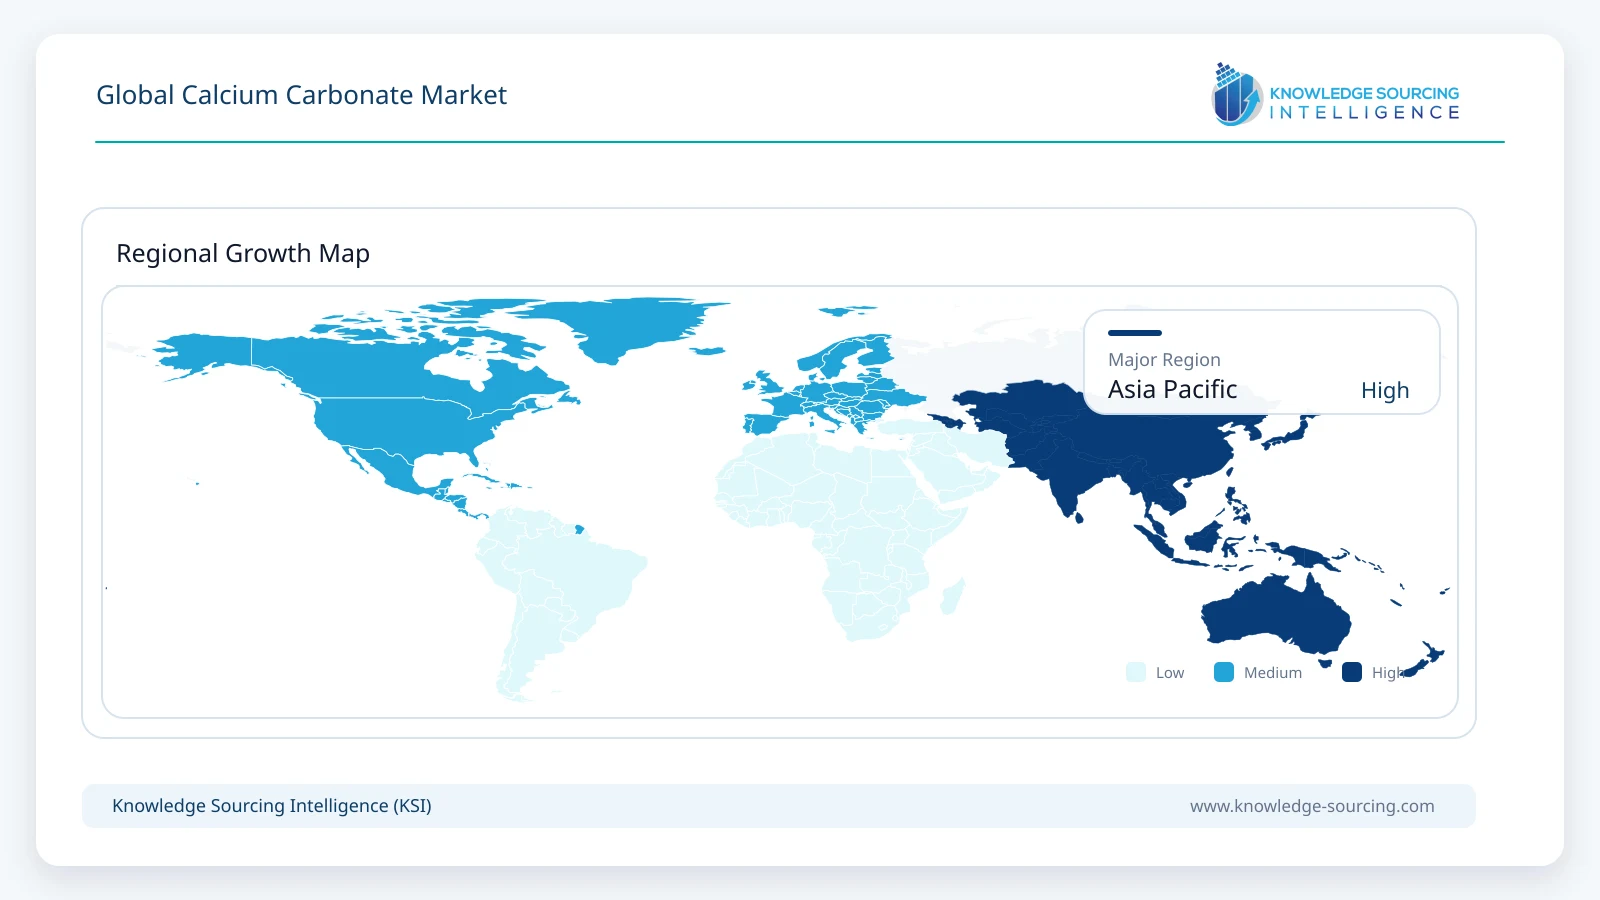
- 3Asia Pacific is estimated to account for approximately 45.0% of global market revenue in 2026, supported by large paper, plastics, coatings, construction and industrial manufacturing bases.
- 4Calcium carbonate is increasingly positioned as a lower-carbon mineral filler in polymers and construction materials, where it can replace a portion of higher-cost or higher-carbon raw materials.
- 5On-site and satellite production remains strategically important in paper and board because local GCC and PCC production reduces freight intensity and supports high-volume mill consumption.
- 6Product differentiation is increasing through ultrafine particle control, surface treatment, coated grades, high-purity food and pharmaceutical products, recycled calcium carbonate and application-specific formulations.
Market Overview
The calcium carbonate market covers commercially processed ground calcium carbonate (GCC), precipitated calcium carbonate (PCC), nano and ultrafine calcium carbonate, coated grades and other specialty calcium carbonate products sold into industrial and consumer applications. The market includes dry powders, slurries and application-specific grades used in paper and board, polymers, paints and coatings, adhesives and sealants, construction materials, agriculture, food, pharmaceuticals and other industrial uses.
The market excludes unprocessed limestone used directly as aggregate, dimension stone, cement kiln feed and other bulk quarry products that do not pass through a calcium-carbonate processing or specialty-mineral value chain. It also excludes quicklime, hydrated lime, dolomite and other carbonate minerals where calcium carbonate is not the commercial product being sold. This boundary maintains consistency between supplier revenues and the value of processed GCC, PCC and specialty grades.
The industry combines a small group of globally diversified mineral companies with a large regional producer base. Omya operates a broad calcium carbonate network across paper, polymers, construction, food and pharmaceutical applications. Minerals Technologies identifies itself as a leading calcium carbonate producer and the largest global supplier of precipitated calcium carbonate, with current PCC and GCC products serving paper and packaging, construction, polymers, food and pharmaceutical markets. Imerys, Huber Specialty Minerals, Sibelco and Nordkalk maintain significant positions across natural and processed calcium carbonate, while regional specialists such as Maruo Calcium, Shiraishi Kogyo, Gulshan Polyols, Wolkem, ACCM, Reverte Minerals, Calcinor and Longcliffe compete through mineral quality, particle engineering and local supply.
Demand growth is increasingly influenced by the role calcium carbonate plays in material efficiency rather than only by underlying volume growth in end-use industries. In polymers, mineral loading can reduce resin consumption while improving stiffness, opacity, thermal transfer and process economics. Omya states that calcium carbonate can replace a substantial share of polymer in selected applications, while newer recycled-calcium-carbonate grades support circularity targets. In paper and board, calcium carbonate continues to improve brightness, opacity, printability and production efficiency. In construction, fine GCC is used in dry mixes, concrete formulations, sealants, flooring, roofing and other mineral-based systems.
The 2026-2031 outlook remains positive but uneven across applications. Traditional printing and writing paper remains structurally pressured in many mature markets, while packaging board, tissue, polymers, construction compounds, sealants, recycled plastics, food fortification and specialty PCC create more resilient growth pools. The market therefore increasingly rewards producers that can shift product mix toward higher-value grades and faster-growing applications rather than relying only on commodity mineral volume.
Calcium Carbonate Market Trends
Mineral Loading Supports Lower-Carbon Polymer Formulations
Calcium carbonate is increasingly used to reduce polymer consumption, lower formulation cost and improve processing efficiency. Fine and surface-treated grades are widely used in polyolefin films, PVC profiles and pipes, masterbatch, cable compounds, automotive plastics and molded products. Omya states that calcium carbonate can replace up to 60% of polymer in selected applications, while thermal-transfer benefits can improve production line throughput.
The next phase of growth is moving beyond conventional virgin-mineral loading. Recycled-calcium-carbonate products such as Omya’s Omyaloop FC are designed to increase recycled content in polymer compounds while maintaining processing performance. This creates a new route for mineral suppliers to participate in circular-economy targets and gives processors another lever for reducing the carbon footprint of finished plastic products.
Paper and Board Remain Core Markets, but Product Mix Is Changing
Paper continues to be one of the largest calcium carbonate applications because GCC and PCC improve brightness, opacity, smoothness and printability while partially replacing more expensive fiber. On-site production is particularly important for large paper mills because mineral slurries are consumed at high volume and freight can materially affect economics. Omya and Minerals Technologies both operate models in which calcium carbonate is produced near or at customer facilities.
Demand is shifting away from some mature printing and writing grades toward packaging board, specialty papers and tissue-related applications. This changes both product mix and plant utilization. Producers with wet-ground GCC, PCC and engineered filler technologies are positioned to serve mills seeking lower fiber usage, higher machine productivity and improved sustainability performance.
Ultrafine, Coated and Specialty Grades Gain Value
Particle-size control and surface treatment increasingly determine value in polymers, sealants, coatings and specialty industrial formulations. Ultrafine GCC and PCC can improve rheology, reinforcement, opacity, dispersion and surface finish. Coated calcium carbonate improves compatibility with hydrophobic polymer systems and can support higher mineral loading without unacceptable processing losses.
Specialty producers are also expanding in food, pharmaceutical and high-purity applications. Huber markets food- and USP-grade calcium carbonate, Minerals Technologies offers certified PCC grades, and Japanese producers such as Maruo Calcium and Shiraishi manufacture controlled-particle products for food, pharmaceutical and advanced industrial uses. These grades represent smaller volumes than conventional GCC but materially higher value per tonne.
Regional Supply and Quarry Quality Remain Competitive Advantages
Calcium carbonate is widely available geologically, but commercial performance depends on brightness, purity, particle morphology, consistency and logistics. High-quality deposits near end-use clusters reduce transportation cost and enable producers to offer stable product properties. ACCM in Egypt, Wolkem in India and Vietnam, Reverte Minerals in Spain and Longcliffe in the United Kingdom illustrate the importance of high-purity regional resources combined with grinding and classification capability.
Large customers increasingly value supply resilience alongside product performance. Producers with multiple quarries, processing sites and local technical service can reduce exposure to freight disruption while tailoring products to regional formulations. This favors companies with integrated mineral reserves and processing networks, but also leaves room for strong regional specialists.
Market Drivers
Growing Use of Mineral Fillers in Plastics
Calcium carbonate lowers formulation cost and can improve stiffness, dimensional stability, opacity, printability and thermal conductivity in many polymer systems. Rising plastics production, greater use of masterbatch and pressure to reduce resin consumption support continued demand for fine and coated GCC. The ability to increase mineral loading while maintaining mechanical performance is a central area of product development.
Sustained Packaging and Paperboard Demand
Paper and board producers use calcium carbonate to reduce fiber requirements and improve surface and optical properties. Growth in packaging, tissue and selected specialty paper grades partially offsets weakness in traditional printing and writing papers. On-site mineral production further improves economics for large mills and supports long-term supplier relationships.
Construction and Building-Material Formulation
Calcium carbonate is used in dry-mix mortars, adhesives, sealants, roofing, flooring, concrete formulations, paints and other building products. Construction demand supports large-volume GCC consumption, while ultrafine and surface-treated products create higher-value opportunities in specialized formulations. The shift toward lower-clinker and material-efficient building systems can also create additional roles for finely engineered limestone and calcium carbonate products.
Food, Pharmaceutical and Nutritional Applications
High-purity calcium carbonate provides a concentrated source of elemental calcium and is used in tablets, supplements, fortified foods, antacid products and pharmaceutical formulations. These applications require tighter purity, heavy-metal, particle-size and quality-control specifications than conventional industrial grades. Higher value per tonne makes food and pharmaceutical products strategically attractive despite their smaller volume base.
Market Restraints
Energy, Freight and Processing Costs
Although calcium carbonate is widely available, fine grinding, drying, classification, surface treatment and slurry handling require energy and capital. Freight is especially important because many grades are relatively low value per unit weight. Producers therefore need well-positioned quarries and processing plants or customer-adjacent production to maintain competitive delivered costs.
Structural Pressure in Graphic Paper
Declining printing and writing paper demand in mature markets reduces consumption of some traditional filler and coating grades. Producers exposed to these applications must shift capacity toward packaging, tissue, polymers, construction and specialty products. The transition can create periods of underutilization at assets designed around older paper demand patterns.
Competition from Alternative Fillers and Pigments
Calcium carbonate competes with kaolin, talc, silica, titanium dioxide, wollastonite and other mineral or synthetic additives depending on the required properties. Substitution is application-specific and can be driven by brightness, reinforcement, density, opacity, rheology, regulatory requirements and cost. Suppliers therefore need technical-service capability rather than relying only on mineral availability.
Environmental and Quarry Permitting Requirements
Mining and mineral processing are subject to land-use, water, dust, energy and permitting requirements. New quarry development can face long approval cycles and community scrutiny. Companies are responding through quarry rehabilitation, environmental-product declarations, renewable electricity, recycled mineral streams and improved water management, but these initiatives can increase near-term operating and capital requirements.
Segmentation Analysis
Market Segmentation by Commercial Grade
Ground Calcium Carbonate (GCC)
Ground calcium carbonate is estimated at approximately USD 23.51 billion in 2026. GCC is the largest commercial-grade segment because it is produced at high volume from natural limestone, marble or chalk and serves a broad range of applications including paper, plastics, paints and coatings, adhesives and sealants, construction compounds, agriculture and food-grade uses.
The segment spans commodity milled products through ultrafine, wet-ground and surface-treated grades. Competitive advantage depends on deposit purity, brightness, particle-size distribution, coating technology, energy efficiency and proximity to customers. Omya, Imerys, Minerals Technologies, Huber, Nordkalk, Sibelco and numerous regional producers maintain broad GCC portfolios, while companies such as ACCM, Wolkem, Reverte Minerals and Longcliffe compete strongly in selected geographic and application markets.
Market Segmentation by Industry
Paper
Paper is estimated at approximately USD 8.69 billion in 2026. Calcium carbonate is used as both filler and coating pigment to improve brightness, opacity, smoothness and printing performance while reducing dependence on fiber. GCC is widely used in coating and filling, while PCC is particularly valuable where controlled particle morphology and optical performance are required.
The segment remains commercially important despite declining graphic-paper demand in some mature economies. Packaging board, tissue, specialty papers and mill-efficiency initiatives support continued mineral consumption. Supplier investment is increasingly focused on on-site production, lower-energy processing and engineered filler systems that improve machine productivity or enable greater replacement of fiber and other mineral pigments.
Regional Outlook
Asia Pacific
Asia Pacific is estimated at approximately USD 14.49 billion in 2026, making it the largest regional calcium carbonate market. China, India, Japan, South Korea and Southeast Asia combine large paper and board industries with major plastics, coatings, construction, rubber and manufacturing demand. The region also contains a substantial base of local and multinational calcium carbonate production.
Growth is supported by packaging demand, polymer processing, infrastructure and construction activity, automotive and electronics manufacturing, and increasing use of mineral fillers to optimize material costs. Omya previously announced approximately one million tonnes per year of new GCC and PCC capacity across seven paper and board locations in China and Indonesia, illustrating the scale of regional demand and the importance of customer-adjacent production.
North America
North America is a mature but high-value market with strong demand from paper and packaging, polymers, construction products, paints and coatings, food, pharmaceuticals and agriculture. Minerals Technologies, Huber and Omya maintain significant regional positions, supported by high-purity reserves and specialty product portfolios. Growth is increasingly concentrated in higher-value functional fillers, packaging, construction formulations and food/pharmaceutical grades rather than commodity printing-paper applications.
Europe
Europe has a broad producer base and mature application infrastructure across paper, polymers, coatings, construction and specialty industrial products. Imerys, Omya, Nordkalk, Sibelco, Calcinor and Reverte Minerals are among the important regional suppliers. Environmental-product declarations, lower-carbon processing, recycled mineral content and material-efficiency claims are becoming more important purchasing factors as customers work toward decarbonization targets.
South America
South American demand is concentrated in paper and pulp, plastics, construction materials, agriculture, paints and coatings. Brazil provides the largest regional industrial base. Growth is supported by packaging, agricultural production and construction activity, although logistics costs and currency volatility can make locally sourced mineral supply particularly important.
Middle East and Africa
The Middle East and Africa combine growing construction, plastics and coatings demand with access to high-quality limestone resources in selected markets. Egypt has developed a significant export-oriented GCC industry around high-brightness deposits, while Gulf markets support construction and polymer applications. The region remains fragmented, with growth dependent on local processing capacity and export logistics.
Competitive Environment
The calcium carbonate market is fragmented globally but has a concentrated multinational tier. Omya, Imerys and Minerals Technologies combine large mineral reserves, application-development capabilities and multi-region production networks. Huber, Sibelco and Nordkalk maintain strong positions in selected geographies and specialty applications. Regional specialists compete effectively where they control high-quality deposits, efficient processing and local customer relationships.
Competition differs materially by application. Paper and board reward wet-grinding capability, slurry logistics and on-site production; polymers and sealants require particle engineering and surface treatment; food and pharmaceutical products require high purity and certification; construction and agriculture place greater emphasis on delivered cost and local availability. The ability to serve multiple applications from the same mineral base provides scale advantages, but technical specialization can create defensible niches for smaller producers.
Recent Developments
September 2026: Minerals Technologies presented its updated long-term growth strategy and new mineral-processing innovations at its 2026 Investor Day, reinforcing investment in higher-value specialty mineral applications and deeper positions in existing core markets.
August 2026: Longcliffe published an updated responsible-sourcing report and maintained current environmental-product declarations for dry ground calcium carbonate grades, reflecting growing customer demand for verified product-footprint information.
April 2026: Omya published its 2025 Sustainability Report with updated environmental performance data and product references covering ultrafine GCC, while continuing to expand recycled-calcium-carbonate and lower-carbon mineral solutions for polymers and other applications.
March 2026: Sibelco reported its 2025 financial performance and launched the Build 2030 strategy, emphasizing portfolio discipline, customer innovation and sustainable growth across its industrial-mineral businesses. Calcium carbonate remains an active product within its specialty mineral portfolio.
2026: Maruo Calcium reported consolidated sales of JPY 12.639 billion for the fiscal year ended March 2026 and continued to market GCC, PCC, colloidal calcium carbonate and food/pharmaceutical grades across industrial applications.
2025: Omya showcased recycled calcium carbonate, high-mineral-loading and engineered polymer solutions at K Show 2025, targeting lower-carbon and higher-recycled-content plastics applications.
Market Outlook
The calcium carbonate market is expected to expand steadily through 2031 as paper and packaging, polymers, construction, coatings and specialty consumer applications continue to absorb large volumes of GCC and PCC. Growth will be supported less by simple commodity-volume expansion and more by increased mineral loading, higher-value particle engineering, surface treatment, application-specific functionality and regional production optimization.
Ground calcium carbonate will remain the dominant commercial grade because of its broad availability and cost effectiveness, while PCC, nano, coated and specialty products are expected to capture a greater share of incremental value in applications requiring controlled particle properties. Asia Pacific is expected to remain the largest demand region because of its manufacturing scale and continued expansion in paperboard, plastics and construction materials.
Competitive advantage will increasingly depend on the combination of mineral-reserve quality, energy-efficient processing, local logistics, technical service and sustainability credentials. Producers able to document product footprints, offer recycled or lower-carbon grades, and support customers in reducing resin, fiber or other higher-impact raw materials are positioned to capture a greater share of premium applications. The market is forecast to add approximately USD 10.9 billion in annual revenue between 2026 and 2031.
Calcium Carbonate Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 32.2 billion |
| Total Market Size in 2031 | USD 43.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Commercial Grade, Industry, Geography |
| Companies |
|
Market Segmentation
By Commercial Grade
Precipitated Calcium Carbonate (PCC)
Ground Calcium Carbonate (GCC)
Nano Calcium Carbonate
Coated Calcium Carbonate
By Industry
Construction
Agriculture
Paper
Food & Beverage
Pharmaceutical
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Egypt
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Market Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Growing Use of Mineral Fillers in Plastics
4.1.2. Sustained Packaging and Paperboard Demand
4.1.3. Construction and Building-Material Formulation
4.1.4. Food, Pharmaceutical and Nutritional Applications
4.2. Market Restraints
4.2.1. Energy, Freight and Processing Costs
4.2.2. Structural Pressure in Graphic Paper
4.2.3. Competition from Alternative Fillers and Pigments
4.2.4. Environmental and Quarry Permitting Requirements
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Pricing and Logistics Structure
4.6. Sustainability and Product-Footprint Trends
5. GLOBAL CALCIUM CARBONATE MARKET BY COMMERCIAL GRADE
5.1. Introduction
5.2. Precipitated Calcium Carbonate (PCC)
5.3. Ground Calcium Carbonate (GCC)
5.4. Nano Calcium Carbonate
5.5. Coated Calcium Carbonate
6. GLOBAL CALCIUM CARBONATE MARKET BY INDUSTRY
6.1. Introduction
6.2. Construction
6.3. Agriculture
6.4. Paper
6.5. Food & Beverage
6.6. Pharmaceutical
6.7. Others
7. GLOBAL CALCIUM CARBONATE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Italy
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Egypt
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Mineral Reserve and Processing Positioning
8.3. Specialty Product and Surface-Treatment Capability
8.4. Market Share Analysis
8.5. Mergers, Acquisitions, Agreements and Capacity Expansion
8.6. Competitive Dashboard
9. COMPANY PROFILES
9.1. Omya AG
9.2. Imerys S.A.
9.3. Minerals Technologies Inc.
9.4. J.M. Huber Corporation
9.5. Sibelco
9.6. Maruo Calcium Co., Ltd.
9.7. Shiraishi Kogyo Kaisha, Ltd.
9.8. Gulshan Polyols Limited
9.9. 20 Microns Limited
9.10. Wolkem India Limited
9.11. ACCM - Ascom Carbonate and Chemicals Manufacturing
9.12. Reverte Minerals, S.A.
9.13. Calcinor
9.14. Longcliffe Quarries Ltd.
9.15. Nordkalk Corporation
10. APPENDIX
Navigate
Trusted by the world's leading organizations











