
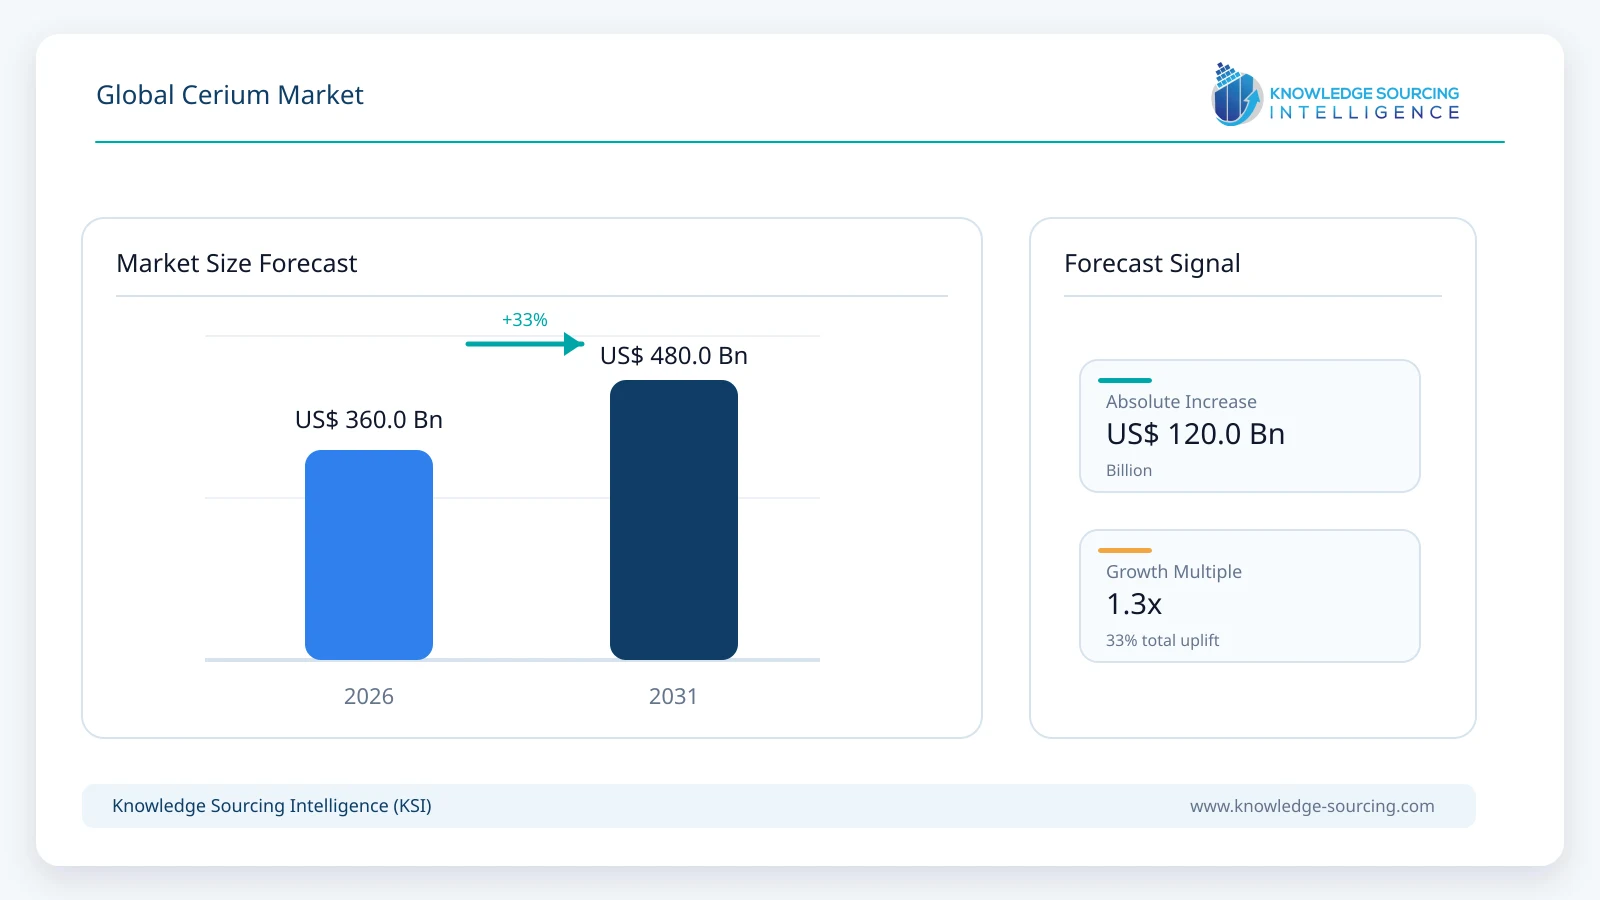
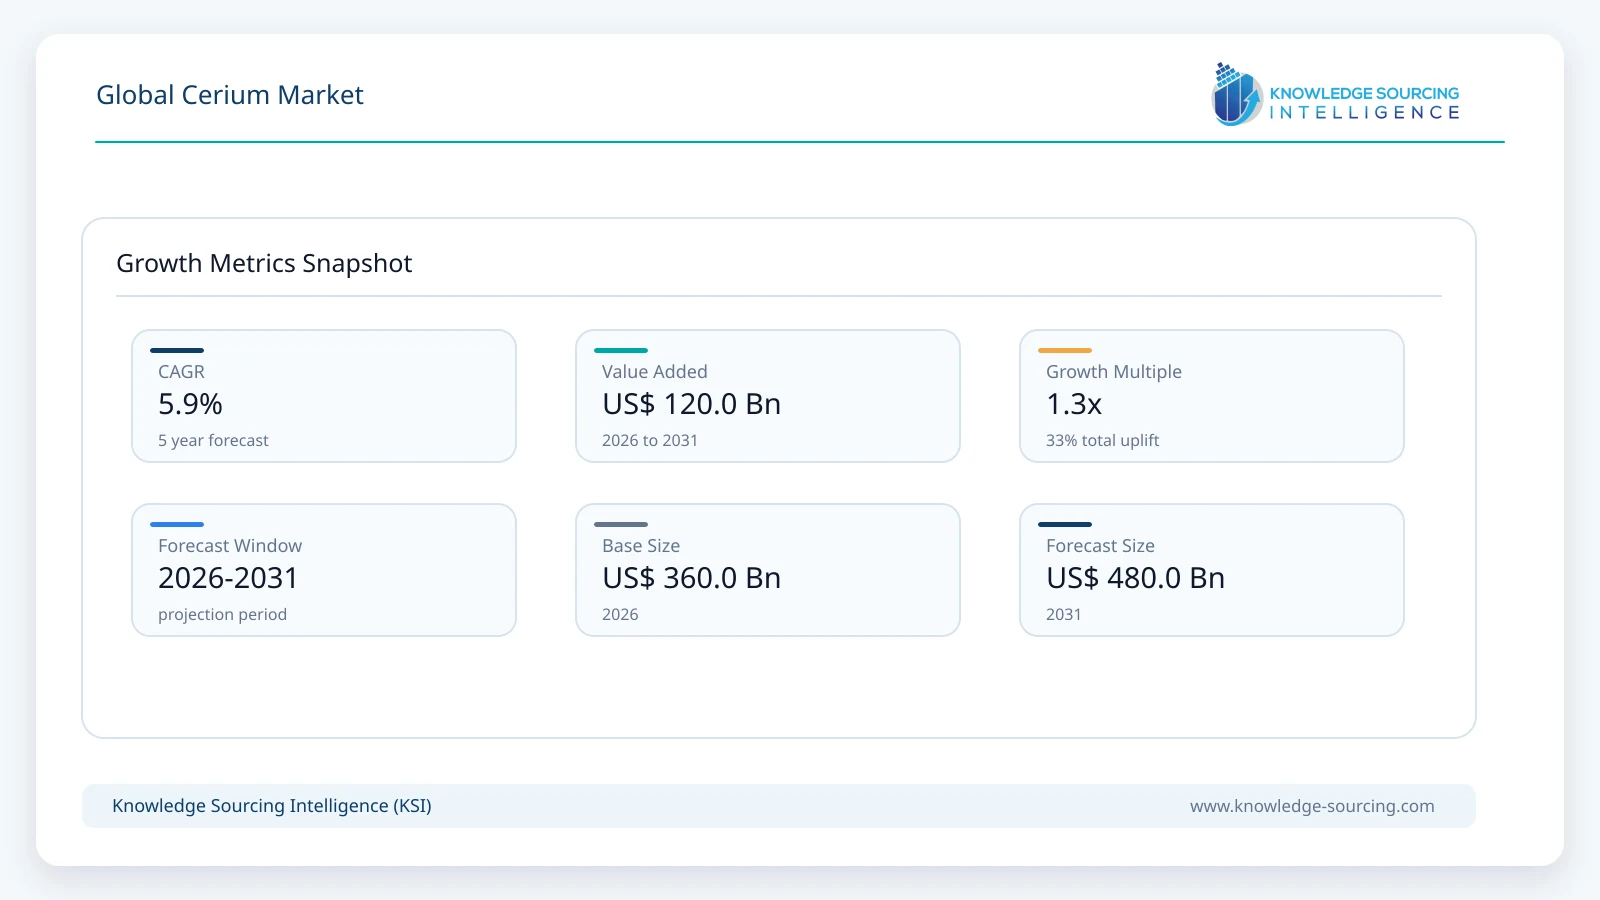
The global cerium market is forecast to grow from USD 360 million in 2026 to USD 480 million by 2031, representing a CAGR of approximately 5.9% during the forecast period.
Highlights:
- 1Cerium oxide accounts for approximately 77% of global cerium market value in 2026, driven by catalysts, glass polishing and specialty material applications.
- 2Bastnäsite-derived material accounts for approximately 64% of market value in 2026, led by major light rare earth resources in China and the United States.
- 3Catalyst applications account for approximately 38% of global cerium demand in 2026, led by automotive emissions control and industrial catalytic uses.
- 4Glass and optics account for approximately 31% of end-user demand in 2026, supported by glass additives and cerium-based polishing materials.
- 5Asia Pacific accounts for approximately 72% of global market value in 2026, with China at the center of mining, separation and downstream manufacturing.
Cerium is the most abundant naturally occurring rare earth element and is commonly recovered from bastnäsite and monazite alongside lanthanum, neodymium, praseodymium and other rare earths. Commercial products include cerium oxide, metallic cerium and compounds such as cerium carbonate, nitrate, chloride and sulfide.
The market covers separated cerium products and cerium-based industrial materials sold for polishing, catalysis, glass manufacturing, alloys and other industrial applications. It excludes the value of unseparated rare earth concentrates and downstream finished products such as catalytic converters, finished optical components and automotive systems in which cerium represents only one material input.
Cerium oxide is the most important commercial form because its oxygen-storage capability, chemical stability and abrasive properties make it useful in automotive catalysts, glass polishing, optical finishing and selected semiconductor chemical-mechanical planarization processes. Metallic cerium and cerium-containing alloys serve smaller metallurgical applications, with salts and other compounds used across catalysts, chemicals, pigments and specialty materials.
Supply is closely tied to the wider light rare earth industry. China Northern Rare Earth controls substantial light rare earth mining and separation capacity, and additional processing infrastructure is operating or expanding in the United States, Australia, India and Europe. Cerium's comparatively low commodity price makes efficient separation, downstream conversion and higher-specification products important to supplier economics.
Market Trends
Shift Toward Engineered Ceria
Cerium oxide is widely available as an industrial rare earth oxide, but greater value is generated through tighter control of purity, particle size, surface area and morphology. These properties determine performance in precision polishing, semiconductor CMP, advanced optics and specialized catalyst formulations.
Solvay markets high-purity cerium oxide polishing products for precision optics and semiconductor applications, while Treibacher supplies conventional cerium oxide alongside engineered Auerpol polishing materials. Chinese producers have also expanded micronized, nanoscale and application-specific grades.
Higher-value formulations give processors a way to improve revenue per tonne in a market where commodity cerium oxide carries a considerably lower unit value than magnet rare earths.
Rare Earth Supply Diversification
China controls the largest rare earth mining and separation base, but investment outside the country continues to broaden processing capacity. Lynas operates integrated mining and processing across Australia and Malaysia, MP Materials is expanding separated rare earth production in the United States, and Solvay is investing further in its La Rochelle facility in France.
Neo Performance Materials operates the Silmet rare earth separation plant in Estonia, while IREL produces separated rare earth oxides from monazite in India. These projects add alternative sources of light rare earth products and reduce reliance on a single processing geography.
Cerium availability will also rise as projects built primarily around neodymium and praseodymium generate additional light rare earth co-products.
Precision Polishing Moves Up the Value Chain
Glass polishing remains a core use for cerium oxide, but tighter surface specifications in semiconductor, optical and electronics manufacturing are pushing suppliers toward more controlled products.
Chemical-mechanical planarization requires abrasives that deliver uniform material removal with low defect rates. Solvay's Zenus range uses engineered colloidal ceria for semiconductor surface finishing, and specialist suppliers increasingly offer nanoscale cerium oxide with tightly controlled particle distributions.
These applications consume less material than conventional glass polishing but command higher values per unit because product purity and particle engineering are critical to performance.
Market Drivers
Emissions-Control Catalysts Maintain Core Demand
Cerium's ability to alternate between oxidation states allows cerium oxide to store and release oxygen, making it useful in automotive emissions-control systems. Ceria-based materials help catalytic converters maintain performance as exhaust conditions vary between oxygen-rich and fuel-rich operating states.
The same redox characteristics are useful in petroleum, chemical and environmental catalyst systems. Conventional and hybrid vehicles continue to require exhaust after-treatment, preserving a substantial automotive application base through the forecast period.
Battery-electric vehicle penetration will gradually reduce the number of new vehicles requiring catalytic converters, shifting a greater proportion of future cerium growth toward non-automotive uses.
Precision Glass and Optics Require Cerium Polishing
Cerium oxide is an established glass-polishing material because it combines mechanical abrasion with chemical interaction at the glass surface. Applications range from flat glass and mirrors to ophthalmic lenses, precision optics and electronic display surfaces.
Manufacturers requiring tighter surface tolerances use higher-specification grades with controlled particle size and purity. Treibacher serves both general glass and precision lens applications, and Solvay supplies specialized cerium products for ophthalmic and optical polishing.
Expansion in precision optics, electronics and advanced surface finishing increases the commercial value of these grades even when bulk glass-polishing volumes grow more slowly.
Additional Rare Earth Processing Expands Supply
New rare earth processing capacity adds cerium supply because it occurs naturally alongside other light rare earth elements. China retains the largest production base, and Lynas, MP Materials, IREL and European processors are adding or improving separation capabilities outside the country.
Lynas increased ready-for-sale rare earth oxide production during FY2026, and MP Materials continues expanding separated production in the United States. India is also pursuing additional rare earth mining and processing capacity around its established monazite resources.
Greater processing availability improves supply security for industrial consumers, though additional material can place pressure on commodity-grade prices if downstream consumption develops more slowly.
Market Restraints and Challenges
Abundant Supply Limits Commodity Pricing
Large bastnäsite deposits contain substantial quantities of cerium. Expansion of mining for higher-value neodymium and praseodymium therefore adds cerium supply even when cerium-specific demand is not the main investment driver.
Commodity cerium oxide trades well below neodymium, praseodymium, dysprosium and terbium products. Producers need efficient separation and sufficient downstream outlets to absorb these volumes economically.
The price environment favors processors that can convert basic oxide into polishing powders, specialized catalysts and other higher-specification products rather than depending entirely on commodity sales.
Automotive Electrification Changes the Demand Mix
Catalytic converters represent an important cerium application, but fully battery-electric vehicles do not use conventional exhaust after-treatment systems. Higher BEV penetration gradually reduces the addressable market associated with new internal-combustion vehicles.
Hybrid vehicles continue to contain combustion engines and require emissions-control systems, slowing the impact of electrification on cerium consumption. Large existing internal-combustion fleets also sustain aftermarket and replacement-related catalyst demand.
Through 2031, the commercial importance of polishing, electronics and specialty industrial applications rises as the automotive mix changes.
Segment Analysis
By Product Type: Cerium Oxide
Cerium oxide is expected to reach approximately USD 360 million by 2031, retaining the largest commercial product position.
Its combination of redox activity, thermal stability and polishing performance allows the same compound to serve catalysts, glass, precision optics and semiconductor manufacturing. Commodity grades address conventional industrial applications, and higher-purity variants command greater value in polishing and advanced catalyst formulations.
Solvay, Treibacher and numerous Chinese processors compete through differences in purity, particle engineering and application-specific performance. Metallic cerium and specialized salts retain smaller positions across metallurgy, chemicals and specialty materials.
By Mineral Type: Bastnäsite
Bastnäsite-derived cerium is forecast to account for approximately USD 300 million by 2031, making it the principal mineral source for commercial supply.
Large bastnäsite resources underpin Bayan Obo in China and Mountain Pass in the United States. These ores contain high concentrations of light rare earths, including cerium, lanthanum, neodymium and praseodymium, allowing processors to recover multiple commercial products from the same feedstock.
Monazite forms another important source, particularly in India and mineral-sand operations. IREL processes monazite-derived material and produces separated rare earth oxides at its Rare Earths Division in Aluva.
By Application: Catalyst
Catalyst applications are expected to account for approximately USD 180 million by 2031, retaining the largest individual application position.
Ceria's oxygen-storage characteristics make it valuable in automotive emissions-control systems, where catalyst efficiency must be maintained under changing exhaust conditions. Petroleum, chemical and environmental catalyst systems provide additional industrial demand.
Automotive electrification moderates expansion in conventional exhaust applications, shifting a greater portion of incremental value toward specialized catalyst formulations and non-automotive uses.
By End-User: Glass and Optics
Glass and optics are expected to account for approximately USD 150 million in cerium demand by 2031.
Cerium compounds are used both during glass production and as polishing materials during finishing. Applications extend across flat glass, mirrors, ophthalmic lenses, precision optical components and electronic displays.
The commercial mix is moving toward products with tighter purity and particle specifications. Solvay and Treibacher compete in engineered polishing materials, with specialty grades commanding substantially more value than basic cerium oxide powders.
Regional Analysis
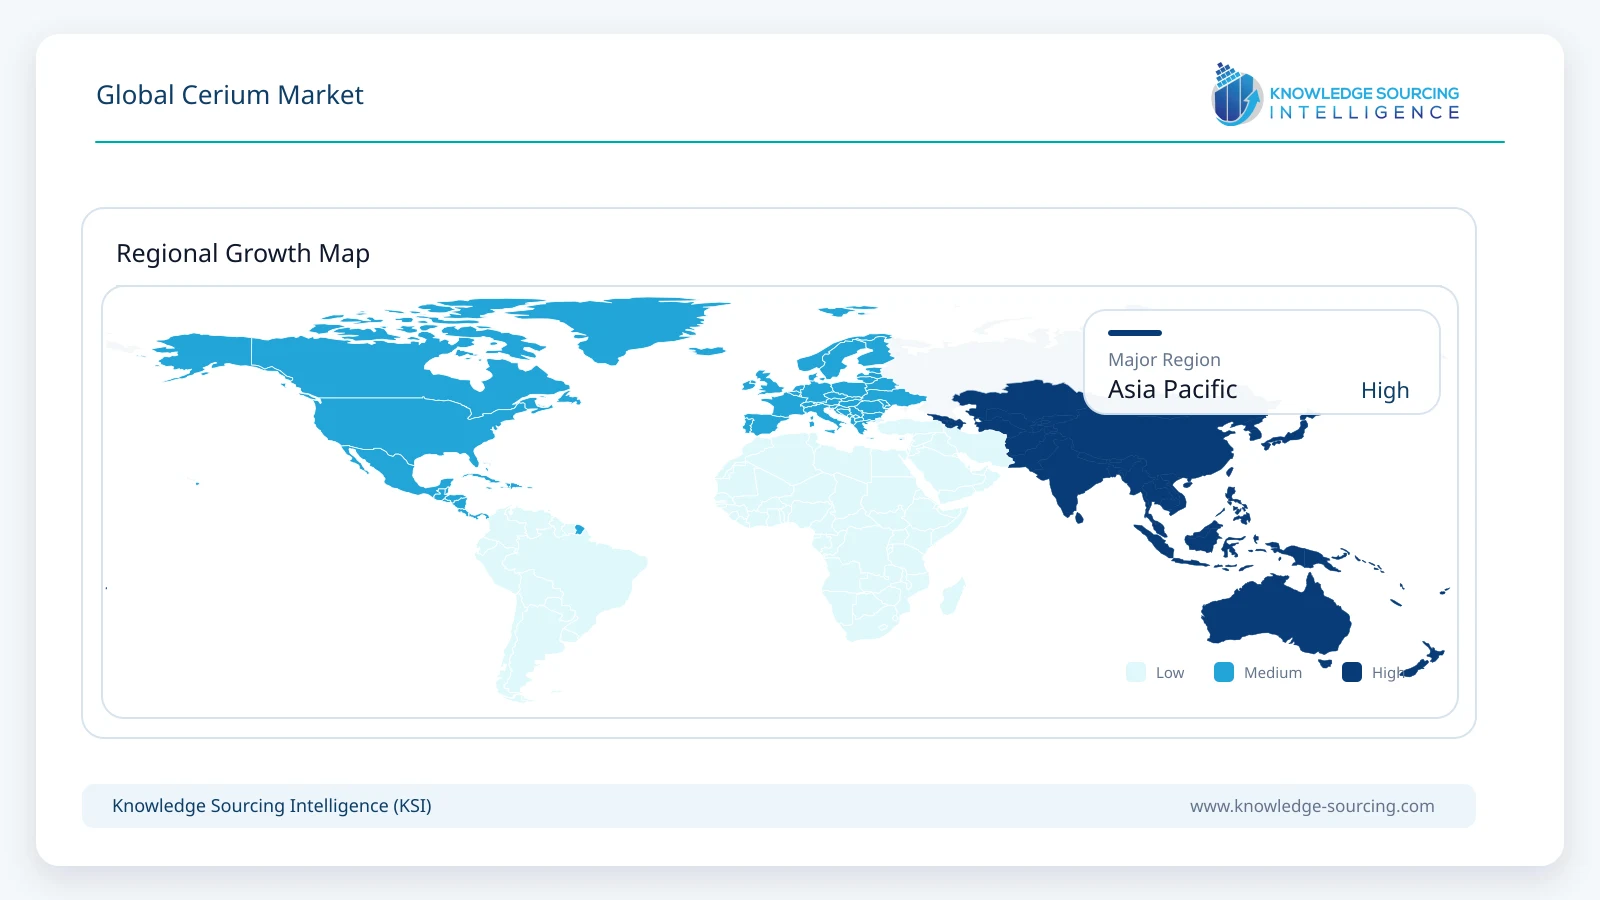
Major Region: Asia Pacific
Asia Pacific is forecast to generate approximately USD 350 million in cerium market revenue by 2031.
China combines the world's largest light rare earth mining and processing base with substantial consumption across automotive catalysts, glass, electronics, ceramics and chemical manufacturing. Japan is an important consumer of high-specification rare earth materials, and India operates an established monazite-processing industry through IREL.
The region also contains numerous specialized suppliers producing cerium oxide, polishing powders, salts and rare earth alloys, keeping much of the industry value chain concentrated in Asia.
Major Country: China
China is expected to account for approximately USD 250 million in cerium market revenue by 2031, making it the largest individual national market.
Its position is built on large light rare earth resources, extensive separation infrastructure and a substantial downstream manufacturing base. China Northern Rare Earth, China Rare Earth Group, Shenghe Resources and numerous specialty processors participate across oxides, compounds, metals and polishing materials.
Domestic demand spans automotive catalysts, glass, electronics, ceramics and chemical applications. At the same time, the volume of cerium produced alongside magnet rare earths keeps supply availability high and encourages further downstream product development.
Competitive Environment and Analysis
The global cerium market combines integrated rare earth miners and separators with specialist chemical and polishing-material suppliers. China Northern Rare Earth holds an important position through access to major light rare earth resources and large-scale separation capacity, with China Rare Earth Group and Shenghe Resources adding further depth to the country's supply chain.
Outside China, Lynas Rare Earths supplies separated light rare earth products from its Australian and Malaysian operations, MP Materials is building greater separation capability at Mountain Pass, and IREL operates India's established monazite-processing infrastructure.
Downstream competition is more fragmented. Solvay combines separation expertise with high-purity cerium oxide and colloidal ceria, Treibacher supplies industrial and precision polishing products, and Neo Performance Materials operates European separation infrastructure through Silmet.
HEFA Rare Earth Canada, Sichuan Wonaixi, Ganzhou Wanfeng, China Loong Rare Earth and other specialist suppliers compete across oxide, salt and polishing grades. Product purity, particle morphology, consistency and customer-specific formulation have greater influence on margins than basic oxide availability.
Recent Developments
September 2026: Neo Performance Materials and Carester entered a partnership covering European rare earth supply and recycling, with Neo's Silmet facility processing mixed rare earth carbonate and retaining separated light rare earth output.
August 2026: Lynas Rare Earths reported FY2026 ready-for-sale rare earth oxide production of 13,089 tonnes, up 25% year over year.
July 2026: Solvay approved an additional EUR 15-20 million investment to expand rare earth separation capacity at its La Rochelle facility in France.
May 2026: IREL inaugurated its Rare Earth and Titanium Theme Park in Bhopal, including demonstration facilities for rare earth metals such as lanthanum, cerium and neodymium.
2026: China Northern Rare Earth reported record output across major rare earth product categories during 2025 and continued supplying cerium oxide for catalysts, colorants, alloys and other industrial uses.
Market Outlook
Commercial growth over the next five years will depend more on product mix than on sharp increases in basic cerium consumption. Precision polishing, advanced optics, semiconductor CMP and specialized catalysts give processors routes to raise revenue per tonne as commodity-grade material stays readily available.
Additional rare earth separation capacity in the United States, Australia, Europe and India will broaden supply options for industrial buyers. This also places greater pressure on producers to find profitable outlets for cerium generated alongside magnet rare earths.
China will retain the largest production and consumption base through 2031. Outside the country, competitive positioning will depend on reliable feedstock access, separation economics and the ability to convert basic cerium into higher-specification industrial products.
Cerium Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 360 million |
| Total Market Size in 2031 | USD 480 million |
| Forecast Unit | Billion |
| Growth Rate | 5.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Mineral Type, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Product Type
Cerium Oxide (Ceria)
Cerium Metal
Cerium Compounds
Cerium Carbonate
Cerium Nitrate
Cerium Chloride
Cerium Sulfide and Others
By Mineral Type
Bastnäsite
Monazite
Others
By Application
Catalyst
Polishing Agent
Alloy Production
Others
By End-User
Glass & Optics
Chemicals & Petrochemical
Automotive
Aerospace
Consumer Electronics
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL CERIUM MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Cerium Oxide (Ceria)
5.3. Cerium Metal
5.4. Cerium Compounds
5.4.1. Cerium Carbonate
5.4.2. Cerium Nitrate
5.4.3. Cerium Chloride
5.4.4. Cerium Sulfide and Others
6. GLOBAL CERIUM MARKET BY MINERAL TYPE
6.1. Introduction
6.2. Bastnäsite
6.3. Monazite
6.4. Others
7. GLOBAL CERIUM MARKET BY APPLICATION
7.1. Introduction
7.2. Catalyst
7.3. Polishing Agent
7.4. Alloy Production
7.5. Others
8. GLOBAL CERIUM MARKET BY END-USER
8.1. Introduction
8.2. Glass & Optics
8.3. Chemicals & Petrochemical
8.4. Automotive
8.5. Aerospace
8.6. Consumer Electronics
8.7. Others
9. GLOBAL CERIUM MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Taiwan
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. China Northern Rare Earth (Group) High-Tech Co., Ltd.
11.2. China Rare Earth Group Co., Ltd.
11.3. Shenghe Resources Holding Co., Ltd.
11.4. Lynas Rare Earths Limited
11.5. MP Materials Corp.
11.6. Solvay SA
11.7. Neo Performance Materials Inc.
11.8. IREL (India) Limited
11.9. Treibacher Industrie AG
11.10. HEFA Rare Earth Canada Co., Ltd.
11.11. Sichuan Wonaixi New Material Technology Co., Ltd.
11.12. Ganzhou Wanfeng Advanced Materials Tech. Co., Ltd.
11.13. China Loong Rare Earth Co., Ltd.
11.14. American Elements
11.15. Sevis Materials Co., Ltd.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for the Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











