
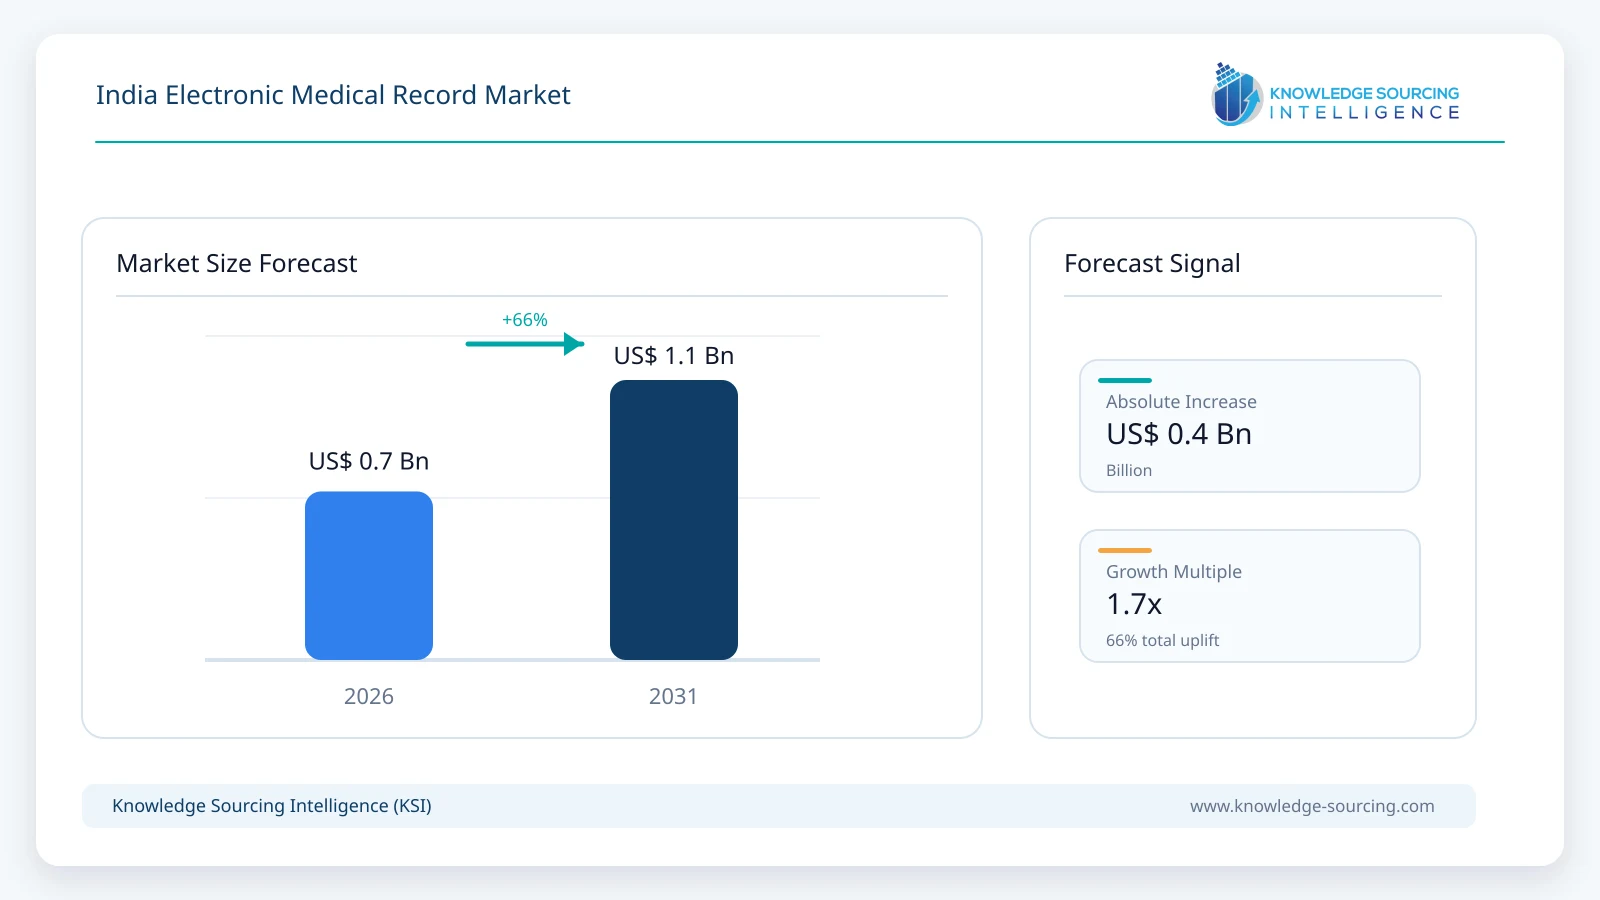
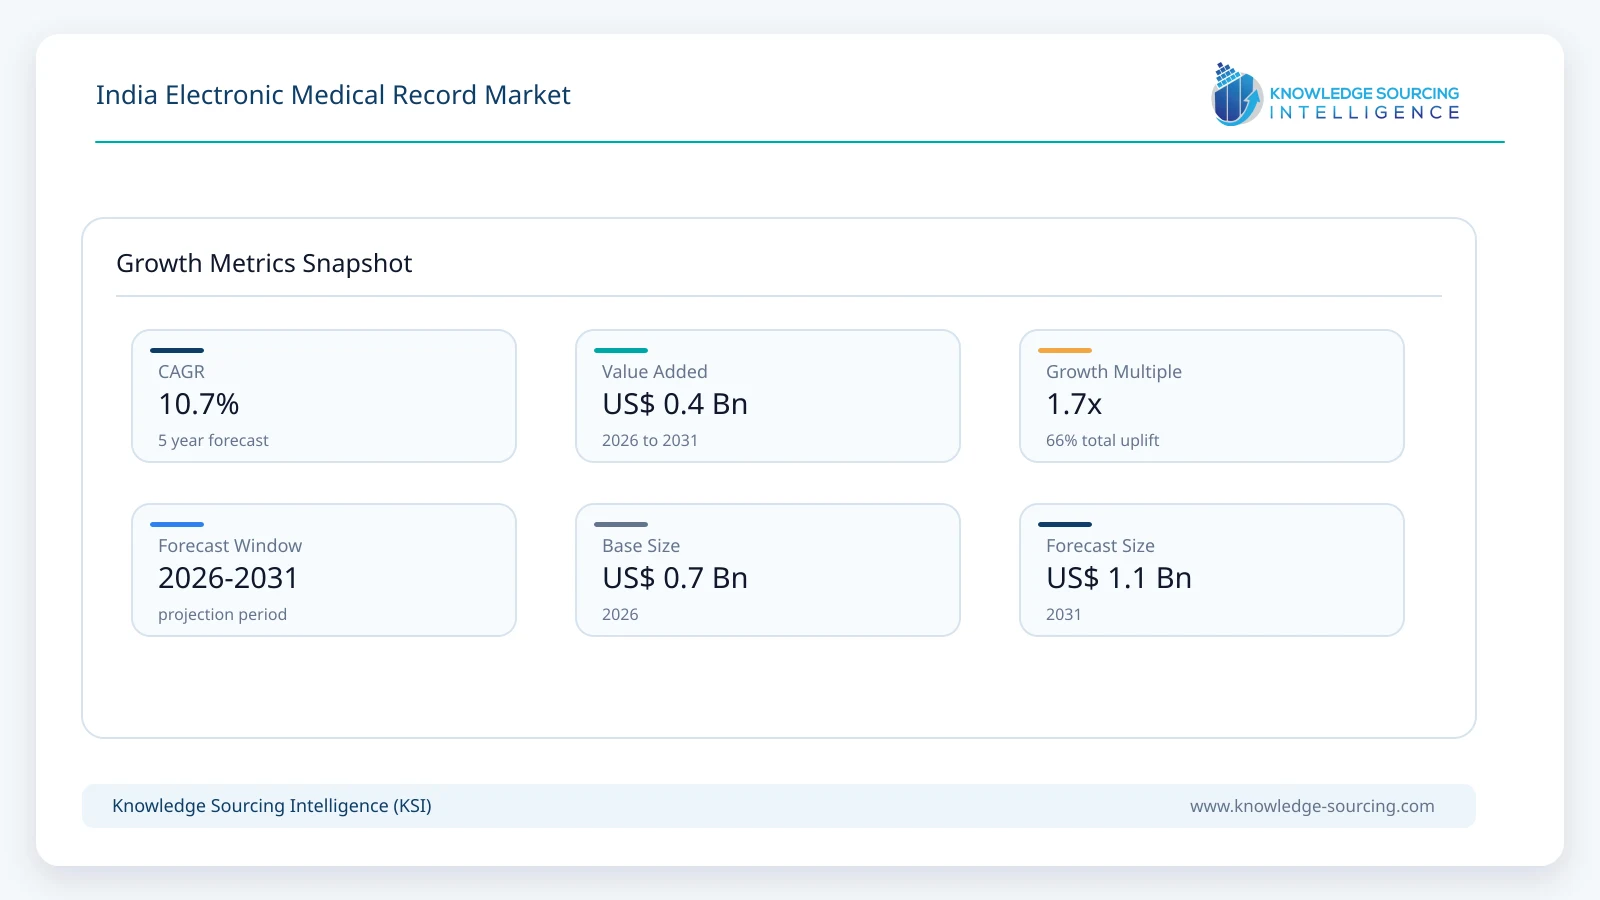
The India Electronic Medical Record Market is projected to expand at a CAGR of 10.7%, reaching USD 1.08 billion in 2031 from USD 0.65 billion in 2026.
Highlights:
- 1Cloud-based deployment accounts for approximately 74% of India EMR revenue in 2026.
- 2Software represents approximately 47% of 2026 market value, ahead of services and hardware.
- 3General EMR platforms account for approximately 69% of revenue, with specialty EMR growing faster.
- 4More than 119.95 crore health records were linked under ABDM by September 2026.
- 5Over 2.7 lakh healthcare facilities had adopted ABDM-enabled software by mid-2026.
- 6Private clinic platforms now support tens of thousands of doctors and millions of patient records.
India now has one of the world's largest digital-health infrastructures. As of September 17, 2026, more than 97.61 crore ABHA numbers were operational, more than 119.95 crore health records had been linked, over 5.78 lakh healthcare facilities were registered and more than 11 lakh healthcare professionals were on national digital registries. The commercial importance of this infrastructure lies in interoperability. EMR suppliers increasingly need to create records that can be linked to ABHA, shared through consent-based workflows and used across different provider applications. The June 2026 launch of the Unified Health Interface (UHI) further increases the value of open, standards-based systems because providers can participate in a common digital-health network rather than remain tied to a single closed application.
Public and private adoption are developing through different routes. The National Informatics Centre's eHospital platform is used by more than 1,000 health facilities, while the newer NextGen eHospital platform is being deployed as a modular, microservices-based system aligned with ABDM standards. Private providers are adopting cloud EMRs to reduce local infrastructure requirements, standardize multi-location operations and support remote access. HealthPlix reports more than 14,000 doctors and over 60 million patients on its platform, while Practo Ray is used by more than 50,000 doctors and Eka Care reports a network of more than 40,000 doctors. These platforms illustrate the depth of clinic-level digitization beyond large hospital information systems.
Selected Segment Estimates
Dimension | Selected Subsegment | 2026 Indicator | Forecast Interpretation |
Component | Software | ~47% share | Subscription and license revenue expands as cloud EMR adoption rises. |
Component | Services | ~33% share | Implementation, migration, integration and support remain material in hospitals. |
Deployment | Cloud-Based | ~74% share | Largest and fastest-growing delivery model across clinics and multi-site providers. |
Type | General EMR | ~69% share | Broad outpatient and hospital workflows retain the largest installed base. |
Type | Specialty EMR | ~31% share | Faster growth in cardiology, oncology, fertility, ophthalmology and other specialties. |
State | Maharashtra | ~21% share | Large private-hospital and clinic base supports the largest commercial revenue pool. |
Market Dynamics
ABDM Interoperability Is Turning Digital Records Into Core Provider Infrastructure
ABDM has moved beyond account creation into high-volume use. More than 100 crore health records were linked by May 2026, while adoption continued to rise through September. The commercial effect is that hospitals and clinics increasingly need systems that can create structured records, validate patient identity, support consent-based exchange and connect to national digital-health services. The launch of UHI in June 2026 strengthens this transition by creating an open network through which patients and providers can interact across different applications. EMR platforms that are ABDM compliant therefore become part of a broader service ecosystem rather than isolated repositories of clinical notes.
Cloud Delivery Is Expanding EMR Adoption Beyond Large Hospital Groups
Cloud deployment is reducing the cost and complexity of digitization for smaller hospitals, clinics and physician practices. Subscription models avoid large upfront server investments and simplify software updates, backup and multi-location access. Practo, HealthPlix, Eka Care, MocDoc, DocEngage and MediXcel all offer cloud-oriented clinical workflows, while enterprise vendors increasingly provide hosted or hybrid options for larger hospitals. This is particularly important in India because the provider base is fragmented. A scalable cloud platform can serve a single-doctor clinic and then extend to specialty groups, diagnostic partners and multi-site chains without requiring a complete local information-technology team at each location.
AI-Assisted Documentation and Specialty Workflows Increase Revenue per User
Artificial intelligence (AI) is moving into routine EMR workflows through speech-to-text documentation, clinical decision support, automated coding, medication checks and structured extraction from conversations. HealthPlix is deploying AI-assisted functionality within a platform that handles more than 1.5 lakh consultations each day, while Napier offers voice-driven EMR documentation and Eka Care is positioning AI-supported clinical documentation for digital hospitals. These capabilities can improve physician adoption because documentation burden remains one of the main practical barriers to EMR use. Specialty templates also increase willingness to pay where generic systems cannot adequately capture procedure, diagnosis or longitudinal treatment requirements.
Market Restraints
Fragmented Provider Economics Limit Uniform Commercial Adoption
India's healthcare provider base ranges from large corporate hospital chains to small nursing homes and individual practices. The economic case for a full-featured EMR therefore varies widely. Large hospitals can justify integration, cybersecurity, analytics and clinical decision-support modules, while smaller providers may prefer low-cost subscription software or continue using limited digital tools alongside paper records. Public-sector digitization also does not translate directly into commercial software revenue because government-developed platforms and centrally funded systems can reduce the addressable opportunity for private vendors in some facilities. Vendors need modular pricing and low implementation friction to expand outside large urban hospitals.
Data Migration, Workflow Change and Cybersecurity Raise Implementation Complexity
EMR implementation affects clinical, administrative and financial workflows at the same time. Hospitals migrating from legacy systems must clean and map historical data, integrate laboratory and radiology systems, configure specialty templates and train doctors, nurses and support staff. Interoperability improves exchange but also increases the importance of consent management, authentication, audit trails and cybersecurity. Providers are increasingly sensitive to downtime and data-loss risk because the EMR becomes operationally critical once paper processes are removed. These requirements support service revenue but can lengthen implementation cycles and delay purchasing decisions.
Segment Analysis
By Component - Software
Software is the largest component of the India EMR market, accounting for approximately 47% of 2026 revenue. The category includes core clinical documentation, prescription management, patient history, specialty templates, scheduling, billing integration, dashboards and interoperability functions. Subscription revenue is increasing as cloud-based products replace perpetual licenses in smaller and mid-sized providers. Hardware remains necessary for servers, terminals, tablets, scanners and local infrastructure in some deployments, but its share gradually declines as hosted delivery becomes more common. Services remain a substantial category because hospital implementations require configuration, migration, interface development, training and long-term support.
By Type - General EMR
General EMR platforms account for approximately 69% of market revenue in 2026 because most hospitals and multispecialty clinics require common workflows for consultation notes, prescriptions, investigations, referrals and longitudinal patient records. Specialty EMR is smaller but grows faster as providers seek disease-specific templates, structured scoring, procedure documentation and specialty analytics. Cardiology, oncology, fertility, ophthalmology, gastroenterology and endocrinology are among the areas where specialized clinical workflows can materially improve physician usability. Vendors increasingly combine a general platform with configurable specialty modules rather than operating separate software stacks.
By Deployment - Cloud-Based
Cloud-based systems account for approximately 74% of market revenue in 2026. Their advantage is strongest among outpatient clinics, diagnostic networks and growing hospital groups that need rapid deployment across multiple locations. Cloud delivery also supports mobile access, centralized updates and easier ABDM connectivity. On-premise systems retain a role in large hospitals with legacy infrastructure, strict internal-control policies or extensive integration requirements. Hybrid architectures remain common where clinical applications are hosted centrally but imaging, laboratory or other high-volume systems remain on local infrastructure.
Technology and Demand Indicators
Indicator | Latest Development | Market Impact |
ABDM records | 119.95 crore health records linked by September 17, 2026. | Raises demand for interoperable EMR creation and exchange. |
Facility adoption | More than 2.7 lakh facilities used ABDM-enabled software by mid-2026. | Expands the practical installed base for standards-compliant systems. |
Digital OPD | Scan and Register crossed 25 crore registrations across 30,800 facilities in August 2026. | Normalizes digital patient identity and front-desk workflows. |
Public hospital IT | NIC eHospital serves 1,000+ facilities; NextGen eHospital adds modular EHR capability. | Sustains public-sector digital hospital adoption and standards usage. |
Private clinic scale | HealthPlix supports 14,000+ doctors; Practo Ray reports 50,000+ doctors. | Demonstrates large commercial demand beyond hospital chains. |
Maharashtra Market Analysis
Maharashtra is the largest commercial state market in this report, accounting for approximately 21% of India EMR revenue in 2026. Mumbai, Pune, Nagpur and other urban centres combine large private hospital networks, diagnostic chains, specialty practices and a strong healthcare technology ecosystem. The state also has a large base of corporate healthcare providers that require enterprise-grade integration across inpatient, outpatient, pharmacy, laboratory, radiology and revenue-cycle systems. These customers generate higher software and service revenue per facility than small standalone clinics, supporting Maharashtra's leading value share even though national digital-health adoption is geographically broad.
The state also benefits from a strong technology and software services base in Mumbai and Pune, making implementation, cloud support and healthcare-data integration more accessible. Growth through 2031 is expected to come from replacement of fragmented legacy systems, multi-hospital standardization, cloud migration and specialty digitization rather than simple conversion from paper records alone. Smaller cities provide an additional adoption pool as subscription-based clinic software becomes easier to implement and as ABDM-linked workflows become more common in routine care.
Competitive Landscape
The India EMR market combines domestic cloud-native platforms, hospital information-system vendors, multinational healthcare-technology companies and government-supported open systems. HealthPlix, Practo and Eka Care have built large physician-facing networks, while MocDoc, KareXpert, DocEngage, MediXcel and SoftClinic compete across clinics and hospitals. Oracle Health, Philips and other global vendors remain relevant in larger enterprise environments. Open-source Bahmni also has an important role in lower-resource hospital settings and is supported by an implementation ecosystem that includes Indian technology partners.
Competitive differentiation is moving from basic digitization toward physician usability, specialty depth, interoperability and automation. Platforms that reduce documentation time, support ABHA-linked records, integrate diagnostics and billing, and provide reliable mobile access are better positioned to retain clinicians. Scale also matters because larger networks generate data that can support analytics, clinical decision tools and real-world evidence services. At the same time, buyers increasingly evaluate data security, uptime, migration support and the ability to avoid vendor lock-in when connecting multiple hospital systems.
Recent Developments
September 2026: ABDM reported more than 97.61 crore operational ABHA numbers and over 119.95 crore linked health records.
August 2026: ABHA-based Scan and Register crossed 25 crore outpatient registrations across 30,800 healthcare facilities.
July 2026: ABDM registries reached 5.36 lakh healthcare facilities and 10.09 lakh healthcare professionals.
June 2026: The National Health Authority launched the Unified Health Interface as an interoperable network for digital health services.
June 2026: Aarogya Setu 2.0 was launched as a citizen-facing national health application with personal health record functionality.
May 2026: ABDM crossed 100 crore linked health records, doubling the linked-record base in approximately 15 months.
India Electronic Medical Record Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.65 billion |
| Total Market Size in 2031 | USD 1.08 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Type, Deployment Model, State |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
Hardware
Software
Services
By Type
General EMR
Specialty EMR
By Deployment Model
Cloud-Based
On-Premise
By State
Delhi
Karnataka
Maharashtra
Gujarat
Tamil Nadu
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. ABDM Interoperability Is Turning Digital Records Into Core Provider Infrastructure
3.1.2. Cloud Delivery Is Expanding EMR Adoption Beyond Large Hospital Groups
3.1.3. AI-Assisted Documentation and Specialty Workflows Increase Revenue per User
3.2. Market Restraints
3.2.1. Fragmented Provider Economics Limit Uniform Commercial Adoption
3.2.2. Data Migration, Workflow Change and Cybersecurity Raise Implementation Complexity
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Digital Health and Data-Interoperability Landscape
4. TECHNOLOGICAL OUTLOOK
4.1. Cloud-Native EMR Architecture
4.2. ABDM and FHIR-Based Interoperability
4.3. AI-Assisted Clinical Documentation
4.4. Clinical Decision Support
4.5. Mobile EMR and Remote Access
4.6. Cybersecurity and Consent Management
5. INDIA ELECTRONIC MEDICAL RECORD MARKET BY COMPONENT
5.1. Hardware
5.2. Software
5.3. Services
6. INDIA ELECTRONIC MEDICAL RECORD MARKET BY TYPE
6.1. General EMR
6.2. Specialty EMR
7. INDIA ELECTRONIC MEDICAL RECORD MARKET BY DEPLOYMENT MODEL
7.1. Cloud-Based
7.2. On-Premise
8. INDIA ELECTRONIC MEDICAL RECORD MARKET BY STATE
8.1. Delhi
8.2. Karnataka
8.3. Maharashtra
8.4. Gujarat
8.5. Tamil Nadu
8.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Partnerships, Investments and Product Development
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. HealthPlix Technologies Pvt. Ltd.
10.2. Practo Technologies Pvt. Ltd.
10.3. Eka Care
10.4. Oracle Health
10.5. Philips India Limited
10.6. KareXpert Technologies Pvt. Ltd.
10.7. MocDoc
10.8. DocEngage Informatics Pvt. Ltd.
10.9. Plus91 Technologies
10.10. JVS Group
10.11. Napier Healthcare
10.12. eClinicalWorks
10.13. Nuchange Informatics
10.14. Bahmni Coalition
10.15. MyHealthcare Technologies
11. RECENT DEVELOPMENTS
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Research Methodology
12.5. Abbreviations





Frequently asked questions
What is the projected market size of India's EMR market by 2031?
India's EMR market is projected to reach USD 1.08 billion by 2031.
What is the compound annual growth rate (CAGR) for the India EMR market?
The India Electronic Medical Record Market is projected to expand at a 10.7% CAGR (2026-2031).
Which deployment model dominates the India EMR market?
Cloud-based deployment accounts for approximately 74% of EMR revenue in 2026.
Which component holds the largest share in the India EMR market?
Software represents approximately 47% of the 2026 market value.
How does ABDM impact the India Electronic Medical Record market?
ABDM enables health record linking and facility adoption across India.
What role does the Unified Health Interface (UHI) play in India EMR?
UHI increases value of open, standards-based EMR systems.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). India Electronic Medical Record Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/india-emr-electronic-medical-record-market