
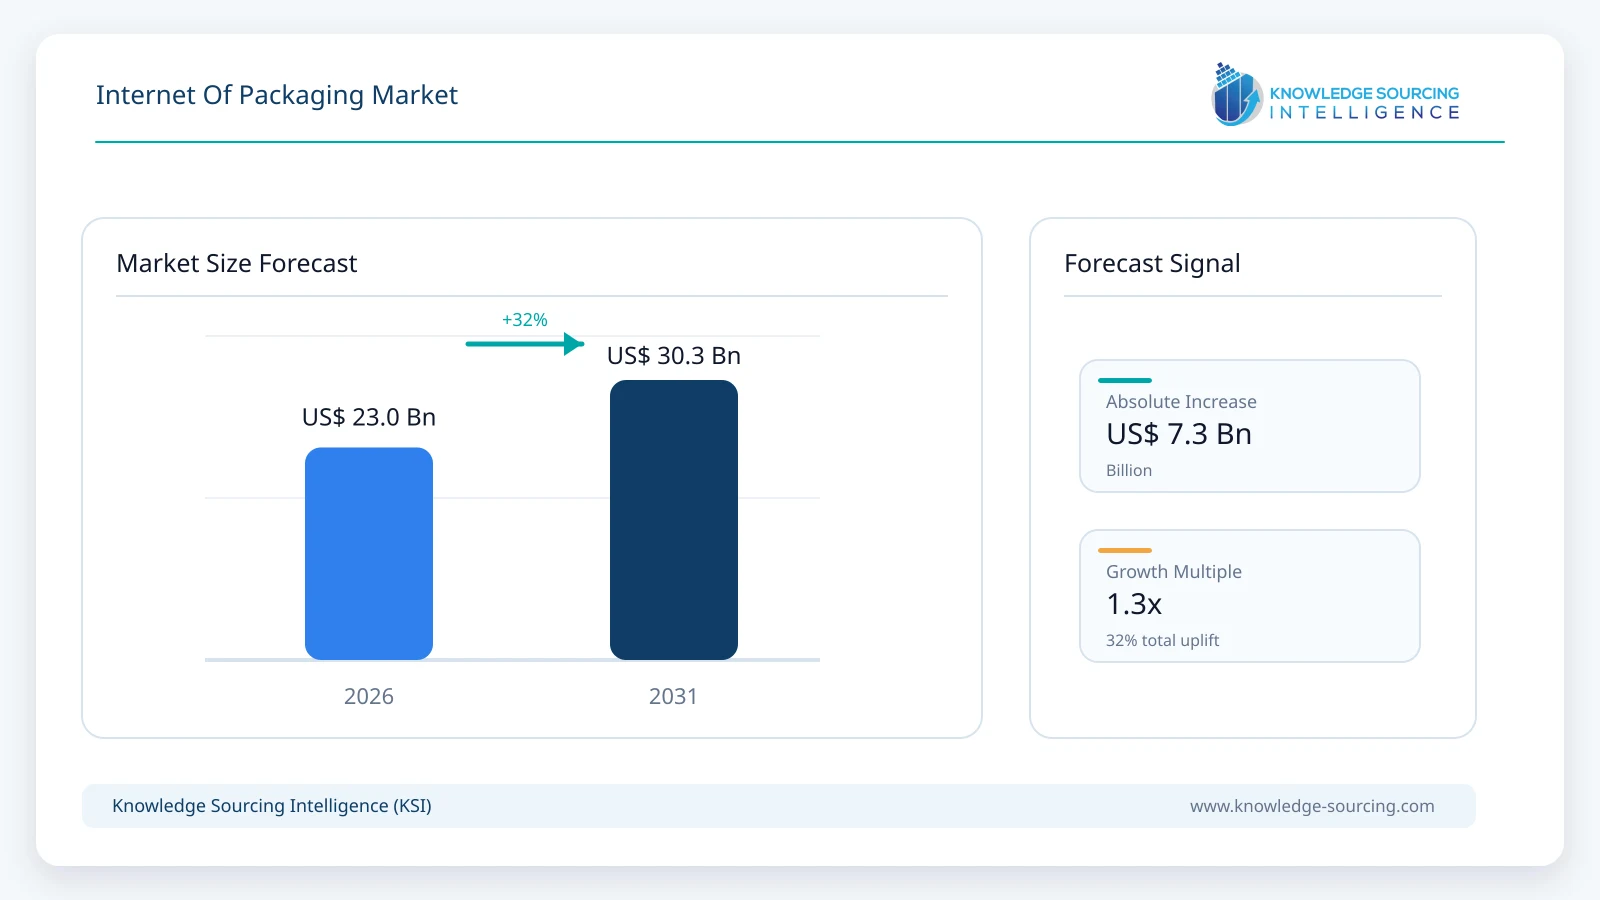
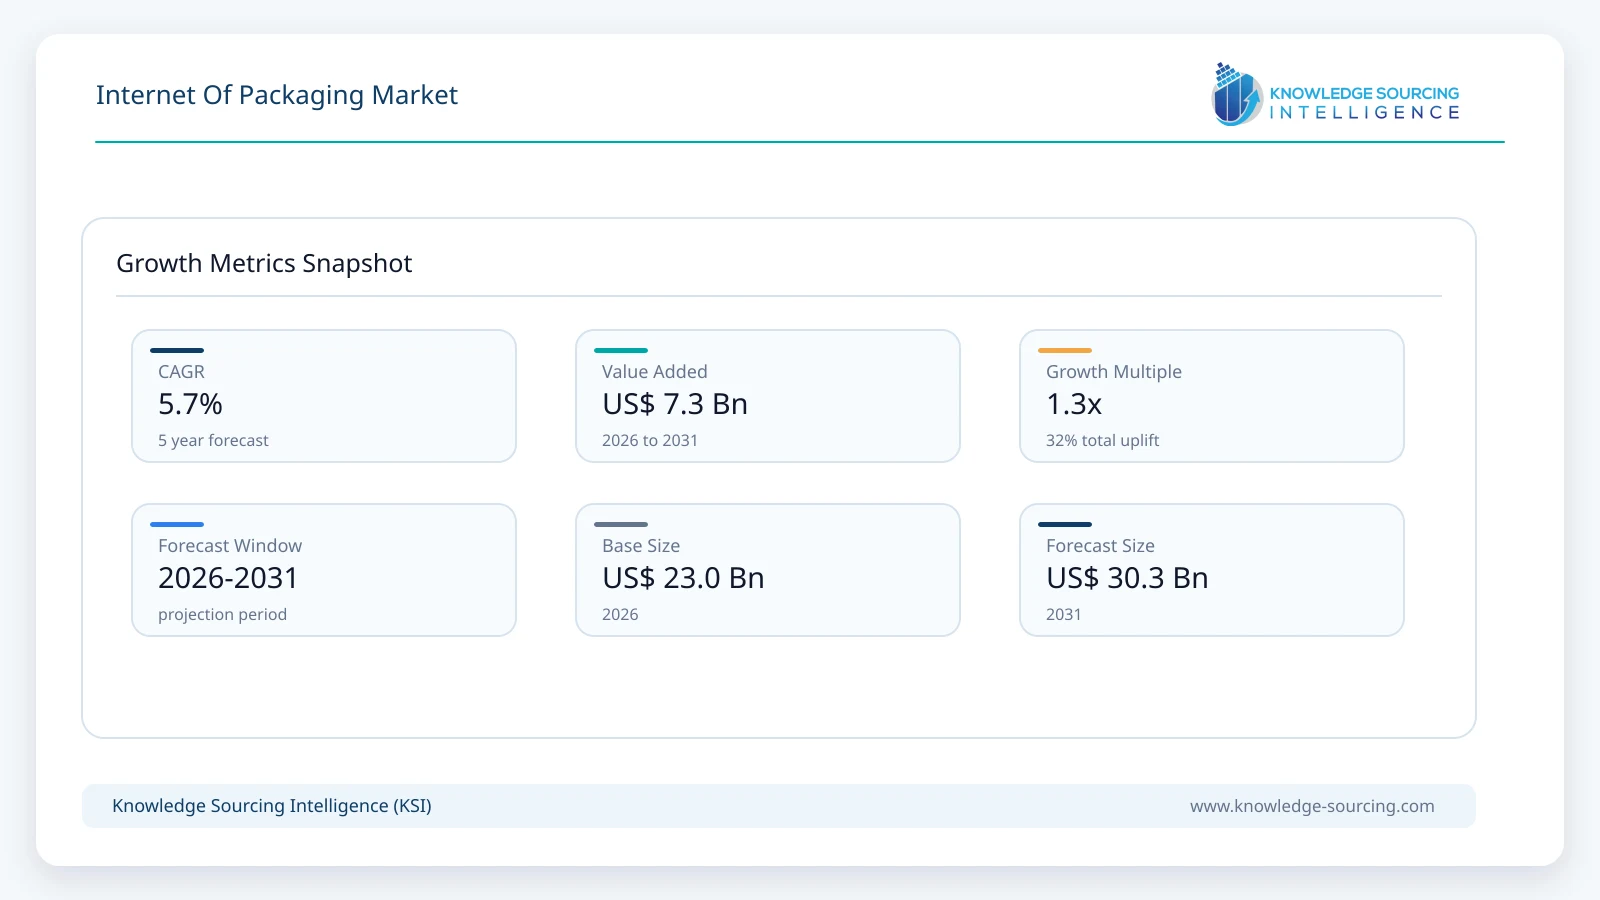
The internet of packaging market is forecast to grow at a CAGR of 5.7%, reaching USD 30.3 billion in 2031 from USD 23.0 billion in 2026.
Highlights:
- 1Barcode and QR-code technologies account for approximately 43% of market value in 2026, supported by low implementation cost, smartphone compatibility and the migration toward GS1-enabled 2D barcodes.
- 2Boxes and cartons account for approximately 29% of market value by packaging type in 2026, reflecting their extensive use across packaged food, consumer goods, pharmaceuticals and e-commerce.
- 3Food and beverages account for approximately 31% of market demand in 2026, supported by traceability, freshness management, recall control and consumer-information requirements.
- 4North America accounts for approximately one-third of market value in 2026, while Asia Pacific is close behind and benefits from substantially larger packaged-product volumes.
- 5RFID, NFC, BLE and sensor-enabled labels grow faster than basic barcode applications through 2031, as more packaging moves from identification toward real-time visibility and condition monitoring.
The internet of packaging market covers technologies and associated software used to give physical packaging a digital identity or communications capability. The scope includes QR codes and GS1 Digital Link, RFID and smart labels, NFC, Bluetooth Low Energy, sensors, indicators, digital watermarks and related connected-product platforms where the technology is embedded in or directly associated with packaging. Conventional packaging without a digital or connected function is excluded.
The market estimate remains commercially reasonable. Independent market references place the 2026 market broadly around USD 22-23 billion, while identifiable supplier activity demonstrates a substantial established commercial base. Avery Dennison reported approximately USD 0.9 billion in enterprise-wide Intelligent Labels sales during 2025, with the platform spanning apparel, general retail, food and logistics. Impinj generated USD 361.1 million in 2025 revenue from its RAIN RFID ecosystem and increased endpoint IC volumes by 9%. Avery Dennison’s Intelligent Labels platform also recorded approximately 10% growth during 2025 in food, logistics and other emerging categories, offsetting softer conditions elsewhere.
The addressable market is considerably broader than RFID alone. GS1 reports that more than one billion products already carry GS1 barcodes and that these codes are scanned billions of times each day. The industry’s Ambition 2027 initiative aims for retail point-of-sale systems globally to be capable of reading GS1-compatible 2D barcodes by the end of 2027. Companies are already testing next-generation barcodes in more than 45 countries representing approximately 85% of global GDP.
Market Trends
• Packaging Is Becoming a Persistent Digital Identity for the Product
Traditional barcodes primarily identify a stock-keeping unit. Connected packaging increasingly links the individual package or product to digital information that can be updated throughout its lifecycle. QR Codes with GS1 Digital Link can combine GTIN identification with batch, lot and expiration data while linking consumers to product information, ingredients, sustainability instructions, promotions and other online content.
GS1’s 2027 transition is important because it integrates consumer engagement and operational identification in the same data carrier. Instead of maintaining a conventional UPC/EAN barcode for checkout and a separate QR code for consumer interaction, brands can progressively use GS1-enabled 2D codes to support both functions. GS1’s July 2026 guidance for private-label products reinforces the move toward a single standards-based 2D code as retail systems become capable of processing it.
• RFID Is Expanding Beyond Apparel Into Food and Packaging Applications
RAIN RFID adoption developed first at scale in apparel and general merchandise, where item-level identification could improve inventory accuracy. Food and grocery are emerging as a larger connected-packaging opportunity because RFID can link individual packages with expiry dates, lot numbers and inventory information without requiring line-of-sight scanning.
Avery Dennison launched its AD IdentiFresh inlay series in February 2026 for bakery, meat, deli and produce applications. The technology uses Impinj M800-series chips and is designed to improve RFID performance in cold, moist and densely packed fresh-food environments where traditional RFID has historically faced limitations. Avery Dennison subsequently indicated that a rollout at a major U.S. grocery retailer was expected to begin during the second half of 2026.
• Smart Labels Are Moving Toward Continuous, Scan-Free Visibility
Barcode and conventional RFID applications generally require a user or fixed reader to initiate the interaction. Ambient IoT technologies are extending packaging into continuous condition and location monitoring. Wiliot’s battery-free Bluetooth IoT Pixels, for example, can transmit product or package information to nearby infrastructure without conventional manual scanning.
Wiliot reported in 2026 that more than one billion assets had been tagged using its technology. The company is targeting food and beverage, retail, parcel, logistics and reusable-asset applications where users require visibility into location, temperature, shrink, mis-ship and spoilage. This represents a higher-value layer of connected packaging than static identification alone.
• Connected Packaging Must Increasingly Be Compatible With Recycling Systems
Adding antennas, chips, adhesives and batteries to packaging can conflict with recyclability objectives. Technology suppliers are therefore redesigning smart labels so the connectivity layer does not undermine material recovery.
In July 2026, Avery Dennison’s AD CleanFlake RFID tags received RecyClass Technology Approval for PET bottle recycling in Europe after previously receiving APR Design Recognition in North America. The company describes the solution as the first RFID construction recognized in both major regional frameworks for compatibility with rigid PET mechanical recycling. This development is commercially important because smart packaging adoption will increasingly depend on digital functionality and recyclability being designed together.
Market Drivers
• The Global Transition to 2D Barcodes
GS1’s Ambition 2027 is one of the clearest identifiable demand catalysts in the market. The initiative targets global retail POS capability for processing GS1-compatible 2D barcodes by the end of 2027. Retailers must upgrade scanners and software while manufacturers need barcode-generation, printing and product-data systems capable of supporting the new standards.
This creates a transition affecting retailers, packaging converters, brand owners, printer manufacturers, scanner companies and connected-product software providers rather than a single packaging-material category.
• Item-Level Supply-Chain Visibility Is Expanding Beyond Apparel
Avery Dennison’s approximately USD 0.9 billion Intelligent Labels platform and Impinj’s more than USD 360 million annual revenue demonstrate that item-level connectivity is already commercially substantial. Avery Dennison expects intelligent-label sales to remain a long-term growth engine and has invested in additional manufacturing capacity, including a new RFID inlay and label production site in India.
Growth increasingly comes from food, logistics, pharmaceuticals and other non-apparel applications, expanding the addressable packaging market.
• Traceability, Authentication and Consumer Transparency
Connected packaging provides a method to connect the physical package with production, origin, batch, authenticity and sustainability data. This is particularly valuable in pharmaceuticals, premium goods and food, where counterfeit products, recalls or incorrect handling can have significant financial or safety consequences.
Digital watermarks provide another data-carrier option. Digimarc embeds machine-readable information directly into packaging artwork and markets the technology for product authenticity, manufacturing quality control, recycling and consumer engagement.
Market Restraints
• Unit Economics Limit Advanced Connectivity on Low-Value Products
A QR code can be printed at negligible incremental cost, but RFID, NFC, BLE and sensor technologies add chips, antennas, converting, readers, gateways and software infrastructure. The economics are therefore easiest to justify in high-value products or applications where inventory, waste, labor or authenticity benefits produce measurable returns.
This limits the speed at which advanced smart labels can penetrate extremely low-value consumer packages even when technical functionality is attractive.
• Fragmented Technology and Infrastructure Requirements Slow Adoption
Connected packaging includes optical codes, UHF RFID, NFC, BLE, sensors and digital watermarks, each requiring different readers and backend systems. Retailers and manufacturers may therefore face integration complexity when implementing solutions across multiple countries, packaging formats and supply-chain partners.
GS1 standardization reduces this constraint for 2D codes, but more advanced connectivity still depends on ecosystem coordination between semiconductor providers, label converters, packaging companies, readers, software providers and end users.
Segment Analysis
• By Technology: Barcode and QR Code
Barcode and QR-code technologies account for approximately 43% of market value in 2026 and remain the largest technology group. Their leading position reflects extremely broad packaging applicability, low unit cost and the ability to interact directly with smartphones without dedicated reading hardware.
The segment is changing from basic product identification toward data-rich 2D codes. GS1 Digital Link enables QR codes to contain or connect with GTINs, expiration dates, batch data and web-based product information. GS1 expects significant global uptake by 2027, with pilots already underway across major developed and emerging markets. This migration expands the commercial value around code creation, printing, serialization, data management and connected-product software even though the physical QR code itself is inexpensive.
RFID represents a smaller but higher-value technology segment because tags require semiconductors, antennas, converting and reader infrastructure. NFC, BLE and sensor technologies remain smaller in unit volume but generate higher value per connected package and are expected to grow faster through 2031.
• By Packaging Type: Boxes and Cartons
Boxes and cartons account for approximately 29% of market value in 2026 and remain the largest packaging-format category. Their large printable surface makes them suitable for QR codes, RFID labels, serialized identifiers and digital watermarks, while widespread use in food, pharmaceuticals, consumer goods and e-commerce provides substantial application volume.
Bottles and jars form another important category as beverage, personal-care and pharmaceutical companies use QR codes, NFC and RFID for authentication, traceability and consumer interaction. Flexible packaging, pouches and films represent a growing opportunity as converters improve methods for incorporating connected labels without compromising packaging performance or recyclability.
• By End User: Food and Beverages
Food and beverages account for approximately 31% of market value in 2026. Connected packaging can address multiple commercially measurable problems within the same application: inventory visibility, expiration management, cold-chain monitoring, recall efficiency, waste reduction and consumer product information.
Avery Dennison’s 2026 food-focused RFID expansion and Wiliot’s activity in food supply chains illustrate the increasing commercial maturity of the segment. Food applications are particularly attractive because high product volumes can support substantial connected-label demand once technology reaches an acceptable unit cost.
Healthcare is a smaller current segment but has higher requirements for serialization, authenticity, chain of custody and condition monitoring. Personal care, luxury goods, consumer electronics and automotive parts provide additional opportunities where product authentication and consumer engagement justify higher-value connected packaging.
Regional Outlook
• North America
North America accounts for approximately 33% of global market value in 2026, narrowly ahead of Asia Pacific in the internal market model. The region’s share is supported by high-value RFID adoption, large retail and consumer-goods markets, advanced logistics infrastructure and significant activity from Avery Dennison, Impinj, Digimarc and Wiliot.
Avery Dennison expected a major U.S. grocery RFID rollout to begin during the second half of 2026, illustrating movement of item-level intelligence into extremely high-volume packaging categories.
Asia Pacific remains close to North America because of its substantially larger manufacturing and packaged-goods volumes. China is particularly important to the transition toward 2D barcodes; GS1 has previously reported thousands of manufacturers and retailers participating in food-industry 2D initiatives in Zhejiang province. Europe remains a major market through food traceability, pharmaceutical serialization, connected consumer products and packaging circularity requirements.
Competitive Landscape
The market combines digital-identification companies, semiconductor suppliers, packaging and label converters, connected-product software companies and specialized smart-packaging technology providers.
Avery Dennison has one of the largest identifiable connected-label businesses, with enterprise-wide Intelligent Labels sales of approximately USD 0.9 billion in 2025. Its portfolio spans UHF RFID, NFC, food traceability and associated digital-identification solutions.
Impinj supplies RAIN RFID chips, readers and associated platform technology and generated USD 361.1 million of revenue in 2025. Its endpoint ICs are used within packaging and smart labels supplied by companies including Avery Dennison.
Zebra Technologies provides RFID, barcode scanning and printing infrastructure. Digimarc provides digital-watermark-based product identification and authentication. Wiliot participates through battery-free Bluetooth Ambient IoT labels and cloud intelligence.
Other relevant companies include Tageos, Identiv, SATO Holdings, CCL Industries, Checkpoint Systems and Toppan. Packaging groups such as Amcor and Smurfit Westrock also participate in connected-packaging projects but should be distinguished from the technology providers whose revenue is more directly tied to digital identification.
Recent Developments
September 2026: Avery Dennison launched its AD Visi range of active Bluetooth Low Energy labels for time-critical and high-value shipments, extending its portfolio beyond passive RFID.
August 2026: Avery Dennison launched AD Fusion, enabling label converters to use materials with pre-inserted RFID inlays without installing dedicated inlay-insertion equipment.
August 2026: Wiliot and CISC announced a partnership to support high-volume production and quality assurance for battery-free IoT Pixels; Wiliot stated that more than one billion assets had been tagged globally.
July 2026: Avery Dennison’s AD CleanFlake RFID tags received RecyClass Technology Approval for PET bottle recycling in Europe.
February 2026: Avery Dennison launched AD IdentiFresh RFID inlays for bakery, meat, deli and produce applications using Impinj M800-series ICs.
Market Outlook
The Internet of packaging market is forecast to increase. The forecast reflects a market in which low-cost 2D codes create extremely broad adoption while higher-value technologies such as RFID, BLE, NFC and sensors expand more rapidly from smaller installed bases.
Barcode and QR-code applications remain the largest technology group through 2031 because GS1’s global 2D transition substantially increases the number of packages capable of linking physical products with structured digital information. RFID expands further into grocery, logistics and pharmaceutical applications, while BLE and Ambient IoT create a higher-value layer for continuous visibility and condition monitoring.
The market is therefore evolving from “smart packaging” as an isolated premium feature toward a broader digital-identity architecture for physical goods. The most important commercial opportunities increasingly lie in the combination of data carriers, standardized product identity, cloud software and measurable supply-chain outcomes rather than in the packaging substrate alone.
Internet of Packaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 23.0 billion |
| Total Market Size in 2031 | USD 30.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Packaging Type, End User, Geography |
| Companies |
|
Market Segmentation
By Technology
Barcode and QR Code
RFID
NFC
Bluetooth Low Energy
Sensors and Tags
Indicators and Digital Watermarks
Others
By Packaging Type
Boxes and Cartons
Bottles and Jars
Films and Wraps
Pouches and Bags
Blisters and Pharmaceutical Packaging
Mailers and E-Commerce Packaging
Others
By End User
Food and Beverages
Healthcare and Pharmaceuticals
Personal Care and Cosmetics
Retail and Consumer Goods
Automotive and Industrial
Consumer Electronics
Logistics and E-Commerce
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Revenue Boundary
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Connected-Packaging Supplier Revenue Analysis
2.5. Smart-Label and Data-Carrier Volume Modelling
2.6. Segment Modelling
2.7. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Internet of Packaging Market Size, 2026-2031
3.3. Technology Outlook
3.4. Packaging Type Outlook
3.5. End-User Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Global Transition Toward GS1-Enabled 2D Barcodes
4.1.2. Expansion of Item-Level Supply-Chain Visibility
4.1.3. Traceability, Authentication and Consumer Transparency
4.2. Market Restraints
4.2.1. Unit Economics of Advanced Smart Labels
4.2.2. Fragmented Technology and Infrastructure Requirements
4.3. Market Opportunities
4.4. Industry Value Chain Analysis
4.5. Connected-Packaging Economics
4.6. Packaging Sustainability and Recycling Compatibility
4.7. Standards and Regulatory Environment
5. TECHNOLOGY OUTLOOK
5.1. GS1 Digital Link and 2D Barcodes
5.2. RAIN RFID and Smart Labels
5.3. Near Field Communication
5.4. Bluetooth Low Energy and Ambient IoT
5.5. Sensors and Condition Indicators
5.6. Digital Watermarks
6. INTERNET OF PACKAGING MARKET BY TECHNOLOGY
6.1. Barcode and QR Code
6.2. RFID
6.3. NFC
6.4. Bluetooth Low Energy
6.5. Sensors and Tags
6.6. Indicators and Digital Watermarks
6.7. Others
7. INTERNET OF PACKAGING MARKET BY PACKAGING TYPE
7.1. Boxes and Cartons
7.2. Bottles and Jars
7.3. Films and Wraps
7.4. Pouches and Bags
7.5. Blisters and Pharmaceutical Packaging
7.6. Mailers and E-Commerce Packaging
7.7. Others
8. INTERNET OF PACKAGING MARKET BY END USER
8.1. Food and Beverages
8.2. Healthcare and Pharmaceuticals
8.3. Personal Care and Cosmetics
8.4. Retail and Consumer Goods
8.5. Automotive and Industrial
8.6. Consumer Electronics
8.7. Logistics and E-Commerce
8.8. Others
9. INTERNET OF PACKAGING MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Australia
9.5.6. Indonesia
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. QR Code and Digital Identity Positioning
10.3. RFID and Smart-Label Capabilities
10.4. NFC, BLE and Ambient IoT Positioning
10.5. Connected-Product Software and Data Platforms
10.6. Packaging Converter and Technology Partnerships
10.7. Sustainability and Recycling Compatibility
10.8. Competitive Dashboard
11. COMPANY PROFILES
11.1. Avery Dennison Corporation
11.2. Impinj, Inc.
11.3. Zebra Technologies Corporation
11.4. Digimarc Corporation
11.5. Wiliot
11.6. Tageos
11.7. Identiv, Inc.
11.8. SATO Holdings Corporation
11.9. CCL Industries Inc.
11.10. Checkpoint Systems
12. APPENDIX
12.1. Market Definition and Revenue Boundary
12.2. Connected Packaging Technology Definitions
12.3. Currency and Conversion Assumptions
12.4. Base Year and Forecast Period
12.5. Market Estimation Approach
12.6. Primary and Secondary Research Framework
12.7. Segment Reconciliation
12.8. Data Triangulation and Validation
12.9. Abbreviations
Navigate
Trusted by the world's leading organizations











