
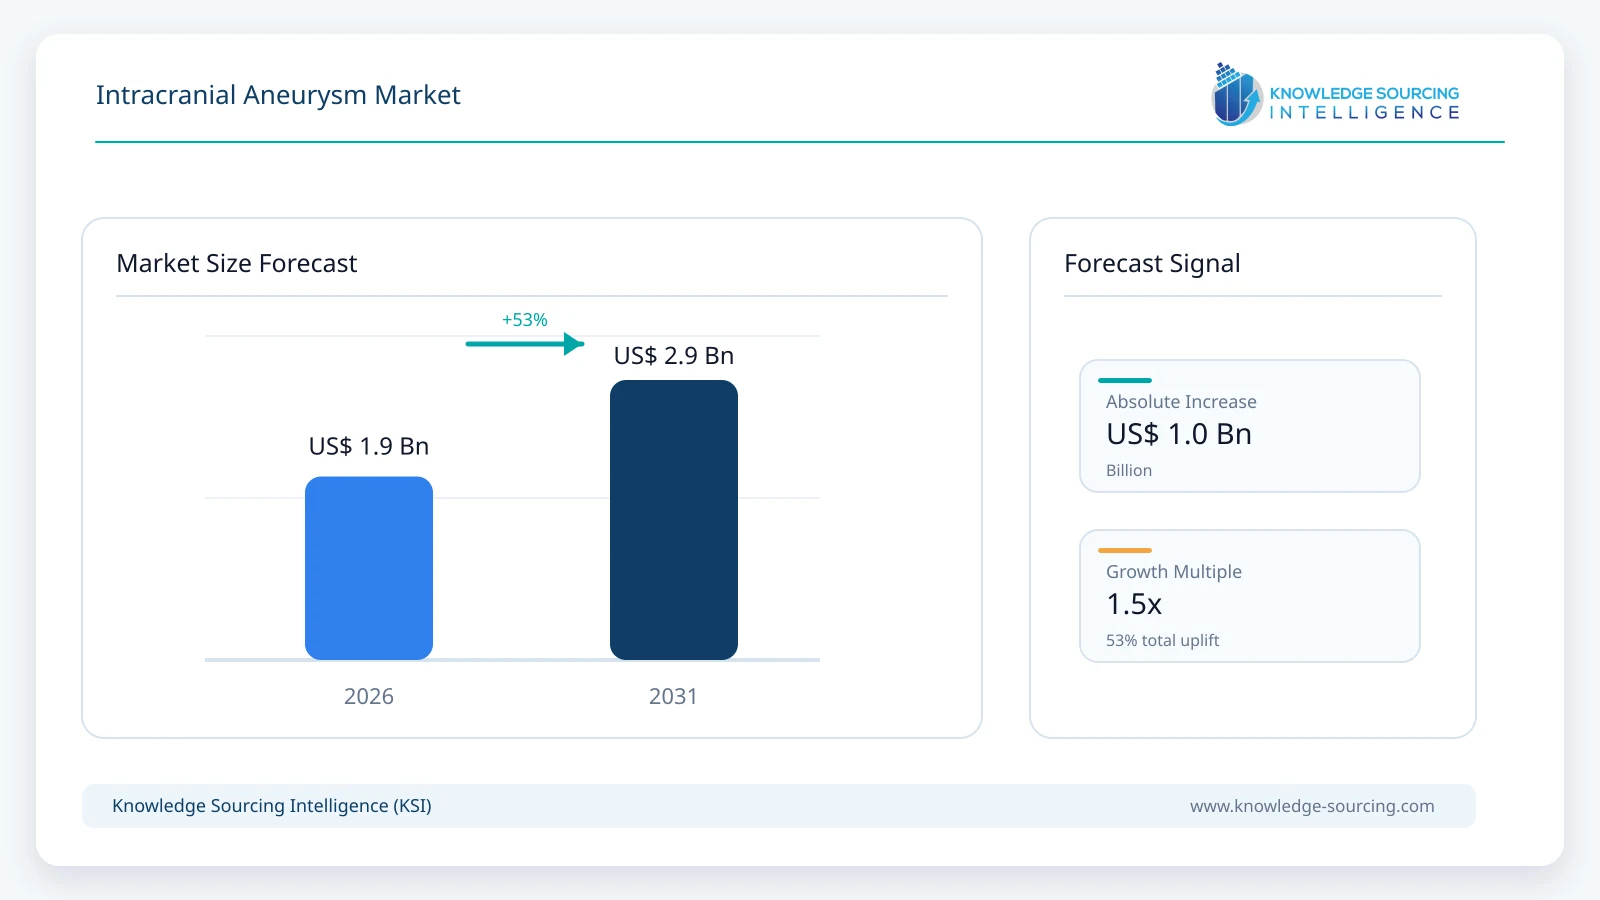
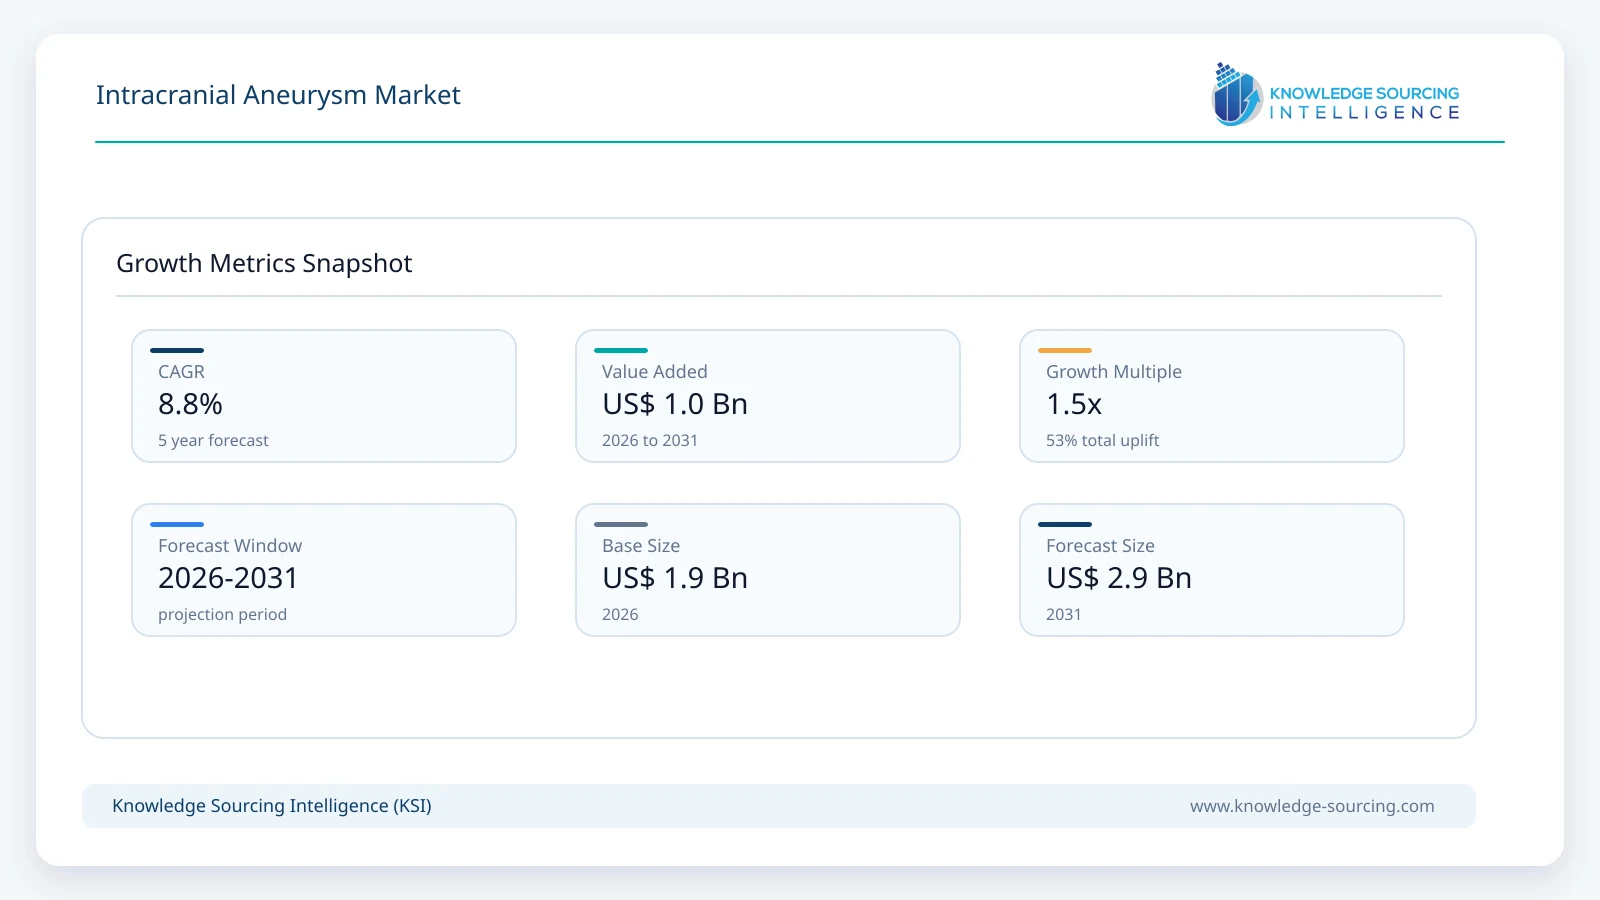
The intracranial aneurysm market is forecast to grow at a CAGR of 8.8%, reaching USD 2.9 billion in 2031 from USD 1.9 billion in 2026.
Highlights:
- 1Endovascular coiling accounts for approximately 42% of global market value in 2026retaining the largest share by treatment type.
- 2Unruptured aneurysms represent approximately 68% of market value in 2026supported by incidental detection and prophylactic treatment.
- 3Hospitals account for approximately 91% of market value in 2026reflecting the concentration of procedures in specialized neurovascular centers.
- 4North America accounts for approximately 41% of the global market in 2026supported by advanced neurointerventional capacity and device availability.
- 5Flow diverters and intrasaccular devices are expected to expand faster than the overall market through 2031from smaller revenue bases.
Market Overview
Intracranial aneurysms are focal dilations of cerebral arteries that can remain asymptomatic for years or rupture and cause aneurysmal subarachnoid hemorrhage. A 2025 systematic review and meta-analysis covering 304,848 subjects estimated overall unruptured intracranial aneurysm prevalence at 5.4%, while the long-established pooled benchmark for populations without major comorbidity is approximately 3.2%. Advancing age, female sex, hypertension and smoking were identified as important predictors, creating a substantial underlying population from which higher-risk patients may progress to surveillance or preventive treatment.
The market boundary is better defined around aneurysm treatment devices and procedure-specific consumables rather than general CT or MRI capital equipment. CTA, MRA and catheter angiography are essential to diagnosis and treatment planning, but the economics of a CT scanner or MRI system cannot reasonably be attributed solely to intracranial aneurysm treatment. Diagnostic modalities are therefore analyzed as clinical-pathway enablers rather than revenue segments. Commercial revenue is concentrated in embolization coils, flow diverters, intrasaccular flow-disruption devices, clipping systems, and related neurovascular delivery products.
Clinical management is increasingly concentrated in experienced neurovascular centers. The American Heart Association and American Stroke Association recommend prompt identification and treatment of ruptured aneurysms, preferably within 24 hours, and emphasize transfer to centers with multidisciplinary neurocritical-care and aneurysm-treatment expertise. This supports high-value device utilization in hospitals while limiting access in regions without established stroke and neurointerventional infrastructure.
Market Trends
• Intrasaccular Flow Disruption Is Expanding Treatment Options
Intrasaccular devices treat an aneurysm from within the sac rather than reconstructing the parent vessel using a conventional flow-diverting stent. Terumo Neuro launched the WEB 17 Aneurysm Embolization System in Japan in May 2026, following regulatory approval in November 2025, for ruptured and unruptured intracranial aneurysms. In August 2026, the company also reported separate one-year WISE study publications covering ruptured and unruptured WEB-treated cohorts. The technology is particularly relevant to wide-neck bifurcation aneurysms where conventional coiling may require additional stents or balloons.
• Flow Diverters Are Moving Toward Improved Surface and Delivery Technologies
Flow diversion remains one of the most important innovation areas for complex and wide-neck aneurysms. Medtronic reports that more than 100,000 patients have been treated using its Shield Technology, while newer Pipeline generations broaden catheter and size options. Stryker is advancing the Surpass Elite platform, with a 2026 publication describing first clinical experience across 81 treated aneurysms. WallabyPhenox began U.S. enrollment in the PIANO IDE trial for its p48 and p64 MW HPC devices in March 2026. Competition increasingly centers on deliverability, wall apposition, surface modification, and thromboembolic performance alongside aneurysm occlusion.
• Intravascular Imaging Is Emerging as a Procedural Adjunct
Aneurysm treatment is beginning to incorporate more detailed intravascular imaging. Spryte Medical completed enrollment in the INSYTE trial in July 2026 for its neuro-optical coherence tomography system, an FDA-approved IDE study evaluating high-resolution intravascular imaging during aneurysm treatment and follow-up. The technology remains an emerging adjunct rather than a large revenue segment, but it could improve assessment of implanted devices, vessel-wall interaction and treatment results if regulatory and reimbursement milestones are achieved.
Segment Analysis
• By Treatment Type: Endovascular Coiling
Endovascular coiling accounts for approximately 42% of global market value in 2026 and remains the largest treatment category. Coils are used across ruptured and unruptured aneurysms, while balloon-assisted and stent-assisted techniques extend their applicability to more complex anatomy. Product development remains active even as flow diversion and intrasaccular devices gain share. Terumo Neuro published results from the RAGE study in May 2026 covering second-generation HydroCoil embolization coils for ruptured intracranial aneurysms. Coiling is expected to lose some relative share through 2031 but remains central because of established clinical familiarity and broad procedural applicability.
• By Aneurysm Status: Unruptured Aneurysms
Unruptured aneurysms account for approximately 68% of market value in 2026. Improved CTA and MRA availability supports incidental detection, while treatment decisions increasingly incorporate aneurysm size, location, morphology, patient age, hypertension, smoking history and other rupture-risk factors. Not every identified aneurysm requires intervention, and surveillance remains appropriate for many lower-risk lesions. However, the large underlying prevalence creates a substantial population undergoing risk assessment and follow-up.
• By End-User: Hospitals
Hospitals account for approximately 91% of global market value in 2026 because intracranial aneurysm procedures require specialized neurovascular teams, advanced angiography, anesthesia, neurocritical care and immediate complication management. Comprehensive stroke centers and tertiary neurological hospitals therefore dominate device procurement. The AHA/ASA notes that experienced, higher-volume centers with dedicated neurocritical-care resources are associated with better outcomes in aneurysmal subarachnoid hemorrhage.
• By Geography: North America
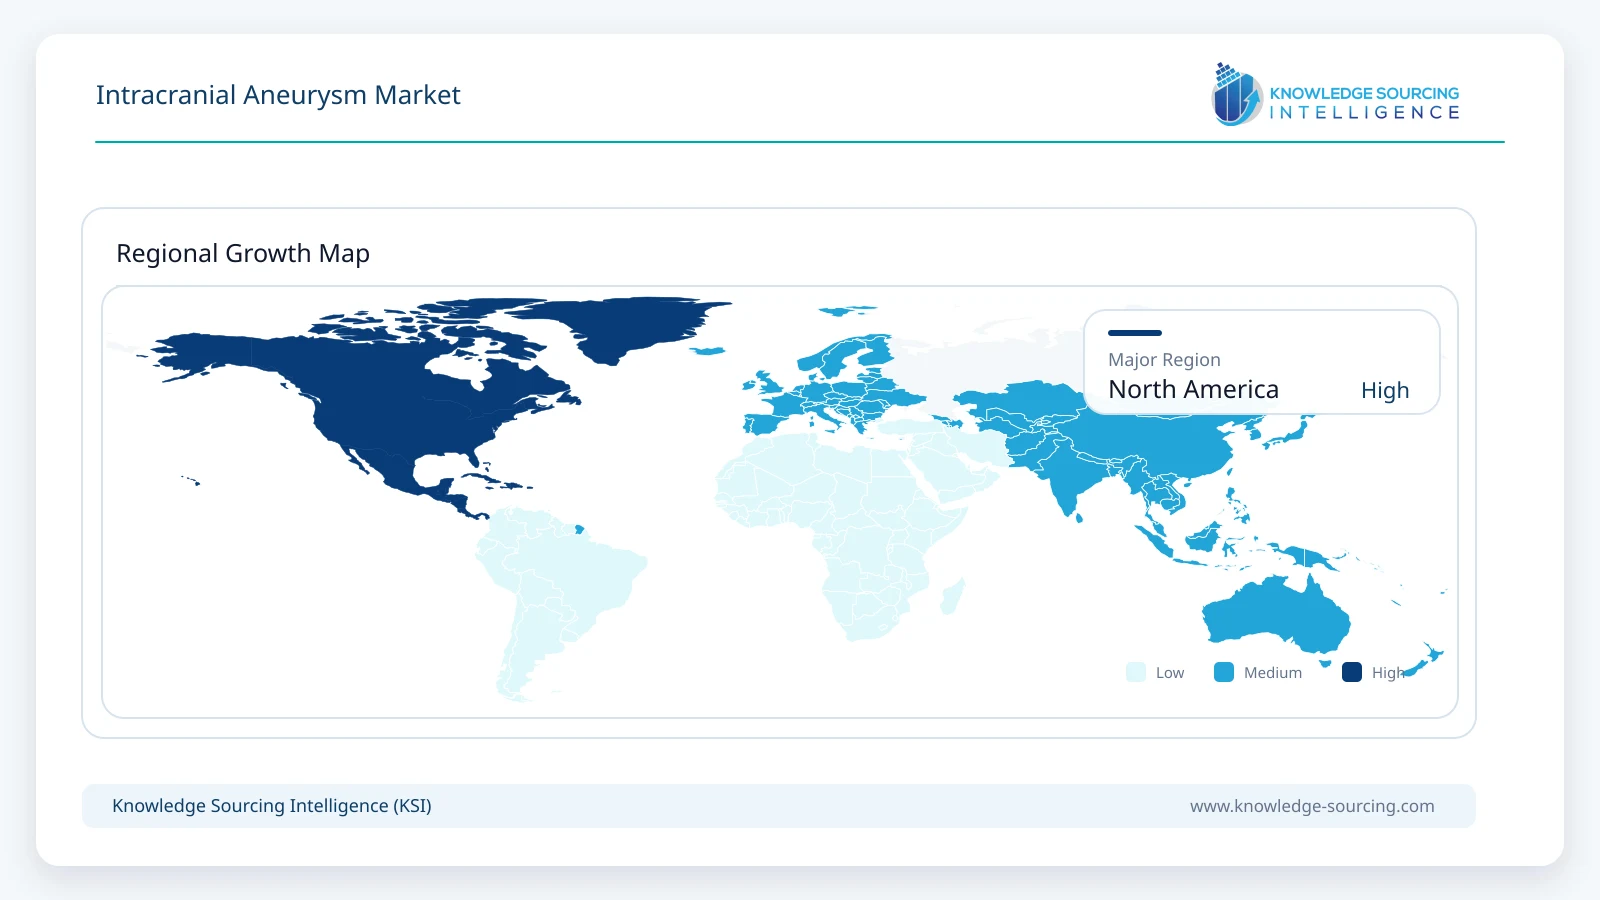
North America accounts for approximately 41% of global market value in 2026, led by the United States. The region combines high access to neuroimaging and neurointerventional care with early adoption of flow diverters and intrasaccular technologies. The U.S. FDA maintains dedicated PMA pathways for intracranial aneurysm flow diverters and intrasaccular flow-disruption devices, creating a regulated but commercially important product environment.
Market Drivers
• Large Diagnosed and Undiagnosed Aneurysm Population
Intracranial aneurysms are considerably more common than treated-procedure volumes suggest. The traditional pooled prevalence estimate is approximately 3.2%, while the 2025 meta-analysis reported 5.4% across its included studies. Most aneurysms do not rupture and many never require treatment, but broader use of non-invasive brain imaging increases incidental identification and expands the population undergoing surveillance and rupture-risk assessment. Aging populations and the continuing prevalence of hypertension and smoking further support the long-term treatment pool.
• Endovascular Innovation Is Broadening Treatable Anatomy
Market expansion increasingly comes from the ability to treat lesions that previously had fewer suitable options. Coils remain broadly applicable, flow diverters reconstruct the parent vessel across the aneurysm neck, and intrasaccular devices offer another option for selected wide-neck bifurcation aneurysms. Lower-profile delivery systems also improve access to smaller and more distal vessels. The expansion of WEB in Japan, current Surpass Elite experience and the U.S. PIANO trial demonstrate a continuing widening of the treatment toolkit rather than convergence around one device category.
• Specialized Stroke Networks Support Advanced Device Adoption
Intracranial aneurysm care benefits from expanding comprehensive stroke centers and dedicated neurointerventional programs because complex procedures require multidisciplinary expertise. AHA/ASA guidance recommends rapid transfer of aneurysmal subarachnoid hemorrhage patients to experienced centers and prompt treatment of the ruptured aneurysm. As countries expand angiography capacity and neurointerventional training, a larger proportion of patients can access advanced treatment.
Market Restraints
• Treatment Decisions Must Balance Rupture Risk Against Procedural Risk
A large underlying prevalence does not translate directly into treatment volume. Many small or stable unruptured aneurysms are managed through surveillance because intervention itself carries risks including thromboembolism, hemorrhage, vessel injury, device complications and retreatment. Flow diversion can also require antiplatelet therapy, affecting patient selection and peri-procedural management. Market growth therefore depends on risk-based treatment rather than widespread screening followed automatically by intervention.
• Advanced Treatment Remains Concentrated in Specialized Centers
Access is constrained by the need for experienced operators, biplane angiography, neurocritical care and multidisciplinary surgical backup. These requirements create substantial regional differences in treatment rates. Device costs can also be significant when complex aneurysms require multiple coils, adjunctive stents, flow diverters or specialized delivery systems, limiting adoption outside high-volume tertiary hospitals.
Competitive Landscape
The intracranial aneurysm market is led by specialized neurovascular device manufacturers rather than hospitals or general diagnostic-imaging companies. Medtronic competes through the Pipeline flow-diverter family and Axium coils; Stryker through Surpass flow diversion and other neurovascular embolization products; Terumo Neuro/MicroVention through WEB, FRED and HydroCoil; and Johnson & Johnson MedTech/CERENOVUS through neurovascular treatment and access technologies. Penumbra, Balt, WallabyPhenox, MicroPort NeuroTech, Rapid Medical and Kaneka Medix broaden competition across coils, flow modulation, access and adjunctive systems.
The existing KSI company list therefore requires correction. Mayo Clinic, Johns Hopkins Medicine and Mayfield Clinic are important clinical institutions but are not commercial aneurysm-device manufacturers. Competitive advantage instead depends on clinical evidence, regulatory approval, physician training, catheter compatibility, deliverability, occlusion performance, complication profile and the breadth of complementary access products.
Recent Developments
August 2026: Terumo Neuro announced one-year WISE publications for WEB treatment in separate ruptured and unruptured aneurysm cohorts.
July 2026: Spryte Medical completed enrollment in the INSYTE IDE trial evaluating neuro-optical coherence tomography during aneurysm treatment and follow-up.
May 2026: Terumo Neuro published North American RAGE study results for second-generation HydroCoil embolization coils in ruptured aneurysms.
May 2026: Terumo Neuro launched the WovenEndoBridge™ 17 (WEB 17) Aneurysm Embolization System in Japan, expanding treatment options for ruptured and unruptured intracranial aneurysms.
March 2026: WallabyPhenox announced the first U.S. patient treated in the PIANO IDE trial evaluating p48 and p64 MW HPC flow-modulation devices.
Market Outlook
The intracranial aneurysm market is expected to expand through 2031 as endovascular treatment becomes applicable to a broader range of aneurysm morphologies and more patients are identified through modern imaging. Coiling remains the largest treatment category in 2026, while flow diverters and intrasaccular devices gain share as clinical evidence and regulatory coverage expand. Hospitals remain the dominant end-user because treatment requires specialized neurovascular infrastructure, and North America retains the largest regional value pool.
Intracranial Aneurysm Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.9 billion |
| Total Market Size in 2031 | USD 2.9 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 8.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Treatment Type, Aneurysm Status, End-User, Geography |
| Companies |
|
Market Segmentation
By Treatment Type
Endovascular Coiling
Flow Diverters
Intrasaccular Flow-Disruption Devices
Surgical Clipping
Other Adjunctive Devices
By Aneurysm Status
Unruptured Intracranial Aneurysms
Ruptured Intracranial Aneurysms
By End-User
Hospitals and Comprehensive Stroke Centers
Specialty Neurosurgery and Neurovascular Centers
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Inclusion and Exclusion Criteria
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Treatment-Volume and Device-Mix Modelling
2.6. Segment Modelling
2.7. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Intracranial Aneurysm Market Size, 2026-2031
3.3. Treatment Type Outlook
3.4. Regional Opportunity Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Large Diagnosed and Undiagnosed Aneurysm Population
4.1.2. Endovascular Innovation Broadening Treatable Anatomy
4.1.3. Expansion of Specialized Stroke and Neurointerventional Networks
4.2. Market Restraints
4.2.1. Procedural Risk and Patient Selection
4.2.2. Concentration of Care in Specialized Centers
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Diagnosis and Treatment Pathway
4.6.1. CTA and MRA
4.6.2. Cerebral Angiography
4.6.3. Role of CSF Analysis in Suspected Subarachnoid Hemorrhage
4.7. Regulatory and Clinical Evidence Environment
5. TECHNOLOGY OUTLOOK
5.1. Intrasaccular Flow Disruption
5.2. Surface-Modified Flow Diverters
5.3. Low-Profile Delivery Systems
5.4. Intravascular Neuro-Imaging
5.5. Treatment Planning and Follow-Up Imaging
6. INTRACRANIAL ANEURYSM MARKET BY TREATMENT TYPE
6.1. Introduction
6.2. Endovascular Coiling
6.3. Flow Diverters
6.4. Intrasaccular Flow-Disruption Devices
6.5. Surgical Clipping
6.6. Other Adjunctive Devices
7. INTRACRANIAL ANEURYSM MARKET BY ANEURYSM STATUS
7.1. Introduction
7.2. Unruptured Intracranial Aneurysms
7.3. Ruptured Intracranial Aneurysms
8. INTRACRANIAL ANEURYSM MARKET BY END-USER
8.1. Introduction
8.2. Hospitals and Comprehensive Stroke Centers
8.3. Specialty Neurosurgery and Neurovascular Centers
8.4. Others
9. INTRACRANIAL ANEURYSM MARKET BY GEOGRAPHY
9.1. North America
9.1.1. By Treatment Type
9.1.2. By Aneurysm Status
9.1.3. By End-User
9.1.4. By Country
9.1.4.1. United States
9.1.4.2. Canada
9.1.4.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Spain
9.3.5. Italy
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Israel
9.4.4. Others
9.5. Asia Pacific
9.5.1. Japan
9.5.2. China
9.5.3. India
9.5.4. South Korea
9.5.5. Indonesia
9.5.6. Thailand
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Coil and Embolization Technology Positioning
10.3. Flow-Diverter Technology Positioning
10.4. Intrasaccular Device Positioning
10.5. Regulatory Approvals and Clinical Evidence
10.6. Partnerships, Distribution and Product Launches
10.7. Competitive Dashboard
11. COMPANY PROFILES
11.1. Medtronic plc
11.2. Stryker Corporation
11.3. Terumo Neuro
11.4. Johnson & Johnson MedTech
11.5. Penumbra, Inc.
11.6. Balt Group
11.7. WallabyPhenox
11.8. MicroPort NeuroTech Co., Ltd.
11.9. Rapid Medical Ltd.
11.10. Kaneka Medix Corporation
12. APPENDIX
12.1. Market Definition and Scope
12.2. Treatment Device Inclusion and Exclusion Criteria
12.3. Currency and Conversion Assumptions
12.4. Base Year and Forecast Period
12.5. Market Estimation Approach
12.6. Clinical and Regulatory Source Framework
12.7. Data Triangulation and Validation
12.8. Abbreviations
Navigate
Trusted by the world's leading organizations











