
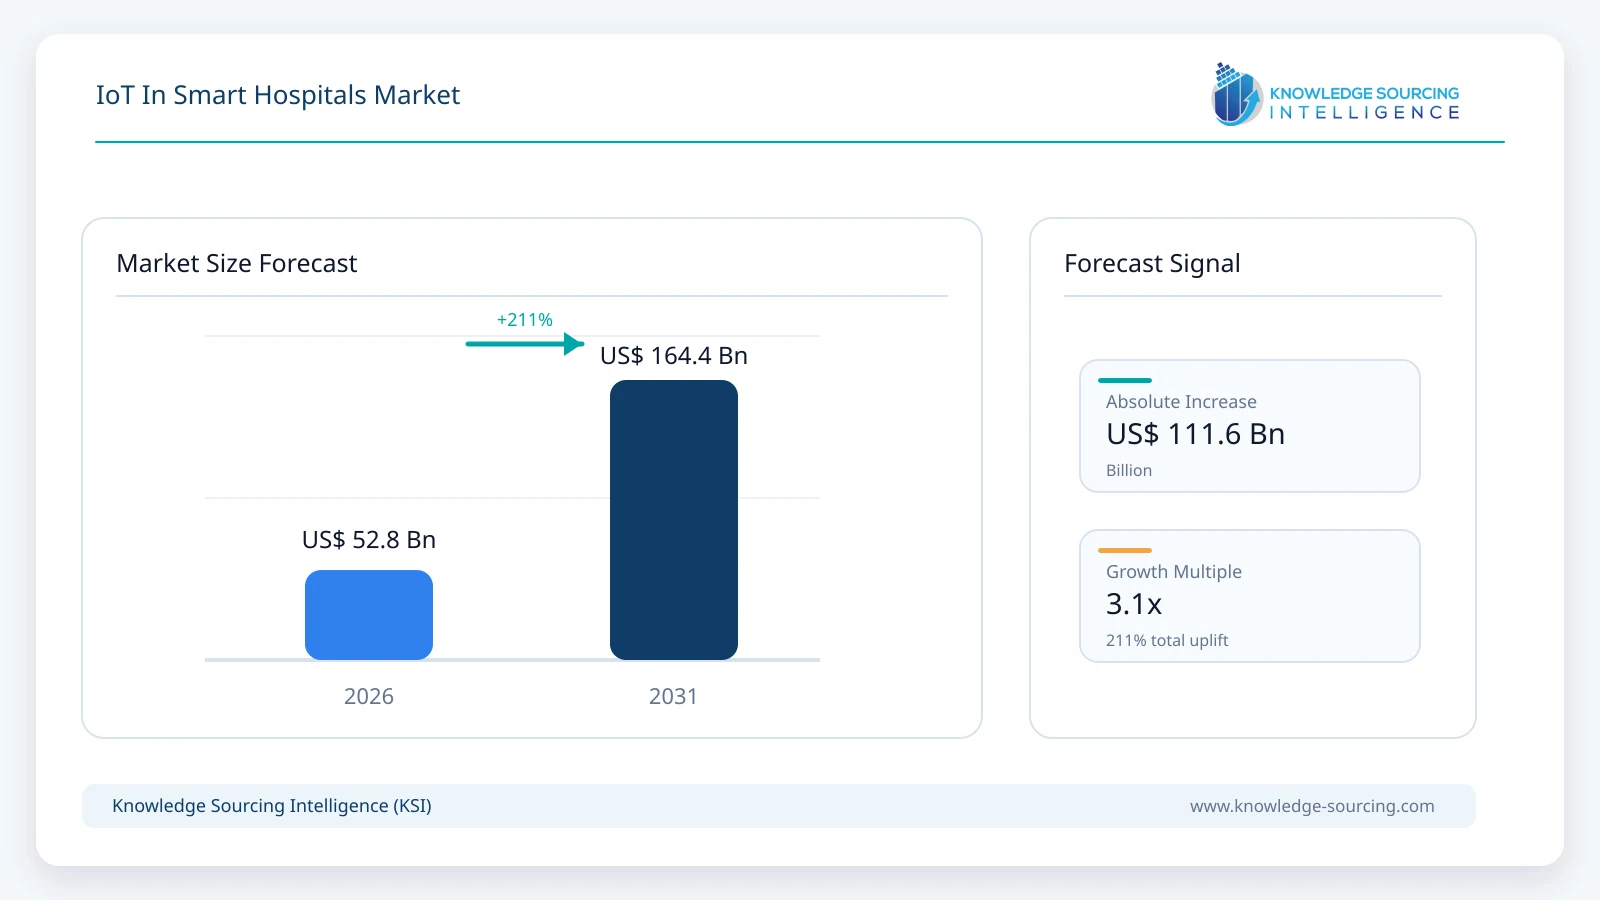
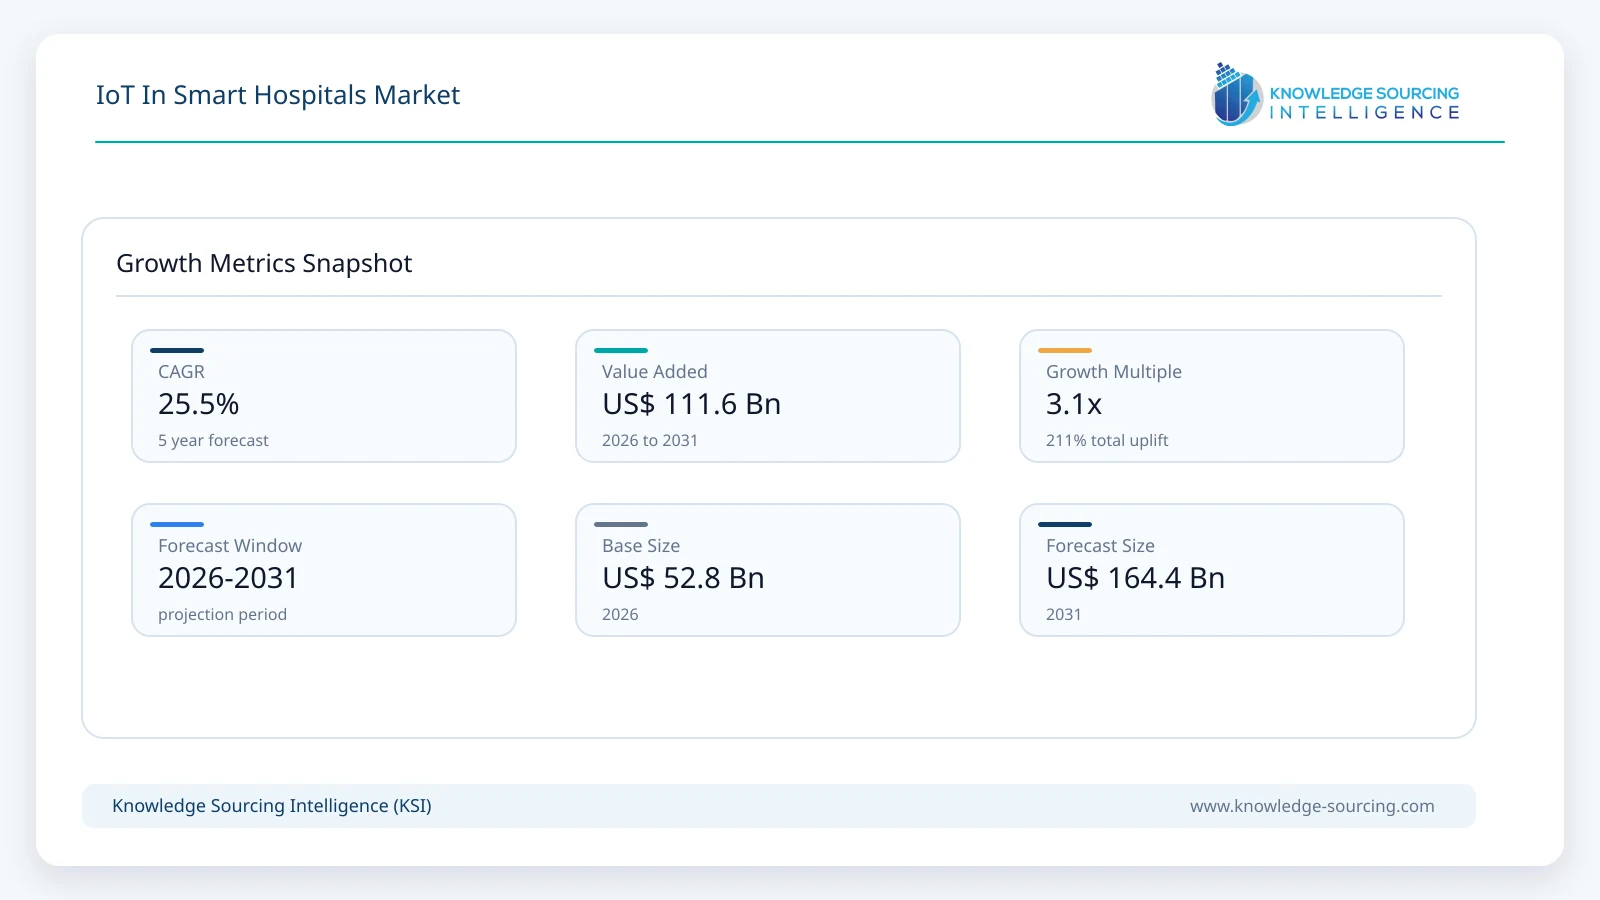
The IoT In Smart Hospitals Market is forecast to grow at a CAGR of 25.5%, reaching USD 164.4 billion in 2031 from USD 52.8 billion in 2026.
Highlights:
- 1Hospital demand is being supported by connected patient monitoring, equipment utilization, workflow automation, and real-time operational visibility.
- 2Connectivity infrastructure is shifting from isolated device networks toward interoperable, multi-department hospital architectures.
- 3Remote monitoring and connected clinical workflows are expanding the value proposition beyond traditional bedside equipment.
- 4Cybersecurity, data governance, interoperability, and lifecycle support are becoming central criteria in hospital technology procurement.
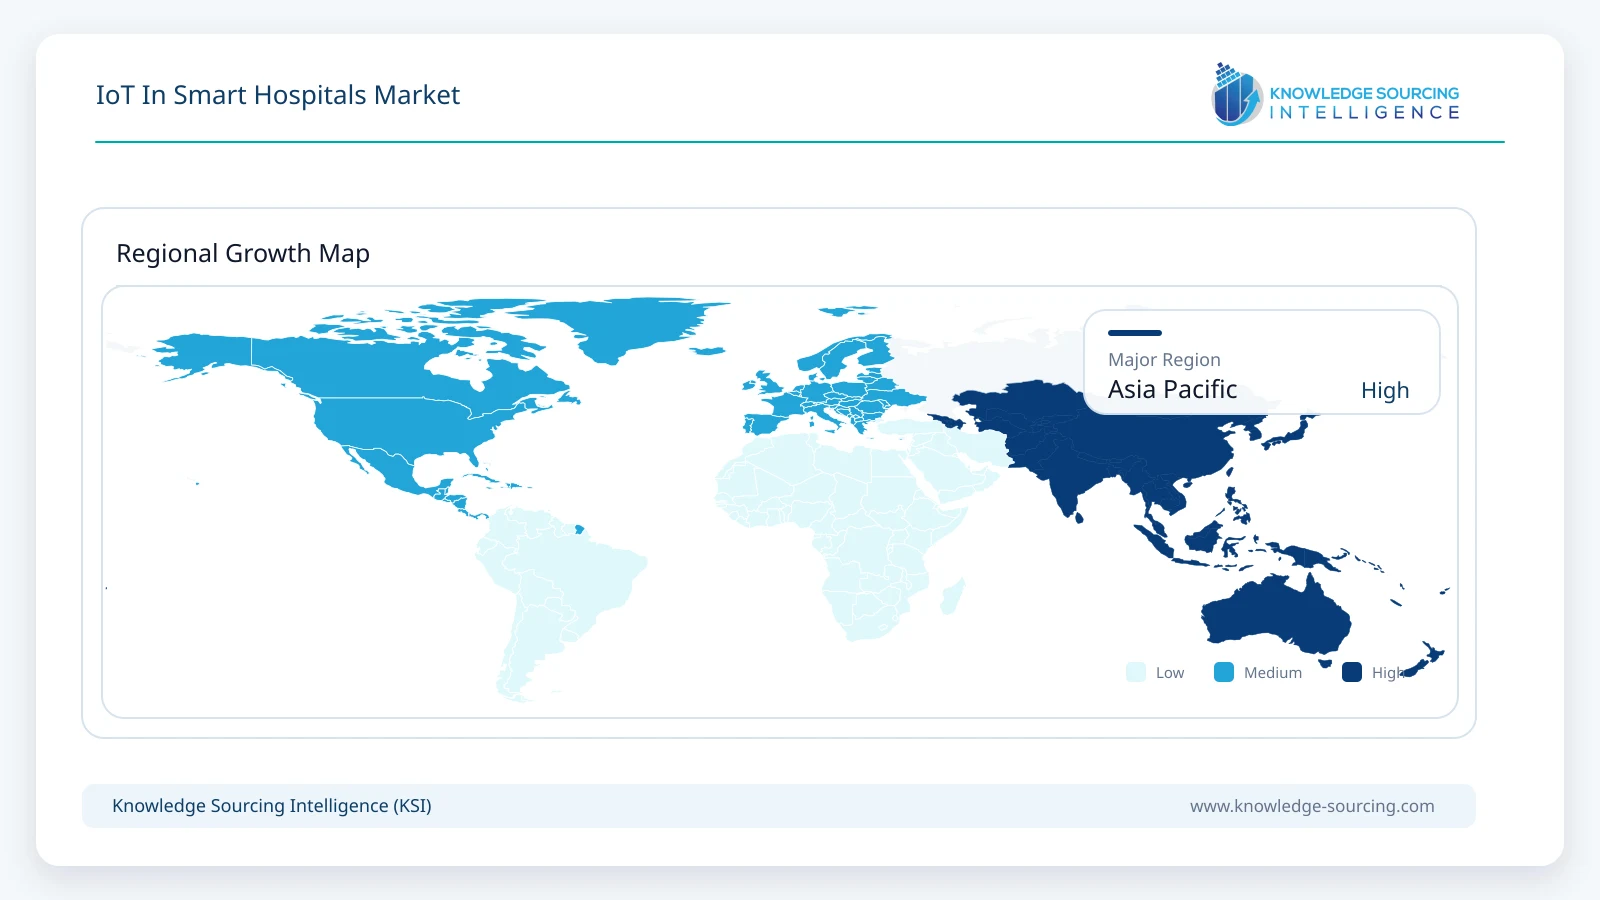
- 5North America remains commercially important because of high healthcare technology spending and mature connected-device infrastructure, while Asia Pacific offers substantial deployment opportunities as hospital systems modernize.
- 6Partnerships and long-term technology agreements are becoming important competitive mechanisms because hospitals prefer integrated platforms, lifecycle services, and predictable upgrade paths.
The IoT in Smart Hospitals Market covers connected hardware, software, communications infrastructure, and related services used to capture, transmit, integrate, analyze, and act on data generated across hospital environments. The scope includes connected medical devices, patient-monitoring equipment, asset tags, environmental sensors, medication-management systems, connected operating rooms, hospital infrastructure controls, inventory systems, and platforms that connect these assets with clinical and operational workflows.
The commercial proposition is broader than simply adding network connectivity to medical equipment. Hospitals purchase IoT capabilities when connected data can improve utilization of expensive assets, reduce avoidable manual work, strengthen clinical visibility, support earlier intervention, or improve coordination between departments. Consequently, purchasing decisions increasingly involve clinical engineering, information technology, nursing leadership, procurement, cybersecurity, facilities management, and finance rather than a single hospital department.
Demand is being shaped by the economics of hospital operations. Hospitals operate large inventories of high-value equipment that frequently move between departments, while clinical teams manage multiple alarms, documentation requirements, medication processes, patient transfers, and staffing constraints. A connected infrastructure can create an operational layer linking these activities. The commercial value therefore depends on whether a deployment produces measurable improvements in equipment utilization, staff productivity, patient monitoring, workflow continuity, or resource planning.
The market also benefits from the expanding availability of network-enabled medical equipment and sensor-based digital health technologies. The U.S. Food and Drug Administration maintains lists of authorized medical devices incorporating digital health technologies, including sensor-based technologies, demonstrating the widening role of connected and software-enabled devices within regulated healthcare.
The demand environment is moving from isolated connected devices toward interoperable hospital ecosystems. A hospital may initially purchase connected patient monitors or real-time location systems for a specific department. Once the infrastructure is installed, the business case can expand into equipment tracking, patient flow, medication management, environmental monitoring, and command-center applications. This creates an important installed-base effect: connectivity investments can reduce the incremental cost of adding subsequent applications, provided the underlying network, identity, security, and integration architecture can support them.
Interoperability is consequently becoming a procurement criterion alongside device performance. Hospitals increasingly need equipment from different manufacturers to exchange usable information without creating additional screens or manual transcription. In July 2025, Philips announced partnerships with Dräger, Hamilton Medical, Getinge, and B. Braun centered on Service-Oriented Device Connectivity standards, illustrating the commercial importance of interoperability across medical devices and platforms.
Cloud and enterprise software are also changing the economics of smart-hospital deployments. Instead of treating every connected device as an independent technology purchase, health systems can adopt centralized platforms for data aggregation, analytics, workflow management, and operational visibility. This supports recurring software and services revenue while allowing hospitals to expand applications without replacing the entire installed equipment base.
Buyer priorities vary according to hospital size and clinical complexity. Large academic medical centers generally have greater capacity to fund enterprise architectures and integrate multiple data sources. General hospitals often prioritize applications with direct operational returns, such as equipment tracking, patient flow, staff communication, and monitoring. Specialty hospitals may prioritize highly specific connected workflows around surgery, oncology, cardiology, intensive care, or diagnostic imaging. Smaller facilities typically require simpler deployments with clear implementation economics and limited infrastructure disruption.
The market is therefore characterized by several overlapping supplier groups. Medical technology companies provide connected devices and clinical platforms; networking companies provide connectivity and security; enterprise software vendors provide data, workflow, cloud, and analytics layers; and specialist integrators connect these technologies to hospital information systems. Competition increasingly occurs at the system level rather than around individual sensors.
Market Drivers
Increasing Need for Continuous Patient Visibility
Continuous monitoring is one of the clearest commercial use cases for IoT within hospitals. Conventional monitoring models can require clinicians to interpret information from multiple bedside systems and manually transfer relevant observations into broader clinical workflows. Connected monitoring can instead make selected physiological information available across designated clinical and operational systems.
The purchasing decision is particularly relevant in intensive care, cardiac care, emergency departments, step-down units, and other areas where patient conditions can change quickly. Hospitals are not purchasing connectivity solely for additional data. They are seeking earlier visibility, reduced dependence on manual observation, better alarm management, and improved allocation of clinical attention.
The business case also extends beyond the bedside. Philips' September 2025 launch of a smart telemetry platform illustrates the industry's movement toward enterprise-wide connectivity for mobile patients, with the company positioning continuous cardiac monitoring around clinical workflow and operational requirements.
For suppliers, this favors platforms that can connect monitoring devices with broader hospital systems. Vendors that can combine hardware, software, connectivity, analytics, and lifecycle support can address more of the purchasing decision and potentially secure longer-term contracts.
Pressure to Improve Utilization of Hospital Assets
Hospitals hold substantial inventories of mobile equipment, including infusion pumps, patient monitors, wheelchairs, beds, ventilators, imaging accessories, and other clinical assets. When staff cannot quickly locate available equipment, hospitals may purchase additional units even when underutilized equipment exists elsewhere.
IoT-enabled asset tracking addresses this economic problem by creating visibility into location, utilization, movement, and availability. The value is not limited to reducing equipment purchases. Better asset visibility can shorten search time, reduce unnecessary equipment transfers, support preventive maintenance, and improve readiness for high-demand departments.
The commercial importance of this application is visible in GE HealthCare's June 2026 expansion of its relationship with Carilion Clinic. The agreement includes a real-time location system intended to improve medical-equipment tracking and operational monitoring.
This type of deployment also creates recurring service opportunities because hospitals require ongoing device management, software updates, analytics, network maintenance, and integration support.
Expansion of Data-Driven Hospital Operations
Hospital executives increasingly need operational information that is available across departments rather than confined to individual systems. Patient movement, bed capacity, staffing availability, equipment utilization, imaging demand, and emergency capacity can interact in ways that make department-level management inefficient.
IoT infrastructure provides a data layer that can feed command centers and operational dashboards. GE HealthCare reported in April 2026 that its Command Center was operating across three Melbourne hospitals, providing real-time visibility of hospital resources and supporting management of patient volumes and workforce availability.
The purchasing rationale is therefore shifting from device connectivity toward operational intelligence. Hospitals can justify larger projects when connected data supports measurable improvements in throughput, resource utilization, or capacity management.
Growth of Hospital-at-Home and Remote Care Models
The boundary of the connected hospital is extending beyond the physical hospital building. Hospital-at-home programs use medical-grade equipment and information systems outside the hospital, requiring reliable data transmission and monitoring workflows.
NIST's December 2025 guidance identifies specific cybersecurity and privacy risks created when hospital-at-home environments incorporate connected devices outside the healthcare organization's direct control. The guidance emphasizes access control, authentication, monitoring, data security, governance, and network segmentation.
This creates demand for connected monitoring devices, secure connectivity, device management, remote clinical oversight, and integration with hospital information systems. It also changes the procurement model because hospitals must evaluate not only the device but the complete communication and security architecture supporting it.
Interoperability Requirements Are Expanding
Hospitals rarely operate a single-vendor technology environment. Imaging equipment, monitors, infusion systems, electronic health records, laboratory systems, pharmacy platforms, building systems, and communication technologies may come from different suppliers.
This fragmentation increases the value of interoperable IoT platforms. Vendors must increasingly demonstrate that their systems can exchange information through recognized standards, APIs, and secure integration methods. Philips' 2025 partnerships around Service-Oriented Device Connectivity demonstrate how interoperability can become a product differentiator rather than merely an IT requirement.
For buyers, interoperability reduces duplicate interfaces and helps protect investments in existing equipment. For suppliers, it can determine whether a product becomes part of an enterprise architecture or remains limited to a departmental deployment.
Market Restraints and Challenges
Cybersecurity Risk Across Connected Medical Devices
Every additional connected device can create another potential entry point into a hospital's information environment. The risk is particularly difficult because hospitals operate heterogeneous equipment with different software versions, manufacturers, replacement cycles, and security capabilities.
The FDA states that connected medical devices can introduce cybersecurity vulnerabilities that may affect device safety and effectiveness. Its February 2026 final cybersecurity guidance addresses device design, labeling, premarket submissions, and cybersecurity requirements for qualifying cyber devices.
Hospitals therefore increasingly require security architecture, vulnerability management, software bills of materials where applicable, patching processes, authentication, segmentation, and incident-response capabilities. These requirements increase implementation costs but also favor suppliers with mature lifecycle-management capabilities.
Legacy Equipment and Integration Costs
A hospital may operate connected equipment alongside older devices that were never designed for modern network environments. Replacing all legacy equipment simultaneously is generally uneconomic, particularly for capital-intensive imaging, surgical, and monitoring systems.
The resulting challenge is integration. Hospitals may need gateways, middleware, interface engines, adapters, or professional services to bring older equipment into a connected architecture. These costs can extend implementation schedules and reduce the apparent return on investment.
Suppliers that offer upgrade pathways rather than complete replacement can address this constraint. GE HealthCare's June 2026 introduction of upgrade pathways for selected interventional systems explicitly focused on modernization while preserving existing infrastructure and limiting construction disruption.
Interoperability and Data Fragmentation
Connectivity does not automatically create usable data. Devices may produce information in different formats, use incompatible interfaces, or operate within departmental silos. A hospital can therefore accumulate large volumes of connected data without obtaining corresponding operational value.
Integration requires standards, middleware, governance, identity management, data normalization, and workflow redesign. These activities create costs that may not be visible in the initial equipment quotation.
The commercial implication is a shift toward total-cost-of-ownership evaluation. Buyers increasingly need suppliers to demonstrate implementation capability and long-term interoperability rather than simply device connectivity.
Procurement Complexity and Long Capital Cycles
Hospital procurement often involves clinical evaluation, information-technology review, cybersecurity assessment, capital budgeting, legal review, biomedical engineering approval, and competitive tendering. Large projects may require multi-year planning.
This creates a barrier for vendors offering technologies that require significant infrastructure changes without a clearly measurable operational return. Suppliers must increasingly show implementation milestones, service-level commitments, measurable utilization benefits, and upgrade paths.
Long-term partnerships can reduce this friction. Recent agreements involving GE HealthCare and Siemens Healthineers demonstrate the growing use of multi-year arrangements combining technology modernization, service, planning, and operational support.
Workforce and Change-Management Constraints
Connected hospital systems change how nurses, clinicians, biomedical engineers, IT teams, and facilities staff interact with technology. Poorly designed systems can increase alerts, create additional dashboards, or add documentation requirements rather than reduce workload.
Hospitals therefore evaluate usability and workflow fit alongside technical specifications. Vendors must provide training, implementation support, device-management tools, and appropriate configuration. The ability to demonstrate workflow improvement can be more commercially persuasive than a higher number of connected endpoints.
Major Segment Analysis
By Application: Remote Patient Monitoring
Remote Patient Monitoring represents a commercially important application because it directly links connected devices with clinical decision-making. The application encompasses connected physiological monitoring, wearable and bedside sensors, communication gateways, data platforms, alerting systems, and clinical workflows used to observe patients continuously or at defined intervals.
Its importance comes from the economics of clinical attention. Hospitals cannot assign the same level of direct observation to every patient. Connected monitoring allows selected measurements to be captured continuously and routed to clinicians or monitoring teams according to defined clinical thresholds.
Within hospitals, the strongest use cases include intensive care, cardiac monitoring, postoperative observation, emergency care, and patients who require extended monitoring without continuous one-to-one observation. The application also connects naturally with hospital-at-home models, where remote monitoring becomes essential to maintaining clinical oversight outside the hospital.
Buyer requirements are becoming more sophisticated. Hospitals need devices that provide reliable measurements, secure communication, low maintenance requirements, appropriate battery life, manageable alarm volumes, and integration with clinical information systems. They also require clear responsibility for data interpretation and escalation.
The competitive model favors suppliers capable of connecting monitoring hardware with enterprise software and clinical workflows. A device with strong measurement performance but weak interoperability can be difficult to deploy across a large health system. Conversely, platforms that connect multiple device types can create broader enterprise value.
Philips' February 2025 collaboration with Mass General Brigham provides a relevant example of this direction. The organizations announced work on data infrastructure and AI designed to process live healthcare information from multiple sources, including medical devices, with the objective of creating a more unified near-real-time data environment.
Remote patient monitoring also generates recurring revenue opportunities. Beyond initial device sales, hospitals may require software subscriptions, connectivity services, analytics, device maintenance, integration, cybersecurity, and clinical-support services.
The segment's market relevance is therefore greater than the value of monitoring devices alone. It can become an entry point for broader connected-care deployments, particularly when the hospital already has the networking and data infrastructure required to support additional IoT applications.
Regional Analysis
North America
North America represents a mature commercial environment for hospital IoT because healthcare organizations have substantial installed bases of connected medical equipment, enterprise software, networking infrastructure, and electronic health records. Large hospital systems are also active buyers of long-term technology agreements that combine equipment, software, services, and modernization programs.
The United States places particular emphasis on cybersecurity and protection of electronic health information. The HIPAA Security Rule requires covered entities and business associates to maintain administrative, physical, and technical safeguards for electronic protected health information. HHS also proposed significant cybersecurity-related modifications to the Security Rule in December 2024.
FDA cybersecurity requirements further influence connected medical-device procurement. The agency's February 2026 final guidance provides recommendations covering cybersecurity design, labeling, premarket submissions, and cyber-device requirements.
Canada provides opportunities through hospital modernization, connected care, digital health, and provincial healthcare technology programs. Mexico represents a more cost-sensitive opportunity, with adoption influenced by healthcare infrastructure investment, connectivity availability, and public-private deployment models.
The region's principal constraint is not basic awareness of connected healthcare but integration complexity. Hospitals increasingly seek measurable returns from large technology programs and prefer vendors capable of providing multi-year support.
Europe
Europe has strong structural support for connected healthcare because interoperability and health-data governance are becoming more coordinated at the regional level. Regulation (EU) 2025/327 established the European Health Data Space, creating a common framework for electronic health-data access, exchange, and reuse. The regulation entered into force in March 2025, with major implementation milestones extending through 2029 and 2031.
This regulatory direction has commercial implications for hospital IoT. Connected devices generate data that increasingly needs to integrate with electronic health records and broader health-data ecosystems. Suppliers that support secure interoperability and standardized data exchange can benefit from the resulting procurement requirements.
Germany, France, the United Kingdom, Italy, Spain, and the Netherlands offer sizeable opportunities because of established hospital systems and investment in digital infrastructure. However, procurement remains fragmented by national and regional healthcare structures, while privacy, cybersecurity, legacy infrastructure, and reimbursement considerations can lengthen deployment cycles.
Europe is therefore likely to favor suppliers with strong interoperability, data governance, cybersecurity, and lifecycle-support capabilities rather than vendors offering isolated connected devices.
Asia Pacific
Asia Pacific offers a wide range of market conditions. Japan, South Korea, Australia, China, India, Taiwan, Indonesia, and Thailand differ substantially in healthcare financing, hospital infrastructure, digital maturity, and procurement practices.
China combines large hospital networks with substantial investment in medical technology and digital infrastructure. Japan and South Korea have mature healthcare technology environments and strong demand for automation, monitoring, and operational efficiency. Australia offers opportunities through digitally enabled hospital operations and geographically distributed healthcare delivery.
India presents a particularly important development market. The Ayushman Bharat Digital Mission provides a national digital-health architecture involving health accounts, health professional and facility registries, and interoperable health records. As of July 28, 2026, the official ABDM platform reported 2,697 active integrators and 502 successful integrators, illustrating an expanding digital-health integration ecosystem.
The National Health Authority's Digital Health Incentive Scheme also provides incentives for eligible hospitals, clinics, laboratories, diagnostic centers, pharmacies, and digital health solution providers to adopt ABDM-compatible systems. The current scheme period specified by NHA runs from April through September 2026.
Asia Pacific's principal challenge is uneven infrastructure. Premium urban hospitals can adopt sophisticated connected systems, while smaller or rural facilities may prioritize basic connectivity, affordability, and interoperability. Suppliers therefore need modular products and flexible financing models.
Middle East and Africa
The Middle East offers opportunities through new hospital construction, healthcare modernization, centralized health systems, and investment in advanced medical infrastructure. Saudi Arabia and the United Arab Emirates are particularly relevant because large healthcare programs can support integrated hospital platforms rather than isolated technology purchases.
Israel has a mature technology ecosystem and strong digital-health capabilities, supporting advanced monitoring, analytics, and connected clinical workflows. South Africa provides an important regional market but faces greater infrastructure and budget constraints than Gulf markets.
Across the region, suppliers must account for varying data-governance requirements, procurement structures, local service capacity, and cybersecurity expectations. New-build hospitals can be particularly attractive because connectivity, networking, building systems, and medical equipment can be specified as an integrated architecture from the beginning.
South America
South America remains a more heterogeneous market. Brazil represents the largest opportunity because of its healthcare scale and mix of public and private providers. Argentina, Colombia, and Chile provide additional opportunities through hospital modernization, telehealth, connected monitoring, and digital health infrastructure.
Budget limitations can constrain large-scale IoT deployments, particularly where hospitals must prioritize essential clinical equipment. Suppliers can address this by targeting applications with measurable returns, such as equipment tracking, remote monitoring, energy management, and inventory visibility.
The region is also likely to favor partnerships with local technology integrators and healthcare organizations because implementation, maintenance, regulatory compliance, and localization can be as important as the underlying IoT technology.
Competitive Landscape
The competitive structure of the IoT In Smart Hospitals Market is fragmented across technology layers rather than dominated by one universal supplier. The provided company universe spans medical devices, clinical systems, networking, cloud infrastructure, enterprise applications, automation, and data platforms.
Koninklijke Philips N.V. and Siemens Healthineers compete strongly where connected medical equipment, imaging, monitoring, clinical workflows, and enterprise healthcare technology intersect. GE HealthCare combines medical technology with software, imaging, monitoring, asset-management, and operational solutions. Recent GE HealthCare agreements demonstrate a preference for long-duration partnerships that combine equipment modernization with services and operational support.
Cisco Systems, Inc. occupies an important infrastructure layer through networking and security, while IBM, Microsoft, Oracle, and SAP compete around enterprise data, cloud, analytics, workflow, and healthcare information environments. Their competitive relevance increases as hospitals seek to connect device-generated data with broader enterprise systems.
Microsoft Corporation has emphasized secure cloud infrastructure and device availability in healthcare environments, reflecting the importance of resilient computing and data access to connected hospital operations.
Oracle Corporation is expanding its healthcare technology footprint across clinical, financial, supply-chain, and operational workflows. Its September 2025 healthcare supply-chain announcement, for example, introduced capabilities intended to provide real-time visibility into medical supplies.
Medtronic and Honeywell add further breadth. Medtronic's clinical technology portfolio provides a route into connected acute-care and monitoring environments, while Honeywell's healthcare activities include technologies supporting laboratory and diagnostic workflows. In July 2026, Medtronic and Apollo Hospitals announced an 11-bed “ICU of the Future” in Hyderabad featuring integrated Acute Care & Monitoring technologies and intended as a clinical innovation hub.
The competition model is consequently moving toward platform breadth and integration capability. Suppliers compete through interoperability, cybersecurity, device portfolios, analytics, cloud architecture, service contracts, local implementation, and the ability to preserve existing infrastructure.
Long-term partnerships are particularly important because hospital technology has long replacement cycles. A supplier that wins a multi-year enterprise agreement can gain access to multiple departments and influence subsequent technology decisions. Siemens Healthineers' July 2026 $87 million value partnership with Vanderbilt Health illustrates this model, combining technology upgrades, standardization, planning, installation support, service operations, and workforce development.
Recent Developments
July 2026: Medtronic and Apollo Hospitals inaugurated an 11-bed ICU of the Future in Hyderabad using integrated Acute Care & Monitoring technologies. The facility creates a reference environment for connected critical-care technology and clinical innovation in India.
April 2026: GE HealthCare announced digital integration between its bkActiv intraoperative ultrasound system and Medtronic's Stealth AXiS surgical navigation system, connecting real-time imaging with surgical navigation workflows. The development supports interoperability across connected operating-room technologies.
March 2026: GE HealthCare completed its acquisition of Intelerad for a base purchase price of $2.3 billion, expanding its enterprise imaging portfolio and cloud-first software capabilities. The transaction strengthens the supplier's position across connected imaging, SaaS, and hospital workflows.
Regulatory and Policy Environment
Regulation is becoming a direct commercial factor in hospital IoT procurement because connected systems combine medical-device regulation, health-data protection, cybersecurity, telecommunications, and software requirements.
In the United States, FDA cybersecurity requirements apply to qualifying cyber devices submitted for regulatory review. The February 2026 final guidance addresses cybersecurity considerations during device design and premarket submissions and supersedes the June 2025 version.
The FDA also emphasizes that manufacturers and healthcare delivery organizations share responsibility for managing cybersecurity risks. Connected devices must be treated as part of a broader hospital technology environment rather than as isolated medical products.
HIPAA remains important for hospital IoT deployments because connected devices and platforms may create, receive, maintain, or transmit electronic protected health information. The Security Rule requires administrative, physical, and technical safeguards addressing confidentiality, integrity, and availability.
Europe's EHDS Regulation introduces another major policy dimension. The framework is intended to improve cross-border access and control of electronic health data while establishing technical and legal conditions for interoperability. Its phased implementation means suppliers will need to consider future interoperability requirements during current product development and hospital procurement.
India is also strengthening the digital infrastructure surrounding healthcare data. ABDM establishes interoperable digital-health building blocks, while the Digital Health Incentive Scheme provides financial incentives for eligible facilities and digital solution providers adopting ABDM-compatible systems.
Cybersecurity guidance increasingly extends beyond the hospital campus. NIST's 2025 work on hospital-at-home environments highlights risks created when healthcare organizations connect medical-grade devices with consumer IoT systems outside direct institutional control. This increases the importance of network segmentation, identity management, secure authentication, monitoring, and governance in distributed care models.
For suppliers, compliance is therefore becoming part of product differentiation. Hospitals are likely to favor vendors that can provide documentation, security controls, lifecycle management, interoperability evidence, and clear responsibilities for vulnerability remediation.
Outlook and Strategic Implications
The 2026–2031 outlook for IoT in smart hospitals will be shaped less by the number of connected devices than by the ability of hospitals to convert device-generated information into operational and clinical value.
Procurement is likely to move toward integrated technology programs. Hospitals increasingly have reasons to connect patient monitors, equipment, clinical systems, inventory, facilities, and operational dashboards through common infrastructure. This favors suppliers that can provide interoperable architectures rather than isolated products.
Investment priorities should concentrate on applications with measurable economic or clinical outcomes. Equipment tracking can reduce unnecessary asset purchases and staff search time. Connected monitoring can improve visibility of selected patient populations. Inventory systems can improve supply availability. Smart infrastructure can reduce operational inefficiencies. These applications provide clearer procurement justification than connectivity projects without defined performance metrics.
Cybersecurity will remain a decisive investment area. The regulatory direction in the United States and Europe, combined with the risks identified by NIST, means hospitals cannot treat security as an optional layer added after deployment. Security architecture, device identity, network segmentation, vulnerability management, authentication, software lifecycle controls, and incident response will increasingly form part of the original procurement specification.
Interoperability will similarly become more important as hospitals attempt to reduce the number of disconnected technology environments. Suppliers that support recognized connectivity and data-exchange standards can improve their position in enterprise tenders. Philips' work around Service-Oriented Device Connectivity provides an example of how standards-based interoperability can support multi-vendor clinical environments.
The competitive model is also likely to favor long-term commercial relationships. Hospitals face high switching costs once connected platforms become embedded in clinical workflows. Suppliers can therefore compete through technology roadmaps, service agreements, financing, upgrade programs, implementation expertise, and measurable operational outcomes.
Cloud-based architectures will support greater scalability, but hospitals will continue to balance cloud adoption against data sovereignty, latency, cybersecurity, resilience, and clinical continuity requirements. Hybrid architectures are likely to remain commercially relevant where critical clinical functions require local processing or high availability.
Asia Pacific should remain a major deployment opportunity because healthcare systems in several countries are expanding digital infrastructure while seeking better access and operational efficiency. India's ABDM ecosystem demonstrates how national digital-health infrastructure can create an enabling environment for connected healthcare systems.
North America and Europe will remain important for higher-value enterprise deployments because hospitals in these regions have mature digital infrastructure and established procurement processes. The Middle East can offer large project opportunities through new hospital construction and healthcare modernization, while South America will likely favor targeted applications with demonstrable economic returns.
The principal strategic risk is that hospitals may accumulate connected devices without achieving interoperability or workflow improvement. Vendors that sell endpoints without addressing integration, cybersecurity, implementation, and lifecycle support may face greater procurement scrutiny.
The strongest commercial opportunity therefore lies in becoming part of the hospital's operating architecture rather than simply supplying another connected device. Suppliers that combine reliable hardware, secure connectivity, interoperable software, analytics, implementation services, and long-term support can address a larger portion of hospital capital and operating budgets.
IoT In Smart Hospitals Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 52.8 billion |
| Total Market Size in 2031 | USD 164.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 25.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Connectivity, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Component
By Connectivity
By Application
By End User
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Key Findings
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies, Regulations, and Standards
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Introduction
4.2. Sensors and Connected Medical Devices
4.3. Edge Computing
4.4. Cloud Computing
4.5. Artificial Intelligence and Analytics
4.6. Digital Twins
4.7. Interoperability and Data Integration
4.8. Cybersecurity
4.9. Real-Time Location Systems
5. IOT IN SMART HOSPITALS MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
6. IOT IN SMART HOSPITALS MARKET BY CONNECTIVITY
6.1. Introduction
6.2. Wi-Fi
6.3. Bluetooth/Bluetooth Low Energy
6.4. Cellular/5G
6.5. RFID
6.6. Zigbee
6.7. LPWAN
6.8. Ethernet and Other Wired Connectivity
6.9. Others
7. IOT IN SMART HOSPITALS MARKET BY APPLICATION
7.1. Introduction
7.2. Remote Patient Monitoring
7.3. Medication Management
7.4. Asset and Equipment Tracking
7.5. Patient and Staff Monitoring
7.6. Connected Operating Rooms and Surgical Systems
7.7. Smart Hospital Infrastructure
7.8. Inventory and Supply Management
7.9. Infection Control and Environmental Monitoring
7.10. Others
8. IOT IN SMART HOSPITALS MARKET BY END USER
8.1. Introduction
8.2. General Hospitals
8.3. Specialty Hospitals
8.4. Teaching and Academic Hospitals
8.5. Other Healthcare Facilities
9. IOT IN SMART HOSPITALS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Component
9.2.2. By Connectivity
9.2.3. By Application
9.2.4. By End User
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Component
9.3.2. By Connectivity
9.3.3. By Application
9.3.4. By End User
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Colombia
9.3.5.4. Chile
9.3.5.5. Others
9.4. Europe
9.4.1. By Component
9.4.2. By Connectivity
9.4.3. By Application
9.4.4. By End User
9.4.5. By Country
9.4.5.1. Germany
9.4.5.2. France
9.4.5.3. United Kingdom
9.4.5.4. Italy
9.4.5.5. Spain
9.4.5.6. Netherlands
9.4.5.7. Others
9.5. Middle East and Africa
9.5.1. By Component
9.5.2. By Connectivity
9.5.3. By Application
9.5.4. By End User
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. United Arab Emirates
9.5.5.3. Israel
9.5.5.4. South Africa
9.5.5.5. Others
9.6. Asia Pacific
9.6.1. By Component
9.6.2. By Connectivity
9.6.3. By Application
9.6.4. By End User
9.6.5. By Country
9.6.5.1. China
9.6.5.2. India
9.6.5.3. Japan
9.6.5.4. South Korea
9.6.5.5. Australia
9.6.5.6. Indonesia
9.6.5.7. Thailand
9.6.5.8. Taiwan
9.6.5.9. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Product and Technology Developments
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Koninklijke Philips N.V.
11.2. Siemens Healthineers AG
11.3. GE HealthCare Technologies Inc.
11.4. Cisco Systems, Inc.
11.5. IBM
11.6. Medtronic plc
11.7. Honeywell International Inc.
11.8. Oracle Corporation
11.9. Microsoft Corporation
11.10. SAP SE
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for the Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











