
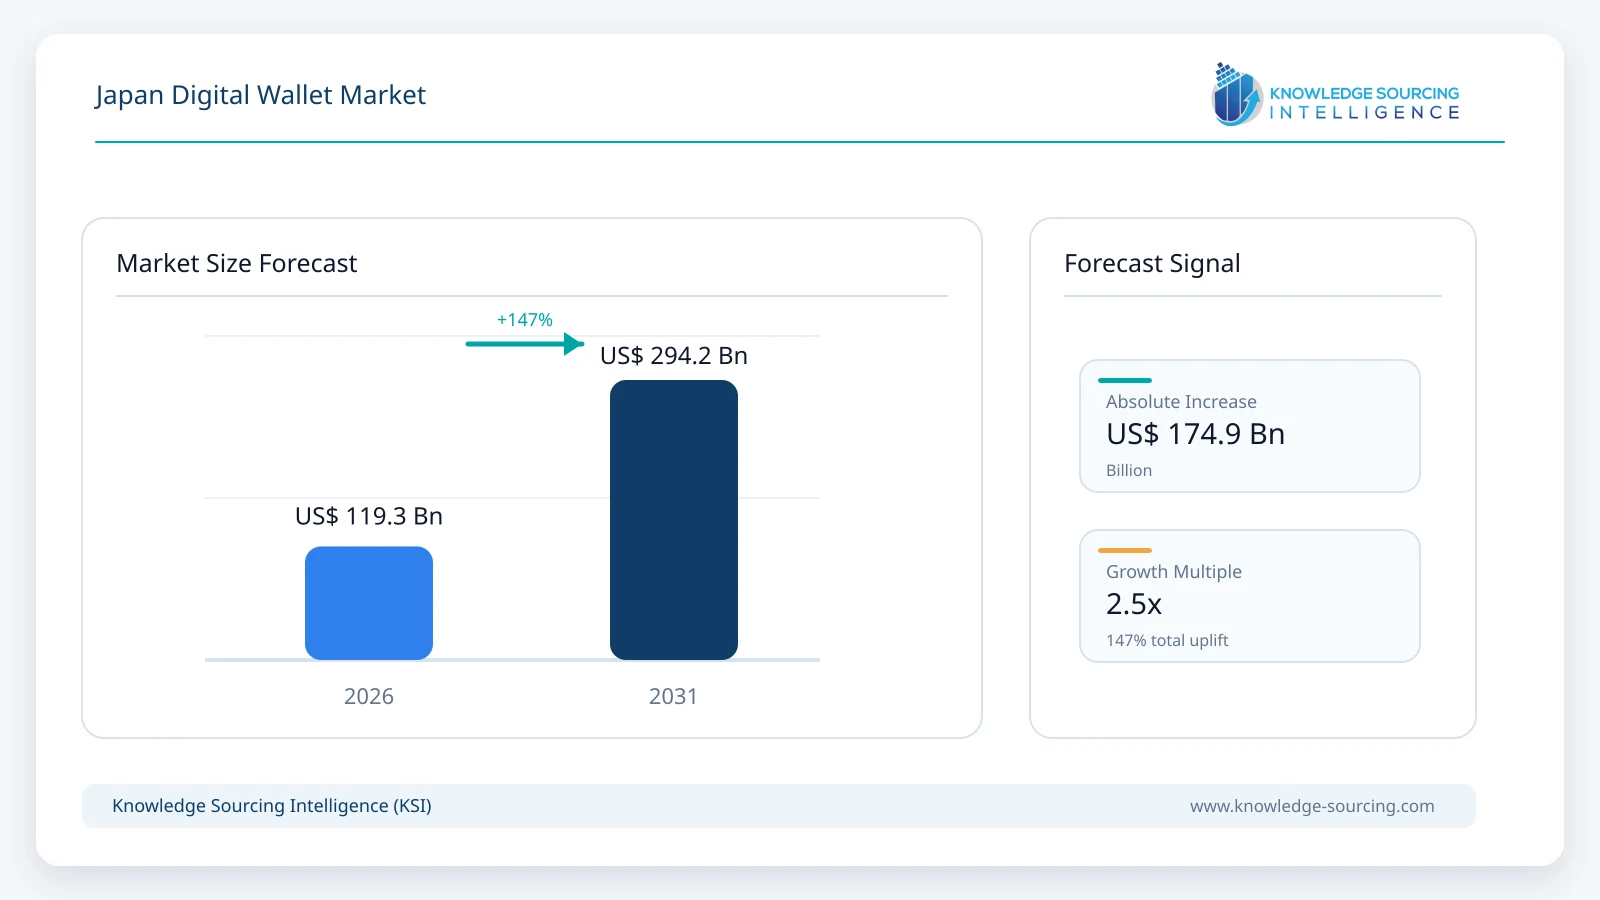
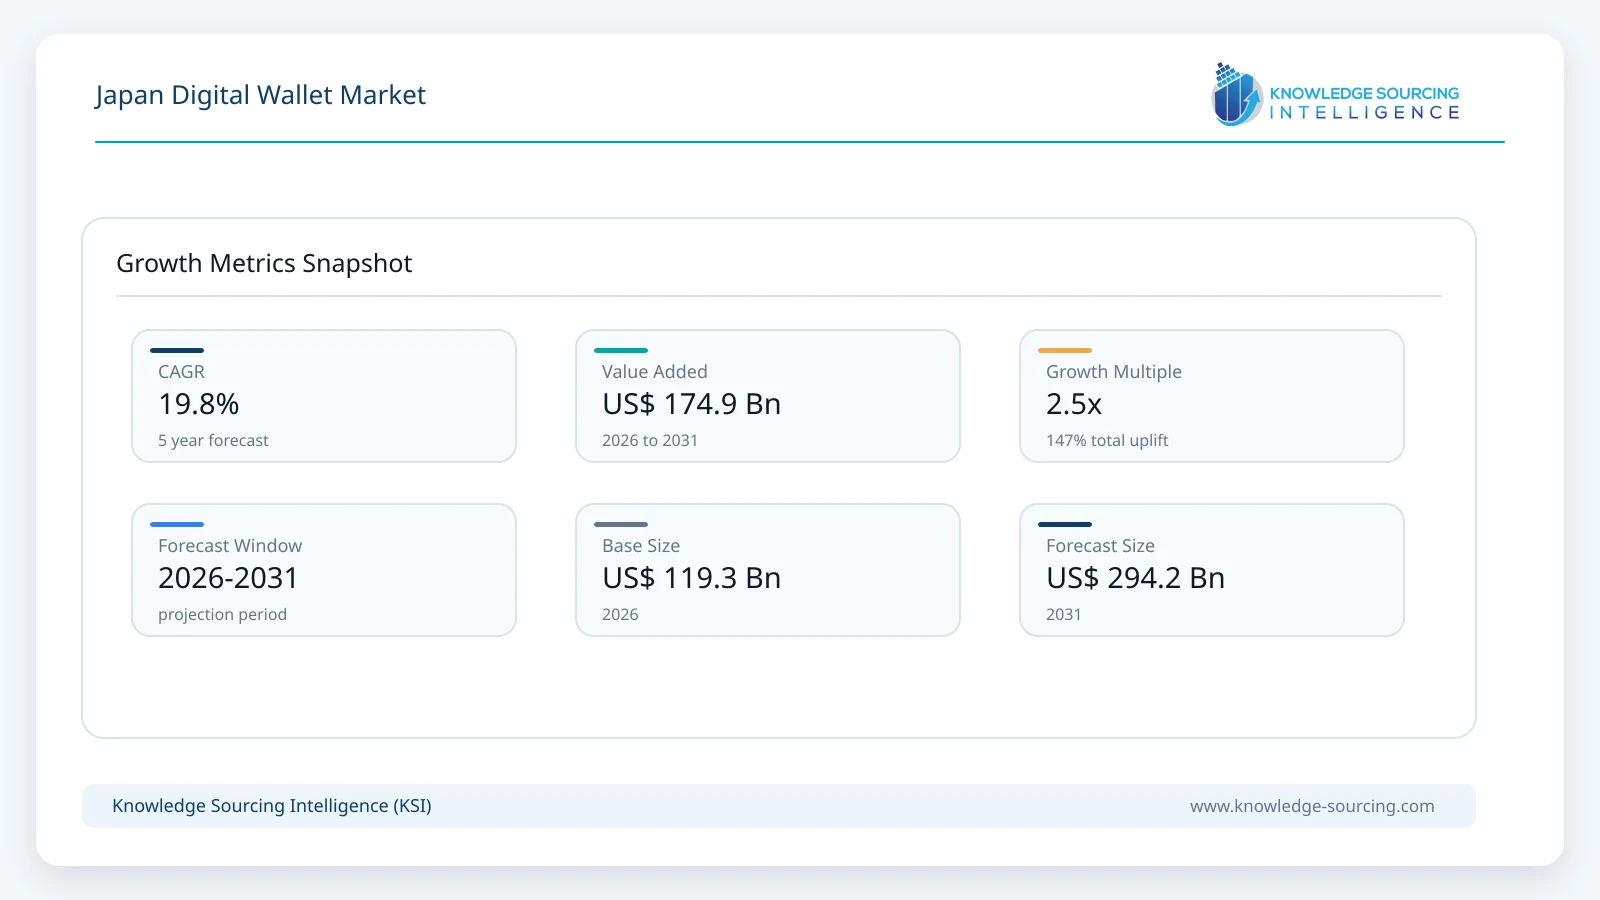
Japan Digital Wallet Market is anticipated to grow at a CAGR of 19.8%, increasing to USD 294.2 billion in 2031 from USD 119.3 billion in 2026.
Highlights:
- 1Japan's digital wallet market is supported by sustained government efforts to expand cashless payments across retail and public services.
- 2Smartphone-based wallets remain the primary access channel, supported by widespread NFC infrastructure and QR code payment acceptance.
- 3Retail and e-commerce payments account for the largest share of transaction activity, driven by consumer convenience and merchant incentives.
- 4Competition increasingly centers on ecosystem integration, loyalty programs, financial services, and merchant acquisition rather than payment functionality alone.
- 5Regulatory oversight, cybersecurity requirements, and interoperability initiatives continue to influence product development and platform expansion.
Demand is increasingly shaped by merchant acceptance, integrated financial services, consumer reward programs, and government policies promoting cashless payments. The customer base extends beyond traditional retail shoppers. Digital wallets are now widely used across supermarkets, convenience stores, transportation systems, online marketplaces, restaurants, hospitality services, and government-supported digital payment initiatives. Buyers increasingly evaluate wallet providers on transaction speed, security, interoperability, loyalty benefits, compatibility with existing banking relationships, and integration with everyday digital services rather than payment capability alone.
Government policy continues to provide an important demand foundation. According to Japan's Ministry of Economy, Trade and Industry (METI), the country's cashless payment ratio reached 58.0% of total private consumption expenditure in 2025, exceeding the government's previous policy target of 40% and moving toward the next objective of approximately 65% by 2030. Growth has been supported by QR code payment adoption, broader merchant acceptance, and continued investment in payment infrastructure.
Value creation increasingly extends beyond transaction processing. Digital wallet providers compete by combining payments with loyalty ecosystems, investment services, consumer lending, insurance products, digital identity, transit ticketing, and merchant marketing tools. This shift raises customer retention while creating additional revenue streams beyond payment fees. At the same time, platform operators continue investing in fraud prevention, cybersecurity, regulatory compliance, and cloud infrastructure to maintain user trust as transaction volumes increase.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Cashless payment ratio | 58.0% (2025) | Demonstrates continued migration from cash to digital payments across consumer transactions. |
Government cashless target | Approx. 65% by 2030 | Supports long-term investment in payment acceptance infrastructure and digital payment ecosystems. |
Smartphone penetration | Above 90% of households (Ministry of Internal Affairs and Communications) | Provides the primary hardware platform for digital wallet adoption. |
Real-time payment infrastructure | Zengin System nationwide banking network | Enables rapid fund transfers supporting wallet-linked financial services. |
Contactless transit infrastructure | Extensive nationwide deployment of IC card systems including Suica and PASMO | Encourages frequent everyday digital payment behaviour beyond retail purchases. |
Key Indicator: METI reported that cashless payments accounted for 58.0% of private consumption expenditure in 2025.
Commercial meaning: Higher cashless adoption expands transaction opportunities for wallet providers while increasing competition for active users rather than first-time adopters.
Market Drivers
Government policies supporting nationwide cashless payment adoption
Japan's digital payment ecosystem continues to benefit from sustained government initiatives designed to reduce cash dependence, improve payment efficiency, and support economic digitalization. METI's successive cashless promotion strategies have encouraged wider merchant acceptance while local governments increasingly use digital payment campaigns to stimulate regional consumption. Public-sector encouragement has reduced adoption barriers for smaller merchants that historically relied on cash transactions. The resulting expansion of acceptance networks creates stronger incentives for consumers to use digital wallets across routine purchases, improving transaction frequency rather than relying solely on new user acquisition.
Retail and e-commerce merchants increasingly integrate wallet-based payment options
Merchant procurement priorities increasingly favor payment platforms capable of shortening checkout times while linking transactions with loyalty programs, digital coupons, customer analytics, and promotional campaigns. Large retail chains, convenience stores, supermarkets, and online marketplaces continue expanding acceptance of QR code and NFC-based payments because digital transactions reduce cash handling costs and simplify reconciliation. Company disclosures from PayPay, Rakuten, and NTT DOCOMO indicate continued investment in merchant acquisition, consumer rewards, and integrated commerce ecosystems rather than standalone payment services. As merchants consolidate payment acceptance around widely used platforms, network effects reinforce customer retention and transaction growth across both online and physical retail environments.
Integrated financial ecosystems increase customer lifetime value
Digital wallets increasingly function as gateways to broader financial services instead of remaining dedicated payment applications. Platform providers now combine payment accounts with banking, securities trading, consumer finance, insurance products, reward programs, subscription management, and digital identity services. Rakuten continues integrating payment services with its broader membership ecosystem, while telecom operators such as NTT DOCOMO and KDDI leverage their customer bases to expand financial offerings alongside mobile services. These ecosystem strategies encourage users to maintain balances, conduct recurring transactions, and engage with multiple financial products, improving customer retention while diversifying provider revenue beyond payment processing fees.
Market Restraints and Challenges
Intensifying competition reduces transaction margins and customer acquisition efficiency
Japan's digital wallet market has become increasingly competitive as technology companies, telecommunications operators, financial institutions, and international payment providers pursue overlapping customer segments. Aggressive reward campaigns, cashback incentives, and merchant subsidies have improved user acquisition but also increased operating costs. Company financial disclosures across several wallet providers indicate continued spending on marketing, merchant incentives, and ecosystem expansion to maintain transaction volumes. As market penetration rises, providers increasingly compete for transaction frequency and customer retention instead of first-time adoption, placing continued pressure on profitability and customer acquisition costs.
Cybersecurity threats and fraud prevention requirements continue to expand operational costs
Growing transaction volumes require continuous investment in fraud detection, authentication technologies, cybersecurity infrastructure, and regulatory compliance. Digital wallet operators process sensitive payment credentials and personal information, making them frequent targets for phishing attacks, account takeover attempts, and payment fraud. Japan's regulatory framework requires payment service providers to strengthen operational resilience and consumer protection, increasing compliance obligations alongside technological investment. These requirements particularly affect smaller providers with limited financial resources, while larger platforms benefit from greater scale in cybersecurity spending and fraud management capabilities.
Dependence on interoperability and legacy payment infrastructure
Although Japan has one of the world's most sophisticated electronic payment environments, interoperability remains an operational challenge because digital wallets must function across multiple payment technologies, banking networks, transport IC systems, card schemes, and merchant platforms. Providers continue investing in application programming interfaces (APIs), cloud infrastructure, and payment gateways to maintain seamless user experiences. Smaller merchants and regional businesses may delay upgrades because terminal replacement and software integration require additional investment. These compatibility requirements lengthen deployment timelines and increase implementation costs, particularly for providers expanding into specialized merchant categories or public-sector payment systems.
An ageing population creates uneven adoption across customer segments
Japan's demographic profile continues to influence payment behaviour. Younger consumers readily adopt mobile-first payment platforms, while older demographics often maintain stronger preferences for cash or traditional banking channels despite wider digital payment acceptance. The Bank of Japan has repeatedly noted that cash remains an important payment instrument alongside electronic alternatives. Wallet providers therefore face the dual challenge of expanding digital adoption while maintaining simple interfaces, accessible customer support, and high levels of transaction reliability. This demographic divide is structural rather than temporary, requiring long-term investment in financial literacy, user education, and inclusive product design instead of relying solely on promotional incentives.
Major Segment Analysis
Retail and E-commerce Payments
Retail and e-commerce payments represent the most commercially important application segment because they account for the highest frequency of consumer transactions and generate recurring payment activity across physical stores and digital commerce platforms. Daily purchases at convenience stores, supermarkets, pharmacies, restaurants, department stores, and online marketplaces provide wallet providers with repeated customer engagement, allowing them to strengthen loyalty ecosystems while generating additional revenue through merchant services, advertising, financial products, and data-driven promotions.
Merchant purchasing priorities increasingly extend beyond payment acceptance. Large retailers evaluate wallet providers based on settlement speed, transaction reliability, customer rewards, integration with inventory and point-of-sale systems, and the ability to support omnichannel commerce. Companies such as PayPay, Rakuten Pay, au PAY, and d Payment continue expanding merchant partnerships by combining payment services with loyalty programmes, digital coupons, and consumer financing. Competition therefore depends less on payment processing capability and more on ecosystem value, merchant support, and customer retention. Smaller application categories, including peer-to-peer transfers and mobile recharges, continue expanding but generally produce lower transaction volumes and weaker merchant network effects than retail commerce.
Competitive Landscape
Competition within Japan's digital wallet market is best characterised as ecosystem-led and service-intensive rather than purely price-driven. Domestic platforms benefit from established relationships with merchants, telecommunications subscribers, financial institutions, and loyalty programme members, while international technology companies compete by integrating payment capabilities into widely used consumer devices and operating systems. Customer retention increasingly depends on the breadth of digital services surrounding the payment function instead of transaction capability alone.
PayPay Corporation has expanded its merchant network and QR-code payment ecosystem through continuous investment in merchant acquisition and consumer rewards. Rakuten Group integrates wallet services with e-commerce, banking, securities, travel, and its loyalty programme, creating strong cross-platform engagement. NTT DOCOMO and KDDI (au PAY) leverage large telecommunications subscriber bases to distribute financial services and encourage recurring wallet usage. Apple and Google compete through secure mobile operating system integration and NFC-based contactless payments, while PayPal remains strongest in cross-border digital commerce and online merchant acceptance.
Barriers to entry continue to increase as providers invest in cybersecurity, fraud management, merchant acceptance infrastructure, regulatory compliance, cloud platforms, and ecosystem partnerships. These investments favour companies capable of sustaining long-term capital expenditure while maintaining broad service portfolios and trusted consumer brands.
Recent Developments
September 2026: NTT DOCOMO launched digital e-gift purchases through d?? Mobile Order, enabling users to buy Google Play gift codes directly within the d?? app from September 1.
June 2026: PayPay expanded tourism payment interoperability, announcing that 80% of Japan’s international visitors could pay through PayPay using payment services from their home countries.
May 2026: Rakuten began renaming Rakuten Cash balances as “Rakuten Pay Balance,” starting within the Rakuten Pay app on May 18 to provide a more unified payment experience across its ecosystem.
Regulatory and Policy Environment
Japan's regulatory framework for digital wallets continues to evolve alongside broader financial digitalization initiatives. Oversight is shared among the Financial Services Agency (FSA), the Ministry of Economy, Trade and Industry (METI), the Bank of Japan, and other authorities responsible for payment systems, consumer protection, cybersecurity, and competition policy. Digital wallet providers operating payment services must comply with the Payment Services Act, the Act on the Protection of Personal Information (APPI), and anti-money laundering (AML) and counter-terrorist financing (CTF) requirements. These rules govern fund transfers, safeguarding of customer assets, identity verification, operational resilience, and incident reporting.
Government policy remains an important demand catalyst. METI continues promoting cashless payments through national policy initiatives intended to improve productivity, strengthen digital commerce, and reduce dependence on cash transactions. According to METI, Japan's cashless payment ratio reached 58.0% in 2025, while the government continues pursuing a long-term objective of raising the ratio to approximately 65% by 2030. These policies encourage merchants to adopt digital payment infrastructure and create favourable conditions for continued wallet usage across retail, transportation, hospitality, and public services.
Cybersecurity and consumer protection requirements are becoming increasingly important as transaction volumes expand. Digital wallet providers continue strengthening multi-factor authentication, fraud monitoring, encryption technologies, and real-time transaction analysis to comply with regulatory expectations and maintain consumer confidence. Financial institutions and payment operators also work closely with industry associations to improve interoperability, payment security, and operational resilience across Japan's digital payment ecosystem.
Outlook and Strategic Implications
Japan's digital wallet market is expected to transition from an expansion phase driven primarily by user acquisition toward one focused on increasing transaction frequency, ecosystem integration, and higher-value financial services. As cashless payments become increasingly embedded in everyday consumer behaviour, competitive advantage will depend less on attracting first-time users and more on maintaining active customer engagement across multiple payment and financial activities. Providers capable of combining payments with banking, investment, lending, insurance, loyalty programmes, mobility services, and digital identity functions are likely to improve customer retention while diversifying revenue sources beyond transaction fees.
Merchant requirements are also evolving. Large retailers increasingly seek payment partners capable of integrating loyalty management, customer analytics, digital marketing, inventory systems, and omnichannel commerce into unified platforms. This trend favours providers with strong software capabilities, broad merchant support networks, and established relationships across financial and telecommunications ecosystems. Smaller providers may increasingly pursue partnerships or specialised market niches rather than competing directly with large platform operators on scale.
Several strategic considerations are likely to influence market performance during the forecast period:
Platform ecosystems will become a stronger competitive differentiator than standalone payment functionality.
Artificial intelligence and data analytics will improve fraud detection, customer personalisation, and merchant marketing effectiveness.
Embedded financial services will expand wallet functionality through lending, investment, insurance, and subscription management.
Regulatory compliance and cybersecurity investment will remain essential operating priorities as transaction values and digital identities become more closely connected.
Merchant digitisation among small and medium-sized enterprises will continue expanding wallet acceptance beyond large urban retail chains, supporting broader transaction growth across regional markets.
The market's commercial outlook therefore depends not only on continued cashless payment adoption but also on providers' ability to create integrated digital ecosystems that support consumers, merchants, financial institutions, and public-sector services within a secure and interoperable payment environment. Continued policy support, high smartphone penetration, established payment infrastructure, and sustained investment by both domestic and international platform providers provide favourable conditions for further market development between 2026 and 2031, although competition is expected to become increasingly centred on service quality, ecosystem depth, operational resilience, and long-term customer value rather than payment processing alone.
Japan Digital Wallet Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 119.3 billion |
| Total Market Size in 2031 | USD 294.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Device, Application |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Device
Smartphones
Wearables (Apple Watch, Garmin, etc.)
Tablets
Others (including PCs/Laptops)
By Application
Retail and E-commerce Payments
Bill Payments
Mobile Recharge
Transportation and Transit Payments
Hospitality and Entertainment
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.3. Market Definition
1.4. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. JAPAN DIGITAL WALLET MARKET ANALYSIS, BY DEVICE
5.1. Introduction
5.2. Smartphones
5.3. Wearables (Apple Watch, Garmin, etc.)
5.4. Tablets
5.5. Others (including PCs/Laptops)
6. JAPAN DIGITAL WALLET MARKET ANALYSIS, BY APPLICATION
6.1. Introduction
6.2. Retail and E-commerce Payments
6.4. Bill Payments
6.5. Mobile Recharge
6.6. Transportation and Transit Payments
6.7. Hospitality and Entertainment
6.8. Others
7. COMPETITIVE ENVIRONMENT AND ANALYSIS
7.1. Major Players and Strategy Analysis
7.2. Emerging Players and Market Lucrativeness
7.3. Mergers, Acquisitions, Agreements, and Collaborations
7.4. Vendor Competitiveness Matrix
8. COMPANIES PROFILES
8.1. PayPay Corporation
8.2. Rakuten Group, Inc.
8.3. PayPal
8.4. Apple Inc.
8.5. NTT DOCOMO, Inc.
8.6. KDDI Corporation (au PAY)
8.7. SoftBank Corp.
8.8. Google LLC (Google Pay)





Frequently asked questions
What is the projected market size and growth rate for the Japan Digital Wallet Market between 2026 and 2031?
The Japan Digital Wallet Market is anticipated to grow at a CAGR of 19.8% during the forecast period. It is projected to increase significantly from USD 119.3 billion in 2026 to reach USD 294.2 billion by 2031, indicating substantial market expansion.
Which sectors are primarily driving transaction activity within Japan's digital wallet market, and what are the key supporting factors?
Retail and e-commerce payments account for the largest share of transaction activity, driven by consumer convenience and merchant incentives. This growth is strongly supported by sustained government efforts to expand cashless payments, widespread smartphone-based wallet usage, and robust NFC infrastructure coupled with QR code payment acceptance.
How are digital wallet providers in Japan differentiating themselves and competing beyond basic payment functionality?
Competition increasingly centers on ecosystem integration, loyalty programs, and the provision of integrated financial services such as investment, consumer lending, and insurance products. Providers are also focusing on merchant acquisition and value creation by combining payments with digital identity, transit ticketing, and merchant marketing tools.
What role do government policies and targets play in the future growth and development of the Japan Digital Wallet Market?
Government policy provides an important demand foundation, with Japan's Ministry of Economy, Trade and Industry (METI) setting a cashless payment ratio target of approximately 65% by 2030, building on the 58.0% achieved in 2025. These targets support long-term investment in payment acceptance infrastructure and the broader digital payment ecosystem.
What are the primary factors influencing consumer and merchant adoption of digital wallets in Japan?
Demand is increasingly shaped by widespread merchant acceptance, integrated financial services, and attractive consumer reward programs. Buyers evaluate wallet providers on transaction speed, security, interoperability, loyalty benefits, compatibility with existing banking relationships, and integration with everyday digital services, rather than payment capability alone.
Beyond traditional retail, what are the expanding applications and customer bases for digital wallets in Japan?
The customer base extends beyond traditional retail shoppers, with digital wallets now widely used across supermarkets, convenience stores, transportation systems, online marketplaces, restaurants, hospitality services, and various government-supported digital payment initiatives. This indicates a broad and diversified application landscape across daily life.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Japan Digital Wallet Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/japan-digital-wallet-market