MMA Adhesives Market - Strategic Insights and Forecasts (2026-2031)
MMA Adhesives Market Size, Share, Forecasts and Trends Analysis By Substrate (Metals, Composites, Plastics, Others), By End User (Transportation, Marine, Aerospace, Building and Construction, Energy and Power, Industrial and Other Applications), and Region
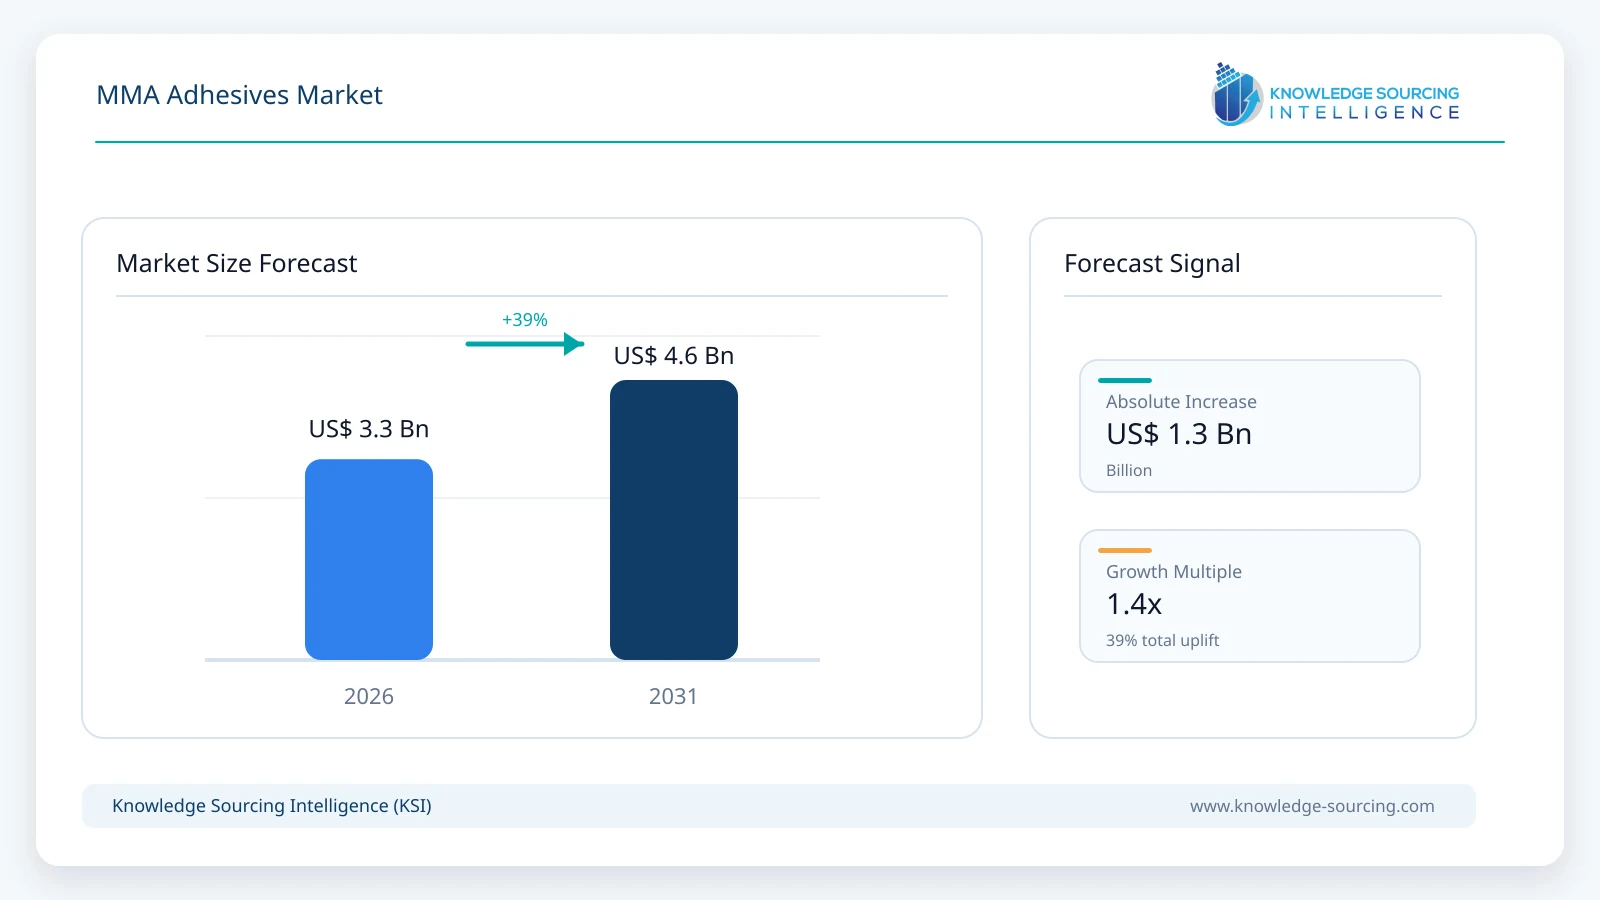
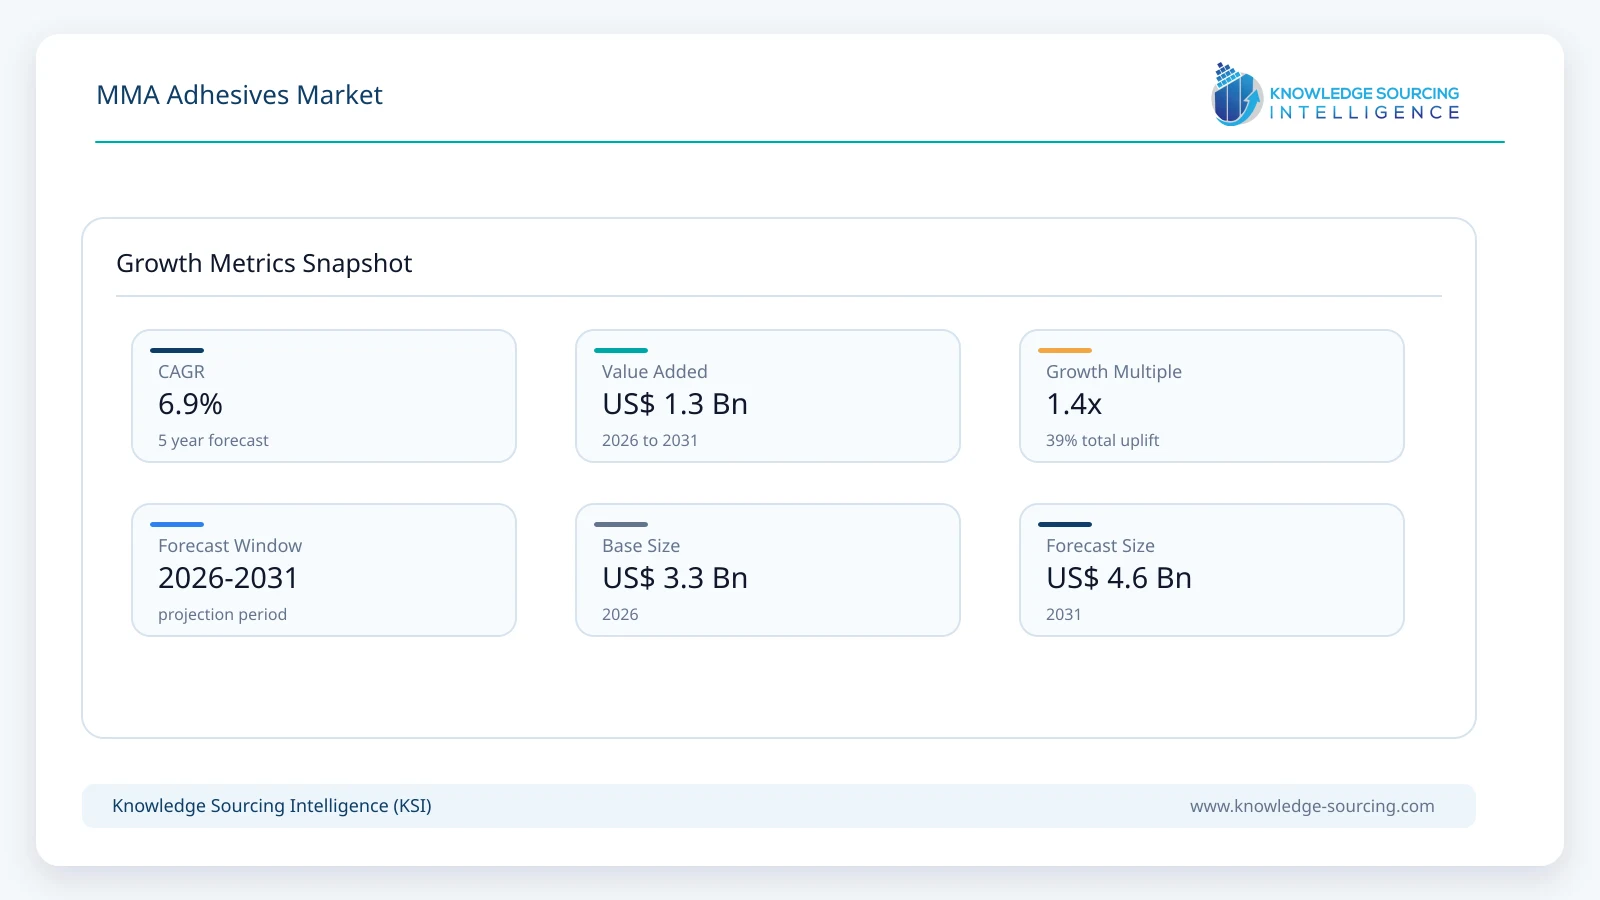
The methyl methacrylate (MMA) adhesives market, with a 6.9% CAGR, is set to grow to USD 4.56 billion in 2031 from USD 3.27 billion in 2026.
Highlights:
1
Metal substrates account for approximately 39% of global MMA adhesive revenue in 2026.
2
Composite bonding is projected to grow at approximately 8.7% annually through 2031.
3
Transportation applications generate approximately USD 1.11 billion of MMA adhesive demand in 2026.
4
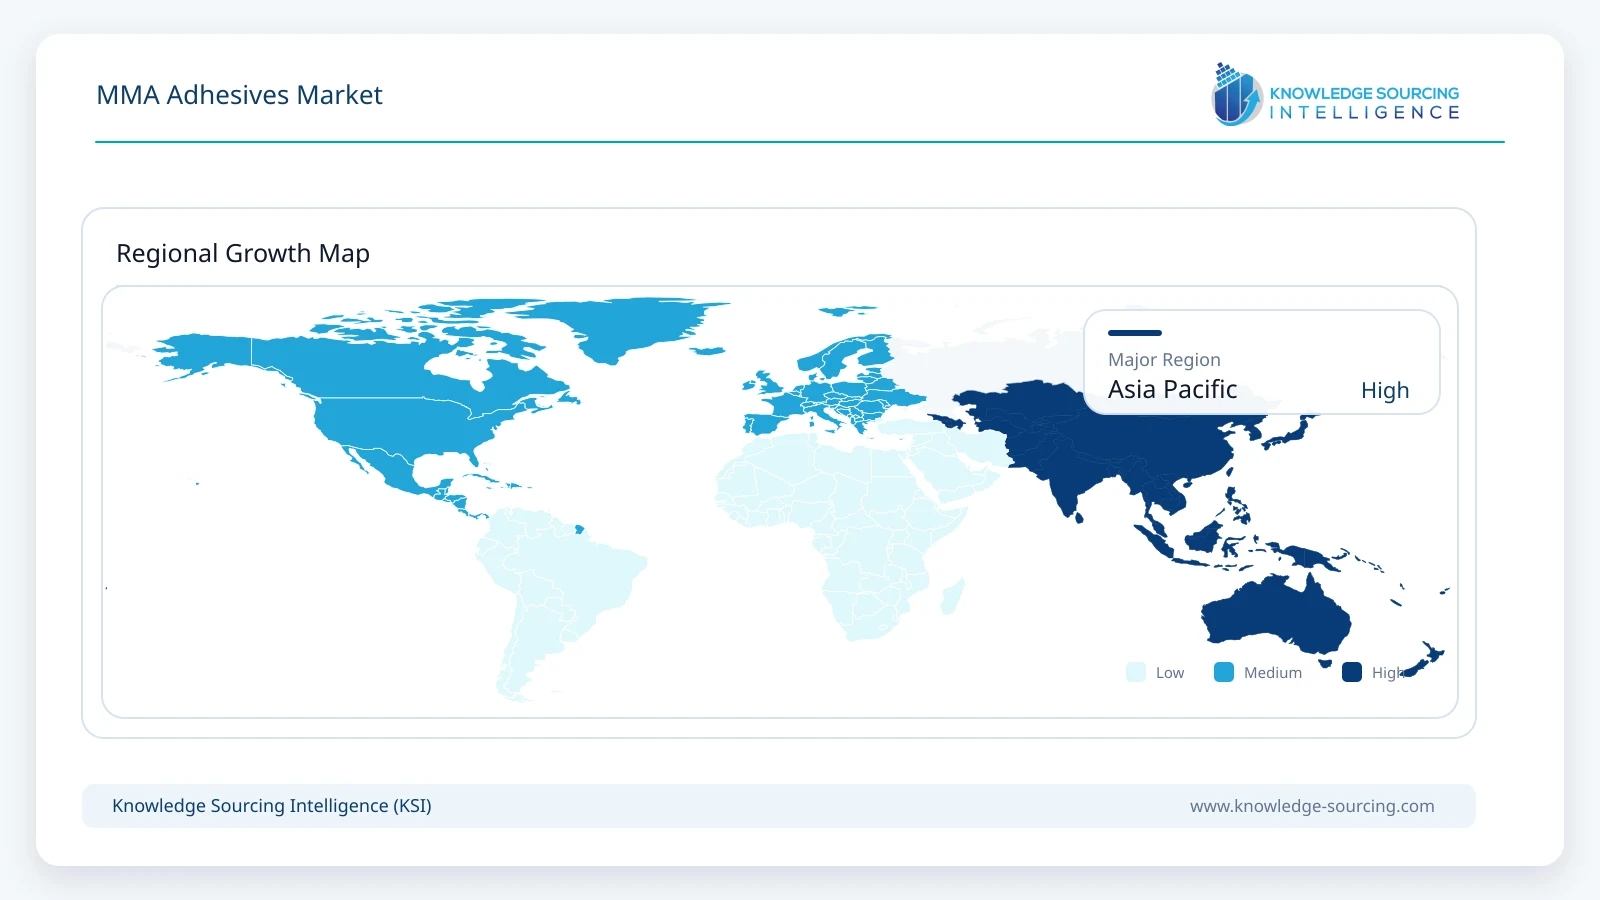
Asia Pacific accounts for approximately 43% of global MMA adhesive revenue in 2026.
5
Low-odor and controlled-open-time products are expanding MMA use in enclosed and larger assembly operations.
6
Lightweight multi-material construction is increasing structural bonding opportunities across mobility and renewable energy.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Overview
MMA adhesives are reactive acrylic structural adhesives in which resin and initiator components are combined to trigger polymerization. Industrial formulations are commonly supplied in 1:1 or 10:1 mixing ratios and can be engineered for short or extended working times, different viscosity profiles, flexibility and gap-filling requirements. Their primary value lies in combining rapid strength development with strong adhesion to dissimilar substrates. SikaFast products are designed for high-strength bonding of metals and plastics with limited surface preparation, while H.B. Fuller positions MMA technology across metals, composites and plastics as an alternative to screws, rivets and welding.
Manufacturers increasingly select an adhesive around the production process rather than ultimate bond strength alone. Large structures may require extended open time so operators can apply adhesive across longer bond lines before positioning components, whereas high-throughput lines may prioritize rapid fixture strength. Other considerations include bond-line thickness, exotherm, odor, elongation, substrate compatibility, operating temperature and resistance to impact or vibration. Bostik, Huntsman, Scott Bader, Permabond and other suppliers therefore offer portfolios with different open times, viscosities and mechanical profiles rather than a single general-purpose MMA grade.
Market Trends
Controlled cure profiles and low-odor formulations are becoming more important
The traditional commercial strength of MMA adhesives has been rapid curing, but manufacturers increasingly require greater control over the interval between adhesive application and fixture. Large vehicle panels, composite structures and marine assemblies need enough working time to dispense adhesive across longer bond lines before positioning components. Permabond launched TA4213 in July 2026 with a 20-minute open time and rapid strength development once parts are joined, illustrating how suppliers are separating working time from final production throughput. Low-odor formulations are also receiving greater attention because conventional MMA chemistry can create workplace ventilation and handling concerns in enclosed production environments.
Structural bonding is moving further into composite and mixed-material assemblies
The addressable market for MMA adhesives is widening as manufacturers combine aluminum, steel, thermoplastics, glass-fiber composites and carbon-fiber composites within the same structure. Conventional joining processes become more difficult when materials with different thermal properties or joining requirements are combined. Structural adhesives spread loads across the bonded surface and eliminate the need to drill many composite parts, making them useful in buses, trailers, recreational vehicles, marine structures, wind components and industrial equipment. Commercial portfolios from Sika, Huntsman, Kisling, Parson Adhesives and Scott Bader increasingly emphasize composite-to-metal and plastic-to-metal bonding.
Market Drivers
Lightweight transportation and multi-material vehicle manufacturing support structural bonding demand
Automotive, commercial vehicle, rail and specialty transportation manufacturers continue to reduce structural weight while increasing the use of aluminum, engineered plastics and composite materials. This raises the number of joints where conventional spot welding or mechanical fastening is inefficient or unsuitable. MMA adhesives benefit because they can bond dissimilar substrates, distribute mechanical loads and cure at room temperature without large heat-curing systems. Nearly 22 million electric cars were produced globally in 2025, more than 25% above the previous year, according to the International Energy Agency. EVs use multiple adhesive chemistries, but the expanding manufacturing base increases opportunities in body components, exterior assemblies, composite panels and commercial electric vehicles.
Composite-intensive marine and renewable energy structures expand large bond-line applications
Marine vessels, wind turbine components and other composite structures provide another important demand pool. Large composite parts often require long bond lines, gap filling and high resistance to fatigue, vibration, weathering and moisture. These requirements suit higher-performance MMA formulations, particularly products that combine extended working time with rapid fixture after assembly. The Global Wind Energy Council reported record wind turbine installations in 2025, expanding the equipment base for composite structural bonding. Marine applications are similarly relevant because hulls, decks, bulkheads and other structures increasingly combine fiberglass-reinforced composites, metals and engineered plastics.
MMA adhesives offer fast curing and broad substrate compatibility, but traditional products can produce a strong odor and require adequate ventilation, while uncured MMA formulations can be flammable. Polymerization is exothermic, which becomes important where thick adhesive masses are applied to heat-sensitive substrates. These characteristics can make epoxy, polyurethane or newer non-MMA structural acrylic systems more suitable for certain manufacturing environments. Suppliers are responding through lower-odor products, optimized mix ratios, controlled open times and lower-exotherm formulations, but customers still evaluate chemistry according to substrate, service temperature, production speed and workplace conditions.
Segment Analysis
By Substrate - Composites
Composite substrates are projected to generate approximately USD 1.39 billion in MMA adhesive revenue by 2031. Their growth is driven by the increasing use of glass-fiber and carbon-fiber reinforced materials in transportation, marine structures, wind equipment, recreational vehicles and other lightweight assemblies. MMA adhesives are particularly useful where composites must be bonded to aluminum, steel or thermoplastics because the joining process does not require drilling through the laminate or exposing the assembly to welding temperatures. Metals remain larger in current market value, while composites provide a faster-growing application base.
By End User - Transportation
Transportation is projected to grow at approximately 7.5% annually between 2026 and 2031, maintaining its position as the largest MMA adhesive end-user segment. Demand spans passenger and commercial vehicles, buses, coaches, trucks, trailers, recreational vehicles, rail equipment and specialty transportation systems. Manufacturers use structural MMA adhesives for exterior panels, flooring, roofs, body components, composite modules and other joints where dissimilar substrates or rapid manufacturing cycles make mechanical fastening less attractive. Marine and renewable-energy applications are expected to grow faster from smaller bases as composite structures expand.
By Geography - Asia Pacific
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Asia Pacific is projected to reach approximately USD 2.08 billion in MMA adhesive revenue by 2031. The region combines the world's largest automotive manufacturing base with growing electric vehicle production, shipbuilding, wind turbine manufacturing, rail equipment, construction materials and composite fabrication. China is particularly important because of its scale in EVs, transportation equipment and renewable-energy manufacturing, while India, Japan, South Korea and Southeast Asia provide additional industrial demand. North America remains important through commercial vehicles, recreational vehicles, marine applications and industrial fabrication, while Europe maintains strong demand from automotive, rail, marine and engineered-composite applications.
Competitive Environment
The MMA adhesive market includes large diversified adhesive manufacturers, specialist structural-bonding companies and regional formulators. ITW Performance Polymers competes through the Plexus portfolio, Scott Bader through Crestabond, Sika through SikaFast, and Arkema through Bostik structural MMA technologies. H.B. Fuller, SCIGRIP, Permabond, Huntsman, Henkel, Parson Adhesives and Kisling also offer methacrylate or closely related structural acrylic technologies for industrial assembly.
Product differentiation increasingly focuses on manufacturing requirements such as open time, fixture time, mix ratio, odor, exotherm, viscosity, elongation, bond-line thickness and compatibility with coated or minimally prepared substrates. Regional availability and application engineering matter because industrial customers typically qualify adhesives for specific substrate combinations and production processes. Suppliers able to conduct joint testing, automate dispensing, provide local inventory and modify formulations can therefore defend accounts even where several MMA products offer broadly similar published mechanical performance.
Recent Developments
September 2026: Sika completed the acquisition of Akkim, a Turkey-based adhesives and sealants manufacturer that generated approximately CHF 220 million in 2025 sales, expanding Sika's manufacturing and distribution footprint across Eastern Europe, Central Asia, the Middle East and North Africa.
July 2026: Permabond launched TA4213, a structural acrylic adhesive with a 20-minute open time and rapid strength development after assembly, targeting larger bonding areas and applications requiring longer positioning periods.
January 2026: Scott Bader appointed Sandtech as a distributor for its high-performance resins, gelcoats and structural adhesives across France, expanding local commercial and technical coverage.
2026: Structural adhesive suppliers continued expanding lower-odor and controlled-cure portfolios for transportation, composite and industrial assembly applications.