
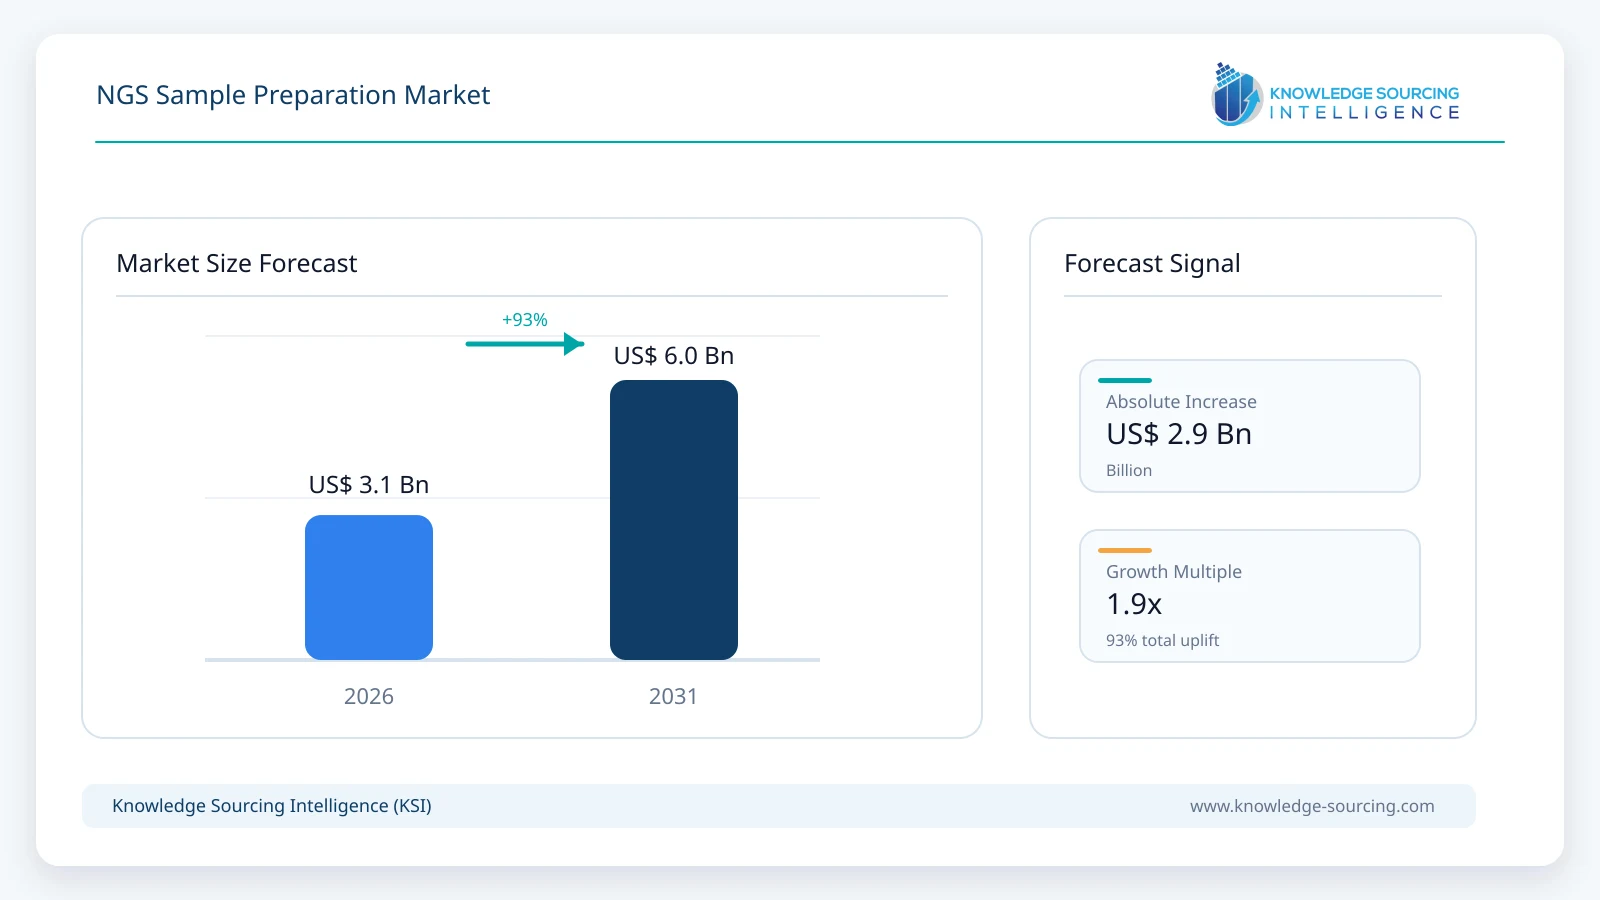
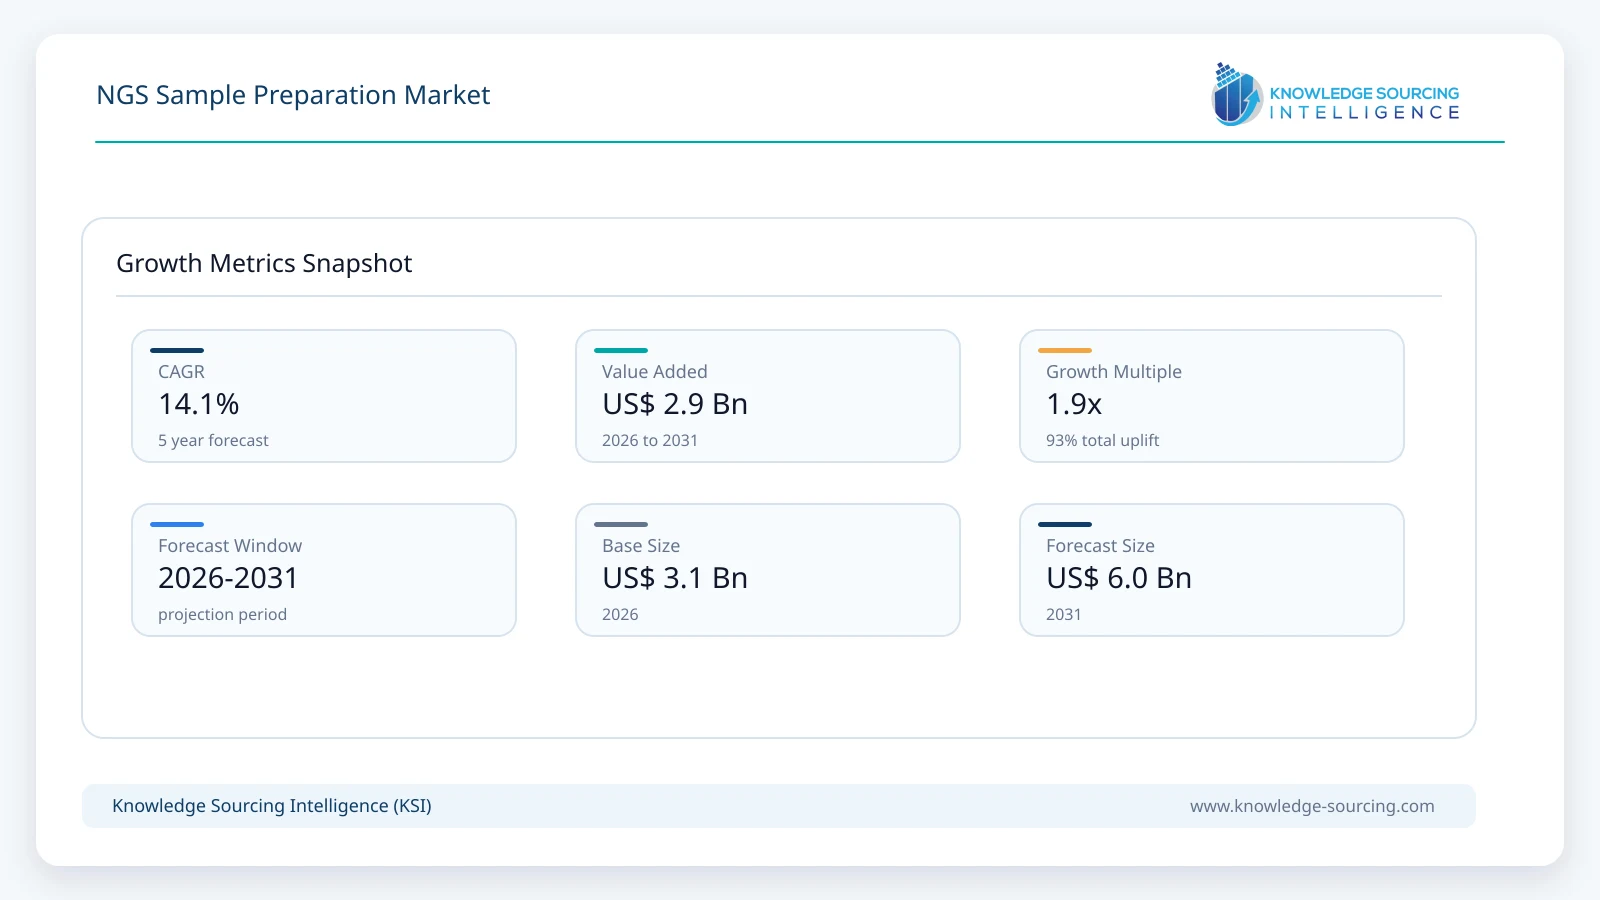
The global NGS sample preparation market is estimated at USD 3.08 billion in 2026 and is forecast to reach USD 5.95 billion in 2031, representing an implied CAGR of 14.1% over the period.
Highlights:
- 1Library preparation kits and reagents account for approximately 46.0% of global NGS sample preparation revenue in 2026, equivalent to about USD 1.54 billion.
- 2Oncology and cancer genomics represent approximately 32.0% of 2026 application revenue, or about USD 1.07 billion, because tissue, liquid-biopsy and comprehensive profiling workflows require repeated library construction and enrichment.
- 3Academic and research institutions account for approximately 38.0% of 2026 revenue, while clinical and diagnostic laboratories are the fastest-expanding end-user group as NGS becomes embedded in regulated testing workflows.
- 4North America represents approximately 42.0% of global 2026 revenue, equivalent to about USD 1.41 billion, supported by a large installed sequencing base, clinical genomics laboratories and biopharma research spending.
- 5Automation systems and workflow instruments remain smaller than reagent categories but are expected to grow faster as laboratories seek higher throughput, lower hands-on time and tighter reproducibility.
- 6The market is increasingly shaped by low-input DNA and RNA, FFPE and cfDNA workflows, long-read sequencing, multiomic library preparation and platform-agnostic automation.
Market Overview
The NGS sample preparation market covers products used to convert RNA/DNA into sequencing-ready libraries before a sequencing run. The scope includes fragmentation and end-repair chemistry, adapter ligation, indexing, amplification, target enrichment, cleanup and size-selection reagents, library quantification and quality-control products, and dedicated automation systems used primarily for NGS preparation. Generic nucleic-acid extraction products are included only where they are sold as an integrated or sequencing-specific workflow. Sequencing instruments, flow cells, downstream bioinformatics and general laboratory liquid handlers without a defined NGS-preparation use case are excluded.
This definition is important because sequencing consumables are substantially larger than sample-preparation revenue. Illumina alone reported USD 2.75 billion of sequencing consumables revenue outside China in 2025, but that figure includes flow cells and run reagents consumed inside the sequencer. Sample preparation sits upstream and is supplied by a broader vendor set that includes platform owners such as Illumina and Thermo Fisher as well as specialist chemistry providers such as New England Biolabs, Twist Bioscience, IDT, Roche KAPA, QIAGEN and Revvity.
The 2026 market estimate is triangulated from the size and utilization of the installed sequencing base, public vendor consumables data, list and contract pricing for library-preparation and enrichment reagents, reagent consumption per sample, clinical and research sequencing volumes, and revenue exposure of diversified genomics suppliers. This approach yields a market above USD 3 billion without treating sequencing flow-cell revenue as sample preparation. It also avoids double counting generic molecular-biology reagents that are not specifically consumed in NGS workflows.
Growth is not modeled as a flat annual CAGR. The forecast path is approximately USD 3.35 billion in 2026, USD 3.85 billion in 2027, USD 4.40 billion in 2028, USD 5.01 billion in 2029, USD 5.68 billion in 2030 and USD 6.42 billion in 2031. Growth moderates gradually as high-throughput short-read sequencing becomes more mature, while clinical genomics, population sequencing, long-read workflows, multiomics and automation continue to expand.
Sample preparation is becoming more strategically important as sequencing itself becomes faster and cheaper. A failed or biased library wastes downstream sequencing capacity, so laboratories increasingly prioritize conversion efficiency, uniform coverage, low duplication, sample traceability and reproducibility. This supports premium chemistry for difficult material such as FFPE DNA, cfDNA, ultra-low-input RNA and methylation-sensitive workflows, while also encouraging standardized automated protocols for higher-volume laboratories.
NGS Sample Preparation Market Trends
Automation Moves the Bottleneck Upstream
As sequencers process more samples per run, manual pipetting and incubation increasingly constrain laboratory throughput. Tecan, SPT Labtech and Volta Labs are positioning library preparation as a walkaway workflow, while reagent suppliers are validating their chemistries on multiple automation platforms. The value proposition is not only labor reduction: automation reduces sample-tracking errors, batch-to-batch variability and protocol drift, which becomes more important in clinical and high-throughput genomics.
Library Preparation Becomes More Platform-Agnostic
Historically, many laboratories purchased library preparation from the same vendor as the sequencer. That boundary is weakening. New England Biolabs, Twist Bioscience, Revvity, Roche, QIAGEN and IDT support multiple sequencing platforms, and automation vendors increasingly expose open methods for Illumina, PacBio and Oxford Nanopore workflows. This increases competition on conversion efficiency, bias, turnaround time and cost per sample rather than on platform lock-in alone.
Long-Read and Multiomic Workflows Expand the Addressable Market
Sample preparation is broadening beyond conventional short-read DNA sequencing. QIAGEN extended its target-enrichment portfolio into long-read sequencing in July 2025, while Illumina commercialized a 5-base workflow that combines genomic and methylation information in a single library-preparation process. These workflows require differentiated chemistry and often command higher value per sample, supporting revenue growth even as sequencing cost per base declines.
Low-Input and Degraded Samples Drive Premium Chemistry
Clinical oncology, liquid biopsy and archived tissue workflows often begin with limited or damaged nucleic acid. Suppliers are therefore competing on library yield from cfDNA, FFPE, single-cell and other low-input samples. Product development is shifting from generic library construction toward application-specific workflows that combine repair, fragmentation, molecular barcoding, target enrichment and quality controls to preserve scarce molecules.
Clinical Quality Control Becomes a Distinct Revenue Layer
The expansion of regulated NGS increases demand for traceable quality-control steps around nucleic-acid integrity and finished libraries. Agilent extended its TapeStation platform into CE-IVD-labeled clinical NGS sample quality control in September 2026. This illustrates how sample preparation is evolving from a research-only reagent category toward a broader workflow market that includes standardized QC instrumentation and software.
Segment Analysis
By Product - Library Preparation Kits and Reagents
Library preparation kits and reagents are estimated at approximately USD 1.54 billion in 2026, or 46.0% of the total market. The segment includes fragmentation, end repair, A-tailing, adapter ligation, indexing, amplification and application-specific library construction. It is the largest revenue pool because every sequencing sample must be converted into a compatible library and because reagents are recurring rather than capital purchases. Major suppliers include Illumina, Roche KAPA, New England Biolabs, Thermo Fisher, QIAGEN, Twist Bioscience, Revvity and Tecan.
Automation systems and dedicated sample-preparation instruments are estimated at approximately USD 0.27 billion in 2026. Although smaller, this is the fastest-growing product group and could approach USD 0.64 billion by 2031 as clinical and core laboratories shift from manual batching toward standardized walkaway methods.
By Application - Oncology and Cancer Genomics
Oncology and cancer genomics are estimated at approximately USD 1.07 billion in 2026. Targeted panels, comprehensive genomic profiling, liquid biopsy, residual-disease research and tumor-normal sequencing create high recurring use of library preparation, UMIs, hybrid capture and QC. Oncology also places a premium on difficult samples such as FFPE tissue and cfDNA, increasing average sample-preparation value.
Population and whole-genome sequencing programs are the fastest-expanding large application pool. Their economics depend on reducing preparation time and reagent cost per sample while preserving coverage uniformity, making PCR-free workflows, normalized pooling and automation important purchasing criteria.
By End User - Academic and Research Institutions
Academic and research institutions are estimated at approximately USD 1.27 billion in 2026, representing about 38.0% of market revenue. Universities, research institutes and core genomics facilities support diverse DNA-seq, RNA-seq, epigenetics, metagenomics and single-cell projects and therefore purchase a wide range of library-preparation chemistries rather than one standardized assay.
Clinical and diagnostic laboratories are expected to grow faster than the academic segment as sequencing moves into oncology, inherited disease, reproductive health and infectious-disease testing. Their requirements favor validated protocols, automation, traceable QC and reproducibility, raising spend per workflow even when sequencing cost per base declines.
By Geography - North America
North America is estimated at approximately USD 1.41 billion in 2026. The region combines a large installed sequencing base, major genomics vendors, high biopharma R&D spending, national research programs and a dense network of clinical and academic sequencing laboratories.
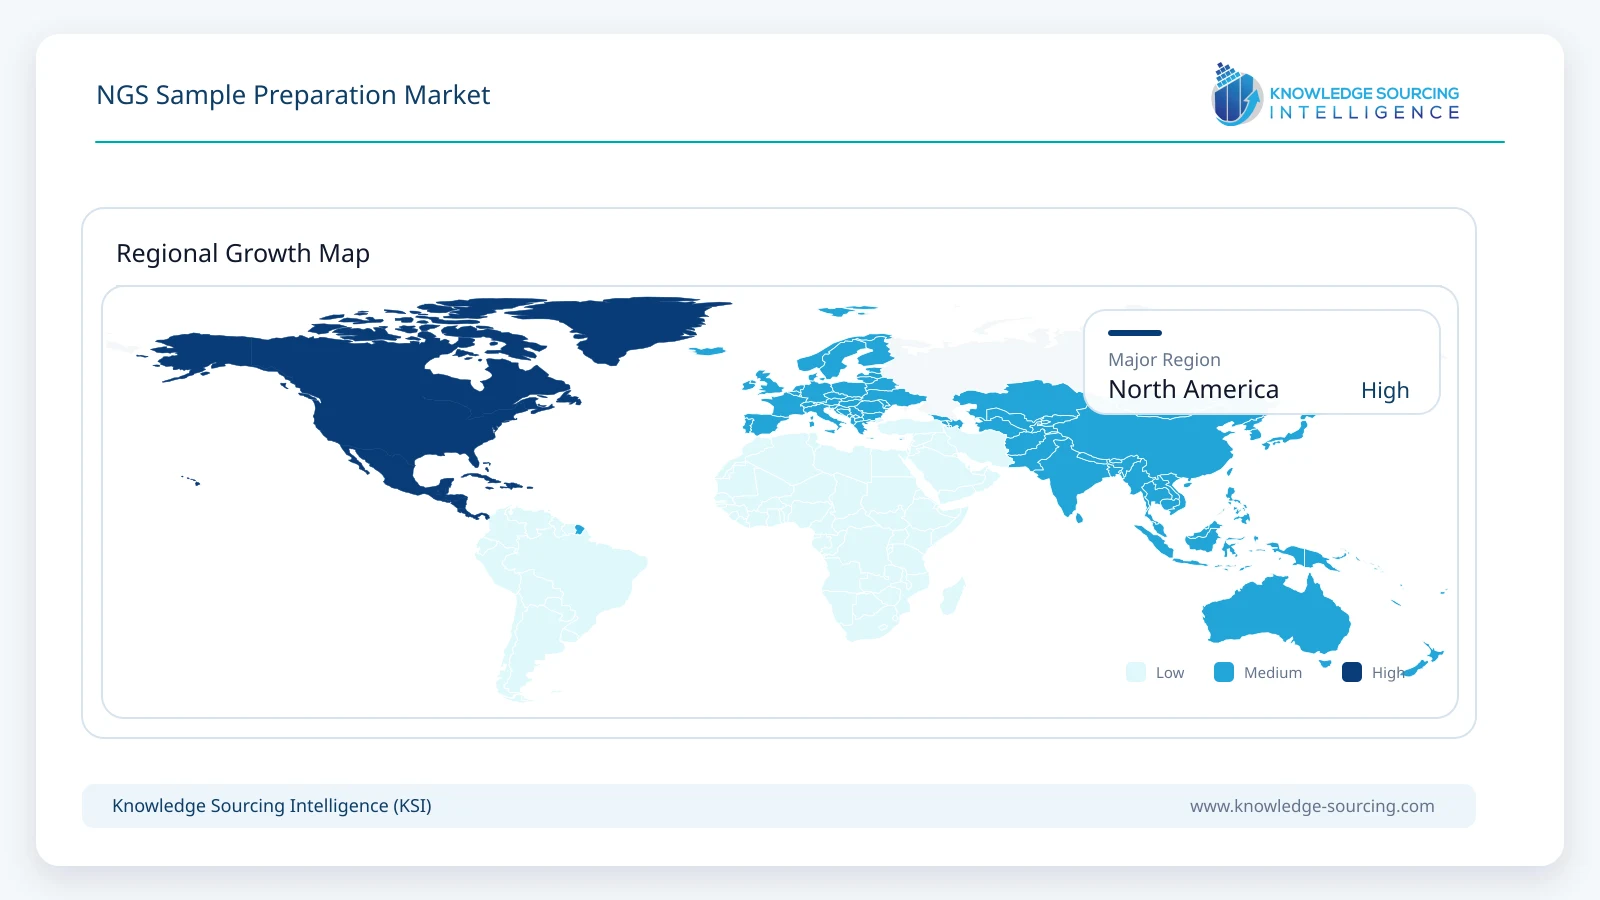
Europe remains an important market for regulated clinical genomics, while Asia Pacific is expected to grow faster as sequencing capacity expands in China, India, Japan, South Korea and Southeast Asia.
Market Drivers
Expansion of Clinical Genomics
NGS is increasingly used in oncology, rare disease, reproductive health and infectious-disease workflows. Each incremental clinical test requires reproducible sample preparation, often with application-specific chemistry and quality controls.
Higher Sequencing Throughput
Newer sequencers process more data and samples per run. Higher instrument throughput raises the number of libraries that laboratories must prepare, normalize and pool, directly increasing recurring upstream reagent consumption.
Growth of Whole-Genome and Population Sequencing
Large cohort and national genomics programs increase demand for standardized high-throughput library construction, especially PCR-free DNA workflows that can be automated across hundreds or thousands of samples.
Long-Read and Multiomic Adoption
Long-read sequencing, methylation-aware sequencing and other multiomic methods introduce new preparation requirements and expand the number of premium workflows beyond conventional short-read DNA libraries.
Automation and Laboratory Standardization
Laboratories are investing in automated preparation to improve reproducibility, reduce hands-on time and make scarce molecular-laboratory staff more productive. This adds an instrument and software layer to the recurring reagent market.
Market Restraints
Reagent Cost Pressure
Sequencing customers continually seek lower cost per sample. Large laboratories negotiate bulk pricing and may switch suppliers if competing kits deliver similar conversion efficiency, putting pressure on mature short-read library-preparation margins.
Protocol Fragmentation
NGS applications differ by sample type, platform, read length, enrichment strategy and downstream objective. A chemistry optimized for cfDNA may not fit RNA-seq or long-read WGS, limiting the scale advantages of a single universal workflow.
Research Funding Volatility
Academic sequencing demand remains sensitive to grant cycles and government research budgets. Illumina reported more conservative consumables purchasing by research and academic customers during periods of funding uncertainty, illustrating the effect on upstream workflows.
Workflow Validation Burden
Clinical laboratories cannot switch reagents or automation methods as easily as research laboratories because protocol changes can require validation, documentation and quality-system updates. This slows adoption even when a new product performs better.
Platform and Chemistry Obsolescence
Rapid changes in sequencing platforms can shorten product lifecycles. Suppliers must continually qualify adapters, barcodes, enrichment chemistry and automation methods against new sequencers and software pipelines.
Competitive Environment
The market is fragmented between sequencing-platform companies, molecular-biology reagent specialists, enrichment specialists and automation vendors. Illumina and Thermo Fisher benefit from platform integration, while Roche, QIAGEN, Agilent, New England Biolabs, Twist Bioscience, IDT and Revvity compete through chemistry performance, enrichment design and compatibility across multiple sequencing systems.
Competition is increasingly application-specific. Oncology workflows emphasize low-input conversion, UMIs and target capture; whole-genome programs prioritize cost, uniformity and PCR-free throughput; RNA workflows focus on depletion, strand specificity and low-input sensitivity; long-read workflows place greater emphasis on high-molecular-weight DNA handling and platform-compatible library structures. Suppliers with broad chemistry portfolios can therefore compete across more workflows, but specialized companies can still win where a single performance metric is critical.
Automation is becoming a second axis of competition. Tecan, SPT Labtech and Volta Labs are not simply replacing manual pipetting; they are building validated method libraries with reagent partners. As laboratories standardize around automated workflows, reagent suppliers gain an incentive to qualify products across multiple robots, while automation vendors gain recurring value from protocol ecosystems and consumables.
Recent Developments
September 2026: Agilent launched the 4150 TapeStationDx and 4200 TapeStationDx systems with CE-IVD-labeled software for standardized DNA and RNA quality control in clinical NGS workflows.
February 2026: Integrated DNA Technologies announced an NGS innovation roadmap focused on simplified library preparation, targeted enrichment and whole-genome applications for cancer research.
February 2026: New England Biolabs launched the Monarch Mag cfDNA Extraction Kit to support scalable, reproducible isolation of cell-free DNA from biofluids and expanded its automation partnerships for NGS library preparation.
February 2026: Twist Bioscience launched the Twist TrueAmp Library Preparation Kit and PCR-Free WGS Library Preparation Kit using proprietary polymerase and ligase enzymes.
January 2026: SPT Labtech and Twist Bioscience released validated automated Twist library-preparation workflows on the firefly liquid-handling platform.
November 2025: Volta Labs and New England Biolabs expanded automated NEBNext library preparation on the Callisto Sample Prep System, reflecting demand for integrated reagent-and-automation workflows.
2025: Illumina commercialized its 5-base DNA preparation workflow for simultaneous genomic and methylation analysis, while QIAGEN launched QIAseq xHYB Long Read Panels for targeted long-read sequencing.
Market Outlook
The NGS sample preparation market is expected to remain a high-growth genomics consumables segment through 2031. The key driver is not simply more sequencers; it is the expansion in samples processed per installed system and the increasing complexity of the workflows performed before sequencing. This supports recurring reagent demand even as sequencing chemistry becomes cheaper per gigabase.
Library preparation kits will remain the largest product category, but automation, quality control and application-specific enrichment should grow faster. Clinical genomics will gradually increase its share of the market because regulated laboratories typically require more standardized preparation, traceable QC and validated automation than research-only users.
The strongest suppliers are likely to be those that combine broad platform compatibility with application-specific performance and automation readiness. Short-read DNA library prep will become more price competitive, while cfDNA, FFPE, long-read, methylation, single-cell and multiomic workflows should continue to support premium pricing and product differentiation.
NGS Sample Preparation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.08 billion |
| Total Market Size in 2031 | USD 5.95 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 14.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, Application, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product
Library Preparation Kits and Reagents
Target Enrichment and Capture Products
Adapters, Beads, Cleanup and Size-Selection Reagents
Quality Control and Quantification Products
Sample Preparation Automation and Instruments
By Application
Oncology and Cancer Genomics
Whole-Genome and Population Sequencing
Transcriptomics and RNA Sequencing
Infectious Disease and Microbiome
Rare and Inherited Disease
Other Applications
By End User
Academic and Research Institutions
Clinical and Diagnostic Laboratories
Pharmaceutical and Biotechnology Companies
CROs, Public Health and Other Laboratories
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Clinical Genomics
4.1.2. Higher Sequencing Throughput
4.1.3. Growth of Whole-Genome and Population Sequencing
4.1.4. Long-Read and Multiomic Adoption
4.1.5. Automation and Laboratory Standardization
4.2. Market Restraints
4.2.1. Reagent Cost Pressure
4.2.2. Protocol Fragmentation
4.2.3. Research Funding Volatility
4.2.4. Workflow Validation Burden
4.2.5. Platform and Chemistry Obsolescence
5. NGS SAMPLE PREPARATION MARKET BY PRODUCT
5.1. Library Preparation Kits and Reagents
5.2. Target Enrichment and Capture Products
5.3. Adapters, Beads, Cleanup and Size-Selection Reagents
5.4. Quality Control and Quantification Products
5.5. Sample Preparation Automation and Instruments
6. NGS SAMPLE PREPARATION MARKET BY APPLICATION
6.1. Oncology and Cancer Genomics
6.2. Whole-Genome and Population Sequencing
6.3. Transcriptomics and RNA Sequencing
6.4. Infectious Disease and Microbiome
6.5. Rare and Inherited Disease
6.6. Other Applications
7. NGS SAMPLE PREPARATION MARKET BY END USER
7.1. Academic and Research Institutions
7.2. Clinical and Diagnostic Laboratories
7.3. Pharmaceutical and Biotechnology Companies
7.4. CROs, Public Health and Other Laboratories
8. NGS SAMPLE PREPARATION MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. India
8.5.4. South Korea
8.5.5. Southeast Asia
8.5.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Library Preparation and Target-Enrichment Positioning
9.3. Automation and Workflow Integration
9.4. Platform Compatibility and Clinical Validation
9.5. Recent Developments
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Illumina, Inc.
10.2. Thermo Fisher Scientific Inc.
10.3. Roche Diagnostics
10.4. QIAGEN N.V.
10.5. Agilent Technologies, Inc.
10.6. New England Biolabs, Inc.
10.7. Twist Bioscience Corporation
10.8. Integrated DNA Technologies, Inc.
10.9. Takara Bio Inc.
10.10. Revvity, Inc.
10.11. Tecan Group Ltd.
10.12. Oxford Nanopore Technologies plc
10.13. Pacific Biosciences of California, Inc.
10.14. SPT Labtech
10.15. Volta Labs, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Abbreviations





Frequently asked questions
What is the NGS sample preparation market forecast?
Market to reach $5.95 billion by 2031, growing at 14.1% CAGR.
Which product segment holds the largest revenue share?
Library preparation kits and reagents account for 46% revenue in 2026.
Which application segment dominates the market?
Oncology and cancer genomics represent 32% of 2026 application revenue.
Which end-user group is expanding fastest?
Clinical and diagnostic laboratories are the fastest-expanding end-user group.
Which region holds the largest market share?
North America represents 42% of global 2026 revenue.
What are key trends shaping the market?
Low-input workflows, multiomic library preparation, and platform-agnostic automation.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). NGS Sample Preparation Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ngs-sample-preparation-market