
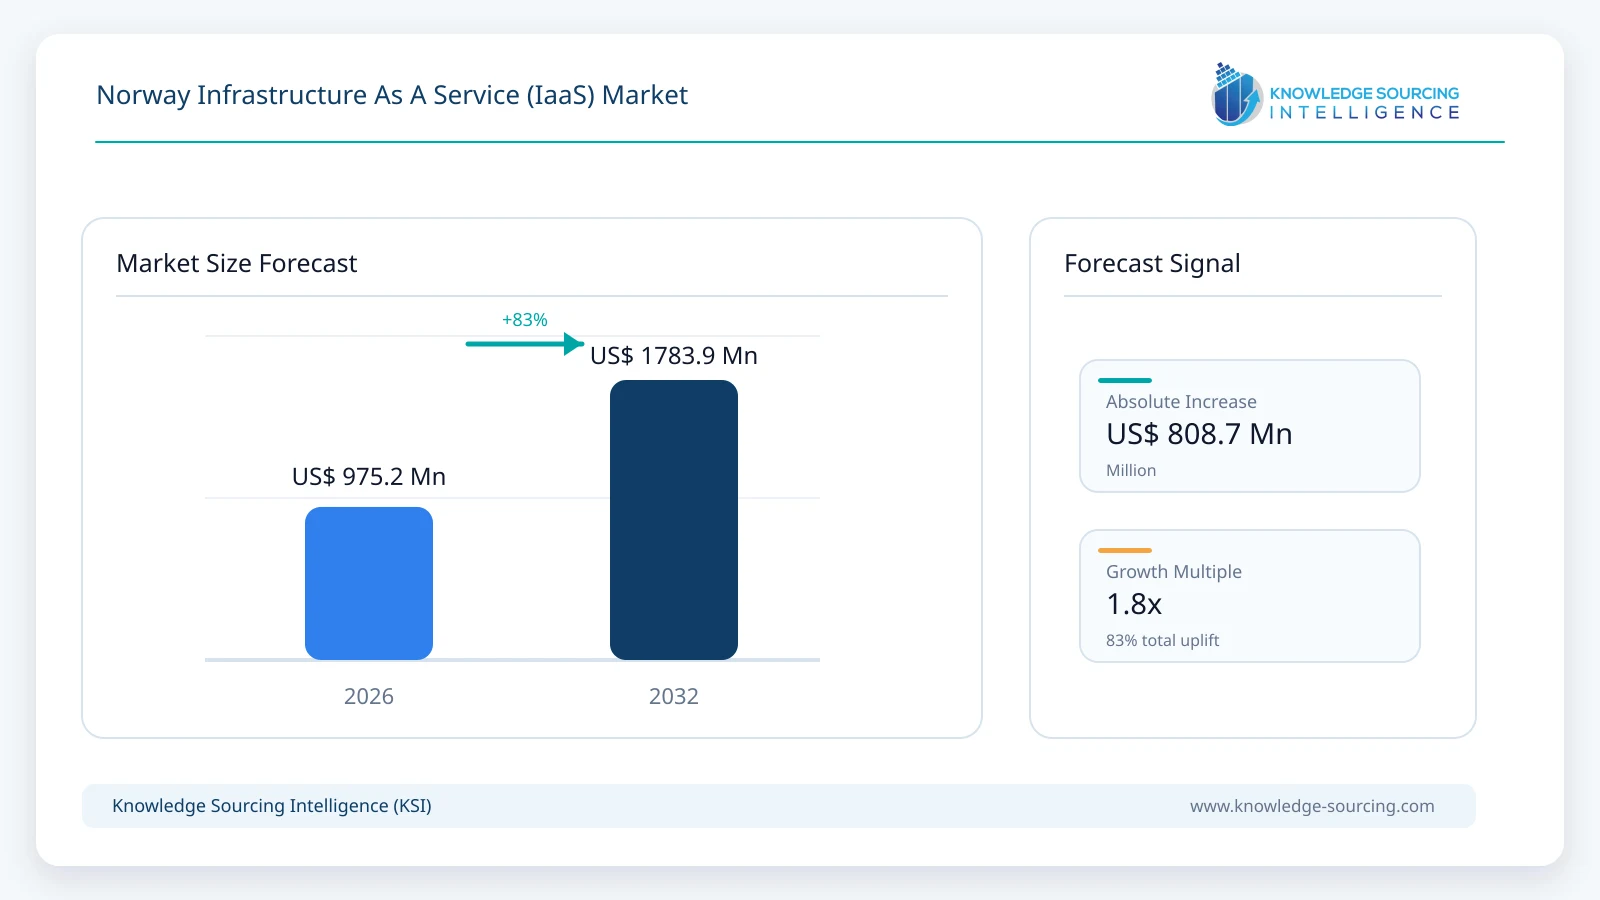
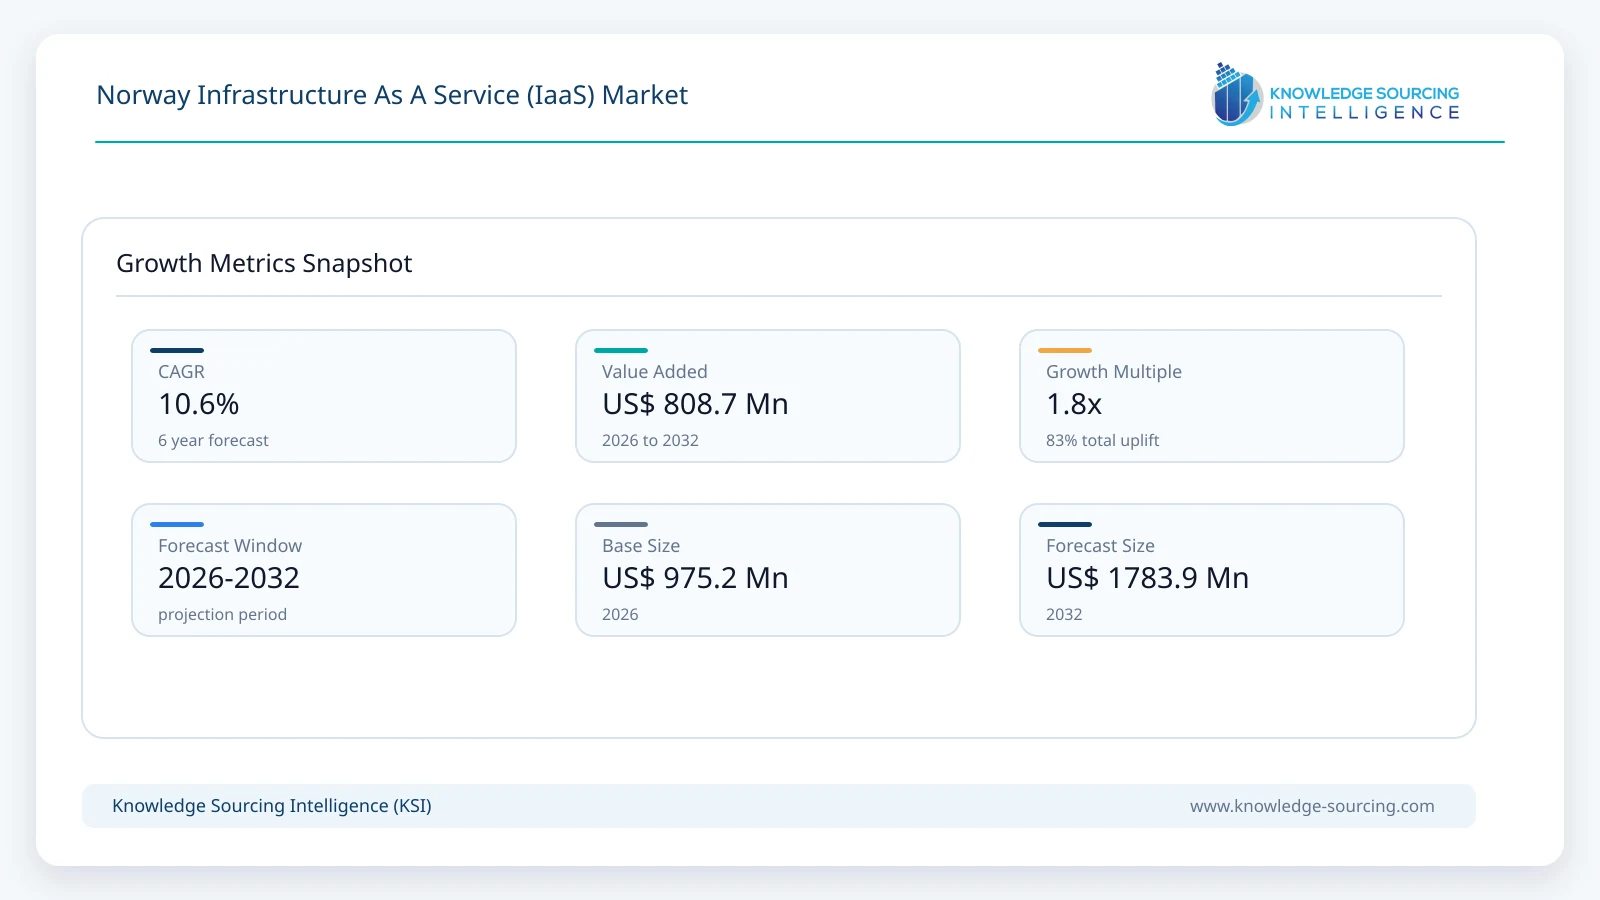
Norway’s infrastructure-as-a-service (IaaS) market is positioned to expand from USD 975.2 million in 2026 to USD 1,783.9 million by 2032, representing a CAGR of 10.6% during the forecast period.
Highlights:
- 1Norway's IaaS market is estimated at US$975.20 million in 2026, with a 2032 outlook of US$1,783.88 million at 10.59% CAGR.
- 2Compute infrastructure accounts for an estimated 60.0% of 2026 IaaS revenue, equivalent to US$585.12 million.
- 3High paid-cloud adoption makes infrastructure expansion within existing accounts more important than first-time cloud conversion.
- 4Norwegian residency and jurisdictional control create differentiation, but cross-border hosting remains important for many workloads.
- 5Infrastructure providers face rising scrutiny of idle capacity, data-transfer costs, supplier concentration and recovery obligations.
- 6Data-centre and GPU investment announcements do not automatically translate into IaaS spending by Norwegian customers.
The market covers metered or contracted infrastructure compute, storage and network resources purchased by Norwegian organizations, whether workloads run in Norway or in permitted foreign regions. It excludes office software, application subscriptions, platform development services, colocation rent and standalone systems integration. This boundary matters because cloud adoption is already widespread while actual infrastructure expenditure is concentrated among comparatively few complex enterprises. Statistics Norway reports that 68% of enterprises covered by its 2026 survey purchase paid cloud computing services, but this includes email, software and other offerings that do not constitute IaaS revenue. For infrastructure suppliers, further growth increasingly depends on workload density, migration of legacy applications, cloud cost management and specialized computing requirements rather than simply winning first-time cloud users. Norwegian demand is also distinct from the revenue generated by data centres physically situated inside the country, because infrastructure bills can fund resources hosted elsewhere in Europe.
The strategic tension is between the scale and service breadth of international hyperscalers and Norwegian customers’ demand for jurisdictional control, resilience and predictable operating costs. Microsoft operates the Norway East cloud region and offers a restricted Norway West region for relevant recovery scenarios; AWS and Google Cloud provide substantial service portfolios to Norwegian customers through regional infrastructure elsewhere in Europe. Norway’s central bank has warned that concentration of technology suppliers creates vulnerabilities when several financial institutions depend on the same infrastructure platforms. At the same time, Norwegian cloud specialists can compete through local operational accountability, integration with domestic networks and tailored sovereignty controls. These differences affect procurement more directly than generic statements about digital transformation. Enterprises operating sensitive workloads must examine legal control, cross-border support access, encryption-key management, recovery testing and exit provisions. Meanwhile, organizations running less sensitive applications can prioritize the cost and elasticity of larger international cloud ecosystems. The result is not a single migration pathway but a market of differentiated workload placement decisions, each with implications for supplier margins, contract length and switching costs.
Market Dynamics
Norway’s high cloud-adoption base changes the commercial logic of future infrastructure spending. Statistics Norway’s 2026 enterprise statistics show meaningful differences by employer size: paid-cloud usage is 58% among companies with 10–19 employees and 89% among companies with at least 100 employees. These figures are not IaaS penetration rates, but they demonstrate where the cost of acquiring new customers may be highest and where additional demand could come from heavier usage rather than new accounts. Smaller companies often adopt cloud through software subscriptions while buying limited raw compute resources directly. Larger organizations have more complex application estates and are more likely to pay for virtual servers, resilient storage, secure connectivity and backup environments. Cloud vendors can therefore grow infrastructure revenue within existing enterprise relationships by modernizing databases, moving production workloads and replacing legacy hardware refresh cycles. This expansion is constrained by enterprise finance teams that increasingly scrutinize idle instances, egress bills, reservations and licensing costs. Providers that deliver measurable unit economics and workload governance can defend renewal values better than vendors relying exclusively on consumption growth.
The Norwegian infrastructure market is shaped by the geographic distinction between domestic data residency and access to foreign cloud regions. Microsoft’s local region gives buyers a clear option for keeping specified workloads inside national borders, whereas Google Cloud lists Finnish and Swedish regions rather than a Norway region, and AWS lists its Oslo Local Zone as announced rather than broadly operational. These offerings should not be described as equivalent local facilities. For a public authority or financial institution, the architectural choice affects latency, disaster recovery, legal risk and the number of vendors able to meet procurement conditions. Cross-border delivery can remain entirely suitable where contractual safeguards and service requirements permit it, and regional diversity may improve resilience when a domestic fault affects connected services. However, controls over encryption, administrator access, incident response and subprocessor locations must be validated separately. The strongest competitive propositions combine transparent hosting options with measurable service levels, rather than using the broad label of sovereign cloud without specifying operational jurisdiction and the exact responsibility for continuity.
Regulatory and security requirements increasingly shape the infrastructure contract rather than merely appearing in tender paperwork. Norway introduced a dedicated data-centre regulatory regime in 2025, and its communications authority published detailed security and preparedness guidance in June 2026. These rules apply to qualifying facilities in Norway; they do not make every foreign-hosted cloud service subject to identical local facility obligations. For cloud buyers, the practical challenge is translating national regulatory expectations into procurement controls over location, audit rights, recovery arrangements and incident escalation. Norges Bank’s 2026 Financial Infrastructure Report highlights how extensive outsourcing and a concentrated supplier market can create common points of failure across essential services. Those concerns favor vendors able to offer verifiable recovery testing, documented subcontracting and clear operational accountability. They also increase the workload for procurement teams because contractual promises about residency do not automatically establish who can access production environments or where technical support takes place. Suppliers that can demonstrate governance at the infrastructure layer may command more durable relationships, even if headline compute prices remain intensely competitive.
The expansion of Norwegian data-centre capacity creates opportunities for cloud infrastructure but should not be mistaken for equivalent growth in domestic IaaS receipts. Statistics Norway’s 2026 research identifies substantial construction and registration activity, while the government’s data-centre strategy notes that electricity consumption may rise sharply and available grid capacity is constrained. A megawatt reservation is not a delivered computing workload, and a completed facility can serve customers located outside Norway. These distinctions are particularly important as large AI-oriented campuses attract substantial investment. Infrastructure suppliers must weigh the advantages of renewable electricity and a cool climate against power-connection queues, construction schedules, network investment, capital intensity and the risk of underutilized specialist hardware. Customers similarly compare domestic hosting benefits against access to established European regions with mature service ecosystems. Only commissioned capacity supporting billable infrastructure services for Norwegian buyers belongs in the demand-side estimate. For business development, the opportunity lies in matching the right compute architecture to verified customer demand, not treating every announced data-centre project as an immediate source of local market revenue.
Service Analysis: Compute Infrastructure
Compute infrastructure is the largest service category in Norway’s IaaS market, accounting for approximately US$585.12 million and 60.0% of estimated revenue in 2026. The category includes virtual machines, provisioned processor and memory capacity, selected dedicated bare-metal instances and infrastructure-grade accelerated compute. It excludes SaaS subscriptions and managed application-platform revenue. Demand is concentrated in enterprise application hosting, database modernization, batch processing, analytics and development environments that require granular control of underlying resources. The commercial measure is effective spending on active capacity rather than advertised list prices or the number of virtual machines created. Enterprises can reduce their bills through reserved capacity, scheduling and rightsizing, while other customers pay premiums for high-memory systems, assured performance or specialized accelerators. Providers that can demonstrate a lower cost per completed workload have a stronger argument than suppliers presenting infrastructure capacity as a commodity. Even where compute is the primary purchase, buyers may incur related storage, data-transfer and backup charges, which need to be allocated consistently rather than added again as independent customer transactions.
The competitive position of compute suppliers depends increasingly on the fit between workload requirements and infrastructure commitments. Standardized enterprise virtual machines benefit from established automation, broad instance families and procurement frameworks. Sovereign and domestic offerings compete by giving customers additional control over location and operations, although they may have a smaller catalogue or different capacity economics. For highly regulated workloads, decision-makers may accept higher effective prices when data governance, service continuity and vendor accountability justify them. For general development environments, the same buyer may choose lower-cost foreign-hosted compute and use domestic services for only selected applications. Multicloud strategies therefore do not necessarily divide infrastructure spending evenly among vendors; migration costs, data-transfer charges, platform tooling and staff skills can reinforce concentration. Providers seeking to increase compute utilization should emphasize application migration planning, workload scheduling and capacity commitments that align with demand. Growth in the service category is closely linked to the ability to translate expanding technical workloads into billable, well-utilized infrastructure rather than only adding hardware capacity.
AI-specific infrastructure may alter Norway’s compute demand, but announced GPU deployments require particularly careful interpretation. In April 2026, Nscale described an expanded arrangement with Microsoft for more than 30,000 NVIDIA Rubin GPUs at a Narvik campus, with deployment planned for 2027. The agreement indicates international interest in Norway as a location for power-intensive computing, yet it does not establish the amount of IaaS expenditure by Norwegian customers in 2026. A large installation can serve foreign cloud users, function under a wholesale capacity contract or be incorporated into a hyperscaler’s broader product portfolio. In each case, revenue attribution differs. The economic constraints also differ from general-purpose infrastructure because accelerated hardware carries higher procurement costs, faster technological obsolescence and material power and networking requirements. Suppliers must secure long-term customers and effective utilization before capacity deployment can translate into sustainable returns. For Norwegian buyers, inference and enterprise analytics may create demand for accelerated infrastructure, but the scope should follow purchased resources rather than extrapolating demand directly from announced GPU counts.
Other Services and Customer Applications
Storage and networking complement compute infrastructure but are distinct revenue pools with different margin and growth characteristics. Object and block storage are purchased for application data, backups, replicas and retention obligations; network resources cover infrastructure-level transfer, load balancing and connectivity where these are separately billable. Bundled allowances must be attributed once, and third-party telecommunications contracts do not belong in an IaaS estimate. Storage decisions increasingly depend on access frequency, retrieval charges, immutability, encryption requirements and backup restoration times. Network costs can become more important when companies distribute workloads across multiple regions or providers, particularly where data movement erodes an apparent compute saving. Customer requirements also vary significantly: financial institutions place emphasis on resilience and access control, industrial groups require integration with plant operations, and smaller digital firms prioritize provisioning speed and cost transparency. Public-sector buyers add procurement and jurisdictional requirements that can slow migration but create long-duration contracts. Suppliers able to coordinate these needs across infrastructure layers may capture a larger share of a customer relationship without redefining software, professional services or physical colocation as infrastructure revenue.
Geographic Outlook
Demand for IaaS is geographically concentrated around Norway’s largest corporate, technology and public-administration centers, although purchased infrastructure may be delivered from multiple domestic and international locations. Oslo and Akershus generate demand from headquarters, financial services, consultancies, public agencies and digital businesses that tend to require diverse application portfolios and continuous availability. This concentration should not be confused with a proportional distribution of installed data-centre equipment, because hosting facilities frequently occupy locations selected for power, land and network considerations rather than customer addresses. The western regions combine maritime, energy and industrial users with operational systems that may place a premium on secure integration and predictable latency. In Trondheim and other technology clusters, research activity and software development support demand for specialized compute, storage and experimentation capacity. For market participants, local sales coverage and partner ecosystems remain important even when infrastructure is provisioned remotely. The central commercial requirement is to connect account demand, procurement authority and workload specifications rather than infer revenue from the number of buildings, server rooms or data-centre registrations in a particular county.
Norway’s regional infrastructure policy creates a further distinction between locally consumed services and nationally hosted capacity sold abroad. The government’s data-centre strategy favors secure, efficient installations that contribute to value creation, while electricity-system constraints and surplus-heat provisions influence site economics. New campuses in locations with attractive power resources may increase Norway’s role in international cloud supply chains, but the value of that output is not automatically part of a Norway end-user IaaS demand market. Some installations support specialized AI workloads contracted by multinational customers, whereas enterprises based in Norway may continue using infrastructure hosted in Stockholm, Finland or other European regions. Providers should report these two markets separately: the location of the purchaser and the location of the supporting infrastructure. This distinction improves the usefulness of commercial sizing for vendors targeting Norwegian enterprise customers, as well as for investors evaluating the economics of Norwegian hosting assets. It also avoids overstating market growth by combining domestic IaaS expenditure, colocation rent, construction investment and export-oriented compute capacity in a single figure.
Competitive Environment
The Norway IaaS competitive environment includes international cloud platforms, regional sovereign providers and Norwegian infrastructure specialists, but their service boundaries differ. Microsoft Azure competes with a locally available cloud region, while AWS, Google Cloud, IBM Cloud, DigitalOcean and other cross-border platforms supply infrastructure resources to Norwegian customers from broader networks. Safespring offers OpenStack-based infrastructure services with Nordic data-centre locations including Norway, and Orange Business provides sovereign cloud IaaS through a regional operating footprint. Intility and Iver offer infrastructure platforms and managed operating models for enterprise customers with control and compliance needs. Their total company revenues cannot be treated as Norwegian IaaS sales without eliminating adjacent managed services, software and network activities. Buyers evaluate service breadth, technical performance, reliability, jurisdictional arrangements and total cost, while smaller providers differentiate on local support and contractual transparency. The sector is likely to remain concentrated around the largest cloud ecosystems even as regulated customers seek alternative deployment options. Commercial differentiation therefore depends more on measurable operating commitments and procurement access than on claims of universal market leadership or unsupported vendor market-share figures.
New offerings also require careful separation between competitive entry and realized revenue. Telenor announced a sovereign cloud company in May 2026 with a planned commercial launch in the first half of 2027, initially serving sensitive public-sector and larger-enterprise workloads. That initiative is relevant to the future competitive structure, but its pilot or development stage should not be presented as established 2026 commercial IaaS turnover. The announcement nevertheless demonstrates that a domestic technology group views national control and geopolitical exposure as sources of customer demand. Its success will depend on technical maturity, regulatory acceptance, available service breadth, procurement cycles and the economics of building a platform that can compete with established hyperscalers. Meanwhile, Norwegian buyers will continue comparing domestic solutions against cross-border cloud platforms, with some selecting hybrid approaches to balance data residency and cost. For incumbent providers, the response may involve clearer sovereignty guarantees, locally accountable support and improved recovery options. For new entrants, the key hurdle is converting policy interest into repeatable paying workloads without overstating the size of the addressable market or counting implementation revenue as IaaS.
Recent Developments
June 2026: Microsoft announced plans for a new data-centre development in Sandnes to increase Norwegian cloud capacity; this is a project announcement, not confirmed live capacity.
May 2026: Telenor established a sovereign-cloud initiative targeting sensitive organizations and stated a planned commercial launch in the first half of 2027.
Norway Infrastructure As A Service (IaaS) Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 975.2 million |
| Total Market Size in 2032 | USD 1,783.9 million |
| Forecast Unit | Million |
| Growth Rate | 10.6% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Service Type, Customer Group |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Service Type
Compute Infrastructure
Storage Infrastructure
Network Infrastructure
By Customer Group
Small Enterprises
Midmarket and Large Enterprises
Public-Sector and Research Customers
By Geography
Oslo and Akershus
Western Norway
Trøndelag and Other Regions
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market size and strategic findings
1.2. Demand, risks and priority opportunities
2. RESEARCH SCOPE AND METHODOLOGY
2.1. Norway buyer-spend scope and revenue boundaries
2.2. Bottom-up demand model and secondary reconciliation
2.3. Segmentation, evidence and sensitivity
3. NORWAY INFRASTRUCTURE AS A SERVICE MARKET OVERVIEW
3.1. Cloud adoption and enterprise workload demand
3.2. Provider structure and buyer economics
3.3. Cloud sovereignty and location requirements
4. MARKET DYNAMICS
4.1. Migration and infrastructure modernization
4.2. Regulatory, security and financial-system requirements
4.3. Grid constraints and infrastructure investment
4.4. Competitive forces and value chain
5. NORWAY INFRASTRUCTURE AS A SERVICE (IAAS) MARKET BY SERVICE TYPE
5.1. Compute infrastructure
5.2. Storage infrastructure
5.3. Network infrastructure
6. NORWAY INFRASTRUCTURE AS A SERVICE (IAAS) MARKET BY CUSTOMER GROUP
6.1. Small enterprises
6.2. Midmarket and large enterprises
6.3. Public-sector and research customers
7. GEOGRAPHIC DEMAND OUTLOOK
7.1. Oslo and Akershus
7.2. Western Norway
7.3. Trøndelag and other regions
8. COMPETITIVE ENVIRONMENT
8.1. Global IaaS platforms
8.2. Nordic and domestic infrastructure providers
8.3. Planned and emerging entrants
8. COMPANY PROFILES
8.1. Microsoft Azure
8.2. Amazon Web Services
8.3. Google Cloud
8.4. IBM Cloud
8.5. DigitalOcean
8.6. Safespring
8.7. Orange Business
8.8. Intility
8.9. Iver
8.10. OVHcloud
8.11. Akamai Cloud (Linode)
8.12. Oracle Cloud Infrastructure





Frequently asked questions
What is the projected size of Norway's IaaS market by 2032?
Norway's IaaS market will reach USD 1,783.9 million by 2032.
What is the Compound Annual Growth Rate (CAGR) for Norway's IaaS market?
The Norway IaaS market forecasts 10.6% CAGR from 2026 to 2032.
Which IaaS component dominates revenue in Norway's market?
Compute infrastructure accounts for 60% of 2026 IaaS revenue.
What key factors drive IaaS market growth for Norwegian organizations?
Workload density, legacy migration, and cloud cost management drive IaaS growth.
What is the key strategic tension in Norway's IaaS market?
Hyperscaler scale versus Norwegian demand for jurisdictional control and resilience.
What does the report's IaaS market definition for Norway exclude?
Excludes office software, application subscriptions, colocation, and systems integration.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Norway Infrastructure As A Service (IaaS) Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/norway-infrastructure-as-a-service-iaas-market