
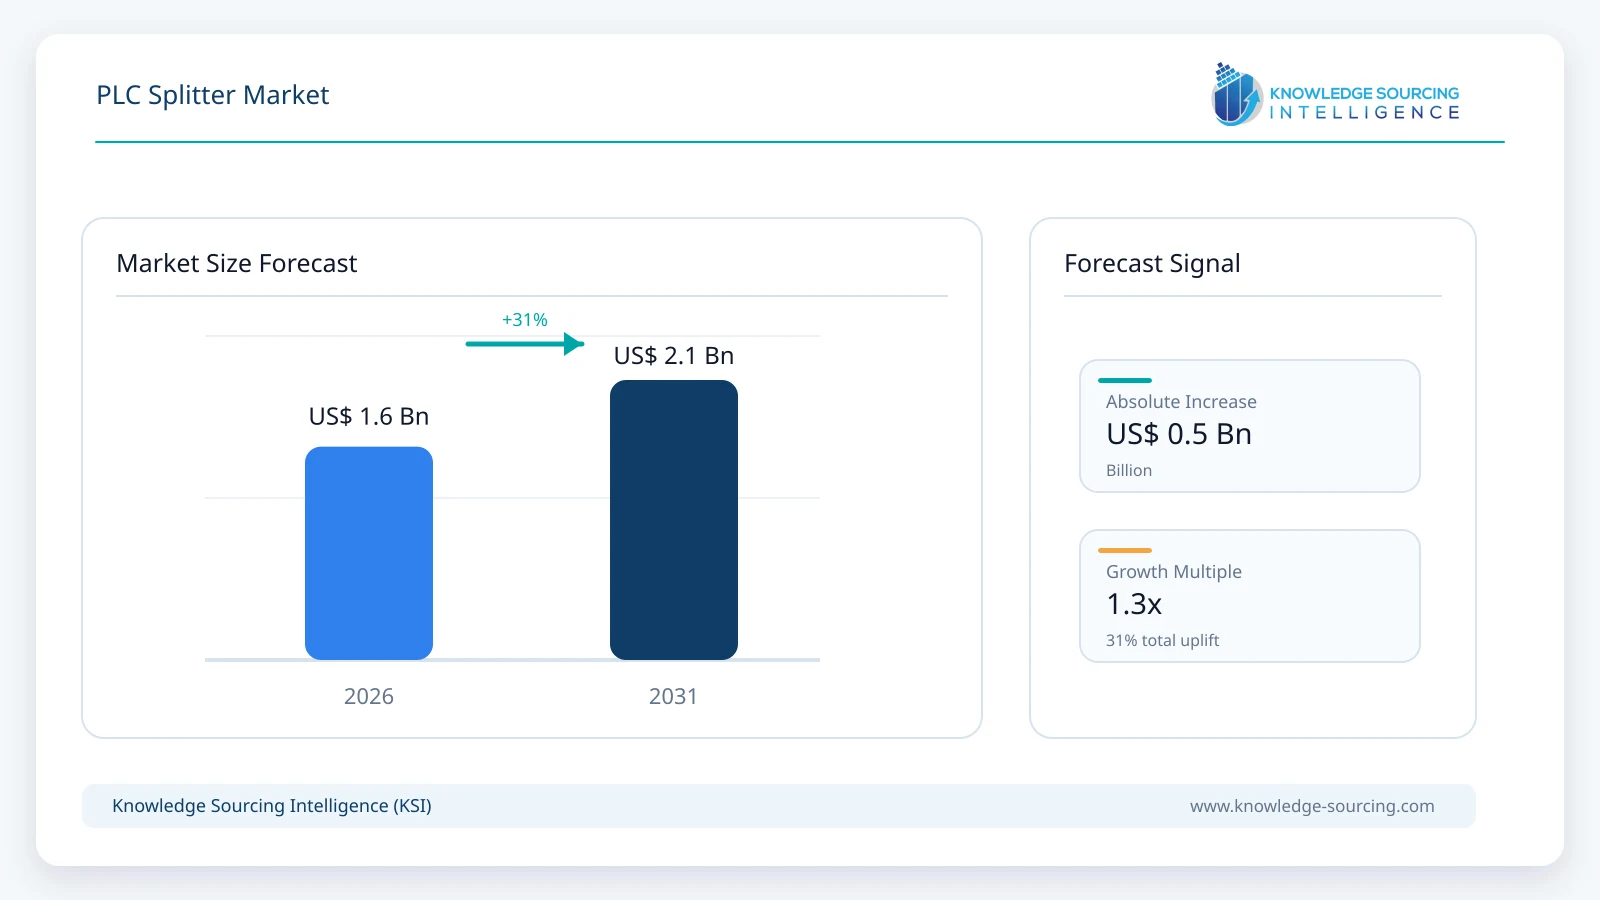
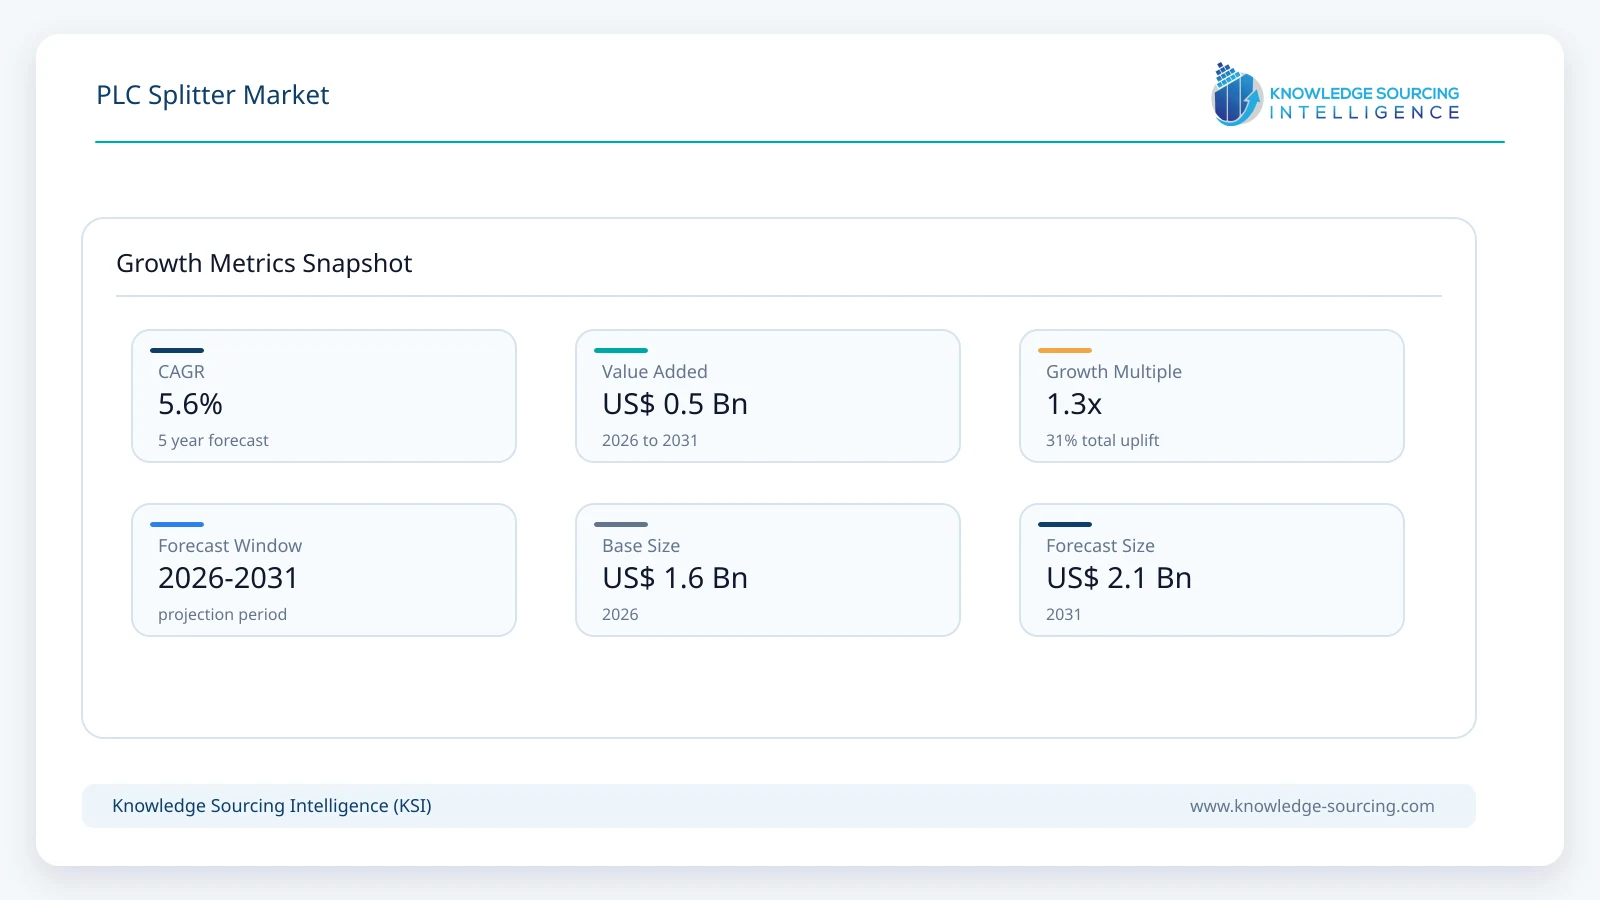
The PLC Splitter market is forecast to grow at a CAGR of 5.6%, reaching USD 2.1 billion in 2031 from USD 1.6 billion in 2026.
Highlights:
- 1Expanding FTTH deployments are increasing demand for efficient optical signal distribution.
- 2Accelerating 5G network rollouts are driving wider adoption of PLC splitters.
- 3Growing smart city projects are boosting fiber network infrastructure investments.
- 4Advancing PON technologies are enhancing splitter performance across broadband applications.
- 5Increasing data center expansion is creating demand for compact low-loss splitters.
- 6Rising IoT connectivity requirements are supporting growth in optical access networks.
The rapid expansion of fibre-to-the-home and fibre-to-the-networks due to the growing push for high-speed broadband is the major factor driving the market of PLC splitters for its critical role in splitting optical signals from a single fiber to multiple users in PONs. The growing deployment of 5G networks, along with increasing adoption of IoT and growing smart cities projects, are leading the market to grow. Alongside, the technological advancement in PON technologies is leading the market to propel.
PLC Splitter Market Overview
The PLC Splitter Market is segmented by:
Type: The PLC Splitter market is segmented into 1×N Splitters, 2×N Splitters, Cascaded Splitters, and Specialized Splitters (such as ultra-low-loss, wideband, and miniaturized variants). During the mentioned timeframe, 1x N splitters will continue to dominate due to their widespread adoption in GPON and FTTx networks. However, the market will witness the growing emergence of specialized splitters for deployments in high-performance and space-constrained environments such as data centers.
By Technology Compatibility: By technology compatibility, the market includes BPON, EPON, GPON, XG-PON/XGS-PON, NG-PON2, and WDM-PON. GPON and EPON currently dominate due to their maturity and deployment across global broadband networks. The growing next-gen networks are driving demand for newer technologies such as XGS-PON and NG-PON2.
By Deployment Location: By deployment location, the market is segmented into Central Offices, Outside Plant, Premises/End-user Locations, and Edge Nodes/Small Cells. Outside plant will constitute the major share.
Application: Based on application, the market is categorized into PON-based FTTx (including FTTH, FTTB, and FTTC), Cable TV (CATV), Optical Signal Monitoring, Testing Equipment, IoT Networks, and 5G Fronthaul/Backhaul. FTTx, particularly FTTH are primary application area, thus holding the largest share.
End-Use Industry: The end-user segment includes Telecom Operators, Data Centers, ISPs (Internet Service Providers), Enterprises, IoT Solution Providers, and Cable/MSOs. ISPs and data centers are emerging as new end-users of PLC splitters due to the growing demand for bandwidth and network densification.
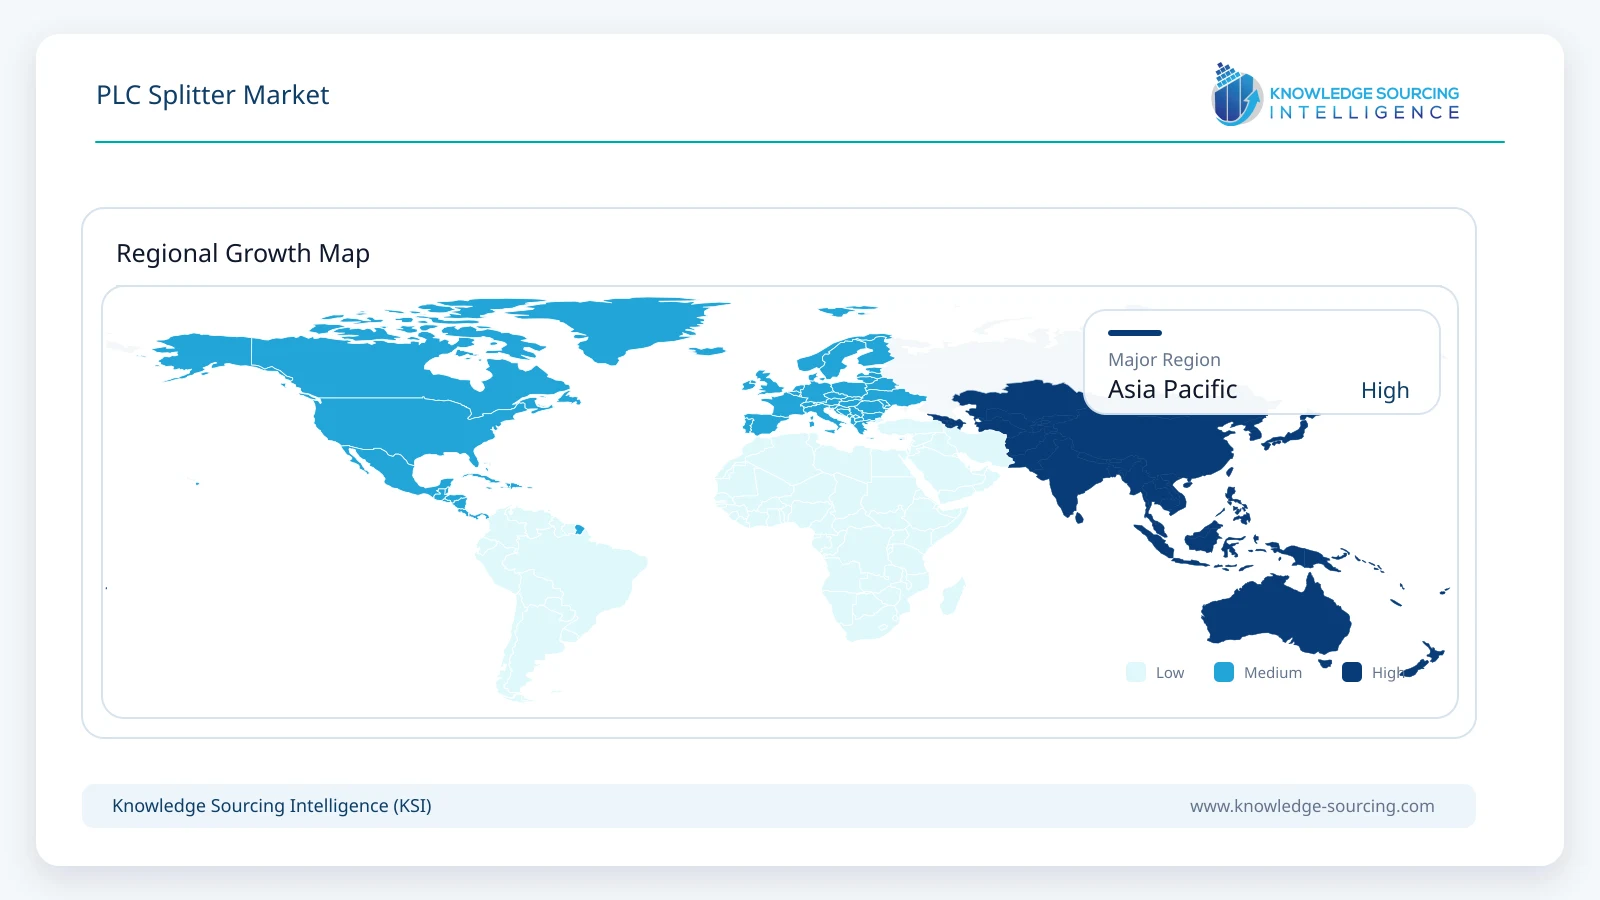
Region: The market is segmented into five major geographic regions, namely North America, South America, Europe, the Middle East and Africa and Asia-Pacific. Asia-Pacific will dominate the market, and it will be growing at the fastest CAGR.
Top Trends Shaping the PLC Splitter Market:
1. Emerging demand for miniaturized and compact designs
The market has an emerging demand for miniaturized and compact designs due to increasing demand from IoT networks, 5G small cells and data centers for space constraints and supporting high-port-count applications. For example, FS offers mini 1x4 PLC splitters with 90 ?m to split 1260nm to 1650nm signals.
Companies such as Fujikura also offer the FSC114 series, which is a compact splitter module. Its FSC114-1X2-SC is in dimensions of w28.4 X H55 XD105 mm.
2. Growing adoption of low-loss splitters
The growth in 5G fronthaul and data centers has increased the demand for wideband splitters and ultra-low-loss design splitters to support higher bandwidths and longer distances. The growth in these markets will impact the PLC splitters market to emerge in low-loss splitters.
For example, the Corning Incorporated PLC Splitter LGX module features low insertion loss, low polarization-dependent loss, and high port-to-port uniformity
PLC Splitter Market Growth Drivers vs. Challenges:
Opportunities:
Rapid expansion of Fibre-to-the-Home (FTTH) and FTTx networks: Growing demand for high-speed broadband, increased data consumption, and fibre infrastructure expansion are supporting the deployment of FTTH and FTTx networks. These developments are creating demand for Planar Lightwave Circuit (PLC) splitters, which distribute optical signals from a single input fibre to multiple outputs in passive optical networks (PONs). According to the Fiber Broadband Association, its December 2025 announcement reported that the United States recorded a record 11.8 million FTTH homes passed in 2025, bringing total fibre passings to 98.3 million. This expansion highlights the continuing investment in fibre access infrastructure and the potential need for optical distribution components, including PLC splitters.
Growing deployments of 5G networks: The continued expansion of 5G infrastructure is supporting investment in optical transport, fibre backhaul, fronthaul and high-capacity connectivity networks. PLC splitters can support optical signal distribution in passive optical network architectures used in fibre access and certain mobile network infrastructure deployments. According to Ericsson’s June 2026 Mobility Report, global 5G subscriptions approached 3.3 billion in the second quarter of 2026, while approximately half of global mobile data traffic was carried over 5G networks. In addition, China’s Ministry of Industry and Information Technology reported that the country had installed 4.838 million 5G base stations by the end of 2025, demonstrating the scale of ongoing telecommunications infrastructure deployment. These developments support demand for optical connectivity components, although PLC splitter requirements depend on individual network architecture and deployment choices.
Challenges:
Complex manufacturing processes: The market faces a constant restraint due to the complex manufacturing process associated with PLC splitters, especially specialized splitters. It required advanced planar waveguide technology, photolithography, and precision packaging, leading the process to be technically complex and capital-intensive. This leads to an entry barrier for small and local manufacturers. Alongside, the complex manufacturing process increases the cost, which makes small manufacturers lose due to technical barriers as well as lack of scaling.
PLC Splitter Market Regional Analysis:
Asia-Pacific:
The Asia-Pacific region is expected to maintain strong growth in the PLC splitter market, supported by expanding fibre-optic broadband infrastructure, increasing FTTH adoption, and the deployment of high-capacity telecommunications networks. China remains a major driver of regional demand. According to China's Ministry of Industry and Information Technology (MIIT), the country had 691 million fixed broadband subscribers at the end of 2025, including 238 million subscribers with connection speeds of 1,000 Mbps or higher. The ministry also reported that China had 1.21 billion FTTH/O access ports by the end of 2025, representing 96.8% of all fixed broadband access ports. These figures demonstrate the scale of China's fibre-optic infrastructure and its continuing importance to demand for passive optical network components, including PLC splitters.
India is also strengthening regional fibre connectivity through the Government of India's BharatNet programme. According to the Ministry of Communications, 2,14,904 Gram Panchayats were service-ready under BharatNet as of December 31, 2025, with further network upgrades planned under the Amended BharatNet Programme. In addition, the government has set a target of 1.5 crore FTTH connections under the programme, supported by plans to lay nearly 7 lakh kilometres of optical fibre cable. These initiatives are expanding the infrastructure required to deliver broadband connectivity to rural households and institutions, supporting demand for optical distribution networks and PLC splitters.
Across the Asia-Pacific region, continued investment in fibre access networks, rising demand for high-speed broadband and the expansion of digital services are expected to support the PLC splitter market. However, these infrastructure indicators demonstrate potential demand drivers rather than directly measured PLC splitter sales, and the pace of market growth will depend on network investment, deployment technology and last-mile connectivity requirements.
PLC Splitter Market Competitive Landscape:
The PLC splitter market comprises established optical communications manufacturers, specialist passive-component suppliers, and regional fiber-optic equipment providers. Competition is shaped by optical performance, insertion loss, reliability, packaging flexibility, manufacturing scale, and compatibility with fiber-to-the-home (FTTH) and passive optical network (PON) architectures. Recent company announcements indicate that investment in fiber-optic infrastructure, high-density connectivity, and AI data centers is creating additional opportunities for optical component suppliers. However, developments involving optical fiber, connectors, and data-center interconnects should be treated as indirect demand drivers, rather than confirmed increases in PLC splitter sales.
September 2026 - Verizon and Corning Expand Fiber Infrastructure Supply: Verizon and Corning announced a multibillion-dollar supply agreement covering more than 80 million miles of high-density optical fiber and connectivity solutions from 2027 through 2032. The agreement supports broadband expansion, fiber-to-the-home connectivity, and AI data center backbone development, potentially benefiting suppliers of compatible passive optical network components as deployment expands.
September 2026 - SENKO, Advantest, and VIAVI Collaborate on Co-Packaged Optics Testing: SENKO Advanced Components, Advantest and VIAVI Solutions announced a collaboration to demonstrate automated testing for high-volume co-packaged optics manufacturing. The platform supports testing 200 Gbps signals per lane through detachable optical connectors, addressing reliability and production scalability requirements in next-generation AI infrastructure. The development reinforces the importance of dependable optical components and manufacturing processes across the wider optical communications market.
March 2026 - SENKO and Lightmatter Advance Co-Packaged Optics Connectivity: SENKO Advanced Components announced a collaboration with Lightmatter on detachable fiber connectivity for its vClick optics architecture. The solution integrates SENKO's detachable Metallic PIC Coupler and SEAT optical interface, targeting reliable, serviceable optical connections for high-bandwidth, high-volume AI infrastructure. This development highlights innovation in adjacent optical connectivity technologies rather than a confirmed PLC splitter launch.
January 2026 - Corning and Meta Announce a Multiyear AI Data Center Agreement: Corning and Meta announced an agreement worth up to USD 6 billion to support U.S. data center expansion. Corning will supply optical fiber, cable, and connectivity products and expand manufacturing capacity in North Carolina. The investment supports the broader optical infrastructure ecosystem, although the announcement does not specify PLC splitter procurement.
PLC Splitter Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.6 billion |
| Total Market Size in 2031 | USD 2.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Technology Compatibility, Application, Deployment Location, End-User, Geography |
| Companies |
|
Market Segmentation
By Type
1×N Splitters
2×N Splitters
Cascaded Splitters
Specialized Splitters (ultra-low-loss, wideband, miniaturized splitters and others)
By Technology Compatibility
BPON
EPON
GPON
XG-PON/XGS-PON
NG-PON2
WDM-PON2
By Application
PON-based FTTx
FTTH
FTTB
FTTC
Cable TV (CATV)
Optical Signal Monitoring
Testing Equipment
IoT Networks
5G Fronthaul/Backhaul
By Deployment Location
Central Offices
Outside Plant
Premises/End-user Location
Edge Nodes/Small Cells
By End-User
Telecom Operators
Data Centers
ISPs (Internet Service Providers)
Enterprises
IoT Solution Providers
Cable/MSOs
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY 
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE 
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. PLC SPLITTER MARKET BY TYPE
5.1. Introduction
5.2. 1×N Splitters
5.3. 2×N Splitters
5.4. Cascaded Splitters
5.5. Specialized Splitters (ultra-low-loss, wideband, miniaturized splitters and others)
6. PLC SPLITTER MARKET BY TECHNOLOGY COMPATIBILITY
6.1. Introduction
6.2. BPON
6.3. EPON
6.4. GPON
6.5. XG-PON/XGS-PON
6.6. NG-PON2
6.7. WDM-PON2
7. PLC SPLITTER MARKET BY APPLICATION
7.1. Introduction
7.2. PON-based FTTx
7.2.1. FTTH
7.2.2. FTTB
7.2.3. FTTC
7.3. Cable TV (CATV)
7.4. Optical Signal Monitoring
7.5. Testing Equipment
7.6. IoT Networks
7.7. 5G Fronthaul/BackhauL
8. PLC SPLITTER MARKET BY DEPLOYMENT LOCATION
8.1. Introduction
8.2. Central Offices
8.3. Outside Plant
8.4. Premises/End-user Location
8.5. Edge Nodes/Small Cells
9. PLC SPLITTER MARKET BY END-USER
9.1. Introduction
9.2. Telecom Operators
9.3. Data Centers
9.4. ISPs (Internet Service Providers)
9.5. Enterprises
9.6. IoT solution providers
9.7. Cable/MSOs
10. PLC SPLITTER MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. USA
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. United Kingdom
10.4.2. Germany
10.4.3. France
10.4.4. Spain
10.4.5. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. Japan
10.6.3. India
10.6.4. South Korea
10.6.5. Taiwan
10.6.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Corning Incorporated
12.2. Broadex Technologies Co., Ltd.
12.3. Go! Foton Holdings Inc.
12.4. Huihong Technologies Co., Ltd.
12.5. Browave Corporation
12.6. NTT Electronics Corporation
12.7. SENKO Advanced Components Inc.
12.8. Oplink Communications LLC (Molex)
12.9. Reliable Photonics Co. Ltd.
12.10. T&S Communications Co., Ltd.
12.11. Qualfiber Technology Co., Ltd.
12.12. Henan Shijia Photons Technology Co., Ltd.
12.13. Fujikura Ltd.
12.14. Sumitomo Electric Industries, Ltd.
12.15. PPI Inc.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key benefits for the stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











