
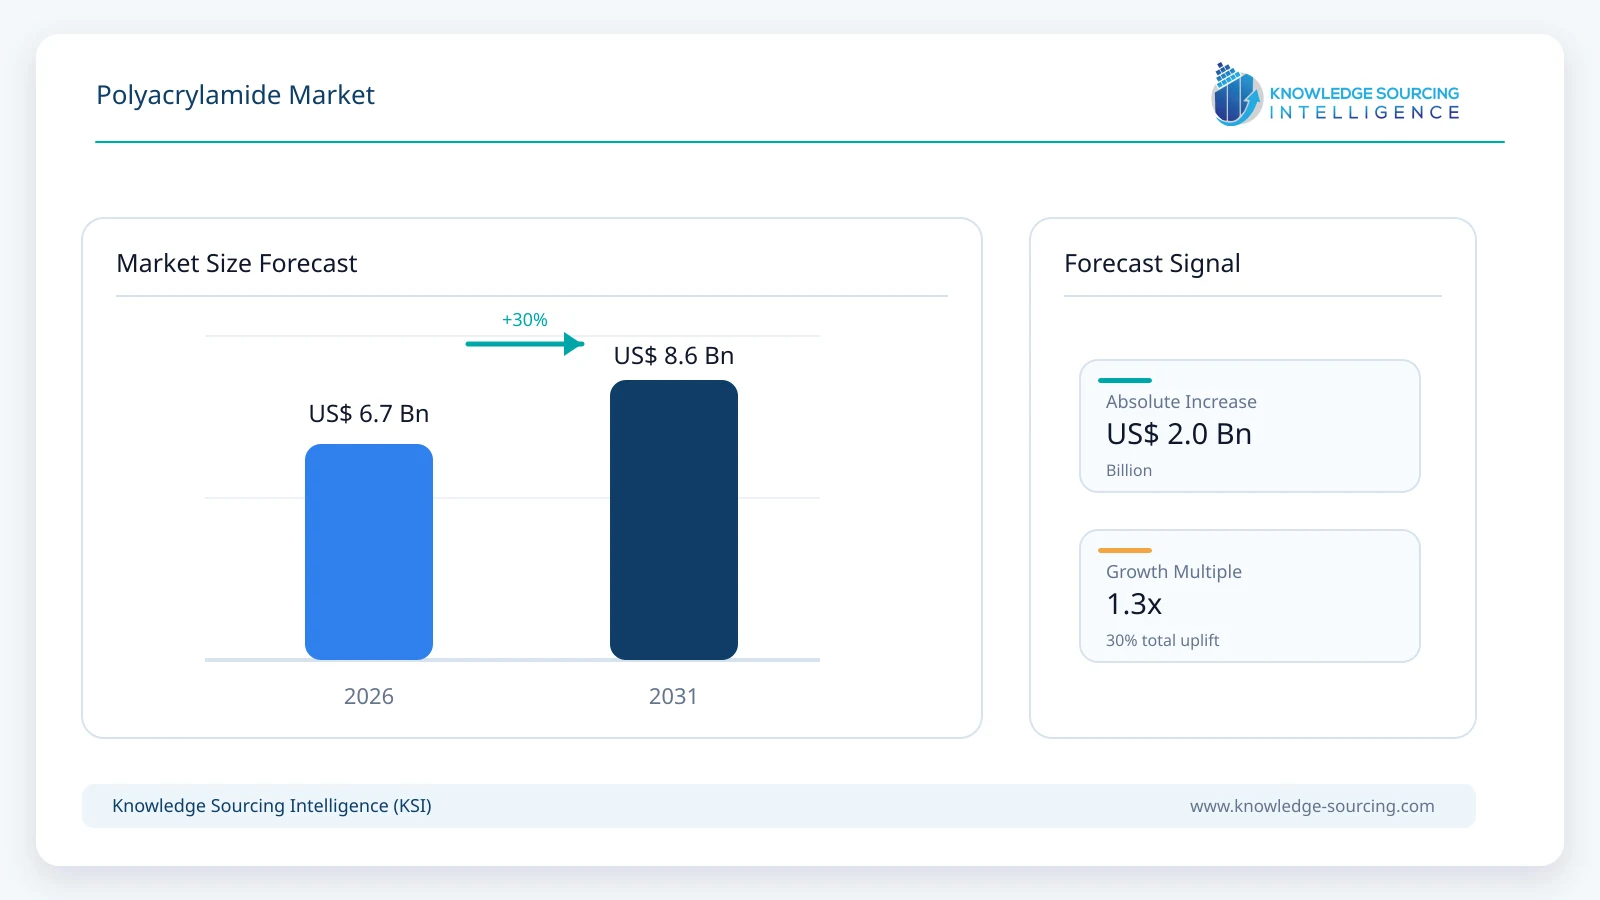
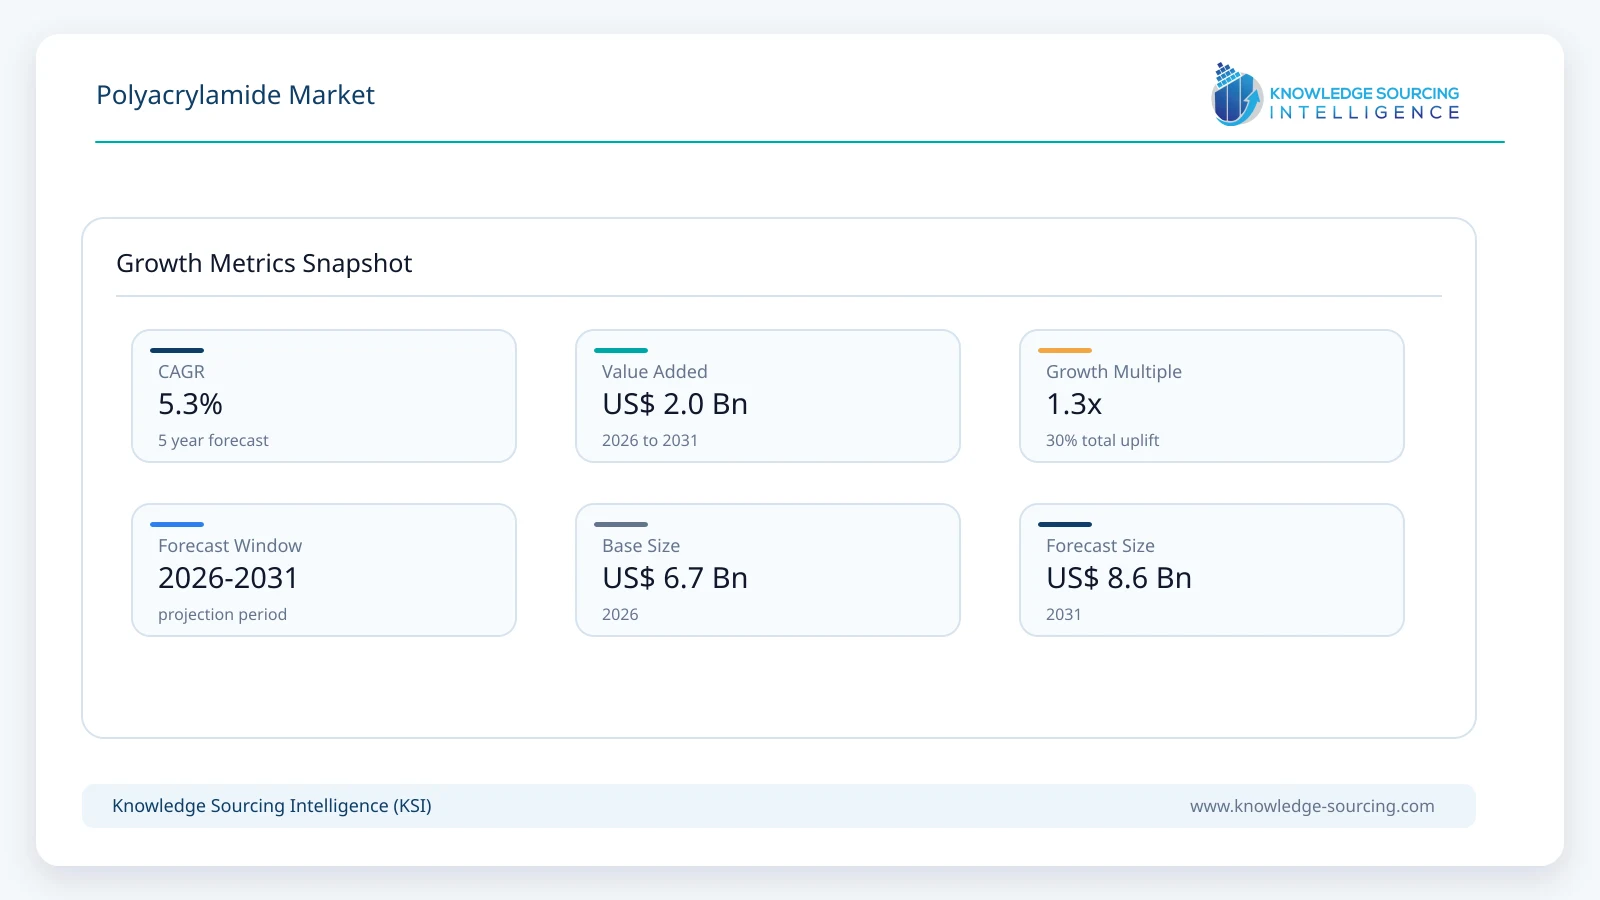
The polyacrylamide market is growing at a CAGR of 5.3%, from USD 6.65 billion in 2026 to USD 8.62 billion by 2031.
Highlights:
- 1Anionic polyacrylamide accounts for approximately 48% of global market revenue in 2026.
- 2Water treatment demand is projected to grow at approximately 5.0% annually through 2031.
- 3Asia Pacific accounts for approximately 42% of global polyacrylamide revenue in 2026.
- 4Oil and gas applications are contributing faster incremental demand through friction reduction and polymer flooding.
- 5Backward integration into acrylamide and regional production capacity are becoming stronger competitive advantages.
Polyacrylamide is sold across dry powder, emulsion and solution formats and is differentiated by ionic charge, molecular weight, residual monomer specification and application performance. Anionic grades are widely used in mineral processing, municipal and industrial water treatment, drilling, friction reduction and enhanced oil recovery. Cationic grades are particularly important in sludge dewatering and papermaking, while non-ionic and amphoteric products address narrower process requirements. This diversity makes the market less dependent on one industry than many specialty polymers, although the economics of individual grades can vary substantially.
The supply side is becoming increasingly scale-driven. SNF operates 23 production sites and reports 1.67 million tonnes of global polyacrylamide capacity. Palladio Industries completed a major expansion in Temple, Texas in October 2025, taking installed capacity to about 270,000 tonnes per year. Kemira remains backward-integrated into acrylamide production and supplies polyacrylamide into municipal water, pulp and paper and energy applications, while Solenis broadened its polymer position after acquiring BASF's flocculants business for mining applications. These investments increase regional supply security but also raise the importance of utilization rates, acrylonitrile costs and customer qualification in supplier economics.
Market Trends
Regionalization of production and backward integration
Polyacrylamide manufacturers are expanding capacity closer to major water, mining and energy customers while strengthening control over acrylamide monomer supply. The strategy reduces freight exposure for high-volume polymer products, improves responsiveness to customers and lowers the operational risk associated with feedstock disruptions. SNF maintains manufacturing across the Americas, Europe and Asia, while Palladio has materially expanded U.S. capacity and Kemira operates an integrated polymer platform serving North American and European customers. Regional capacity is particularly valuable in oilfield applications, where rapid changes in drilling activity and produced-water volumes can alter demand over relatively short periods.
Lower-carbon and performance-optimized polymer programs
Sustainability initiatives are shifting from simple dosage reduction toward lower-carbon feedstocks, higher dewatering efficiency and process-level resource savings. Kemira continues to commercialize biomass-balanced polyacrylamide products using renewable feedstock allocation, while Solenis has demonstrated glyoxalated polyacrylamide programs that improve fiber efficiency and reduce refining energy in tissue production. In water and mining applications, suppliers increasingly compete on the amount of dry solids recovered, water recycled or throughput gained per unit of polymer rather than on polymer price alone. This favors suppliers with strong application laboratories and on-site technical service.
Market Drivers
Expansion of wastewater treatment and water reuse
Municipal and industrial wastewater treatment remains the most durable source of polyacrylamide demand because flocculation and sludge dewatering are recurring operating requirements rather than one-time capital purchases. Urbanization, stricter discharge standards and greater emphasis on water reuse are increasing the volume of sludge that must be thickened and dewatered efficiently. Polyacrylamide can reduce settling time, improve solids capture and raise cake dryness, which lowers downstream hauling and disposal costs. The commercial effect is especially important in large treatment plants, mining operations and industrial sites where modest improvements in polymer performance can reduce total operating cost across millions of cubic metres of water.
Higher polymer use in oilfield recovery and water management
Oilfield demand is strengthening through friction reducers used in hydraulic fracturing, produced-water treatment and polymer flooding for chemical enhanced oil recovery. In March 2026, SNF Flopam India secured an INR 547 crore contract from ONGC for polymer-injection facilities at the Bechraji field, illustrating the scale of polymer demand that can arise from field-wide EOR programs. SNF also completed its acquisition of Syensqo's oil and gas division in January 2026, broadening its product and customer base across drilling, stimulation and production. These projects support higher-value polymer grades that must maintain viscosity and performance under challenging salinity, temperature and shear conditions.
Market Restraint
Feedstock volatility and application-specific qualification requirements
Polyacrylamide production remains exposed to acrylonitrile and acrylamide economics, energy costs and plant operating conditions. Sharp feedstock movements can compress margins when supply contracts prevent immediate price adjustments, while regional shortages can disrupt availability for customers that rely on narrowly qualified grades. Qualification itself creates another constraint because polymer performance depends heavily on water chemistry, solids characteristics, ionic charge and molecular weight. A product that works well in one mine, refinery or wastewater plant cannot always be substituted directly into another. This limits rapid supplier switching and raises testing costs, while also making new market entry more difficult for manufacturers without local technical support.
Segment Analysis
By Type - Anionic Polyacrylamide
Anionic polyacrylamide is the largest type, accounting for approximately 48% of global market revenue in 2026 and projected to reach about USD 4.23 billion by 2031. Its position is supported by broad use in mineral processing, water clarification, tailings treatment, oilfield friction reduction and enhanced oil recovery. High-molecular-weight anionic grades can deliver strong flocculation at relatively low dosage, while partially hydrolyzed products are widely used where viscosity and mobility control are required. The segment also benefits from large-scale Chinese and North American production capacity, which supports supply into mining and energy applications. Competitive differentiation increasingly centers on molecular-weight consistency, dissolution performance, residual acrylamide control and resistance to salinity or shear rather than on basic polymer chemistry alone.
By End-User Industry - Water Treatment
Water treatment remains the largest end-user category and is projected to expand at approximately 5.0% CAGR between 2026 and 2031, reaching about USD 2.59 billion by 2031. Municipal wastewater plants use cationic and anionic polyacrylamides for clarification, sludge thickening and dewatering, while industrial users apply polymers in process-water recovery, dissolved-air flotation and effluent treatment. Demand is comparatively resilient because polymer consumption tracks water throughput and sludge generation rather than discretionary capital spending. Growth is strongest where utilities are adding tertiary treatment, expanding reuse or attempting to reduce sludge-disposal costs. Industrial demand is also broadening as mining, food processing, chemicals, power and pulp and paper facilities tighten internal water-recycling targets.
By Geography - Asia Pacific
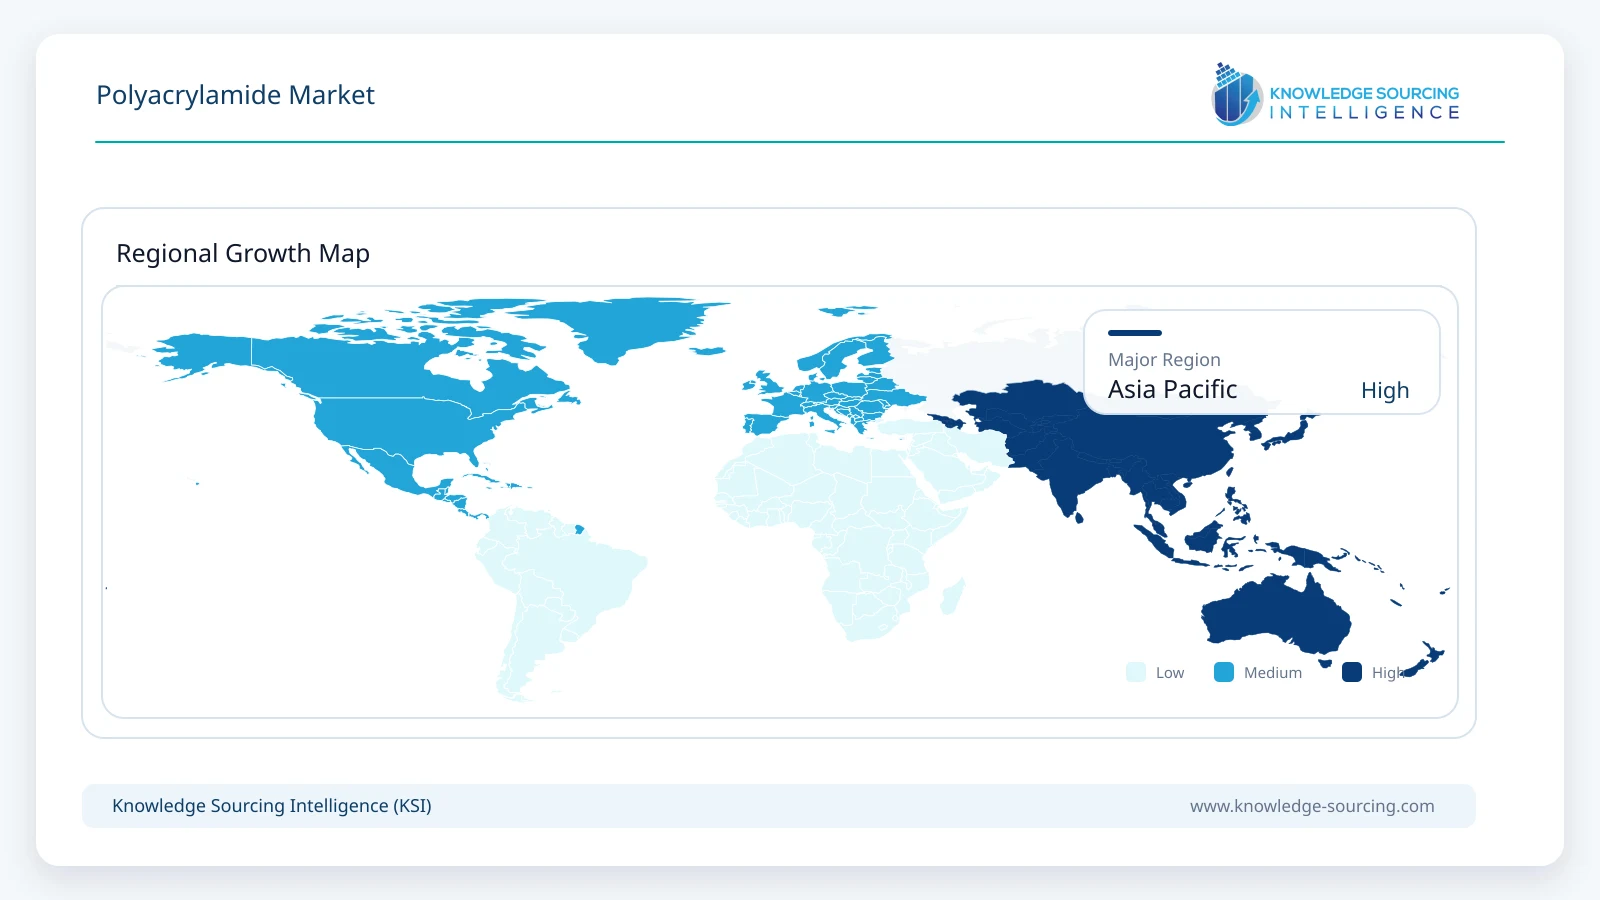
Asia Pacific accounts for approximately 42% of global polyacrylamide revenue in 2026 and is projected to generate about USD 3.75 billion by 2031. China provides the largest regional base through municipal water treatment, oilfield polymer flooding, coal and mineral processing, paper production and a large domestic manufacturing sector. India is expanding through urban wastewater investment, refinery and oilfield applications, mining and paper production, while Southeast Asia contributes growing demand from industrial wastewater and mineral processing. The region also contains a dense supplier base that exerts price pressure on commodity grades, making technical service, quality consistency and access to higher-performance formulations increasingly important for international suppliers.
Competitive Environment
The market is moderately concentrated at the top but remains fragmented across regional producers. SNF holds the largest global production footprint and combines polyacrylamide capacity with acrylamide integration, application laboratories and direct presence across water, oil and gas, mining and paper markets. Kemira and Solenis maintain strong positions in water-intensive industries, while BASF continues to supply polyacrylamide-based oilfield chemistries and has historically maintained a significant production base. Palladio Industries has become a materially larger North American producer following its Texas expansion.
Competition differs by application. Municipal treatment customers prioritize regulatory compliance, residual-monomer control, dosing efficiency and local service. Mining customers focus on settling rates, tailings performance and water recovery. Oilfield customers require polymers capable of maintaining friction-reduction or viscosity performance under difficult temperature and salinity conditions. Asian manufacturers compete strongly in standard dry-polymer grades, but qualification barriers and technical-service requirements remain higher in mining, EOR and regulated drinking-water applications.
Recent Developments
April 2026: Solenis highlighted commercial use of its glyoxalated polyacrylamide strength program at Hainan Gold Hongye Paper, where the program improved fiber efficiency while reducing refining energy and chemical consumption.
March 2026: SNF Flopam India secured an INR 547 crore (approximately USD 59 million) ONGC contract for full-field polymer injection facilities at the Bechraji field, strengthening commercial demand for oilfield polyacrylamide systems.
January 2026: SNF completed the acquisition of Syensqo's Oil & Gas division for an enterprise value of EUR 135 million, expanding its oilfield chemicals platform and technical portfolio.
October 2025: Palladio Industries completed a major expansion at its Temple, Texas plant, increasing installed polyacrylamide capacity to approximately 270,000 tonnes per year.
Polyacrylamide Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 6.65 billion |
| Total Market Size in 2031 | USD 8.62 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-User Industry, Geography |
| Companies |
|
Market Segmentation
By Type
Cationic
Anionic
Non-Ionic
Amphoteric and Others
By End-User Industry
Water Treatment
Oil & Gas
Mining & Mineral Processing
Pulp & Paper
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of Wastewater Treatment and Water Reuse
3.1.2. Higher Polymer Use in Oilfield Recovery and Water Management
3.2. Market Restraint
3.2.1. Feedstock Volatility and Application-Specific Qualification Requirements
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Biomass-Balanced and Lower-Carbon Polyacrylamides
4.2. High-Performance Polymer Formulations
4.3. Polymer Dosing and Process Optimization
5. POLYACRYLAMIDE MARKET BY TYPE
5.1. Introduction
5.2. Cationic
5.3. Anionic
5.4. Non-Ionic
5.5. Amphoteric and Others
6. POLYACRYLAMIDE MARKET BY END-USER INDUSTRY
6.1. Introduction
6.2. Water Treatment
6.3. Oil & Gas
6.4. Mining & Mineral Processing
6.5. Pulp & Paper
6.6. Others
7. POLYACRYLAMIDE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Italy
7.4.5. Spain
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Australia
7.6.6. Indonesia
7.6.7. Thailand
7.6.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. SNF Group
9.2. Kemira Oyj
9.3. Solenis LLC
9.4. BASF SE
9.5. Palladio Industries, Inc.
9.6. PetroChina Daqing Refining & Chemical Company
9.7. Beijing Hengju Chemical Group Corporation
9.8. Jiangsu Feymer Technology Co., Ltd.
9.9. Shandong Nuoer Biotechnology Co., Ltd.
9.10. Anhui Tianrun Chemicals Co., Ltd.
9.11. Xitao Polymer Co., Ltd.
9.12. Anhui Jucheng Fine Chemicals Co., Ltd.
9.13. Shandong Polymer Bio-Chemicals Co., Ltd.
9.14. Yixing Bluwat Chemicals Co., Ltd.
9.15. Henan Zhengjia Green Energy Co., Ltd.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











